
 Europe Jackup Rig Market | 2026-2036
Europe Jackup Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Jackup Rig Market Foresight
North Sea rig owners is pivoting toward higher-specification jackup fleets to capture premium dayrates in harsh-environment drilling. KCA DEUTAG Drilling Ltd leverages its North Sea operational heritage to sustain long-term client relationships with major operators. Maersk Drilling AS anchors its competitive stance through advanced harsh-environment jackup designs purpose-built for Danish and Norwegian waters. Saipem SpA differentiates via integrated offshore engineering capabilities that extend beyond bare rig provision into subsea construction support.
A jackup rig is a self-elevating mobile offshore drilling platform with tubular or truss-type legs that penetrate the seabed, typically operating in water depths up to 120 meters and capable of supporting drilling loads exceeding 5,000 tons. The platform hull houses drilling equipment, crew quarters, and power generation systems, enabling stable operations independent of wave motion for offshore hydrocarbon extraction and field maintenance. Premium jackup rigs command the strongest dayrate premiums in the Europe Jackup Rig Market due to their enhanced leg-length capacity and dynamic positioning redundancy for North Sea winter operations. Decommissioning applications represent the fastest-expanding segment as aging UK and Norwegian platforms require specialized heavy-lift jackups for topside removal and well plugging.
The EU Green Deal and F-Gas Regulation are tightening emissions standards for offshore drilling equipment, compelling rig operators to retrofit diesel-electric power systems or face exclusion from European contracting pools. EMDR and CE marking requirements under the EU Machinery Directive enforce structural integrity and safety protocols for jackup leg systems and elevating machinery. Norway's Petroleum Safety Authority and the UK Health and Safety Executive impose additional national standards for offshore installation management that shape fleet deployment decisions. Stakeholders must monitor regulatory divergence between EU-wide decarbonization mandates and national safety regimes when allocating capital across the European jackup fleet.
Market Dynamics
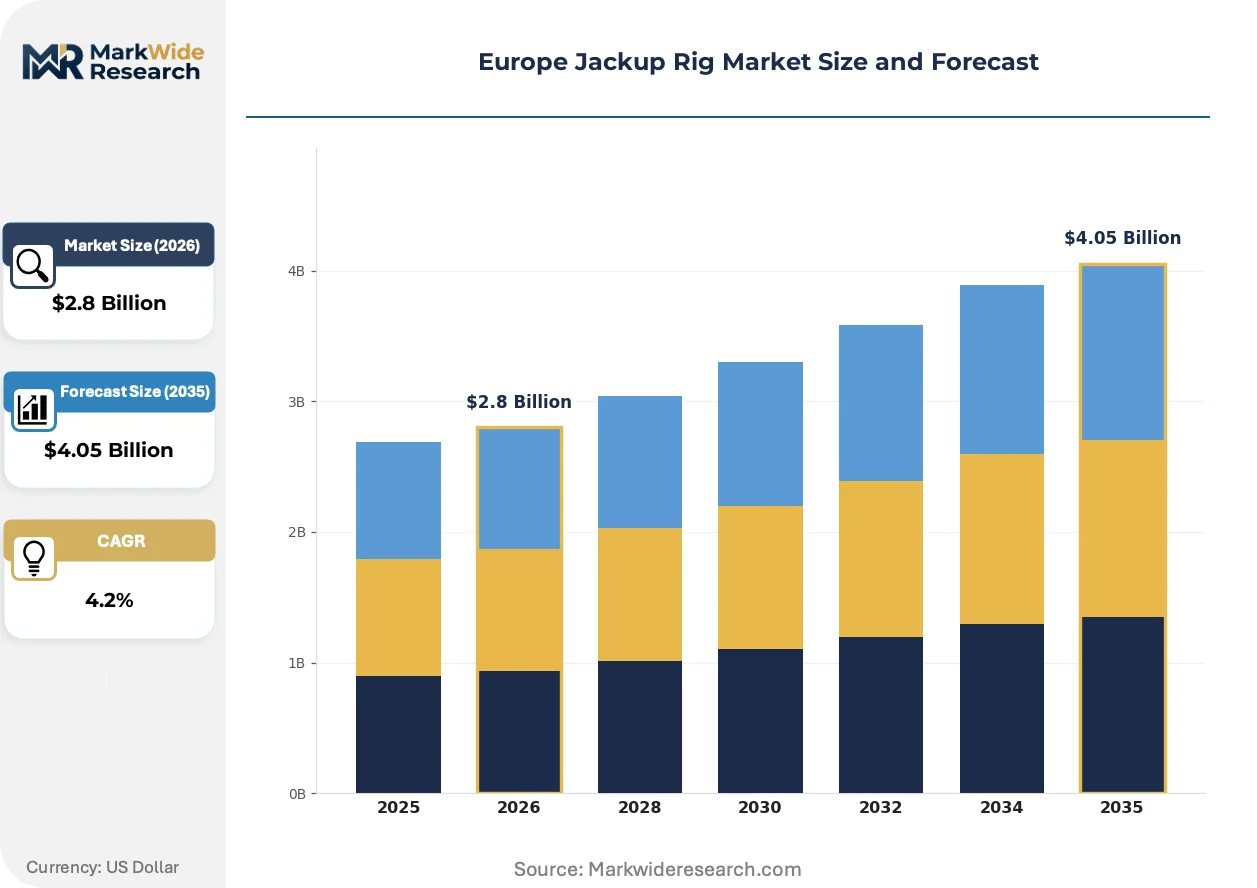
The Europe Jackup Rig Market is undergoing structural compression as EU Green Deal mandates force simultaneous fleet electrification and decommissioning capability expansion, creating capital allocation tension for rig owners serving North Sea operators.
Growth Catalysts
- EU F-Gas Regulation:Tightening emissions standards for offshore equipment are compelling E&P firms to contract only retrofitted diesel-electric rigs, accelerating replacement cycles for legacy units across Norwegian and UK sectors.
- North Sea decommissioning wave:Aging platform infrastructure in British and Norwegian waters is generating sustained demand for heavy-lift capable jackups specialized in topside removal and well plugging operations.
- Harsh-environment premium dayrates:Enhanced leg-length capacity and dynamic positioning redundancy command pricing power during winter drilling windows in the Danish and Norwegian North Sea.
Market Restraints
- Steel and alloy input volatility:Jackup leg fabrication depends on specialized high-strength steel grades subject to supply concentration from a limited base of European specialty mills.
- CE marking compliance costs:EMDR and EU Machinery Directive certification for elevating machinery and leg systems imposes multi-year approval timelines that freeze fleet expansion capital.
- Offshore wind substitution:Floating turbine installation vessels are capturing capital allocation from hydrocarbon-focused rig investments as North Sea energy transition accelerates.
Strategic Opportunities
- UK well P&A backlog:Thousands of suspended wells require plug-and-abandonment campaigns where jackup-based intervention units face limited competition from platform rigs.
- Battery-hybrid retrofits:Convergence of marine battery systems with diesel-electric architectures opens upgrade revenue streams for existing fleet owners without full newbuild commitments.
- Norwegian sector clustering:Concentrated operator headquarters in Stavanger and Oslo create channel efficiency for integrated service packages bundling rig provision with subsea engineering.
Industry Challenges
- Marine electrical engineer scarcity:Hybrid power system integration demands specialized skills that outpace European technical training pipeline output.
- Dual certification timelines:Simultaneous EU Machinery Directive CE marking and Norway Petroleum Safety Authority approval create parallel compliance tracks that extend deployment readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Jackup Rig Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Rig Type: Premium, Standard, Basic, Advanced Application: Offshore Drilling, Platform Maintenance, Subsea Construction, Decommissioning Installation Type: Fixed, Self-Elevating, Spud Can, Mat Supported End User: Exploration Companies, E&P Firms, Contract Drillers, Oilfield Service Providers |
| Companies Covered | Borr Drilling Ltd, KCA DEUTAG Drilling Ltd, Noble Corporation PLC, Saipem SpA, Nabors Industries Ltd, Maersk Drilling AS, Valaris PLC, Stena Drilling Ltd, Seadrill Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Jackup Rig Market Shifts & Advancements
Electrification architectures and digital power management are redefining competitive differentiation in North Sea contracting, while procurement patterns shift toward integrated service bundles.
Diesel-electric hybrid power systems with lithium-ion battery banks are electrifying jackup rig operations by enabling peak shaving and zero-emission harbor transits. Norwegian and UK operators are specifying these configurations in new tenders to preempt EU emissions compliance deadlines. The technology is compressing the operational cost gap between premium newbuilds and retrofitted legacy units.
The EU Green Deal's offshore decarbonization mandates are cascading into national implementation through Norway's Petroleum Safety Authority safety case revisions and UK Health and Safety Executive offshore installation management updates. These frameworks are forcing rig owners to document emissions reduction pathways alongside traditional structural integrity proofs. Harsh-environment jackup segments face the steepest compliance cost escalation as winter operational reliability standards tighten concurrently.
Charter contracting is consolidating around multi-year integrated service agreements that bundle rig provision with subsea construction and well intervention scopes. This model is displacing bare rig dayrate structures in Norwegian sector negotiations. Stavanger-based operators are driving this consolidation, seeking single-accountability partners for complex decommissioning campaigns.
Europe Jackup Rig Market Segmentation
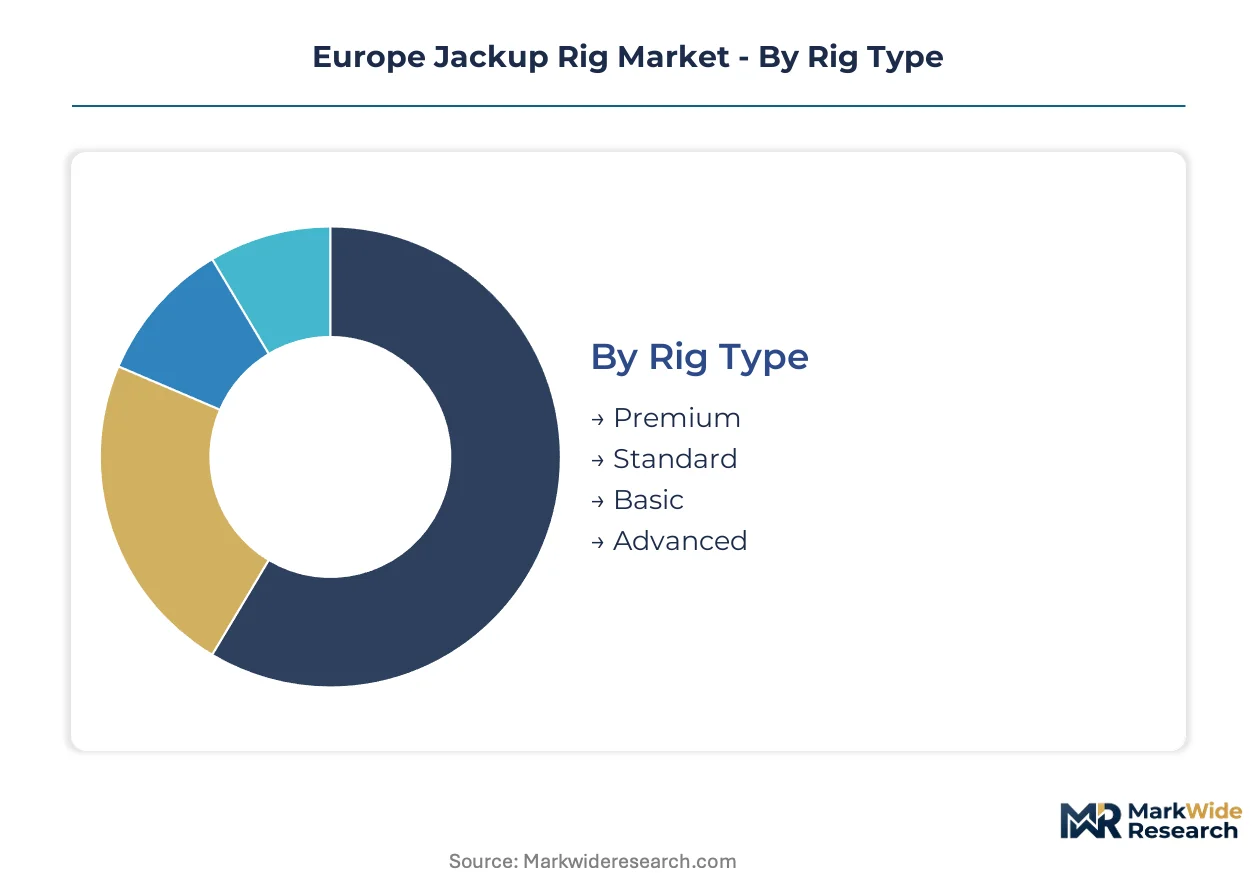
Segmentation in the Europe Jackup Rig Market reveals how technical specifications and operational requirements fragment contracting pools across the North Sea. Each dimension shapes capital allocation, regulatory compliance pathways, and dayrate negotiations differently for rig owners and operators.
Rig Type:
Customization intensity spans from fully optimized harsh-environment units to commoditized shallow-water workhorses, with specification tiers directly locking access to premium contracting windows.
- Premium:Extended leg-length capacity beyond 120 meters and dynamic positioning redundancy enable winter operations in Norwegian and UK northern sectors. Demand concentrates with Equinor and Shell for high-pressure high-temperature drilling where downtime penalties exceed dayrate premiums.
- Advanced:Integrated battery-hybrid power architectures and automated jacking systems reduce emissions profiles for EU Green Deal compliance. Maersk Drilling and KCA DEUTAG are retrofitting existing fleets toward this specification to defend market position without full newbuild commitments.
- Standard:Conventional diesel-mechanical power and fixed positioning systems serve summer-only campaigns in southern North Sea sectors.
- Basic:Legacy units with limited leg-length and minimal automation handle shallow-water well intervention and plug-and-abandonment work.
Most installed capacity flows through Standard rigs. Expansion is steepest in Advanced configurations as hybrid retrofits outpace newbuild deliveries.
Application:
Operational complexity and asset specificity create divergent margin profiles across drilling versus construction-support missions.
- Decommissioning:Heavy-lift jackups with 3,000+ ton crane capacity execute topside removal and jacket severing for aging UK and Norwegian platforms. The UK Oil and Gas Authority's decommissioning timelines are compressing contracting windows into concentrated campaign seasons.
- Offshore Drilling:Exploration and development drilling in Norwegian deepwater blocks demands premium harsh-environment specifications with winterized equipment and enhanced station-keeping. Johan Sverdrup phase expansions are sustaining rig demand here.
- Platform Maintenance:Workover and well intervention operations on mature UKCS fields utilize lower-specification units with modular equipment packages.
- Subsea Construction:Integrated vessel capabilities combining jacking systems with ROV spreads and flexible pipe lay equipment serve tieback developments.
Platform Maintenance absorbs the largest share of operating days. Decommissioning is gaining share fastest as UK and Norwegian shelf maturation accelerates.
Installation Type:
Foundation mechanics determine water depth envelopes and seabed condition tolerance across the North Sea's variable geology.
- Spud Can:Individual cylindrical footings with concentrated bearing pressure penetrate stiff clays and dense sands in central and northern North Sea sectors. Saipem's fleet deployment emphasizes this configuration for Norwegian deepwater independence.
- Self-Elevating:Truss-leg systems with rack-and-pinion elevation machinery dominate the installed base and enable rapid site relocation between UK and Norwegian campaigns.
- Mat Supported:Continuous foundation mats distribute load across soft seabed conditions in southern North Sea gas fields.
- Fixed:Permanent piled foundations for specialized heavy-lift applications with minimal relocation requirements.
Self-Elevating systems carry the majority of active fleet capacity. Spud Can configurations are climbing fastest as operators prioritize single-well relocation efficiency.
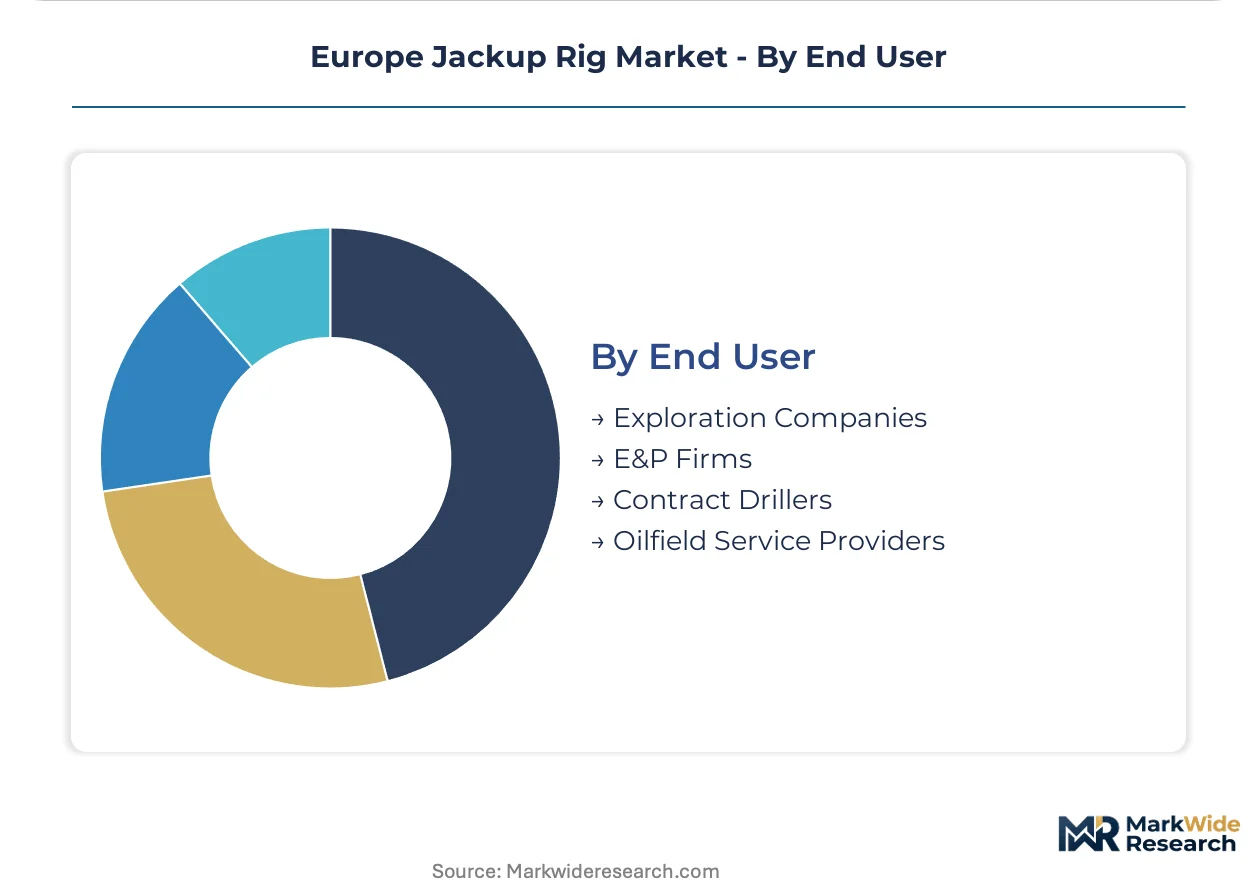
End User:
Procurement sophistication and contract duration preferences separate national oil companies from independent drillers and service intermediaries.
- E&P Firms:Integrated operators like Equinor, Aker BP, and Harbour Energy negotiate multi-year integrated service agreements bundling rig provision with subsea engineering and construction management. Stavanger headquarters proximity shapes supplier selection.
- Contract Drillers:Pure-play drilling contractors including KCA DEUTAG and Maersk Drilling operate on bare rig dayrate structures with shorter tenor and higher utilization risk exposure.
- Exploration Companies:Independents and private equity-backed ventures charter on single-well or campaign-specific terms with premium pricing for short-notice availability.
- Oilfield Service Providers:Schlumberger and Halliburton subsidiaries subcontract rig capacity as part of integrated well delivery packages.
E&P Firms command the largest share of contracted rig years. Contract Drillers are expanding share fastest as operator outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compliance-cost arbitrage is redirecting jackup rig deployment toward jurisdictions with streamlined safety case approval timelines, concentrating fleet investment in Norwegian and UK waters where regulatory harmonization reduces dual-certification burdens.
Norway
Johan Sverdrup expansion campaigns and Northern Sea decommissioning drive demand for harsh-environment units with extended leg capacity. The Petroleum Safety Authority mandates emissions reduction documentation alongside traditional structural integrity proofs. Stavanger anchors operator headquarters clusters where Equinor and Aker BP negotiate integrated service bundles.
United Kingdom
UK Oil and Gas Authority decommissioning timelines compress contracting windows for heavy-lift jackups executing topside removal. The Health and Safety Executive updates offshore installation management standards to incorporate EU Green Deal decarbonization pathways. Aberdeen sustains fabrication and engineering service ecosystems supporting rig upgrade programs.
Denmark
Danish North Sea mature field workovers sustain demand for winterized jackup specifications. National implementation of EU F-Gas Regulation accelerates diesel-electric retrofit requirements across contracted fleets. Copenhagen-based operators prioritize battery-hybrid configurations in tender specifications.
Netherlands
Southern North Sea gas field maintenance utilizes mat-supported and standard jackup configurations for summer campaigns. Dutch emission control zones enforce harbor transit standards that favor electrified power architectures. Rotterdam port infrastructure supports rig mobilization for cross-border Norwegian and UK campaigns.
Germany
Specialty steel supply from German mills underpins jackup leg fabrication for North Sea fleet renewal. KBA maritime equipment standards intersect with CE marking requirements under EU Machinery Directive. Hamburg and Bremen harbor engineering clusters provide elevating machinery and jacking system technical services.
Europe Jackup Rig Market Competitive Landscape
Scandinavian and UK producers anchor one tier of premium harsh-environment specialists; North American drillers hold scale positions through consolidated fleet holdings. Market structure concentrates around integrated service providers capable of bundling rig provision with subsea construction management. Three archetypes dominate: legacy North Sea operators with operational heritage advantages, global drillers with capital-scale fleet diversification, and engineering-integrated contractors extending beyond bare rig provision. Competitive moves center on battery-hybrid retrofit programs and multi-year integrated service agreement negotiations with Stavanger and Oslo headquartered operators.
Within the integrated engineering tier, Saipem SpA and KCA DEUTAG Drilling Ltd exemplify archetypes combining rig provision with extended offshore construction capabilities. Maersk Drilling AS occupies a position among Scandinavian specialists with purpose-built harsh-environment designs. These entities represent differentiated positioning against pure-play contract drillers operating on shorter-tenor bare rig structures.
| Leading Market Players |
|---|
| Borr Drilling Ltd |
| KCA DEUTAG Drilling Ltd |
| Noble Corporation PLC |
| Saipem SpA |
| Nabors Industries Ltd |
| Maersk Drilling AS |
| Valaris PLC |
| Stena Drilling Ltd |
| Seadrill Ltd |
| Others |
Supply & Pricing Matrix
Marine electrical engineer concentration in Norwegian Stavanger and UK Aberdeen clusters creates labor-cost differentials that widen pricing-tier spreads between premium hybrid-electric jackups and legacy diesel-mechanical units. EU F-Gas Regulation compliance deadlines compress these spreads as retrofit capital requirements standardize across specification tiers.
Pricing Analysis
Direct-to-E&P contracting discounts dominate bare rig dayrate structures, while integrated service bundles capture channel margins through subsea construction packaging. Price differentiation hinges on CE marking tier under EU Machinery Directive and battery-hybrid certification grade. Pricing pressure stems from offshore wind substitution as floating turbine vessels capture capital allocation. Independent exploration companies exhibit highest price sensitivity; Equinor and Aker BP demonstrate lowest sensitivity through multi-year integrated agreements.
Supply Chain Analysis
Single-source vulnerability sits with German specialty steel mills supplying high-strength leg alloys for harsh-environment jackup fabrication. Component sourcing draws from Norway for elevating machinery, Germany for structural steel, and Netherlands for marine electrical systems. Raw material dependencies include high-yield steel grades, lithium-ion battery cells, and rack-and-pinion jacking components. Tariff exposure on steel imports creates supply chain risk. Distribution runs through Stavanger and Oslo operator headquarters for integrated service contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Jackup Rig Market functions as a geographic-arbitrage play where Norway's streamlined Petroleum Safety Authority approval timelines reduce compliance costs versus UK dual-certification burdens.
For Market Incumbents: Hedge against offshore wind capital reallocation by accelerating battery-hybrid retrofit programs in existing fleets. Secure backward integration into marine electrical engineering talent pools through Stavanger technical training partnerships. Defend market position against integrated engineering contractors by bundling bare rig provision with subsea intervention capabilities. For New Entrants and Emerging Players: Digital platform-based charter marketplaces offer route penetration into spot-contracting segments where independents seek short-notice jackup availability. Target UK well P&A backlog as most penetrable application segment with modular intervention unit configurations. Pursue direct-to-exploration-company positioning bypassing integrated operator procurement consolidation. For Investors and Strategic Acquirers: Engineering-integrated contractors are the most active acquirer in this space, seeking single-accountability partners for decommissioning campaigns. Long-term viability centers on hybrid-electric fleet transformation completion within the next decade. Monitor EU Green Deal implementation velocity as inflection indicator for retrofit investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Hybrid Retrofit Program | Reduces emissions profiles for EU F-Gas Regulation compliance without full newbuild capital commitment. |
| Integrated Service Agreement Expansion | Bundles rig provision with subsea construction to capture Stavanger-based operator procurement consolidation. |
| Marine Electrical Engineer Training Pipeline | Addresses hybrid power system skill scarcity constraining fleet electrification timelines. |
| Dual Certification Streamlining | Reduces parallel EU Machinery Directive and Norway PSA approval timelines extending deployment readiness. |
| Decommissioning Capability Investment | Positions for UK Oil and Gas Authority topside removal campaign concentration. |
Research Methodology
Bottom-up E&P firm contracting volume modeling reconciled against top-down jackup fleet capacity tracking forms the analytical core of this study. Primary interviews with rig fleet managers, offshore installation engineers, and Stavanger-based operator procurement leads combined with secondary validation from Norway Petroleum Safety Authority safety case databases, UK Health and Safety Executive offshore installation registers, and EU Machinery Directive CE marking records. Triangulation across supply-side fleet utilization data and demand-side charter tender analysis ensures coverage integrity.
Input-output matrix framing connects rig type segmentation, application intensity, and water depth specifications to dayrate and utilization assumptions across the projection horizon. CAGRs derive from segmented fleet deployment modeling incorporating decommissioning campaign schedules, Johan Sverdrup phase expansion timelines, and EU Green Deal regulatory implementation trajectories. Industry-specific forecast inputs include hybrid retrofit penetration curves and marine electrical engineer supply elasticity.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery marine systems would alter the outlook. Forecasts reflect assumptions on regulatory harmonization between EU-wide decarbonization mandates and national safety regimes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Brazil Oil and Gas Upstream Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Qatar Oil and Gas Upstream Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market