
 Thailand Oil and Gas Downstream Market | 2026-2036
Thailand Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Oil and Gas Downstream Market Analytics
Aftermarket service revenue is tilting toward integrated refining-chemical complexes as operators seek yield optimization beyond commodity margins. PTT Public Company Limited leverages its nationwide pipeline network and retail footprint to sustain downstream control. Bangchak Corporation PCL anchors its position through biofuel blending investments and renewable feedstock trials. IRPC Public Company Limited specializes in aromatics and polyolefin derivatives that differentiate its product slate from standard fuel producers.
Thailand oil and gas downstream encompasses crude oil refining, petrochemical processing, and finished product distribution through physical infrastructure serving transportation, industrial, and power generation needs. Refineries operate with complexity indices determining distillate yields, while crackers process naphtha and LPG into ethylene, propylene, and benzene feedstocks for plastics and synthetic rubber manufacturing. Refined Fuels retains the largest volume share though margin compression from electrification trends pressures gasoline and diesel returns. Petrochemicals captures expanding margin pools as SCG Chemicals Co Ltd and regional competitors build derivative capacity for automotive and packaging resins. Specialty Chemicals remains the smallest segment by tonnage but commands premium pricing for lubricant additives and process solvents used in precision manufacturing.
Thailand's Department of Energy Business enforces fuel quality specifications aligned with Euro 5 emission standards, compelling refinery investments in hydrotreating and sulfur recovery units. The Board of Investment coordinates with the Ministry of Industry to condition tax incentives on emissions disclosures and energy efficiency benchmarks for new downstream projects. Stakeholders must weigh feedstock flexibility against product slate lock-in as biofuel mandates and circular economy regulations reshape long-term asset valuations.
Market Dynamics
Thailand's downstream sector confronts a fundamental margin squeeze as electrification erodes transport fuel demand while petrochemical integration absorbs capital that once expanded refining capacity. The Board of Investment's conditional tax incentives now steer investment toward hydrotreating upgrades and biofuel blending infrastructure rather than greenfield refinery construction.
Growth Catalysts
- Eastern Economic Corridor infrastructure:Integrated refining-chemical complexes in Rayong and Chonburi provinces attract industrial buyers seeking feedstock proximity and shared utilities. Cluster density reduces logistics costs for naphtha crackers and aromatics producers.
- Euro 5 fuel quality mandates:Thailand's Department of Energy Business enforces sulfur specifications compelling hydrotreater investments. Compliance spending creates aftermarket service demand for catalyst replacement and reactor maintenance.
- Biofuel blending requirements:Biodiesel and ethanol mandates expand addressable volume for domestic crushers and fermentation facilities. Palm oil and cassava processors gain offtake certainty through compulsory blending floors.
Market Restraints
- Crude import dependency:Thailand sources over ninety percent of crude from Middle Eastern term contracts, exposing refiners to freight rate volatility and geopolitical supply disruptions. Limited domestic production eliminates feedstock flexibility.
- Electrification substitution:Battery electric vehicle adoption in Bangkok's commercial fleet compresses gasoline and diesel demand growth. Refineries face stranded asset risk on gasoline hydrotreaters and FCC units.
- Capital intensity of complexity upgrades:Coker and hydrocracker installations require billion-dollar commitments with decade-long payback horizons. Smaller independents lack balance sheet capacity to match PTT's investment scale.
Strategic Opportunities
- Circular feedstock integration:Pyrolysis oil from plastic waste offers alternative cracker feedstock as EU border carbon adjustments approach. Chemical recyclers can anchor offtake agreements with aromatics producers.
- Specialty lubricant additives:Precision manufacturing in Thailand's automotive and electronics sectors demands high-performance process solvents and metalworking fluids. Local blending capacity captures premium pricing over commodity fuels.
- Carbon capture retrofitting:Board of Investment incentives for emissions disclosures create project finance structures for refinery CCS installations. Hydrogen production from syngas separation supports ammonia and methanol derivatives.
Industry Challenges
- Process control engineering talent scarcity:Advanced refinery automation and digital twin deployment require specialists conversant in both petrochemical kinetics and IIoT architecture. Universities produce insufficient graduates at this intersection.
- Legacy equipment integration:Sixty-year-old atmospheric distillation units must interface with modern distributed control systems without shutdown windows. Migration projects risk operational disruption during cutover phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Oil and Gas Downstream Market |
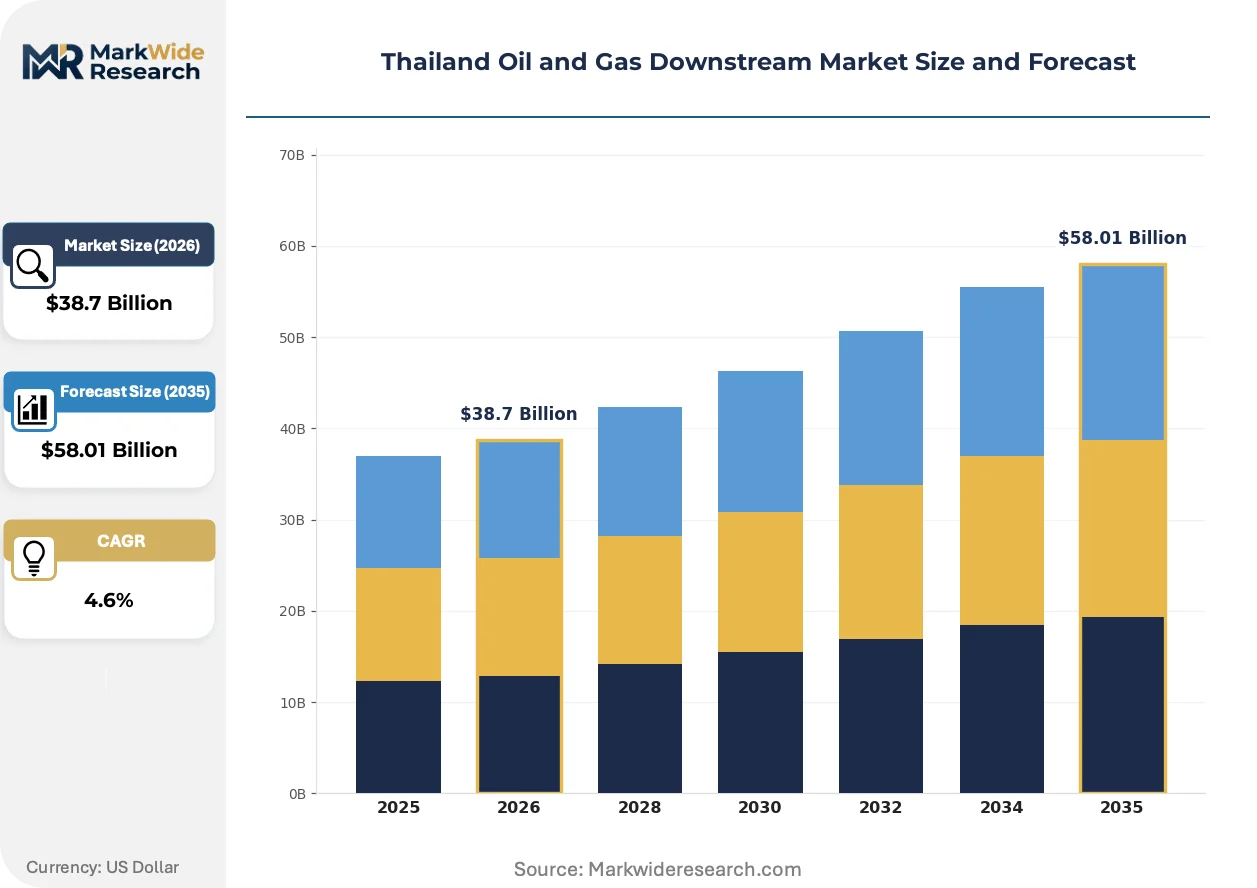
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $58.01 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Fuels, Petrochemicals, Lubricants, Specialty Chemicals End User: Transportation, Industrial, Residential, Commercial Distribution Channel: Direct Sales, Retail Outlets, Wholesale, Online Application: Automotive, Power Generation, Manufacturing, Aviation |
| Companies Covered | Star Petroleum Refining PCL, Royal Dutch Shell PLC, PTT Public Company Limited, TotalEnergies SE, SCG Chemicals Co Ltd, Bangchak Corporation PCL, IRPC Public Company Limited, ExxonMobil Corporation, Esso Thailand PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Oil and Gas Downstream Market Evolving Landscape
Digital instrumentation and alternative feedstock processing are compressing traditional refining economics while regulatory disclosure requirements reshape capital allocation priorities across Thailand's downstream value chain.
Residual fluid catalytic cracking is hybridizing with bio-oil co-processing to produce renewable diesel and sustainable aviation fuel from palm fatty acid distillate and used cooking oil. IRPC and Bangchak pilot units demonstrate commercial viability at ten to twenty percent renewable feedstock rates. This hybridization allows existing FCC infrastructure to generate compliance credits under emerging low-carbon fuel standards without full unit replacement.
Thailand's Board of Investment now conditions five-to-eight year tax holidays on verified emissions disclosures and energy efficiency benchmarks exceeding baseline refinery performance. The Ministry of Industry coordinates audit protocols with the Department of Energy Business to prevent greenwashing claims. Complex refineries with integrated petrochemical output face the steepest compliance thresholds given their absolute emission volumes.
Fleet operators in Bangkok and Laem Chabang port logistics are consolidating fuel procurement through direct refinery offtake contracts, bypassing traditional wholesale distributors. Large transport and construction companies negotiate formula pricing linked to Singapore spot benchmarks rather than posted retail differentials. This disintermediation compresses distributor margins while rewarding refiners with volume certainty and reduced working capital requirements.
Thailand Oil and Gas Downstream Market Segmentation
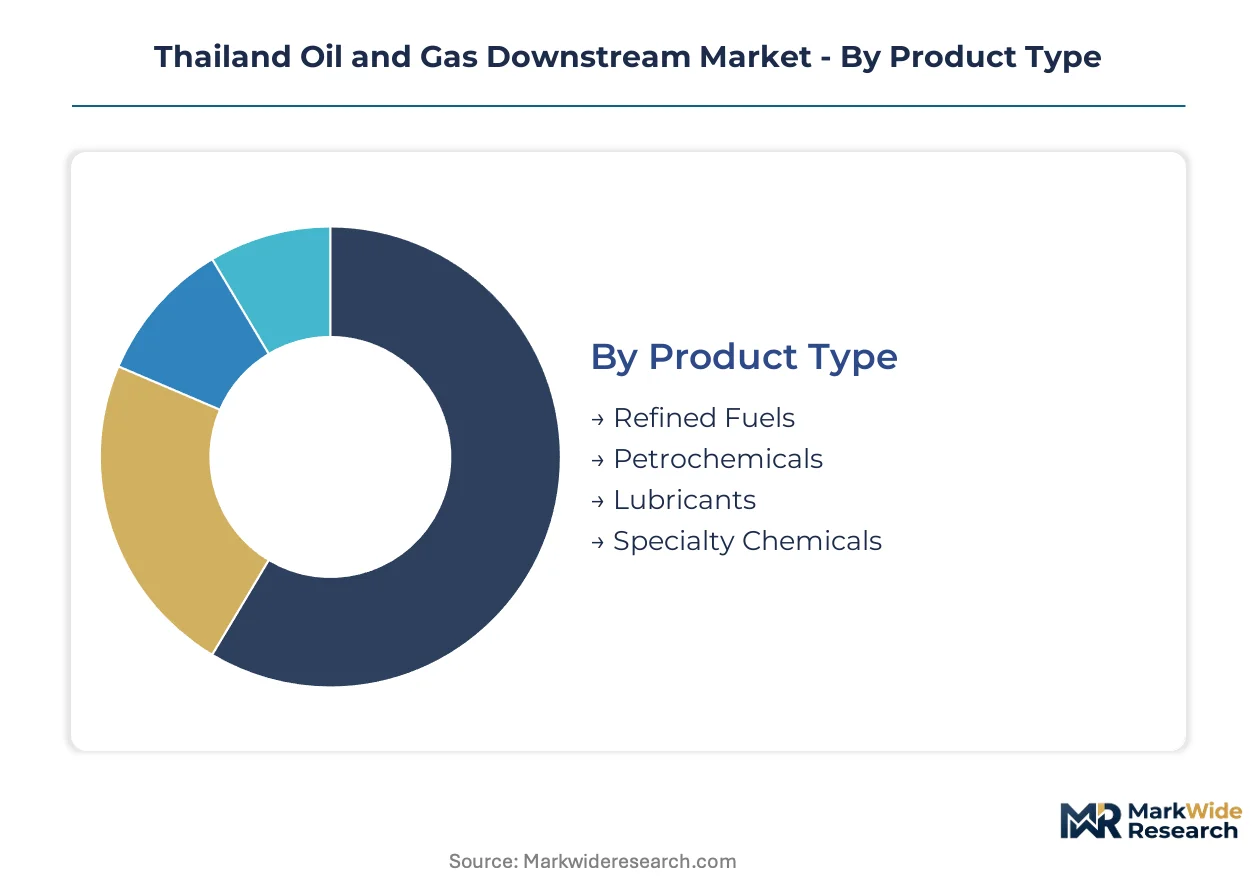
Segmentation in Thailand's downstream oil and gas market reveals how refinery complexity, petrochemical integration depth, and distribution infrastructure determine margin capture. Product slate flexibility and end-use concentration dictate capital allocation priorities across the Eastern Economic Corridor.
Product Type:
Refineries configure their conversion units around distinct output slates serving transportation fuel demand, polymer feedstock supply, and industrial process requirements.
- Refined Fuels:Atmospheric and vacuum distillation yields gasoline, diesel, and fuel oil fractions processed through hydrotreaters to meet Euro 5 sulfur specifications. Transportation fleets in Bangkok and Laem Chabang port logistics anchor offtake volumes, though electrification compresses gasoline demand growth trajectories.
- Petrochemicals:Steam crackers and catalytic reformers convert naphtha and LPG into ethylene, propylene, and aromatics for plastics and synthetic rubber manufacturing. SCG Chemicals Co Ltd and IRPC Public Company Limited concentrate derivative capacity in Rayong province to serve automotive and packaging resin demand.
- Lubricants:Base oil blending with additive packages produces engine oils and industrial lubricants for precision manufacturing sectors. Metalworking fluids for Thailand's electronics and automotive component suppliers command premium pricing over commodity fuel margins.
- Specialty Chemicals:Process solvents, catalysts, and refinery chemicals support downstream operations with formulation customization for specific unit operations. Small-batch production for hydrotreater catalyst regeneration and sulfur recovery units generates service revenue.
Established volume favors Refined Fuels; emerging adoption favors Petrochemicals as crackers displace standalone refinery expansions.
End User:
Demand concentration varies by fuel type and industrial application, with transport electrification reshaping historical consumption patterns.
- Transportation:Fleet operators and private vehicle owners consume gasoline, diesel, and biofuel blends through retail networks and direct refinery contracts. Bangkok's commercial vehicle electrification compresses diesel demand growth while sustainable aviation fuel trials at Suvarnabhumi Airport create new offtake channels.
- Industrial:Manufacturing facilities burn fuel oil and natural gas for process heat while purchasing naphtha and chemical feedstocks for polymer production. Eastern Economic Corridor integrated complexes achieve feedstock cost advantages through pipeline connectivity and shared utility infrastructure.
- Residential:LPG cylinders for cooking and heating dominate household energy consumption outside metropolitan natural gas distribution networks. Rural provinces rely on bottled gas distribution through PTT's retail footprint.
- Commercial:Hotels, hospitals, and retail complexes purchase diesel for backup generators and LPG for kitchen operations. Bangkok's commercial real estate sector negotiates bulk fuel contracts bypassing traditional wholesale intermediaries.
Transportation retains the largest volume share; Industrial captures expanding margin pools as chemical integration deepens.
Distribution Channel:
Channel selection reflects customer scale, product specification requirements, and working capital constraints across the value chain.
- Direct Sales:Large industrial buyers negotiate formula pricing linked to Singapore spot benchmarks for naphtha, fuel oil, and petrochemical feedstocks. Fleet operators and construction companies consolidate procurement through refinery offtake agreements reducing distributor margins.
- Retail Outlets:PTT and Bangchak operate branded service stations dispensing gasoline, diesel, and biofuel blends with convenience retail attachments. The nationwide network provides last-mile access for private vehicle owners and small commercial operators.
- Wholesale:Distributors aggregate volumes for industrial accounts, agricultural users, and remote commercial facilities lacking pipeline access. Margin compression from direct sales disintermediation pressures traditional wholesale operators.
- Online:Digital platforms for lubricant and specialty chemical ordering streamline procurement for small and mid-sized industrial accounts. E-commerce penetration remains limited for regulated fuel products requiring physical custody transfer.
Direct Sales is climbing the fastest as large buyers consolidate procurement; Retail Outlets maintains infrastructure dominance for consumer fuels.
Application:
End-use specifications determine product quality tiers and certification requirements across transport and industrial sectors.
- Automotive:Engine oils, transmission fluids, and gasoline/diesel fuels must meet Thailand Department of Energy Business quality specifications and OEM approval standards. Euro 5 compliance mandates hydrotreater investments affecting refinery yield structures.
- Power Generation:Fuel oil and diesel serve distributed generation and grid backup applications, particularly in industrial estates lacking natural gas pipeline access. Dual-fuel turbines capable of burning naphtha or fuel oil provide operational flexibility.
- Manufacturing:Process heat, chemical feedstocks, and metalworking fluids support Thailand's automotive, electronics, and food processing sectors. Precision manufacturing demands high-performance lubricant additives with local blending capacity capturing premium pricing.
- Aviation:Jet fuel specifications require dedicated hydrant systems and quality testing protocols at Suvarnabhumi and Don Mueang airports. Sustainable aviation fuel blending trials with renewable feedstocks address emerging low-carbon fuel standards.
Automotive commands the largest volume base; Aviation presents the steepest specification barriers for new market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's downstream consumption tilts toward petrochemical integration and biofuel blending, diverging from neighbors prioritizing export-oriented refining. The Eastern Economic Corridor absorbs disproportionate investment as integrated complexes replace standalone fuel production.
Rayong Province
Petrochemical crackers and aromatics units cluster along the eastern seaboard, drawing naphtha feedstock through PTT's pipeline network. Thailand's Board of Investment conditions tax holidays on emissions disclosures exceeding baseline refinery performance. The Map Ta Phut industrial estate anchors derivative capacity for automotive and packaging resins.
Chonburi Province
Laem Chabang port logistics drive direct refinery offtake contracts from fleet operators bypassing wholesale distributors. The Department of Energy Business enforces Euro 5 sulfur specifications compelling hydrotreater investments. Eastern Seaboard development zones concentrate biofuel blending infrastructure for biodiesel and ethanol mandates.
Bangkok Metropolitan Region
Commercial vehicle electrification compresses gasoline demand growth while sustainable aviation fuel trials at Suvarnabhumi Airport create new offtake channels. The Ministry of Industry coordinates audit protocols with energy regulators to prevent greenwashing claims. PTT and Bangchak operate branded retail networks providing last-mile fuel access.
Saraburi Province
Cement and construction material manufacturers consume fuel oil and diesel for process heat and distributed generation. The country's national energy regulator mandates fuel quality specifications aligned with emission standards. Industrial estates lacking natural gas pipeline access rely on dual-fuel turbine flexibility burning naphtha or fuel oil.
Songkhla Province
Southern Thailand's logistics corridor serves rubber processing and palm oil crushing facilities feeding biofuel blending requirements. The Board of Investment steers capital toward hydrotreating upgrades rather than greenfield refinery construction. Hat Yai's industrial zone attracts agricultural processors gaining offtake certainty through compulsory blending floors.
Thailand Oil and Gas Downstream Market Competitive Landscape
Capability concentration sits with integrated petrochemical operators; scale advantage sits with nationwide pipeline and retail network owners. The sector structures around three tiers: state-linked energy conglomerates with downstream-to-chemical integration, international majors with trading and technology licensing positions, and domestic specialists with biofuel or aromatics focus. Dominant competitive moves include refinery complexity upgrades for Euro 5 compliance and circular feedstock integration for plastic waste pyrolysis.
Within the integrated conglomerate tier, PTT Public Company Limited and SCG Chemicals Co Ltd exemplify state-linked operators leveraging captive infrastructure and petrochemical derivative capacity. Bangchak Corporation PCL occupies a position among domestic specialists prioritizing biofuel blending investments and renewable feedstock trials. These three entities represent distinct strategic archetypes: pipeline-retail scale, chemical integration depth, and alternative fuel specialization.
| Leading Market Players |
|---|
| Star Petroleum Refining PCL |
| Royal Dutch Shell PLC |
| PTT Public Company Limited |
| TotalEnergies SE |
| SCG Chemicals Co Ltd |
| Bangchak Corporation PCL |
| IRPC Public Company Limited |
| ExxonMobil Corporation |
| Esso Thailand PLC |
| Others |
Value Network & Pricing Analysis
Middle Eastern crude term contracts supplying over ninety percent of Thai refinery feedstock concentrate pricing power with upstream exporters, leaving downstream operators to capture margin through complexity upgrades and petrochemical integration rather than feedstock cost control. This upstream concentration forces refiners to compete on yield optimization and product slate flexibility, with margin pools migrating toward aromatics and polyolefin derivatives that command premium over commodity fuels.
Pricing Analysis
Long-term offtake contracts linked to Singapore spot benchmarks dominate naphtha and fuel oil transactions, while retail gasoline and diesel prices track government-notified ceilings adjusted periodically by the Department of Energy Business. Price differentiation rests on sulfur compliance grades and volume scale, with Euro 5-certified products capturing premium over Euro 4 equivalents. Cost compression in gasoline hydrotreating is intensifying because electrification compresses demand growth, stranding units without cracker co-location. Fleet operators with direct refinery contracts exhibit lowest price sensitivity; rural LPG distributors face highest pressure from working capital constraints.
Supply Chain Analysis
Tariff exposure between Middle Eastern suppliers and Thai refiners dominates supply chain risk management, with freight rate volatility compounding landed cost uncertainty for term crude cargoes. Geographic supply concentration centers on Saudi Arabia, Kuwait, and the UAE, with limited diversification into African or Latin American grades due to refinery configuration constraints. Raw material dependencies rest on atmospheric residue for coker feedstock, naphtha for steam crackers, and natural gas liquids for LPG recovery. Single-source vulnerability characterizes catalyst supply for hydrotreater units. Distribution runs through PTT's pipeline network to Eastern Economic Corridor complexes, with coastal tanker discharge at Map Ta Phut and Sri Racha anchoring import logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as electrification and biofuel mandates splinter historical fuel demand into specialty chemical and circular feedstock niches. This demand-side shift creates openings for operators with flexible cracking capacity and alternative feedstock processing capabilities.
For Market Incumbents: Harden refinery resilience through hydrotreater-coker integration that preserves gasoline yield while expanding petrochemical feedstock output. Secure backward integration into palm fatty acid distillate supply chains to anchor renewable diesel and sustainable aviation fuel trials. Electrification substitution represents the core threat; feedstock flexibility is the critical defensive lever.
For New Entrants and Emerging Players: Pursue circular feedstock processing as the most penetrable white-space target, specifically pyrolysis oil offtake agreements with Map Ta Phut aromatics producers. Target specialty lubricant additives for precision manufacturing in Bangkok's electronics and automotive component sectors. A certification-first go-to-market angle leveraging Board of Investment emissions disclosure requirements unlocks project finance structures unavailable to commodity fuel competitors.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated refining-chemical complexes with demonstrated bio-oil co-processing capability and established Eastern Economic Corridor infrastructure access. Long-term viability in this sector hinges on asset flexibility across the energy transition horizon. The signal to watch is sustainable aviation fuel offtake commitment depth from Suvarnabhumi Airport logistics operators, indicating policy-driven demand creation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Refinery Complexity Upgrade | Hydrotreater investments satisfy Department of Energy Business Euro 5 mandates while preserving gasoline yield. |
| Bio-oil Co-processing Expansion | Hybrid FCC units at IRPC and Bangchak demonstrate commercial viability for renewable diesel and SAF production. |
| Circular Feedstock Integration | Pyrolysis oil offtake agreements with aromatics producers preempt EU border carbon adjustment exposure. |
| Carbon Capture Retrofitting | Board of Investment emissions disclosure incentives create project finance structures for refinery CCS installations. |
| Specialty Chemical Capacity Buildout | Local lubricant additive blending captures premium pricing from Bangkok precision manufacturing demand. |
Research Methodology
A spread of perspectives from refinery operations managers, petrochemical procurement leads at SCG Chemicals and IRPC, downstream distribution channel partners, and Board of Investment project approval officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through Thailand Department of Energy Business fuel quality filings, customs import records for crude and naphtha, and SEC disclosures from PTT, Bangchak, and IRPC. Bottom-up capacity and utilization estimates triangulated against top-down demand projections from transportation fleet operators and Eastern Economic Corridor industrial estate developers.
Demand-supply balance modeling across the analysis window incorporated refinery complexity indices, cracker feedstock slates, and biofuel blending mandate trajectories. Segmentation dimensions included product type, end-use sector, distribution channel, and regional production hub concentration. CAGRs were derived from trend extrapolation of historical utilization rates adjusted for announced capacity additions and regulatory phase-in schedules. Industry-specific forecast inputs encompassed electric vehicle adoption curves in Bangkok commercial fleets and sustainable aviation fuel trial scale-up timelines at Suvarnabhumi Airport.
Macroeconomic conditions sit as an overlay; deviation in crude price volatility, freight rate spikes, or baht-dollar exchange rate movements would shift the trajectory of refinery margin projections and capital commitment timelines. Forecasts reflect documented assumptions regarding policy continuity for biofuel mandates and Euro 5 enforcement stringency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
South Sudan Oil and Gas Upstream Market
Offshore Oil and Gas
Norway Oil and Gas EPC Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
Africa Oil and Gas Downstream Market
Offshore Oil and Gas
North America Floating Offshore Wind Power Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market