
 Europe Next Generation Storage Market | 2026-2036
Europe Next Generation Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Next Generation Storage Market Foresight
Cloud computing is decoupling from traditional on-premise enterprise storage across European utilities and financial services. Dell Technologies leverages its server-storage convergence portfolio to anchor large institutional deployments across Frankfurt and Amsterdam. Samsung Electronics sustains NAND flash supply leadership that feeds downstream solid-state assembly for regional OEMs. Pure Storage differentiates through all-flash array architectures purpose-built for cloud-native workloads.
Europe next generation storage encompasses solid-state, hard disk, hybrid, and cloud architectures engineered for sub-millisecond latency, petabyte-scale capacity, and automated tiering across edge-to-core pipelines. NVMe-over-fabrics protocols now deliver throughput exceeding six gigabytes per second per controller, enabling real-time analytics pipelines for automotive telemetry and pharmaceutical simulation. Solid state drives command the fastest expansion trajectory as datacenter operators retire mechanical disks to meet EU energy efficiency directives. Cloud storage segments accumulate margin pools through subscription revenue models, while hybrid drives retain niche positions in cost-sensitive archival tiers.
The EU Green Deal and Ecodesign for Sustainable Products Regulation impose binding energy efficiency thresholds on storage hardware deployed across member states. EMA data integrity requirements for pharmaceutical batch records mandate immutable object storage with cryptographic chain-of-custody verification. REACH compliance on rare earth elements in NAND flash controllers shapes supplier qualification timelines and sourcing geography. Stakeholders must monitor how the EU AI Act's training data retention rules will reshape capacity planning for machine learning infrastructure.
Market Dynamics
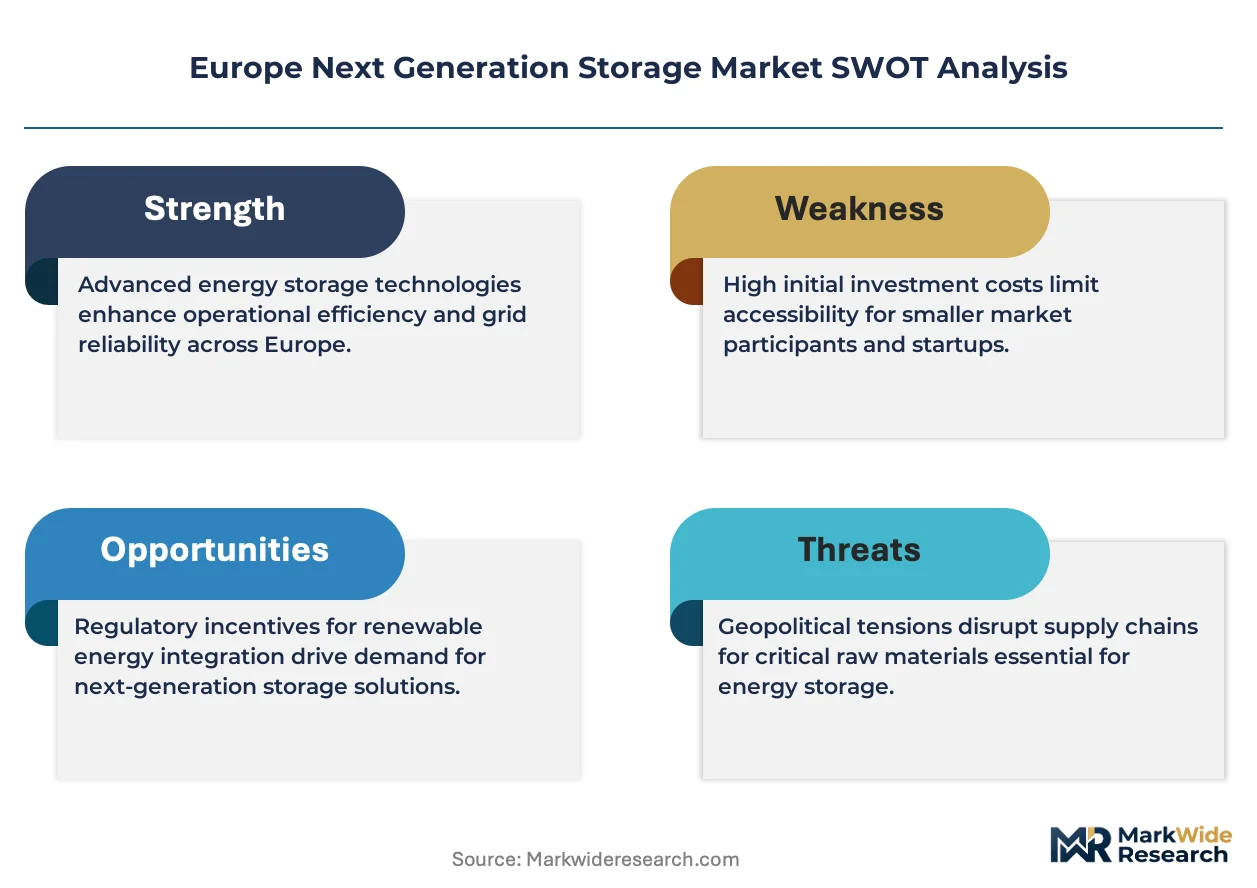
NVMe-over-fabrics deployment is compressing storage latency thresholds across European pharmaceutical and automotive verticals, while the EU Green Deal's binding efficiency mandates force synchronous hardware refresh cycles that bypass traditional depreciation schedules.
Growth Catalysts
- EU Green Deal Ecodesign Mandates:Binding energy efficiency thresholds for data infrastructure are forcing datacenter operators in Germany and France to accelerate flash-based storage replacements ahead of mechanical disk end-of-life.
- Automotive Telemetry Pipelines:Real-time analytics requirements for connected vehicle fleets in Stuttgart and Wolfsburg are driving petabyte-scale NVMe array deployments with sub-millisecond latency specifications.
- EMA Data Integrity Requirements:Immutable object storage with cryptographic chain-of-custody verification is now mandatory for pharmaceutical batch records across European manufacturing sites.
Market Restraints
- NAND Flash Supply Concentration:Controller fabrication and rare earth element processing concentrate in East Asian supply chains, exposing European OEMs to REACH compliance delays and qualification timeline extensions.
- CAPEX Intensity of All-Flash Arrays:Per-terabyte capital requirements for enterprise solid-state deployments remain four to six times higher than hybrid alternatives, constraining adoption at mid-tier datacenter operators.
- Technical Limitation of QLC Endurance:Quad-level cell NAND's reduced write cycle tolerance limits its deployment to read-heavy archival tiers, segmenting addressable workload pools.
Strategic Opportunities
- Edge-to-Core Pipeline Convergence:Automated tiering architectures that synchronize NVMe performance at core with object storage at edge nodes are capturing new workloads in Dutch logistics hubs and Nordic renewable energy monitoring.
- EU AI Act Training Data Retention:Emerging machine learning infrastructure mandates will reshape capacity planning for hyperscale cloud regions clustered in Frankfurt, Amsterdam, and Dublin.
- Subscription Revenue Models:Cloud storage segments are accumulating margin pools through consumption-based pricing that displaces traditional capital procurement cycles in financial services.
Industry Challenges
- Integration Complexity with Legacy SAN:Fibre Channel and iSCSI infrastructure at European banks and insurers requires costly protocol bridging to adopt NVMe-over-TCP without forklift upgrades.
- Skill Scarcity in Computational Storage:Shortage of engineers proficient in in-situ data processing and near-memory compute architectures is delaying deployment timelines for advanced analytics workloads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Next Generation Storage Market |
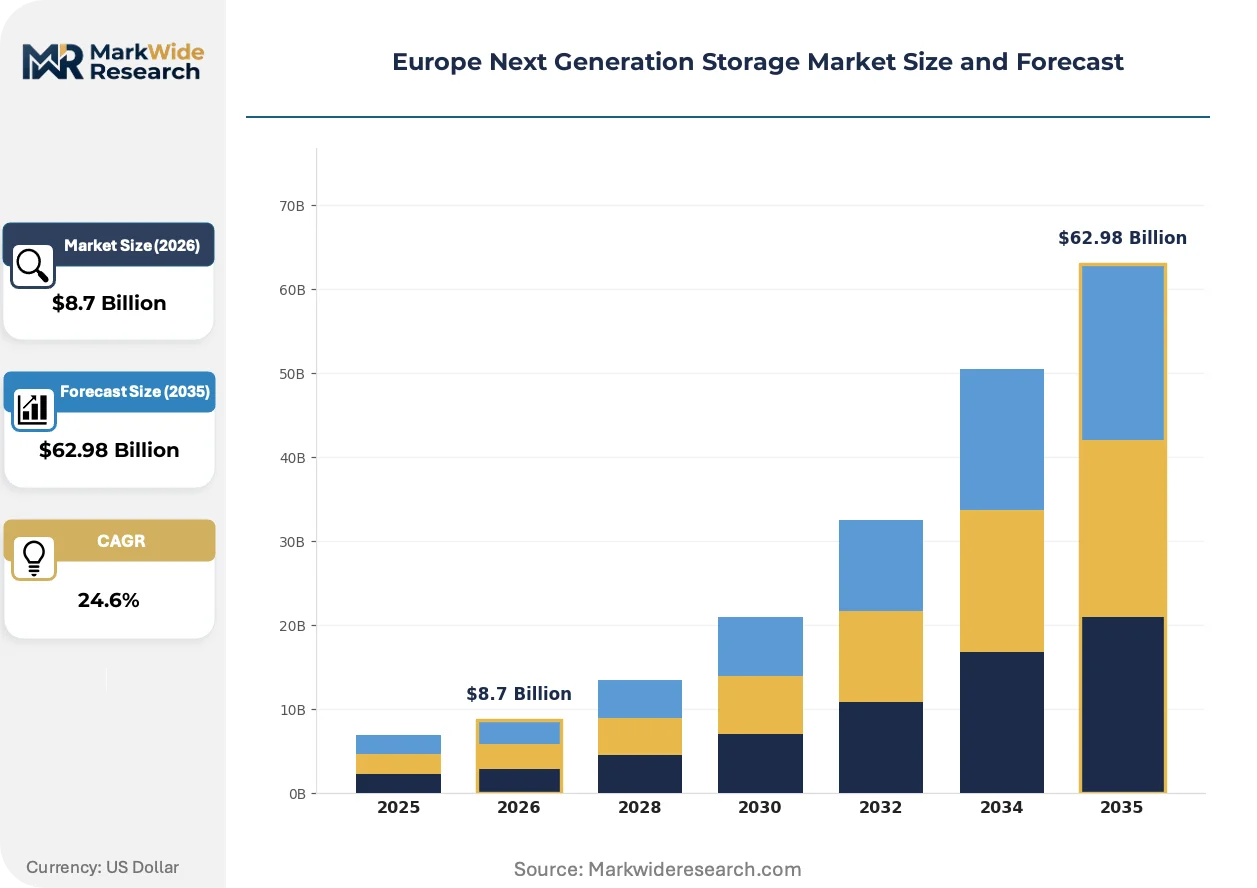
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State Drives, Hard Disk Drives, Hybrid Drives, Cloud Storage Use Case: Data Backup, Cloud Computing, Virtualization, Big Data Analytics Technology: NVMe, SATA, SCSI, Object Storage End User: IT Services, Telecom, Healthcare, Education |
| Companies Covered | NetApp, Toshiba Corporation, Dell Technologies, Samsung Electronics, Hitachi Vantara, Hewlett Packard Enterprise, Pure Storage, Western Digital Corporation, IBM, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Next Generation Storage Market Shifts & Advancements
Computational storage architectures and software-defined disaggregation are compressing traditional hardware refresh cycles. European operators now prioritize energy-adjusted performance metrics over raw throughput specifications.
Computational storage drives with integrated processing units are rewriting the economics of data-intensive workloads. Pharmaceutical simulation clusters in Basel and Cambridge are adopting these devices to reduce data movement overhead. The technology is compressing analytics pipeline latencies by executing filter and aggregation operations at the storage layer rather than the host CPU.
The EU AI Act's training data retention provisions are mandating immutable storage with audit-grade provenance tracking. Cloud operators in Frankfurt and Amsterdam are rearchitecting object storage tiers to support cryptographic verification chains. Financial services and healthcare verticals face the steepest compliance timelines, with immutable bucket configurations now specified in procurement requirements.
Consumption-based procurement models are displacing traditional capital expenditure cycles for storage infrastructure. Hyperscale cloud regions in the Netherlands and Ireland are capturing enterprise workloads previously hosted in on-premise datacenters. Utilities and regional banks are the most visible adopters, with operational expenditure accounting now preferred over depreciation schedules for capacity expansion decisions.
Europe Next Generation Storage Market Segmentation
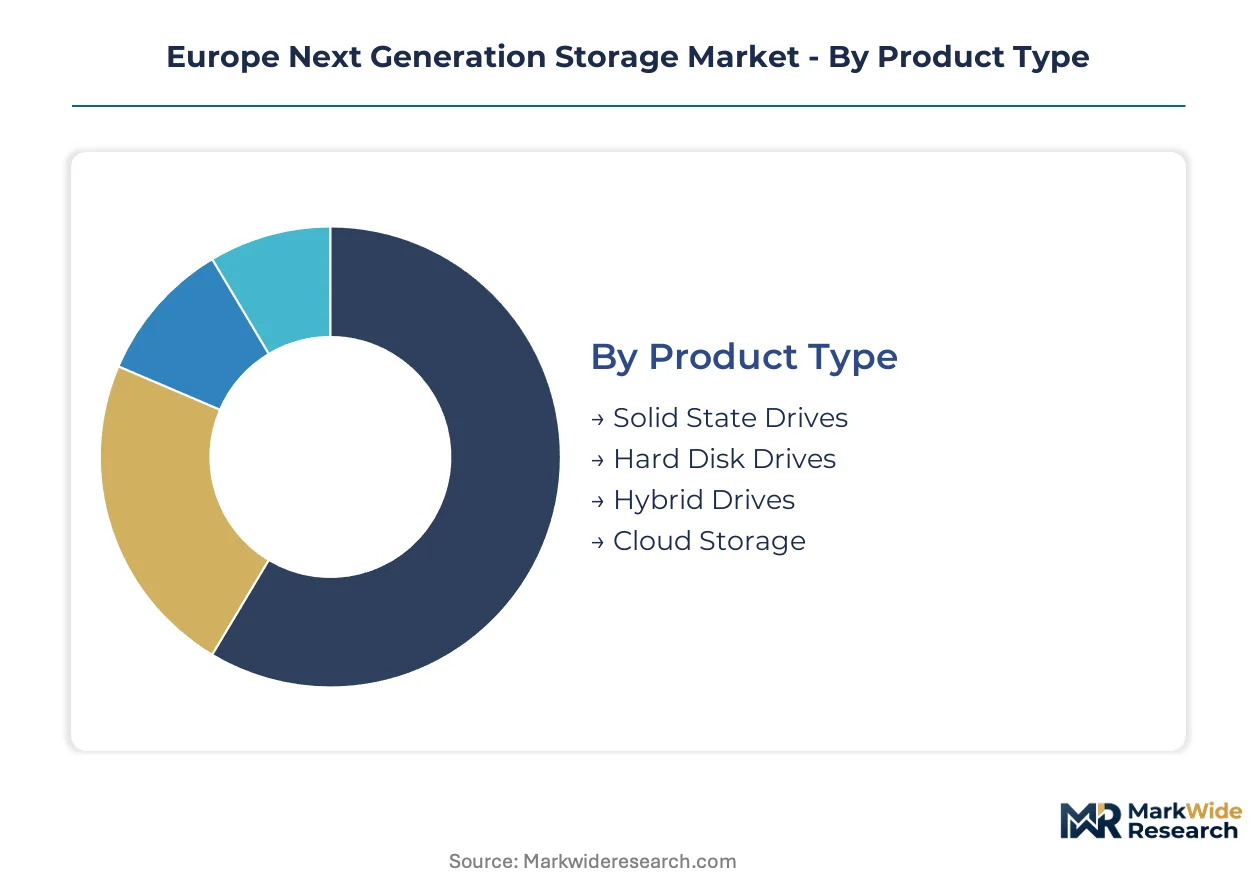
Segmentation in Europe's next generation storage market reveals how procurement priorities diverge across workload characteristics and compliance obligations. Product architecture choices now hinge on energy-adjusted performance metrics mandated by EU Ecodesign regulations, while use case segmentation exposes where cloud-native displacement is most advanced.
Product Type:
Standardization dominates at the high-performance tier where NVMe protocols have consolidated interface specifications, while customization persists in hybrid configurations balancing cost and latency requirements.
- Solid State Drives:Flash-based architectures with NAND cell densities ranging from TLC to QLC configurations deliver sub-millisecond access times. German automotive manufacturers in Stuttgart and Wolfsburg are deploying petabyte-scale NVMe arrays for real-time telemetry processing, driven by EU Green Deal mandates accelerating mechanical disk retirement.
- Hard Disk Drives:Rotating magnetic media continue serving sequential read workloads at the lowest per-terabyte acquisition cost. Mid-tier datacenter operators in France retain HDDs for archival tiers where latency tolerance accommodates mechanical seek times, constrained by binding efficiency thresholds that compress depreciation schedules.
- Hybrid Drives:Integrated flash-cache and spinning disk combinations occupy niche positions in cost-sensitive edge deployments.
- Cloud Storage:Subscription-based object and block services are displacing capital procurement cycles across European financial services.
Leading the category by volume: Hard Disk Drives. Growing fastest: Solid State Drives.
Use Case:
Volume concentration tracks data gravity patterns, with cloud computing workloads clustering in Frankfurt and Amsterdam hyperscale regions while big data analytics distributes across pharmaceutical and automotive research sites.
- Data Backup:Immutable object storage with cryptographic verification chains satisfies EMA data integrity requirements for pharmaceutical batch records. Basel and Cambridge manufacturing sites are mandating these configurations for audit-grade provenance tracking, driven by regulatory compliance timelines.
- Cloud Computing:Hyperscale regions in the Netherlands and Ireland capture enterprise workloads through consumption-based pricing models. Utilities and regional banks prefer operational expenditure accounting, displacing on-premise depreciation schedules.
- Virtualization:Consolidated server-storage convergence demands low-latency block storage for mixed workload consolidation.
- Big Data Analytics:Computational storage architectures with in-situ processing reduce data movement overhead in simulation clusters.
Cloud Computing commands the largest revenue pool. Big Data Analytics shows the steepest expansion trajectory as AI training data retention rules reshape capacity planning.
Technology:
Interface protocol selection determines performance ceilings and integration complexity with legacy Fibre Channel infrastructure at European banks and insurers.
- NVMe:PCIe-based command sets deliver throughput exceeding six gigabytes per second per controller. Dutch logistics hubs and Nordic renewable energy monitoring sites are adopting NVMe-over-fabrics for edge-to-core pipeline convergence, driven by real-time analytics requirements.
- SATA:Legacy interface protocol retains position in cost-optimized bulk storage where bandwidth demands remain modest.
- SCSI:Parallel and serial variants persist in enterprise SAN environments requiring protocol bridging for NVMe migration.
- Object Storage:Flat namespace architectures with erasure coding optimize for petabyte-scale capacity and geographic distribution.
NVMe leads technology investment. Object Storage is climbing the fastest on AI Act training data retention mandates.
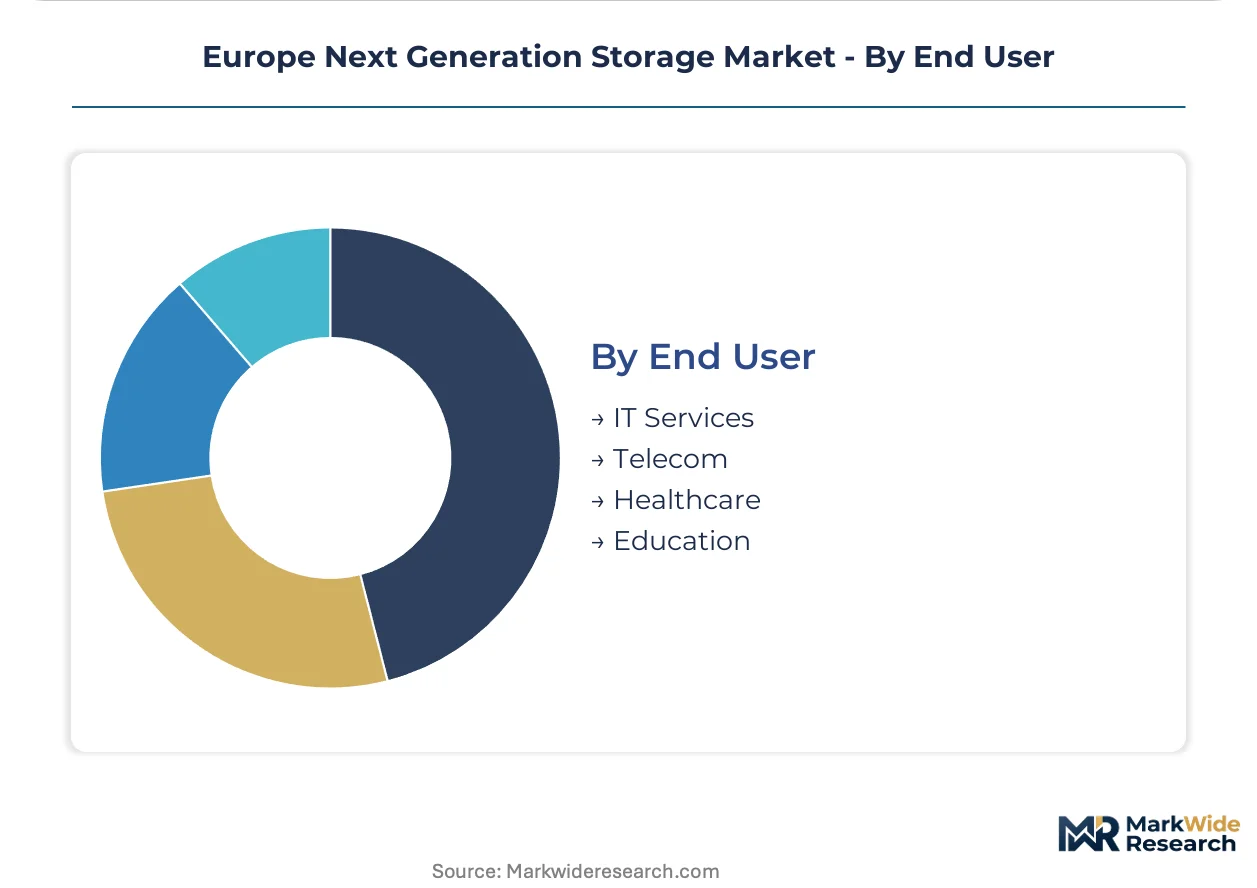
End User:
Margin structure varies by vertical compliance intensity, with healthcare and IT services facing the steepest data sovereignty and retention requirements.
- IT Services:Managed service providers and systems integrators aggregate demand across mid-market enterprises. Frankfurt-based colocation operators are standardizing all-flash architectures for multi-tenant cloud delivery, responding to hyperscale competitive pressure.
- Telecom:5G core network functions and edge computing infrastructure drive distributed storage deployments. French and German carriers are consolidating subscriber data management on NVMe platforms, constrained by latency specifications for network slicing.
- Healthcare:Hospital systems and research institutions require immutable storage for diagnostic imaging and genomic datasets.
- Education:University research clusters and national supercomputing centers prioritize price-performance for simulation workloads.
IT Services generates the largest addressable demand. Healthcare is expanding most quickly on EMA data integrity enforcement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of NAND flash controllers and rare earth processing concentrates in East Asian supply chains, while consumption clusters in German automotive hubs and Dutch hyperscale regions. European datacenter operators source finished storage systems through regional distribution channels anchored in Frankfurt and Amsterdam.
Germany
Automotive telemetry pipelines in Stuttgart and Wolfsburg drive petabyte-scale NVMe array procurement for connected vehicle fleets. The EU Green Deal's Ecodesign mandates accelerate mechanical disk retirement schedules across Bavarian manufacturing sites. Frankfurt's hyperscale cloud region anchors continental demand for all-flash enterprise storage.
Netherlands
Dutch logistics hubs and port automation systems require edge-to-core pipeline convergence with automated tiering architectures. REACH compliance on rare earth elements in NAND controllers extends supplier qualification timelines for Rotterdam-based systems integrators. Amsterdam's cloud region captures financial services workloads migrating from London post-Brexit.
France
French carriers consolidate 5G core network functions on NVMe platforms to meet latency specifications for network slicing. The Ecodesign for Sustainable Products Regulation imposes binding efficiency thresholds on storage hardware deployed at Île-de-France datacenters. Parisian pharmaceutical manufacturers adopt immutable object storage for EMA-mandated batch record integrity.
United Kingdom
Cambridge pharmaceutical simulation clusters deploy computational storage architectures to reduce data movement overhead in molecular modeling workloads. UK financial regulators align with emerging EU AI Act provisions on training data retention, reshaping capacity planning for London-based machine learning infrastructure. Scottish renewable energy monitoring sites adopt NVMe-over-fabrics for real-time grid analytics.
Ireland
Hyperscale cloud operators in Dublin rearchitect object storage tiers to support cryptographic verification chains for AI training data provenance. Irish datacenter expansion concentrates in the Greater Dublin Area, constrained by national grid capacity allocation for energy-intensive facilities. Cork-based pharmaceutical manufacturing sites implement immutable storage configurations ahead of EMA compliance deadlines.
Europe Next Generation Storage Market Competitive Landscape
Top-tier vendors anchor hyperscale cloud and enterprise datacenter deployments, while mid-tier specialists occupy niche positions in edge computing and computational storage. The vendor base stratifies across three tiers: integrated infrastructure conglomerates with server-storage convergence portfolios, pure-play flash array architects, and component suppliers controlling NAND fabrication. Two dominant competitive moves define current positioning: strategic partnerships between systems vendors and cloud operators to secure hyperscale allocations, and portfolio diversification into software-defined disaggregation to bypass hardware refresh cycle compression.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify server-storage convergence strategies that capture large institutional deployments. Pure Storage occupies a position as the flash-native architect purpose-built for cloud-native workloads. Samsung Electronics anchors the component supply tier through NAND fabrication leadership that feeds downstream assembly networks.
| Leading Market Players |
|---|
| NetApp |
| Toshiba Corporation |
| Dell Technologies |
| Samsung Electronics |
| Hitachi Vantara |
| Hewlett Packard Enterprise |
| Pure Storage |
| Western Digital Corporation |
| IBM |
| Others |
Supply & Pricing Matrix
NAND flash spot price indices cascade through controller fabrication and module assembly stages before crystallizing into three distinct procurement tiers for European datacenter operators. REACH compliance timelines on rare earth elements extend supplier qualification windows, compressing margin pools at mid-tier OEMs while hyperscale cloud operators leverage volume scale to extract preferential contract terms.
Pricing Analysis
Cost-down pressure on all-flash arrays accelerates because EU Ecodesign mandates are forcing synchronous hardware refresh cycles ahead of traditional depreciation schedules. Pricing stratifies across premium NVMe-over-fabrics configurations, standard TLC-based enterprise SSDs, and economy-tier QLC archival storage, with differentiation resting on latency specifications and endurance ratings. Margin tightening in mid-tier hybrid arrays reflects buyer migration toward subscription-based cloud storage models. Financial services procurement committees exhibit the highest price sensitivity due to operational expenditure accounting preferences, while automotive manufacturers in Stuttgart and Wolfsburg prioritize sub-millisecond performance over per-terabyte acquisition cost.
Supply Chain Analysis
Container freight rates from South Korean and Taiwanese fabrication hubs to Rotterdam and Hamburg directly influence landed cost structures for finished storage systems. Controller fabrication and rare earth element processing concentrate in South Korea, Taiwan, and Japan, with European OEMs sourcing NAND wafers and DRAM modules from these supply nodes. Single-source vulnerability in advanced node controller production exposes qualification timelines to ECHA regulatory delays. Distribution runs through Frankfurt and Amsterdam logistics hubs serving hyperscale cloud regions and enterprise datacenter operators across Germany, France, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's next generation storage market sits in a technology-transition phase as NVMe-over-fabrics protocols displace legacy Fibre Channel and iSCSI infrastructure at continental banks and insurers. Flash-based architectures are systematically replacing mechanical disks across German automotive and French pharmaceutical verticals.
For Market Incumbents: Deploy software-defined disaggregation architectures to bypass hardware refresh cycle compression caused by EU Green Deal efficiency mandates. Deepen backward integration into NAND flash supply through strategic allocations from South Korean fabrication partners. Anchor multi-year service contracts with Frankfurt and Amsterdam hyperscale operators to defend against pure-play flash array specialists. For New Entrants and Emerging Players: Launch via edge-to-core pipeline convergence offerings targeting Dutch logistics hubs and Nordic renewable energy monitoring sites where automated tiering architectures remain underpenetrated. Capture computational storage workloads in Basel and Cambridge pharmaceutical simulation clusters where in-situ processing capability scarcity delays incumbent deployment timelines. Prioritize consumption-based pricing models to align with financial services operational expenditure preferences. For Investors and Strategic Acquirers: The window for entry favors component suppliers with captive NAND fabrication and established REACH compliance pathways. Long-term viability rests on positioning for EU AI Act training data retention mandates that will reshape capacity planning across hyperscale regions. Monitor EMA data integrity enforcement timelines as the inflection signal for immutable object storage demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| NVMe-over-Fabrics Deployment | Sub-millisecond latency specifications capture automotive telemetry workloads in Stuttgart and Wolfsburg. |
| Software-Defined Disaggregation | Storage-compute separation architectures bypass synchronous refresh cycles imposed by EU Ecodesign mandates. |
| Immutable Object Storage Configuration | Cryptographic chain-of-custody verification satisfies EMA batch record requirements for Basel manufacturing sites. |
| Edge-to-Core Pipeline Convergence | Automated tiering architectures synchronize NVMe performance with Dutch logistics hub operational requirements. |
| Consumption-Based Pricing Transition | Subscription revenue models align with financial services operational expenditure accounting preferences post-Brexit. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe next generation storage market analysis. Primary interviews with datacenter procurement directors, storage systems engineers, and cloud infrastructure planners combined with ECHA REACH documentation, EU Green Deal implementation guidance, and hyperscale operator capex disclosures. Bottom-up shipment data from NAND module assemblers and top-down revenue estimates from systems vendors were triangulated to validate segment sizing.
Data-stream reconciliation across volume shipments, average selling prices, and installed base depreciation schedules informed the analytical framework. Segmentation dimensions modeled include product architecture, interface protocol, deployment model, end-use vertical, and geographic demand cluster. CAGRs were derived from fitted growth curves applied to technology substitution rates and regulatory compliance timelines. Forecast inputs incorporated EU AI Act training data retention provisions and EMA data integrity enforcement schedules.
Supply chain disruption, regulatory timeline acceleration, and technology transition velocity are the dominant revision risks for projections across the analysis window. Forecasts reflect documented assumptions on NAND flash price trajectories and hyperscale cloud region expansion plans. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Storage
SSD Controller Market
Data Storage
North America AMH and Storage Systems Market
Data Storage
Universal Flash Storage Market
Data Storage
Data Storage Devices Market
Data Storage
Electrochromic Storage Devices Market
Data Storage
Tape Storage Market
Data Storage
North America SSD Caching Market
Data Storage
NAND Flash Market
Data Storage
External Storage Market
Data Storage
Powered Storage Devices Market
Data Storage
Global Digital Storage Devices Market
Data Storage
Flash-Based Array Market
Data Storage
USB Key Market
Data Storage
Distributed Storage System Market
Data Storage
China Solid-State Drive Market
Data Storage
Hybrid Flash Storage Market