
 Electric Submersible Cables (ESP) Market | 2026-2036
Electric Submersible Cables (ESP) Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Submersible Cables (ESP) Market Intelligence
The integration of fiber optic sensors for downhole monitoring within the power cable itself is fragmenting the traditional product architecture. Schlumberger Limited leverages its extensive oilfield services network to deploy these advanced, data-enabled cable systems. Prysmian Group competes by specializing in the development of high-specification composite cables for harsh subsea environments. Baker Hughes differentiates through its portfolio of integrated artificial lift solutions, where the ESP cable is a critical component.
Electric Submersible Cables are specialized multi-conductor power cables designed to supply electricity to downhole submersible pumps. Their construction often includes steel armor and insulation materials like Ethylene Propylene Rubber (EPR) to withstand extreme downhole conditions. Armored cable types represent the largest segment due to durability needs in oil extraction applications. Within insulation materials, demand for high-temperature EPR is outpacing other options for deep and unconventional wells.
A framework of ISO standards and American Petroleum Institute (API) recommended practices governs product design and safety. In Europe, ATEX directives are critical for market access, mandating specific protections for equipment in explosive atmospheres. Future investment decisions will hinge on balancing the cost of advanced insulation materials against performance gains required for challenging ultra-deepwater and high-temperature well environments.
Market Dynamics
The market's central dynamic is the relentless push into deeper, hotter, and more complex wellbores. This drive, particularly in unconventional and offshore reservoirs, necessitates continuous innovation in cable materials and construction to withstand extreme operational pressures and temperatures.
Growth Catalysts
- Unconventional Resource Development:Sustained investment in shale and tight oil plays, especially in the Permian Basin of the United States, requires a high volume of ESP systems and associated cables for artificial lift.
- Material Science Advances:The development of enhanced Ethylene Propylene Rubber (EPR) and other high-temperature insulation compounds enables ESP cables to operate reliably in downhole environments exceeding standard temperature ratings.
- Brownfield Optimization:Efforts to maximize recovery from mature oilfields in regions like the North Sea and Southeast Asia are driving demand for ESP system retrofits, including upgraded, more durable power cables.
Market Restraints
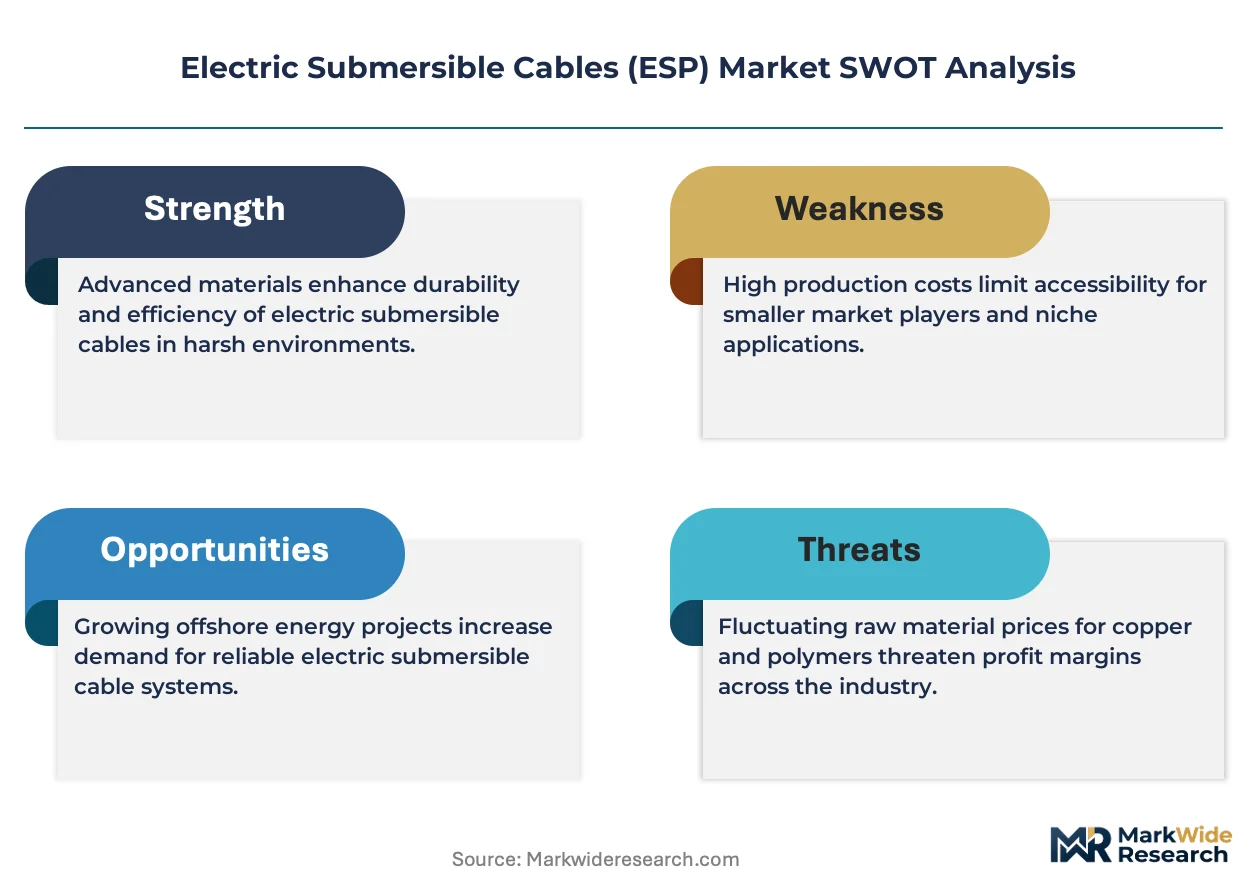
- Raw Material Volatility:Price fluctuations in essential commodities, particularly copper for conductors and specialized steel alloys for armor, create significant cost uncertainty and margin pressure for cable manufacturers.
- Technical Performance Limits:In ultra-long horizontal wells, voltage drop and signal degradation over extended cable lengths can impair pump performance and limit the effectiveness of integrated monitoring systems.
- Strict Compliance Regimes:Adherence to rigorous standards like the American Petroleum Institute (API) recommended practices and Europe's ATEX directives adds substantial cost and time to product development and certification.
Strategic Opportunities
- Integrated Sensing Technologies:Embedding fiber optic sensors within the cable structure offers a new value proposition, providing real-time distributed temperature and acoustic data for enhanced reservoir management.
- Geothermal Energy Expansion:The growing geothermal sector in countries like Indonesia and Turkey presents a new market for high-temperature submersible cables, leveraging technology originally developed for oil and gas.
- Carbon Sequestration Projects:The deployment of Carbon Capture, Utilization, and Storage (CCUS) initiatives requires robust downhole equipment, including ESP cables, for powering injection pumps and monitoring well integrity.
Industry Challenges
- Specialized Labor Scarcity:A shortage of field service technicians skilled in the installation, splicing, and troubleshooting of advanced, sensor-enabled ESP cables can lead to project delays and operational failures.
- Qualification and Testing Costs:The high capital investment needed to build test facilities and conduct rigorous qualification programs for new cable designs under simulated downhole conditions is a barrier to entry.
- System Interoperability:Ensuring seamless integration between sensor-equipped cables and various third-party surface control units and data platforms remains a significant technical hurdle for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Submersible Cables (ESP) Market |
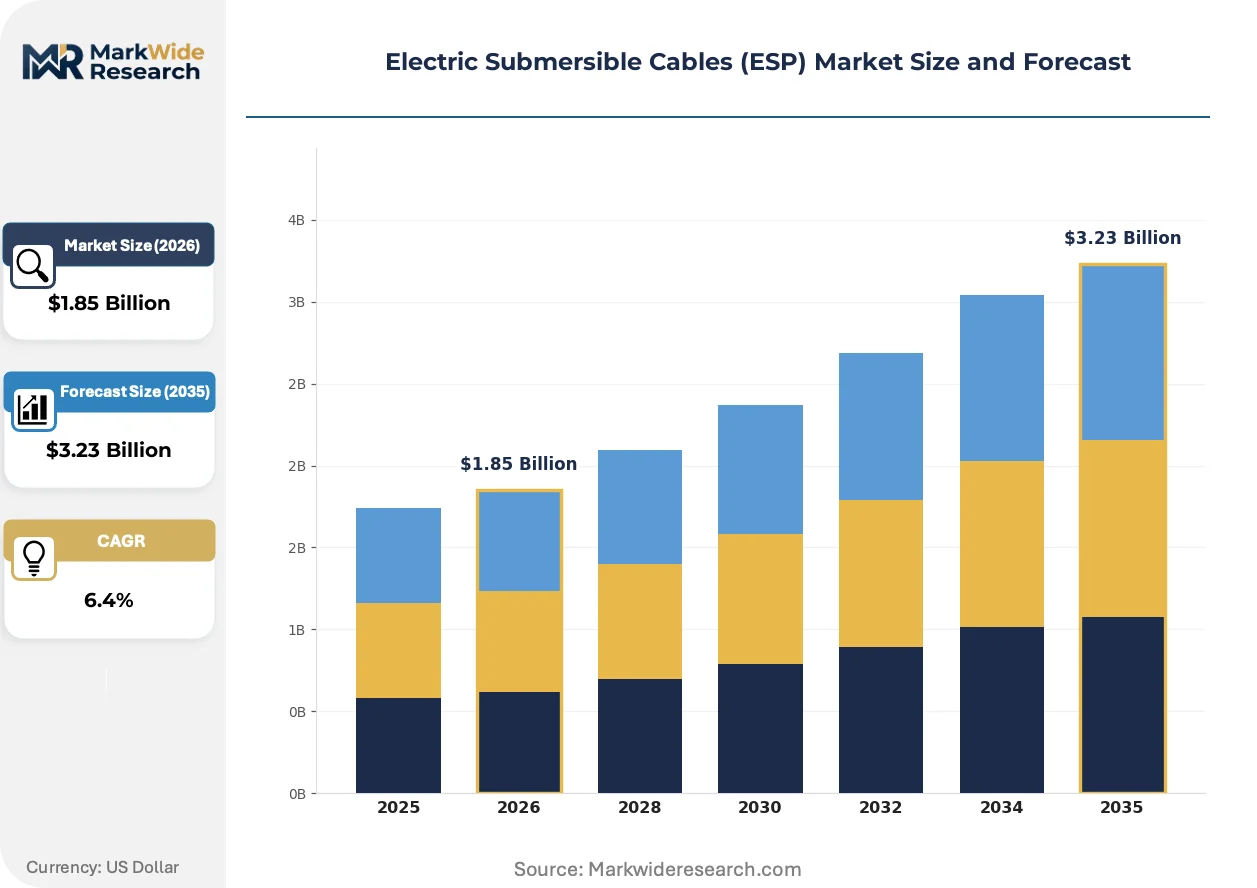
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
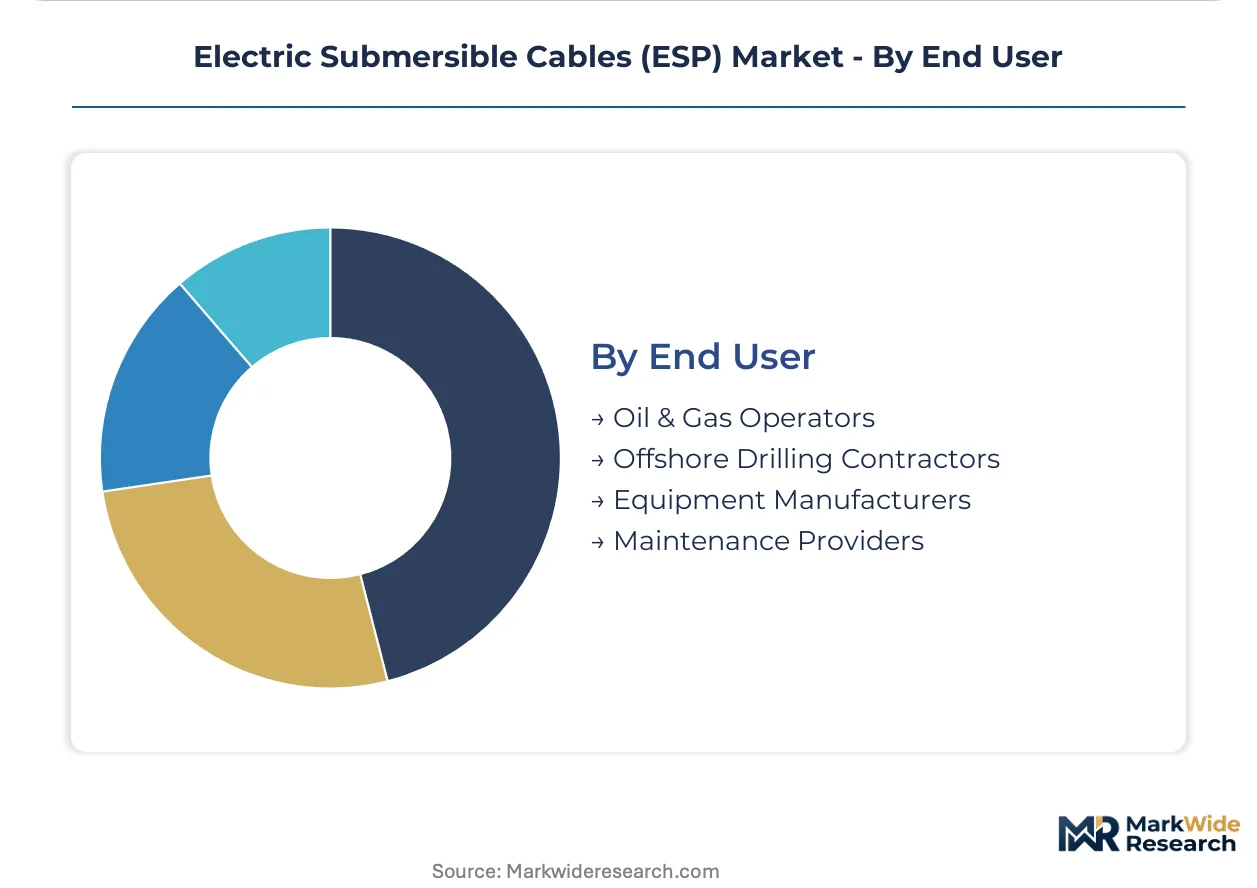
| Segmentation | Cable Type: Armored, Unarmored, Self-Supporting, Composite, High-Temperature Insulation Material: XLPE, EPR, PVC, Neoprene, Silicone Rubber Application: Oil Extraction, Gas Production, Marine Exploration, Water Injection, Geothermal Power End User: Oil & Gas Operators, Offshore Drilling Contractors, Equipment Manufacturers, Maintenance Providers |
| Companies Covered | Siemens AG, The Kerite Company, Prysmian Group, Southwire Company, LLC, Nexans SA, Schlumberger Limited, Halliburton Company, Baker Hughes, Borets International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Submersible Cables (ESP) Market Strategic Shifts & Innovations
Material science and digitalization are converting ESP cables from passive power conduits into active downhole intelligence assets. This evolution is driven by the operational need for real-time well diagnostics and predictive failure analysis in high-value production environments.
Embedded fiber optic lines provide Distributed Temperature Sensing (DTS) and Distributed Acoustic Sensing (DAS) along the entire cable. Oil and gas producers are adopting this technology to monitor inflow performance and detect anomalies in pump operation. This integration of sensing capability is virtualizing the wellbore, creating a dynamic digital model of downhole conditions without costly well interventions.
Europe's ATEX directives impose strict requirements for equipment operating in explosive atmospheres, impacting cable design and material selection. Manufacturers must use certified components and demonstrate protection against ignition risks, which adds complexity to the supply chain. The flat cable segment, critical for workover operations, faces the most significant design challenges to meet both dimensional constraints and ATEX safety standards.
A shift toward integrated system procurement is altering purchasing behavior for artificial lift equipment. Operators are increasingly sourcing the complete ESP package—pump, motor, seal, and cable—from a single supplier to guarantee component compatibility and simplify lifecycle management. This model is most prevalent in complex deepwater projects in Brazil and West Africa, favoring vendors with a full-system portfolio.
Electric Submersible Cables (ESP) Market Segmentation
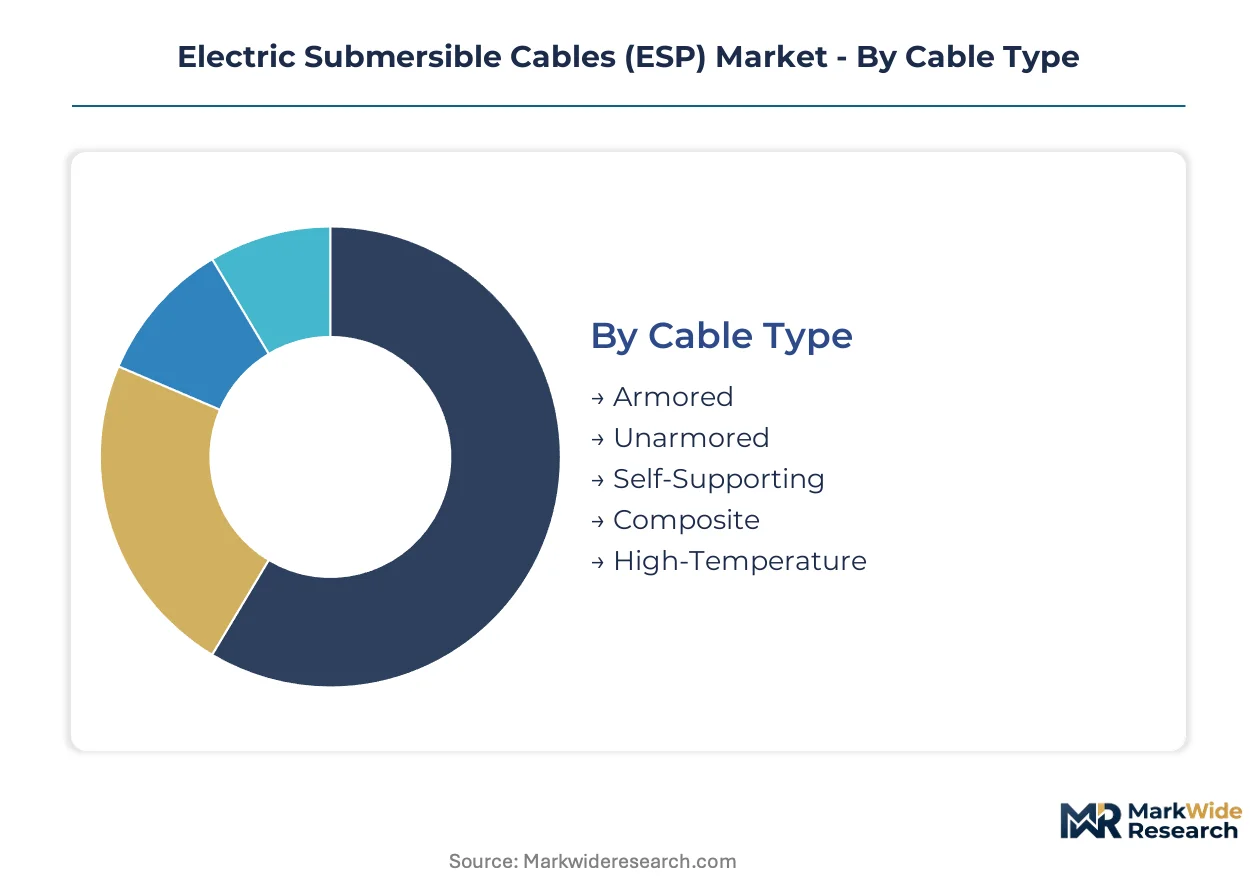
The Electric Submersible Cables market is segmented across critical dimensions, reflecting diverse operational demands and technological specifications for artificial lift systems. Understanding these segments clarifies varying performance needs across well environments, highlighting established demand and emerging shifts.
Cable Type:
Cable type segmentation reflects varying replacement cycles and operational lifespans of ESP systems. Certain constructions are for rapid deployment, others prioritize long-term durability.
- Armored:These cables feature an external metallic layer, typically steel, providing robust mechanical protection against abrasion and crushing forces. Demand concentrates in oil extraction, especially the Permian Basin, where durability is paramount.
- High-Temperature:Designed with advanced insulation materials like specialized EPR, these cables maintain electrical integrity in extreme thermal conditions. Geothermal expansion in Indonesia drives procurement, requiring sustained operation above 200°C.
- Unarmored:Lacking external metallic protection, these cables are lighter, flexible, suitable for less abrasive or temporary installations.
- Self-Supporting:These cables incorporate integral strength members, allowing them to bear their own weight in vertical installations.
- Composite:Composite cables integrate power conductors with fiber optic lines for downhole monitoring, enhancing well diagnostics.
Armored cables dominate the installed base due to widespread use in oil extraction. High-Temperature cables are where expansion concentrates, driven by deeper and hotter well development.
Insulation Material:
Insulation material choice directly impacts ESP cable cost structure and performance envelope, with specialized compounds commanding higher price points. Selection balances thermal resistance, dielectric strength, and chemical inertness.
- EPR:Ethylene Propylene Rubber offers excellent thermal stability and flexibility, preferred for high-temperature and deep well applications. Demand for enhanced EPR is strong in offshore Brazil, where extreme conditions prevail.
- XLPE:Cross-linked polyethylene provides good electrical properties and mechanical toughness, suitable for moderate temperature environments and standard wells. Its use is prevalent in less demanding North American oil and gas operations.
- PVC:Polyvinyl Chloride is a cost-effective insulation for lower temperature, less aggressive downhole conditions.
- Neoprene:Neoprene offers good oil and chemical resistance, finding niche applications where hydrocarbon exposure is a primary concern.
- Silicone Rubber:Silicone rubber provides superior temperature resistance, ideal for ultra-high temperature applications.
EPR material accounts for the largest volume due to its adaptability in challenging environments. Silicone Rubber adoption is accelerating for specialized ultra-high temperature geothermal projects.
Application:
Application segments reflect the primary purpose and operational context for ESP cable deployment, defining volume requirements across the energy sector. Each
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized ESP cables, often developed in North American technology hubs, are increasingly exported to support demanding oil and gas operations in regions like Brazil and the Middle East. This global movement of advanced cable technology underscores the international nature of the ESP market. Investment decisions for high-performance cables align with regional energy policies and geological challenges.
United States
Sustained unconventional resource development, particularly in shale and tight oil plays, drives significant demand for ESP systems and associated cables. American Petroleum Institute (API) recommended practices govern product design and safety for these applications. Houston, Texas, serves as a critical hub for oilfield services and ESP system integration, concentrating procurement activities.
Brazil
Deepwater offshore projects in the pre-salt reservoirs necessitate highly durable and reliable ESP cables for artificial lift. The National Agency of Petroleum, Natural Gas and Biofuels (ANP) enforces stringent regulations for offshore safety and environmental compliance. Macaé, Rio de Janeiro, functions as a primary operational base for these extensive deepwater oil and gas activities.
Indonesia
The expanding geothermal energy sector in Indonesia presents a significant market for high-temperature submersible cables. The Ministry of Energy and Mineral Resources (ESDM) actively promotes renewable energy development, including geothermal power. Java and Sumatra host substantial geothermal power projects, requiring specialized cable procurement for extreme thermal conditions.
Norway
Brownfield optimization initiatives in the North Sea region aim to maximize recovery from mature oilfields, driving demand for upgraded ESP systems. The Petroleum Safety Authority (PSA) sets rigorous standards for offshore operations and equipment performance. Stavanger acts as a key center for North Sea oil and gas technology and services, supporting these retrofit projects.
Saudi Arabia
Continuous investment in oil production capacity and enhanced oil recovery (EOR) initiatives sustains high demand for ESP cables. The Ministry of Energy's policies guide hydrocarbon extraction and infrastructure development across the kingdom. Dhahran and Ras Tanura are central to Aramco's vast oil and gas operations, requiring consistent volumes of robust ESP cables.
Electric Submersible Cables (ESP) Market Key Industry Players
Channel-controlling players compete with product-specialist players in the Electric Submersible Cables market, creating a tiered competitive structure. Large integrated oilfield service companies offer comprehensive solutions, while specialized manufacturers focus on advanced material science and cable design. This market structure favors both broad portfolio integration and niche technological leadership. Strategic partnerships and targeted technology development represent dominant competitive moves.
Integrated service providers, such as Schlumberger Limited, leverage extensive oilfield networks to deploy advanced, data-enabled cable systems. Baker Hughes occupies a similar position by offering integrated artificial lift solutions where the ESP cable is a critical component. Meanwhile, Prysmian Group, an Italy-based multinational, exemplifies specialized cable manufacturing, focusing on high-specification composite cables for harsh subsea environments.
| Leading Market Players |
|---|
| Siemens AG |
| The Kerite Company |
| Prysmian Group |
| Southwire Company, LLC |
| Nexans SA |
| Schlumberger Limited |
| Halliburton Company |
| Baker Hughes |
| Borets International Limited |
| Others |
Cost & Logistics Intelligence
Raw material volatility, particularly for copper and specialized steel alloys, directly impacts the cost structure of ESP cables and where margin pools concentrate for manufacturers. This upstream cost pressure often translates into higher procurement costs for downstream operators in high-demand regions.
Pricing Analysis
The pricing gap between conventional and next-generation composite cables with integrated sensors reflects significant technology differentiation. Project-based pricing dominates for complex integrated artificial lift solutions, while per-unit transactional models apply to standard cable replacements. Price differentiation stems from advanced insulation materials like high-temperature EPR and stringent certifications such as ATEX directives. Pricing pressure stems from the continuous need for advanced materials to meet extreme downhole conditions. Operators focused on brownfield optimization exhibit the highest price sensitivity, balancing cost against extended operational life.
Supply Chain Analysis
Contract manufacturing capacity for specialized cable components is concentrated in regions with advanced material science capabilities, including parts of Europe and North America. The supply chain relies heavily on specific raw materials such as high-purity copper for conductors and specialized steel alloys for armor. Raw material price volatility represents a significant structural risk, creating cost uncertainty for cable manufacturers. Distribution runs primarily through direct sales channels from large integrated oilfield service providers, supplemented by specialized distributors for niche cable types.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electric Submersible Cables market is in an early-cycle expansion, driven by the increasing penetration of integrated sensing technologies in downhole applications. This technology shift enhances reservoir management and operational efficiency.
For Market Incumbents: Harden existing market share by deepening vertical integration into specialized insulation material production. Invest in advanced testing facilities to meet rigorous API and ATEX standards, mitigating the threat from new entrants lacking such infrastructure. Control the full ESP package offering to counter component-focused competitors. Prioritize research and development in high-temperature EPR and fiber optic integration.
For New Entrants and Emerging Players: Geothermal energy expansion in Southeast Asia, particularly Indonesia, presents a penetrable segment for high-temperature cable specialists. Develop cost-effective, high-temperature composite cables for these specific applications. A go-to-market angle involves partnering with local renewable energy developers to provide tailored solutions. Focus on niche applications where established players have less specialized offerings.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized material science firms developing advanced insulation compounds. The long-term viability of high-performance ESP cables is strong over a ten-year window, supported by sustained energy demand and well complexity. Target acquisition archetypes include niche technology providers with proprietary high-temperature insulation or fiber optic integration capabilities. A signal to watch is the increasing adoption rate of integrated sensing cables in unconventional well developments.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in High-Temperature Material R&D | Enables ESP systems to operate reliably in ultra-deepwater and geothermal well environments. |
| Acquire Fiber Optic Sensor Specialists | Integrates real-time downhole monitoring capabilities directly into power cables, enhancing well diagnostics. |
| Expand Manufacturing Capacity for Armored Cables | Addresses sustained demand from oil extraction applications in regions like the Permian Basin. |
| Pursue ATEX Certification for Flat Cable Designs | Unlocks market access in European explosive atmospheres, particularly for workover operations. |
| Form Partnerships with Geothermal Project Developers | Secures early-stage contracts for high-temperature cables in emerging renewable energy markets. |
Research Approach
The analysis maps cable type, insulation material, and application sub-sectors, each validated through primary interviews with ESP system engineers, procurement managers, and material scientists. Secondary validation utilized API standards, ATEX directives, and national energy agency reports. This approach triangulates bottom-up market intelligence with top-down industry trends.
Assumptions held stable include current geopolitical stability and consistent energy transition policies, while variables such as oil and gas prices and renewable energy investment rates were modeled. The quantitative framework segments demand by cable type, insulation material, application, and regional energy policy across the analysis window. CAGRs were derived through regression analysis of historical data and projected market drivers. Forecast inputs included projected well completions and geothermal capacity additions.
Practitioners should monitor raw material price fluctuations and shifts in regulatory frameworks for early signals impacting market dynamics. Forecasts reflect current market conditions and known project pipelines. Quarterly review of commodity prices and major project announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
HVDC Cables Market
Cables
EDM Wires Market
Cables
Data Center Wire and Cable Market
Cables
Cable Tags Market
Cables
GCC Cable Accessories Market
Cables
Submarine Communication Cables Market
Cables
XLPE Cables Market
Cables
South Africa Wire and Cable Market
Cables
Control Cable Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
Cable Accessories Market
Cables
Direct Attach Cable Market
Cables
Cable Testing Market
Cables
Military Cable Market
Cables
Flat Flexible Cables Market
Cables
Global Cable Gland Market