
 Analog and Digital IC Development Tools Market | 2026-2036
Analog and Digital IC Development Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Analog and Digital IC Development Tools Market Outlook
Platform licensing is rewriting margin economics across the semiconductor toolchain. Texas Instruments leverages captive design software to extend its analog product ecosystem into customer workflows. Analog Devices anchors its high-precision signal chain strategy through proprietary simulation environments that lock in component selection.
Analog and digital IC development tools encompass electronic design automation software, hardware validation platforms, and test instrumentation used to architect, verify, and characterize integrated circuits before tape-out. These systems process transistor-level netlists, execute mixed-signal simulations at nanometer geometries, and validate power integrity across process-voltage-temperature corners. Design software commands the largest revenue pool as complexity migration toward 3nm-class nodes extends license values. Simulation tools represent the fastest-expanding category as multi-physics analysis becomes mandatory for automotive-grade reliability. Testing equipment remains structurally mature with replacement cycles tied to capital expenditure timing at foundries.
The EU AI Act imposes conformity requirements on autonomous system chips that reshape validation tool specifications across European design houses. REACH and RoHS substance restrictions force material declarations into component libraries, embedding compliance checks directly within EDA databases. FDA and FAA certification pathways for medical and avionics ICs create dual-use demand for fault-simulation capabilities in North American markets. Stakeholders must weigh regulatory divergence against unified platform strategies as jurisdictional standards harden.
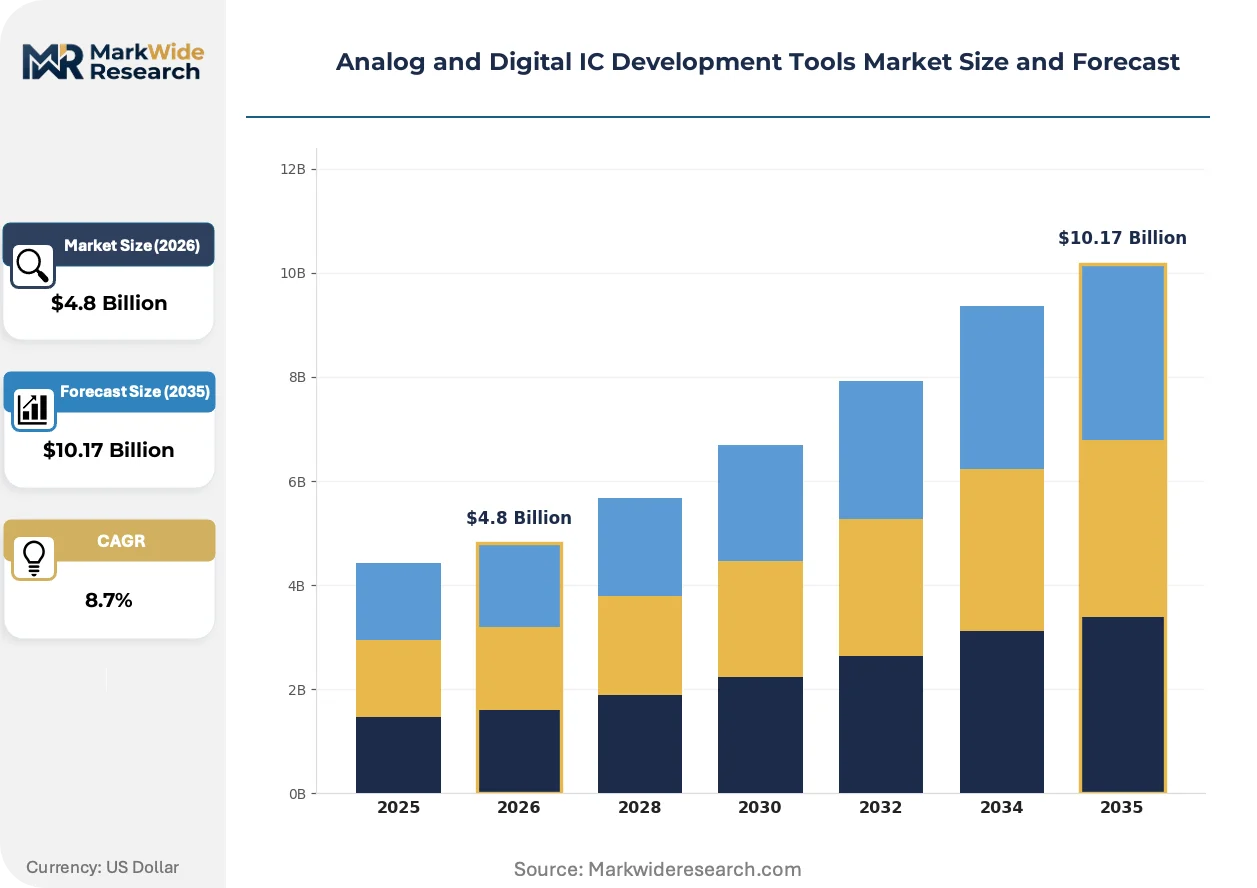
Market Dynamics
Platform licensing economics are compressing standalone tool margins while automotive electrification mandates from NHTSA and the EU AI Act force validation complexity into every design cycle.
Growth Catalysts
- Automotive electrification mandates:NHTSA fuel-economy standards and EU CO2 regulations compel power management IC redesigns. Foundry-adjacent design houses in Taiwan and Germany expand simulation tool procurement to meet reliability grades.
- REACH material declaration integration:ECHA substance restrictions embed compliance checks directly within EDA component libraries. European design houses now require certified simulation environments as standard procurement criteria.
- 3nm-class node migration:Transistor-level complexity at advanced geometries extends license values for electronic design automation software. Multi-physics analysis becomes mandatory for process-voltage-temperature corner validation.
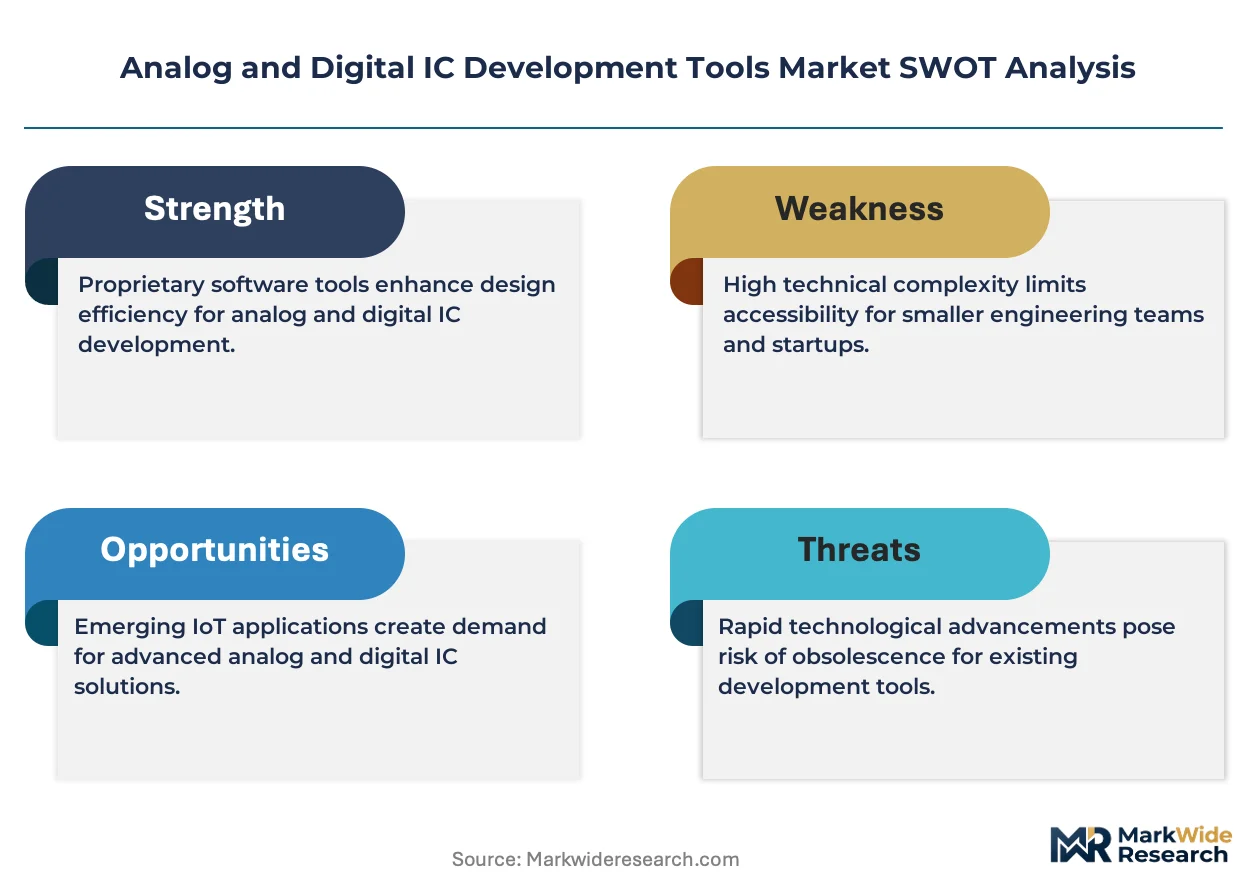
Market Restraints
- Specialized engineering talent scarcity:Mixed-signal verification expertise concentrates among a limited pool of practitioners. Compensation inflation for analog-mixed-signal designers constrains tool vendor expansion timelines.
- Foundry process access concentration:Leading-edge fabrication capacity clusters with Taiwan-based semiconductor manufacturers. Design tool vendors face customer concentration risk when foundry expansion pauses.
- Legacy tool lock-in effects:Decades of proprietary format accumulation creates switching friction. Migration costs for established netlist libraries deter platform transitions even when superior alternatives emerge.
Strategic Opportunities
- India semiconductor ecosystem buildout:PLI scheme incentives and BIS standards alignment attract foundry-adjacent design houses. Tool vendors can establish early relationships as domestic fabrication capacity scales.
- Medical device IC certification pathways:FDA 510(k) and FAA DO-254 requirements create dual-use demand for fault-simulation capabilities. North American aerospace and medical electronics manufacturers seek pre-certified validation platforms.
- Cloud-native EDA delivery models:Simulation workload elasticity matches variable project cadences at fabless startups. Usage-based licensing lowers entry barriers for pre-revenue design houses in Israel and Singapore.
Industry Challenges
- Multi-physics simulation integration:Thermal, electromagnetic, and power integrity analysis require cross-domain expertise that few engineering teams possess. Tool vendors must embed automated coupling between previously siloed solvers.
- IP licensing complexity:Standard cell libraries, memory compilers, and interface PHYs carry entangled royalty structures. Design houses face audit exposure when tool flows auto-instantiate third-party IP without clear provenance tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog and Digital IC Development Tools Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Simulation Tools, Testing Equipment, Design Software, Evaluation Boards End User: Semiconductor Manufacturers, Automotive Electronics, Consumer Electronics, Aerospace Application: Signal Processing, Power Management, Communication, Control Systems Development Phase: Prototype Development, Production Optimization, Functional Testing, Design Validation |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, STMicroelectronics, NXP Semiconductors, Skyworks Solutions, Renesas Electronics Corporation, ON Semiconductor, Microchip Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog and Digital IC Development Tools Market Strategic Shifts
Artificial intelligence is embedding inference capabilities throughout the semiconductor toolchain, compressing verification cycles and automating constraint optimization that previously demanded manual engineering iteration.
Machine learning-based layout optimization is digitizing physical design workflows that historically consumed months of expert engineer time. Automotive electronics manufacturers in Germany and Japan adopt these tools most aggressively to meet compressed time-to-market windows for autonomous system chips. The technology is digitizing the power-performance-area tradeoff analysis that previously required iterative manual refinement.
EU AI Act conformity requirements are mandating traceable validation documentation for chips deployed in safety-critical autonomous systems. European design houses must now demonstrate systematic fault coverage analysis that exceeds traditional manufacturing test requirements. Medical and avionics IC segments are responding by procuring fault-simulation platforms that preemptively satisfy both EASA and FDA certification pathways.
Subscription-based access models are displacing perpetual license structures across the EDA vendor base. Fabless startups in Austin and Tel Aviv prefer operational expenditure treatment that aligns tool costs with funding cycles. This shift is most visible among pre-revenue design houses targeting automotive and aerospace verticals where certification timelines extend beyond traditional depreciation periods.
Analog and Digital IC Development Tools Market Segmentation
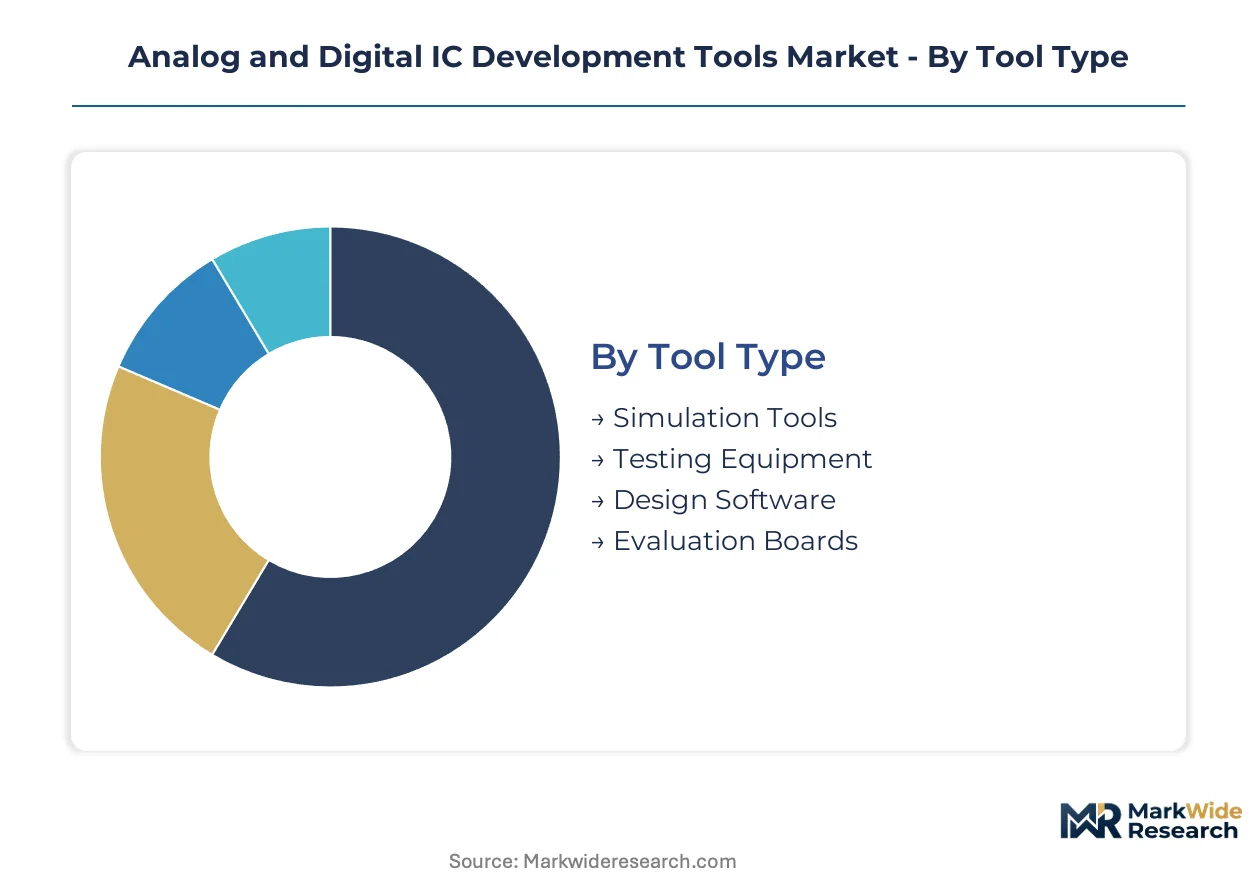
Segmentation in this market reflects divergent procurement rhythms across the semiconductor lifecycle. Tool categories exhibit starkly different replacement cycles, from perpetual design software licenses to capital-intensive testing equipment with decade-long depreciation schedules.
Tool Type:
Cycle times vary dramatically: simulation tools refresh every 2-3 years with node migrations, while testing equipment remains on 7-10 year replacement horizons tied to foundry capex.
- Design Software:Electronic design automation platforms process transistor-level netlists and execute mixed-signal simulations at nanometer geometries. License values extend as complexity migrates toward 3nm-class nodes, with procurement concentrating among foundry-adjacent design houses in Taiwan and Germany where process development demands continuous tool evolution.
- Simulation Tools:Multi-physics analysis environments validate power integrity across process-voltage-temperature corners. Automotive electronics manufacturers in Germany and Japan expand procurement most aggressively as EU AI Act conformity requirements mandate traceable validation documentation for safety-critical autonomous system chips.
- Testing Equipment:Hardware validation platforms and test instrumentation for pre-tape-out characterization. Replacement cycles tie directly to capital expenditure timing at Taiwan-based foundries.
- Evaluation Boards:Reference hardware for silicon validation and customer design-in support. Demand tracks new product introduction cycles at analog and mixed-signal vendors.
Design software dominates installed base. Simulation tools are where expansion concentrates.
End User:
Cost tier stratification separates high-volume semiconductor manufacturers from specialized verticals with certification-intensive procurement requirements.
- Semiconductor Manufacturers:Fabless design houses and integrated device manufacturers constitute the core revenue pool. Procurement concentrates among foundry-adjacent clusters in Taiwan, Germany, and the United States where 3nm-class node development demands continuous tool investment.
- Automotive Electronics:Tier-1 suppliers and OEM captive design teams drive power management IC redesigns. NHTSA fuel-economy standards and EU CO2 regulations compel simulation tool procurement for reliability-grade validation.
- Consumer Electronics:Smartphone and wearable chipset designers with compressed time-to-market windows. Procurement favors cloud-native EDA delivery models with usage-based licensing.
- Aerospace:Avionics IC developers facing FAA DO-254 and EASA certification pathways. Fault-simulation capabilities command premium pricing for dual-use medical and aerospace applications.
Semiconductor manufacturers anchor volume procurement. Automotive electronics is climbing the fastest as electrification mandates reshape tool specifications.
Application:
Volume concentration in power management and signal processing segments reflects automotive and industrial end-market pull.
- Power Management:Voltage regulator and battery management IC design for electrified vehicles. Automotive electronics manufacturers in Germany expand tool procurement to meet NHTSA and EU reliability grades.
- Signal Processing:High-precision analog-to-digital and digital-to-analog conversion. Analog Devices anchors proprietary simulation environments that lock in component selection across the signal chain.
- Communication:RF transceiver and high-speed interface PHY development. 5G infrastructure buildouts drive mixed-signal verification complexity.
- Control Systems:Motor driver and actuator IC architectures for industrial automation. EU AI Act conformity requirements reshape validation tool specifications for autonomous system deployment.
Signal processing commands mature installed base economics. Power management is gaining share fastest under electrification mandates.
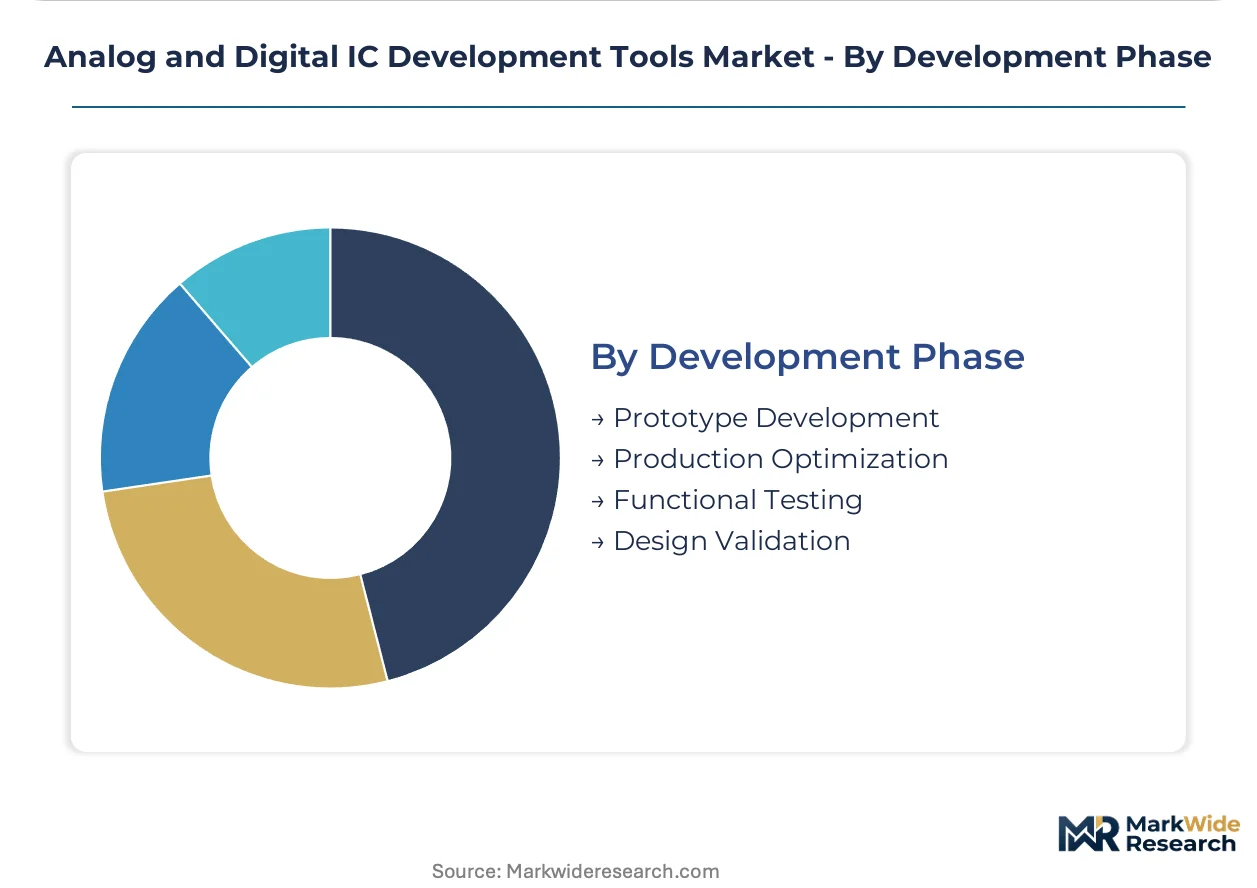
Development Phase:
Maturity gradients separate early-phase prototyping tools from production-hardened validation platforms with embedded compliance frameworks.
- Design Validation:Pre-silicon functional verification and corner case analysis. REACH and RoHS substance restrictions force material declarations into EDA component libraries at European design houses.
- Prototype Development:First silicon bring-up and characterization workflows. Fabless startups in Austin and Tel Aviv prefer subscription-based access models that align tool costs with funding cycles.
- Functional Testing:Manufacturing test pattern generation and fault coverage analysis. FDA and FAA certification pathways create dual-use demand in North American aerospace and medical electronics segments.
- Production Optimization:Yield enhancement and process window refinement tools. Access concentrates with Taiwan-based semiconductor manufacturers where leading-edge fabrication capacity clusters.
Design validation holds the deepest tool penetration. Functional testing is where certification-driven expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German automotive electronics manufacturers prioritize certified simulation environments for EU AI Act compliance, while Taiwanese foundry-adjacent design houses concentrate procurement on 3nm-class node development tools. United States aerospace and medical device segments drive dual-use demand for fault-simulation capabilities.
United States
FAA DO-254 certification pathways and FDA 510(k) requirements create specialized demand for fault-simulation platforms. NHTSA fuel-economy standards compel power management IC redesigns among Detroit-area automotive suppliers. Austin and Greater Boston fabless startups prefer cloud-native EDA delivery models with usage-based licensing.
Germany
Automotive electrification mandates from EU CO2 regulations reshape tool procurement for power management and signal chain validation. ECHA REACH substance restrictions embed material declaration requirements directly within EDA component libraries. Munich and Stuttgart design houses cluster around foundry-adjacent development centers for reliability-grade simulation.
Taiwan
Leading-edge fabrication capacity concentration drives continuous investment in 3nm-class node design software. Hsinchu Science Park anchors the densest cluster of foundry-adjacent design houses globally. Local procurement prioritizes transistor-level complexity tools for process-voltage-temperature corner validation.
Japan
METI industrial policy supports domestic semiconductor ecosystem resilience through design tool procurement incentives. Automotive electronics manufacturers in Nagoya and Tokyo metropolitan areas adopt machine learning-based layout optimization aggressively. Mixed-signal verification expertise concentrates among established engineering teams with decades of proprietary format experience.
India
PLI scheme incentives and BIS standards alignment attract foundry-adjacent design house establishment. Bengaluru and Hyderabad emerging as fabless startup clusters with preference for subscription-based tool access. Domestic fabrication capacity scaling creates early vendor relationship opportunities as the ecosystem builds out.
Analog and Digital IC Development Tools Market Competitive Environment
Capability concentration sits with specialized analog-mixed-signal tool vendors; scale advantage sits with diversified semiconductor manufacturers with captive design environments. The vendor base stratifies across three tiers: integrated device manufacturers with proprietary platforms, independent EDA vendors with multi-foundry support, and emerging cloud-native challengers. Dominant competitive moves include strategic partnerships for IP library integration and backward integration into specialized simulation engines.
Within the integrated device manufacturer tier, Texas Instruments and Analog Devices exemplify platform licensing strategies that embed design tools within broader component ecosystems. Infineon Technologies occupies a position bridging automotive certification requirements with industrial power management tool development. These three anchors represent divergent approaches to customer workflow capture—captive software extension, high-precision signal chain lock-in, and vertical application certification.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| STMicroelectronics |
| NXP Semiconductors |
| Skyworks Solutions |
| Renesas Electronics Corporation |
| ON Semiconductor |
| Microchip Technology |
| Others |
Value Chain & Pricing Dynamics
Hsinchu Science Park anchors the densest concentration of foundry-adjacent design houses globally, and this capacity clustering translates directly into pricing leverage for Taiwan-based tool vendors serving 3nm-class node development. German automotive electronics manufacturers absorb premium pricing for certified simulation environments as EU AI Act compliance mandates reshape procurement criteria.
Pricing Analysis
Long-term enterprise licensing contracts dominate procurement at integrated device manufacturers, while subscription-based SaaS tiers attract fabless startups in Austin and Tel Aviv seeking operational expenditure alignment. Price differentiation rests on certification grade—FDA DO-254 and EASA pathways command substantial premiums—and volume scale, with foundry-adjacent clusters extracting tiered discounts. Pricing pressure stems from cloud-native challengers offering usage-based simulation access that undercuts perpetual license economics. Pre-revenue design houses exhibit highest price sensitivity; aerospace and medical device segments demonstrate lowest sensitivity due to certification lock-in requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard practice among Taiwan-based semiconductor manufacturers negotiating with Japanese and US testing equipment vendors. Geographic supply concentration centers on Taiwan, the United States, and Germany, where foundry-adjacent design houses cluster. Raw material dependencies span advanced photoresist chemicals from Japan, precision optics from Germany, and specialized substrates from South Korea. Single-source vulnerability in EUV lithography components creates structural risk exposure. Distribution runs through direct enterprise sales teams for large accounts and value-added resellers serving mid-market design houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Analog and Digital IC Development Tools Market is entering a cyclical recovery phase as automotive electrification mandates from NHTSA and EU CO2 regulations force sustained power management IC redesign cycles across German and US manufacturing bases.
For Market Incumbents: Entrench proprietary simulation environment lock-in by embedding REACH compliance checks and EU AI Act traceability features directly within EDA component libraries. Extend backward integration into specialized multi-physics solvers to defend against cloud-native challengers offering elastic workload pricing. Prioritize certification pre-qualification with FAA and FDA pathways to capture aerospace and medical device procurement premiums. For New Entrants and Emerging Players: Cloud-native delivery models for mixed-signal verification tools represent the most penetrable entry point among pre-revenue fabless startups in Israel and Singapore. India semiconductor ecosystem buildout under PLI scheme incentives offers white-space opportunity as domestic fabrication capacity scales and design house procurement patterns crystallize. Lead with usage-based licensing that aligns tool costs with funding cycles rather than competing on perpetual license economics. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified semiconductor manufacturers seeking to monetize captive design software assets as standalone platform businesses. Long-term viability favors vendors with embedded regulatory compliance frameworks that harden switching costs across automotive and aerospace verticals. Monitor foundry expansion announcements in India and Southeast Asia as inflection indicators for regional tool procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Texas Instruments extends captive design software into customer workflows, tightening ecosystem lock-in. |
| Regulatory Pre-Certification | Analog Devices anchors FDA and FAA pathway compliance within proprietary simulation environments. |
| Cloud-Native Delivery Model | Elastic simulation workloads match variable project cadences at fabless startups in Tel Aviv and Austin. |
| Backward Integration into Solvers | Infineon Technologies embeds automated thermal-electromagnetic coupling for automotive reliability validation. |
| Geographic Expansion | Early vendor relationships in Bengaluru and Hyderabad capture India PLI scheme design house formation. |
Study Parameters
Desk research of SEC 10-K filings, EDA vendor annual reports, and foundry capex disclosures preceded structured interviews with analog-mixed-signal design leads, EDA product managers, automotive Tier 1 procurement officers, and semiconductor foundry planning executives. Secondary validation drew from Taiwan Stock Exchange filings, EU regulatory impact assessments, and US FDA 510(k) databases. Bottom-up license volume estimates triangulated against top-down semiconductor R&D spending allocations across the analysis window.
Assumptions held fixed include sustained automotive electrification mandate enforcement and continued 3nm-class node migration timelines, while variables included foundry capacity expansion pacing and cloud-native adoption rates among pre-revenue design houses. Segmentation dimensions modeled encompass tool type, end user vertical, application category, and development phase maturity. CAGRs derived from license value evolution at advanced geometry nodes and replacement cycle compression under multi-physics simulation mandates. Forecast inputs incorporated EU AI Act implementation schedules and NHTSA fuel-economy standard phase-in curves.
Practitioners should monitor foundry utilization rates, regulatory certification timeline shifts, and cloud-native EDA funding round velocity for early signals of demand inflection. Forecasts reflect documented assumptions; foundry expansion pauses, regulatory divergence acceleration, or generative AI disruption of verification workflows would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Nanoimprint Lithography System Market
Semiconductor Equipment
SMT Reflow Soldering Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Chip Conveyors Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
India Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
Asia-Pacific Aligner Sheet Market
Semiconductor Equipment
Reticle Pod Cleaning System Market