
 India Optic Fiber Cable and Accessories Market | 2026-2036
India Optic Fiber Cable and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
India Optic Fiber Cable and Accessories Market Insights
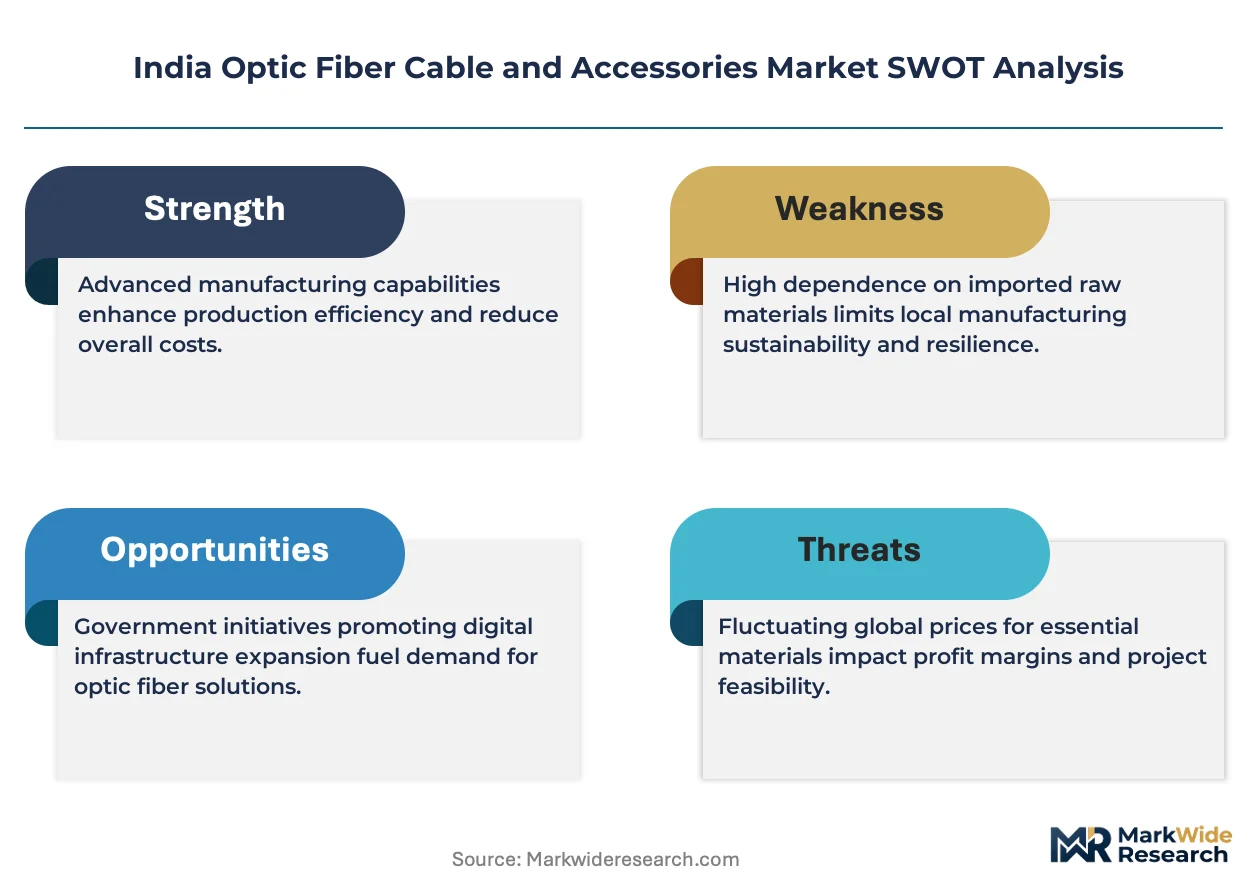
The India optic fiber cable market is recalibrating around a widening gap between premium low-attenuation single-mode products for long-haul networks and commodity-grade multi-mode cables for short-reach enterprise use. Sterlite Technologies Limited leverages its integrated optical fiber preform capacity to dominate premium supply for telecom operators. HFCL Limited anchors its position through dense distribution across tier-two and tier-three cities for BharatNet tenders. Polycab India Limited differentiates via backward integration into copper and specialty polymers that feed hybrid cable lines.
Optic fiber cable and accessories encompass silica-core transmission media with cladding diameters typically standardized at 125 micrometers, plus splice closures, patch panels, and termination hardware engineered to minimize insertion loss across wavelengths from 1260 to 1625 nanometers. Single-mode fiber commands the largest volume share in telecommunications backbones where attenuation below 0.35 dB per kilometer at 1310 nanometers remains critical. Multi-mode fiber segments in data center applications are expanding fastest as hyperscalers build captive facilities in Chennai and Noida, though ribbon fiber for dense urban ducting captures concentrated margin pools.
BIS certification under IS 16712 and TRAI's quality of service mandates shape product standards and market access for domestic manufacturers. The PLI scheme for telecom equipment creates procurement preference for local producers meeting specified value-add thresholds. Stakeholders must monitor how BIS testing protocols evolve for bend-insensitive fiber variants before committing to capacity expansion plans.
Market Dynamics
The India optic fiber cable market is bifurcating around BharatNet's rural mandate versus hyperscaler demand for low-latency metro fiber, creating divergent specification requirements that strain manufacturer tooling flexibility.
Growth Catalysts
- TRAI Quality Mandates:The regulator's service-level benchmarks compel telecom operators to replace legacy copper with certified single-mode fiber, accelerating upgrade cycles in Maharashtra and Gujarat.
- Hyperscaler Data Center Builds:Captive facilities in Chennai and Noida require dense ribbon fiber for intra-campus connectivity, pulling premium multi-core products from domestic suppliers.
- PLI Scheme Thresholds:Local value-add requirements under the telecom equipment production-linked incentive create procurement preference for manufacturers meeting domestic content norms.
Market Restraints
- Optical Preform Import Dependence:Silica preform supply concentrates among Japanese and American producers, exposing Indian cable makers to yen-dollar volatility and shipping delays.
- BIS Certification Timelines:IS 16712 testing protocols for bend-insensitive variants extend product approval cycles by four to six months, freezing capacity commitments.
- Wireless Backhaul Substitution:5G millimeter-wave small cells reduce fiber pull requirements in dense urban pockets where right-of-way costs exceed radio deployment economics.
Strategic Opportunities
- Smart City Fiberization:Integrated command centers in Indore and Surat require hardened fiber for traffic and surveillance networks, opening municipal procurement channels outside telecom.
- Defense Communication Modernization:Strategic optical ground wire for border infrastructure demands armored, rodent-resistant cables with classified attenuation specifications.
- Optical Fiber Composite Overhead Ground Wire:Power grid modernization under CEA directives creates hybrid cable demand where utilities bundle fiber with high-tension transmission lines.
Industry Challenges
- Splicing Technician Scarcity:Fusion splicing certification programs lag deployment timelines, forcing contractors to import skilled labor from Kerala and Tamil Nadu fiber hubs.
- Last-Mile Duct Congestion:Overlapping BharatNet, commercial ISP, and municipal smart city fiber pulls exhaust available sub-duct capacity in tier-two city centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Optic Fiber Cable and Accessories Market |
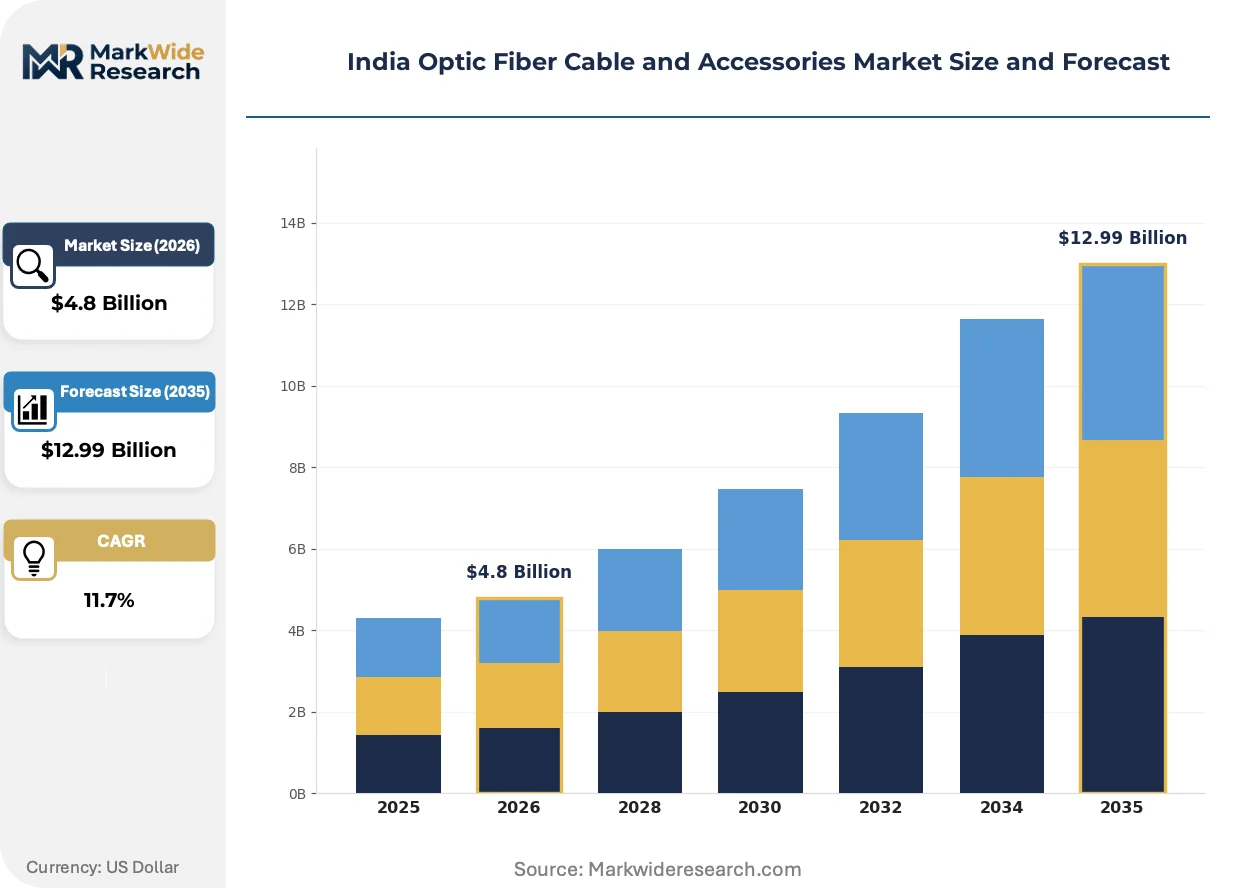
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Fiber, Multi-Mode Fiber, Armored Cables, Ribbon Fiber Application: Telecommunications, Data Centers, CATV, Military Installation Method: Aerial, Buried, Indoor, Underground End User: Telecom Operators, Enterprises, Government, Utilities |
| Companies Covered | Finolex Cables Limited, KEI Industries Limited, Polycab India Limited, Sterlite Technologies Limited, Birla Cable Limited, Vindhya Telelinks Limited, Universal Cables Limited, HFCL Limited, Aksh OptiFibre Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Optic Fiber Cable and Accessories Market Trends and Innovations
Active optical systems are compressing the traditional cable-patch-panel-splice hierarchy, forcing accessory suppliers to integrate intelligence directly into termination hardware.
Bend-insensitive single-mode fiber is decentralizing metro network architecture by enabling tighter coiling in congested underground ducts. Municipal corporations in Bengaluru and Hyderabad are specifying G.657.A2-compliant cables for smart city backbones. This fiber grade eliminates the need for dedicated splice enclosures at every bend point, reducing civil works costs by half.
BIS is tightening IS 16712 protocols to include macro-bend testing at 1550 nanometers, mirroring IEC 60793-2-50 revisions. Domestic manufacturers must retest existing product lines or risk de-listing from government tenders. Tier-one suppliers with in-house metrology labs are accelerating certification batches while smaller competitors face six-month approval queues.
Enterprise buyers are consolidating optical infrastructure procurement under hyperscale leasing arrangements. Data center operators in Mumbai and Chennai now specify turn-key fiber connectivity including termination, testing, and twenty-year maintenance in single contracts. This bundling compresses margins for standalone cable distributors while favoring integrated solution providers with field service capabilities.
India Optic Fiber Cable and Accessories Market Segmentation
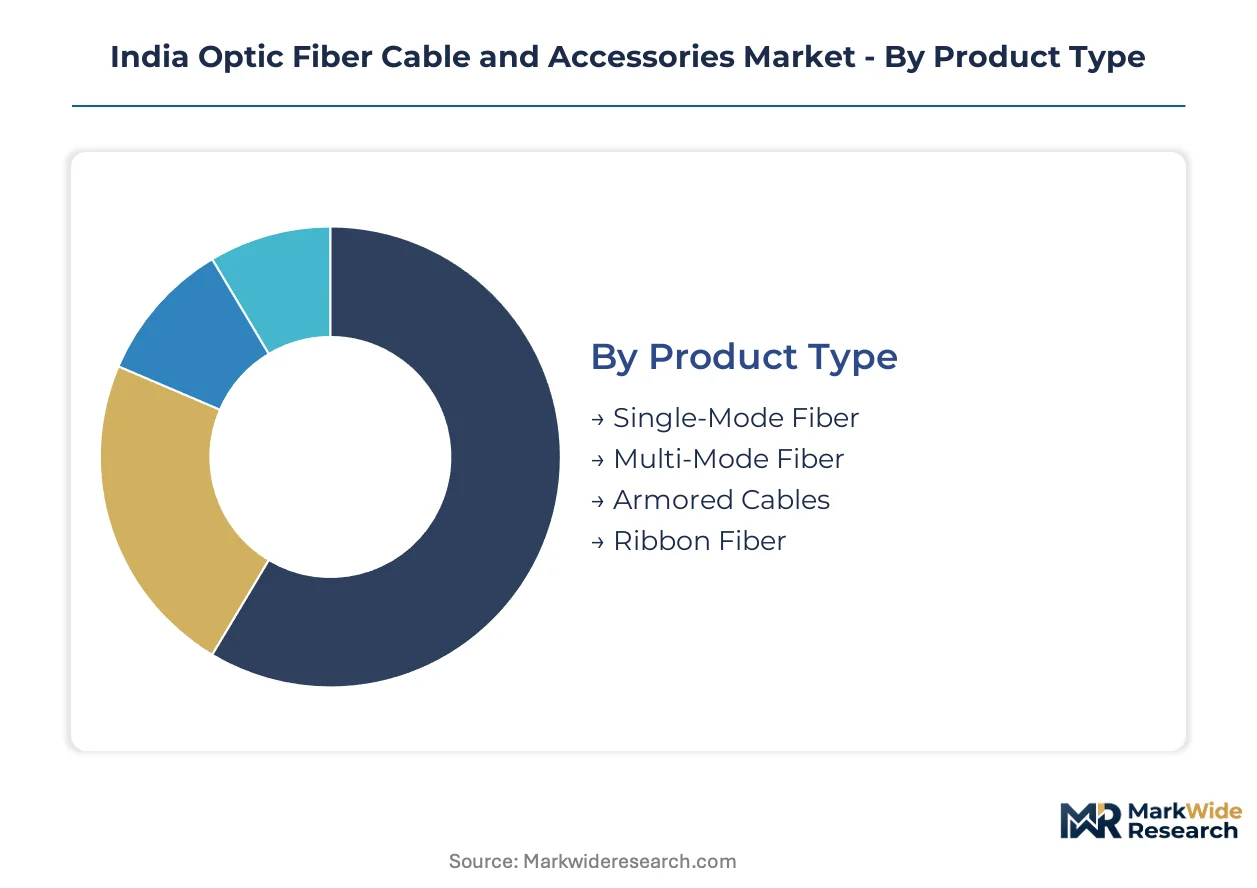
Segmentation in the India optic fiber cable market reveals how capital deployment, technical specifications, and procurement channels fragment supply. Manufacturers must align product portfolios with distinct buyer economics across telecom infrastructure, hyperscaler facilities, and government mandates.
Product Type:
Capital intensity varies sharply across fiber grades, with preform manufacturing and specialized coating lines demanding the heaviest upfront investment.
- Single-Mode Fiber:Silica-core cables with 8-10 micrometer core diameters transmit signals across 100+ kilometer spans with attenuation below 0.35 dB/km at 1310 nanometers. Demand concentrates in BharatNet rural backbones across Maharashtra and Gujarat, driven by TRAI quality mandates compelling copper replacement.
- Multi-Mode Fiber:50-62.5 micrometer core designs optimize for short-reach, high-bandwidth applications using lower-cost vertical-cavity surface-emitting lasers. Hyperscaler data centers in Chennai and Noida pull premium OM4 and OM5 grades for intra-campus connectivity.
- Armored Cables:Steel or aluminum protective layers shield fiber from rodent damage and mechanical stress in harsh environments.
- Ribbon Fiber:Multiple fibers bonded in flat arrays enable mass fusion splicing for dense urban duct deployments.
Most installed capacity flows through Single-Mode Fiber. Expansion is steepest in Ribbon Fiber.
Application:
Application segments diverge by latency tolerance, with financial trading and cloud computing imposing the strictest performance thresholds.
- Telecommunications:Long-haul and metro networks form the volume foundation, spanning BharatNet rural infrastructure and 5G fronthaul in tier-one cities. TRAI service benchmarks and PLI scheme procurement preferences steer operator purchasing toward BIS-certified domestic supply.
- Data Centers:Hyperscale and colocation facilities demand low-latency, high-fiber-count connectivity for server-to-server and storage networking. Captive builds in Mumbai, Bengaluru, and Hyderabad specify turn-key fiber infrastructure bundling installation, testing, and long-term maintenance.
- CATV:Cable television operators deploy hybrid fiber-coaxial architectures for last-mile video distribution.
- Military:Strategic communication networks require armored, EMP-resistant cables with classified attenuation specifications for border infrastructure.
Telecommunications absorbs the largest share of domestic production. Data Centers are gaining share fastest.
Installation Method:
Installation economics hinge on right-of-way access and labor intensity, with underground deployment commanding premium pricing per kilometer.
- Aerial:Pole-mounted deployment dominates rural BharatNet rollout where trenching costs prove prohibitive across Maharashtra and Gujarat farmland.
- Buried:Direct-buried cables with polyethylene sheathing serve suburban and industrial corridors lacking existing conduit.
- Indoor:Plenum-rated tight-buffered cables meet fire safety codes for enterprise buildings and data center meet-meet rooms.
- Underground:Duct-laid cables in municipal sub-duct infrastructure support dense urban fiberization in Bengaluru and Hyderabad smart city projects.
Aerial methods account for the greatest kilometer deployment. Underground installation is climbing the fastest.
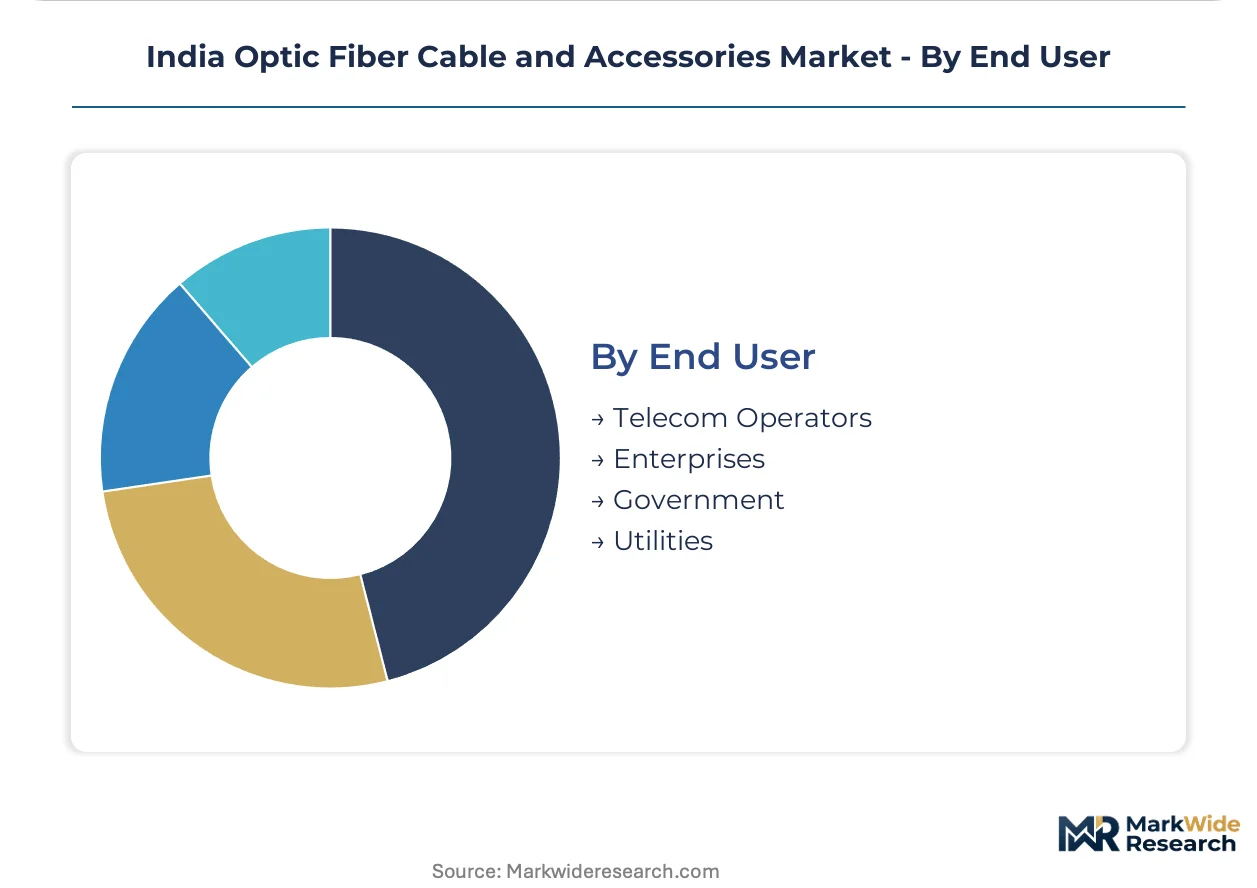
End User:
End user procurement patterns split between centralized tender processes and decentralized technical specifications.
- Telecom Operators:Reliance Jio, Bharti Airtel, and BSNL drive volume through multi-year framework agreements with integrated preform-to-cable suppliers.
- Enterprises:Banking, IT services, and manufacturing verticals specify campus-wide fiber LANs and data center interconnects.
- Government:BharatNet, defense, and smart city mandates create procurement pools with domestic content requirements under PLI and Make in India directives.
- Utilities:Power transmission operators bundle fiber within optical ground wire for grid modernization under CEA directives.
Telecom Operators channel the majority of contracted volume. Government procurement is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized fiber splicing technicians from Kerala and Tamil Nadu anchor India's optic fiber deployment capacity, migrating to project sites across Maharashtra, Gujarat, and Karnataka as BharatNet and 5G rollouts accelerate.
Maharashtra
Reliance Jio and Bharti Airtel drive dense fiber-to-the-home deployments across Mumbai and Pune metropolitan regions. TRAI quality mandates compel operators to replace legacy copper infrastructure with certified single-mode fiber. The Mumbai-Pune corridor concentrates premium cable demand for enterprise data center interconnects and financial services networks.
Gujarat
Aerial fiberization dominates rural BharatNet rollout across Surat, Vadodara, and Ahmedabad districts where trenching costs prove prohibitive. The state's electrical utilities bundle fiber within optical ground wire under CEA directives for smart grid modernization. Surat's integrated command center mandates hardened fiber for traffic and surveillance networks.
Karnataka
Hyperscaler facilities in Bengaluru pull premium multi-mode and ribbon fiber grades for intra-campus connectivity. BIS certification timelines for bend-insensitive variants under IS 16712 extend product approval cycles, freezing capacity commitments for smaller suppliers. The city's municipal corporation specifies G.657.A2-compliant cables for smart city backbone infrastructure.
Tamil Nadu
Chennai's captive data center builds by cloud operators demand dense fiber counts with turn-key installation and long-term maintenance contracts. The state anchors India's fusion splicing technician training ecosystem, exporting skilled labor to fiber deployment projects nationwide. Coimbatore and Madurai emerge as secondary hubs for cable distribution to tier-two markets.
Telangana
Hyderabad's smart city fiberization requires underground duct-laid cables in congested municipal sub-duct infrastructure. Government procurement under PLI scheme thresholds creates preference for domestic manufacturers meeting local value-add requirements. The city's HITEC City corridor concentrates enterprise demand for campus-wide fiber LANs.
India Optic Fiber Cable and Accessories Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across India's optic fiber cable market, where integrated preform-to-cable operations face specialized accessory fabricators. The structure bifurcates between tier-one suppliers with in-house metrology labs and regional distributors dependent on imported optical preforms. Three archetypes dominate: integrated optical fiber preform manufacturers, dense distribution network operators, and backward-integrated polymer specialists. Capacity expansion and BIS certification acceleration constitute the dominant competitive moves as approval timelines stretch to six months.
Among integrated producers, Sterlite Technologies Limited and HFCL Limited occupy positions at the scale-driven end, while Polycab India Limited exemplifies the backward-integrated archetype leveraging captive polymer supply. Finolex Cables Limited and KEI Industries Limited sit within the diversified electrical cable tier, representing manufacturers with cross-category infrastructure expertise. Aksh OptiFibre Limited anchors the specialist fiber optic segment alongside Vindhya Telelinks Limited, both exemplifying focused pure-play positioning. Birla Cable Limited and Universal Cables Limited represent diversified industrial conglomerate subsidiaries with cable manufacturing heritage.
| Leading Market Players |
|---|
| Finolex Cables Limited |
| KEI Industries Limited |
| Polycab India Limited |
| Sterlite Technologies Limited |
| Birla Cable Limited |
| Vindhya Telelinks Limited |
| Universal Cables Limited |
| HFCL Limited |
| Aksh OptiFibre Limited |
| Others |
Pricing and Supply Chain Analysis
Government procurement pools under BharatNet and PLI scheme mandates anchor pricing power toward integrated domestic manufacturers with in-house optical preform capacity, compressing margins for distributors dependent on imported silica inputs. Contract structures bifurcate between turn-key bundled services for hyperscaler data centers and transactional per-kilometer pricing for rural telecom infrastructure, with certification timelines and raw material volatility feeding through to quoted rates.
Pricing Analysis
Bundled turn-key contracts encompassing installation, testing, and twenty-year maintenance command premium positioning for hyperscaler data centers in Mumbai and Chennai, while unbundled per-kilometer transactional pricing dominates BharatNet rural tenders. Price differentiation rests on BIS certification tier and volume scale, with G.657.A2 bend-insensitive fiber carrying material premiums over standard G.652.D grades. Cost compression in commodity multi-mode segments is intensifying as ribbon fiber capacity expands, though splicing technician scarcity limits downward price elasticity. Government procurement under PLI domestic content thresholds demonstrates lowest price sensitivity, while tier-two commercial ISP deployments exhibit acute cost consciousness.
Supply Chain Analysis
Direct-to-telecom-operator channels handle hyperscale buyer demand from Reliance Jio and Bharti Airtel, while distributor networks reach tier-two and tier-three BharatNet contractors. Geographic supply concentration centers on Japan and the United States for optical preform feedstock, with domestic cable manufacturing drawing from Chinese and South Korean specialty polymer and coating material suppliers. Raw material dependencies include silica preforms, UV-curable acrylate coatings, and steel or aluminum armoring tapes. Single-source vulnerability in preform supply exposes Indian manufacturers to yen-dollar volatility and maritime logistics disruptions. Distribution runs through integrated preform-to-cable producers, electrical cable distributors with fiber crossover, and project-specific contractors with direct operator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India optic fiber cable market represents a late-cycle quality story as hyperscaler demand for low-latency metro fiber and bend-insensitive smart city specifications displaces commodity multi-mode volume. Specification divergence between BharatNet rural mandates and premium enterprise requirements rewards manufacturers with accelerated BIS certification and in-house metrology capabilities.
For Market Incumbents: Anticipate margin compression from wireless backhaul substitution in dense urban pockets where 5G millimeter-wave small cells undercut fiber economics. Defensive consolidation around captive optical preform capacity and in-house splicing technician training programs locks out import-dependent competitors. Priority investment in G.657.A2 bend-insensitive fiber certification under evolving IS 16712 protocols preserves government tender eligibility.
For New Entrants and Emerging Players: Begin with smart city fiberization opportunities in Indore, Surat, and Hyderabad municipal command centers, where hardened fiber specifications for traffic and surveillance networks sit outside telecom operator procurement concentration. Municipal infrastructure verticals demonstrate penetrable white space with less consolidated supplier relationships than BharatNet or hyperscaler channels. Go-to-market positioning as integrated solution providers with field service capabilities captures turn-key contract bundling trends.
For Investors and Strategic Acquirers: Integrated electrical cable conglomerates are the most active acquirer in this space, seeking fiber optic capabilities to complement power transmission and building wire portfolios. Long-term viability across the projection horizon favors manufacturers with backward integration into polymers and metals, insulating margin structures from raw material volatility. Acquisition target archetypes include regional distributors with dense tier-two city presence and pending BIS certification pipelines. The signal to watch is PLI scheme threshold adjustments for domestic value-add requirements, which would accelerate consolidation toward integrated producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Optical Preform Capacity Expansion | In-house silica preform production eliminates import dependency and yen-dollar exposure for Sterlite Technologies and HFCL. |
| BIS Certification Acceleration | IS 16712 compliance for bend-insensitive variants secures eligibility under TRAI quality mandates and PLI procurement preferences. |
| Splicing Technician Training Ecosystem | Kerala and Tamil Nadu labor hub development addresses field deployment bottlenecks constraining BharatNet rollout timelines. |
| Smart City Municipal Partnership | Indore and Surat integrated command center contracts diversify revenue beyond telecom operator concentration. |
| Ribbon Fiber Manufacturing Scale-Up | Dense urban duct deployment in Bengaluru and Hyderabad pulls premium multi-core products with concentrated margin pools. |
Research Methodology
Bottom-up telecom operator and hyperscaler demand modeling reconciled against top-down optical fiber preform and cable capacity tracking forms the analytical core of this study. Primary interviews with fiber deployment project managers, BIS certification laboratory directors, telecom procurement officers, and municipal smart city infrastructure planners combined with secondary validation from TRAI regulatory filings, CEA power grid modernization directives, PLI scheme administrative guidelines, and customs trade data for silica preform imports. Triangulation between installation method economics, product grade specifications, and end-user procurement patterns grounds volume and value estimates.
Input-output matrices map optical fiber core and cladding manufacturing through coating, cabling, and accessory fabrication to downstream deployment across aerial, buried, and underground methods. Segmentation dimensions modeled include single-mode versus multi-mode fiber grades, telecommunications versus data center versus government applications, and tier-one operator versus enterprise versus municipal end-user categories. CAGRs derive from projected kilometer deployment against average selling price trajectories, with hyperscaler data center build announcements and BharatNet phase allocation schedules serving as key forecast inputs.
Several conditions sit outside the modeled scope, including defense communication modernization with classified specifications, export market dynamics, and potential wireless technology substitution rates beyond 5G millimeter-wave baseline assumptions. Forecasts reflect assumptions regarding PLI scheme continuity, BIS certification timeline stability, and optical preform import tariff structures. Periodic stress-testing of base assumptions is recommended against regulatory shifts in domestic content requirements and raw material supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
United States Cable Accessories Market
Cables
HVDC Cables Market
Cables
Submarine Optical Fiber Cables Market
Cables
North America Coaxial Cable Market
Cables
Europe Cable Accessories Market
Cables
Multicore Cables Market
Cables
Medium Voltage Cables Market
Cables
Downhole Cables Market
Cables
Cable Drum Market
Cables
Cable Fault Locator Market
Cables
Mexico Wires and Cables Market
Cables
Data Center Wire and Cable Market
Cables
Cable Flange Market
Cables
Power and Signal Cables Market
Cables
Cable Market
Cables
Copper Cabling Systems Market