
 Molded Case Circuit Breaker Market | 2026-2036
Molded Case Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Case Circuit Breaker Market Intelligence
The gap between premium electronic trip units and commodity thermal-magnetic breakers is restructuring procurement patterns across industrial and commercial verticals. Schneider Electric leverages its IEC portfolio dominance to anchor high-margin projects in European infrastructure. Eaton competes through vertical integration into semiconductor-based trip mechanisms. Siemens specializes in digitalized breaker platforms that integrate with building energy management systems.
A molded case circuit breaker is an electromechanical protective device housed in a molded insulating frame, typically rated between 15 and 3,000 amperes, designed to interrupt overload and short-circuit currents through thermal-magnetic, electronic, or solid-state sensing mechanisms. Its primary purpose is to protect electrical distribution systems, motors, and connected equipment from damage caused by excessive current flow. Electronic breakers command the strongest margin pool due to precision selectivity and communication capabilities demanded by data centers and renewable energy systems. DIN rail mounted installation dominates control panel and OEM applications where space density and modularity drive specification. Thermal magnetic products retain volume leadership in construction and standard industrial environments where cost sensitivity outweighs advanced functionality.
The US National Electrical Code, IEC 60947-2 standards, and EU Ecodesign regulations collectively dictate breaker performance thresholds, energy efficiency minimums, and market access requirements across major economies. These frameworks compel manufacturers to redesign thermal-magnetic cores and upgrade solid-state trip algorithms to maintain compliance. Stakeholders must monitor evolving arc-fault detection mandates and carbon-border adjustment mechanisms that will reshape sourcing decisions and certification investments.
Market Dynamics
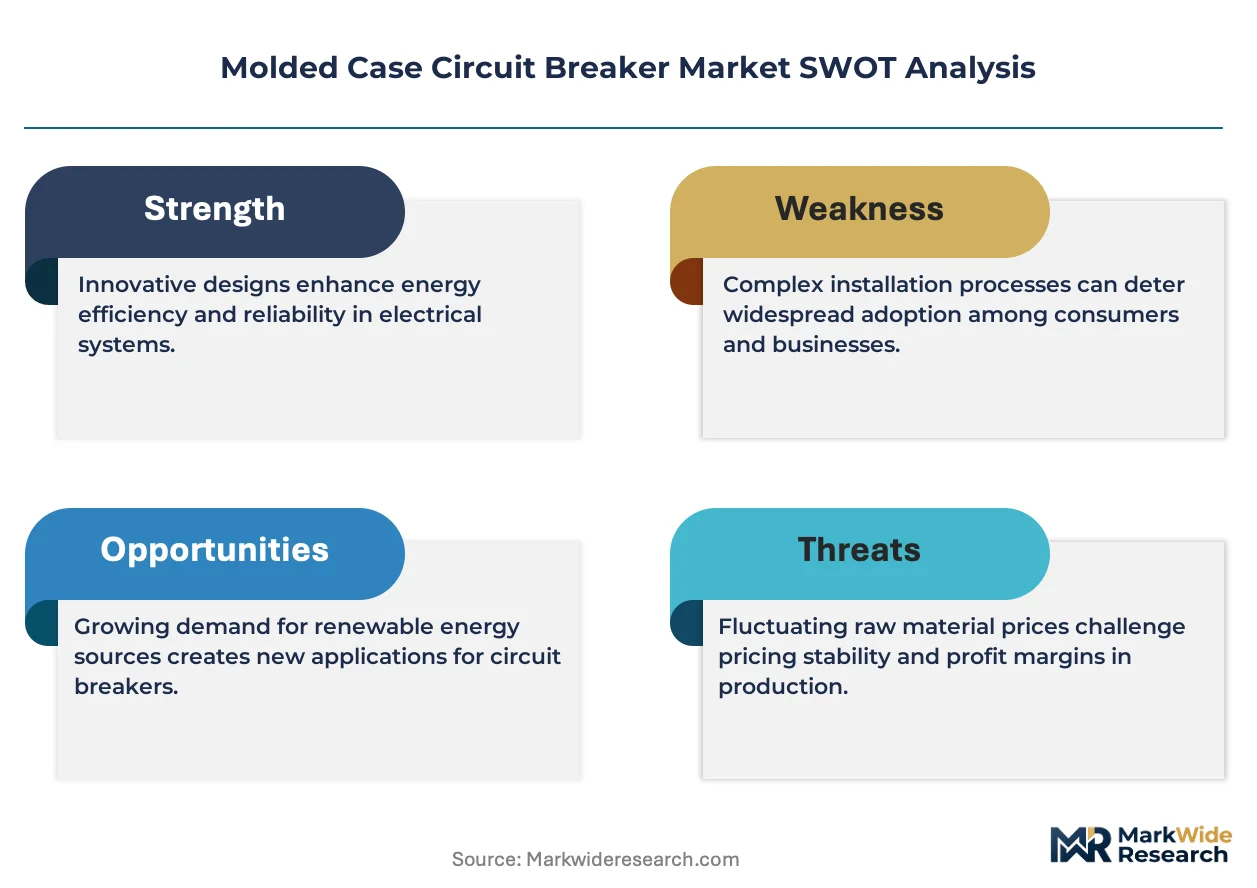
The divergence between electronic trip unit precision and thermal-magnetic cost efficiency is fragmenting procurement tiers across industrial power distribution. Grid operators and facility managers now face forced technology choices as efficiency mandates tighten and critical load protection demands escalate.
Growth Catalysts
- Data center power density requirements:Hyperscale facilities drive specification of electronic breakers with zone-selective interlocking and communication protocols for fault isolation.
- IEC 60947-2 certification expansion:European infrastructure renewal programs mandate upgraded breaking capacity ratings, accelerating replacement cycles in aging industrial substations.
- China grid modernization:State Grid Corporation electrification initiatives prioritize intelligent distribution equipment with remote monitoring capabilities.
Market Restraints
- Copper and silver price volatility:Contact and conductor material costs fluctuate with commodity markets, compressing margins on standardized thermal-magnetic products.
- Semiconductor supply concentration:Solid-state trip unit production depends on concentrated Asian wafer fabrication capacity, creating lead time vulnerability.
- Technical interoperability limits:Proprietary communication protocols between breaker platforms and energy management systems lock buyers into single-vendor architectures.
Strategic Opportunities
- India industrial electrification:PLI scheme incentives for manufacturing capacity expansion create first-mover advantage for localized electronic breaker assembly.
- Renewable integration applications:Solar and wind farm DC-coupled storage systems require arc-flash rated breakers with modified trip curves.
- Digital twin convergence:Integration of breaker telemetry with predictive maintenance platforms opens recurring software revenue streams.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for solid-state trip algorithms competes with automotive and consumer electronics for talent.
- Multi-standard certification timelines:Simultaneous UL 489, IEC 60947-2, and GB 14048.2 testing extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Case Circuit Breaker Market |
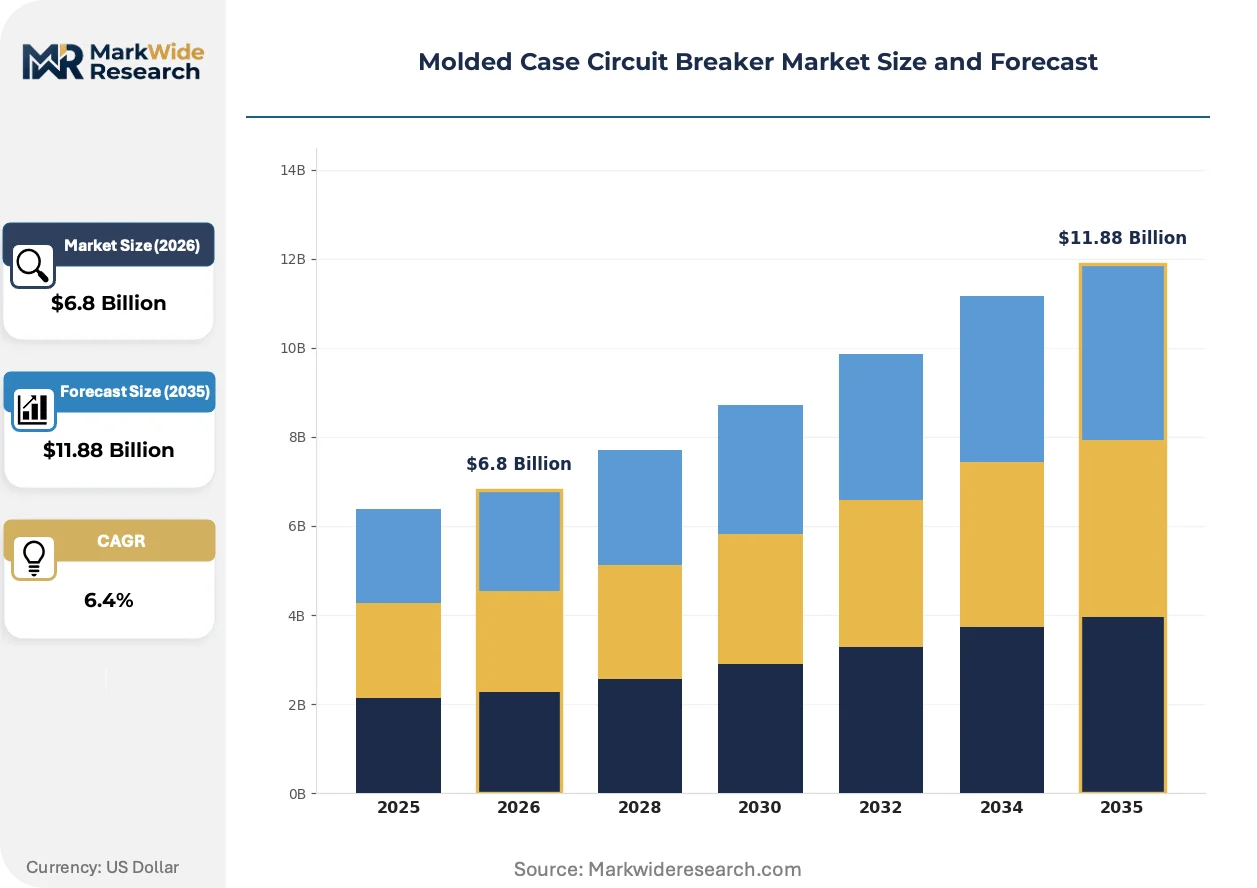
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Magnetic, Electronic, Hydraulic Magnetic, Magnetic Only, Solid State Application: Power Distribution, Motor Protection, Renewable Energy Systems, Control Panels, Data Centers End User Industry: Utilities, Construction Companies, Data Center Operators, Manufacturing Facilities, Infrastructure Developers Installation Type: Surface Mounted, Flush Mounted, DIN Rail Mounted, Panel Mounted |
| Companies Covered | Eaton, Mitsubishi Electric, Schneider Electric, Legrand, Hitachi Industrial Equipment Systems Co. Ltd., ABB, Fuji Electric Co., Ltd., Rockwell Automation, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Case Circuit Breaker Market Strategic Shifts & Innovations
Breaker intelligence is migrating from centralized switchgear to edge-mounted devices, embedding protection logic directly at the load connection point. This architectural shift compresses response times and enables granular power quality monitoring.
Solid-state current limiting technology is decentralizing fault management by replacing mechanical arc interruption with semiconductor-based current suppression. Data center operators in Northern Virginia and Frankfurt deploy these units for sub-cycle response to cascading failures. The technology is decentralizing traditional hierarchy between main and feeder breakers, enabling flatter distribution topologies.
The US Department of Energy FERC Order 2222 implementation compels breaker manufacturers to certify grid-interactive functionality for distributed energy resource aggregation. Industrial facilities must now demonstrate bidirectional communication capability for demand response participation. Commercial building portfolios face the steepest compliance burden as they retrofit legacy thermal-magnetic installations.
Buyer preference is gravitating toward lifecycle service contracts that bundle hardware with firmware updates and predictive analytics. Distributors are repositioning as power infrastructure advisors, displacing transactional component sales with engineered solution packages. This pattern is most pronounced in German manufacturing clusters where energy management outsourcing has matured.
Molded Case Circuit Breaker Market Segmentation
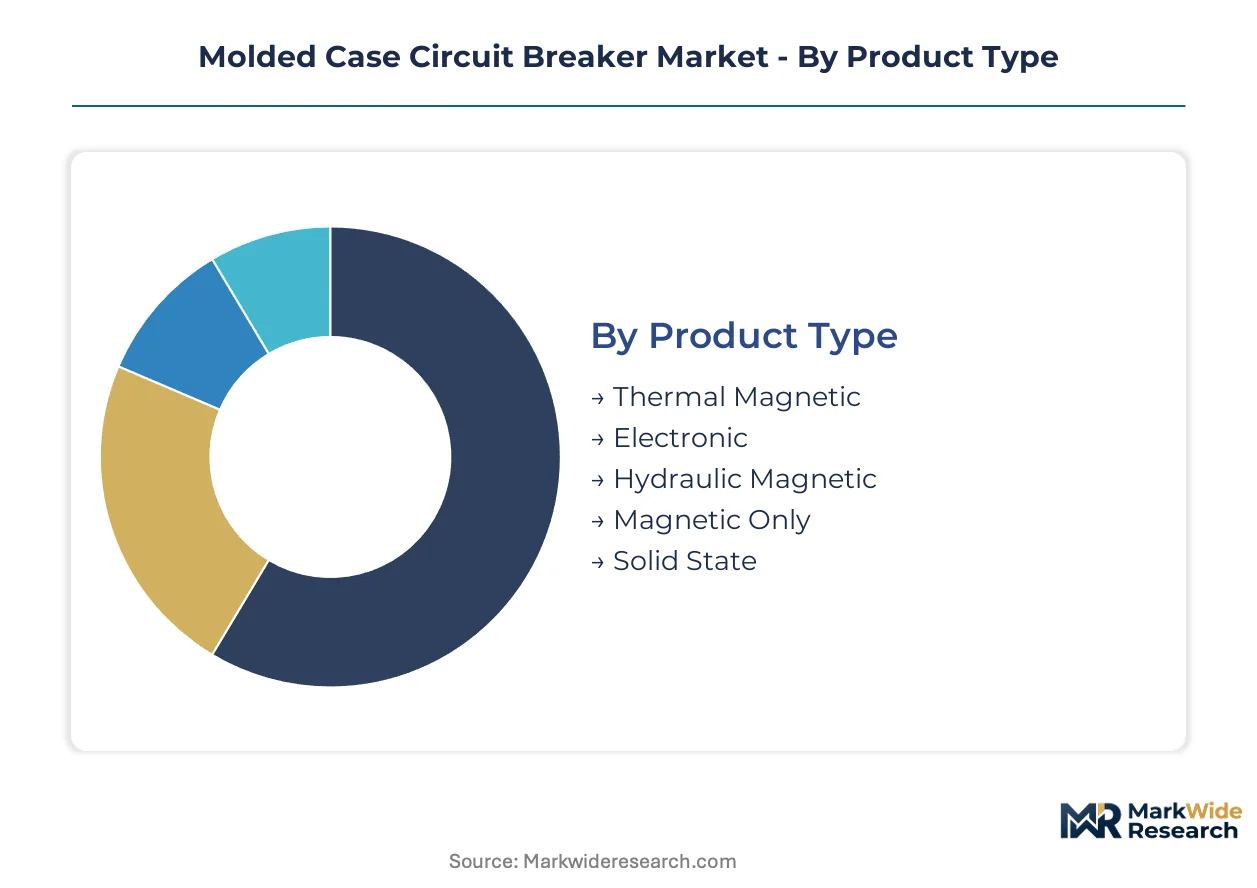
Segmentation in molded case circuit breakers reveals how certification burdens, performance tiers, and installation constraints fragment procurement across industrial verticals. Buyers navigate distinct approval pathways depending on trip mechanism sophistication and end-use criticality.
Product Type:
UL 489 and IEC 60947-2 impose divergent testing protocols across trip technologies, with electronic and solid-state units facing the steepest firmware validation requirements while thermal-magnetic designs clear faster certification cycles.
- Electronic:Microprocessor-controlled trip units enable zone-selective interlocking and Modbus communication. Data center operators in Northern Virginia and Frankfurt specify these for sub-cycle fault isolation in hyperscale facilities. FERC Order 2222 compliance now mandates bidirectional grid communication for DER aggregation.
- Thermal Magnetic:Bimetallic strip and magnetic coil combinations provide cost-efficient overload and short-circuit protection. Construction contractors in Texas and Florida favor these for commercial building installations where code compliance outweighs advanced functionality. Copper contact material costs fluctuate with commodity markets.
- Hydraulic Magnetic:Oil-dashpot time delay mechanisms deliver temperature-stable performance in harsh environments. Offshore oil platforms and mining operations specify these for vibration-resistant protection.
- Magnetic Only:Instantaneous short-circuit detection without thermal overload capability serves motor starter applications where separate overload relays handle sustained overcurrent.
- Solid State:Semiconductor-based current limiting suppresses faults without mechanical arc interruption. Northern Virginia data centers deploy these for cascading failure prevention in flat distribution topologies.
Thermal Magnetic sits at the top of the volume ranking, with Electronic climbing the fastest.
Application:
Application segmentation tracks how duty cycle severity and fault current magnitude reshape breaker specification, with renewable integration and data center density forcing the steepest performance escalations.
- Data Centers:Hyperscale facilities demand electronic breakers with Ethernet-enabled power quality monitoring and predictive maintenance telemetry. Ashburn, Virginia and Frankfurt clusters drive specification of arc-flash rated units with modified trip curves for DC-coupled storage.
- Power Distribution:Utility substations and industrial switchgear require high-breaking-capacity units certified to IEC 60947-2 for fault current interruption. State Grid Corporation procurement in China prioritizes intelligent distribution equipment with remote monitoring.
- Motor Protection:Adjustable magnetic trip settings accommodate motor inrush currents while thermal elements prevent winding damage. Manufacturing facilities specify these for conveyor systems and pump stations.
- Renewable Energy Systems:Solar and wind farms need breakers rated for bidirectional current flow and rapid reclosure. Inverter-based generation creates harmonic distortion challenges for traditional trip algorithms.
- Control Panels:DIN rail mounted miniature breakers protect PLC racks and instrumentation circuits. OEM panel builders favor modular designs for space-constrained enclosures.
Power Distribution commands the widest installed base, though Data Centers shows the steepest expansion trajectory.
End User Industry:
End user segmentation exposes how capital intensity and regulatory exposure differentiate procurement authority, with data center operators and utilities wielding specification power that construction contractors cannot match.
- Data Center Operators:Hyperscale providers like Equinix and Digital Realty mandate electronic trip units with digital twin integration for predictive maintenance. Lifecycle service contracts bundle hardware with firmware updates and analytics subscriptions.
- Utilities:Grid operators specify IEC-certified breakers for substation modernization and distributed energy resource interconnection. FERC Order 2222 implementation compels grid-interactive functionality certification.
- Manufacturing Facilities:Automotive and chemical plants prioritize selective coordination between main and feeder breakers to minimize production line outages. Arc-flash hazard analysis drives specification of current-limiting designs.
- Construction Companies:Commercial and residential contractors face cost pressure that favors thermal-magnetic units in standard industrial enclosures. Multi-family housing projects specify panel-mounted configurations for electrical rooms.
- Infrastructure Developers:Airport, hospital, and transit projects require breakers with enhanced reliability ratings for critical load protection. Public-private partnerships extend procurement cycles through design-build contracts.
Construction Companies anchor volume demand, while Data Center Operators gain share fastest.
Installation Type:
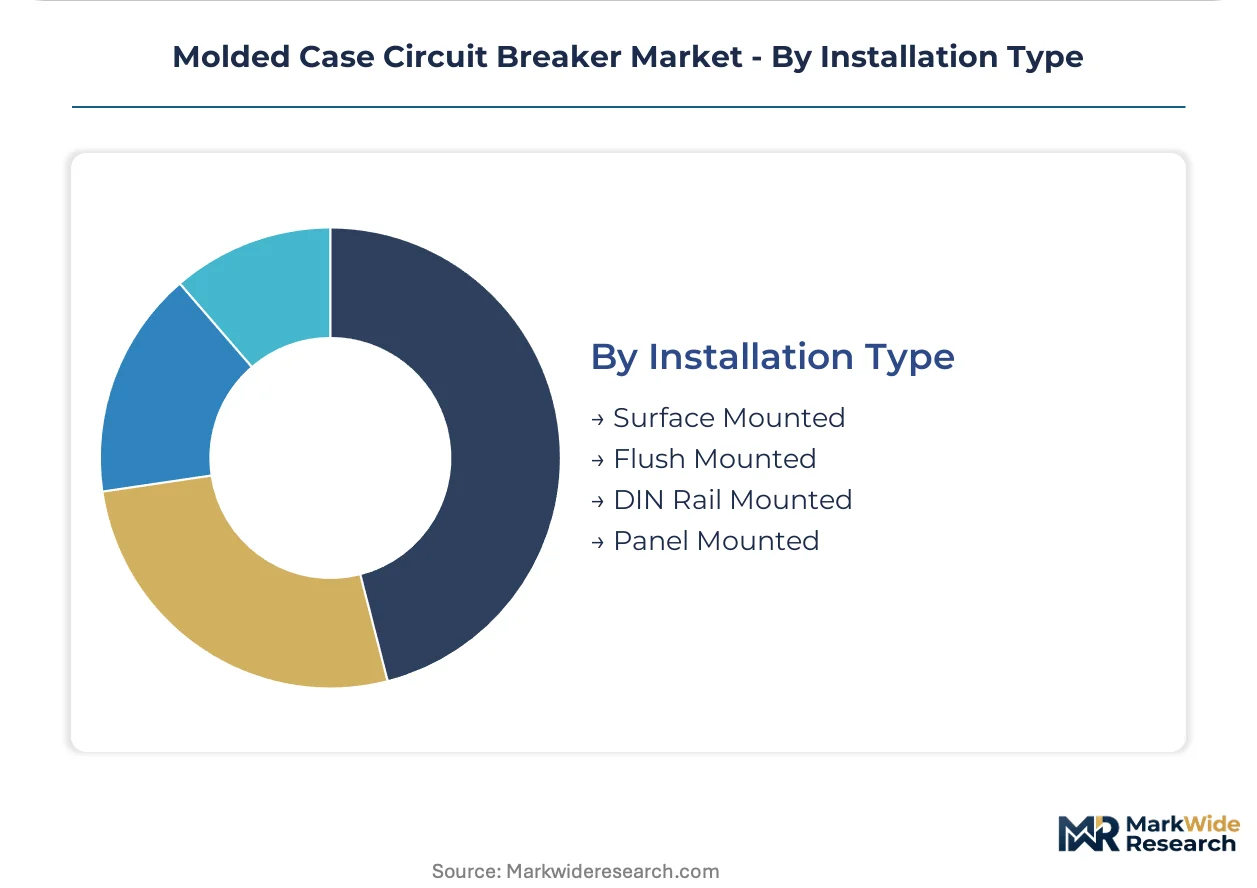
Installation segmentation reflects how enclosure geometry and maintenance access reshape physical breaker selection, with modularity and space density driving divergence between industrial and commercial applications.
- DIN Rail Mounted:35mm standardized rail systems enable rapid component swap-out in control panels and MCC buckets. German manufacturing clusters favor these for energy management outsourcing contracts.
- Panel Mounted:Direct bolt-on installation in switchboard bus structures accommodates high-current mains up to 3,000 amperes. Utilities specify these for substation switchgear.
- Surface Mounted:External enclosure attachment suits retrofit applications and temporary power distribution. Construction sites deploy these in portable power centers.
- Flush Mounted:Recessed installation in walls or columns meets aesthetic requirements for commercial building lobbies and healthcare facilities.
Panel Mounted retains the largest installed base, with DIN Rail Mounted expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineering talent pools in Germany, China, and the United States anchor the trip unit design and firmware development capabilities that differentiate premium breaker production from commodity assembly.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives specification of electronic breakers with zone-selective interlocking. FERC Order 2222 mandates grid-interactive functionality certification for distributed energy resource aggregation. Ashburn, Virginia clusters deploy solid-state current limiting units for sub-cycle fault isolation in flat distribution topologies.
Germany
Industrial electrification programs and energy management outsourcing contracts favor DIN rail mounted configurations with predictive maintenance telemetry. EU Ecodesign regulations and CE marking requirements enforce minimum energy efficiency thresholds for thermal-magnetic cores. Manufacturing clusters in Bavaria and Baden-Württemberg specify lifecycle service contracts bundling hardware with firmware updates.
China
State Grid Corporation procurement prioritizes intelligent distribution equipment with remote monitoring for grid modernization initiatives. GB 14048.2 standards and dual carbon goals accelerate replacement cycles in aging industrial substations. Yangtze River Delta manufacturing bases concentrate electronic breaker assembly capacity for domestic and export markets.
India
PLI scheme incentives for manufacturing capacity expansion create procurement pull for localized electronic breaker assembly in industrial electrification programs. Central Electricity Authority mandates tighten product standards for utility-scale installations. Maharashtra and Gujarat industrial corridors specify IEC-certified units for automotive and chemical plant protection.
Japan
Semiconductor fabrication facilities and precision manufacturing drive demand for solid-state trip units with harmonic distortion compensation. METI efficiency standards and JIS certification requirements enforce performance thresholds for industrial switchgear. Kanto and Kansai manufacturing belts specify hydraulic magnetic breakers for vibration-resistant motor protection.
Molded Case Circuit Breaker Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the molded case circuit breaker landscape, with integrated electrical conglomerates controlling captive semiconductor supply chains while specialized trip unit developers license firmware to third-party assemblers. The vendor base concentrates around three strategic archetypes: diversified industrial electrification groups with full portfolio coverage, component specialists focused on solid-state current limiting technology, and regional manufacturers serving construction and standard industrial verticals. Capacity expansion and backward integration into semiconductor-based trip mechanisms represent the dominant competitive moves as manufacturers respond to lead time vulnerability in Asian wafer fabrication.
Among diversified industrial electrification groups, Schneider Electric, Siemens, and ABB exemplify the scale-driven archetype that anchors high-margin infrastructure projects through IEC portfolio dominance and digitalized breaker platforms. These European-headquartered entities occupy positions spanning electronic trip unit design, building energy management system integration, and lifecycle service contract bundling. Their competitive positioning reflects the premium-tier vector where firmware-controlled selectivity and communication capabilities command margin premiums over commodity thermal-magnetic alternatives.
| Leading Market Players |
|---|
| Eaton |
| Mitsubishi Electric |
| Schneider Electric |
| Legrand |
| Hitachi Industrial Equipment Systems Co. Ltd. |
| ABB |
| Fuji Electric Co., Ltd. |
| Rockwell Automation |
| Siemens |
| Others |
Cost & Logistics Intelligence
Copper and silver commodity indices cascade through molded case circuit breaker manufacturing, compressing margins on thermal-magnetic units while electronic trip units absorb volatility through firmware-enabled premium pricing. Buyers in construction verticals face cost pressure from conductor material fluctuations, whereas data center operators lock in lifecycle contracts that decouple hardware from service pricing.
Pricing Analysis
The bundled-vs-unbundled service split separates procurement tiers across the market. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and communication capability, with UL 489 and IEC 60947-2 compliance tiers commanding measurable premiums. Cost compression in thermal-magnetic segments is intensifying because copper contact material costs fluctuate with commodity markets. Construction contractors exhibit the highest price sensitivity, while data center operators accept premium positioning for zone-selective interlocking and predictive maintenance telemetry.
Supply Chain Analysis
Electrical engineering talent scarcity in Germany, China, and the United States constrains trip unit design capacity and fragments production geography. Semiconductor wafer fabrication concentrates in Taiwan and South Korea, while copper conductor processing and molded frame injection molding anchor in China and Mexico. Raw material dependencies center on silver alloy contacts, epoxy resin compounds, and silicon carbide substrates. Single-source vulnerability in Asian wafer fabrication creates lead time exposure for solid-state trip unit production. Distribution runs through electrical distributors repositioning as power infrastructure advisors, displacing transactional component sales with engineered solution packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded case circuit breaker market offers margin expansion through firmware-enabled service bundling and backward integration into semiconductor trip mechanisms, offsetting commodity cost volatility in thermal-magnetic tiers.
For Market Incumbents: Extend firmware development capabilities through captive semiconductor supply chains to reduce lead time vulnerability from concentrated Asian wafer fabrication. Anchor high-margin infrastructure projects through IEC 60947-2 portfolio dominance and digitalized breaker platforms that integrate with building energy management systems. Defend against asset-light trip unit designers by controlling certification investment timelines that extend product launch cycles. For New Entrants and Emerging Players: Capture PLI scheme incentives in India for localized electronic breaker assembly, exploiting manufacturing capacity expansion in Maharashtra and Gujarat industrial corridors. Target renewable integration applications requiring arc-flash rated breakers with modified trip curves for DC-coupled storage systems. Pursue licensing agreements with established firmware developers to bypass multi-standard certification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where semiconductor supply concentration meets firmware engineering scarcity across trip unit design. Long-term viability favors diversified industrial electrification groups with captive semiconductor supply chains and lifecycle service contract portfolios. Acquisition target archetypes include specialized solid-state current limiting developers and regional manufacturers with GB 14048.2 certification access. Watch FERC Order 2222 implementation pace as inflection indicator for grid-interactive functionality demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Trip Mechanisms | Captive wafer supply reduces lead time vulnerability from concentrated Asian fabrication capacity. |
| Lifecycle Service Contract Bundling | German manufacturing clusters already outsource energy management, creating recurring software revenue streams. |
| Multi-Standard Certification Investment | Simultaneous UL 489, IEC 60947-2, and GB 14048.2 testing accelerates market access across regulatory clusters. |
| Digital Twin Platform Integration | Predictive maintenance telemetry from breaker sensors opens software subscription revenue in data center verticals. |
| Localized Assembly Capacity Expansion | India PLI scheme incentives create first-mover advantage for electronic breaker manufacturing in industrial corridors. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, electrical distributor channel partners, and aftermarket service heads with secondary validation. Regulatory filings from FERC, IEC standards documentation, and customs trade data provided foundational benchmarks. SEC 10-K disclosures from diversified industrial electrification groups and State Grid Corporation procurement records supplied volume indicators. Bottom-up segment sizing and top-down macroeconomic triangulation anchored forecast integrity.
Segment-weighting approaches distributed value across trip mechanism type, installation configuration, and end-use criticality tiers. The analytical framework modeled electronic, thermal-magnetic, hydraulic magnetic, magnetic only, and solid-state product categories alongside DIN rail, panel, surface, and flush mounting options. CAGRs derived from shipment volume trajectories and average selling price movements across the projection horizon. Data center power density requirements and renewable integration application growth supplied industry-specific demand inputs.
Underlying measurement precision varies by segment; electronic and solid-state categories carry tighter precision than commodity thermal-magnetic tiers due to concentrated supplier disclosure. Forecasts reflect documented assumptions regarding copper price stability, semiconductor supply normalization, and regulatory implementation timelines. Material deviation in FERC Order 2222 compliance pacing or GB 14048.2 enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Switches
North America Switchgear Market
Switches
Surface Mount Switch Market
Switches
Fixed Switch Cabinet Market
Switches
Micro Switch Market
Switches
Fusible Switches Market
Switches
DC Circuit Breaker Market
Switches
Analog Switches Market
Switches
ASEAN Switchgear Market
Switches
United States Circuit Breaker Market
Switches
Safety Limit Switches Market
Switches
North America Push Buttons & Signaling Devices Market
Switches
Smart Plugs and Switches Market
Switches
Global High Voltage Switchgear Market
Switches
Temperature and Pressure Switches Market
Switches
High-Voltage Disconnect Switch Market
Switches
Disconnect Switch Market