
 Cable Assembly Market | 2026-2036
Cable Assembly Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Assembly Market Intelligence
Asset-light manufacturing partnerships and contract-assembly financing is reconfiguring competitive entry barriers for mid-tier cable producers. TE Connectivity leverages captive polymer compounding to sustain margin control across high-flexibility product lines. Amphenol anchors its position through deep vertical integration into connector-cable subsystems for aerospace applications. Molex competes aggressively in data center interconnects where density and signal integrity requirements escalate.
A cable assembly comprises terminated conductors, shielding layers, and insulating jackets engineered to transmit power or signals between electronic subsystems, with typical specifications spanning 28 AWG to 4/0 AWG conductor sizes and temperature ratings from minus 65 degrees Celsius to 200 degrees Celsius depending on jacket material. Fiber optic cable assemblies now dominate bandwidth-intensive applications where electromagnetic immunity and terabit-scale throughput are mandatory. Shielded technology commands premium positioning due to escalating electromagnetic compatibility mandates in automotive and industrial automation environments. Low smoke zero halogen formulations represent the fastest-growing technology segment as building codes and mass transit specifications tighten flame-retardant requirements without toxic gas emission.
FCC Part 15 emissions standards and the EU F-Gas Regulation shape product design criteria for cable assemblies deployed in telecommunications infrastructure and climate-controlled data environments. OSHA electrical safety directives and CE marking obligations further constrain market access for non-compliant suppliers. Stakeholders must monitor evolving material compliance frameworks and qualification protocols to preserve supply eligibility across regulated end-use sectors.
Market Dynamics
AI-driven computing loads are forcing data center operators to reconfigure physical layer infrastructure, compressing procurement cycles for high-density fiber optic interconnects while tightening material compliance requirements across halogen-free insulation supply chains.
Growth Catalysts
- EU REACH and RoHS compliance mandates:Tightening restrictions on halogenated flame retardants are redirecting R&D budgets toward low smoke zero halogen formulations, creating qualified supplier scarcity that benefits early movers.
- Electric vehicle platform localization:Chinese OEMs are consolidating domestic cable assembly procurement for battery management and charging infrastructure, displacing incumbent import-dependent supply chains.
- FCC Part 15 emissions standards:Escalating electromagnetic compatibility requirements in telecommunications infrastructure are accelerating shielded cable assembly specification across 5G base station deployments.
Market Restraints
- Copper and fluoropolymer price volatility:Raw material input swings compress margin predictability for mid-tier producers lacking captive compounding capabilities or long-term purchase agreements.
- Concentrated fiber optic preform supply:Geographic concentration of optical fiber core manufacturing creates single-source vulnerability for bandwidth-intensive assembly producers.
- Technical substitution by wireless power:Inductive and resonant charging architectures are displacing traditional power cable assemblies in consumer electronics and automotive cabin applications.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component ecosystems are attracting cable assembly investment to serve domestic and export demand.
- Convergence of fiber and power in single jacket designs:Hybrid cable architectures combining optical data and electrical power transmission are opening specification opportunities in industrial automation and smart building infrastructure.
- EU F-Gas Regulation phase-down:Climate-controlled data center cooling requirements are creating demand for specialized cable assemblies rated for low-temperature flexibility in heat pump and chiller interconnects.
Industry Challenges
- Certification timeline compression:Accelerated product qualification cycles for automotive and aerospace applications strain testing capacity at third-party laboratories, extending time-to-revenue for new designs.
- Skill scarcity in polymer compounding:Formulation chemistry expertise for high-temperature and chemically resistant jacket materials is concentrating among a shrinking pool of specialized engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Assembly Market |
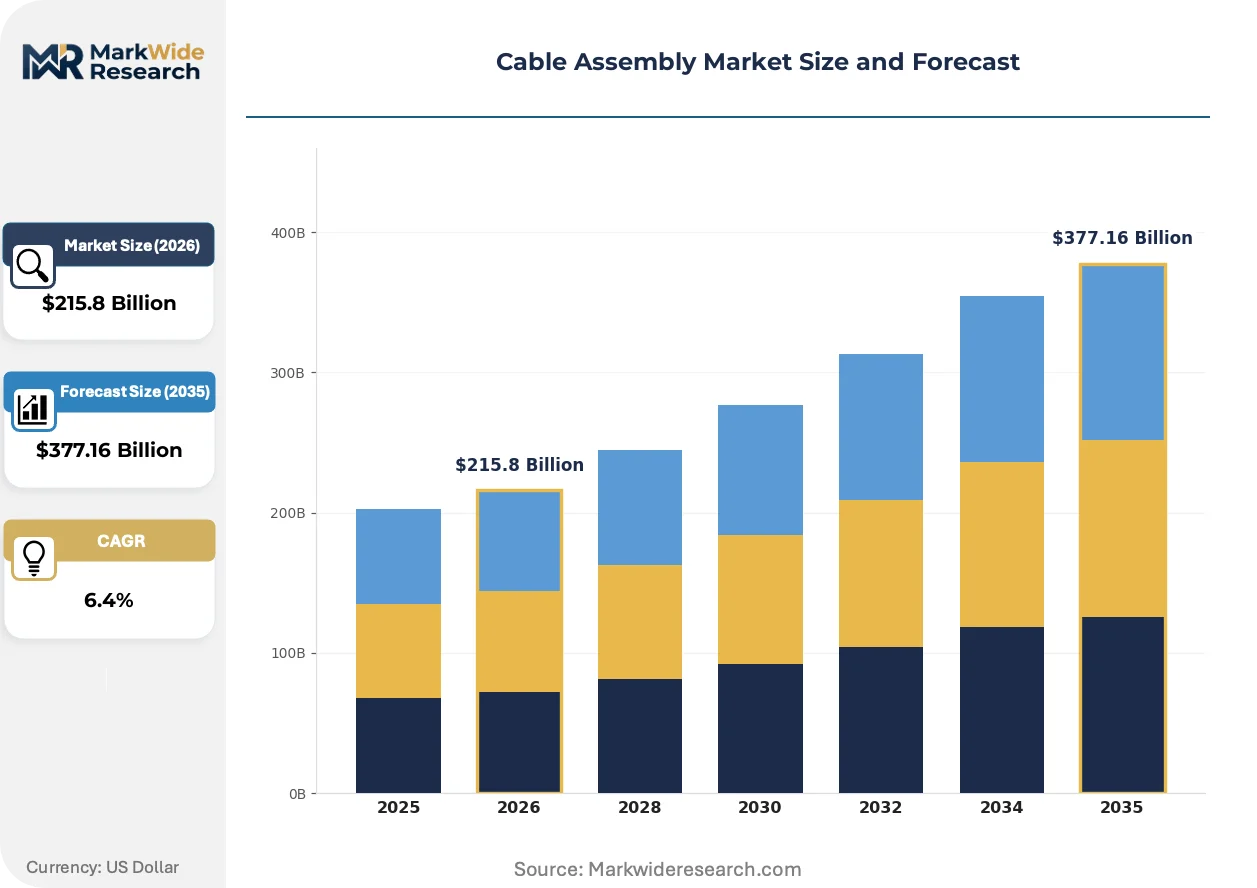
| Market Size in 2026 | $215.8 Billion |
| Market Size in 2035 | $377.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ribbon Cable, Coaxial Cable, Twisted Pair Cable, Fiber Optic Cable, Flat Cable Technology: Shielded, Unshielded, Armored, High-Flexibility, Low Smoke Zero Halogen Application: Telecommunications, Consumer Electronics, Aerospace & Defense, Renewable Energy, Data Centers End User: OEMs, System Integrators, Telecommunications Service Providers, Renewable Energy Installers, Data Center Operators |
| Companies Covered | Samtec, Fischer Connectors, TE Connectivity, Y.C. Cable, Gore, Molex, Aptiv, NAI Group, Amphenol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Assembly Market Strategic Shifts & Innovations
Active optical cable technology is digitizing signal transmission architectures, while regulatory material bans and procurement model evolution are simultaneously reshaping supplier qualification protocols and buyer-seller contracting structures.
Active optical cable assemblies incorporating silicon photonics transceivers are digitizing rack-to-rack and chip-to-chip interconnects in hyperscale data centers. Cloud operators are specifying these cables for distances under 100 meters where power consumption and signal integrity requirements exceed copper capabilities. This transition is digitizing physical layer infrastructure procurement, compressing the addressable market for traditional passive copper assemblies while expanding value capture for integrated photonics suppliers.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are tightening climate-controlled environment specifications for telecommunications infrastructure. Data center operators must now specify cable assemblies rated for wider temperature cycling in heat pump-based cooling architectures. North American colocation providers are responding fastest, rewriting procurement specifications to prioritize low-temperature flexibility ratings alongside fire safety certifications.
Consolidated procurement through contract manufacturing partnerships is displacing direct OEM-supplier relationships in automotive and consumer electronics verticals. Tier-1 electronics manufacturing services providers are capturing cable assembly specification authority, unbundling design engineering from volume production. This concentration is most visible in China, where domestic OEMs are mandating single-source responsibility for entire interconnect subsystems rather than discrete component procurement.
Cable Assembly Market Segmentation
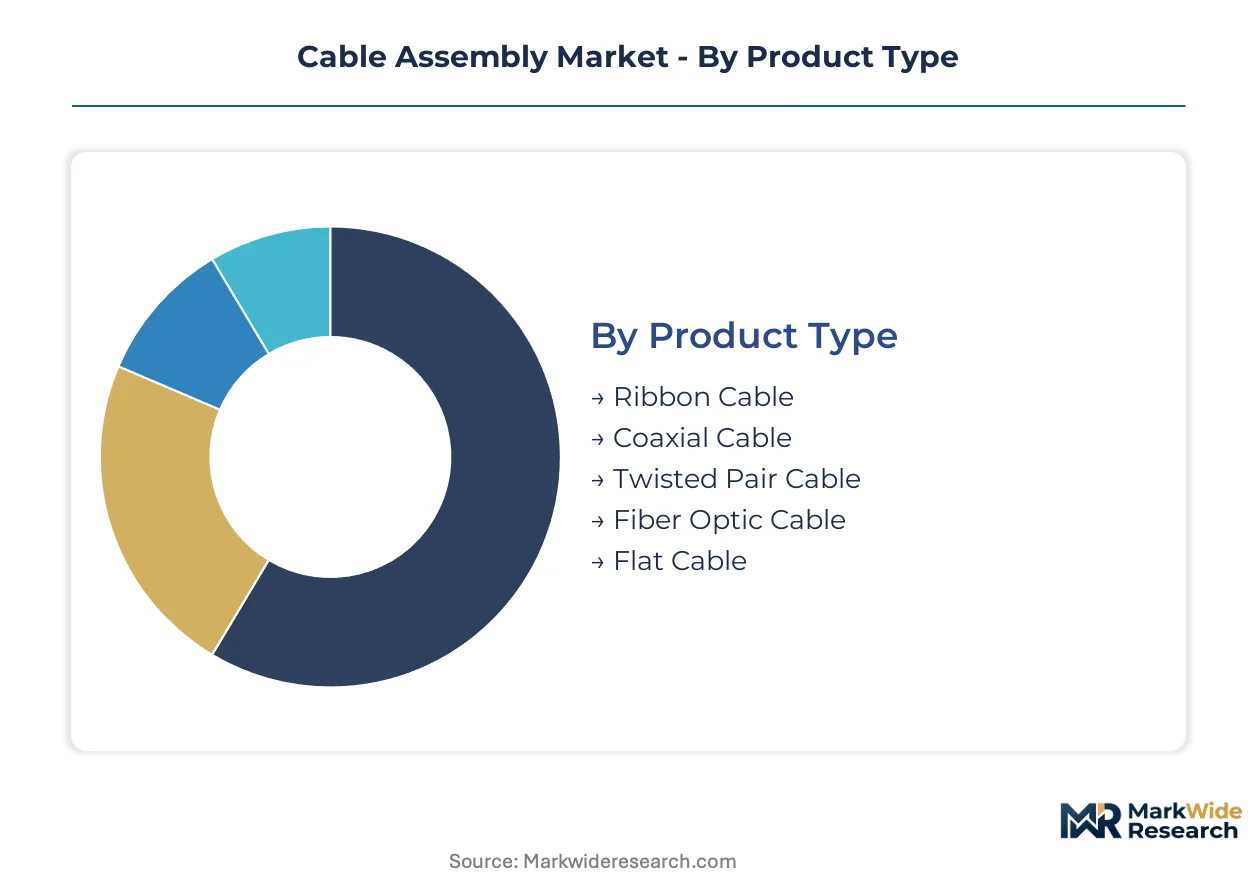
Cable assembly procurement cycles vary dramatically by segment, from commodity consumer electronics orders turning monthly to aerospace qualifications spanning years. Understanding these velocity differentials helps suppliers align inventory strategies and R&D prioritization with actual revenue timing.
Product Type:
Cycle times compress from years for aerospace-grade fiber to weeks for standard consumer ribbon cables, creating divergent working capital requirements across manufacturing footprints.
- Fiber Optic Cable:Silica-core waveguides with precision-polished terminations enable terabit-scale data transmission. Hyperscale data center operators in the United States and China dominate procurement, driven by AI training cluster densification and signal integrity mandates exceeding copper capabilities.
- Coaxial Cable:Concentric conductor-shield-dielectric construction preserves signal fidelity across RF applications. 5G base station deployments in Germany and South Korea concentrate demand, constrained by FCC Part 15 emissions compliance timelines and antenna subsystem integration complexity.
- Ribbon Cable:Parallel conductor arrays in planar configuration suit high-density PCB interconnects. Consumer electronics OEMs in Vietnam and Mexico specify these for laptop and display assemblies.
- Twisted Pair Cable:Paired conductor twisting rejects electromagnetic interference across analog and digital signaling. Industrial automation retrofits in Japan and Italy sustain replacement demand.
- Flat Cable:Extruded planar conductors enable compact routing in space-constrained enclosures. Automotive infotainment modules and medical device housings in Switzerland and Canada specify these for flex-life reliability.
Fiber optic cable anchors the volume base while low smoke zero halogen formulations gain share at the steepest rate.
Technology:
Cost tiers separate validated aerospace formulations from commodity building wire, with certification overhead creating 10-40x price multiples between adjacent tiers.
- Low Smoke Zero Halogen:Thermoplastic elastomer and polyolefin formulations eliminate halogenated flame retardants while maintaining IEC 60332-3-24 vertical tray burn performance. EU REACH compliance deadlines and London Underground specifications are redirecting mass transit and high-rise infrastructure procurement toward qualified suppliers.
- Shielded:Braided copper or aluminum foil layers attenuate electromagnetic emissions per CISPR 22 and FCC Part 15 limits. Automotive ADAS harnesses and industrial robotics in Germany and the United States specify these for functional safety integrity.
- High-Flexibility:Stranded conductor geometries and specialized jacket compounds survive millions of bending cycles. Semiconductor manufacturing equipment and cable carrier systems in Taiwan and the Netherlands require these for continuous motion reliability.
- Armored:Interlocked metal or corrugated stainless steel jackets resist mechanical abuse and rodent damage. Wind turbine tower installations and mining operations in Australia and Chile specify these for field durability.
- Unshielded:Basic insulated conductor construction serves cost-sensitive applications with minimal electromagnetic threat exposure. Residential and light commercial building wiring in India and Brazil sustains volume demand.
Unshielded technology captures the highest shipment volumes while low smoke zero halogen climbs the fastest on regulatory substitution.
Application:
Customer concentration runs from fragmented renewable energy installers to consolidated hyperscale data center operators with single-source qualification authority.
- Data Centers:Structured cabling and active optical interconnects supporting server-to-switch and switch-to-switch traffic. Cloud operators in Virginia, Singapore, and Ireland specify these for 400G/800G migration timelines and power efficiency mandates.
- Telecommunications:Outside plant and central office cable assemblies for wireline and wireless infrastructure. 5G fronthaul and midhaul deployments in South Korea and Germany concentrate demand, constrained by EU F-Gas Regulation cooling architecture changes.
- Aerospace & Defense:MIL-DTL-38999 connectorized harnesses and custom RF assemblies for platform electronics. Defense primes in the United States and France specify these for SWaP-C optimization and ITAR compliance.
- Renewable Energy:Solar string harnesses, wind turbine power cables, and battery storage interconnects. Utility-scale project developers in Spain and Morocco drive procurement for photovoltaic and offshore wind installations.
- Consumer Electronics:Internal device wiring and charging cable assemblies for smartphones, laptops, and wearables. Contract manufacturers in Vietnam and India consolidate specification authority under tier-1 EMS providers.
Telecommunications anchors the volume base while data centers gain share at the steepest rate.
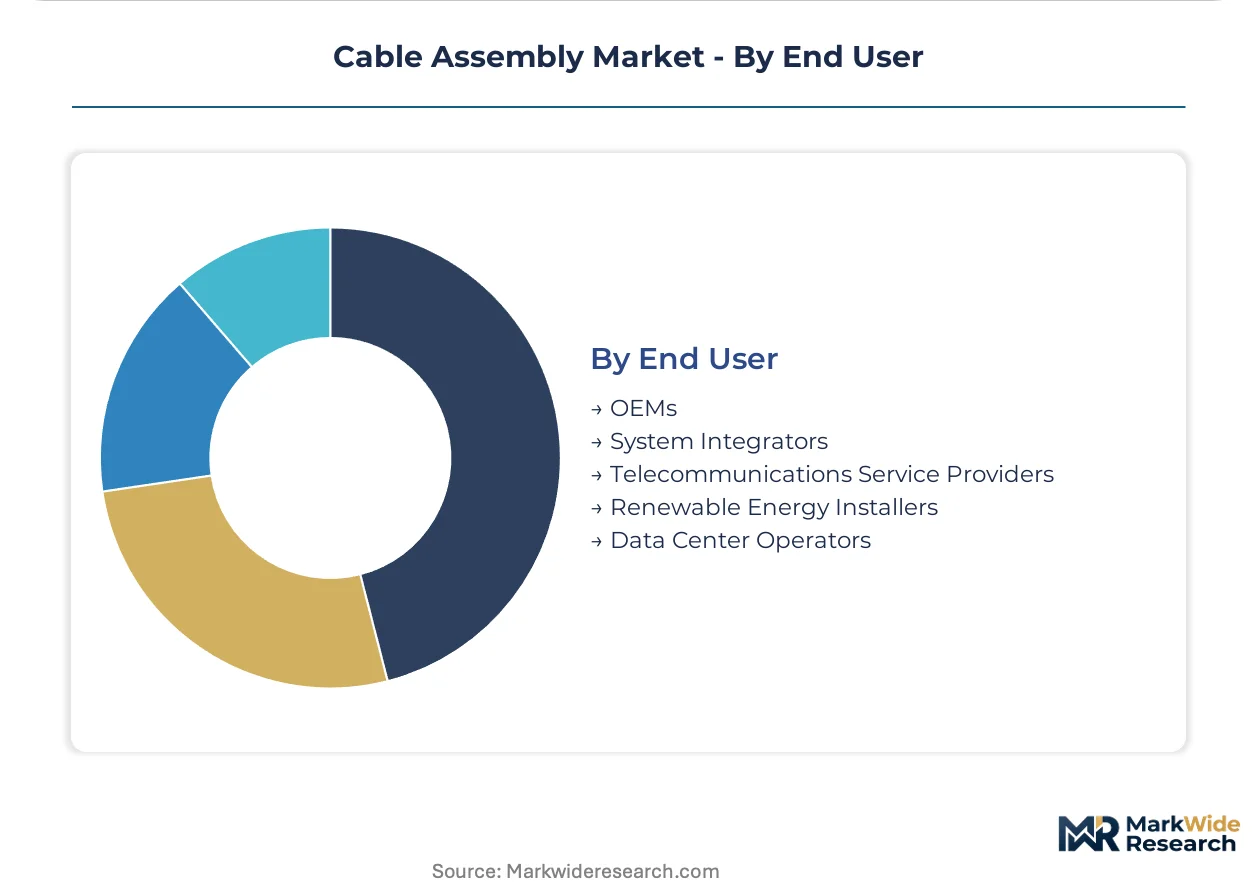
End User:
Procurement sophistication separates OEMs with captive engineering teams from installer channels relying on distributor technical support.
- Data Center Operators:Hyperscale and colocation providers with direct supplier relationships and custom specification authority. Operators in Northern Virginia, Frankfurt, and Singapore rewrite procurement standards for liquid cooling compatibility and fire safety.
- OEMs:Original equipment manufacturers across automotive, industrial, and medical verticals with design-controlled harness requirements. Electric vehicle platforms in China and Germany are consolidating domestic supply chain localization.
- Telecommunications Service Providers:Mobile network operators and fixed-line incumbents with outside plant deployment responsibility. Carriers in Japan and the United Kingdom specify these for fiber-to-the-premises and 5G densification programs.
- System Integrators:Industrial automation and building technology specialists assembling subsystem solutions. Machine builders in Italy and the United States source these for customized motion control and HVAC integration.
- Renewable Energy Installers:EPC contractors and field technicians executing solar and wind project construction. Developers in Brazil and Australia procure these for utility-scale installation and commissioning schedules.
OEMs anchor the volume base while data center operators gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances diverge sharply across manufacturing geographies. China maintains surplus positions in fiber optic and EV-grade assemblies, while the United States and Germany absorb net imports for data center and aerospace applications. Currency volatility and localized content mandates are rewiring traditional trade corridors.
China
Domestic OEMs are consolidating procurement for electric vehicle battery management systems and charging infrastructure. MIIT dual carbon goals and GB standards for halogen-free materials are accelerating supplier qualification protocols. Manufacturing clusters in Guangdong and Jiangsu provinces are scaling output for localized supply chains serving BYD and CATL platforms.
United States
Hyperscale data center operators in Northern Virginia and Dallas-Fort Worth are compressing procurement cycles for active optical interconnects. FCC Part 15 emissions standards and OSHA electrical safety directives constrain non-compliant market access. Defense primes in California and Texas specify MIL-DTL-38999 harnesses for platform electronics requiring ITAR compliance.
Germany
Automotive ADAS harness demand from Stuttgart and Munich engineering centers sustains shielded cable assembly volumes. EU REACH restrictions on halogenated flame retardants and KBA type-approval requirements redirect procurement toward LSZH-qualified suppliers. Industrial automation retrofits in the Ruhr region sustain twisted pair replacement demand.
Japan
Semiconductor manufacturing equipment builders in Tokyo and Osaka require high-flexibility assemblies for continuous motion reliability. METI energy efficiency mandates and JIS standards for fire safety shape material selection criteria. Robotics OEMs in Aichi Prefecture specify these for cable carrier systems in precision automation.
India
PLI scheme incentives for electronics manufacturing are attracting cable assembly investment to serve domestic and export demand. BIS certification requirements and CEA electrical safety regulations constrain import-dependent supply chains. Contract manufacturers in Tamil Nadu and Karnataka are consolidating specification authority under tier-1 EMS providers.
Cable Assembly Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with formulation and termination expertise. The vendor base separates into three strata: global diversified interconnect houses, regional contract assemblers, and captive polymer compounders. Competitive moves concentrate on backward integration into jacket material production and strategic partnerships with hyperscale data center operators.
Within the diversified interconnect tier, TE Connectivity, Amphenol, and Molex exemplify distinct strategic positions. TE Connectivity represents captive polymer compounding capabilities that sustain margin control across high-flexibility product lines. Amphenol anchors aerospace and defense positioning through connector-cable subsystem integration. Molex occupies a position in data center interconnects where density and signal integrity requirements escalate.
| Leading Market Players |
|---|
| Samtec |
| Fischer Connectors |
| TE Connectivity |
| Y.C. Cable |
| Gore |
| Molex |
| Aptiv |
| NAI Group |
| Amphenol |
| Others |
Cost & Logistics Intelligence
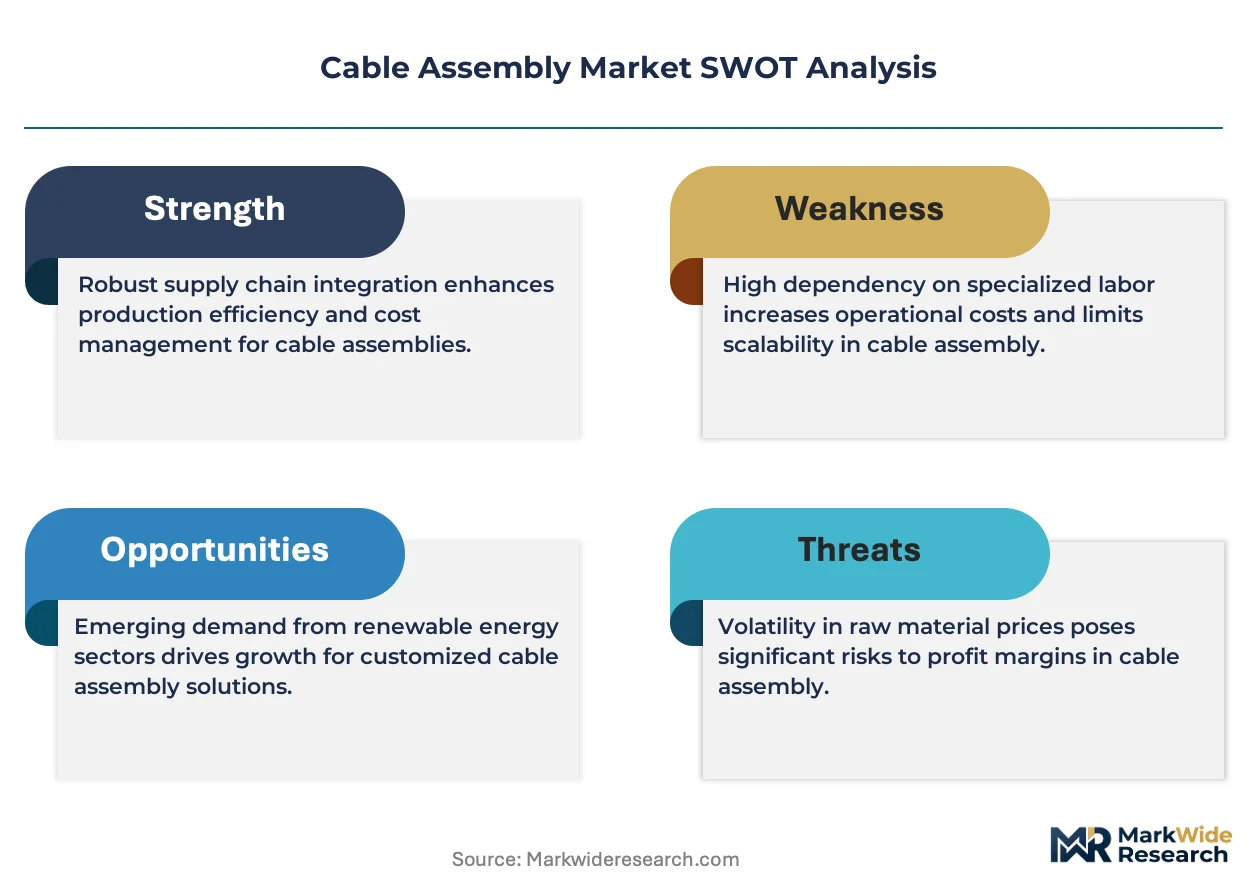
The Shanghai-Rotterdam maritime corridor carries fluoropolymer compounds and optical fiber preforms whose freight cost volatility amplifies margin compression for mid-tier cable assemblers lacking long-term material hedges. This logistics chokepoint concentrates pricing power among compounders with captive polymer production, forcing downstream buyers into tiered contract structures that separate certified aerospace suppliers from commodity wire distributors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on UL/CE certification grade and volume scale, with automotive harness producers commanding premiums for functional safety documentation. Cost compression in the standard tier intensifies because Chinese contract manufacturers are consolidating specification authority under tier-1 EMS providers. Renewable energy installers exhibit highest price sensitivity due to project-based procurement cycles, while data center operators show lowest sensitivity given signal integrity mandates.
Supply Chain Analysis
Export control restrictions on silicon photonics transceivers and advanced fluoropolymer formulations limit technology flows between the United States and China. Manufacturing concentrates in China, Vietnam, and Mexico for consumer-grade assemblies, while Germany and Japan anchor high-flexibility specialty production. Raw material sourcing draws from concentrated copper smelters in Chile, optical fiber preform suppliers in the United States and Japan, and halogen-free compounders in the Netherlands. Single-source vulnerability in fiber optic core manufacturing creates supply chain risk. Distribution runs through tier-1 electronics manufacturing services providers who capture specification authority from direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cable assembly market functions as a defensive-moat industry where regulatory entrenchment creates durable supplier advantages. Certification timelines and material qualification protocols erect barriers that reward incumbents with validated compound formulations.
For Market Incumbents: Build regulatory moats through accelerated EU REACH and RoHS compliance investments that strain testing capacity at third-party laboratories. Deepen backward integration into halogen-free polymer compounding to defend margin position against copper price volatility. Threaten emerging entrants by capturing tier-1 EMS provider specification authority in China and Vietnam through subsystem bundling rather than discrete component sales. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors where production-linked incentives are attracting cable assembly investment for domestic and export demand. Target renewable energy installers in Brazil and Australia with armored cable solutions for utility-scale solar and wind projects, a segment showing penetrable pricing elasticity. Go-to-market through direct EPC contractor relationships that bypass consolidated OEM procurement channels. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates divesting non-core interconnect divisions with stranded aerospace certifications. Long-term viability favors suppliers with validated low smoke zero halogen formulations as EU building codes tighten. Watch the fiber optic preform supply concentration as an inflection indicator—geographic diversification initiatives by hyperscale data center operators signal margin expansion for qualified alternative sources.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive halogen-free formulation production insulates TE Connectivity from fluoropolymer price swings. |
| Active Optical Cable Platform Launch | Silicon photonics integration enables Molex to capture value from hyperscale data center 400G/800G migrations. |
| Long-term Supply Agreement with EV OEM | CATL and BYD localization mandates in China create captive demand for battery management harness specialists. |
| Joint Venture for India PLI Corridor | Tamil Nadu and Karnataka EMS clusters offer tariff-advantaged export platforms for ribbon cable producers. |
| Certification Investment for EU REACH Compliance | Early LSZH qualification captures supplier scarcity premiums as London Underground specifications tighten. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with data center procurement officers, automotive platform engineers, tier-1 EMS provider supply chain directors, and polymer compounding R&D leads. Secondary validation drew from SEC 10-K filings, EU ECHA substance restriction databases, FCC equipment authorization records, and customs trade flow data for fluoropolymer and copper conductor categories. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure cross-verification.
Calibration against historical volume trajectories and material input cost indices shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, jacket technology tier, application vertical, and end-user procurement sophistication. CAGRs were derived from regression analysis of shipment volumes against capital expenditure cycles in data center and electric vehicle end markets. Forecast inputs incorporated MIIT dual carbon policy timelines and hyperscaler disclosed infrastructure spending plans.
Stress conditions across copper and fluoropolymer price bands, EU regulatory acceleration scenarios, and wireless power substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about certification timeline compression and EMS provider consolidation trajectories. Cross-checking against disclosed hyperscale data center capex benchmarks and automotive OEM electrification roadmaps is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
SATA Power Cable Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Active Optical Cable Market
Cables
Underground Cable Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Sensing Cable Market
Cables
Coaxial Cable Market
Cables
Cable Fault Locator Market
Cables
Copper Stranded Wire Market
Cables
Cable Organisers Market
Cables
Insulated Wire and Cable Market
Cables
Copper Cable Market
Cables
Global Wires and Cables Market
Cables
Fire Resistance Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Asia-Pacific Premise Cable Market