
 Connecting Chiplets Market | 2026-2036
Connecting Chiplets Market Size, Share, and Industry Trends Forecast 2026-2036
Connecting Chiplets Market Outlook
Multi-source procurement for advanced packaging substrates is recalibrating how semiconductor firms secure interconnect capacity. Intel Corporation leverages its IDM model to sustain captive production of EMIB and Foveros technologies at scale in Arizona and Oregon. TSMC anchors global supply of silicon interposer-based CoWoS, competing directly with Samsung Electronics, which controls its own 2.5D and 3D packaging roadmap out of Pyeongtaek.
Connecting chiplets refers to the electrical and thermal interfacing of discrete semiconductor dies through high-density interconnect layers, typically employing copper pillar microbumps with pitches below 55 micrometers or hybrid bonding below 10 micrometers, to functionally operate as a single integrated device. The technique enables yield recovery, node mixing, and die-size optimization for processors exceeding reticle limits. Silicon interposer and CoWoS connection technologies dominate current revenue pools, while embedded bridge architectures and fan-out packaging differentiate on cost-sensitive consumer electronics and mid-range telecom gear where substrate area constraints matter less.
The U.S. CHIPS Act, Japan's METI semiconductor subsidy program, and China's MIIT dual carbon goals collectively shape where advanced packaging capacity localizes and which connection technologies qualify for public funding. FDA and FCC frameworks indirectly influence chiplet demand through medical device and telecommunications equipment certification pathways that specify thermal cycling reliability. Stakeholders must monitor which regulatory jurisdictions relax environmental permitting for new packaging fabs, as this determines where supply bottlenecks for high-bandwidth memory interfaces will ease first.
Market Dynamics
Silicon interposer capacity constraints at TSMC and Samsung are forcing AI accelerator designers to qualify alternative bridge architectures and fan-out substrates, redistributing procurement risk across multiple packaging nodes.
Growth Catalysts
- Reticle-Limit Compute Demand:AI training clusters require multi-die processors exceeding 800mm² reticle boundaries, mandating chiplet disaggregation and high-density interconnect layers for functional yield.
- Japan's METI Semiconductor Subsidy Program:Tokyo's funding framework for advanced packaging equipment is accelerating domestic substrate and interposer capacity buildout to reduce import dependency for 2.5D assembly.
- Hybrid Bonding Below 10 Micrometers:Copper-to-copper direct bonding eliminates microbump pitch limitations, enabling memory-logic stacking for high-bandwidth interfaces in next-generation accelerators.
Market Restraints
- ABF Substrate Supply Concentration:Taiwan and Japan control over 80% of ABF laminate production, creating single-source vulnerability for CoWoS and EMIB base layers during demand spikes.
- Hybrid Bonding Capex Intensity:Wafer-to-wafer alignment equipment and cleanroom upgrades require $500M+ per fab line, limiting adoption to captive IDM and foundry ecosystems.
- EU REACH Chemical Restrictions:Candidate substance listings for novel dielectric polymers and underfill materials extend qualification timelines by 12-18 months for European-bound packaging flows.
Strategic Opportunities
- India's PLI Scheme for Electronics:Modified incentive structures now cover semiconductor assembly and test operations, attracting OSAT investment for mid-range consumer chiplet packaging.
- Automotive Functional Safety Certification:ISO 26262-compliant chiplet architectures open ADAS and autonomous drive compute to disaggregated silicon, replacing monolithic SoCs with qualified multi-die modules.
- Photonics-Electronics Convergence:Co-packaged optical I/O chiplets bonded to switch ASICs enable 51.2Tbps router capacity, with Intel and Ayar Labs driving foundry process co-development.
Industry Challenges
- Known-Good-Die Testing Complexity:Pre-bond electrical screening of chiplets at advanced nodes requires probe card investments exceeding $10M per device type, raising cost barriers for heterogeneous integration.
- Thermal Interface Material Standardization:Proprietary TIM formulations between stacked dies complicate second-source qualification and field replacement protocols for data center operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connecting Chiplets Market |
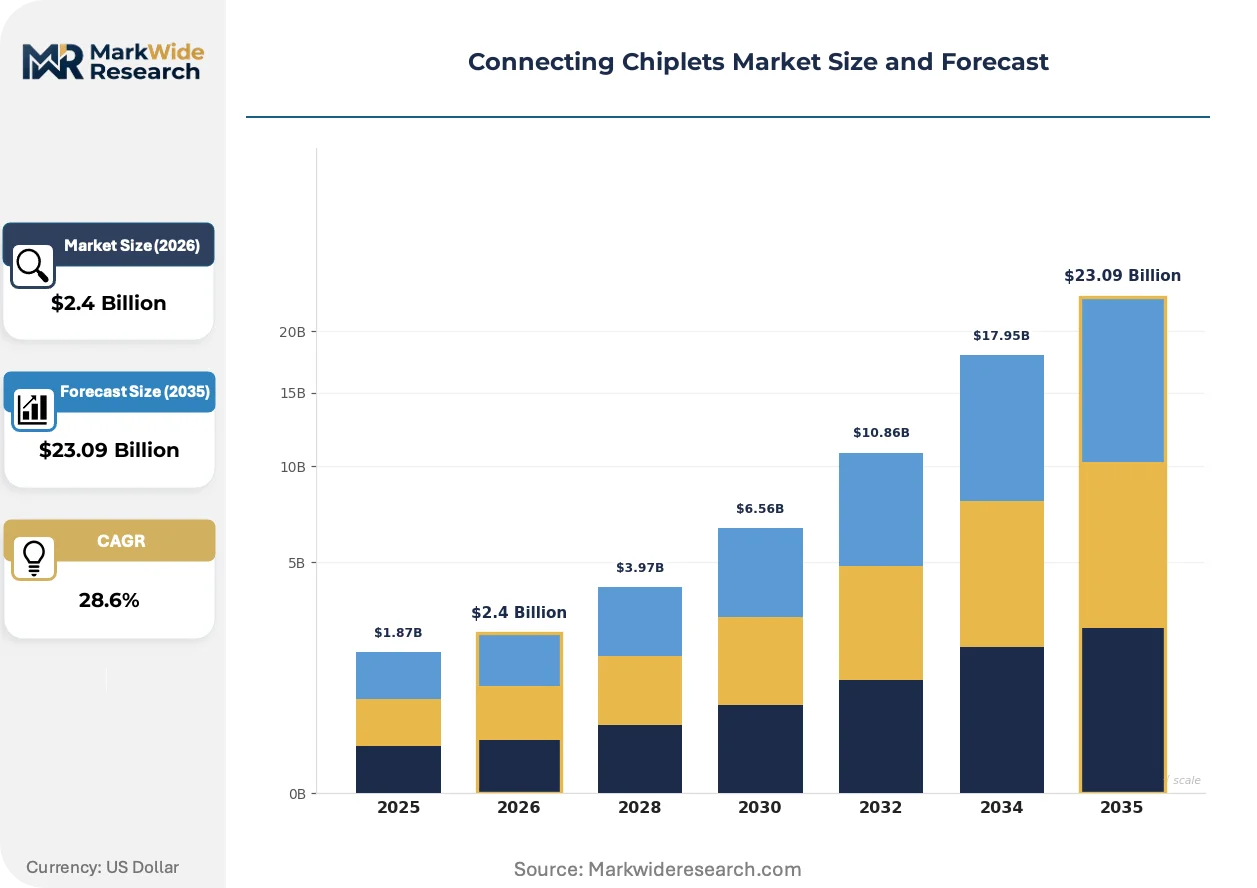
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $23.09 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Connection Technology: Silicon Interposer, Embedded Bridge, CoWoS, EMIB, Foveros End Application: Data Centers, Consumer Electronics, Aerospace Systems, Telecommunication Equipment, High-Performance Computing Packaging Type: 2.5D Packaging, 3D Packaging, Fan-Out Packaging, Flip Chip Packaging End User Industry: Semiconductor Foundries, Integrated Device Manufacturers, Fabless Companies, OSAT Providers |
| Companies Covered | Intel Corporation, Advanced Micro Devices (AMD), TSMC (Taiwan Semiconductor Manufacturing Company), NVIDIA Corporation, Samsung Electronics, IBM Corporation, Marvell Technology, Apple Inc., Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connecting Chiplets Market Strategic Shifts
Interconnect pitch scaling and substrate material diversification are compressing traditional packaging hierarchies, enabling new combinations of logic, memory, and photonics in unified footprints previously unreachable.
Hybrid bonding is integrating copper-to-copper interfaces at sub-10 micrometer pitches, eliminating solder microbumps entirely. Hyperscale data center operators are qualifying these stacks for AI training accelerators where thermal cycling reliability exceeds 1,000 cycles. This integration is compressing the gap between 2.5D interposer and true 3D stacking economics, forcing substrate suppliers to develop compatible dielectric formulations.
China's MIIT dual carbon goals are restricting energy-intensive packaging fab expansions in coastal provinces, redirecting capacity inland to Sichuan and Hubei where hydropower dominates the grid. Foreign equipment vendors face localization requirements for bonding tools and inspection systems. Domestic OSATs are responding by accelerating captive development of bridge and fan-out processes to reduce licensing exposure.
Accelerator designers are unbundling memory procurement from logic sourcing, negotiating HBM supply independently from foundry wafers. This disintermediation fragments traditional turnkey packaging contracts, with AI chip firms now managing three-tier supplier relationships across interposer, memory, and compute die vendors. The practice is most visible in Taiwan, where CoWoS capacity constraints have normalized multi-vendor integration risk management.
Connecting Chiplets Market Segmentation
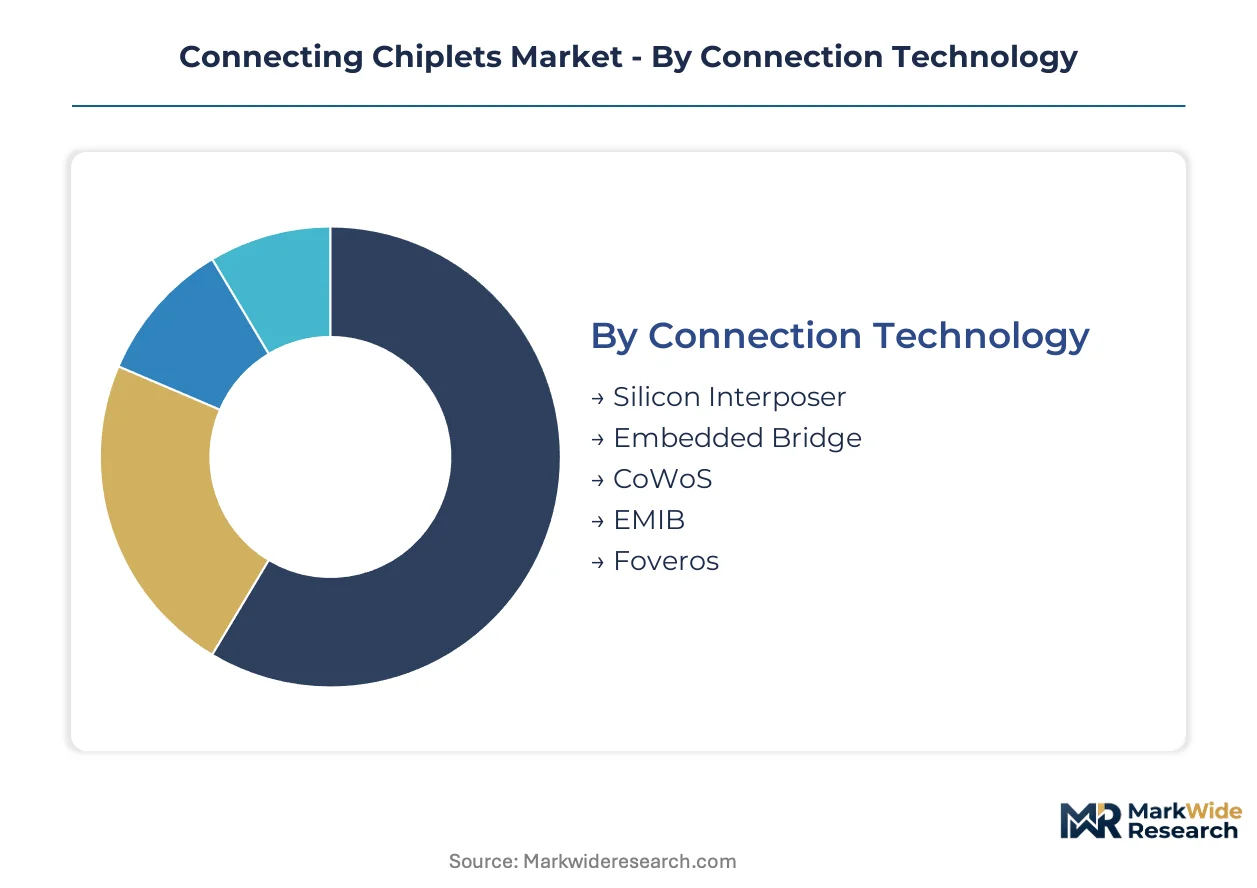
Chiplet connectivity architectures fragment across multiple technical and commercial dimensions. Procurement teams qualify suppliers against packaging node maturity, thermal performance thresholds, and captive versus outsourced manufacturing strategies.
Connection Technology:
Equipment refresh cycles in advanced packaging fabs determine which interconnect generations achieve scale adoption.
- Silicon Interposer:TSV-based silicon substrates enable sub-micron routing densities between logic and memory dies. TSMC's CoWoS-S platform dominates AI accelerator procurement from Taiwan and Arizona fabs, constrained by ABF substrate availability during demand surges.
- CoWoS:Chip-on-Wafer-on-Substrate integrates multiple dies on silicon interposer with organic substrate base. NVIDIA and AMD datacenter GPU roadmaps depend entirely on TSMC CoWoS capacity expansion in Taichung and Kaohsiung.
- Embedded Bridge:Localized silicon interconnect segments embedded within organic substrates reduce interposer area requirements. Intel's EMIB 2.0 qualifies for client CPU disaggregation where cost sensitivity exceeds bandwidth demands of full interposer solutions.
- EMIB:Intel's proprietary embedded multi-die interconnect bridge enables 2.5D integration without full silicon interposer. Production concentrates at Chandler, Arizona and Hillsboro, Oregon facilities serving internal product roadmaps.
- Foveros:Face-to-face die stacking with active interposers enables true 3D logic-on-logic integration. Meteor Lake and Arrow Lake client processors utilize Foveros Direct for power efficiency gains in mobile compute segments.
Silicon Interposer sits at the top of the volume ranking, with Embedded Bridge climbing the fastest.
End Application:
Application-specific thermal cycling requirements and reticle-size constraints dictate packaging node selection across customer segments.
- Data Centers:AI training clusters drive CoWoS and 3D stacking adoption where thermal design power exceeds 700W per accelerator. Hyperscale operators in Northern Virginia, Frankfurt, and Singapore specify chiplet architectures for bandwidth scaling beyond monolithic reticle limits.
- High-Performance Computing:Exascale systems from Oak Ridge, RIKEN, and Forschungszentrum Jülich mandate heterogeneous integration for memory bandwidth and power efficiency. Government procurement cycles favor qualified 2.5D solutions over emerging 3D stacks.
- Telecommunication Equipment:Baseband processors and optical transceivers utilize fan-out packaging where substrate area constraints matter less than cost optimization. 5G infrastructure buildouts in South Korea and Germany sustain mid-range packaging demand.
- Consumer Electronics:Smartphone application processors and wearables prioritize fan-out and flip-chip solutions for thickness reduction. Apple's A-series and M-series silicon at TSMC InFO anchors high-volume consumption.
- Aerospace Systems:Radiation-hardened requirements and extreme thermal cycling specifications favor qualified 2.5D over unproven 3D stacks. Satellite constellation operators qualify multi-die modules through NASA and ESA certification pathways.
Data Centers command the largest revenue share, with High-Performance Computing gaining share fastest.
Packaging Type:
Capital intensity and yield learning curves stratify supplier capabilities across packaging generations.
- 2.5D Packaging:Silicon interposer-based integration enables multi-die processors without through-silicon vias through active logic. Mature yield curves and established supply chains sustain dominance for AI accelerators and networking switch ASICs.
- 3D Packaging:True vertical stacking with hybrid bonding or microbumps maximizes interconnect density and power efficiency. Wafer-to-wafer alignment equipment requirements limit adoption to TSMC, Samsung, and Intel captive facilities.
- Fan-Out Packaging:Redistribution layer on molded epoxy compound eliminates substrate cost for mobile and IoT applications. TSMC InFO and ASE FOCoS-B compete for smartphone AP and baseband processor volumes.
- Flip Chip Packaging:Solder bump interconnect to organic substrate remains cost-optimized solution for mature nodes and lower I/O counts. OSATs in Malaysia and Vietnam sustain high-volume production for automotive and industrial segments.
2.5D Packaging leads current revenue pools, with 3D Packaging expanding most quickly.
End User Industry:
Business model differentiation determines captive versus outsourced packaging procurement strategies.
- Semiconductor Foundries:TSMC, Samsung Foundry, and Intel Foundry Services bundle advanced packaging with wafer fabrication for AI accelerator customers. CoWoS and 3D stacking capacity constraints force allocation decisions based on customer strategic priority.
- Fabless Companies:NVIDIA, AMD, Broadcom, and Marvell design multi-die architectures without captive manufacturing, depending entirely on foundry packaging roadmaps. HBM procurement disintermediation fragments traditional turnkey relationships.
- Integrated Device Manufacturers:Intel and Samsung retain in-house packaging for product differentiation and supply security. IDM 2.0 strategy expands Intel Foundry Services packaging availability to external customers.
- OSAT Providers:ASE, Amkor, and JCET handle mid-range 2.5D, fan-out, and flip-chip volumes where foundry capacity is constrained or cost-prohibitive. India's PLI scheme attracts OSAT investment for assembly and test operations.
Semiconductor Foundries capture the highest value-add per unit, with OSAT Providers scaling fastest on volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwan's Hsinchu Science Park anchors global chiplet interconnect capacity, with TSMC's CoWoS and InFO platforms processing the majority of AI accelerator and high-performance computing silicon worldwide.
United States
Data center operators in Northern Virginia and Phoenix are scaling chiplet-based server deployments to manage thermal loads exceeding 700W per accelerator. The CHIPS Act directs subsidies toward advanced packaging fabs in Arizona and Oregon. Intel's Hillsboro and Chandler facilities sustain captive EMIB and Foveros production for internal and external foundry customers.
China
Domestic AI chip designers are accelerating bridge and fan-out process development to reduce licensing exposure to foreign interconnect technologies. MIIT dual carbon goals restrict energy-intensive packaging expansions in coastal provinces, redirecting capacity inland to Sichuan and Hubei. OSATs in Jiangsu and Guangdong are qualifying alternative substrate materials for mid-range consumer chiplet assembly.
South Korea
Samsung Electronics controls its own 2.5D and 3D packaging roadmap from Pyeongtaek, competing directly with TSMC for HBM-logic integration contracts. Government semiconductor subsidies under the K-Semiconductor Belt program support advanced packaging equipment localization. The Yongin cluster is emerging as a secondary hub for hybrid bonding process development.
Japan
Tokyo's METI semiconductor subsidy program accelerates domestic substrate and interposer capacity buildout to reduce import dependency for 2.5D assembly. ABF laminate suppliers in Nagoya and Osaka are expanding output to qualify as second sources for CoWoS base layers. Government procurement for exascale computing at RIKEN sustains demand for qualified heterogeneous integration.
India
Modified PLI scheme incentives now cover semiconductor assembly and test operations, attracting OSAT investment for mid-range consumer chiplet packaging. State governments in Gujarat and Karnataka are offering land and power concessions for packaging fab development. Domestic electronics manufacturers are qualifying fan-out processes for smartphone application processor integration.
Connecting Chiplets Market Competitive Environment
Global majors compete with regional champions across interconnect technology generations, with captive IDM facilities in the United States and South Korea vying against foundry-dependent fabless designers concentrated in Taiwan and California. The vendor structure stratifies across three tiers: integrated device manufacturers controlling end-to-end packaging roadmaps, pure-play foundries bundling advanced assembly with wafer fabrication, and outsourced assembly providers handling cost-optimized mid-range volumes. Two dominant competitive moves are reshaping positioning: capacity expansion in Arizona, Taiwan, and Pyeongtaek to relieve CoWoS bottlenecks, and strategic partnerships between logic designers and memory suppliers to secure HBM allocation independent of traditional turnkey contracts.
Within the foundry-tier, TSMC and Samsung Electronics exemplify the scale-driven archetype, anchoring global supply of silicon interposer-based integration for AI accelerators. Intel Corporation occupies a hybrid position, leveraging IDM 2.0 strategy to expand packaging availability to external customers while sustaining captive production for internal product roadmaps.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices (AMD) |
| TSMC (Taiwan Semiconductor Manufacturing Company) |
| NVIDIA Corporation |
| Samsung Electronics |
| IBM Corporation |
| Marvell Technology |
| Apple Inc. |
| Broadcom Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive packaging integration at Intel, TSMC, and Samsung anchors both supply security and pricing power, with IDM-controlled EMIB and Foveros roadmaps insulating against foundry allocation volatility while fabless designers absorb CoWoS scarcity premiums. The CHIPS Act subsidy framework in the United States and METI programs in Japan are redirecting capital toward domestic advanced packaging capacity, reshaping where interconnect costs localize and which buyers capture volume discounts.
Pricing Analysis
Input-cost pass-through from ABF substrate shortages and hybrid bonding equipment capex is compressing margins across mid-range packaging tiers. Contract-based long-term offtake dominates AI accelerator procurement, with CoWoS capacity constraints forcing premium pricing for expedited silicon interposer slots. Price differentiation hinges on thermal cycling certification grade and HBM integration complexity, with hyperscale data center operators showing lowest price sensitivity due to reticle-limit compute requirements, while consumer electronics OEMs face acute pressure from fan-out packaging cost floors.
Supply Chain Analysis
Reverse-logistics flows for probe card refurbishment and thermal interface material replacement are emerging as secondary supply channels, though known-good-die testing complexity limits viable recovery rates. Taiwan, South Korea, and the United States concentrate silicon interposer and hybrid bonding capacity, with the supply chain drawing from Japanese ABF laminate, German wafer-to-wafer alignment equipment, and domestic Chinese bridge substrates. Single-source vulnerability in Taiwan-Japan ABF production creates structural risk during demand spikes. Distribution runs through foundry-direct allocation for AI accelerators, with OSATs handling fan-out and flip-chip volumes for cost-optimized segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the U.S. CHIPS Act and Japan's METI semiconductor subsidy program driving domestic capacity buildout that reshapes procurement geography and pricing power.
For Market Incumbents: Lock in HBM-logic integration contracts through captive CoWoS allocation agreements before Pyeongtaek and Arizona capacity comes online. Expand hybrid bonding cleanroom footprints in Taiwan and Oregon to defend against Samsung's 3D packaging roadmap. Prioritize ISO 26262 automotive certification investment as ADAS compute shifts from monolithic SoCs to qualified multi-die modules, creating defensible switching costs against emerging bridge architectures. For New Entrants and Emerging Players: The premium-to-economy gap in mid-range telecom baseband processors offers white-space entry, with fan-out packaging demand from India's PLI scheme attracting OSAT investment for smartphone application processor integration. Target Gujarat and Karnataka state concessions for assembly and test operations. Pursue photonics-electronics convergence partnerships with switch ASIC designers as co-packaged optical I/O chiplets displace pluggable transceivers in 51.2Tbps router deployments. For Investors and Strategic Acquirers: Roll-up economics work for specialized substrate suppliers because ABF laminate qualification timelines and CoWoS base-layer certification create sticky foundry relationships that resist commoditization. Target second-source ABF producers in Nagoya and Osaka expanding output for TSMC qualification. Monitor MIIT dual carbon enforcement intensity in coastal Chinese provinces as the inflection signal for domestic OSAT captive process development and foreign equipment localization requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Capacity Expansion | TSMC and Samsung wafer-to-wafer alignment investments in Taichung and Pyeongtaek relieve AI accelerator bottlenecks. |
| Automotive Functional Safety Certification | ISO 26262-compliant chiplet architectures open ADAS compute to heterogeneous integration at Intel and Samsung. |
| Photonics-Electronics Convergence Partnership | Co-packaged optical I/O chiplets bonded to switch ASICs enable 51.2Tbps router capacity at hyperscale operators. |
| Domestic Substrate Capacity Buildout | METI-funded ABF laminate expansion in Nagoya reduces CoWoS import dependency for Japanese exascale procurement. |
| India PLI Scheme Assembly Investment | Modified incentives for semiconductor test operations attract ASE and Amkor to Gujarat packaging fab development. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging engineering directors, foundry allocation managers, OSAT procurement leads, and hyperscale data center hardware strategists with secondary validation from SEC 10-K filings, TSMC and Intel technology disclosure documents, and CHIPS Act subsidy award announcements. Bottom-up die shipment estimates and top-down wafer fab equipment spend analysis were triangulated against CoWoS and InFO revenue disclosures.
Segment-weighting approaches modeled connection technology, end application, packaging type, and end user industry dimensions across the projection horizon. CAGRs were derived from equipment refresh cycle timing, yield learning curve slopes, and regulatory subsidy disbursement schedules. Forecast inputs incorporated ABF substrate capacity expansion timelines and hybrid bonding cleanroom construction lead times specific to advanced packaging fab economics.
Caveats apply where MIIT dual carbon enforcement intensity, EU REACH chemical restrictions on novel dielectric polymers, or TSMC CoWoS allocation priority shifts could materially shift the outlook. Practitioners should monitor Japan METI subsidy disbursement velocity and U.S. EPA environmental permitting timelines for Arizona packaging fabs as early signals of supply bottleneck resolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Global Wireless Chipsets Market
Chipset and Processors
South Korea Data Center Processor Market
Chipset and Processors
Poe Chipsets Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
Tablet and E-Reader Application Processor Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Americas Digital Signal Processor Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Advanced Audio Processor Market
Chipset and Processors
Global Neural Processors Market
Chipset and Processors
Global LCD TV Core Chip Market
Chipset and Processors
Multi-Core Processors Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Wi-Fi Chipset Market