
 Flat Flexible Cables Market | 2026-2036
Flat Flexible Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Flat Flexible Cables Market Analytics
Buyer concentration in consumer electronics is recalibrating as smartphone OEMs consolidate supplier rosters while automotive tier-1s fragment procurement across regional cable specialists. TE Connectivity leverages its automotive connector heritage to anchor high-reliability FFC programs for electric powertrains. Sumitomo Electric sustains dominant positions in fine-pitch copper lamination through captive metallurgy capabilities in Japan. Luxshare-ICT competes aggressively for Apple supply chain slots, extending its vertical reach from assembly into cable subcomponent production.
Flat flexible cables are thin, multi-conductor interconnects manufactured by laminating flat copper conductors between polyester or polyimide dielectric layers, typically achieving pitch dimensions below 0.5 mm for high-density signal routing in space-constrained assemblies. Their primary purpose is replacing round wire harnesses where weight reduction, bending tolerance, and planar routing geometry prove critical. FPC variants command premium positioning in medical devices and foldable display hinge circuits where dynamic flex life exceeds one million cycles, while standard FFC volumes concentrate in consumer electronics printer heads and flat-panel displays where cost sensitivity dominates. PVC-insulated constructions retain share in industrial equipment despite polymer alternatives gaining traction under EU REACH substance restrictions.
FCC electromagnetic compatibility rules in the United States, China's GB 4943.1 safety standards for information technology equipment, and the EU's CE marking framework under the Low Voltage Directive collectively shape product certification burdens and market access timelines for cable manufacturers. RoHS and REACH compliance costs disproportionately burden smaller material suppliers, accelerating consolidation in European polymer compound sourcing. Stakeholders must monitor evolving automotive functional safety standards and substrate material substitutions as electrification volumes scale and sustainability reporting obligations tighten across OEM procurement criteria.
Market Dynamics
Automotive electrification is compressing development cycles for high-reliability interconnects, forcing cable manufacturers to reconcile fine-pitch copper lamination with functional safety certification timelines that stretch 18-24 months for new powertrain programs.
Growth Catalysts
- ADAS Sensor Proliferation:Camera and lidar modules in vehicles require flexible routing solutions that withstand vibration and thermal cycling. Automotive tier-1s are expanding FFC procurement for surround-view systems.
- RoHS Compliance Mandates:The EU's hazardous substance restrictions are phasing out lead-based solder connections. Manufacturers are accelerating halogen-free dielectric development to maintain European market access.
- Foldable Display Hinge Circuits:Dynamic flex life requirements exceeding one million cycles are driving polyimide substrate adoption. South Korean panel makers are qualifying new metallization processes for book-type phone form factors.
Market Restraints
- Copper Price Volatility:Raw material fluctuations compress margins on standard FFC constructions used in cost-sensitive printer and display applications. Smaller compounders lack hedging capacity.
- East Asian Supply Concentration:Fine-pitch lamination capacity clusters in Japan and South Korea. Western automotive OEMs face single-source risk for 0.3 mm pitch specifications.
- Polymer Substitution Limits:Liquid crystal polymer alternatives promise superior moisture resistance but require incompatible termination equipment. Retrofit costs stall adoption in existing assembly lines.
Strategic Opportunities
- Indian Electronics Manufacturing:Production-linked incentive schemes are attracting smartphone assembly investment. Local cable sourcing gaps create entry points for qualified suppliers.
- Medical Imaging Miniaturization:Portable ultrasound and endoscopic systems demand biocompatible flex circuits. ISO 10993 certification opens premium positioning beyond consumer electronics.
- Battery Management Integration:Cell monitoring architectures in electric vehicles combine voltage sensing with temperature telemetry. Multi-layer FFC designs consolidate wiring density in constrained pack geometries.
Industry Challenges
- Functional Safety Talent Scarcity:ISO 26262 implementation for automotive programs requires specialized reliability engineers. Cable specialists compete with semiconductor firms for qualified personnel.
- Cross-Contamination Control:Medical and automotive production lines demand segregated cleanroom protocols. Capital allocation for dual-facility qualification strains mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flat Flexible Cables Market |
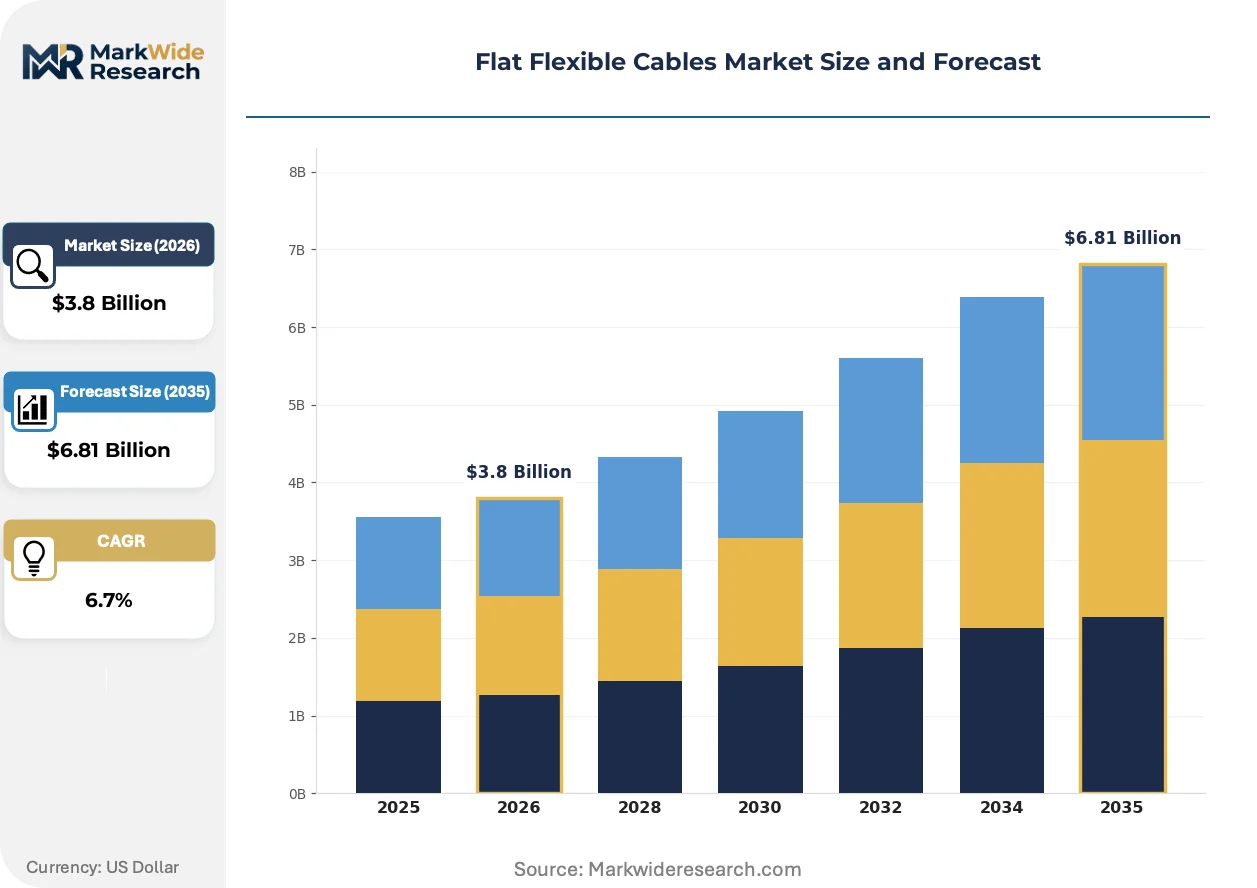
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: FFC, FPC, TFFC, RFFC Application: Consumer Electronics, Automotive, Industrial Equipment, Medical Devices Material: Copper, Polymer, PVC, Insulated Metals End User: Manufacturers, OEMs, Distributors, Retailers |
| Companies Covered | Samtec, Würth Elektronik, Sumitomo Electric, TE Connectivity, Luxshare-ICT, Johnson Electric, Axon Cable, Nicomatic, Molex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flat Flexible Cables Market Evolving Landscape
Material science advances and certification regime tightening are redefining competitive differentiation. Manufacturers are racing to align substrate formulations with evolving sustainability disclosure requirements while maintaining signal integrity at finer pitches.
Embedded passive technology is converging with traditional FFC constructions to integrate resistive and capacitive elements directly into the laminate stack. Automotive module suppliers are piloting these configurations for antenna and sensor applications where discrete component placement consumes excessive board area. This convergence is compressing the traditional separation between cable and printed circuit board procurement categories.
REACH substance restrictions are expanding the SVHC candidate list faster than reformulation cycles. European polymer compounders are accelerating bio-based polyester development to preempt authorization requirements for conventional flame retardants. Medical device manufacturers face the steepest compliance burden, as biocompatibility testing must be repeated for each material substitution.
Consolidated supplier rosters among top-tier smartphone OEMs are squeezing second-tier cable vendors into automotive and industrial verticals. Direct procurement relationships are replacing distributor-mediated transactions for high-volume programs. This pattern is most pronounced in China's Pearl River Delta, where assembly plants now mandate vendor-managed inventory arrangements with component suppliers.
Flat Flexible Cables Market Segmentation
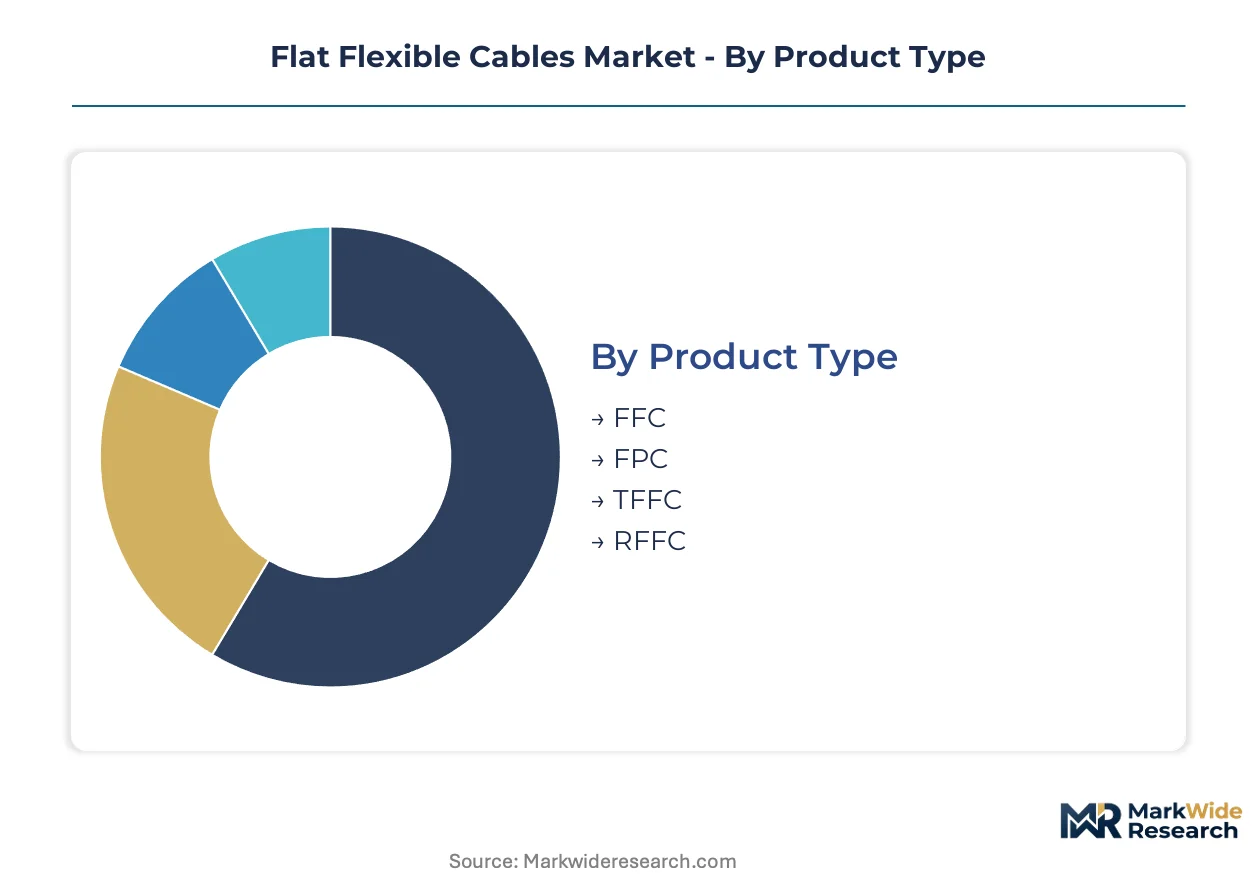
FFC product differentiation hinges on bending tolerance, pitch density, and dielectric material selection. Procurement patterns diverge sharply between cost-driven consumer electronics and reliability-critical automotive programs. Material compliance requirements under REACH and RoHS further stratify supplier capabilities across segment boundaries.
Product Type:
Fine-pitch lamination capacity clusters in Japanese and South Korean manufacturing corridors, creating supply-side bottlenecks for automotive qualification programs.
- FPC:Polyimide-based constructions achieve dynamic flex life exceeding one million cycles through specialized metallization processes. South Korean panel makers dominate procurement for foldable display hinge circuits where book-type phone form factors demand extreme bending tolerance.
- FFC:Standard polyester-laminated copper conductors serve cost-sensitive printer heads and flat-panel displays. China's consumer electronics assembly corridors absorb the highest volumes, though margin compression from copper price volatility strains smaller compounders.
- TFFC:Twisted flat constructions address crosstalk limitations in high-speed signal routing for data transmission equipment.
- RFFC:Reinforced variants incorporate additional structural layers for industrial automation environments requiring enhanced mechanical durability.
Today's leader: FPC. Tomorrow's challenger: TFFC.
Application:
Customer procurement maturity separates specification-heavy automotive tier-1s from price-elastic consumer electronics OEMs.
- Automotive:Electric powertrain and ADAS sensor modules require ISO 26262 functional safety certification with 18-24 month qualification timelines. TE Connectivity anchors high-reliability programs where vibration resistance and thermal cycling tolerance prove non-negotiable.
- Medical Devices:Portable ultrasound and endoscopic systems demand ISO 10993 biocompatibility certification. Polyimide substrates command premium positioning through sterilization compatibility and miniaturization enablement.
- Consumer Electronics:Smartphone OEM consolidation into single-digit supplier rosters squeezes second-tier vendors toward industrial verticals. Apple's direct procurement relationships with Luxshare-ICT exemplify the distributor displacement trend.
- Industrial Equipment:PVC-insulated constructions retain share despite polymer substitution pressure under EU REACH substance restrictions.
Automotive applications are climbing the fastest; medical devices offer the steepest margin expansion trajectory.
Material:
Substrate formulation decisions increasingly incorporate sustainability disclosure obligations alongside electrical performance metrics.
- Copper:Fine-pitch lamination below 0.3 mm pitch relies on captive metallurgy capabilities concentrated in Japanese suppliers. Raw material hedging capacity separates integrated producers from margin-vulnerable compounders.
- Polymer:Bio-based polyester development accelerates among European compounders seeking to preempt SVHC authorization requirements for conventional flame retardants.
- PVC:Industrial equipment segments retain this cost-optimized insulation despite REACH-driven phase-out pressures in European markets.
- Insulated Metals:Specialized constructions serve niche applications requiring combined conductivity and environmental sealing.
Polymer formulations are gaining share fastest as regulatory compliance reshapes specification requirements.
End User:
Channel structure fragmentation reflects the divergence between high-volume direct procurement and fragmented distributor-mediated transactions.
- OEMs:Automotive and medical device OEMs impose vendor-managed inventory arrangements and segregated cleanroom protocols. Dual-facility qualification requirements strain mid-tier manufacturer capital allocation.
- Manufacturers:Contract electronics manufacturers in China's Pearl River Delta mandate just-in-time delivery structures with penalty clauses for supply disruption.
- Distributors:Role diminishes in consumer electronics as consolidated supplier rosters enable direct relationships, though industrial segments retain intermediary value for technical support.
- Retailers:Minimal direct engagement; aftermarket replacement cables represent marginal revenue contribution.
OEM direct procurement dominates value capture; distributor relevance concentrates in technical industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese metallurgical engineers and South Korean display panel specialists anchor the industry's technical workforce concentration, with Chinese assembly technicians scaling manufacturing operations across coastal manufacturing corridors.
China
Consumer electronics assembly corridors in the Pearl River Delta absorb the highest FFC volumes globally, with smartphone OEMs consolidating supplier rosters under vendor-managed inventory arrangements. GB 4943.1 safety standards for information technology equipment shape certification timelines for cable manufacturers seeking domestic market access. Shenzhen and Dongguan host dense concentrations of contract electronics manufacturers mandating just-in-time delivery structures with penalty clauses for supply disruption.
Japan
Fine-pitch copper lamination below 0.3 mm pitch relies on captive metallurgy capabilities concentrated among integrated producers with deep metallurgical heritage. METI industrial policy supports advanced materials development for automotive electrification applications. Nagoya and Osaka manufacturing belts sustain dominant positions in polyimide substrate qualification for foldable display hinge circuits requiring dynamic flex life exceeding one million cycles.
South Korea
Display panel makers drive premium FPC procurement for book-type phone form factors demanding extreme bending tolerance and specialized metallization processes. MFDS pharmaceutical regulations create secondary demand channels for biocompatible flex circuits in portable medical imaging equipment. Seoul Capital Area and Busan-Ulsan corridors concentrate qualification programs for automotive tier-1s expanding FFC procurement for surround-view camera systems.
Germany
Automotive tier-1s fragment procurement across regional cable specialists for electric powertrain programs requiring ISO 26262 functional safety certification. ECHA REACH substance restrictions and RoHS hazardous substance directives accelerate halogen-free dielectric development to maintain European market access. Bavaria and Baden-Württemberg host dense concentrations of industrial automation OEMs retaining PVC-insulated constructions despite polymer substitution pressures.
United States
FCC electromagnetic compatibility rules shape product certification burdens for cable manufacturers targeting telecommunications and data transmission equipment markets. FDA medical device regulations create premium positioning opportunities for ISO 10993-certified biocompatible flex circuits in portable ultrasound and endoscopic systems. Greater Boston and Pacific Northwest technology corridors concentrate development activity for embedded passive technology converging with traditional FFC constructions.
Flat Flexible Cables Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with consolidated supplier rosters among top-tier smartphone OEMs squeezing second-tier vendors toward automotive and industrial verticals. The vendor base stratifies across three archetypes: integrated metallurgy producers with captive copper lamination capabilities, assembly-originated suppliers extending backward into cable subcomponent production, and connector heritage players anchoring high-reliability automotive programs. Dominant competitive moves include geographic expansion into Indian electronics manufacturing corridors and portfolio diversification toward medical device certification tiers.
Among Japanese integrated producers, Sumitomo Electric exemplifies the metallurgy-anchored archetype with fine-pitch lamination capabilities, while TE Connectivity represents the connector heritage model for automotive electrification programs. Luxshare-ICT occupies a position exemplifying assembly-originated vertical expansion into cable subcomponent production for consolidated consumer electronics supply chains.
| Leading Market Players |
|---|
| Samtec |
| Würth Elektronik |
| Sumitomo Electric |
| TE Connectivity |
| Luxshare-ICT |
| Johnson Electric |
| Axon Cable |
| Nicomatic |
| Molex |
| Others |
Value Network & Pricing Analysis
Captive metallurgy capabilities in Japan anchor supply positions for fine-pitch lamination below 0.3 mm pitch, simultaneously insulating integrated producers from copper volatility and preserving premium pricing power against margin-compressed compounders. This backward integration into copper refining and substrate qualification creates durable cost advantages that standard polyester-laminated competitors cannot replicate.
Pricing Analysis
Capacity additions in China's Pearl River Delta manufacturing corridors are reshaping price floors for standard FFC constructions used in printer heads and flat-panel displays. Three-tier pricing structure across automotive-certified, medical-grade, and consumer electronics tiers separates ISO 26262-qualified supply from commodity polyester volumes. Cost compression in consumer electronics tiers is intensifying because smartphone OEMs consolidate supplier rosters under vendor-managed inventory arrangements. Automotive tier-1s exhibit least price sensitivity due to 18-24 month qualification timelines and functional safety non-negotiability.
Supply Chain Analysis
Metallurgical engineer availability in Japan's Nagoya-Osaka manufacturing belt and display panel specialist concentrations in South Korea's Seoul Capital Area constrain expansion velocity for Western automotive qualification programs. Fine-pitch lamination draws from captive copper refining, polyimide substrate formulation, and halogen-free dielectric development. Single-source vulnerability pervades 0.3 mm pitch specifications where Japanese integrated producers dominate. Distribution runs through direct procurement relationships with smartphone OEMs and tier-1 automotive suppliers, displacing traditional distributor mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through medical-grade certification tiers where ISO 10993 biocompatibility requirements sustain premium positioning beyond REACH-driven polymer substitution pressures in consumer electronics.
For Market Incumbents: Lock in automotive tier-1 relationships through accelerated ISO 26262 functional safety certification timelines before emerging Asian cable specialists complete metallurgy capability buildouts. Prioritize dual-facility qualification investments to satisfy medical and automotive cleanroom segregation demands, defending against mid-tier manufacturers capital-constrained from cross-contamination control infrastructure. For New Entrants and Emerging Players: Portable medical imaging OEMs represent the most penetrable buyer archetype for ISO 10993-certified biocompatible flex circuits, where incumbent concentration in consumer electronics has left qualified supply gaps. Target Indian electronics manufacturing corridors where production-linked incentive schemes attract smartphone assembly investment without established local cable sourcing. Lead with technical sales support emphasizing sterilization compatibility and miniaturization enablement rather than commodity volume pricing. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier automotive cable specialists because fragmented procurement patterns across regional European tier-1s prevent scale advantages from concentrating. Long-term viability hinges on substrate material substitution capabilities as sustainability reporting obligations tighten across OEM procurement criteria. Monitor ECHA SVHC candidate list expansion velocity for inflection signals on bio-based polyester development returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive metallurgy insulates margins from LME volatility and secures fine-pitch lamination supply. |
| ISO 26262 Functional Safety Certification | Automotive electrification programs require 18-24 month qualification timelines that lock in supplier positions. |
| ISO 10993 Biocompatibility Qualification | Medical device miniaturization creates premium pricing tiers beyond consumer electronics margin compression. |
| Halogen-Free Dielectric Development | ECHA REACH substance restrictions accelerate reformulation to preempt SVHC authorization requirements. |
| Indian Manufacturing Corridor Expansion | PLI scheme investment gaps in local cable sourcing create first-mover entry opportunities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with automotive tier-1 procurement officers, medical device biomedical engineers, consumer electronics supply chain directors, and polymer compounder R&D leads with secondary validation through SEC filings, customs trade data, ECHA SVHC candidate list updates, and automotive production databases. Bottom-up segment sizing and top-down macro anchoring were cross-checked for consistency.
Historical reference periods spanning pre-pandemic baseline through electrification acceleration phases anchored the projection horizon across product type, application, material formulation, and end-user channel dimensions. CAGRs were derived from segment-level volume trajectories and value-per-unit trends, incorporating copper price scenario modeling and regulatory compliance cost pass-through assumptions specific to REACH and RoHS implementation timelines.
Underlying measurement precision varies by segment; automotive and medical device applications carry tighter precision than fragmented industrial equipment categories due to concentrated OEM reporting. Forecasts reflect assumptions on electrification penetration rates and foldable display adoption curves that could revise materially. Practitioners should monitor ECHA authorization list expansion and Chinese GB standard updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optic Cables for Military & Aerospace Market
Cables
India Wire and Cable Market
Cables
Audio and Video Cables Market
Cables
Industrial Cable Reels Market
Cables
Cable Organisers Market
Cables
Military Cable Market
Cables
Magnetic Charging Cable Market
Cables
Cable Trunking Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Water Leak Sensing Cable Market
Cables
Submarine Cables Market
Cables
Copper Stranded Wire Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Cable Tags Market
Cables
Cable Detector Market
Cables
Cable Lugs Market