
 Cable Detector Market | 2026-2036
Cable Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Detector Market Outlook
Electromagnetic-to-digital signal processing integration is rewriting cable detector architecture, compressing sensor arrays into portable units with real-time mapping outputs. Fluke Corporation leverages its calibration heritage to anchor premium handheld segments where accuracy tolerances tighten. Megger competes through utility-specific testing protocols that sustain long-term service contracts with electrical infrastructure operators. Radiodetection Ltd. dominates underground detection applications through proprietary antenna configurations that extend operational depth in congested urban environments.
A cable detector identifies buried or hidden conductive pathways through electromagnetic field detection, typically operating across frequency ranges from 50 Hz to 200 kHz with depth capabilities spanning 3 to 10 meters depending on conductor characteristics and soil conditions. These instruments serve critical safety and operational functions by preventing excavation damage to energized lines, fiber optic bundles, and pipeline tracer wires. Handheld product types occupy the highest volume tier due to universal deployment across construction and maintenance crews, while wireless connectivity features represent the fastest-expanding capability segment as field data integration with GIS platforms becomes standard. Underground detectors command concentrated margin pools where municipal and utility procurement specifications demand certified depth accuracy and multi-frequency discrimination.
FCC equipment authorization requirements govern wireless-enabled detector emissions in the United States, while OSHA excavation safety standards directly mandate pre-dig cable location practices that sustain baseline demand. ISO 9001 quality system certification shapes supplier qualification criteria for European utility procurement frameworks, filtering market access toward documented manufacturing controls. Stakeholders must monitor evolving electromagnetic compatibility standards and trench safety enforcement intensity as regulatory alignment between North American and European frameworks accelerates product platform consolidation decisions.
Market Dynamics
Electromagnetic-to-digital signal processing integration is compressing sensor architectures into portable units with real-time mapping outputs, forcing established manufacturers to redesign core detection platforms around software-defined functionality rather than hardware-centric discrimination.
Growth Catalysts
- OSHA excavation safety mandates:Pre-dig cable location requirements in the United States sustain baseline demand across municipal and contractor procurement channels.
- Utility infrastructure replacement cycles:Aging electrical grid systems in the United States drive recurring detector procurement for maintenance and safety compliance operations.
- Multi-frequency electromagnetic sensing:Advances in antenna array configurations extend operational depth thresholds in congested urban deployment environments.
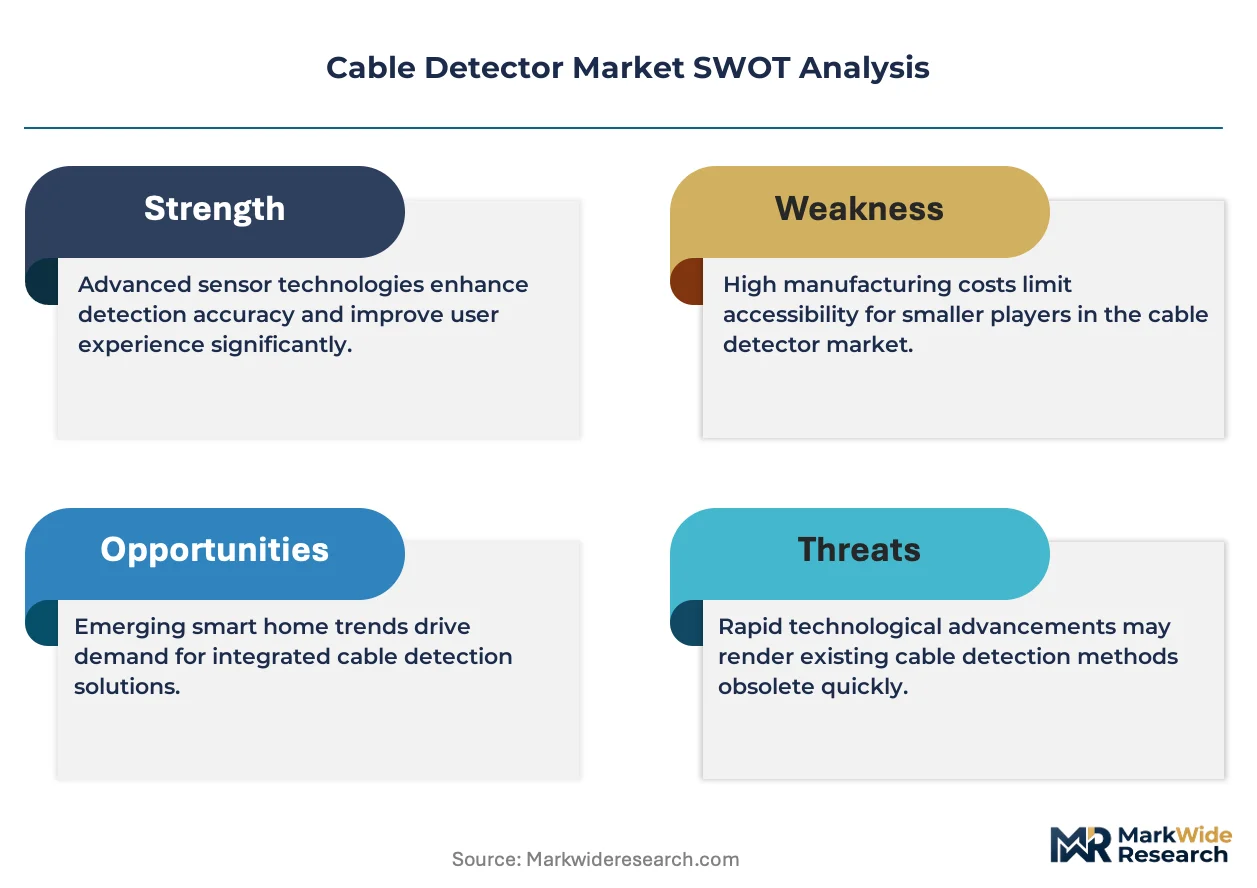
Market Restraints
- Precision sensor input cost volatility:Rare earth magnetometer components face supply concentration risks from Chinese processing facilities.
- Soil condition variability:Conductive or saturated ground environments degrade electromagnetic signal propagation and limit detection accuracy.
- FCC equipment authorization friction:Wireless-enabled detector emissions testing creates extended product launch timelines for connectivity-integrated models.
Strategic Opportunities
- GIS platform integration:Wireless connectivity features enable real-time field data synchronization with utility geographic information systems.
- Fiber optic tracer wire detection:Expanding fiber deployments create adjacent application demand beyond traditional electrical cable location.
- European utility procurement frameworks:ISO 9001 certification requirements filter market access toward documented manufacturing controls, favoring prepared entrants.
Industry Challenges
- Electromagnetic compatibility certification timelines:Multi-jurisdiction testing protocols delay product commercialization for global platform strategies.
- Signal processing talent scarcity:Specialized firmware engineering for real-time field discrimination algorithms concentrates in limited geographic pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Detector Market |
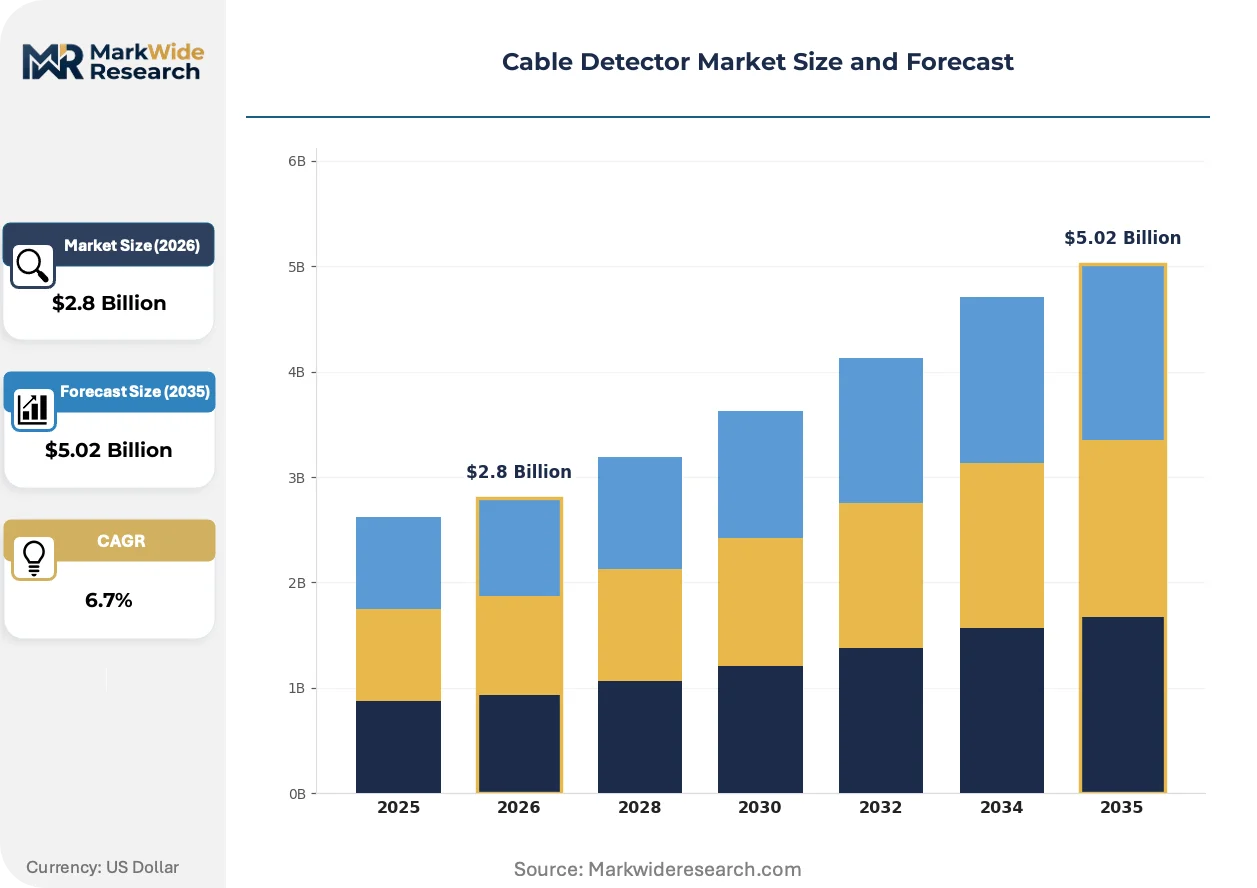
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Underground, Wireless, Advanced Technology: Electromagnetic, Passive, Active, Infrared End User: Construction, Telecommunications, Electrical, Utilities Application: Facility Maintenance, Cable Installation, Emergency Repair, Surveying |
| Companies Covered | Fluke Corporation, 3M, Megger, Radiodetection Ltd., BAUR GmbH, C.Scope International, SONEL S.A., Vivax-Metrotech, Leica Geosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Detector Market Strategic Shifts
Software-defined detection architectures are displacing fixed-frequency hardware designs, compressing product development cycles while expanding functional upgrade paths through firmware deployment rather than physical replacement.
Multi-frequency antenna arrays is virtualizing traditional single-purpose detector categories by enabling dynamic frequency hopping that adapts to conductor material and soil composition in real time. Municipal utilities in the United States are adopting these platforms for consolidated fleet standardization. The technology is virtualizing procurement decisions around modular upgrade paths rather than discrete hardware replacement cycles.
OSHA excavation safety standard enforcement intensity is tightening documentation requirements for pre-dig cable location practices across contractor segments. This regulatory pressure is elevating certified accuracy specifications in municipal procurement criteria. Underground detector categories with documented depth verification protocols command preference in United States utility frameworks.
Service contract unbundling is separating hardware ownership from calibration and maintenance obligations across electrical infrastructure operators. Traditional bundled procurement models are fragmenting into discrete equipment and service line items. This pattern concentrates in United States utility maintenance operations seeking operational expenditure flexibility.
Cable Detector Market Segmentation
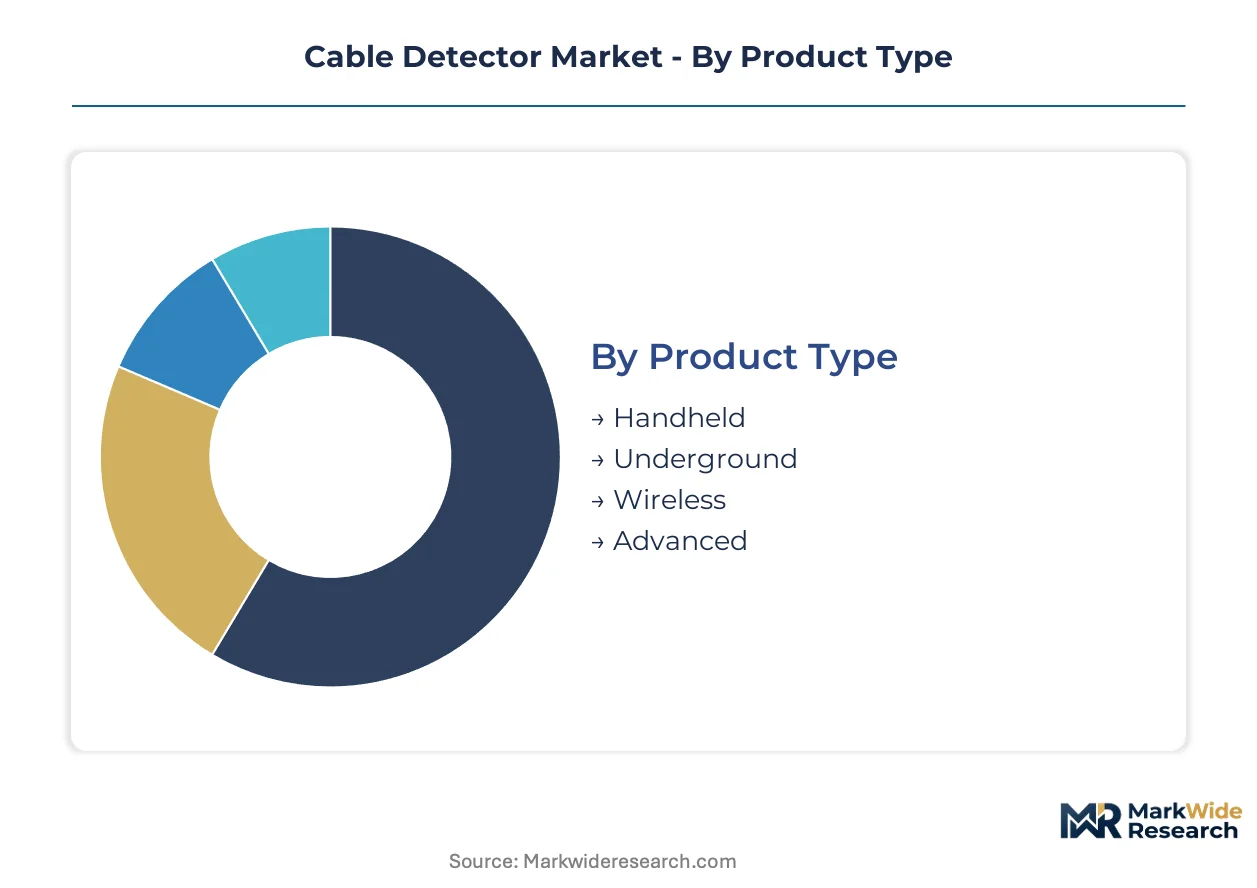
Cable detector procurement patterns diverge sharply across deployment contexts, with calibration service intensity and replacement cycle predictability varying by product architecture and operational environment. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization pressures dominate.
Product Type:
After-sales service intensity defines competitive positioning across product type segments, with calibration frequency and firmware upgrade dependency creating divergent revenue recurrence profiles.
- Handheld:Portable electromagnetic units dominate construction crew deployment with universal battery-powered operation across 50 Hz to 200 kHz frequency ranges. Demand concentrates in United States municipal maintenance operations where OSHA excavation mandates drive fleet standardization. Service intensity remains moderate with annual calibration cycles.
- Underground:Deep-detection platforms with proprietary antenna configurations extend operational depth to 10 meters in congested urban soil conditions. United States utility procurement specifications demand certified depth accuracy protocols that sustain premium pricing tiers. These systems require quarterly calibration and firmware maintenance, anchoring long-term service contracts.
- Wireless:Connectivity-integrated models enable real-time GIS synchronization but face extended FCC equipment authorization timelines. The segment climbs fastest as field data integration becomes standard across utility operators.
- Advanced:Multi-frequency software-defined architectures with dynamic frequency hopping adapt to conductor material and soil composition in real time. These platforms command consolidated fleet decisions from large electrical infrastructure operators seeking modular upgrade paths.
Handheld detectors hold the largest share; momentum sits with wireless connectivity integration.
Technology:
Detection methodology determines signal processing complexity and the depth of specialized firmware engineering talent required for competitive positioning.
- Electromagnetic:Field generation and reception across variable frequency ranges remains the foundational detection paradigm with established supply chains for magnetometer components. Construction and utility maintenance crews across the United States deploy these systems for standard cable location tasks. Component cost volatility from rare earth supply concentration creates margin pressure.
- Passive:Detection of ambient electromagnetic fields from energized conductors requires no active signal injection, enabling rapid deployment in live electrical environments. Electrical infrastructure operators favor these systems for safety-critical emergency repair scenarios where signal injection risks are unacceptable.
- Active:Signal injection methods improve detection accuracy for de-energized or non-metallic cables through tracer wire attachment. Telecommunications fiber deployment crews utilize active modes for locating non-conductive fiber bundles.
- Infrared:Thermal signature detection supplements electromagnetic methods for identifying cable faults and overload conditions in facility maintenance applications. The technology expands most quickly in industrial electrical diagnostics.
Electromagnetic technology holds the largest share; steepest expansion trajectory belongs to passive detection for live-line safety compliance.
End User:
Procurement authority and budget cycle timing vary substantially across end user categories, with utility capital planning contrasting sharply with construction project-based purchasing.
- Construction:Project-based procurement of handheld units for pre-dig cable location dominates volume tiers. United States contractor segments face tightening OSHA documentation requirements that elevate certified accuracy specifications in equipment selection.
- Telecommunications:Fiber optic tracer wire detection creates specialized demand beyond traditional electrical cable location. Carrier infrastructure investment cycles drive replacement timing for detection fleets.
- Electrical:Grid maintenance operations concentrate margin pools where multi-frequency discrimination and depth verification capabilities command specification priority. United States aging infrastructure replacement sustains recurring procurement.
- Utilities:Municipal and regional operators consolidate fleet standardization around platforms with documented calibration protocols and service contract availability. These buyers exhibit longest replacement cycles but highest per-unit expenditure.
Construction holds the largest share; telecommunications fiber deployment drives fastest segment expansion.
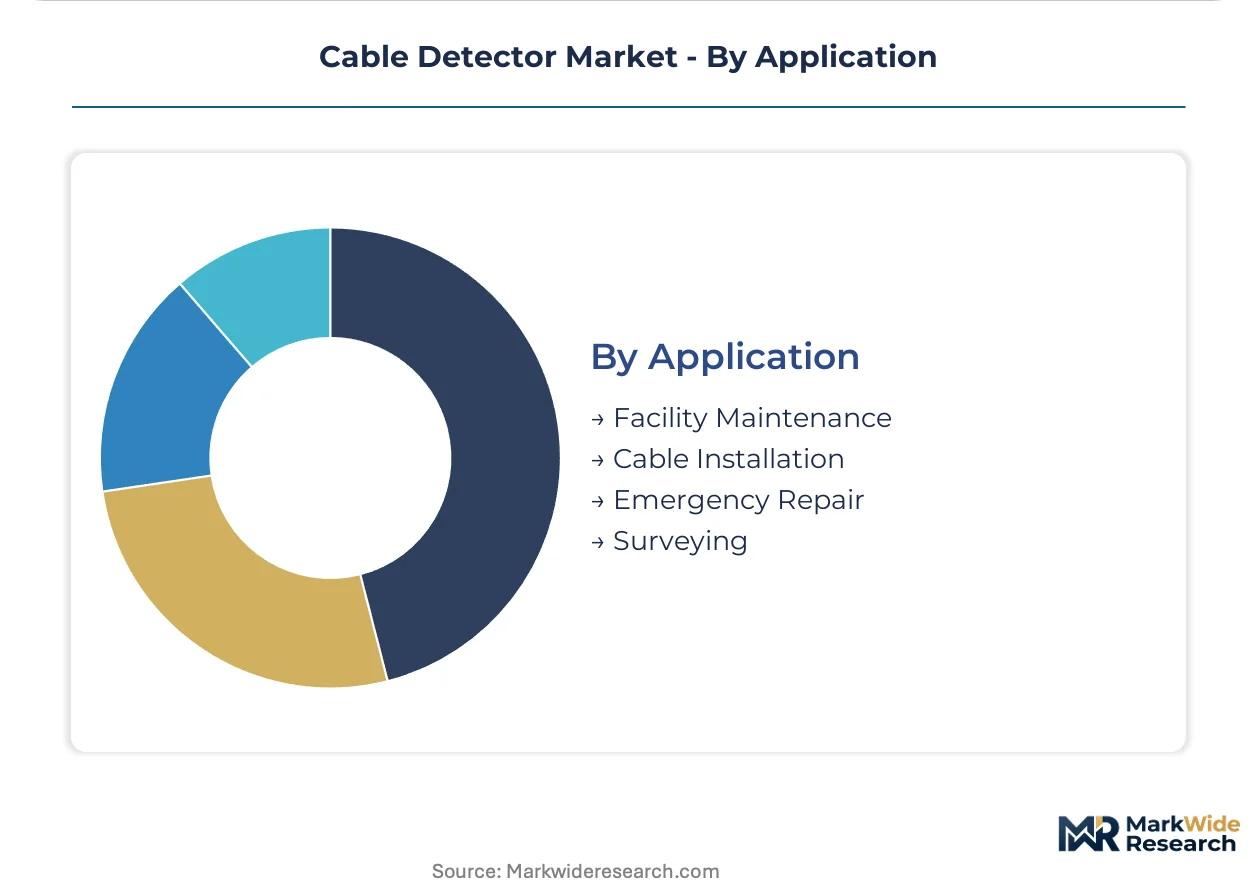
Application:
Operational urgency and accuracy tolerance thresholds shape application-specific equipment requirements, with emergency scenarios demanding rapid deployment over maximum precision.
- Facility Maintenance:Indoor and campus environment cable tracing for electrical and telecommunications infrastructure requires compact handheld units with interference rejection capabilities. Corporate and institutional maintenance departments sustain steady replacement demand.
- Cable Installation:New infrastructure deployment demands accurate as-built documentation for future maintenance access. Installation contractors prioritize wireless connectivity for immediate GIS record updates.
- Emergency Repair:Fault location under time pressure drives demand for passive detection modes and intuitive user interfaces that minimize training requirements. Electrical utilities maintain dedicated emergency response fleets.
- Surveying:Pre-construction site assessment for buried utility mapping requires maximum depth capability and multi-frequency discrimination. Engineering survey firms command concentrated procurement of advanced underground detection platforms.
Facility maintenance holds the largest share; cable installation applications gain share fastest through GIS integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal utility procurement departments and electrical infrastructure operators concentrate cable detector demand in markets with aging grid systems and stringent excavation safety enforcement.
United States
OSHA excavation safety mandates and electrical grid replacement cycles sustain the largest national demand pool. FCC equipment authorization requirements govern wireless-enabled detector emissions, extending product launch timelines for connectivity-integrated models. Underground detection platforms with certified depth accuracy command premium positioning in Texas and California utility procurement frameworks.
Germany
Industrial facility maintenance and underground utility mapping drive steady replacement demand across engineering survey firms. CE marking and electromagnetic compatibility standards filter market access toward documented manufacturing controls. Bavaria-based electrical infrastructure operators consolidate fleet standardization around multi-frequency software-defined architectures.
China
Rapid urban infrastructure expansion and fiber optic deployment create adjacent application demand beyond traditional electrical cable location. GB standards and MIIT equipment certification shape product platform requirements for domestic and export markets. Yangtze River Delta manufacturing clusters supply precision sensor components facing rare earth processing concentration risks.
Japan
High-density urban environments and disaster-resilient grid investments sustain demand for deep-detection platforms with interference rejection capabilities. METI industrial standards and JIS certification requirements elevate accuracy specifications in utility procurement criteria. Kanto region electrical operators prioritize documented calibration protocols for fleet standardization decisions.
United Kingdom
Telecommunications fiber deployment and construction sector safety compliance drive handheld detector volume across contractor segments. HSE excavation safety guidance and ISO 9001 quality system certification shape supplier qualification frameworks. London and Southeast England engineering survey firms command concentrated procurement of advanced underground detection platforms.
Cable Detector Market Competitive Environment
Channel-controlling players compete with product-specialist players across a moderately consolidated structure where calibration heritage and utility-specific testing protocols sustain differentiation. Three archetypes dominate: multinationals with broad electrical testing portfolios, specialists in electromagnetic sensing hardware, and regional fabricators serving price-sensitive construction segments. Strategic moves concentrate on geographic expansion through distribution partnerships and technology licensing for software-defined detection architectures.
Among multinationals with calibration heritage, Fluke Corporation and Megger occupy positions where accuracy tolerances and long-term service contracts anchor premium-tier procurement. Radiodetection Ltd. exemplifies the electromagnetic sensing specialist archetype through proprietary antenna configurations. BAUR GmbH and SONEL S.A. represent European manufacturers where CE marking and ISO 9001 certification sustain access to utility procurement frameworks. Vivax-Metrotech and Leica Geosystems sit within the precision instrumentation tier where integration with surveying and mapping platforms creates adjacent value capture.
| Leading Market Players |
|---|
| Fluke Corporation |
| 3M |
| Megger |
| Radiodetection Ltd. |
| BAUR GmbH |
| C.Scope International |
| SONEL S.A. |
| Vivax-Metrotech |
| Leica Geosystems |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnetometer processing concentration in Chinese facilities anchors cost volatility for precision sensor inputs, compressing margins in handheld detector tiers while concentrating pricing power with underground platform manufacturers who pass through component inflation via long-term service contracts.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate procurement between sensor suppliers and detector manufacturers, creating margin pressure when processing bottlenecks emerge. Pricing stratifies across certified-accuracy tiers, with ISO 9001-documented calibration protocols commanding premium positioning against uncertified alternatives. Cost compression in handheld segments intensifies as construction contractor procurement consolidates around fleet standardization programs. Municipal utilities exhibit lowest price sensitivity due to safety compliance mandates, while independent contractors face acute margin pressure from OSHA documentation requirements.
Supply Chain Analysis
Tariff exposure between Chinese rare earth processors and North American detector manufacturers dominates supply chain risk assessment for electromagnetic sensor arrays. Magnetometer components and antenna substrates draw from Chinese, German, and Japanese manufacturing clusters. Single-source vulnerability concentrates in neodymium magnet supply for precision field generation. Distribution runs through authorized electrical testing equipment distributors with calibration service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal utility procurement consolidation around fleet standardization programs has shifted bargaining power toward buyers, fragmenting vendor pricing power across standardized multi-frequency platform tenders.
For Market Incumbents: Harden calibration service moats by embedding firmware upgrade dependencies into quarterly maintenance protocols, defending against software-defined entrants who unbundle hardware from service revenue. Deepen backward integration into antenna array manufacturing to offset rare earth price volatility. Prioritize FCC pre-certification investment to compress wireless-enabled product launch timelines against connectivity-focused competitors. For New Entrants and Emerging Players: European utility procurement frameworks present accessible white-space where ISO 9001 certification barriers filter incumbent-dominated competition. Fiber optic tracer wire detection for telecommunications carriers offers adjacent application entry with lower calibration heritage requirements. Pursue partnership routes with established electrical testing distributors rather than direct channel buildout. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrical testing portfolio companies seeking platform consolidation. Five-to-ten year viability hinges on software-defined architecture transition completion. Monitor FCC equipment authorization backlog intensity as inflection signal for wireless-enabled segment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Transition | Firmware-upgradeable platforms displace fixed-frequency hardware, extending replacement cycles while anchoring recurring service revenue. |
| GIS Platform Integration Partnership | Real-time field data synchronization with Esri and Autodesk utility platforms becomes procurement specification standard. |
| FCC Pre-Certification Investment | Early wireless emissions testing compresses product launch timelines for connectivity-integrated detector models. |
| Calibration Service Unbundling | Discrete service line-item contracts capture operational expenditure flexibility demand from United States utilities. |
| Fiber Optic Tracer Wire Capability Expansion | Telecommunications infrastructure investment cycles create adjacent demand beyond traditional electrical cable location. |
Study Parameters
A spread of perspectives from utility procurement managers, electrical maintenance directors, construction safety officers, and FCC compliance consultants converged on the working assumptions driving this analysis. Primary field interviews with municipal fleet standardization committees and underground detection equipment operators combined with secondary validation from OSHA enforcement records, FCC equipment authorization databases, and ISO certification registries. Bottom-up segment sizing triangulated against top-down utility capital expenditure patterns across the analysis window.
Demand-supply balance framing anchored the forecast framework, modeling procurement timing from electrical grid replacement cycles against rare earth magnetometer production capacity constraints. Segmentation dimensions included product architecture, detection technology, end-user procurement authority, and application urgency. CAGRs derived from utility fleet refresh timing and construction safety enforcement intensity trajectories. Antenna array configuration advancement rates and firmware upgrade adoption curves supplied industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by software-defined platform entrants or rapid rare earth supply diversification would shift outcomes. Macroeconomic deviation in utility capital planning, regulatory acceleration in electromagnetic compatibility standards, or breakthroughs in passive detection accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
North America Patch Cable Market
Cables
Latin America Wire and Cable Market
Cables
Smartphone Type-C Charging and Data Cable Market
Cables
Radio Frequency Cables Market
Cables
Cable Trunking Market
Cables
Aluminum Cable Market
Cables
Cable Racks Market
Cables
Nuclear Multi-Conductor Cables Market
Cables
Water Leak Sensing Cable Market
Cables
High Voltage Cables Market
Cables
Cable Market
Cables
Coaxial Cable Market
Cables
Global Cable Tie Market
Cables
Cable Tray Market
Cables
High-Temperature Superconducting Cables Market
Cables
GCC Cable Accessories Market