
 High Voltage Cable Termination Market | 2026-2036
High Voltage Cable Termination Market Size, Share, and Industry Trends Forecast 2026-2036
High Voltage Cable Termination Market Insights
Aftermarket service revenue is tilting toward installation supervision and condition monitoring as utilities extend asset life cycles rather than replace terminations outright. Prysmian leverages its cable manufacturing scale to bundle termination contracts with high-voltage cable orders across European transmission projects. Hitachi Energy anchors its position through integrated digital monitoring systems that track partial discharge in live termination assemblies. Nexans competes on geographic reach, maintaining localized termination kit inventories near major offshore wind installation ports.
High voltage cable termination comprises insulated assemblies designed to manage electrical stress at conductor endpoints, typically employing silicone rubber or ethylene-propylene compounds with prefabricated geometric stress cones controlling field distribution up to 550 kV. These components prevent insulation breakdown where cables interface with switchgear, transformers, or overhead lines in transmission networks. Outdoor termination demand leads product type segments due to relentless grid interconnection investments across coastal and desert climates where pollution flashover risks dominate specification criteria. Cold shrink technology displaces heat shrink in utility procurement because field installation eliminates open-flame permits and reduces contractor crew certification burdens. Renewable energy application growth outpaces power distribution as offshore wind arrays require dry-type terminations rated for salt-fog environments and cyclic loading.
IEC 62271-209 governs gas-insulated switchgear terminations across European markets while IEEE 404 shapes product qualification protocols for North American utilities, with both frameworks mandating accelerated aging tests that filter out lower-tier suppliers. China's GB/T 12706 and State Grid Corporation technical specifications impose additional seismic and pollution-class requirements that reshape competitive qualification thresholds for market entry. Stakeholders must monitor how evolving fire-resistance standards for data center and tunnel installations redirect material substitution toward ceramic-composite housings and intumescent sealing systems.
Market Dynamics
Cold shrink technology is compressing installation timelines and contractor certification burdens, forcing utilities to rewrite procurement specifications around field-ready assembly methods rather than traditional heat-shrink protocols.
Growth Catalysts
- Offshore wind buildouts:European and Chinese developers are specifying dry-type terminations rated for salt-fog environments and cyclic mechanical loading in subsea collector systems.
- IEC 62271-209 standardization:Gas-insulated switchgear termination requirements are filtering out lower-tier suppliers across European transmission markets, consolidating qualified vendor pools.
- EPDM compound advances:Ethylene-propylene formulations with enhanced tracking resistance are extending service intervals in desert and coastal pollution zones, reducing lifecycle costs for grid operators.
Market Restraints
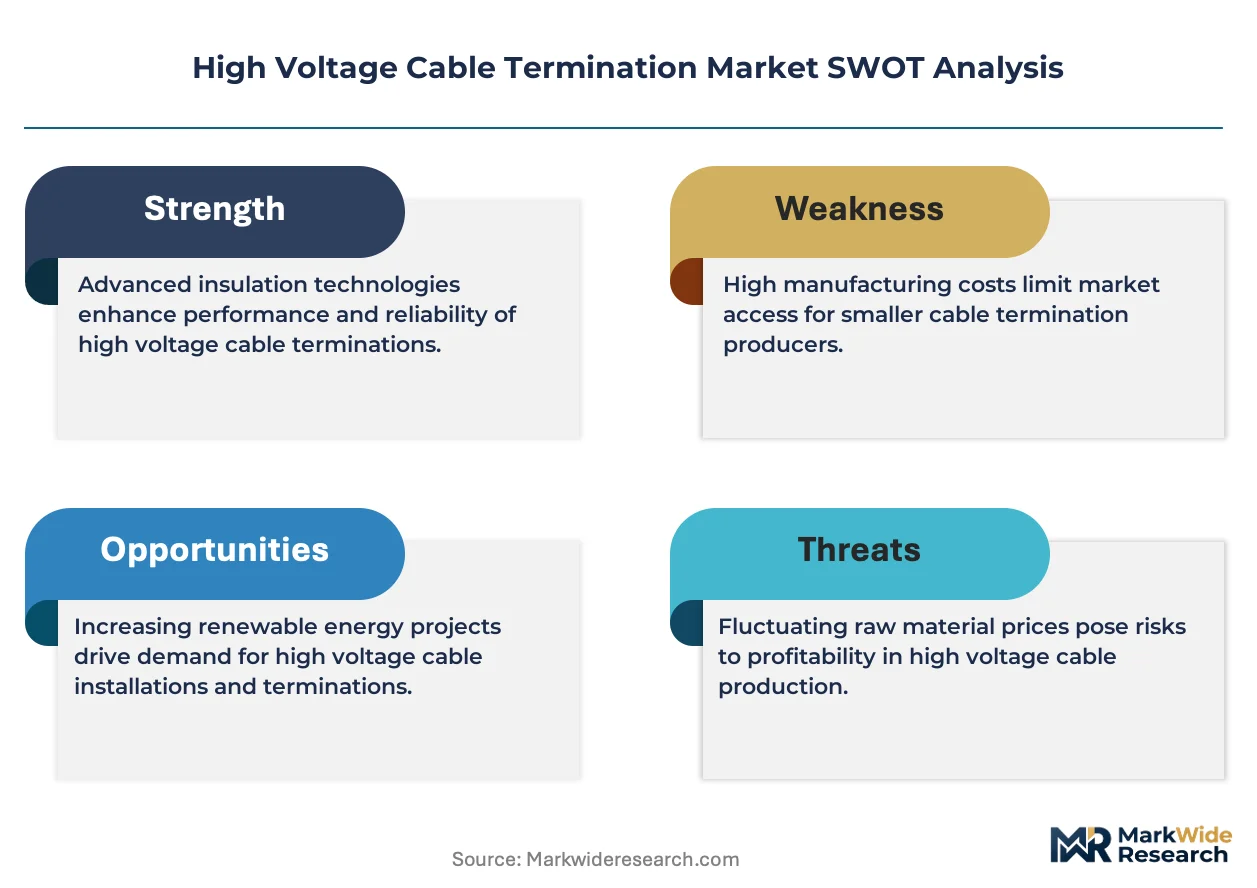
- Silicone rubber feedstock volatility:Petrochemical price swings and constrained specialty polymer supply from Asian manufacturers are compressing margin structures for termination kit producers.
- Ultra-high voltage qualification barriers:China's GB/T 12706 seismic and pollution-class requirements impose multi-year testing cycles that lock out new entrants from State Grid Corporation tenders.
- Prefabricated joint substitution:Factory-integrated cable-joint-termination assemblies from integrated cable manufacturers are capturing share in greenfield transmission corridors.
Strategic Opportunities
- Digital monitoring convergence:Partial discharge sensors embedded in live termination assemblies create recurring revenue streams through condition-based maintenance contracts.
- India's transmission expansion:Power Grid Corporation of India's green energy corridors require localized termination kit inventories and installation supervision capabilities.
- Fire-resistance mandates:Tunnel and data center installations are redirecting material specifications toward ceramic-composite housings and intumescent sealing systems.
Industry Challenges
- Field technician certification gaps:Utilities report shortages of contractors qualified for live-work installation of 245 kV and above cold shrink assemblies, extending project timelines.
- Legacy switchgear integration:Retrofit terminations must accommodate dimensional constraints from 1980s-vintage GIS designs without compromising electrical clearance margins under revised IEEE 404 protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Voltage Cable Termination Market |
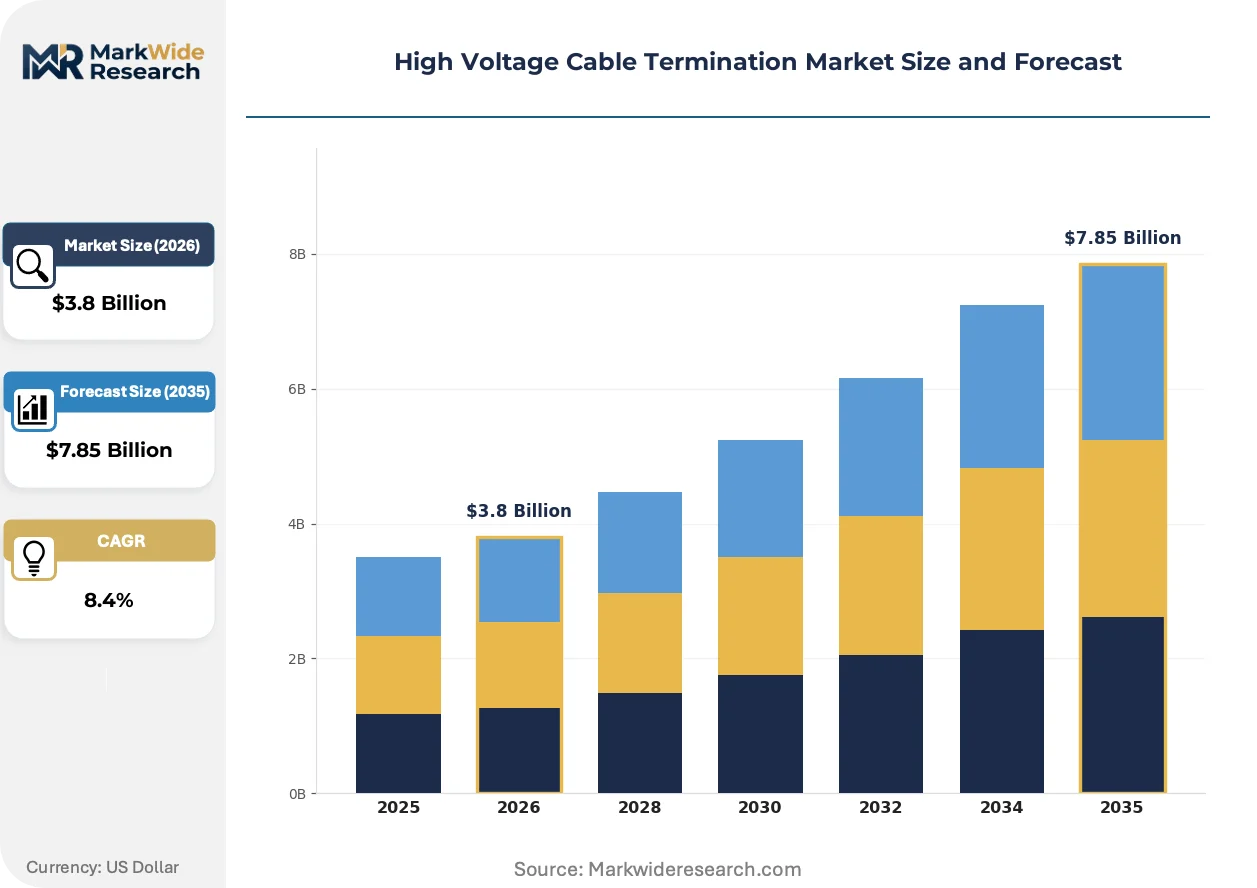
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Termination, Outdoor Termination, Joint Termination, Separable Connectors Technology: Heat Shrink, Cold Shrink, Resin Cast, Oil Impregnated Application: Power Transmission, Power Distribution, Renewable Energy, Railways, Data Centers End User Industry: Utilities, Electrical Contractors, Infrastructure Projects, Oil & Gas Facilities |
| Companies Covered | Prysmian, Nexans, Hitachi Energy, TE Connectivity, PFISTERER Holding, Brugg Cables, Sumitomo Electric Industries, LS Cable & System, Elcon Megarad, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Voltage Cable Termination Market Trends and Innovations
Termination technology is pivoting from passive insulation components to intelligent, monitor-enabled assets that feed real-time diagnostic data into utility asset management platforms.
Silicone rubber cold shrink assemblies with integrated geometric stress cones are rendering obsolete heat-shrink terminations that require open-flame permits and specialized contractor certifications. Offshore wind developers in the North Sea and Bohai Bay are specifying these field-ready kits exclusively. The shift is compressing installation windows from days to hours while eliminating hot-work safety protocols.
REACH restrictions on persistent organic pollutants are forcing reformulation of conventional housing materials across European supply chains. Manufacturers are accelerating validation of halogen-free compound alternatives. German and Danish utilities are now requiring full material disclosure documentation for termination kits deployed in coastal substations.
Asset owners are unbundling installation supervision from hardware procurement, creating standalone service contracts for commissioning oversight and post-installation testing. Contractors with localized technician networks are capturing this spend. Brazil and Saudi Arabia represent the most visible markets where utilities have separated installation services from material supply in tender structures.
High Voltage Cable Termination Market Segmentation
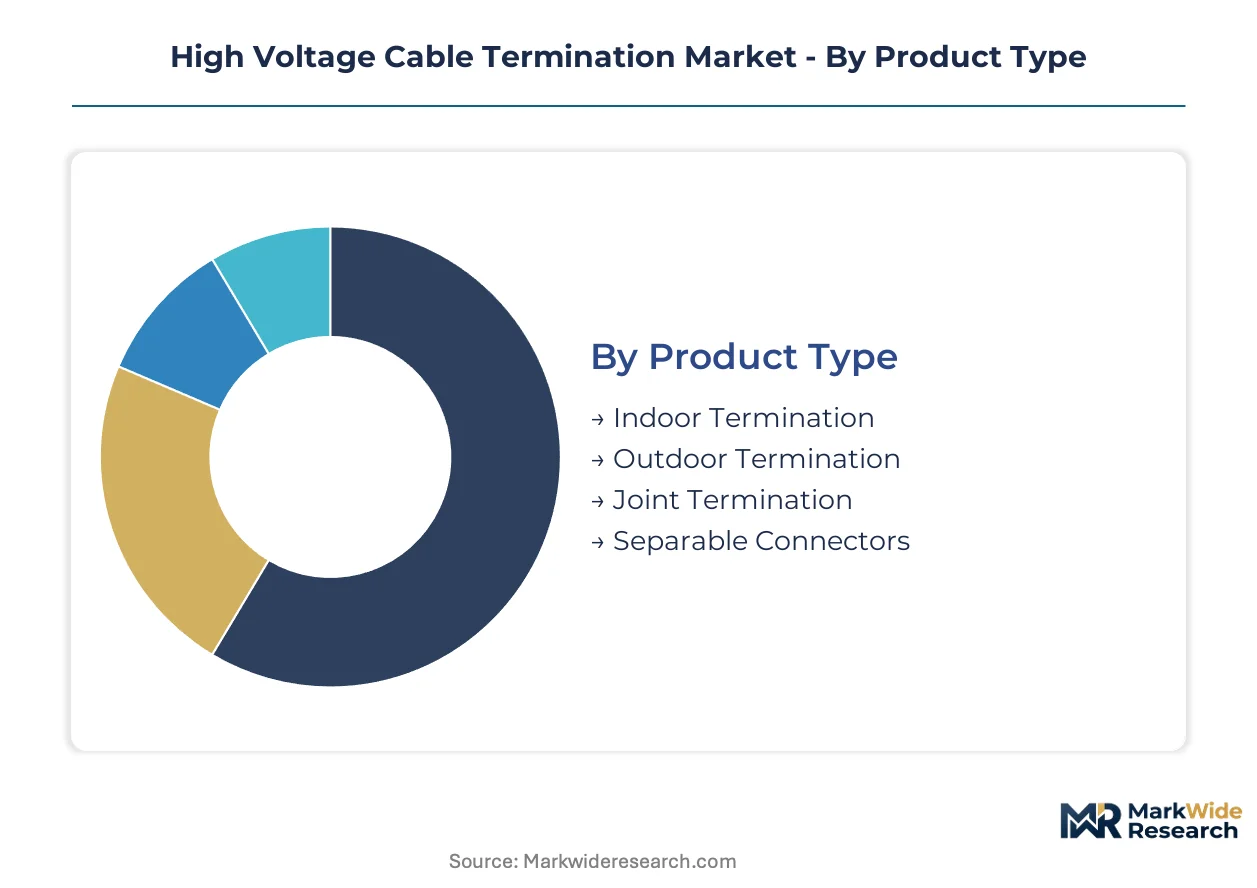
High voltage cable termination procurement splits across four distinct category systems that govern specification, installation method, and lifecycle economics. Each segmentation layer reveals different competitive dynamics: product type determines margin structure, technology drives contractor qualification requirements, application sets regulatory compliance burdens, and end user industry shapes purchasing behavior between bundled and unbundled procurement.
Product Type:
Outdoor terminations turn over fastest due to pollution flashover degradation and coastal corrosion cycles, while indoor terminations in climate-controlled substations persist for decades. Joint terminations and separable connectors occupy intermediate replacement rhythms tied to cable system upgrades rather than standalone failure modes.
- Outdoor Termination:Silicone rubber or EPDM housings with geometric stress cones manage electrical stress in exposed environments. Demand concentrates in China, where State Grid Corporation's ultra-high voltage corridors link western generation bases to eastern load centers under severe pollution-class specifications.
- Indoor Termination:Compact assemblies for switchgear and transformer interfaces prioritize space constraints over weatherproofing. European utilities specify these for gas-insulated substations governed by IEC 62271-209, filtering qualified vendors through accelerated aging protocols.
- Joint Termination:Factory-integrated assemblies combine cable joints with termination functions for greenfield corridors. Integrated cable manufacturers capture share through bundled procurement.
- Separable Connectors:Modular plug-in interfaces enable rapid switchgear connection and isolation. Offshore wind developers specify these for salt-fog environments in North Sea collector systems.
Outdoor termination dominates installed base due to relentless grid interconnection investments. Indoor termination is where expansion concentrates as utilities prioritize climate-controlled asset longevity.
Technology:
Cost tiers separate field-ready cold shrink kits from labor-intensive heat shrink and premium resin cast systems. Oil impregnated technology commands the highest material costs but delivers extended service intervals in harsh environments.
- Cold Shrink:Pre-expanded silicone rubber tubes with integrated stress cones deploy without open-flame permits. Offshore wind arrays in the Bohai Bay specify these exclusively, compressing installation windows from days to hours.
- Heat Shrink:Cross-linked polyolefin sleeves requiring propane torches and specialized contractor certifications. Legacy utility specifications still mandate these for 145 kV and below in mature markets.
- Resin Cast:Epoxy or polyurethane compounds poured in field molds for custom geometries. Tunnel and data center installations specify these for fire-resistance compliance.
- Oil Impregnated:Paper-oil insulation systems for ultra-high voltage terminations above 420 kV. State Grid Corporation tenders require these for seismic resilience under GB/T 12706.
Heat shrink retains legacy installed base across North American utilities. Cold shrink is climbing the fastest as procurement specifications rewrite around field-ready assembly methods.
Application:
Volume concentration tracks capital deployment cycles, with power transmission commanding the longest project timelines and data centers the most compressed procurement windows. Renewable energy applications impose the most stringent material specifications.
- Power Transmission:Terminations for overhead line interfaces and substation switchgear at 245 kV and above. India's Power Grid Corporation drives demand through green energy corridor buildouts.
- Renewable Energy:Dry-type terminations rated for salt-fog, cyclic loading, and subsea pressure in offshore wind arrays. European developers in the North Sea specify cold shrink exclusively.
- Power Distribution:Medium-voltage terminations for urban underground networks and rural overhead systems. Brazilian utilities separate installation services from material supply in tender structures.
- Railways:Compact terminations for traction power supply and signaling systems. Electrification projects in Saudi Arabia require localized installation supervision capabilities.
- Data Centers:Fire-resistant terminations for tunnel and building services with ceramic-composite housings. REACH restrictions on persistent organic pollutants force material disclosure documentation.
Power transmission anchors revenue concentration through multi-year project cycles. Renewable energy is gaining share fastest as offshore wind buildouts accelerate procurement of salt-fog-rated assemblies.
End User Industry:
Customer type determines bundling preferences: utilities favor integrated supply, contractors seek unbundled installation services, and infrastructure projects prioritize localized inventory proximity.
- Utilities:Grid operators with captive engineering staff who specify termination kits for in-house installation. China's State Grid Corporation imposes seismic and pollution-class requirements that reshape competitive qualification thresholds.
- Infrastructure Projects:Transportation and urban development authorities procuring through EPC contractors. Brazilian and Saudi Arabian markets have separated installation supervision from hardware procurement in tender structures.
- Electrical Contractors:Third-party installation specialists capturing standalone service contracts for commissioning oversight. Shortages of technicians qualified for live-work installation at 245 kV and above extend project timelines.
- Oil & Gas Facilities:Petrochemical and LNG terminal operators requiring explosion-proof terminations in hazardous area classifications. Specifications prioritize fire-resistance and material traceability.
Utilities dominate procurement volume through centralized transmission investment. Electrical contractors represent the steepest expansion trajectory as asset owners unbundle installation services from hardware supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. European utilities absorb premium cold shrink pricing for offshore wind reliability, while Indian transmission planners prioritize localized inventory availability over brand premiums. Chinese procurement imposes the steepest qualification barriers, locking out cost-competitive challengers from State Grid Corporation tenders.
China
State Grid Corporation's ultra-high voltage corridors drive concentrated demand for 550 kV terminations linking western generation bases to eastern load centers. GB/T 12706 seismic and pollution-class requirements impose multi-year testing cycles that reshape competitive entry thresholds. Manufacturing clusters in Jiangsu and Shandong provinces supply prefabricated stress cone assemblies for domestic transmission buildouts.
Germany
North Sea offshore wind developers specify dry-type terminations rated for salt-fog environments and cyclic mechanical loading in subsea collector systems. ECHA REACH restrictions on persistent organic pollutants force reformulation of conventional housing materials across supply chains. Industrial concentration in Hamburg and Bremen ports supports localized termination kit inventories for Baltic and North Sea installation campaigns.
United States
Utilities in Texas and California prioritize field-ready cold shrink assemblies that eliminate open-flame permits and reduce contractor certification burdens. IEEE 404 protocols govern product qualification for North American transmission markets, mandating accelerated aging tests that filter supplier pools. Gulf Coast petrochemical facilities require explosion-proof terminations in hazardous area classifications.
India
Power Grid Corporation of India's green energy corridors create demand for localized termination kit inventories and installation supervision capabilities. Central Electricity Authority technical specifications impose seismic resilience requirements for Himalayan and northeastern transmission routes. Manufacturing presence in Gujarat and Maharashtra supports regional distribution networks for 245 kV and above assemblies.
Saudi Arabia
Renewable energy and railway electrification projects separate installation supervision from hardware procurement in tender structures, creating standalone service contract opportunities. The national petroleum regulator mandates fire-resistance documentation for tunnel and facility installations. Industrial cities in Jubail and Yanbu concentrate demand for ceramic-composite housings in petrochemical termination applications.
High Voltage Cable Termination Market Competitive Landscape
Integrated cable manufacturers and specialized termination suppliers split the market along bundled versus unbundled procurement lines. Consolidation pressures intensify as utilities rewrite specifications around field-ready assembly methods. Three archetypes dominate: European industrial conglomerates with cable manufacturing scale, Asian electrical equipment specialists with utility relationships, and regional fabrication houses with localized installation networks. Competitive moves center on backward integration into silicone rubber compounding and geographic expansion through technician certification partnerships.
Within the integrated-tier segment, Prysmian and Nexans exemplify archetypes that leverage cable manufacturing scale to bundle termination contracts with high-voltage orders. Hitachi Energy anchors the digital convergence tier through integrated monitoring systems that track partial discharge in live assemblies. These three occupy positions that reflect distinct strategic bets: manufacturing integration, geographic reach through port-proximate inventories, and sensor-enabled service revenue streams.
| Leading Market Players |
|---|
| Prysmian |
| Nexans |
| Hitachi Energy |
| TE Connectivity |
| PFISTERER Holding |
| Brugg Cables |
| Sumitomo Electric Industries |
| LS Cable & System |
| Elcon Megarad |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Asian silicone rubber compounding facilities is compressing feedstock pricing power while simultaneously triggering consolidation among termination kit assemblers seeking margin defense through captive material supply.
Pricing Analysis
Aftermarket service revenue from installation supervision and condition monitoring contracts now drives lifetime value capture, displacing pure hardware margins. Pricing stratifies across premium cold shrink assemblies with embedded partial discharge sensors, standard field-ready kits for utility procurement, and economy heat shrink alternatives for legacy retrofit work. Cost compression in the standard tier intensifies because Chinese State Grid Corporation tenders impose multi-year qualification cycles that lock out cost-competitive challengers. Distribution utilities exhibit the sharpest price sensitivity, while offshore wind developers absorb premium positioning for salt-fog-rated dry-type terminations.
Supply Chain Analysis
Upstream silicone rubber and EPDM compound supply draws from petrochemical clusters in China, South Korea, and Germany, with specialty polymer grades tethered to Asian manufacturers serving the high-voltage insulation market. Key inputs span geometric stress cone prefabrication, ceramic-composite housing molding, and intumescent sealing compound formulation. Single-source vulnerability concentrates in medical-grade silicone feedstock for ultra-high voltage applications above 420 kV. Distribution runs through integrated cable manufacturers bundling termination contracts with high-voltage orders, alongside regional fabrication houses maintaining localized inventories near offshore wind installation ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement concentration among State Grid Corporation, Power Grid Corporation of India, and European offshore wind consortia is shifting negotiating leverage toward buyers with multi-year corridor commitments.
For Market Incumbents: Entrench position through backward integration into silicone rubber compounding and captive stress cone manufacturing in Jiangsu or Shandong clusters. Prefabricated joint substitution from integrated cable manufacturers poses the most direct share threat. Certification investment in GB/T 12706 seismic resilience and IEC 62271-209 accelerated aging protocols creates qualification moats that filter lower-tier competitors from tender pools.
For New Entrants and Emerging Players: Pursue standalone installation supervision contracts in Brazil and Saudi Arabia where utilities have unbundled commissioning services from hardware procurement. India's green energy corridors present the most penetrable geography given localized inventory gaps and technician certification shortages for live-work assembly at 245 kV and above. Partner with regional electrical contractors possessing established technician networks rather than competing on manufacturing scale.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cold shrink assembly lines as pre-expanded silicone rubber tube production achieves scale economies. Long-term viability favors targets with digital monitoring capabilities feeding utility asset management platforms. Acquisition focus should center on regional fabrication houses with certified technician partnerships. Watch for inflection when State Grid Corporation accelerates ultra-high voltage corridor commissioning beyond current seismic qualification capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Compounding | Captive supply of specialty polymers insulates margin structures from petrochemical volatility. |
| Embedded Partial Discharge Sensor Development | Real-time diagnostic integration creates recurring condition-based maintenance revenue streams with utilities. |
| Localized Technician Certification Partnerships | Regional training networks capture unbundled installation supervision spend in Brazilian and Saudi tenders. |
| GB/T 12706 Seismic Qualification Investment | Multi-year testing cycles lock out challengers from State Grid Corporation ultra-high voltage procurement. |
| Ceramic-Composite Housing Scale-Up | Fire-resistance mandates in tunnel and data center installations redirect material specifications toward non-polymer alternatives. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, EPC contractor procurement leads, offshore wind project developers, termination kit manufacturing engineers, and aftermarket service technicians. Secondary validation drew from IEC and IEEE standards documentation, State Grid Corporation technical specifications, customs trade data for high-voltage cable assemblies, FERC interconnection filings, and ECHA REACH regulatory updates. Bottom-up segment sizing across product type, technology, application, and end user industry was triangulated against top-down transmission investment forecasts from national grid operators.
Calibration against historical procurement volumes from Power Grid Corporation of India and European offshore wind auction awards anchored the analytical framework across the projection horizon. Segmentation dimensions modeled span outdoor versus indoor termination type, cold shrink versus heat shrink versus resin cast technology, renewable energy versus power transmission application, and utility versus contractor versus infrastructure project end user. CAGRs were derived from regression analysis of capital deployment cycles and standard adoption curves. Industry-specific inputs included offshore wind capacity installation schedules and ultra-high voltage corridor commissioning timelines from State Grid Corporation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by integrated cable manufacturers or accelerated digital monitoring convergence by electrical equipment specialists would shift outcomes. Cross-checking against transmission project development databases and utility capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Detector Market
Cables
Instrumentation Cables Market
Cables
Flexible Cables Market
Cables
Premise Cable Market
Cables
Copper Cable Market
Cables
SATA Power Cable Market
Cables
Cable Carrier Market
Cables
Europe Cable Management Market
Cables
Ethernet Converters Market
Cables
North America Coaxial Cable Market
Cables
Cable Lugs Market
Cables
Cable Management System Market
Cables
Aluminum Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Twisted Pair Cable Market
Cables
US Medium Voltage Cable Accessories Market