
 Usb Data Cable Market | 2026-2036
Usb Data Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Usb Data Cable Market Analytics
USB-IF certification is redrawing competitive boundaries as power-delivery thresholds climb past 240W. Belkin International leverages its first-party retail presence to sustain premium positioning in North American electronics channels. Anker Innovations anchors its expansion through GaN-integrated charging ecosystems that bundle high-wattage cables with adapter sales. Samsung Electronics dominates supply for its own Galaxy device ecosystem, controlling captive demand through proprietary Super Fast Charging protocols.
A USB data cable is a conductive assembly comprising copper-alloy conductors, thermoplastic elastomer jackets, and precision-molded connector housings engineered to transmit digital signals and DC power between host and peripheral devices under USB Implementers Forum electrical specifications. USB-C configurations now lead volume shipments as the connector type subsumes legacy USB-A and Micro USB interfaces across consumer electronics and automotive infotainment systems. Nylon braided materials command margin premiums over PVC and rubber alternatives by addressing flex-fatigue failure in industrial and high-mobility applications. Consumer electronics remains the dominant application segment, though automotive integration of USB-C for data and power delivery represents the fastest-expanding demand pool.
FCC equipment authorization governs electromagnetic interference thresholds for cables sold in the United States, while the EU's Radio Equipment Directive mandates USB-C as the universal charging interface, directly reshaping connector-type demand across the European market. China's GB standards, administered by MIIT, set domestic baseline specifications that many export-oriented Shenzhen manufacturers exceed to qualify for international certification. Stakeholders must monitor whether India's BIS compulsory registration order expands to cover USB cables, as that would create a new compliance gate for suppliers targeting the country's accelerating smartphone replacement cycle.
Market Dynamics
The EU's common charger directive is compressing legacy connector demand while Shenzhen's component clusters concentrate supply-side power among vertically integrated manufacturers.
Growth Catalysts
- USB-C Mandates:The EU Radio Equipment Directive now requires USB-C as the universal charging interface across smartphones, tablets, and cameras, eliminating fragmentation in European device ecosystems.
- GaN Adapter Bundling:Gallium nitride power electronics are shrinking adapter footprints and driving cable wattage requirements past 100W, creating pull-through demand for high-gauge copper assemblies.
- Automotive Infotainment Integration:USB-C ports are proliferating in vehicle center consoles for both data and power delivery, opening a new demand channel distinct from consumer electronics replacement cycles.
Market Restraints
- Copper Price Volatility:Raw material swings in copper-alloy conductors compress margin predictability for cable assemblers operating on fixed-price retail contracts.
- Shenzhen Supply Concentration:Over 70% of global USB cable manufacturing capacity clusters in Guangdong province, exposing buyers to single-region geopolitical and logistics disruption risk.
- Wireless Charging Substitution:Qi2 magnetic alignment standards are capturing bedside and desktop charging occasions, eroding cable replacement frequency in residential settings.
Strategic Opportunities
- India BIS Expansion:India's compulsory registration order for electronics may extend to USB cables, creating first-mover certification advantages for suppliers ahead of formal mandate.
- Industrial Nylon Braiding:Flex-fatigue-resistant thermoplastic elastomer jackets are penetrating factory automation and medical mobility applications where PVC fails under repetitive motion stress.
- USB-IF Certification Premiums:Official certification logos are commanding shelf price separation in North American retail channels where power-delivery safety concerns dominate purchase decisions.
Industry Challenges
- USB-IF Testing Backlogs:Certification queue delays at USB Implementers Forum laboratories are stretching product launch timelines for new power-delivery specifications.
- Legacy Micro USB Inventory:Distributors face write-down exposure on aging connector stock as USB-C penetration accelerates in emerging market entry-level smartphones.
- EMI Shielding Complexity:FCC equipment authorization for 240W cables requires advanced braided shielding designs that strain thermoplastic molding capabilities at mid-tier assemblers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Usb Data Cable Market |
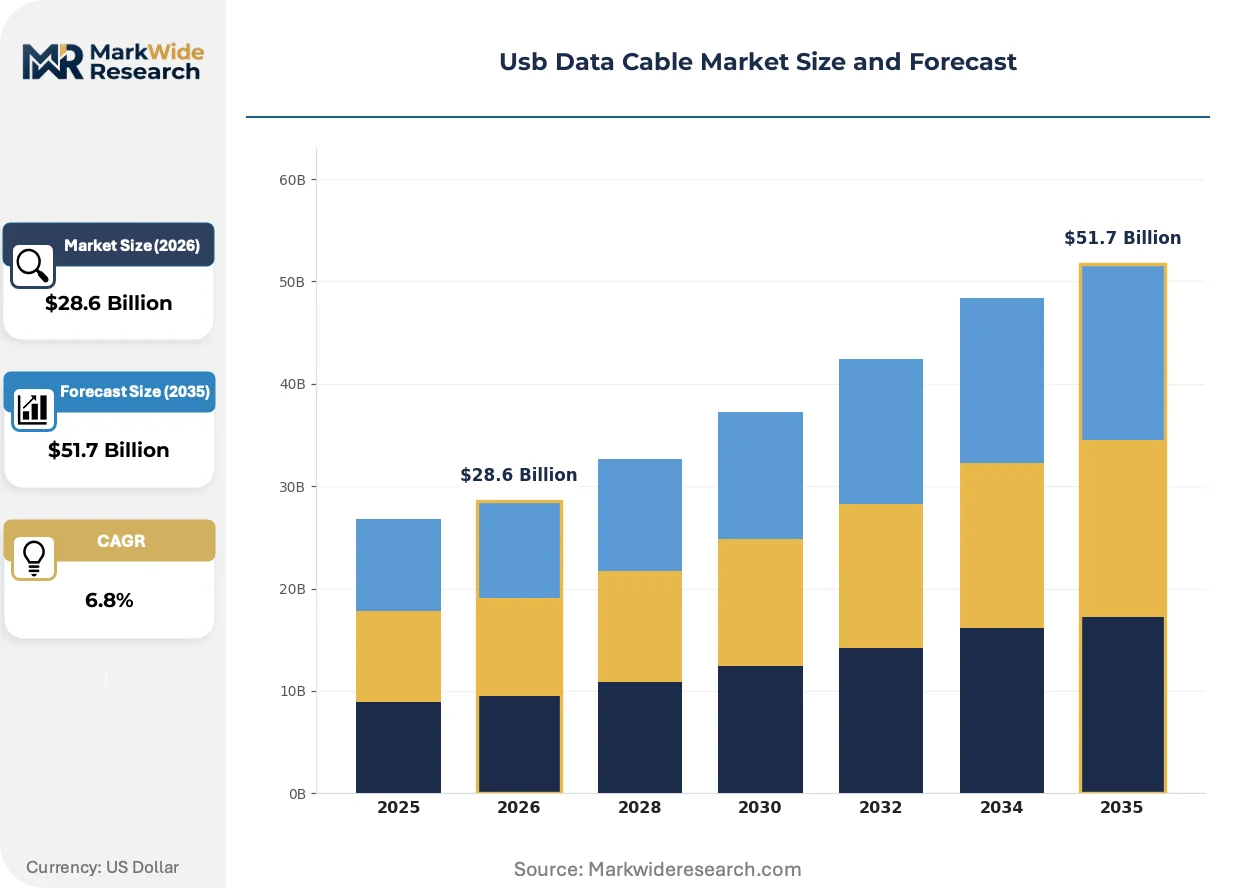
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: USB-A, USB-B, USB-C, Micro USB Material: Plastic, Nylon Braided, PVC, Rubber Connector Type: Standard, Fast Charge, Data Transfer, Lightning Application: Consumer Electronics, Automotive, Industrial, Others |
| Companies Covered | Belkin International, Anker Innovations, Samsung Electronics, Apple Inc, UGREEN Group, Baseus Technology Group, Black Box, Ching Tai Electric Wire and Cable, GORE Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Usb Data Cable Market Evolving Landscape
Active optical cable technology is breaching copper's bandwidth ceiling while regulatory mandates and procurement centralization are rewriting competitive entry requirements across distribution channels.
Silicon photonics is supplanting copper conductors in data-center interconnects exceeding 10Gbps. Hyperscale cloud operators are piloting active optical USB-C assemblies for rack-scale architectures where electrical signal degradation limits copper runs. This displacement is compressing the addressable market for premium copper shielding in enterprise storage applications.
China's GB standards administered by MIIT are tightening electromagnetic compatibility thresholds for domestic-market cables. Export-oriented Shenzhen manufacturers must now maintain dual specification lines to satisfy both international USB-IF certification and stricter local baseline requirements. Automotive OEMs sourcing for Chinese domestic production are most exposed to this compliance bifurcation.
Enterprise IT procurement is consolidating cable purchasing through managed service contracts rather than ad-hoc retail acquisition. Value-added distributors are displacing big-box electronics retailers in North American B2B channels by bundling certified cables with device deployment services. This concentration is most visible in healthcare and financial services verticals where asset-tracking requirements dominate specification decisions.
Usb Data Cable Market Segmentation
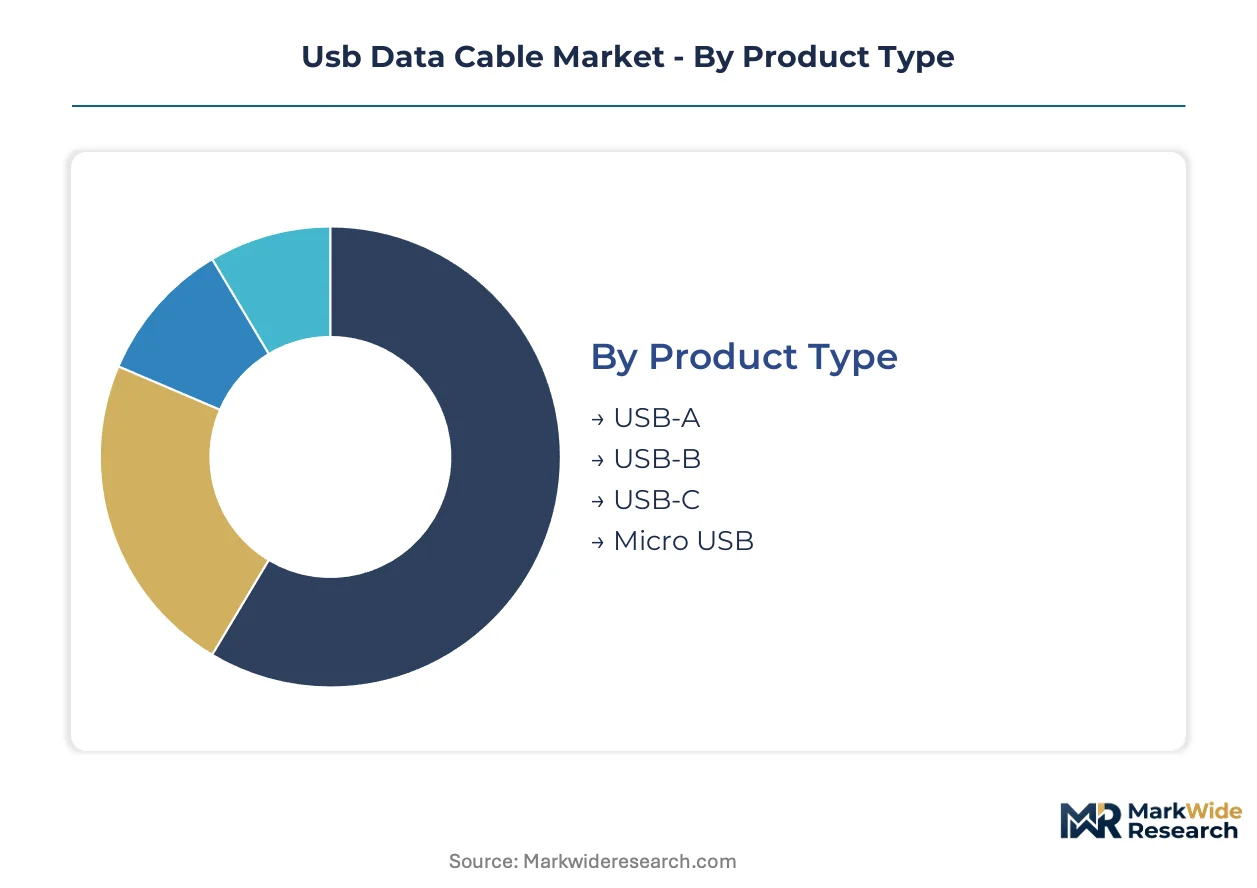
USB cable segmentation tracks how connector standards, material specifications, and end-use applications map to distinct procurement channels. Channel strategy diverges sharply between retail consumer electronics, automotive OEM supply contracts, and industrial distributor networks.
Product Type:
Channel mix splits between retail electronics for consumer connectors and direct automotive supply for vehicle-integrated assemblies. USB-C flows through both channels, while legacy formats concentrate in aftermarket retail and emerging market replacement cycles.
- USB-C:Copper-alloy conductors with 24-pin reversible housings now dominate new device shipments. Automotive infotainment systems in Germany and consumer electronics in Shenzhen anchor demand concentration, with EU Radio Equipment Directive mandates eliminating competing formats in European retail channels.
- USB-A:Legacy rectangular connectors persist in desktop computing peripherals and automotive rear-seat charging ports. Replacement demand concentrates in North American office supply distributors where enterprise IT procurement maintains backward compatibility requirements.
- USB-B:Squared peripheral connectors serve industrial printers and medical imaging equipment. Demand clusters in Japanese factory automation supply chains where equipment refresh cycles lag consumer electronics by multiple years.
- Micro USB:Tapered 5-pin connectors retain volume in emerging market entry-level smartphones and IoT sensors. Indian distributor networks and African retail channels carry residual inventory as USB-C penetration accelerates from premium tiers downward.
USB-A dominates installed base. USB-C is where expansion concentrates.
Material:
Cost tier stratification separates commodity PVC for price-sensitive retail from engineered thermoplastic elastomers for industrial specifications. Margin structure inverses raw material cost, with premium braiding commanding shelf price separation.
- Nylon Braided:Interwoven polyamide fibers over thermoplastic cores resist flex-fatigue failure under repetitive motion stress. German automotive harness suppliers and Korean medical mobility equipment manufacturers specify braided jackets for factory automation and patient monitoring applications where PVC fractures.
- PVC:Polyvinyl chloride jackets offer lowest unit cost for high-volume consumer retail. Chinese e-commerce platforms and North American big-box electronics channels move PVC assemblies in multi-pack configurations where replacement frequency exceeds durability requirements.
- Plastic:Molded ABS or polycarbonate housings with basic strain relief serve disposable promotional and hospitality applications. Indian hospitality technology distributors and Brazilian corporate procurement channels source plastic assemblies for conference room and guest room installations.
- Rubber:Thermoplastic elastomer formulations provide oil resistance and temperature stability for industrial environments. Japanese manufacturing equipment suppliers and Mexican automotive Tier 2 suppliers specify rubber jackets for production floor and under-hood applications.
PVC captures highest shipment volumes. Nylon braided is climbing the fastest.
Connector Type:
Application specificity determines whether connectors optimize for power delivery, data bandwidth, or proprietary protocol compatibility. Automotive and industrial procurement prioritizes power-delivery certification, while consumer retail segments on charging speed claims.
- Fast Charge:Power-delivery configurations support 100W+ wattage with dedicated VBUS and CC pin architectures. Samsung Electronics captive supply chains and Anker Innovations retail bundles drive specification concentration, with USB-IF certification logos commanding price separation in North American electronics channels.
- Data Transfer:USB 3.2 and USB4 signaling configurations prioritize differential pair integrity for 10-40Gbps throughput. Hyperscale cloud operators in Virginia and Hesse pilot active optical alternatives where copper signal degradation limits rack-scale runs.
- Standard:Baseline 5V/0.5A configurations serve low-power peripherals and legacy device compatibility. Chinese white-label assemblers and Southeast Asian retail distributors move standard connectors in bulk configurations for cost-sensitive replacement cycles.
- Lightning:Apple's proprietary 8-pin connector retains captive demand within iOS device ecosystems. Authorized accessory programs and MFi certification requirements constrain supply to approved manufacturing partners, with Belkin International holding retail channel positioning.
Standard connectors dominate installed base. Fast charge is gaining share fastest.
Application:
Customer type and volume concentration separate high-frequency consumer replacement from long-cycle industrial procurement. Automotive applications sit between these poles with OEM specification lock-in and aftermarket accessory demand.
- Consumer Electronics:Smartphones, tablets, laptops, and peripherals drive replacement and upgrade cycles. Shenzhen component clusters anchor production capacity, with EU common charger directive standardizing USB-C across device ecosystems and compressing legacy connector demand.
- Automotive:Center console infotainment integration and rear-seat charging ports create dual demand channels. German OEMs and Japanese Tier 1 suppliers specify USB-C for data and power delivery, with domestic content requirements in China forcing dual specification lines for export versus local production.
- Industrial:Factory automation, medical equipment, and ruggedized field devices prioritize flex-fatigue resistance and EMI shielding. FDA equipment authorization for medical mobility and FCC electromagnetic interference thresholds govern specification requirements in North American healthcare and industrial channels.
- Others:Aerospace, defense, and specialized telecommunications applications impose custom shielding and connector locking mechanisms. ITAR-controlled supply chains and national security procurement constraints limit supplier qualification to domestic manufacturers in United States and European defense industrial bases.
Consumer electronics dominates installed base. Automotive is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex anchors Asia-Pacific cable throughput, handling raw copper imports and finished assembly exports for consumer electronics supply chains. Rotterdam's container terminals serve as the European distribution node for USB-C inventory entering EU common charger directive markets. Dubai's Jebel Ali port facilitates Middle East transshipment for cables bound for African retail channels.
China
Shenzhen's component clusters concentrate over 70 percent of global manufacturing capacity for USB-C assemblies. MIIT's GB standards enforce stricter electromagnetic compatibility thresholds than international baselines, forcing dual specification lines for export versus domestic production. Guangdong province's vertically integrated manufacturers control connector molding, copper drawing, and final assembly within single industrial parks.
United States
FCC equipment authorization governs electromagnetic interference thresholds for cables sold through North American electronics channels. Enterprise IT procurement is consolidating purchasing through managed service contracts rather than ad-hoc retail acquisition. Virginia's hyperscale data center operators pilot active optical alternatives where copper signal degradation limits rack-scale architectures.
Germany
Automotive OEMs specify USB-C for center console infotainment integration and rear-seat charging ports. The EU Radio Equipment Directive mandates USB-C as the universal charging interface, eliminating competing formats in European retail channels. Baden-Württemberg's Tier 1 suppliers source certified assemblies for vehicle-integrated data and power delivery systems.
India
BIS compulsory registration order for electronics may extend to USB cables, creating first-mover certification advantages for suppliers ahead of formal mandate. Mumbai and Delhi-NCR distributor networks carry residual Micro USB inventory as USB-C penetration accelerates from premium smartphone tiers downward. Maharashtra's retail channels show accelerating replacement cycles driven by the country's smartphone upgrade momentum.
Japan
METI-administered JIS standards govern industrial cable specifications for factory automation and medical imaging equipment. Osaka-based manufacturing equipment suppliers specify rubber-jacketed assemblies for production floor applications requiring oil resistance. Kanto region's medical mobility equipment manufacturers prioritize flex-fatigue-resistant thermoplastic elastomer jackets for patient monitoring systems.
Usb Data Cable Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and channel access dimensions. The vendor base splits between publicly traded electronics conglomerates controlling captive device ecosystems and privately held accessory specialists dominating third-party retail placement. Three archetypes define competitive positioning: vertically integrated device OEMs, retail-channel accessory brands, and industrial specification suppliers. Dominant competitive moves include USB-IF certification queue positioning and GaN adapter bundling strategies.
Among retail-channel specialists, Belkin International and Anker Innovations exemplify the premium-tier positioning archetype through first-party electronics channel presence and certified power-delivery portfolios. Samsung Electronics represents the captive ecosystem model, controlling internal demand through proprietary charging protocols. Shenzhen-based UGREEN Group occupies the scale-driven, cross-platform compatibility segment serving multi-device households.
| Leading Market Players |
|---|
| Belkin International |
| Anker Innovations |
| Samsung Electronics |
| Apple Inc |
| UGREEN Group |
| Baseus Technology Group |
| Black Box |
| Ching Tai Electric Wire and Cable |
| GORE Electronics |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with Shenzhen manufacturers lock in copper-alloy supply access while fixing unit costs against raw material swings. This structure concentrates price-setting power among vertically integrated Guangdong producers who control connector molding through final assembly.
Pricing Analysis
Certification level creates the primary spread between USB-IF verified assemblies and uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects USB-IF logo presence, copper gauge thickness, and jacket material grade. Price erosion runs through PVC commodity tiers as Chinese e-commerce platforms compress retail premiums. Enterprise IT procurement through managed service contracts shows lowest price sensitivity, while Southeast Asian retail distributors exhibit highest elasticity.
Supply Chain Analysis
China and Vietnam anchor global cable assembly capacity, with Guangdong province housing over seventy percent of USB-C production. Raw material flows draw from Chilean copper concentrates, Japanese thermoplastic elastomer formulations, and Korean connector contact alloys. Single-region concentration in Shenzhen exposes buyers to geopolitical disruption risk. Distribution runs through Rotterdam for European markets, Dubai for Middle East and Africa transshipment, and Los Angeles for North American retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise IT procurement consolidation is shifting buyer power toward managed service providers who bundle certified cables with device deployment. This concentration favors suppliers with USB-IF certification depth and direct B2B channel relationships.
For Market Incumbents: Compound certification queue positioning at USB-IF laboratories to secure early access to 240W power-delivery specifications. Deepen backward integration into copper-alloy drawing and connector molding to defend margin position against raw material volatility. Wireless charging substitution in residential settings threatens replacement frequency—counter through GaN adapter bundling that locks in cable pull-through demand. For New Entrants and Emerging Players: Differentiate on industrial nylon braiding specifications for factory automation and medical mobility applications where flex-fatigue resistance commands premium positioning. India's BIS registration expansion represents the most penetrable geography, with Mumbai and Delhi-NCR distributor networks seeking certified suppliers ahead of formal mandate. Pursue automotive Tier 2 qualification in Germany and Japan where OEM specification lock-in creates multi-year revenue visibility. For Investors and Strategic Acquirers: USB-IF certified mid-cap specialists with automotive qualification represent the most defensible acquisition profile for long-term viability across the five-to-ten year window. These targets combine regulatory moats with exposure to automotive infotainment integration. Monitor India's BIS compulsory registration order implementation timeline as the critical inflection signal for geographic reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| USB-IF Certification Investment | Official logos command shelf price separation in North American electronics channels where power-delivery safety concerns dominate purchase decisions. |
| GaN Adapter Bundling | Shrinking adapter footprints drive cable wattage requirements past 100W, creating pull-through demand for high-gauge copper assemblies. |
| Automotive Tier 1 Qualification | German OEMs specify USB-C for center console infotainment integration, opening multi-year supply contracts distinct from consumer replacement cycles. |
| India BIS Pre-Registration | First-mover certification advantages ahead of formal mandate create procurement preference among Mumbai and Delhi-NCR distributor networks. |
| Active Optical Cable Development | Silicon photonics supplants copper in hyperscale data-center interconnects exceeding 10Gbps, compressing addressable market for premium copper shielding. |
Research Methodology
Operator-level perspectives from cable assembly plant managers, electronics procurement officers at OEMs, USB-IF certification engineers, and retail channel category buyers anchored the qualitative base. Secondary validation drew from FCC equipment authorization databases, EU Radio Equipment Directive implementation notices, MIIT GB standard publications, and USB Implementers Forum specification releases. Bottom-up volume estimates triangulated against top-down market sizing across connector type, material grade, and application segments.
Sensitivity analysis tested forecast outputs against copper price volatility scenarios, USB-C mandate acceleration timelines, and wireless charging penetration rates. Segmentation dimensions modeled include connector standard, jacket material specification, power-delivery rating, and end-use application category. CAGRs were derived from installed base replacement cycles, device shipment forecasts, and automotive infotainment port penetration assumptions. Industry-specific inputs incorporated EU common charger directive compliance deadlines and India's BIS registration expansion trajectory.
Material uncertainties—copper commodity swings, geopolitical disruption in Guangdong province, and Qi2 magnetic alignment standard adoption—sit outside the modeled envelope. Forecasts reflect assumptions about regulatory mandate implementation and technology substitution timelines. Recalibration cycles align with material shifts in USB-IF specification releases, BIS regulatory announcements, and automotive OEM platform decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Solar Cable Market
Cables
Europe Cable Accessories Market
Cables
Global Cable Blowing Equipment Market
Cables
Copper Cable Market
Cables
Instrumentation Cables Market
Cables
Cable Testers Market
Cables
Europe HVAC Cables Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Fiber Optic Cable Materials Market
Cables
Medium Voltage Cables Market
Cables
Electric Vehicle Cables Market
Cables
Patch Cable Market
Cables
Submarine Communication Cables Market
Cables
Wire and Cable Label Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Cable Market