
 Submarine Optical Fiber Cables Market | 2026-2036
Submarine Optical Fiber Cables Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Optical Fiber Cables Market Analysis
The premium-to-commodity split in submarine cable systems is repositioning around repeater spacing and fiber pair count as the decisive technical boundary. Alcatel Submarine Networks leverages its integrated manufacturing of both cable and repeater housings to control delivery timelines on complex routes. SubCom sustains dominance in the trans-Atlantic corridor through dedicated cable-laying vessel fleets. HMN Technologies competes aggressively on cost-engineered shallow-water deployments for regional island networks.
Submarine optical fiber cables consist of fiber-optic strands encased in copper power conductors, polyethylene insulation, and steel-wire armor, engineered to transmit terabit-scale traffic across oceanic distances with repeater-assisted signal regeneration. Their primary commercial purpose is to form the physical backbone of international internet traffic, carrying over ninety-nine percent of intercontinental data flows. Single mode fiber dominates long-haul routes due to lower attenuation and compatibility with dense wavelength division multiplexing systems that multiply per-fiber capacity. Shallow water installation commands distinct engineering requirements for burial and fishing protection, creating separate margin pools from deep-water lays where cable ships operate in uninterrupted descent. Data centers as an end-user category are reshaping procurement patterns, with hyperscale buyers now contracting directly for dedicated fiber pairs rather than purchasing capacity from telecom operators.
The International Cable Protection Committee coordinates seabed corridor governance, while national regulators including the FCC in the United States and Japan's MIC enforce landing station licensing and cable station security protocols. These frameworks shape project timelines, as permit delays in any single coastal jurisdiction can stall multi-thousand-kilometer systems. Stakeholders must monitor how seabed mining claims and marine protected area expansions constrain route planning flexibility in corridors that have carried cables for decades.
Market Dynamics
Hyperscale data center operators now contract directly for dedicated fiber pairs, bypassing traditional telecom carriers and compressing procurement cycles from multi-year capacity leases to asset-specific ownership models.
Growth Catalysts
- Trans-Pacific corridor expansion:Cloud infrastructure deployment between the United States and Japan requires continuous subsea capacity augmentation to synchronize distributed computing regions.
- Coastal zone management frameworks:Streamlined permitting in select jurisdictions accelerates project approval timelines for cable landing stations.
- Dense wavelength division multiplexing:DWDM technology multiplication of per-fiber capacity enables terabit-scale traffic without additional physical cable lays.
Market Restraints
- Specialized cable-laying vessel scarcity:Fleet concentration among three operators limits simultaneous project execution across multiple oceanic corridors.
- Copper conductor price volatility:Power feed components embedded in cable construction expose manufacturers to commodity metal cost swings.
- Marine protected area expansion:Seabed corridor restrictions in the Pacific and Atlantic constrain historically viable route planning options.
Strategic Opportunities
- Southeast Asian island networks:Indonesia, the Philippines, and Vietnam present underpenetrated shallow-water deployment potential for regional connectivity meshes.
- Seabed mining corridor co-location:Cable routes aligned with emerging mineral extraction zones enable shared survey and maintenance infrastructure.
- Japan's MIC security protocol harmonization:Standardized cable station protection requirements reduce bilateral negotiation friction for trans-Pacific projects.
Industry Challenges
- Subsea optical amplification expertise scarcity:Repeater engineering and ocean-floor installation specialization outpaces vocational training program output.
- Multi-jurisdictional permit synchronization:FCC licensing in the United States, Japan's MIC approvals, and United Kingdom coastal permits must align for single system completion.
- Legacy system interoperability:New high-fiber-count cables must interface with decades-old landing station infrastructure without signal degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Optical Fiber Cables Market |
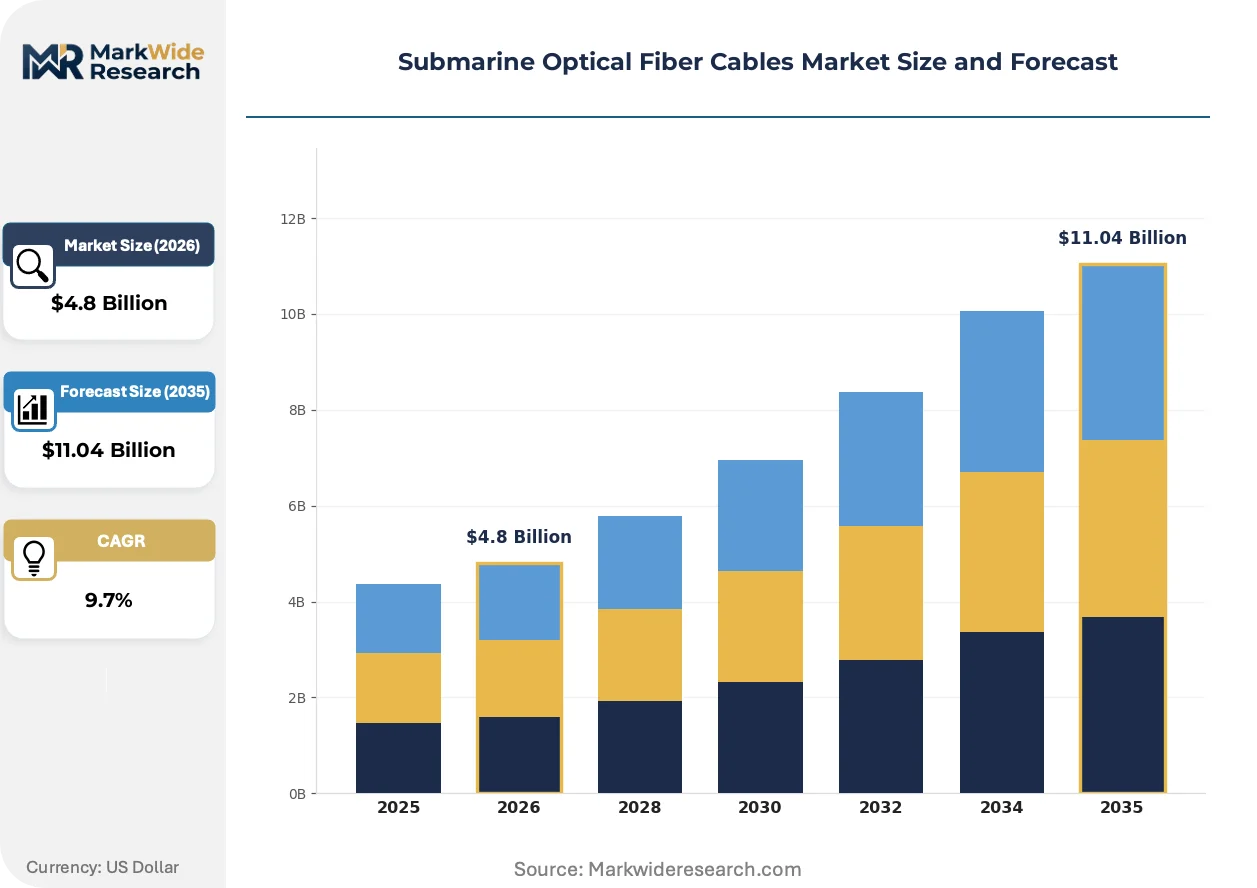
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Mode, Multi Mode, Armored, Non-armored Installation Type: Shallow Water, Deep Water, Terrestrial, Hybrid End User: Telecom Operators, Data Centers, Government, Corporations Transmission Technology: Wavelength Division Multiplexing, Optical Amplifiers, Dense Wavelength Division Multiplexing, Frequency Division Multiplexing |
| Companies Covered | Alcatel Submarine Networks, SubCom, HMN Technologies, NEC Corporation, Prysmian Group, Nexans, Global Marine Group, Corning, Hengtong Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Optical Fiber Cables Market Emerging Trajectories
Signal regeneration automation and direct fiber pair ownership models are compressing traditional carrier intermediation while forcing manufacturers to integrate predictive maintenance capabilities into cable system design.
Space-division multiplexing through multi-core fiber architectures is automating capacity scaling without proportional vessel deployment expansion. Hyperscale operators in the United States and Japan are adopting these systems for trans-Pacific routes. The technology is automating route economics by decoupling bandwidth growth from physical cable count.
Japan's MIC has tightened cable station security protocols requiring biometric access controls and seismic isolation standards. This policy elevates capital requirements for landing facility construction. Trans-Pacific corridor projects are responding by consolidating station designs to reduce certification complexity across multiple coastal jurisdictions.
Direct asset ownership by data center operators displaces traditional indefeasible rights of use agreements. Cloud buyers now specify fiber pair count, repeater spacing, and maintenance terms in initial contracts. This pattern concentrates in the United States-Japan-United Kingdom triangle where hyperscale infrastructure investment is deepest.
Submarine Optical Fiber Cables Market Segmentation
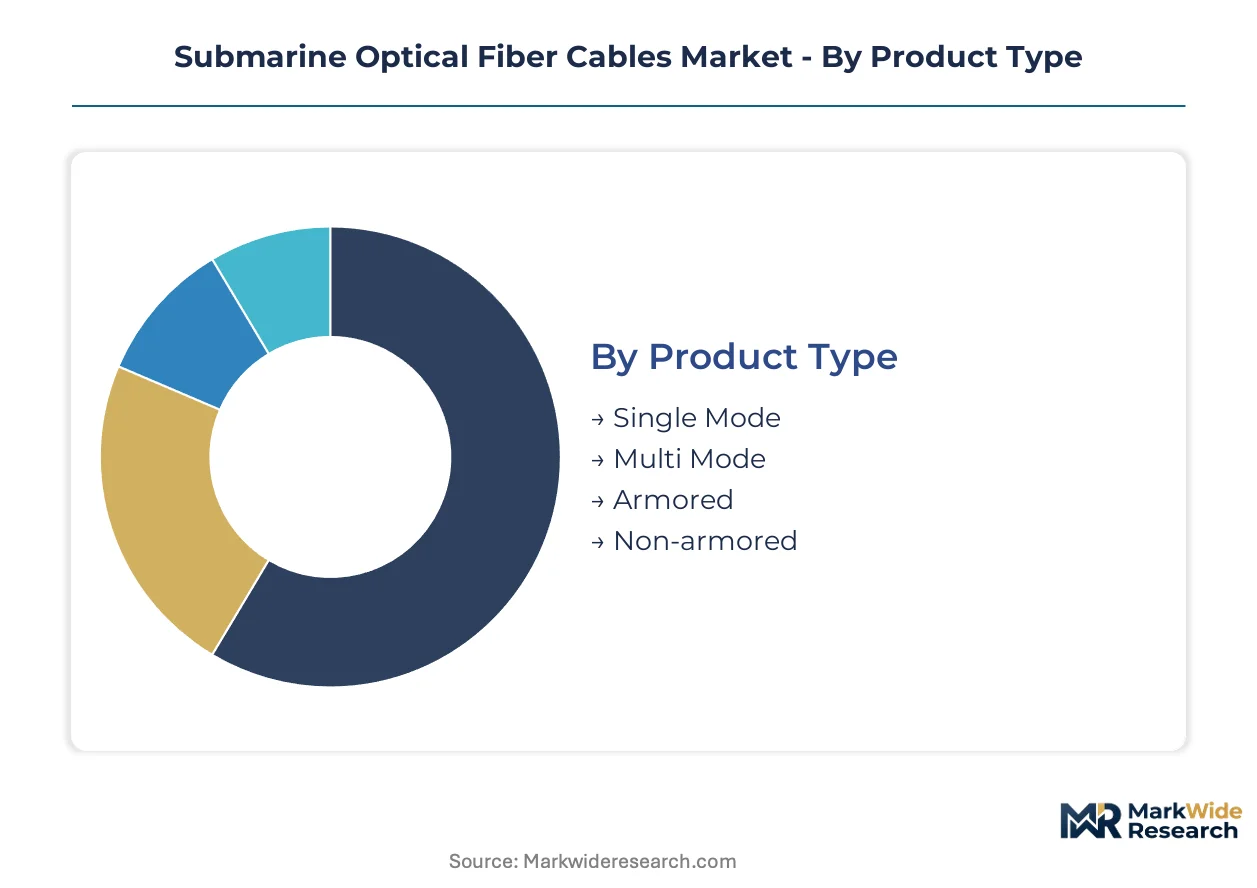
Submarine cable procurement patterns diverge sharply between standardized shallow-water deployments and bespoke deep-ocean systems requiring custom repeater engineering. Segmentation reveals how hyperscale buyers now prioritize fiber pair ownership over capacity leases, reshaping manufacturer priorities across product tiers.
Product Type:
Standardization dominates high-volume shallow-water orders, while deep-ocean routes demand customized fiber count and armor specifications.
- Single Mode:Engineered with narrow core diameter to minimize signal dispersion across trans-Pacific distances. Data center operators between the United States and Japan specify single mode exclusively for cloud region synchronization, driving dedicated fiber pair contracting.
- Multi Mode:Larger core diameter supports shorter-haul island networks with relaxed attenuation requirements. Regional connectivity meshes in Indonesia and the Philippines deploy multi mode for cost-engineered shallow-water links.
- Armored:Steel-wire reinforcement protects against fishing gear and seabed abrasion in coastal zones.
- Non-armored:Lightweight construction reduces vessel payload for deep-water lays where burial is impractical.
Most installed capacity flows through Single Mode. Expansion is steepest in Armored configurations for Southeast Asian island networks.
Installation Type:
Cost structures separate dramatically between vessel-intensive deep-water operations and shallow-water burial programs.
- Deep Water:Cable ships operate in uninterrupted descent beyond continental shelves, requiring specialized fleet availability. The trans-Atlantic corridor sustains concentrated demand here, though vessel scarcity limits simultaneous project execution.
- Shallow Water:Burial and fishing protection engineering create distinct margin pools. Vietnam, Indonesia, and the Philippines present underpenetrated deployment potential for regional connectivity meshes.
- Terrestrial:Landing station-to-backhaul links complete end-to-end connectivity.
- Hybrid:Combined shallow-deep routing optimizes cost on complex archipelago topologies.
Deep Water claims the majority of capital deployment. Shallow Water is climbing the fastest as island network densification accelerates.
End User:
Procurement authority is shifting from carrier intermediaries to asset-direct buyers with specific engineering requirements.
- Data Centers:Hyperscale operators now contract directly for dedicated fiber pairs, specifying repeater spacing and maintenance terms. Cloud infrastructure deployment between the United States and Japan compresses procurement cycles from multi-year leases to ownership models.
- Telecom Operators:Traditional indefeasible rights of use agreements face displacement as cloud buyers bypass carrier intermediation. Remaining carrier demand concentrates on wholesale capacity aggregation.
- Government:Cable station security protocols and coastal zone permits drive sovereign infrastructure investment.
- Corporations:Private network demand remains fragmented across regional banking and energy consortia.
Telecom Operators still host the largest installed base. Data Centers are gaining share fastest through direct asset ownership.
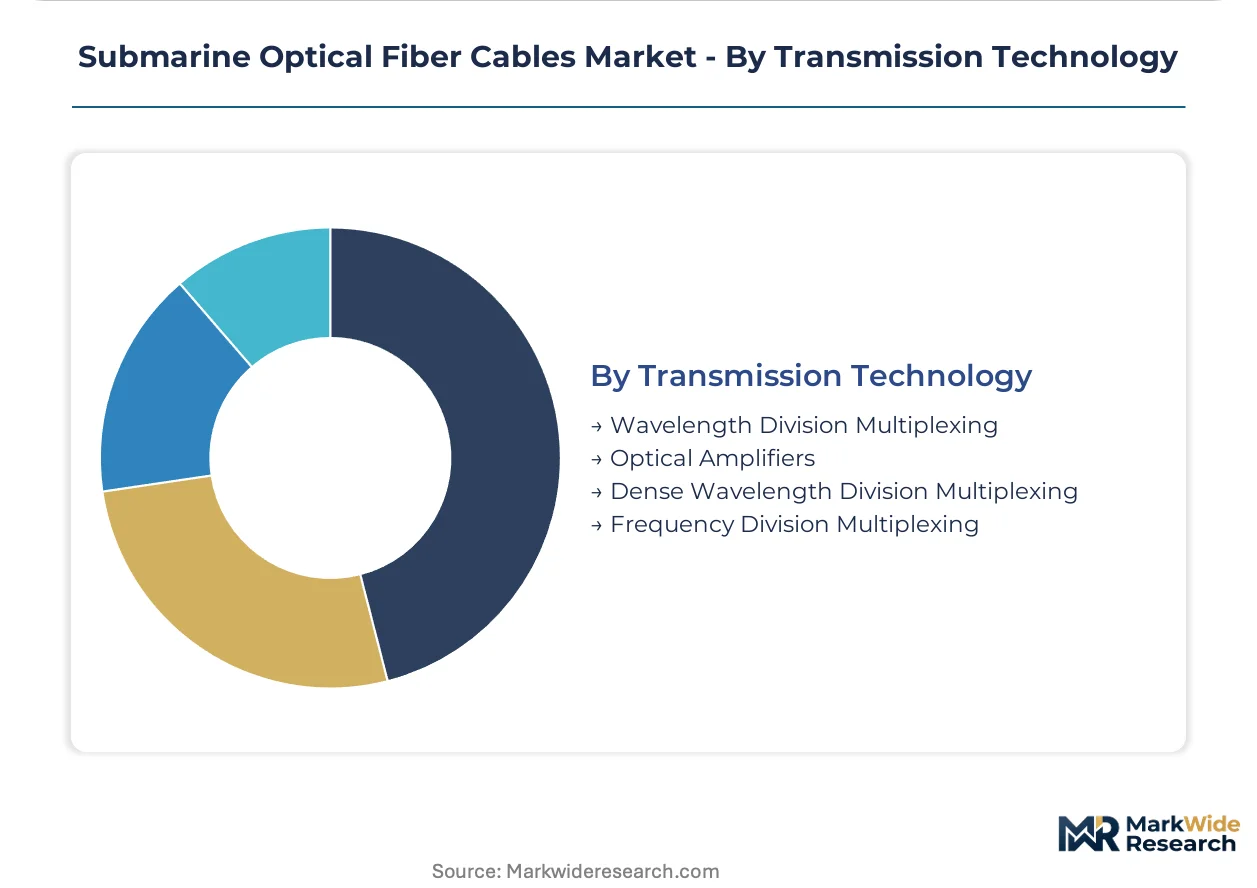
Transmission Technology:
Capacity multiplication without physical cable expansion depends on multiplexing sophistication and amplification density.
- Dense Wavelength Division Multiplexing:DWDM multiplies per-fiber capacity into terabit-scale traffic, automating route economics by decoupling bandwidth growth from vessel deployment. Space-division multiplexing through multi-core architectures extends this trajectory.
- Wavelength Division Multiplexing:Standard WDM serves legacy system interoperability requirements where landing station infrastructure dates back decades.
- Optical Amplifiers:Subsea repeater engineering specialization outpaces vocational training output, creating expertise scarcity.
- Frequency Division Multiplexing:FDM retains niche application in specific legacy corridor upgrades.
DWDM carries the preponderance of active traffic. Optical Amplifiers face the steepest expansion trajectory as repeater spacing extends on new routes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Japan command disproportionate influence over trans-Pacific cable deployment, while the United Kingdom anchors Atlantic corridor investment and emerging markets in Southeast Asia reshape shallow-water procurement patterns.
United States
Hyperscale data center operators in Virginia and Oregon drive dedicated fiber pair contracting for transpacific routes. The FCC enforces cable landing station licensing with biometric security mandates. Los Angeles anchors the primary Pacific cable landing cluster, where new stations consolidate to reduce multi-jurisdictional certification friction.
Japan
Cloud region synchronization between Tokyo and Osaka demands continuous subsea capacity augmentation. The MIC tightened cable station protocols requiring seismic isolation and access control standardization. Chiba Prefecture hosts concentrated landing infrastructure where manufacturers align repeater specifications with security requirements.
United Kingdom
Trans-Atlantic corridor traffic sustains deep-water deployment demand from London financial and cloud hubs. Coastal zone management frameworks govern landing permits under marine conservation designations. Cornwall anchors submarine cable landing concentration, with stations positioned to minimize fishing corridor conflicts.
Indonesia
Island network densification across the archipelago creates shallow-water deployment potential for regional connectivity meshes. National regulators coordinate seabed corridor governance with marine protected area boundaries. Batam and Jakarta anchor manufacturing and installation coordination for cost-engineered armored cable systems.
Vietnam
Underpenetrated coastal zones present expansion opportunities for fishing-protected shallow-water links. The government streamlines permitting for digital infrastructure under national broadband objectives. Ho Chi Minh City anchors submarine cable landing development, with routes engineered for burial in contested fishing zones.
Submarine Optical Fiber Cables Market Vendor Landscape
Top-tier vendors anchor integrated system supply, while specialized fabricators compete on cost-engineered regional deployments. The market structure concentrates around three operators controlling cable-laying vessel fleets, with tier-two players capturing shallow-water island networks through manufacturing efficiency. Strategic archetypes include integrated cable-repeater manufacturers, dedicated installation fleet operators, and cost-optimized shallow-water specialists. Dominant competitive moves encompass captive vessel capacity expansion and backward integration into repeater housing production.
Within the integrated manufacturing tier, Alcatel Submarine Networks and SubCom exemplify archetypes of end-to-end system control, while HMN Technologies occupies a position among cost-engineered deployment specialists. These three entities collectively represent the spectrum from premium deep-ocean bespoke systems to standardized regional connectivity meshes.
| Leading Market Players |
|---|
| Alcatel Submarine Networks |
| SubCom |
| HMN Technologies |
| NEC Corporation |
| Prysmian Group |
| Nexans |
| Global Marine Group |
| Corning |
| Hengtong Group |
| Others |
Supply Flow & Price Mechanics
Space-division multiplexing through multi-core fiber architectures is compressing per-terabit infrastructure costs while concentrating manufacturing scale among integrated cable-repeater producers in Japan and France. This technology transition simultaneously reduces unit economics for hyperscale buyers and elevates capital barriers for tier-two competitors without captive amplification expertise.
Pricing Analysis
The bundled-vs-unbundled service split separates traditional carrier capacity leases from direct fiber pair ownership contracts. Three-tier pricing structure across premium, standard, and economy levels differentiates by repeater spacing density and fiber pair count. Pricing pressure stems from hyperscale procurement compression as cloud buyers negotiate asset-specific terms rather than indefeasible rights of use. Regional island network operators exhibit highest price sensitivity, while trans-Pacific data center operators prioritize technical specifications over cost.
Supply Chain Analysis
Workforce availability constraints in Japanese and French manufacturing hubs limit repeater housing production expansion despite order backlogs. Cable manufacturing draws from copper conductor suppliers in Chile, polyethylene resin producers in the United States, and specialty steel wire armor fabricators in South Korea. Single-source vulnerability concentrates in cable-laying vessel fleets where three operators control global deployment capacity. Distribution runs through integrated system vendors for deep-ocean routes and regional fabricators for shallow-water island networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hyperscale demand for dedicated fiber pairs with custom repeater specifications favors integrated manufacturers over commodity assemblers.
For Market Incumbents: Hedge against vessel fleet concentration risk by securing long-term charter agreements or captive vessel construction slots before order backlogs extend. Alcatel Submarine Networks and SubCom should deepen backward integration into copper conductor drawing and polyethylene compounding to insulate margins from commodity volatility. Repeater engineering specialization creates defensive moats against cost-engineered shallow-water specialists.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Southeast Asian island networks offers white-space entry below integrated vendor minimum order thresholds. Target Indonesia, Vietnam, and Philippines regional connectivity meshes where armored shallow-water specifications permit standardized manufacturing without custom repeater development. Go-to-market through national broadband program procurement channels bypasses direct competition with tier-one system vendors.
For Investors and Strategic Acquirers: Valuations sit cheapest among cost-engineered shallow-water specialists with regional installation partnerships but without captive repeater capabilities. Long-term viability favors integrated cable-repeater manufacturers controlling both manufacturing and vessel deployment assets. Monitor hyperscale direct contracting velocity as the inflection signal—acceleration indicates sustained premium pricing power, while carrier re-intermediation suggests commoditization pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Cable-Laying Vessel Expansion | Captive fleet capacity secures project execution slots as trans-Pacific demand outstrips vessel availability. |
| Backward Integration into Repeater Housing | In-house amplification manufacturing compresses delivery timelines for complex deep-ocean routes. |
| Regional Island Network Partnerships | Shallow-water specialization in Indonesia and Philippines captures underpenetrated connectivity mesh demand. |
| Multi-Core Fiber Architecture Adoption | Space-division multiplexing decouples bandwidth growth from physical cable deployment frequency. |
| Biometric Security Certification Investment | Japan's MIC compliance opens trans-Pacific corridor access requiring seismic isolation and access control standards. |
Methodological Framework
Direct dialogue with cable system procurement executives at hyperscale data center operators, submarine network engineering directors at telecom carriers, FCC and Japan MIC regulatory affairs specialists, and cable-laying vessel fleet managers grounded qualitative findings. Secondary validation drew from FCC cable landing license filings, Japan MIC security protocol bulletins, International Cable Protection Committee seabed corridor databases, and customs records for copper conductor and polyethylene resin trade flows. Bottom-up project pipeline assessment triangulated against top-down hyperscale capex trajectory analysis.
Bottom-up volume modeling aggregated individual cable system announcements by fiber pair count and route distance, while top-down analysis calibrated against aggregate subsea bandwidth demand projections across the analysis window. Segmentation dimensions included product type, installation depth, end-user archetype, and transmission technology sophistication. CAGRs derived from slope-log regression on normalized capacity deployment curves, with repeater spacing extension rates and DWDM channel multiplication serving as industry-specific forecast inputs.
Caveats apply where marine protected area expansion, seabed mining corridor claims, or copper price volatility could materially shift the outlook. Forecasts embed assumptions about hyperscale direct contracting persistence and vessel fleet availability without contingency for carrier re-intermediation or fleet casualty events. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Fiber Optical Cable and Cable Assembly Products Market
Cables
Twisted Pair Cable Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Insulated Wire and Cable Market
Cables
US Cables Market
Cables
Network Cable Tester Market
Cables
Submarine Cabling Systems Market
Cables
Global Low Voltage Cable Market
Cables
Power Cable Accessories Market
Cables
Cable Material Market
Cables
Cable Tags Market
Cables
Fire Resistance Cable Market
Cables
North America HVAC Cables Market
Cables
Industrial Cable Reels Market
Cables
Cable Assembly Market
Cables
Cable Trunking Market