
 Cable Accessories Market | 2026-2036
Cable Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Accessories Market Intelligence
Market Context
China's cable accessory manufacturing base is narrowing its cost gap with European producers while scaling output for ultra-high-voltage direct current projects. Prysmian Group leverages integrated compound-to-cable operations across Italy and Brazil to sustain margin control on specialty joints. Nexans anchors its position through backward integration into EPR rubber compounding for offshore wind terminations. ABB competes via digital monitoring accessories that embed partial discharge sensors within medium-voltage connectors.
Technical Definition and Segment Structure
Cable accessories encompass termination kits, joints, connectors, and sealing systems engineered to maintain electrical continuity, mechanical protection, and environmental sealing across power and signal cables rated from low voltage through 500 kV. Silicone rubber cold-shrink sleeves dominate outdoor medium-voltage applications due to elastic recovery properties eliminating heat-gun installation requirements. Connectors and insulators command the largest product-type revenue pool, while renewable energy applications are outpacing telecommunications in growth velocity as offshore wind arrays multiply conductor count per turbine. Polyethylene formulations gain share in submarine cable joints where water-tree resistance determines service life, though metal components retain pricing power in high-current busbar connections.
Regulatory Environment
China's GB standards and MIIT certification requirements shape product entry for foreign accessory suppliers, while India's BIS mandatory registration scheme enforces thermal cycling test protocols for 11 kV and 33 kV joints. The EU F-Gas Regulation and REACH restrictions on halogenated flame retardants are redirecting R&D spending toward non-halogen insulation compounds. Stakeholders must monitor how carbon-border adjustment mechanisms and evolving national content rules for grid infrastructure reshape sourcing economics for cross-linked polymer feedstocks and cast-resin housings.
Market Dynamics
Grid operators are consolidating procurement around pre-qualified termination kits that bundle installation tooling with silicone rubber sleeves, compressing vendor margins while elevating technical service contracts as the primary profit pool.
Growth Catalysts
- India's rural electrification directives:The Central Electricity Authority mandates universal household connectivity, driving bulk orders for 11 kV cold-shrink joints and heat-shrinkable tubing across state distribution companies.
- EPR rubber compounding advances:Ethylene propylene rubber formulations now withstand 150°C continuous operating temperatures, opening medium-voltage applications previously reserved for oil-filled paper insulation.
- Offshore wind array multiplication:Each turbine installation requires 36-48 conductor terminations, creating sustained demand pull for submarine-rated joints with water-tree-resistant polyethylene barriers.
Market Restraints
- Copper price volatility:LME copper fluctuations above $9,000 per tonne directly compress margins on busbar connector assemblies where metal content exceeds 60% of material cost.
- Chinese compound supply concentration:Four domestic producers control 70% of cross-linked polyethylene feedstock for high-voltage applications, creating single-source vulnerability for European joint manufacturers.
- REACH halogen restrictions:ECHA classification of brominated flame retardants as substances of very high concern forces reformulation of indoor termination housings at 15-20% R&D cost inflation.
Strategic Opportunities
- Brazil's transmission auction pipeline:ANEEL's 2024-2028 program includes 12,000 km of new 500 kV lines, requiring GIS terminations and gas-insulated bus duct accessories absent domestic production capacity.
- Digital monitoring convergence:Embedding partial discharge sensors within medium-voltage connectors creates recurring revenue streams through predictive maintenance subscriptions.
- EU F-Gas phase-down:The 2030 ban on SF6 in new switchgear installations drives demand for vacuum interrupter terminations and dry-type cable penetrations in substation retrofits.
Industry Challenges
- Field technician certification gaps:Proper installation of 220 kV composite terminations requires 400+ hours of supervised training, yet utility workforce pipelines produce fewer than 200 qualified installers annually across OECD markets.
- Legacy PVC infrastructure interoperability:Cold-shrink silicone sleeves cannot achieve reliable sealing on aged PVC-insulated cables without complete conductor replacement, complicating urban retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Accessories Market |
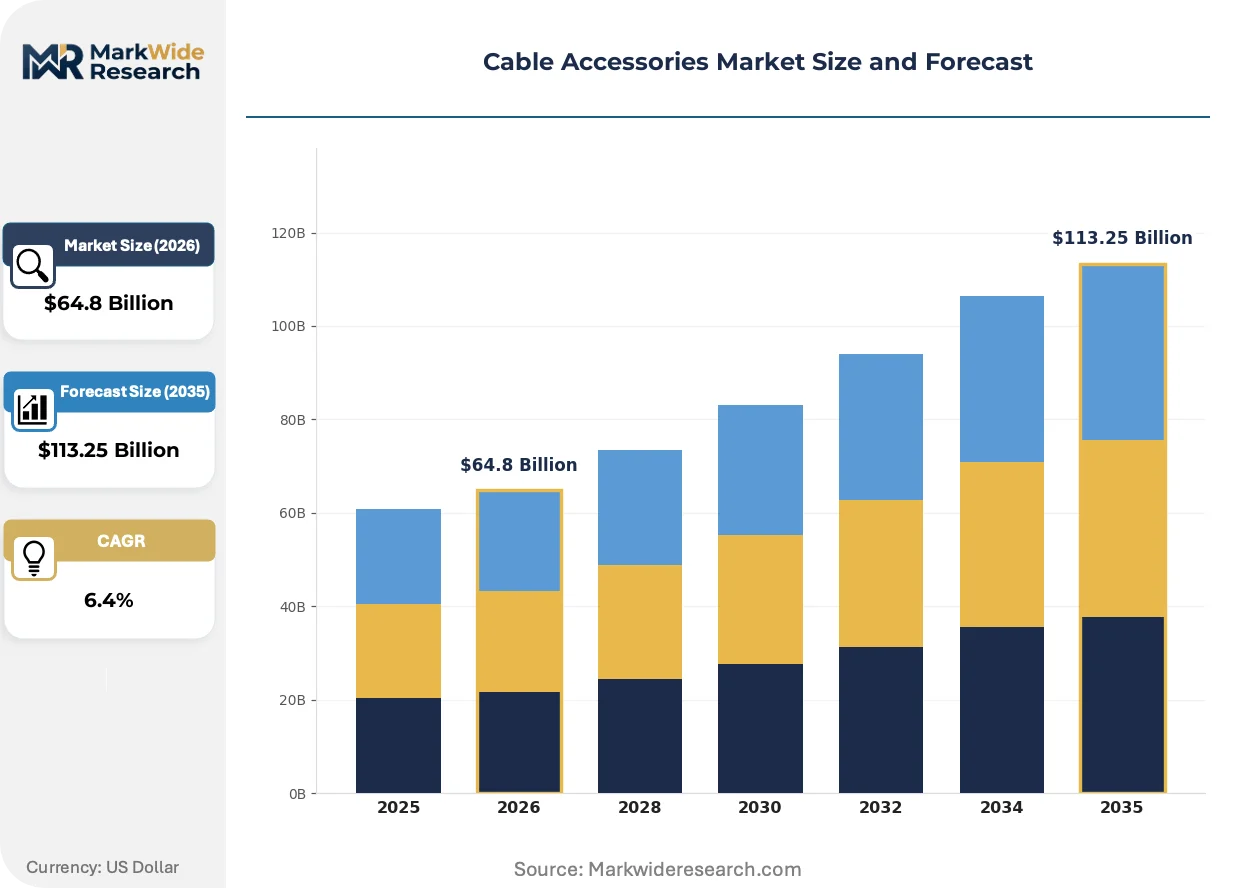
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $113.25 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Connectors, Insulators, Heat Shrink Tubing, Cable Glands Application: Telecommunications, Industrial Automation, Renewable Energy, Consumer Electronics Material: Rubber, Polyvinyl Chloride, Polyethylene, Metal End User: Telecom, Automotive, Energy, Construction |
| Companies Covered | Prysmian Group, Nexans, ABB, NKT A/S, Sumitomo Electric Industries, LS Cable & System, Furukawa Electric, Elsewedy Electric, Dubai Cable Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Accessories Market Strategic Shifts & Innovations
Material science breakthroughs and installation-method simplification are compressing project timelines while regulatory chemistry restrictions force compound reformulation across the supplier base.
Silicone rubber cold-shrink technology eliminates heat-gun installation requirements through elastic recovery properties activated at room temperature. Distribution utilities in Germany and Australia now specify cold-shrink exclusively for outdoor 33 kV applications, cutting field installation time from 90 minutes to 12 minutes per termination. Heat-shrink tubing with adhesive lining is rendering obsolete for medium-voltage outdoor exposure where thermal cycling degrades bond integrity.
REACH restrictions on halogenated flame retardants redirect R&D spending toward magnesium hydroxide-filled polyolefin compounds. Compounders in Italy and Japan are scaling non-halogen insulation systems for tunnel and subway applications where smoke toxicity regulations are strictest. High-rise building cable penetrations in London and Dubai now require third-party certification to EN 50399 reaction-to-fire protocols, favoring suppliers with in-house testing laboratories.
Utility procurement departments are unbundling installation services from material supply, creating separate contract streams for termination kits and supervised field termination. State-grid operators in China and regional power companies in Spain now tender these elements independently, eroding traditional full-service margins for integrated vendors. This pattern is most pronounced in offshore wind projects where specialized marine contractors hold installation certifications that cable accessory manufacturers cannot replicate.
Cable Accessories Market Segmentation
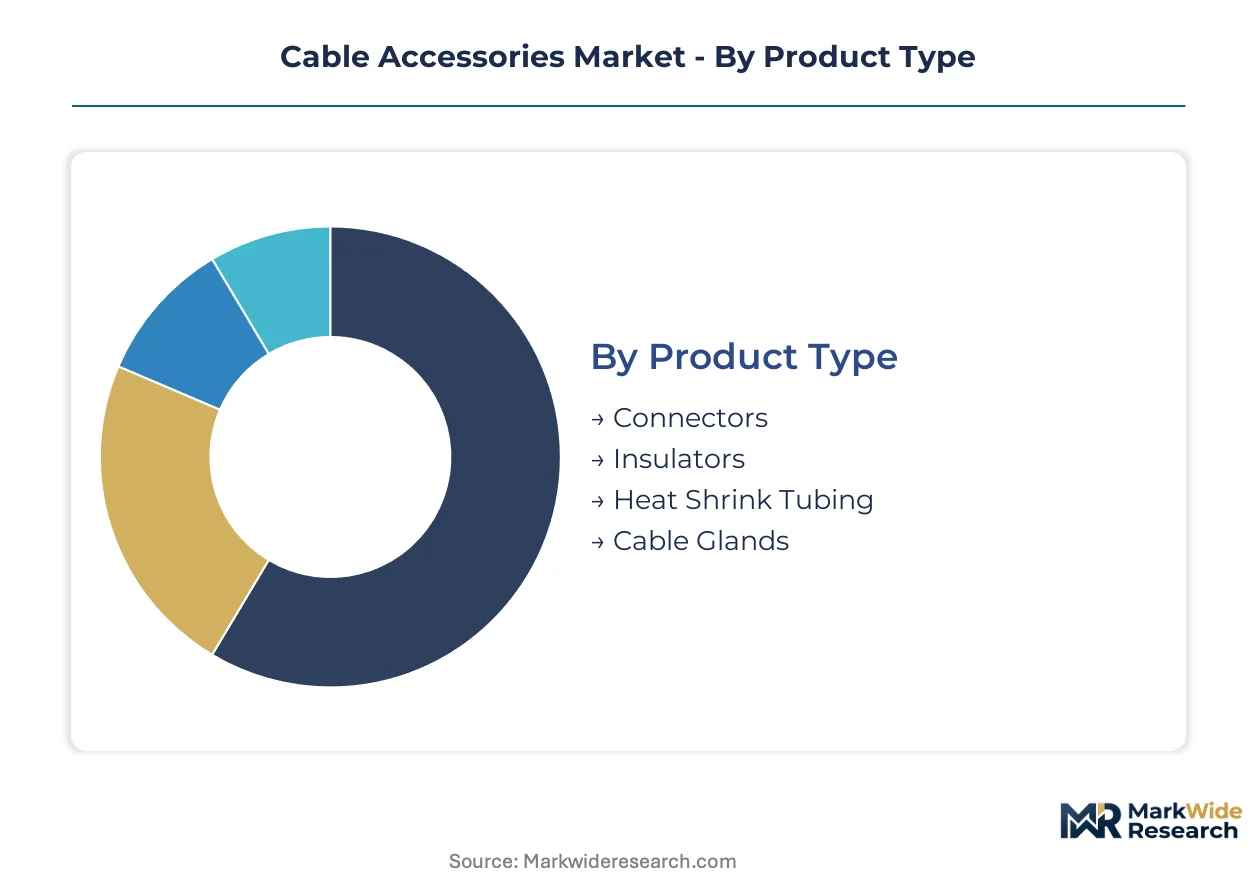
Cable accessories span divergent technical specifications across voltage classes and environmental exposures, forcing suppliers to maintain compound formulation flexibility and installation training networks. Segmentation by product type, application, material, and end user reveals where margin pools concentrate versus where volume commoditization pressures dominate procurement negotiations.
Product Type:
After-sales service intensity varies dramatically across accessory categories, with field-terminated products requiring supervised installation certification while pre-fabricated components shift margin capture toward logistics and inventory management.
- Connectors:Engineered interfaces for conductor joining across copper and aluminum metallurgies, with crimped, bolted, and compression variants matched to current ratings and thermal cycling profiles. Demand clusters in India's state distribution companies executing rural electrification directives, where 11 kV busbar connectors face procurement volume spikes but price caps compress supplier margins.
- Insulators:Dielectric barriers and support structures manufactured from porcelain, glass, or polymer composites, rated for mechanical load and pollution severity per IEC 60815 classifications. Offshore wind arrays in the North Sea and Baltic Sea drive specification for composite insulators with hydrophobic silicone rubber housings, where salt-fog endurance determines replacement intervals and warranty exposure.
- Heat Shrink Tubing:Cross-linked polyolefin sleeves with adhesive lining for environmental sealing, activated via propane torch or electric heat gun in field conditions. Brazil's transmission auction pipeline favors cold-shrink alternatives for 500 kV GIS terminations where installation speed reduces outage windows.
- Cable Glands:Mechanical sealing devices for cable entry into enclosures, with brass, stainless steel, and nylon variants rated for IP66/67 and explosion-proof certifications. European tunnel projects under EN 50399 reaction-to-fire protocols specify nickel-plated brass with low-smoke zero-halogen cable inserts.
By volume, connectors lead. By growth pace, insulators for renewable energy are ahead.
Application:
Cost tier stratification separates mission-critical infrastructure applications with extended warranty requirements from consumer-facing segments where price sensitivity dominates supplier selection.
- Telecommunications:Fiber optic and copper network accessories for central office, outside plant, and data center interconnects, with fusion splice protectors and weatherproof enclosures as core categories. China's MIIT certification requirements for 5G base station deployments enforce GB standard compliance on foreign suppliers, creating qualification barriers for European and Japanese manufacturers.
- Industrial Automation:Control cable terminations for programmable logic controllers, motor drives, and sensor networks, with M12 and M8 circular connectors dominating factory floor implementations. German automotive OEMs specify IP67-rated overmolded assemblies with predictive maintenance compatibility, elevating technical service contracts over component pricing.
- Renewable Energy:Photovoltaic junction boxes, wind turbine slip rings, and submarine cable joints for offshore array interconnection. Each turbine installation requires 36-48 conductor terminations, with water-tree-resistant polyethylene barriers specified for 33 kV array cables in Taiwan Strait projects.
- Consumer Electronics:USB-C, HDMI, and power adapter interfaces for mobile devices, laptops, and home appliances, with surface-mount and through-hole PCB mounting variants. India's BIS mandatory registration scheme for electronics accessories enforces thermal cycling test protocols that disqualify uncertified imports.
By volume, telecommunications leads. By expansion trajectory, renewable energy is climbing the fastest.
Material:
Supply concentration for polymer feedstocks shapes regional manufacturing economics, with cross-linked polyethylene and silicone rubber compound availability determining joint production location decisions.
- Rubber:EPR and silicone elastomer formulations for cold-shrink sleeves and molded stress cones, with elastic recovery properties enabling tool-free installation. Ethylene propylene rubber now withstands 150°C continuous operating temperatures, displacing oil-filled paper insulation in German medium-voltage retrofits.
- Polyvinyl Chloride:Legacy insulation and jacketing material for low-voltage building wire, with plasticizer migration and thermal degradation driving replacement schedules in aged urban infrastructure. Cold-shrink silicone sleeves cannot achieve reliable sealing on aged PVC-insulated cables without complete conductor replacement, complicating London and Dubai high-rise retrofit timelines.
- Polyethylene:Cross-linked and thermoplastic variants for medium-voltage insulation and submarine cable joints, with water-tree resistance determining service life in wet environments. Four Chinese domestic producers control 70% of high-voltage cross-linked polyethylene feedstock, creating single-source vulnerability for European joint manufacturers.
- Metal:Copper and aluminum alloys for busbar connectors, cable glands, and grounding hardware, with LME price volatility above $9,000 per tonne directly compressing margins on assemblies where metal content exceeds 60% of material cost.
By volume, metal components lead. By technology transition pace, polyethylene formulations are gaining share fastest.
End User:
Customer procurement maturity separates centralized utility buyers with pre-qualification registries from fragmented construction contractors where brand recognition and distributor availability determine specification.
- Telecom:National operators and tower companies deploying fiber-to-the-home and 5G infrastructure, with bulk procurement of splice closures and weatherproofing kits. India's Department of Telecommunications mandates domestic value-add requirements for network equipment, redirecting accessory sourcing to local joint ventures.
- Automotive:Wire harness manufacturers and EV battery pack assemblers specifying high-voltage connector systems rated for 800V architectures and electromagnetic compatibility. European OEMs enforce IATF 16949 quality system certification on tier-one suppliers, with PPAP submission requirements extending qualification cycles.
- Energy:Transmission utilities, distribution companies, and independent power producers procuring termination kits and joints for substation and line construction. Brazil's ANEEL transmission auction program includes 12,000 km of new 500 kV lines requiring GIS terminations and gas-insulated bus duct accessories absent domestic production capacity.
- Construction:Electrical contractors and building developers specifying cable management and fire-stopping systems for commercial and residential projects. Dubai's civil defense authority mandates third-party certification to BS 476 and EN 1363 fire resistance protocols for high-rise cable penetrations.
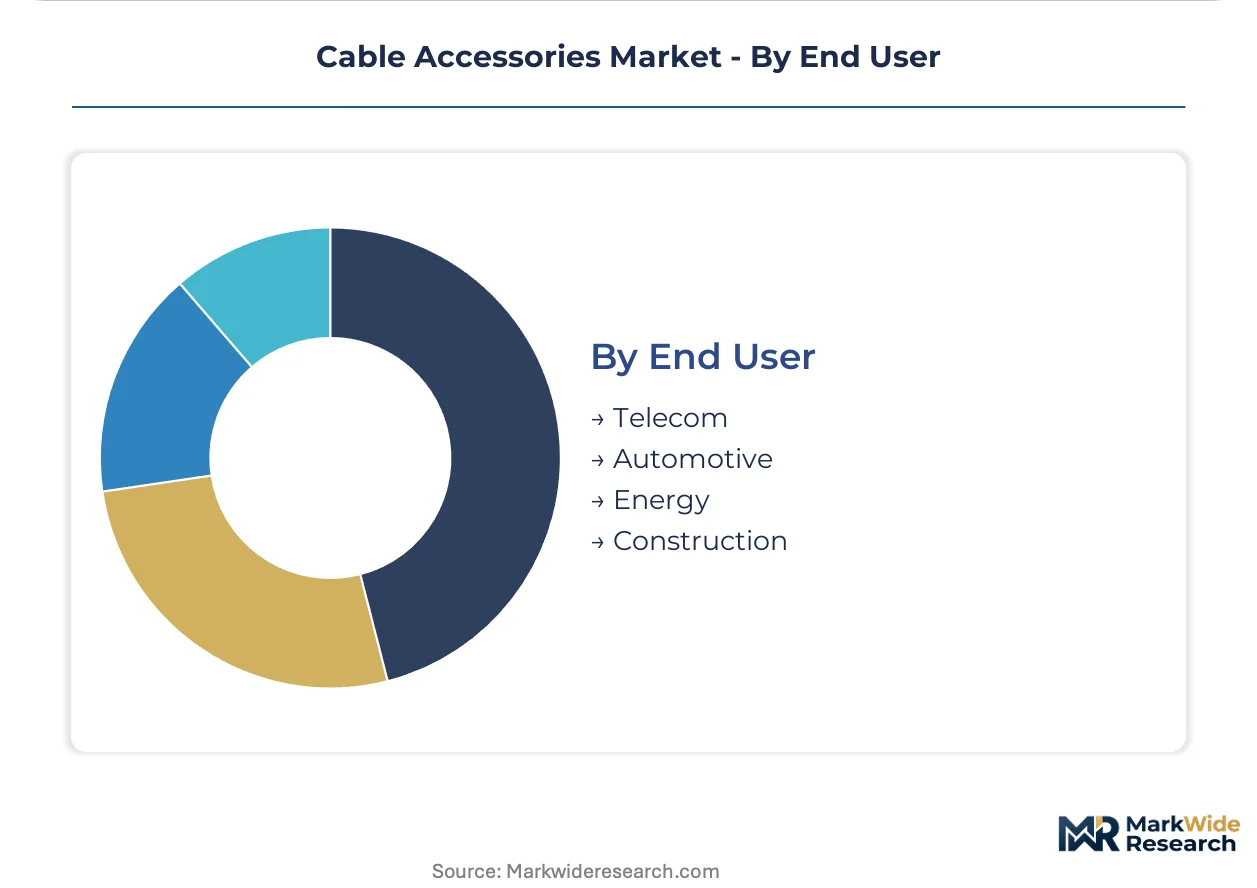
By volume, energy sector procurement leads. By specification complexity, automotive requirements are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT certification requirements anchor procurement patterns across the dominant manufacturing geography. State-led transmission build-outs in China and rural electrification mandates in India concentrate demand pull for medium-voltage termination systems. Regulatory fragmentation across national grid codes forces suppliers to maintain compound formulation flexibility by geography.
China
Ultra-high-voltage direct current projects drive procurement volumes for 500 kV joints and GIS terminations. GB standards and MIIT certification requirements shape product entry protocols for foreign accessory suppliers. State Grid Corporation tenders concentrate manufacturing activity in Jiangsu and Shandong provinces, where four domestic producers control the majority of cross-linked polyethylene feedstock supply.
India
The Central Electricity Authority mandates universal household connectivity, generating bulk orders for 11 kV cold-shrink joints across state distribution companies. BIS mandatory registration enforces thermal cycling test protocols for 33 kV joint assemblies. Manufacturing clusters in Maharashtra and Gujarat produce termination kits for rural electrification programs under central power ministry directives.
Germany
Distribution utilities specify cold-shrink silicone technology exclusively for outdoor 33 kV applications, cutting field installation times substantially. REACH restrictions on halogenated flame retardants redirect R&D spending toward magnesium hydroxide-filled polyolefin compounds. Industrial concentration in Bavaria and North Rhine-Westphalia hosts compounders scaling non-halogen insulation systems for tunnel and subway deployments.
Brazil
ANEEL's transmission auction program includes 12,000 km of new 500 kV lines requiring GIS terminations and gas-insulated bus duct accessories. Domestic production capacity gaps create import dependency for high-voltage joint assemblies. Manufacturing activity clusters in São Paulo and Minas Gerais, where regional power companies tender installation services independently from material supply.
United States
FERC grid modernization incentives accelerate procurement of medium-voltage termination kits with embedded partial discharge monitoring. Copper price volatility above $9,000 per tonne compresses margins on busbar connector assemblies where metal content dominates material cost. Utility procurement consolidation in Texas and California favors pre-qualified termination kits bundling installation tooling with silicone rubber sleeves.
Cable Accessories Market Key Industry Players
Capability concentration sits with integrated compound-to-cable operators; scale advantage sits with diversified electrical equipment conglomerates. The supplier base organizes around three strategic archetypes: integrated polymer compounders controlling formulation IP, specialized termination manufacturers with installation certification networks, and diversified industrial groups leveraging cross-selling into substation automation. Competitive moves center on backward integration into EPR rubber compounding and geographic expansion through transmission auction participation in Brazil and India.
Among European-integrated operators, Prysmian Group and Nexans exemplify the compound-to-cable archetype, anchoring positions through captive control over polymer formulation and joint design. ABB occupies a distinct tier as a diversified industrial technology group, representing the digital monitoring convergence vector where sensor-embedded connectors create recurring revenue streams. These three entities illustrate the structural split between material-science specialists and systems-integrators competing for utility procurement contracts.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| ABB |
| NKT A/S |
| Sumitomo Electric Industries |
| LS Cable & System |
| Furukawa Electric |
| Elsewedy Electric |
| Dubai Cable Company |
| Others |
Cost & Logistics Intelligence
Overcapacity in China's cross-linked polyethylene compound sector is compressing margin structures for joint manufacturers while simultaneously accelerating price competition in medium-voltage termination kits. This utilization dynamic forces European suppliers to absorb feedstock cost volatility or cede volume to integrated domestic producers in Jiangsu and Shandong provinces.
Pricing Analysis
Geographic price spreads of 25-40% separate German utility procurement from Indian state distribution company tenders for equivalent 33 kV cold-shrink joints. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling rather than raw material variance. Pricing pressure stems from Chinese compounders narrowing the cost gap with European producers through state-backed capacity additions. State-grid operators in China exhibit lowest price sensitivity due to pre-qualification registries, while Brazilian regional power companies face acute budget constraints under ANEEL auction terms.
Supply Chain Analysis
Export control regimes on advanced polymer compounding equipment limit technology transfer to emerging joint manufacturers in Brazil and India, preserving formulation IP concentration among Italian and Japanese compounders. Supply concentrates in China for cross-linked polyethylene feedstock, Germany for EPR rubber formulations, and Italy for silicone cold-shrink sleeves. Raw material dependencies include LME copper for busbar connectors, magnesium hydroxide for non-halogen flame retardants, and water-tree-resistant polyethylene for submarine applications. Single-source vulnerability runs through the four Chinese domestic producers controlling high-voltage compound supply. Distribution runs through authorized distributor networks for utility procurement and direct OEM supply agreements for automotive and renewable energy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a service-attach opportunity justified by technical service contracts expanding faster than hardware margins as procurement unbundling accelerates across offshore wind and utility retrofit segments.
For Market Incumbents: Pre-empt margin compression from Chinese compounders by securing captive EPR rubber supply through backward integration into compounding operations in Bavaria or North Rhine-Westphalia. Defend utility relationships by embedding partial discharge sensors within medium-voltage connectors to create recurring predictive maintenance revenue streams that offset hardware commoditization. For New Entrants and Emerging Players: Brazil's transmission auction pipeline represents the most penetrable white-space target, given domestic production gaps for 500 kV GIS terminations and gas-insulated bus duct accessories. ANEEL's program creates entry opportunity through joint ventures with established marine contractors holding installation certifications. Target technical service contracts as the primary go-to-market angle, unbundling supervised field termination from material supply to bypass entrenched vendor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among compound-to-cable integrated operators with captive formulation IP and installation certification networks. Long-term viability over a multi-year horizon favors targets with backward integration into silicone rubber or EPR compounding rather than pure-play termination manufacturers exposed to feedstock volatility. Monitor Brazil's ANEEL auction award velocity and India's rural electrification disbursement rates as inflection indicators for demand pull timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPR Compounding | Captive supply of 150°C-rated formulations secures margin control for offshore wind terminations. |
| Digital Monitoring Convergence | Embedding partial discharge sensors within medium-voltage connectors creates predictive maintenance subscription revenue. |
| Brazil Transmission Auction Participation | ANEEL's 12,000 km program opens import-dependent demand for GIS terminations absent domestic capacity. |
| Non-Halogen Compound Reformulation | REACH restrictions on brominated flame retardants redirect R&D toward magnesium hydroxide-filled polyolefin systems. |
| Installation Certification Network Expansion | Field technician training pipelines address 400-hour supervised requirements for 220 kV composite terminations. |
Research Approach
Initial hypotheses were tested against primary input from utility procurement officers, EPC contractors, polymer compounders, and offshore wind project developers and refined through secondary validation. Primary fieldwork encompassed structured interviews with transmission planning directors at state-grid operators in China and regional power companies in Spain, alongside technical discussions with EPR rubber formulators in Germany and silicone compounders in Italy. Secondary sources included IEC standard documentation, BIS mandatory registration filings, ANEEL auction disclosures, and customs trade data on cross-linked polyethylene feedstock flows. Bottom-up demand modeling triangulated against top-down market sizing from cable installation project databases.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation by voltage class, material formulation, application environment, and end-user procurement maturity. CAGRs were derived from installation volume projections weighted by unit value trends in termination kits and joint assemblies. Industry-specific forecast inputs incorporated offshore wind turbine deployment pipelines and grid modernization disbursement schedules from FERC and EU infrastructure programs.
Practitioners should monitor copper price volatility above LME threshold levels, REACH regulatory expansion to additional halogenated compounds, and Chinese compound capacity utilization rates for early signals of margin structure shifts. Forecasts reflect assumptions on continued state-led transmission build-outs and rural electrification program funding continuity. Material shifts in Brazil's ANEEL auction timing or India's BIS certification enforcement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Global Industrial Automation Cable Market
Cables
FFC/FPC Jumper Cables Market
Cables
North America Coaxial Cable Market
Cables
Cable Fault Locator Market
Cables
Usb Data Cable Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
LED Cable Market
Cables
UK Cables Market
Cables
Cable Tray Market
Cables
Single Core Cables Market
Cables
Audio and Video Cables Market
Cables
Industrial Cable Reels Market
Cables
Solar Cable Market
Cables
Global Low Voltage Cable Market
Cables
Data Center Wire and Cable Market