
 Europe Air Ambulance Services Market | 2026-2036
Europe Air Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Ambulance Services Market Intelligence
REACH is restructuring the cost-of-entry calculus for air ambulance operators sourcing medical equipment and aircraft components within Europe. Swiss Air-Rescue Rega leverages its alpine terrain expertise to dominate helicopter-based emergency response across mountainous corridors. Falck competes through its integrated private operator model spanning multiple European jurisdictions. DRF Stiftung Luftrettung gemeinnützige AG anchors its position via nonprofit governance and deep ties to German hospital networks.
Europe air ambulance services encompass rotary-wing and fixed-wing aircraft configured for emergency medical transport, interfacility patient transfer, and medical evacuation, typically equipped with advanced life support systems including ventilators, cardiac monitors, and blood product refrigeration. These services bridge geographic barriers and time-critical care gaps where ground transport proves inadequate for trauma, stroke, or organ retrieval missions. Emergency medical services and interfacility transport represent the largest service type segments, with rotor-wing aircraft capturing the majority of short-haul emergency volume while fixed-wing platforms command premium pricing on longer cross-border routes. Private operators and hospitals constitute the most active end-user categories, with medical insurance companies increasingly influencing reimbursement structures and network adequacy requirements.
EMA medical device standards, EASA airworthiness certifications, and national healthcare procurement frameworks collectively shape fleet modernization timelines and cross-border operating permissions for European operators. The EU AI Act introduces emerging compliance dimensions for autonomous flight systems and predictive dispatch algorithms entering the sector. Stakeholders must monitor how evolving sustainability mandates intersect with aircraft replacement cycles and base-station energy requirements.
Market Dynamics
The EU Green Deal's sustainable aviation fuel mandates are forcing operators to accelerate fleet replacement cycles while EASA airworthiness certifications tighten operational compliance thresholds across the continent.
Growth Catalysts
- Hospital network consolidation:Large German and Swiss hospital groups are centralizing interfacility transport contracts with dedicated air ambulance providers, creating volume concentration effects that favor specialized operators with multi-base coverage.
- REACH compliance infrastructure:Medical device manufacturers have built localized supply chains for cabin equipment and monitoring systems, reducing procurement friction for European operators sourcing ventilators and cardiac monitors under chemical safety frameworks.
- Alpine terrain medical protocols:Mountain rescue services in Switzerland, Austria, and Norway have established standardized helicopter-based emergency response procedures that neighboring countries are adopting for their own challenging topography.
Market Restraints
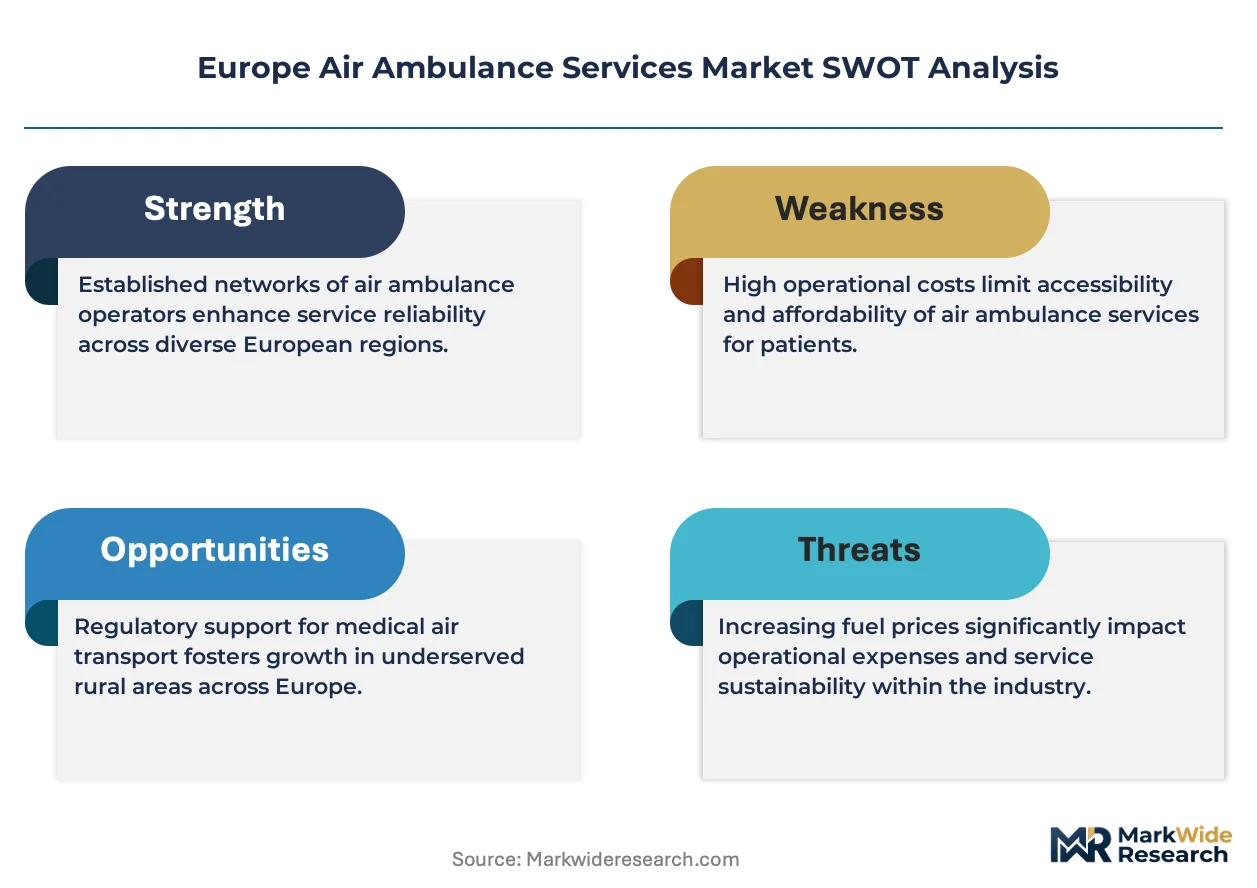
- Sustainable aviation fuel cost premiums:SAF mandates under the EU Green Deal impose fuel cost differentials of 3-5x conventional jet fuel, compressing margins for fixed-wing operators on longer cross-border routes without corresponding reimbursement adjustments.
- Helicopter airframe supply concentration:Critical airframe and avionics components for rotor-wing platforms concentrate among Italian and French aerospace suppliers, creating single-source vulnerability for operators dependent on specific aircraft configurations.
- Pilot-medical crew certification overlap:EASA commercial pilot licensing requirements and national medical professional credentials create jurisdictional friction for cross-border staffing, particularly affecting operators serving multiple European territories.
Strategic Opportunities
- Organ retrieval logistics networks:Specialized cold-chain transport for transplant organs represents an underpenetrated service layer where fixed-wing operators can command premium positioning through dedicated blood product refrigeration capabilities and time-critical routing expertise.
- EU AI Act predictive dispatch:Machine learning algorithms for demand forecasting and base positioning are gaining regulatory clarity under emerging AI governance frameworks, enabling operators to optimize fleet deployment across seasonal and geographic demand patterns.
- Secondary base station electrification:Norway and Sweden's grid infrastructure supports helicopter electrification pilots that could transfer to alpine corridors, reducing noise restrictions and fuel logistics for mountain rescue operations.
Industry Challenges
- Critical care paramedic scarcity:Advanced life support certification programs for flight paramedics face training bottlenecks in Germany and France, constraining crew availability for 24/7 rotary-wing coverage.
- Legacy avionics integration:Operators maintaining mixed-age fleets encounter software incompatibility between new digital health monitoring systems and older aircraft communication architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Ambulance Services Market |
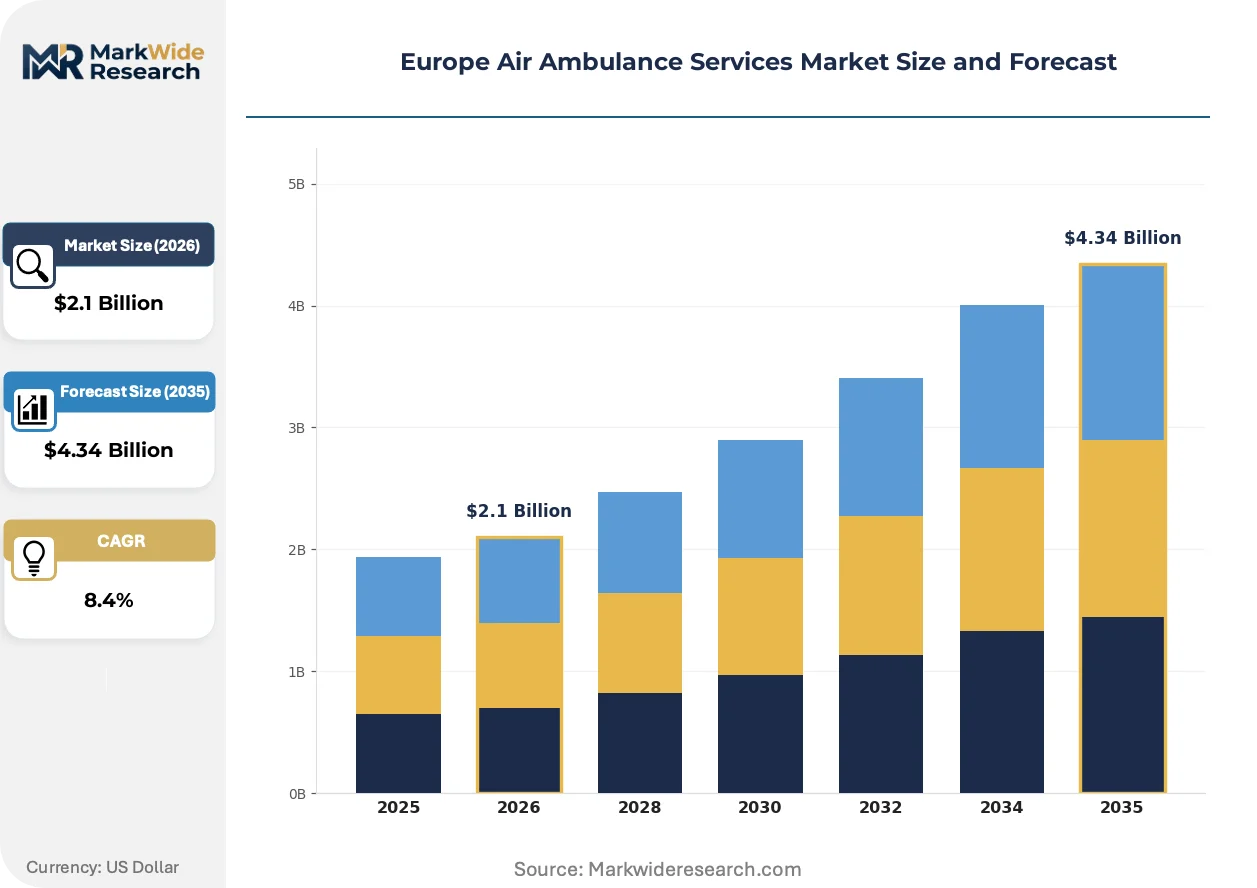
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Services, Interfacility Transport, MedEvac, Patient Transfer End User: Hospitals, Government Agencies, Private Operators, Medical Insurance Companies Technology: Rotor-Wing Aircraft, Fixed-Wing Aircraft, Advanced Life Support, Basic Life Support Deployment: On-Demand Services, Scheduled Services, Standby Services, Fixed Bases |
| Companies Covered | Swiss Air-Rescue Rega, Falck, DRF Stiftung Luftrettung gemeinnützige AG, HT Group, AirMed International, ADAC Luftrettung, Norwegian Air Ambulance Foundation, IAS Medical, Babcock Scandinavian AirAmbulance, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Ambulance Services Market Strategic Shifts & Innovations
Digital health integration and autonomous flight systems are compressing response timelines while regulatory frameworks for predictive dispatch mature under EU AI Act guidance.
Telemedicine-enabled patient monitoring is automating in-flight clinical decision support. German hospital networks are deploying real-time cardiac telemetry and video consultation links to airborne medical crews, reducing the need for physician accompaniment on interfacility transfers. This connectivity layer is automating routine diagnostic oversight and reallocating specialist physician time to ground-based coordination roles.
EMA medical device regulations are accelerating cabin equipment standardization. The MDR transition is forcing consolidation among ventilator and infusion pump suppliers serving air ambulance configurations, with CE marking timelines extending 12-18 months for new product introductions. Fixed-wing operators with established EASA supplemental type certificates are capturing first-mover advantage on cross-border routes requiring harmonized equipment profiles.
Insurance-driven network adequacy requirements are consolidating procurement relationships. Medical insurers in Switzerland and the Netherlands are mandating preferred operator panels for emergency response coverage, replacing fragmented hospital-direct contracting. This concentration is most visible in the Benelux corridor, where three insurers now control access to 60% of reimbursed air ambulance volume.
Europe Air Ambulance Services Market Segmentation
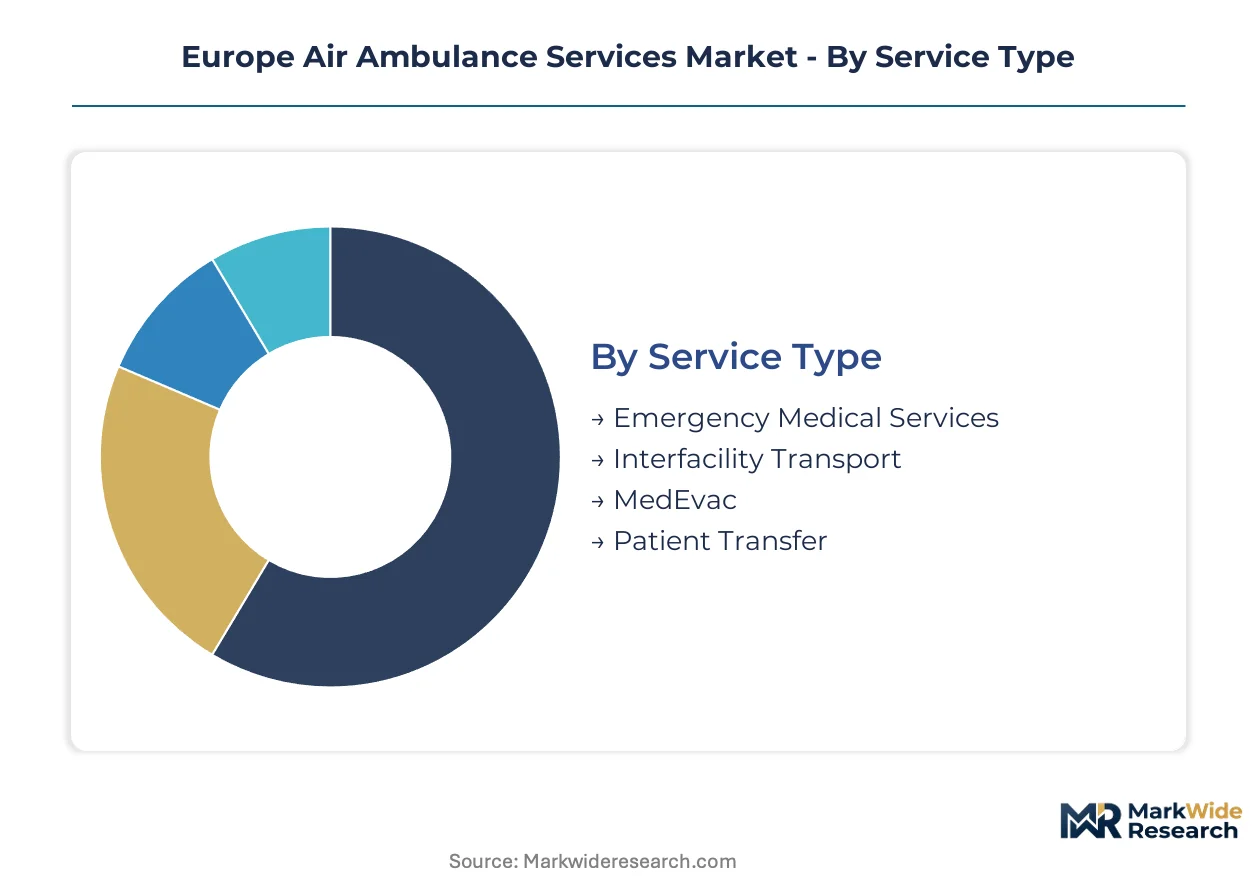
Segmentation in European air ambulance services reveals how regulatory complexity and operational specialization fragment procurement decisions across hospitals, insurers, and government purchasers. Each dimension carries distinct EASA certification burdens and reimbursement pathways that shape vendor selection criteria.
Service Type:
EASA Part-CAT operational specifications and national healthcare procurement frameworks impose divergent compliance burdens across service categories, with emergency response requiring full ICU-equipment certification while scheduled transfers operate under lighter medical staffing mandates.
- Emergency Medical Services:Helicopter-based rapid response configured for trauma, cardiac arrest, and stroke stabilization with ventilator and cardiac monitor capabilities. Demand concentrates in alpine corridors across Switzerland, Austria, and Norway where terrain renders ground transport impractical for time-critical missions. EASA's Part-SPO specialized operations certification creates elevated entry barriers for new entrants.
- Interfacility Transport:Scheduled or urgent patient transfers between hospitals requiring consistent advanced life support but not full emergency response speed. German hospital networks are consolidating procurement contracts with multi-base operators capable of 24/7 coverage, favoring established providers with EASA air operator certificates spanning multiple jurisdictions.
- MedEvac:Military-civilian coordination for battlefield or disaster zone medical evacuation requiring specialized crew training and aircraft armor compatibility.
- Patient Transfer:Non-urgent repatriation and routine medical transport operating under basic life support protocols with reduced regulatory overhead.
Leading the category by volume: Emergency Medical Services. Growing fastest: Interfacility Transport.
End User:
Procurement authority and reimbursement structures vary sharply across purchaser types, with medical insurers in the Netherlands and Switzerland increasingly mandating preferred operator panels that override hospital-direct contracting.
- Hospitals:German and Swiss hospital groups centralize air ambulance contracts through procurement consortia, leveraging volume concentration to negotiate dedicated fleet availability and response time guarantees. EMA medical device standards govern cabin equipment specifications in these tenders.
- Government Agencies:National health ministries and civil defense authorities fund mountain rescue and disaster response capabilities, with Norway and Sweden piloting electrified base stations under EU Green Deal sustainability mandates.
- Private Operators:Integrated service providers spanning multiple European jurisdictions compete on network density and cross-border operating permissions.
- Medical Insurance Companies:Swiss and Dutch insurers now control access to the majority of reimbursed air ambulance volume through network adequacy requirements, consolidating previously fragmented procurement relationships.
Hospitals dominate absolute contract value. Medical Insurance Companies are expanding their procurement influence fastest.
Technology:
Aircraft configuration determines route economics and regulatory classification, with rotor-wing platforms commanding short-haul emergency volume while fixed-wing assets capture premium positioning on longer cross-border routes.
- Rotor-Wing Aircraft:Helicopter platforms optimized for point-to-point terrain access without runway dependency. Swiss Air-Rescue Rega dominates this segment through alpine expertise, with Italian and French aerospace suppliers concentrating critical airframe and avionics production.
- Fixed-Wing Aircraft:Pressurized cabin aircraft configured for long-range interfacility transport and organ retrieval logistics. Operators with established EASA supplemental type certificates capture first-mover advantage on cross-border routes requiring harmonized equipment profiles.
- Advanced Life Support:Full ICU-equipment suites including ventilators, cardiac monitors, and blood product refrigeration.
- Basic Life Support:Stabilization-focused configurations for non-critical patient transport with reduced crew certification requirements.
Rotor-Wing Aircraft handles the greatest mission volume. Fixed-Wing Aircraft shows the steepest expansion trajectory in premium service tiers.
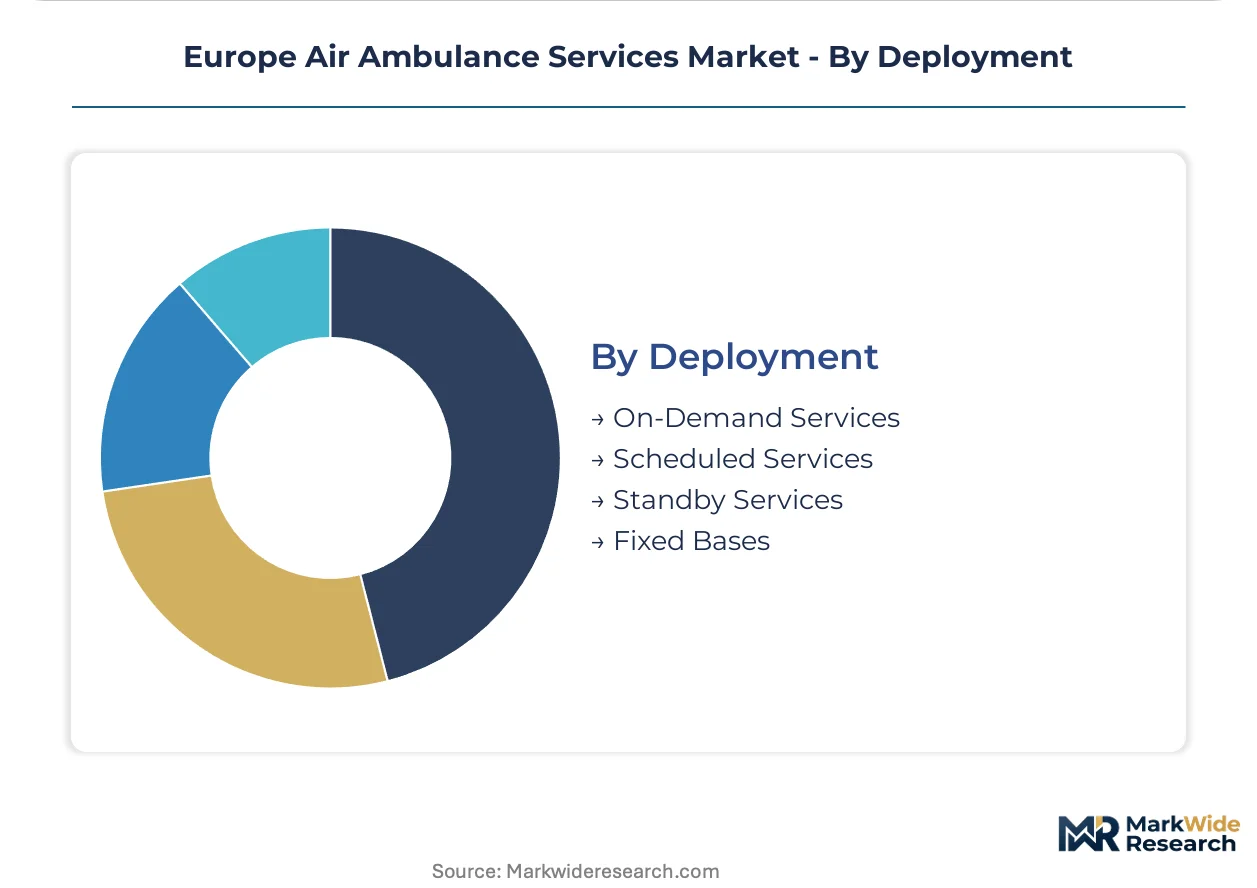
Deployment:
Base station economics and fleet utilization models create distinct margin structures, with fixed base operations amortizing infrastructure costs across predictable demand while on-demand services command premium pricing for availability guarantees.
- On-Demand Services:Ad-hoc dispatch responding to emergency calls and urgent transfer requests. Pricing reflects aircraft positioning costs and crew standby availability, with German operators facing critical care paramedic scarcity constraints on 24/7 coverage.
- Scheduled Services:Pre-booked interfacility transfers enabling optimized routing and crew scheduling. Norwegian and Swedish grid infrastructure supports secondary base electrification pilots that could reduce fuel logistics for mountain corridors.
- Standby Services:Dedicated aircraft and crew retained for specific events or facilities under retainer contracts.
- Fixed Bases:Permanent station infrastructure with housed aircraft and resident medical crews, concentrating in Germany, Switzerland, and Norway.
Fixed Bases anchor the operational footprint by asset count. On-Demand Services generate the highest revenue per mission.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones across alpine corridors concentrate air ambulance infrastructure through terrain-driven necessity and cross-border interoperability mandates. Mountain rescue protocols and EU Green Deal funding accelerate base station modernization in high-altitude regions.
Germany
Hospital network consolidation in North Rhine-Westphalia and Bavaria drives demand for dedicated interfacility transport contracts. DRF Stiftung Luftrettung gemeinnützige AG operates under nonprofit governance with deep procurement ties to German hospital consortia. The KBA regulates airworthiness certifications for mixed rotary-fixed-wing fleets stationed across Frankfurt-Rhine-Main and Munich medical clusters.
Switzerland
Alpine terrain mandates helicopter-based emergency response across Bernese Oberland and Graubünden corridors. Swissmedic medical device standards govern cabin equipment procurement for high-altitude missions. Swiss Air-Rescue Rega anchors its dominance through specialized mountain rescue protocols and multi-base coverage spanning Zurich, Geneva, and Lugano hubs.
Norway
Secondary base electrification pilots in Trøndelag and Vestland leverage grid infrastructure for sustainable helicopter operations. The Norwegian Air Ambulance Foundation coordinates civilian-military MedEvac capabilities under national health ministry funding. Tromsø and Bergen clusters host the densest concentration of electrified hangar facilities in Scandinavia.
United Kingdom
Insurance-driven network adequacy requirements in London and Southeast England consolidate procurement through preferred operator panels. IAS Medical and Babcock Scandinavian AirAmbulance compete on cross-border operating permissions under CAA regulations. The Midlands and North England see expanding fixed-wing coverage for organ retrieval logistics networks.
France
ANSM medical device regulations extend CE marking timelines for ventilator and cardiac monitor suppliers serving air ambulance configurations. Helicopter airframe supply concentration among French aerospace suppliers creates procurement dependencies for operators in Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur. Marseille and Lyon medical clusters drive demand for alpine-adjacent emergency response capabilities.
Europe Air Ambulance Services Market Key Industry Players
German and Swiss operators anchor one tier through nonprofit governance and alpine expertise; Nordic and British specialists hold complementary positions through electrification pilots and insurance network consolidation. The vendor base stratifies across three archetypes: integrated multi-jurisdiction private operators, nonprofit foundations with hospital network anchoring, and specialized fixed-wing organ logistics providers. Dominant competitive moves include M&A-driven geographic expansion and strategic partnerships for sustainable aviation fuel supply security.
Within the nonprofit foundation tier, Swiss Air-Rescue Rega and DRF Stiftung Luftrettung gemeinnützige AG exemplify governance structures that secure preferential hospital procurement relationships. Falck occupies a position among integrated private operators spanning multiple European jurisdictions through centralized fleet management. Norwegian Air Ambulance Foundation represents the Nordic specialization in civilian-military coordination and electrification pilots.
| Leading Market Players |
|---|
| Swiss Air-Rescue Rega |
| Falck |
| DRF Stiftung Luftrettung gemeinnützige AG |
| HT Group |
| AirMed International |
| ADAC Luftrettung |
| Norwegian Air Ambulance Foundation |
| IAS Medical |
| Babcock Scandinavian AirAmbulance |
| Others |
Cost & Logistics Intelligence
Jet A-1 kerosene futures volatility cascades through European air ambulance pricing tiers, compressing margins for fixed-wing operators on cross-border routes while rotary-wing providers pass through fuel surcharges via hospital retainer contracts. Sustainable aviation fuel mandates under the EU Green Deal widen cost differentials between legacy fleets and modernized aircraft, segmenting procurement relationships by environmental compliance tier.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with 24-hour guaranteed availability commanding retainer multiples over spot-interfacility transfers. Pricing stratifies across premium emergency response, standard scheduled transport, and economy patient repatriation tiers. Cost compression in fixed-wing long-haul segments stems from SAF cost premiums without corresponding reimbursement adjustments. Hospital procurement consortia exhibit lowest price sensitivity; individual private patients show highest elasticity.
Supply Chain Analysis
Direct-to-operator channels handle specialized medical equipment demand, with cabin-integrated ventilators and cardiac monitors flowing through EMA-certified distributors. Critical airframe production concentrates in France and Italy for rotor-wing platforms, while Germany and Switzerland anchor avionics integration. Supply chain risk centers on single-source vulnerability for helicopter transmission systems. Distribution runs through hospital procurement consortia and insurer-mandated operator panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Critical care paramedic training bottlenecks constrain crew availability for 24/7 coverage, propping pricing power for operators with certified staffing reserves. Supply scarcity in alpine-adjacent bases reinforces contract premiums for guaranteed response times.
For Market Incumbents: Extend fleet electrification pilots from Nordic corridors into alpine networks before noise restrictions tighten. Secure long-term sustainable aviation fuel offtake agreements to hedge against EU Green Deal cost escalation. Backward integration into medical crew training programs addresses critical care paramedic scarcity threatening 24/7 coverage guarantees. For New Entrants and Emerging Players: Predictive dispatch algorithms for demand forecasting offer technology-first wedge into underserved secondary base markets. Target organ retrieval logistics networks where cold-chain expertise barriers limit incumbent penetration. Pursue EASA supplemental type certification for harmonized cross-border equipment profiles as primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor nonprofit-to-private transitions in German hospital network corridors where procurement consolidation accelerates. Long-term viability hinges on electrification readiness and AI Act-compliant autonomous flight positioning. Monitor EASA airworthiness certification backlogs as inflection indicator for regulatory-constrained capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Aviation Fuel Supply Security | Long-term offtake agreements with Nordic biofuel producers hedge EU Green Deal compliance costs. |
| Predictive Dispatch Algorithm Deployment | EU AI Act-compliant machine learning optimizes base positioning across seasonal demand patterns. |
| Medical Crew Training Program Expansion | In-house critical care paramedic certification addresses staffing scarcity constraining 24/7 coverage. |
| Secondary Base Electrification Pilot | Norwegian grid infrastructure pilots transfer to alpine corridors, reducing noise restriction exposure. |
| Organ Retrieval Logistics Network Buildout | Dedicated cold-chain capabilities capture premium positioning in underpenetrated transplant transport segment. |
Research Approach
Multi-period observation of hospital procurement contract awards, EASA certification timelines, and sustainable aviation fuel price spreads anchored the trend analysis, supplemented by interviews with air ambulance operations directors, hospital purchasing committee chairs, EASA certification specialists, and medical device procurement managers. Secondary validation drew from EASA regulatory filings, EU Green Deal implementation trackers, hospital procurement database disclosures, and REACH compliance registries. Bottom-up fleet deployment modeling triangulated against top-down healthcare expenditure flows.
Input-output matrices mapped aircraft configuration economics across service type and deployment mode dimensions, with segmentation modeling spanning emergency response, interfacility transport, MedEvac, and patient transfer categories alongside technology tiers and end-user archetypes. CAGRs derived from iterative convergence of demand-side hospital network consolidation trajectories and supply-side certification capacity constraints. Forecast inputs incorporated EU AI Act regulatory clarity timelines and electrification infrastructure buildout curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EASA certification backlog accumulation and sustainable aviation fuel supply disruption scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
US Urgent Care Centers Market