
 Transport Chairs Market | 2026-2036
Transport Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Chairs Market Intelligence
Aftermarket service revenue is narrowing as manufacturers bundle preventive maintenance into initial equipment contracts. Invacare Corporation leverages its North American distribution network to capture recurring parts revenue from legacy installed bases. Sunrise Medical LLC anchors its position through European rehabilitation center relationships and specialized seating configurations. Drive DeVilbiss Healthcare, Inc. competes aggressively on price in the home care channel while sustaining margin through volume scale.
Transport chairs are mobile seating devices designed for patient transfer, typically featuring foldable aluminum or steel frames with seat widths of 16 to 20 inches and weight capacities spanning 200 to 400 pounds, built for short-duration mobility in clinical and residential settings. Lightweight wheelchairs command premium positioning due to caregiver ergonomics and vehicle lift compatibility, while electric wheelchairs represent the fastest-growing product category as battery density improves and indoor navigation precision advances. Hospitals remain the dominant end user channel, though home care procurement is expanding fastest as discharge planning shifts toward outpatient recovery models.
FDA 510(k) requirements govern transport chair safety testing and biocompatibility standards, while ISO 7176 technical specifications define crash-test integrity and durability benchmarks for institutional procurement. The EU Medical Device Regulation mandates notified body oversight for European market access, adding conformity assessment costs that favor established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor reimbursement code consolidation across Medicare and private payers, as coding density directly influences provider willingness to upgrade fleet equipment.
Market Dynamics
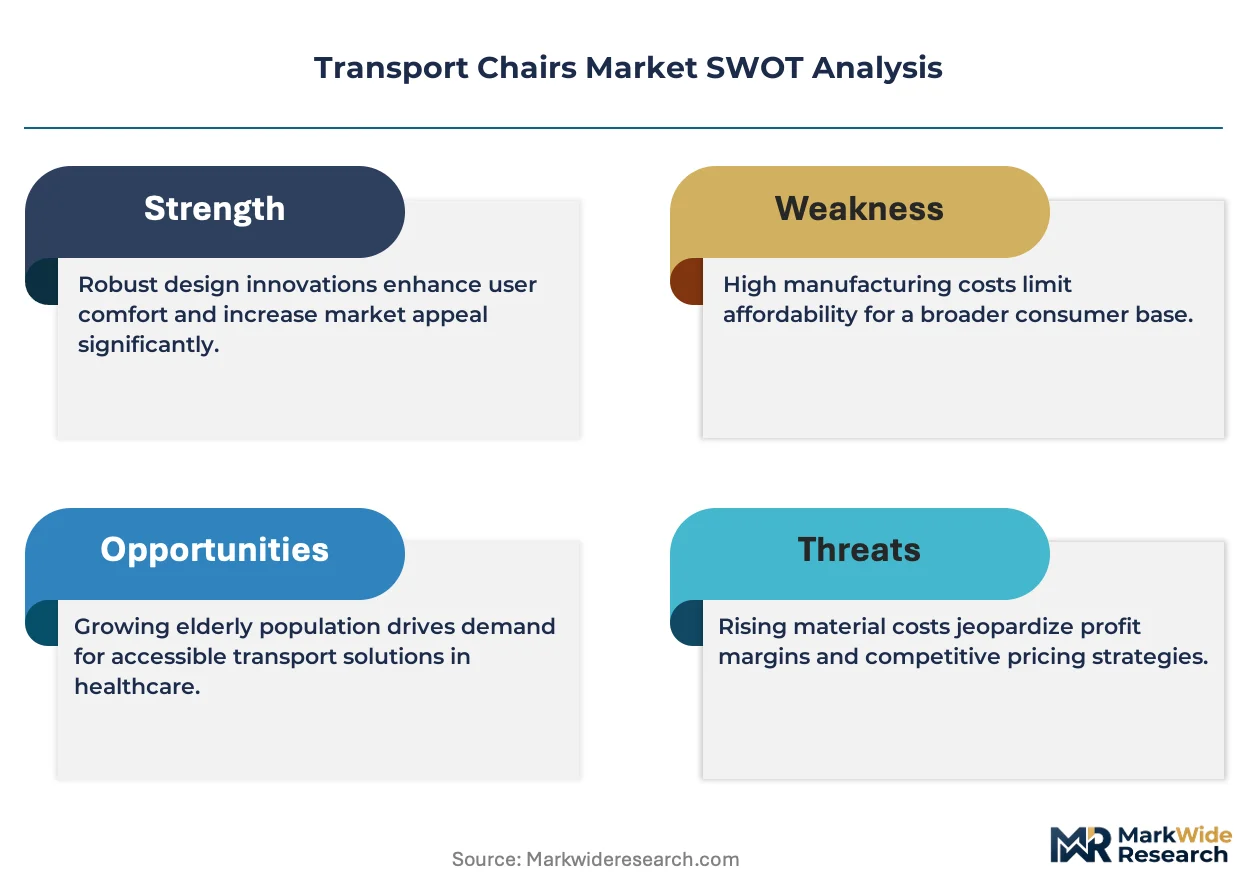
Medicare durable medical equipment reimbursement code consolidation is compressing provider upgrade cycles and forcing manufacturers toward bundled service contracts that absorb lifecycle costs.
Growth Catalysts
- Lightweight aluminum frame adoption:Home care agencies are standardizing 16-20 pound transport chairs for caregiver ergonomics and vehicle lift compatibility, accelerating fleet replacement in discharge programs.
- FDA 510(k) pathway maturation:Established documentation templates for Class II medical devices are reducing time-to-market for incremental design improvements, though they still filter out undercapitalized entrants.
- Aging-in-place policy frameworks:United States federal and state Medicaid waivers are expanding home-based care eligibility, directly stimulating procurement from long-term care networks and hospital discharge planners.
Market Restraints
- Steel price volatility:Input cost swings for chromoly and carbon steel frames are compressing margin on economy-tier models, forcing manufacturers toward aluminum substitution or geographic sourcing shifts.
- Supply concentration in Chinese casting:Die-cast aluminum frame production clusters in Zhejiang and Guangdong provinces, creating single-source vulnerability for North American and European assemblers.
- Electric wheelchair substitution:Battery density improvements and indoor navigation precision in powered mobility devices are capturing patients who would otherwise use manual transport chairs for short-duration transfers.
Strategic Opportunities
- Underpenetrated rural home care:United States non-metropolitan counties show transport chair penetration gaps exceeding 40 percent against urban benchmarks, creating whitespace for direct-to-patient distribution models.
- Crash-test certification convergence:ISO 7176-19 wheelchair tie-down standards are harmonizing with NHTSA motor vehicle safety requirements, enabling single-certification products that access both institutional and automotive retrofit channels.
- Smart sensor integration:Pressure mapping and fall-detection electronics are converging with lightweight frame platforms, opening premium positioning for technology-enabled transport chairs in rehabilitation center settings.
Industry Challenges
- Biocompatibility testing backlog:FDA 510(k) submissions for new upholstery materials and frame coatings face extended review timelines, delaying product launches and freezing R&D allocation decisions.
- Legacy fleet maintenance fragmentation:Installed bases of 5-7 year-old transport chairs require parts from discontinued SKUs, forcing manufacturers to maintain obsolete component inventories or abandon recurring service revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Chairs Market |
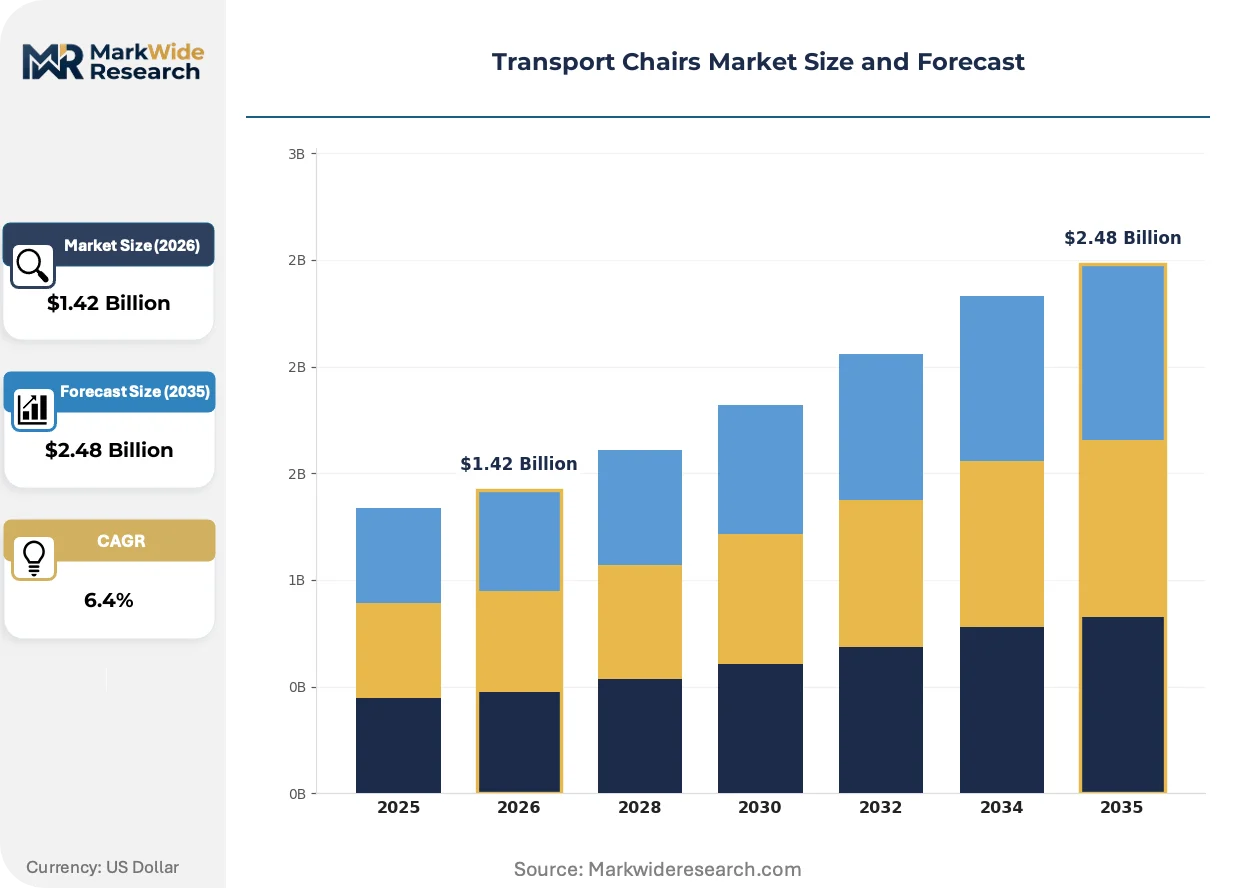
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Electric Wheelchairs, Reclining Wheelchairs, Lightweight Wheelchairs End User: Hospitals, Rehabilitation Centers, Home Care, Nursing Facilities Weight Capacity: Up to 200 lbs, 200-300 lbs, 300-400 lbs, 400+ lbs Material: Aluminum, Steel, Titanium, Plastic |
| Companies Covered | Invacare Corporation, Sunrise Medical LLC, Drive DeVilbiss Healthcare, Inc., Medline Industries, L.P., Stryker Corporation, Karman Healthcare, Inc., Nova Medical Products, Inc., Permobil AB, Carex Health Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Chairs Market Strategic Shifts & Innovations
Active material substitution and regulatory harmonization are compressing product development cycles while reshaping channel economics across institutional and residential buyer segments.
Carbon fiber composite frame technology is rendering obsolete steel and aluminum construction in premium transport chair segments. Rehabilitation centers and high-acuity home care agencies are adopting 12-14 pound carbon models for patient transfers exceeding 50 daily cycles. This material shift is rendering obsolete traditional foundry-based supply chains and compressing assembly labor content by 30 percent.
EU Medical Device Regulation notified body oversight is elevating conformity assessment costs for European market access. Manufacturers now dedicate 8-12 percent of product development budgets to regulatory affairs teams managing technical documentation and post-market surveillance. Small and mid-tier producers are responding by ceding EU distribution to established partners with dedicated MDR compliance infrastructure.
Hospital supply chain consolidation is compressing vendor rosters and lengthening contract terms. Integrated delivery networks are replacing transactional purchasing with multi-year equipment leases that bundle preventive maintenance and fleet refresh guarantees. This behavioral shift is most visible in United States health systems exceeding 10,000 beds, where procurement committees now prioritize total cost-of-ownership metrics over unit price.
Transport Chairs Market Segmentation
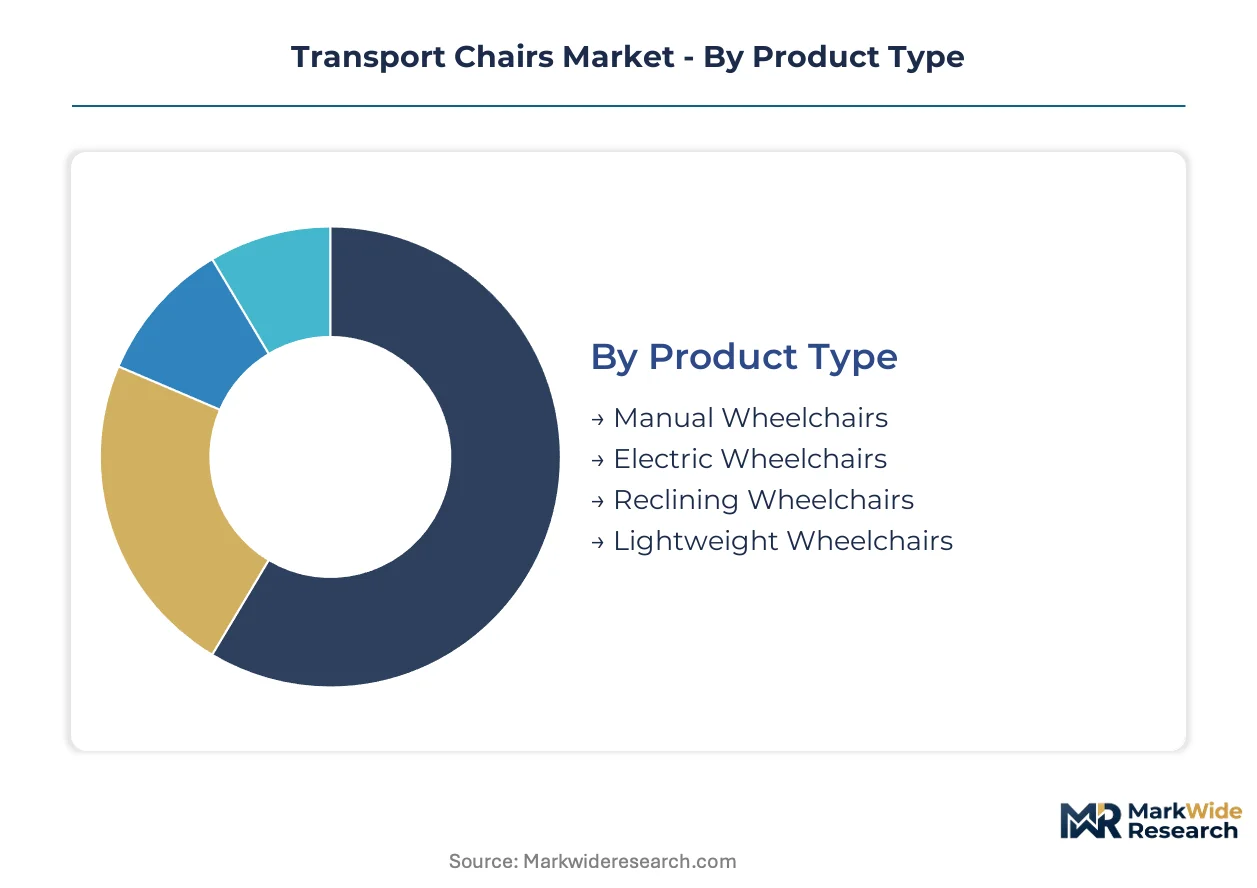
Transport chair procurement patterns diverge sharply across clinical versus residential settings, with material composition and weight specifications driving reimbursement eligibility and caregiver adoption. Understanding segment-level demand concentration enables manufacturers to align R&D allocation with channel-specific purchasing authority.
Product Type:
Cost tier differentiation separates institutional bulk purchasing from premium retail channels, with reimbursement codes anchoring volume distribution.
- Manual Wheelchairs:Foldable aluminum or steel frames with 16-20 inch seat widths dominate hospital discharge programs and nursing facility fleets. Medicare durable medical equipment reimbursement sustains replacement cycles across United States long-term care networks, though margin compression from bundled service contracts is forcing manufacturers toward aluminum substitution.
- Electric Wheelchairs:Battery-powered mobility devices with indoor navigation precision and improved battery density are capturing patients who previously relied on manual transport for short-duration transfers. Rehabilitation centers in Germany and the United States are standardizing powered models for high-acuity patients requiring independent mobility.
- Reclining Wheelchairs:Tilt-in-space mechanisms support pressure redistribution for bariatric and wound-care patients in skilled nursing settings.
- Lightweight Wheelchairs:12-20 pound carbon fiber and aluminum frames command premium positioning for caregiver ergonomics and vehicle lift compatibility in home care agencies.
Manual wheelchairs command the established base. The steepest expansion runs through electric wheelchairs.
End User:
Application context determines specification requirements, with clinical settings prioritizing durability ratings and residential buyers emphasizing portability.
- Hospitals:Integrated delivery networks exceeding 10,000 beds are consolidating vendor rosters around multi-year equipment leases bundling preventive maintenance. FDA 510(k) clearance requirements elevate documentation burdens for new entrants seeking institutional procurement committee approval.
- Rehabilitation Centers:European facilities under EU Medical Device Regulation oversight demand ISO 7176-19 crash-test certification for wheelchair tie-down compatibility. Carbon fiber models supporting 50+ daily patient transfer cycles are displacing traditional aluminum construction in high-throughput German and Swiss centers.
- Home Care:United States non-metropolitan counties show penetration gaps exceeding 40 percent against urban benchmarks, creating whitespace for direct-to-patient distribution models.
- Nursing Facilities:Medicaid waiver expansion under aging-in-place policy frameworks is stimulating fleet refresh demand across United States state-level long-term care networks.
Hospitals anchor procurement volume. Home care channels are gaining share fastest.
Weight Capacity:
Patient anthropometrics and bariatric prevalence rates shape specification requirements across institutional buyer segments.
- Up to 200 lbs:Standard-duty aluminum frames serve the general patient population in acute care discharge settings.
- 200-300 lbs:Reinforced cross-brace construction addresses the modal weight distribution in United States skilled nursing facilities.
- 300-400 lbs:Heavy-duty steel and titanium frames with widened seat bases support bariatric patient mobility protocols in hospital bariatric surgery units.
- 400+ lbs:Specialized bariatric transport chairs with reinforced casters and extended wheelbases are procured through dedicated medical equipment suppliers serving United States long-term care networks with high obesity prevalence.
The 200-300 lbs segment captures the standard institutional base. The 300-400 lbs category is climbing fastest.
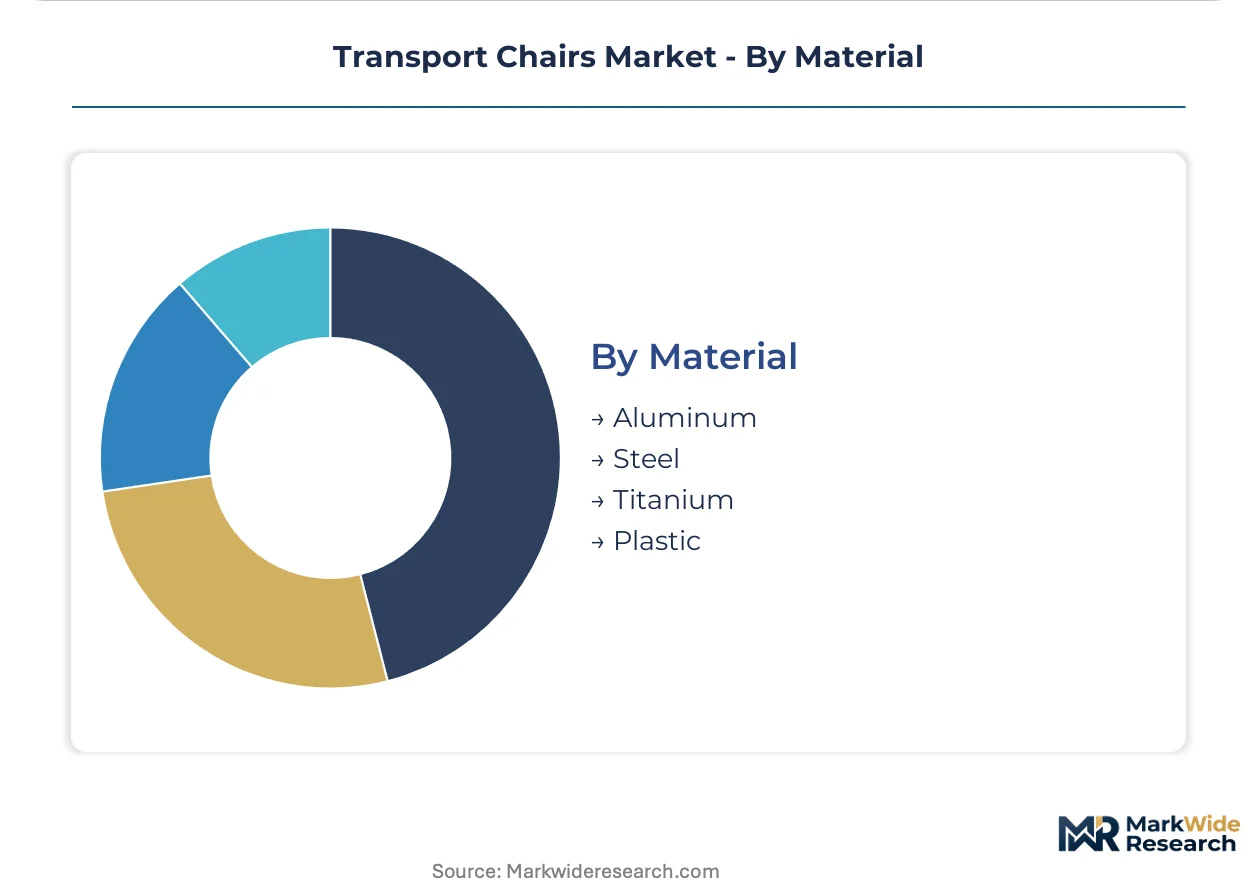
Material:
Supply concentration and input cost volatility are compressing margin structures and accelerating substitution patterns across frame construction.
- Aluminum:Die-cast frame production clusters in Zhejiang and Guangdong provinces create single-source vulnerability for North American and European assemblers. Home care agencies are standardizing 16-20 pound aluminum models for caregiver ergonomics.
- Steel:Chromoly and carbon steel frames face margin compression from input price volatility, forcing manufacturers toward geographic sourcing shifts or material substitution.
- Titanium:Premium-grade frames serve bariatric and high-cycle rehabilitation applications where strength-to-weight ratios justify unit cost premiums.
- Plastic:Injection-molded components reduce assembly labor content in economy-tier models targeted at emerging market price-sensitive procurement.
Aluminum dominates installed fleet composition. Titanium is expanding most quickly in premium rehabilitation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for transport chairs diverge sharply between aging-in-place economies with established Medicare reimbursement infrastructure and emerging markets where out-of-pocket procurement dominates acute care settings.
United States
Medicare durable medical equipment reimbursement codes sustain replacement cycles across hospital systems and long-term care networks. FDA 510(k) clearance requirements for Class I and II medical devices elevate documentation burdens for new entrants seeking institutional procurement approval. Die-cast aluminum frame sourcing concentrates in Zhejiang province, creating supply chain vulnerability for North American assemblers.
Germany
Rehabilitation centers under EU Medical Device Regulation oversight demand ISO 7176-19 crash-test certification for wheelchair tie-down compatibility. Carbon fiber models supporting 50-plus daily patient transfer cycles displace traditional aluminum construction in high-throughput centers. Bavaria-based medical device clusters anchor premium manufacturing for institutional procurement.
China
Domestic production of die-cast aluminum frames clusters in Guangdong and Zhejiang provinces, supplying global assembly operations. NMPA medical device registration requirements are tightening for export-oriented manufacturers serving North American and European markets. Shanghai and Shenzhen medical equipment trade zones facilitate component aggregation for multinational supply chains.
Japan
PMDA regulatory frameworks govern transport chair safety testing and biocompatibility standards for domestic market access. METI aging-society initiatives stimulate procurement from municipal long-term care insurance programs. Osaka-based rehabilitation equipment distributors specialize in lightweight carbon fiber models for home care agency fleets.
United Kingdom
NHS supply chain consolidation compresses vendor rosters around multi-year equipment leases bundling preventive maintenance. MHRA medical device regulations align with EU MDR technical specifications post-Brexit, maintaining conformity assessment requirements. London and Southeast England integrated care systems prioritize total cost-of-ownership metrics over unit price in procurement decisions.
Transport Chairs Market Key Industry Players
Capability concentration sits with specialized seating and rehabilitation equipment fabricators; scale advantage sits with diversified medical device conglomerates with North American distribution density. The vendor base stratifies across three tiers: premium carbon fiber specialists serving high-acuity rehabilitation centers, aluminum frame volume manufacturers capturing home care agency procurement, and diversified hospital supply conglomerates bundling transport chairs into capital equipment contracts. Dominant competitive moves include backward integration into aluminum die-casting operations and strategic partnerships with Medicare durable medical equipment suppliers.
Among North American medical device specialists, Invacare Corporation, Sunrise Medical LLC, and Drive DeVilbiss Healthcare, Inc. occupy positions across distinct competitive vectors. Invacare exemplifies the legacy installed-base service model, leveraging distribution infrastructure for recurring parts revenue. Sunrise Medical represents European rehabilitation center relationships and specialized seating configurations. Drive DeVilbiss sits within aggressive price-competitive positioning in home care channels sustained through volume scale.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical LLC |
| Drive DeVilbiss Healthcare, Inc. |
| Medline Industries, L.P. |
| Stryker Corporation |
| Karman Healthcare, Inc. |
| Nova Medical Products, Inc. |
| Permobil AB |
| Carex Health Brands |
| Others |
Cost & Logistics Intelligence
Trans-Pacific container freight corridors from Shanghai to Los Angeles govern landed cost dynamics for aluminum frame components, compressing margin on economy-tier models while enabling premium positioning for manufacturers with captive die-casting operations in Zhejiang province. This logistics cost structure feeds directly into three-tier pricing differentiation across institutional procurement channels.
Pricing Analysis
Long-term equipment lease contracts dominate institutional procurement, bundling preventive maintenance and fleet refresh guarantees into multi-year agreements that absorb lifecycle costs. Price differentiation separates ISO 7176-19 crash-test certified models for rehabilitation centers from standard-duty aluminum frames serving home care discharge programs. Pricing pressure stems from Medicare reimbursement code consolidation, which compresses provider upgrade willingness and forces margin absorption into service bundling. Home care agencies exhibit highest price sensitivity due to direct Medicaid waiver reimbursement exposure, while integrated delivery networks prioritize total cost-of-ownership metrics over unit acquisition cost.
Supply Chain Analysis
Extended payment terms from North American assemblers to Zhejiang and Guangdong die-casting suppliers have become standard practice, with supply-chain finance facilities bridging working capital gaps for component manufacturers. Raw material dependencies center on aluminum ingot, chromoly steel tubing, and lithium-ion battery cells for electric wheelchair substitution threats. Single-source vulnerability concentrates in Chinese aluminum casting clusters, where NMPA export registration tightening creates regulatory friction. Distribution runs through Medicare durable medical equipment suppliers and hospital GPO contracts, with direct-to-patient channels emerging in rural United States counties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern anchored to Medicare durable medical equipment reimbursement cycle refreshes, with replacement demand accelerating as hospital systems emerge from capital expenditure constraints.
For Market Incumbents: Entrench position through backward integration into aluminum die-casting operations, securing captive supply against Zhejiang province concentration risk. Deepen hospital system partnerships by embedding biomedical engineers into integrated delivery network procurement committees, countering electric wheelchair substitution with demonstrable caregiver ergonomics data. For New Entrants and Emerging Players: United States non-metropolitan counties present whitespace exceeding forty percent penetration gaps against urban benchmarks, enabling direct-to-patient distribution models that bypass incumbent GPO relationships. Target rural home care agencies with lightweight aluminum models optimized for vehicle lift compatibility, leveraging telehealth discharge planning partnerships as the primary go-to-market channel. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors carbon fiber composite specialists with ISO 7176-19 certification infrastructure and rehabilitation center relationships. Long-term viability rests on material substitution momentum and regulatory harmonization across FDA and EU MDR frameworks. Monitor NHTSA wheelchair tie-down standard adoption as the inflection signal for automotive retrofit channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 7176-19 Crash-Test Certification | Unlocks rehabilitation center procurement in Germany and United States markets requiring tie-down compatibility. |
| Aluminum Die-Casting Backward Integration | Reduces Zhejiang supply concentration exposure while capturing margin from frame component production. |
| Medicare DME Supplier Partnership | Secures reimbursement code access for home care agency fleet replacement programs. |
| Carbon Fiber Platform Development | Addresses high-cycle rehabilitation center demand exceeding fifty daily patient transfers. |
| Direct-to-Patient Rural Distribution | Captures forty percent penetration gap in United States non-metropolitan home care markets. |
Research Approach
A standing panel of hospital procurement committee members, biomedical engineers, home care agency discharge planners, and Medicare durable medical equipment supplier executives provided ongoing calibration throughout the research process. Primary fieldwork combined structured interviews with GPO contracts managers and rehabilitation center clinical directors, validated against secondary sources including FDA 510(k) clearance databases, CMS Medicare reimbursement code filings, and ISO 7176 technical specification documentation. Bottom-up demand modeling from institutional fleet replacement cycles triangulated with top-down market sizing from aluminum frame production data.
Scenario-bracketing framed the analytical approach, with volume and value outputs reflecting segmented modeling across product type, end user channel, weight capacity tier, and material composition dimensions. CAGRs were derived from replacement cycle analysis and reimbursement policy trajectory assessment. Key forecast inputs incorporated battery density improvement curves for electric wheelchair substitution pressure and Medicaid waiver expansion rates under aging-in-place policy frameworks.
Macroeconomic conditions sit as an overlay; deviation in freight rates, aluminum ingot pricing, or Medicare reimbursement schedule adjustments would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway stability and supply chain concentration persistence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Middle-East and Africa Cardiac Arrhythmia Monitoring Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Insulin Storage Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Fixed and Mobile C-Arms Market
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Liver-On-Chip Market
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Asia-Pacific Intraoral Scanners Market
Medical Devices
Global Next Generation Surgical Robotics Market
Medical Devices
Global Obstetrics Devices Market
Medical Devices
Kirschner Wires Market