
 US Urgent Care Centers Market | 2026-2036
US Urgent Care Centers Market Size, Share, and Industry Trends Forecast 2026-2036
US Urgent Care Centers Market Intelligence
Telemedicine integration is consolidating into standard urgent care workflows, replacing standalone virtual visit models with hybrid in-person and remote protocols. Concentra leverages its occupational health heritage to anchor employer-contracted clinic networks across industrial corridors. American Family Care sustains multi-state expansion through franchise-operated freestanding locations. Fast Pace Health competes in rural and semi-urban markets where hospital-affiliated systems maintain weaker geographic coverage.
Urgent care centers deliver episodic ambulatory services for non-life-threatening conditions, typically operating with extended evening and weekend hours, on-site diagnostic equipment including X-ray and point-of-care laboratory testing, and physician assistant or nurse practitioner staffing models designed for throughput efficiency. Freestanding urgent care locations dominate volume distribution due to lower capital requirements and faster site development timelines compared to hospital-affiliated counterparts. Telemedicine and EHR systems represent the fastest-growing technology segment as interoperability mandates and patient convenience expectations reshape intake and follow-up protocols.
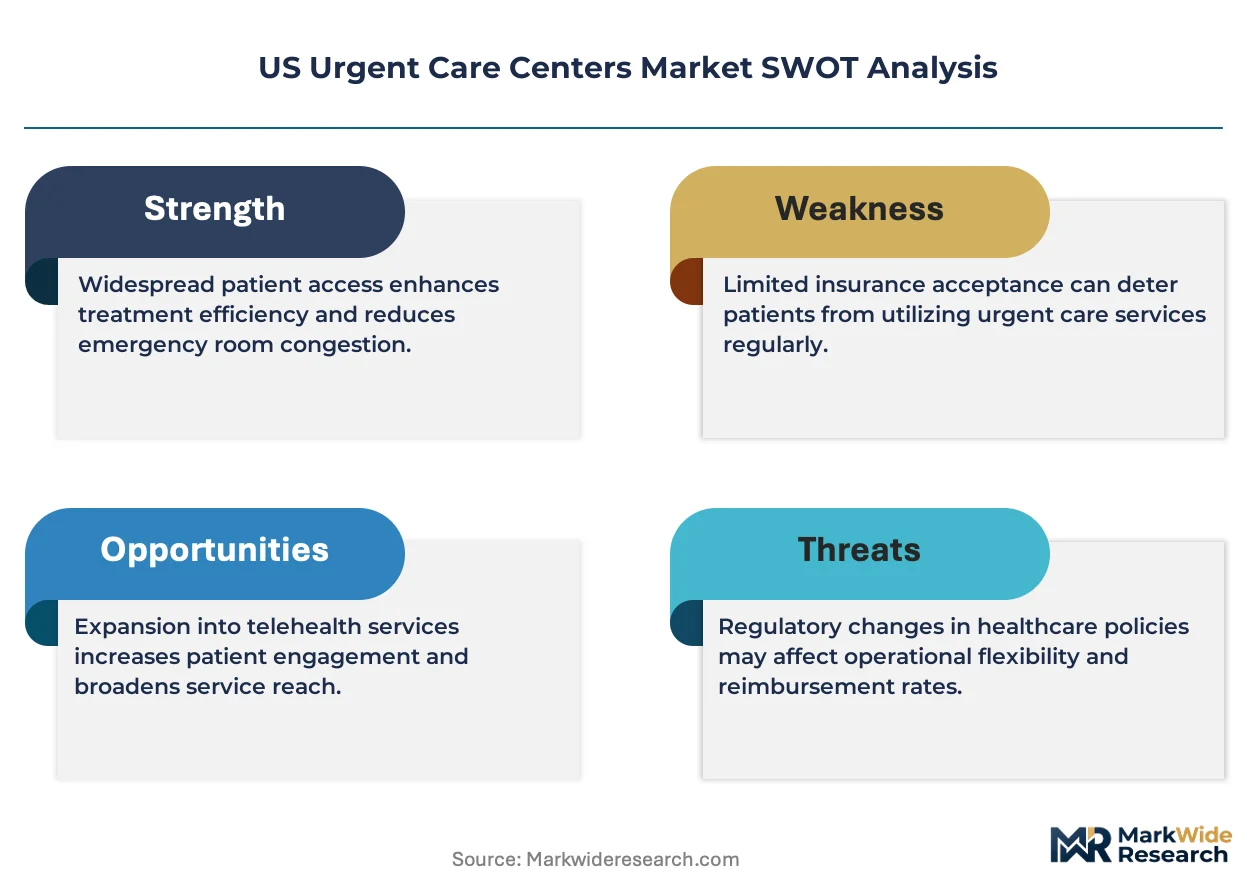
CMS value-based reimbursement frameworks and state-level certificate-of-need regulations shape site expansion feasibility and service line economics across jurisdictions. OSHA workplace health standards and HIPAA data privacy requirements impose operational compliance burdens that influence technology procurement and staffing credentialing decisions. Stakeholders must monitor state Medicaid expansion trajectories and commercial insurer narrow-network strategies to anticipate volume shifts between urgent care and competing access points.
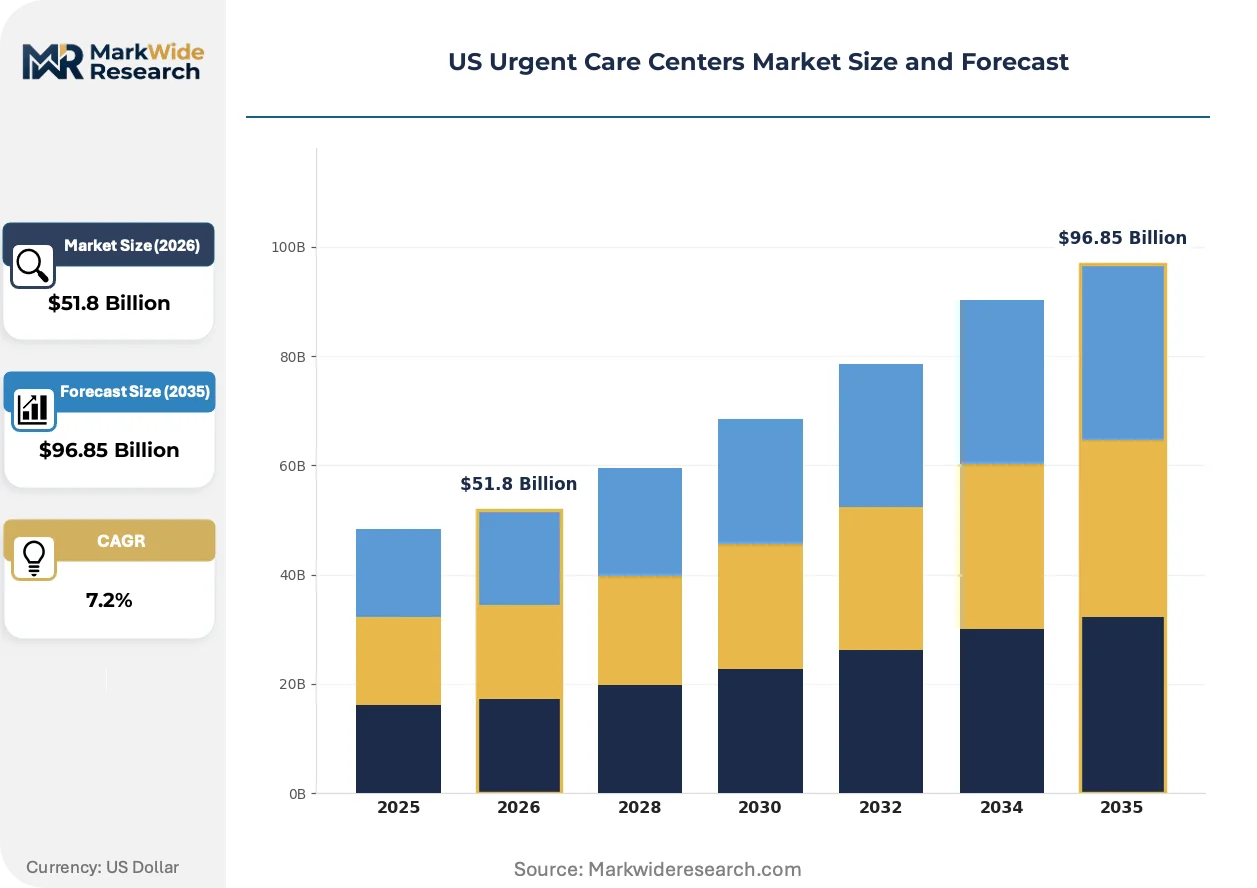
Market Dynamics
CMS reimbursement shifts toward value-based care models are redirecting patient volumes from emergency departments to lower-cost urgent care settings, while employer-sponsored health plans aggressively expand clinic networks as a cost-containment strategy.
Growth Catalysts
- Employer-Sponsored Plan Expansion:Large employers in Texas, Florida, and Arizona are contracting directly with urgent care networks to reduce per-episode costs and bypass traditional primary care bottlenecks.
- CMS Value-Based Reimbursement:Medicare payment reforms penalize unnecessary emergency department utilization, creating financial incentives for beneficiaries to seek urgent care for non-critical conditions.
- Telemedicine-EHR Convergence:Interoperability mandates from HIPAA and state-level health information exchange requirements are accelerating hybrid care model adoption.
Market Restraints
- Certificate-of-Need Regulations:State-level CON laws in New York, California, and Illinois restrict site expansion and create regulatory moats protecting incumbent hospital-affiliated systems.
- Physician Shortage Concentration:Rural and semi-urban markets face acute primary care physician deficits, limiting staffing scalability for freestanding urgent care operators.
- Reimbursement Compression:Commercial insurers are narrowing networks and reducing fee-for-service rates, squeezing margin structures for independent clinic operators.
Strategic Opportunities
- Rural Market Penetration:Underserved counties in Appalachia and the Mississippi Delta present white-space opportunities where hospital systems maintain weak geographic coverage.
- Occupational Health Integration:OSHA workplace health standards are driving demand for employer-contracted clinics that combine urgent care with injury prevention and compliance testing.
- Medicaid Expansion Tailwinds:States that expanded Medicaid under the Affordable Care Act are seeing elevated urgent care utilization among newly insured populations.
Industry Challenges
- Nurse Practitioner Credentialing Bottlenecks:State-level scope-of-practice restrictions limit staffing flexibility and force reliance on more expensive physician labor in certain jurisdictions.
- Point-of-Care Diagnostic Integration:X-ray and laboratory equipment procurement requires substantial capital outlay, compressing cash flow for new site development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Urgent Care Centers Market |
| Market Size in 2026 | $51.8 Billion |
| Market Size in 2035 | $96.85 Billion |
| CAGR (2026 – 2036) | 7.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Freestanding, Hospital-affiliated, Retail-based, Urgent Care Chains Service Type: Physical Therapy, Diagnostic Imaging, Lab Services, Illness Treatment Customer Type: Individuals, Families, Employers, Insurers Technology: Telemedicine, EHR Systems, Mobile App Platforms, Wearable Devices |
| Companies Covered | Concentra, American Family Care, Fast Pace Health, CityMD Urgent Care, WellNow Urgent Care, NextCare Urgent Care, MedExpress Urgent Care, Patient First, FastMed Urgent Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Urgent Care Centers Market Strategic Shifts & Innovations
Hybrid care delivery models are replacing standalone virtual visit platforms, while regulatory pressure and shifting consumer expectations are compressing traditional intake and follow-up protocols.
Telemedicine integration is decentralizing patient access by embedding remote consultation capabilities directly into urgent care workflows. Health systems in Arizona and Texas are deploying hybrid protocols that route low-acuity cases to virtual triage before physical site assignment. This convergence is compressing wait times and expanding catchment radius without proportional capital expansion.
CMS value-based care mandates are forcing reimbursement model restructuring across Medicare Advantage plans. Hospital-affiliated urgent care networks in Florida are restructuring service lines to capture shared savings from reduced emergency department referrals. Independent operators lacking payer integration capabilities face exclusion from narrow-network contracts.
Consumer preference for transparent pricing is disrupting traditional fee-for-service billing. Employer-sponsored plans in industrial corridors are demanding episode-based bundled rates for occupational health and urgent care services. This shift is most visible in Texas, where direct contracting between self-insured employers and clinic networks is displacing traditional insurance intermediaries.
US Urgent Care Centers Market Segmentation
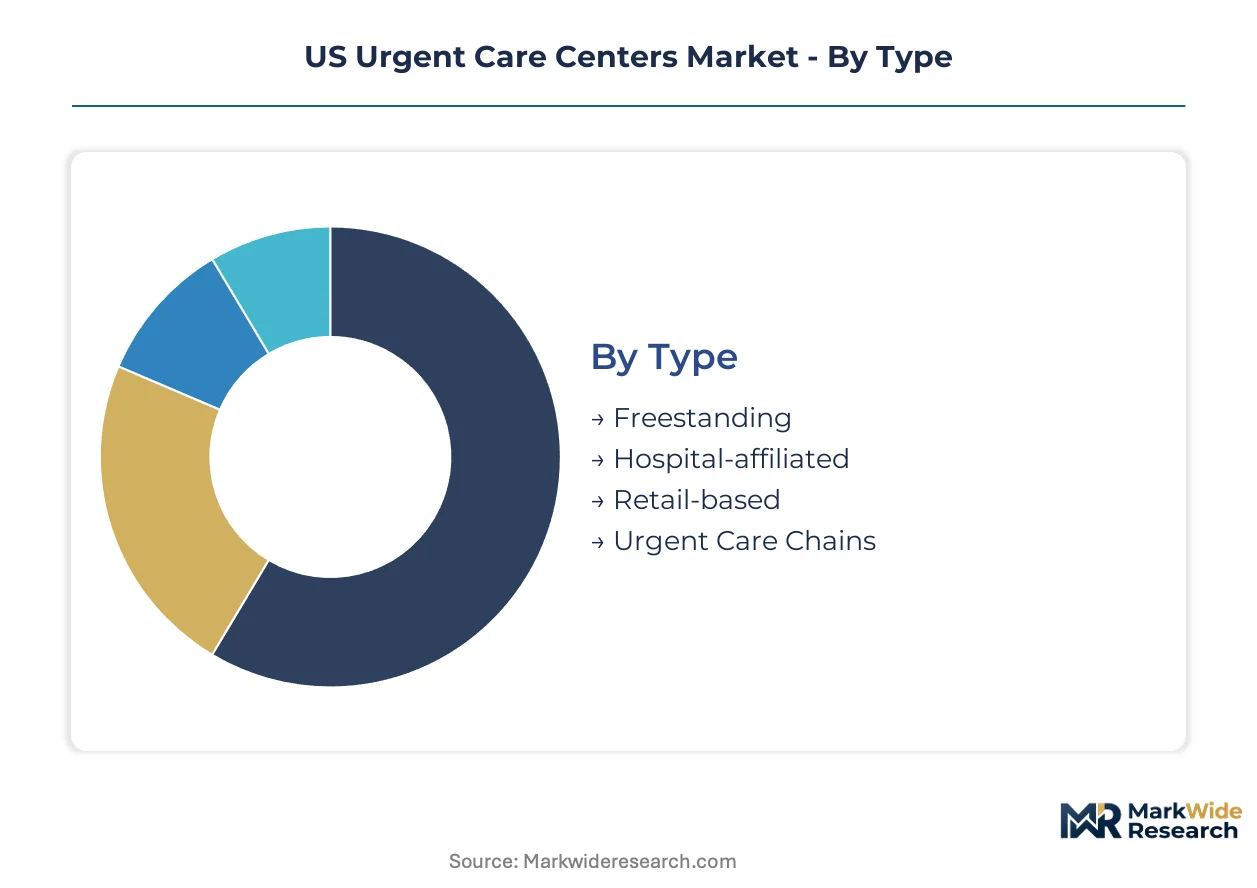
Urgent care operators compete across distinct operational models and service configurations that determine capital intensity, payer mix, and geographic scalability. Segment boundaries are blurring as hospital systems acquire freestanding networks and employers demand integrated occupational health platforms.
Type:
Ownership structure dictates site economics, with independent operators facing narrower network contracts than system-affiliated competitors.
- Freestanding:Independent clinics operate with lower overhead and faster development timelines, concentrating in Texas and Florida suburbs where physician shortages strain primary care access. These locations capture walk-in volume through extended hours and transparent pricing, though reimbursement compression from commercial insurers squeezes margin structures.
- Hospital-affiliated:Health system-owned clinics leverage existing payer contracts and EHR infrastructure, redirecting emergency department overflow to lower-cost settings. CMS value-based reimbursement frameworks reward these networks for reduced hospital admissions, creating shared savings opportunities in Medicare Advantage markets.
- Retail-based:Pharmacy-anchored clinics in Arizona and Florida shopping corridors capture convenience-driven demand with limited service menus.
- Urgent Care Chains:Multi-site operators achieve procurement scale for diagnostic equipment and standardized staffing models.
Freestanding locations sit at the top of the volume ranking, with hospital-affiliated networks climbing the fastest as systems consolidate market share.
Service Type:
Service line breadth determines reimbursement rates and patient capture frequency, with episodic illness treatment competing against recurring revenue from diagnostic and rehabilitation services.
- Physical Therapy:Post-injury rehabilitation and workers' compensation cases generate recurring visit patterns with higher per-episode reimbursement than acute illness treatment. OSHA workplace health standards in industrial corridors drive employer-contracted volume for injury prevention and return-to-work protocols.
- Diagnostic Imaging:On-site X-ray capabilities differentiate urgent care from primary care offices, capturing trauma and respiratory cases that require immediate radiological confirmation. Capital requirements for equipment and radiologist overread contracts create barriers for new entrants.
- Lab Services:Point-of-care testing for strep, flu, and COVID-19 accelerates throughput and supports episode-based billing.
- Illness Treatment:Acute respiratory and minor injury care constitutes the core value proposition driving initial patient visits.
Illness treatment commands the highest visit frequency, with diagnostic imaging expanding most quickly as operators add capabilities to compete with emergency departments.
Customer Type:
Payer and patient categories shape pricing power, with direct employer contracts offering rate stability compared to individual self-pay collections.
- Individuals:Uninsured and high-deductible plan patients prioritize transparent cash pricing and convenient access over continuity of care. Demand concentrates in states without Medicaid expansion where emergency department alternatives remain limited.
- Families:Pediatric-capable clinics with evening and weekend hours capture household decision-makers seeking alternatives to crowded emergency departments for after-hours illness.
- Employers:Self-insured companies in Texas manufacturing corridors contract directly with clinic networks for occupational health and urgent care, bypassing traditional insurance intermediaries.
- Insurers:Narrow-network strategies by commercial payers steer members toward contracted urgent care sites with pre-negotiated rates.
Individual patients generate the highest visit volume, with employer contracts gaining share fastest as direct contracting displaces traditional benefit structures.
Technology:
Digital infrastructure investment separates scalable operators from single-site competitors, with interoperability mandates accelerating EHR and telemedicine convergence.
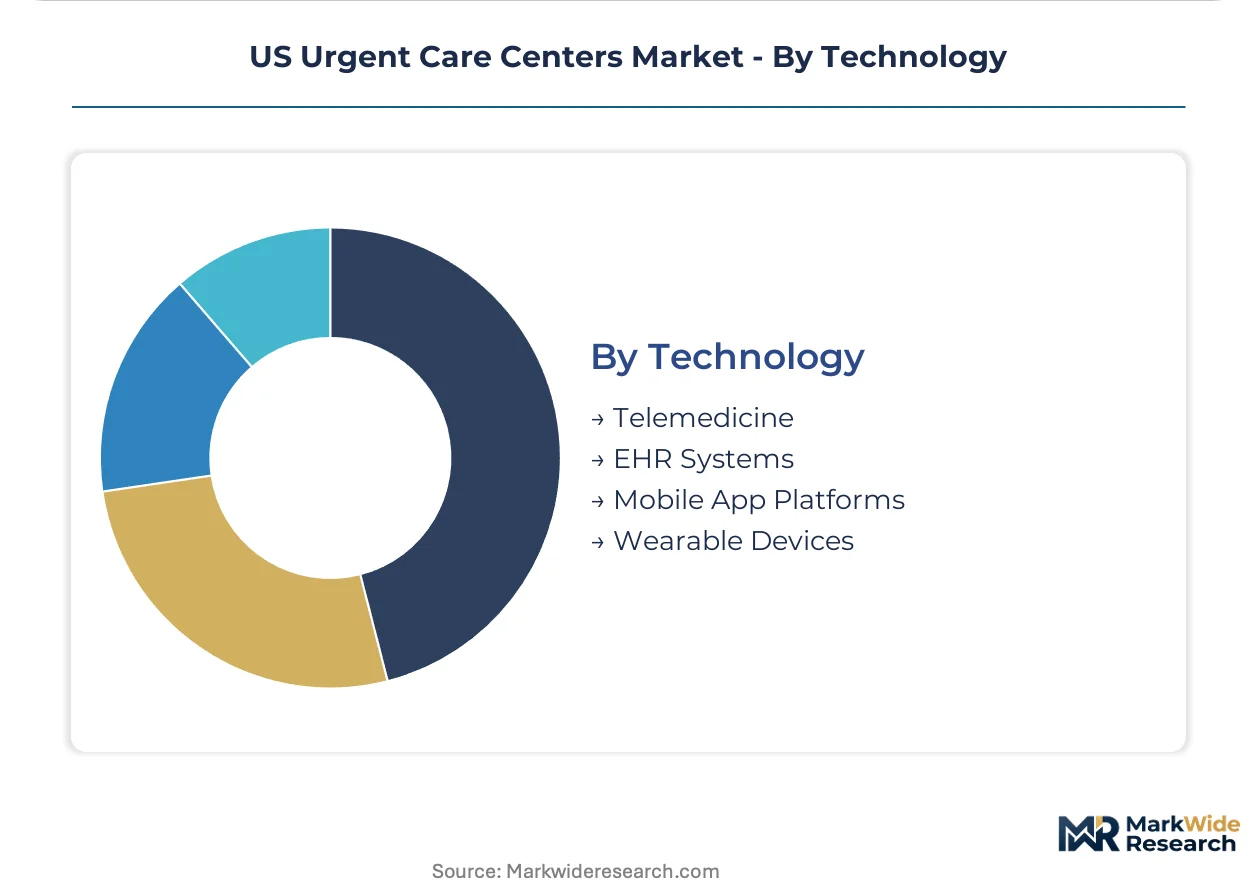
- Telemedicine:Virtual triage and follow-up capabilities extend catchment radius without proportional capital expansion, with Arizona health systems deploying hybrid protocols that route low-acuity cases to remote consultation before physical site assignment. HIPAA interoperability requirements accelerate platform integration into standard workflows.
- EHR Systems:Electronic health record connectivity with hospital networks and state health information exchanges enables care coordination and quality reporting for value-based contracts. Systems lacking interoperability face exclusion from narrow-network arrangements.
- Mobile App Platforms:Patient-facing scheduling and queue management tools reduce no-show rates and capture demographic data for marketing.
- Wearable Devices:Remote monitoring integration supports post-visit follow-up for chronic condition management in employer wellness programs.
EHR systems anchor current infrastructure spending, with telemedicine posting the steepest expansion trajectory as hybrid care models displace standalone virtual visit platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas manufacturing corridors anchor urgent care expansion as employer-contracted clinic networks displace traditional primary care bottlenecks across industrial suburbs.
Texas
Self-insured employers in Houston and Dallas-Fort Worth metro areas drive direct contracting with freestanding clinic operators. OSHA workplace health standards mandate injury prevention protocols that combine urgent care with compliance testing. The Permian Basin oilfield corridor concentrates occupational health demand where hospital-affiliated systems maintain weaker rural coverage.
Florida
Medicare Advantage penetration and retiree population density generate high episodic visit volumes for respiratory and minor injury treatment. CMS value-based reimbursement frameworks reward health systems for reduced emergency department referrals. The I-4 corridor between Tampa and Orlando anchors hospital-affiliated network expansion as systems consolidate market share.
Arizona
Population growth in Phoenix and Tucson suburbs strains traditional primary care access, redirecting patients to extended-hours urgent care. State health information exchange requirements accelerate EHR interoperability adoption across hybrid care platforms. Maricopa County health systems deploy virtual triage protocols that route low-acuity cases to remote consultation before physical site assignment.
California
Certificate-of-need regulations in Los Angeles and San Francisco Bay Area markets restrict freestanding site expansion, protecting incumbent hospital-affiliated systems. Medi-Cal managed care contracts steer newly insured populations toward contracted urgent care networks. The Central Valley agricultural corridor presents access gaps where independent operators face reimbursement compression from commercial narrow-network strategies.
North Carolina
Medicaid expansion implementation elevates urgent care utilization among newly insured populations in Charlotte and Research Triangle metros. State-level scope-of-practice restrictions for nurse practitioners limit staffing flexibility, forcing reliance on physician labor. The Piedmont Triad industrial corridor generates employer-contracted volume for occupational health and workers' compensation cases.
US Urgent Care Centers Market Key Industry Players
Geographic expansion dominates the current landscape as multi-site operators achieve procurement scale for diagnostic equipment and standardized staffing models. The vendor base clusters around three strategic archetypes: hospital-affiliated networks leveraging existing payer contracts, employer-focused occupational health specialists, and franchise-operated freestanding chains pursuing suburban penetration. Consolidation through health system acquisitions of independent clinic networks accelerates alongside direct contracting between self-insured employers and urgent care operators.
Within the employer-contracted tier, Concentra anchors occupational health integration across industrial corridors. American Family Care exemplifies franchise-operated expansion through multi-state freestanding locations. Fast Pace Health occupies a position in rural and semi-urban markets where hospital-affiliated systems maintain weaker geographic coverage.
| Leading Market Players |
|---|
| Concentra |
| American Family Care |
| Fast Pace Health |
| CityMD Urgent Care |
| WellNow Urgent Care |
| NextCare Urgent Care |
| MedExpress Urgent Care |
| Patient First |
| FastMed Urgent Care |
| Others |
Cost & Logistics Intelligence
Horizontal integration of occupational health and urgent care platforms anchors pricing power for employer-contracted networks across Texas and Florida industrial corridors. This consolidation pattern simultaneously compresses procurement costs for diagnostic equipment and enables episode-based bundled rates that displace traditional fee-for-service intermediaries.
Pricing Analysis
Input-cost pass-through from point-of-care diagnostic equipment and radiologist overread contracts shapes margin structures across freestanding and hospital-affiliated operators. Three-tier pricing structure across premium, standard, and economy levels separates employer-contracted occupational health from individual self-pay and narrow-network commercial volumes. Cost compression in the individual self-pay tier is intensifying because uninsured patients prioritize transparent cash pricing over continuity relationships. Employer-contracted segments exhibit lowest price sensitivity due to direct contracting arrangements that bypass traditional insurance intermediaries.
Supply Chain Analysis
FDA and CMS certification requirements for X-ray equipment, CLIA-waived laboratory devices, and HIPAA-compliant EHR systems create qualification gating that limits vendor pools for urgent care operators. Supply concentration rests on domestic manufacturing for diagnostic imaging equipment, with secondary sourcing from Germany and Japan for specialized radiology components. Raw material dependencies span medical-grade imaging sensors, lithium-ion battery systems for portable equipment, and semiconductor components for telemedicine platforms. Single-source vulnerability runs through specialized radiologist overread networks that serve multiple clinic operators. Distribution runs through direct manufacturer relationships for capital equipment and group purchasing organizations for consumable medical supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as employer-sponsored plans shift demand toward integrated occupational health platforms with OSHA compliance capabilities and transparent episode-based pricing.
For Market Incumbents: Anchor market position through EHR interoperability investments that satisfy state health information exchange mandates and qualify operators for narrow-network commercial contracts. Pursue backward integration into point-of-care diagnostic equipment servicing to capture recurring revenue streams and reduce capital replacement cyclicality. Defensive consolidation of independent freestanding networks in Texas and Florida suburbs will preempt emerging regional chains from achieving procurement scale. For New Entrants and Emerging Players: Rural counties in Appalachia and the Mississippi Delta present white-space targets where hospital-affiliated systems maintain weak geographic coverage and physician shortages strain traditional primary care access. Self-insured employers in manufacturing corridors offer the most penetrable buyer archetype through direct contracting models that displace traditional insurance intermediaries. A telemedicine-first hybrid protocol with virtual triage capabilities enables market entry without proportional capital expenditure on physical site development. For Investors and Strategic Acquirers: Roll-up economics work for multi-site urgent care operators because certificate-of-need regulations in New York, California, and Illinois create regulatory moats protecting incumbent positions while leaving fragmented independent networks in unregulated states. Long-term viability centers on platforms with demonstrated employer-contracted revenue stability and occupational health integration capabilities. The signal to watch is Medicaid expansion trajectories in holdout states, which would elevate utilization among newly insured populations and reshape volume distribution between urgent care and emergency department alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Occupational Health Platform Integration | OSHA workplace health standards drive employer-contracted clinic networks across industrial corridors. |
| Telemedicine-EHR Convergence | HIPAA interoperability mandates accelerate hybrid care model adoption in Arizona and Texas health systems. |
| Freestanding Network Acquisition | Hospital systems consolidate market share by acquiring independent clinics in Florida and Texas suburbs. |
| Direct Employer Contracting | Self-insured companies in manufacturing corridors bypass traditional insurance intermediaries for episode-based rates. |
| Rural Market Penetration | Underserved counties in Appalachia present white-space opportunities with weaker hospital-affiliated coverage. |
Research Approach
Bottom-up employer-contracted volume modeling reconciled against top-down diagnostic equipment procurement tracking forms the analytical core of this study. Primary interviews with urgent care network executives, occupational health contract managers at self-insured employers, hospital system strategy officers, and CMS policy specialists combined with secondary validation from CMS Medicare cost reports, state certificate-of-need filings, OSHA workplace health compliance databases, and commercial payer narrow-network disclosures. Triangulation across these sources ensures segmentation integrity for freestanding, hospital-affiliated, and employer-contracted operational models.
Input-output matrix framing connects site-level utilization assumptions to macro-level reimbursement trends across the projection horizon. Segmentation dimensions modeled include ownership structure, service line breadth, payer category, and technology infrastructure maturity, with geographic regulatory clusters capturing state-level certificate-of-need and scope-of-practice variation. CAGRs derive from reconciliation of bottom-up site development pipelines against top-down Medicare Advantage penetration and employer-sponsored plan expansion trajectories. Forecast inputs incorporate CMS value-based reimbursement shift rates and telemedicine adoption curves by state health information exchange maturity.
Underlying measurement precision varies by segment; employer-contracted volumes carry tighter precision than individual self-pay estimates due to contract disclosure requirements. Forecasts reflect assumptions about Medicaid expansion timing, commercial narrow-network strategies, and diagnostic equipment procurement cycles that could revise trajectories upon material policy or reimbursement shifts. A model refresh is warranted upon material change in CMS value-based care mandate implementation schedules or state-level certificate-of-need regulatory amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
Adrenal Crisis Management Market