
 South East Asia Ambulance Services Market | 2026-2036
South East Asia Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
South East Asia Ambulance Services Market Analytics
Subscription-based fleet maintenance contracts is repositioning how ambulance operators monetize vehicle uptime across South East Asia. Hope Ambulances leverages long-term service agreements with provincial health departments to lock in recurring revenue. Asia Medvac Services anchors its model on air-ambulance retainers for corporate mining and energy clients in remote Indonesian archipelagos. Ziqitza Healthcare competes through integrated emergency call-center and dispatch software that reduces average response intervals.
Ambulance services encompass ground and air-based patient transport vehicles equipped with life-support systems, stretcher mechanisms, and medical monitoring devices designed for pre-hospital emergency care and inter-facility transfers. These vehicles integrate oxygen delivery, defibrillation, and ventilation equipment to stabilize patients during transit from incident sites to healthcare facilities. Emergency service contracts dominate revenue pools across the region, while air ambulance segments capture premium pricing for remote-island and cross-border evacuations. Non-emergency patient transport represents a maturing category where public health agencies and private hospitals negotiate bulk-rate agreements for scheduled dialysis and post-surgical transfers.
Malaysia's Ministry of Health, Indonesia's Ministry of Health, and Thailand's National Institute for Emergency Medicine enforce ambulance equipment standards and operator licensing that determine market access for private providers. These regulators mandate GPS tracking integration and minimum crew certification levels that elevate capital requirements for new entrants. Stakeholders must monitor evolving telemedicine reimbursement policies and provincial decentralization of emergency procurement authority across the region.
Market Dynamics
Private hospital networks across Indonesia, Thailand, and Vietnam are consolidating emergency transport procurement under multi-year service agreements, compressing vendor fragmentation and elevating fleet certification requirements as the dominant market-shaping force.
Growth Catalysts
- Malaysia's Ministry of Health ambulance certification standards:Tightening vehicle equipment mandates force fleet modernization, creating replacement demand for GPS-integrated units and advanced life-support platforms across private operators.
- Metropolitan corridor congestion:Bangkok, Jakarta, and Manila traffic patterns amplify rapid-response capability requirements, driving investment in motorcycle-based first-response units and dedicated ambulance lanes.
- Air ambulance retainers:Corporate mining and energy clients in remote Indonesian archipelagos contract fixed-availability emergency evacuation services, expanding premium service revenue pools beyond ground transport.
Market Restraints
- Specialized vehicle chassis supply:European and Japanese commercial vehicle manufacturers control ambulance-specific chassis production, exposing operators to import duty volatility and extended delivery timelines.
- Medical crew certification requirements:Thailand's National Institute for Emergency Medicine mandates paramedic licensing tiers that extend hiring timelines and elevate training costs for new market entrants.
- Telemedicine reimbursement uncertainty:Provincial health authorities across the region lack standardized protocols for reimbursing remote patient monitoring during transit, constraining technology adoption.
Strategic Opportunities
- Vietnam's provincial decentralization:Emergency procurement authority shifting to municipal governments creates entry points for regional operators to secure district-level service contracts outside Ho Chi Minh City and Hanoi.
- Subscription-based fleet maintenance:Long-term service agreements with provincial health departments lock in recurring revenue streams and reduce customer acquisition costs for established providers.
- Non-emergency patient transport maturation:Scheduled dialysis and post-surgical transfer contracts represent underexploited volume as public health agencies negotiate bulk-rate agreements with private hospitals.
Industry Challenges
- Paramedic workforce scarcity:Indonesia's Ministry of Health licensing requirements outpace training program output, creating crew availability bottlenecks during peak demand periods.
- Telemedicine-legacy dispatch integration:Provincial emergency call centers operate on fragmented software platforms, complicating unified patient data flow from initial contact through hospital handoff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South East Asia Ambulance Services Market |
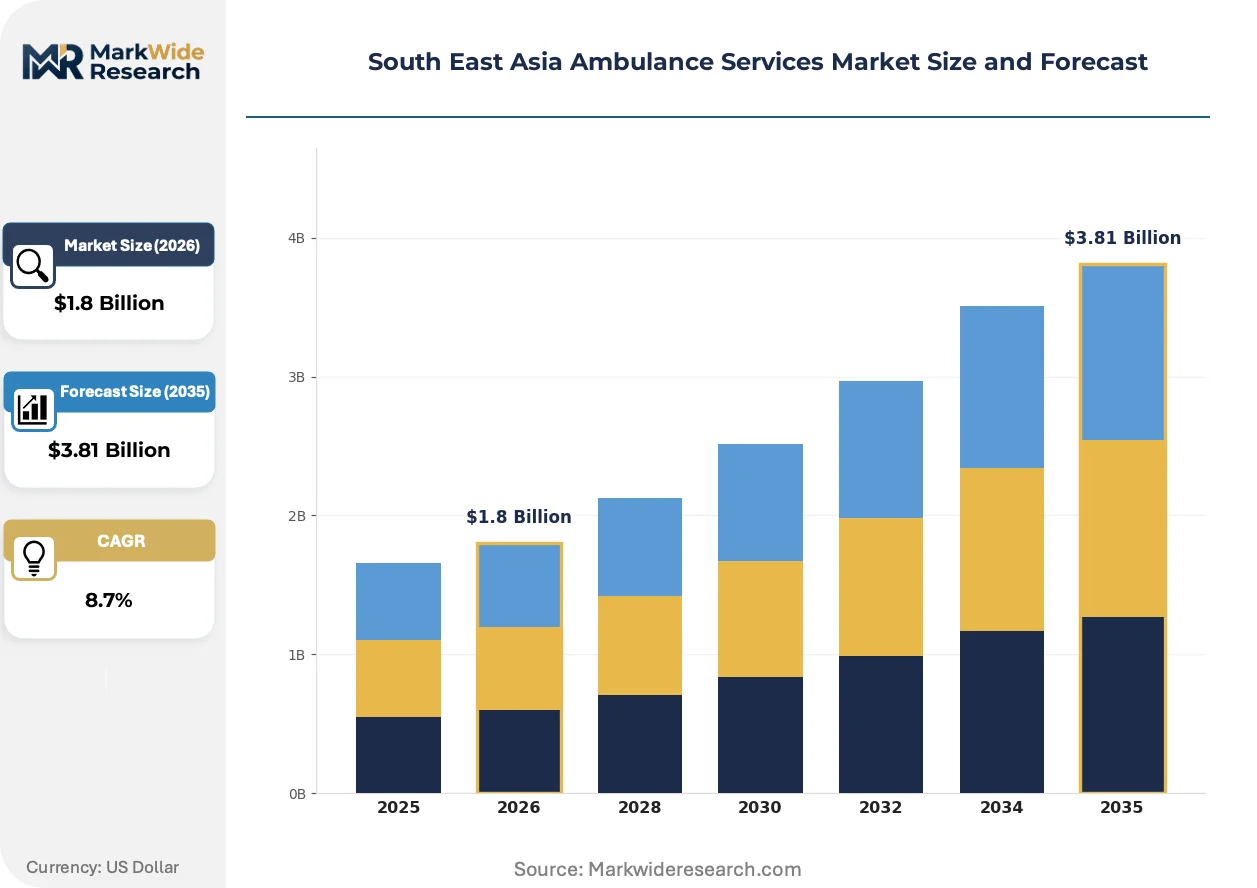
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency, Non-Emergency, Inter-Facility, Air Ambulance Vehicle Type: Basic Life Support, Advanced Life Support, Patient Transport, Wheelchair Accessible Customer Type: Public Health Agencies, Private Hospitals, Insurance Companies, Corporate Clients Technology: Telemedicine, GPS Tracking, Mobile Apps, Communication Systems |
| Companies Covered | Medical Air Services, Emsos Medicals, Hope Ambulances, MUrgency, Red Ambulance Services, Asia Medvac Services, First Ambulance, Ziqitza Healthcare, Prime Air Ambulances, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South East Asia Ambulance Services Market Evolving Landscape
Telemedicine integration and real-time patient data transmission are compressing response-to-treatment timelines across South East Asia's emergency transport networks, reshaping competitive differentiation beyond vehicle speed alone.
Telemedicine-enabled ambulance units are unifying pre-hospital diagnostics with hospital triage protocols. Private hospital networks in Thailand and Malaysia deploy these platforms to reduce emergency department congestion. The technology is unifying dispatch, clinical decision support, and bed management into continuous care workflows that compress handoff delays.
Indonesia's Ministry of Health mandates GPS tracking integration for all privately operated ambulances serving public health contracts. The regulation forces fleet operators to retire non-compliant vehicles or retrofit legacy units with certified tracking hardware. Operators in Jakarta and Surabaya face compressed compliance deadlines, accelerating capital deployment toward connected vehicle platforms.
Corporate buyers in mining and energy sectors now specify outcome-based availability metrics rather than per-trip pricing. Fixed monthly retainers for guaranteed response times displace traditional fee-for-service contracts in remote Indonesian operations. This model concentrates most visibly in Papua and Kalimantan, where evacuation distances exceed standard ground transport range.
South East Asia Ambulance Services Market Segmentation
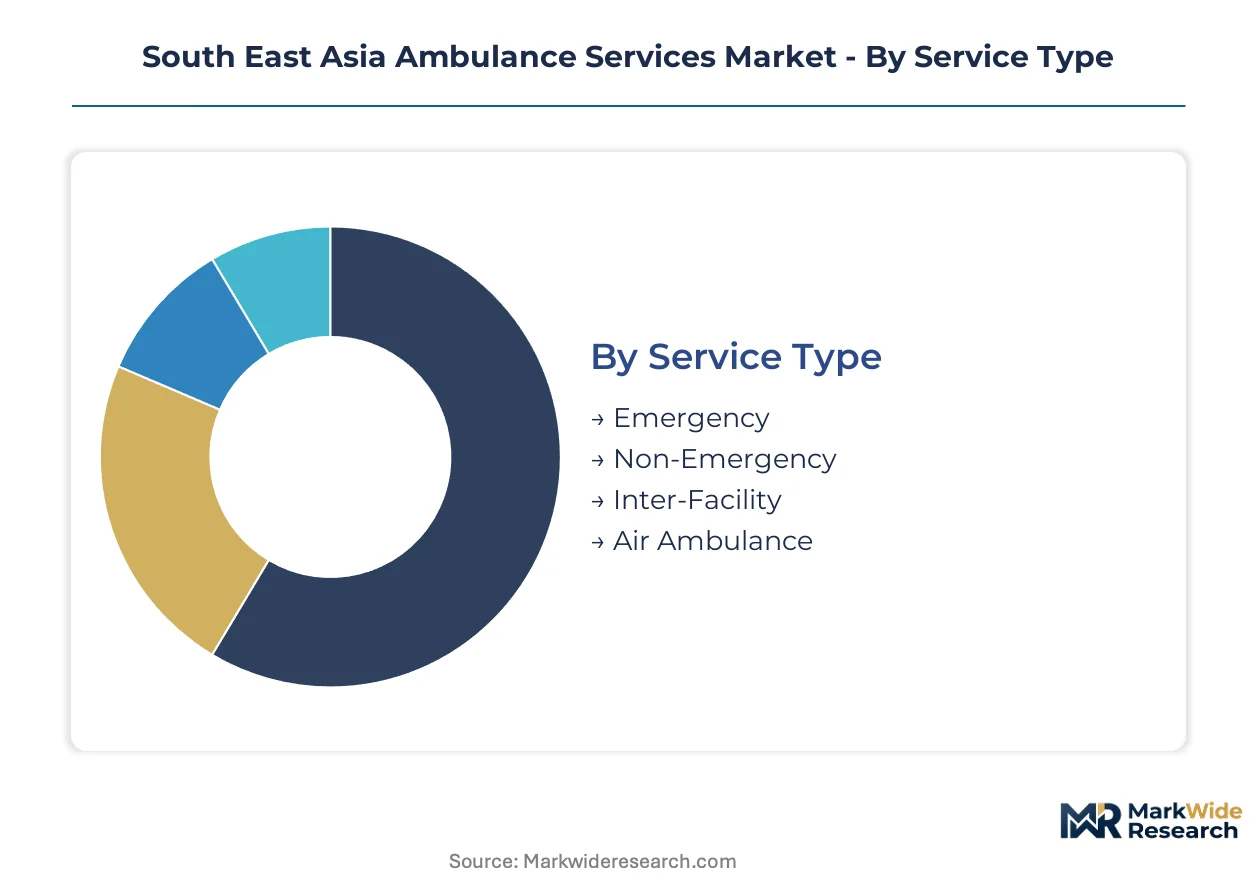
Segmentation in South East Asia's ambulance services market reveals how procurement authority, vehicle specification tiers, and connectivity infrastructure determine contract profitability and operational scalability across diverse metropolitan and archipelago geographies.
Service Type:
Technology integration intensity varies sharply across service modalities, with life-support sophistication and response-time guarantees defining contract pricing structures.
- Emergency:Vehicles equipped with defibrillation, ventilation, and advanced cardiac monitoring systems stabilize patients during golden-hour transport from incident sites to tertiary facilities. Demand concentrates in Bangkok, Jakarta, and Manila where traffic congestion compresses response windows and elevates motorcycle-based first-responder deployment.
- Air Ambulance:Fixed-wing and rotary-wing platforms with pressurized cabins and intensive-care equipment enable evacuation from remote Indonesian mining sites and island chains beyond ground transport range. Corporate retainers from Papua and Kalimantan energy operations anchor premium revenue pools through outcome-based availability contracts.
- Non-Emergency:Scheduled dialysis and post-surgical transfers utilize basic monitoring equipment for stable patients between facilities.
- Inter-Facility:Transfers between hospitals for specialized procedures require consistent life-support continuity.
Emergency services lead on scale; air ambulance leads on momentum.
Vehicle Type:
Capital deployment intensity tracks clinical capability tiers, with regulatory certification mandates from Malaysia's Ministry of Health and Indonesia's Ministry of Health forcing fleet modernization cycles.
- Advanced Life Support:Intensive-care platforms integrate multi-parameter monitors, ventilators, and infusion pumps for critical patients requiring continuous intervention during transit. Private hospital networks in Thailand and Vietnam consolidate procurement under multi-year agreements that specify ALS unit percentages.
- Basic Life Support:Oxygen delivery, automated external defibrillation, and trauma stabilization equipment serve non-critical emergency and inter-facility transfers. Provincial health departments across Vietnam negotiate bulk-rate BLS contracts as municipal procurement authority decentralizes outside Ho Chi Minh City and Hanoi.
- Patient Transport:Stretcher-equipped vehicles without active intervention capability move stable patients.
- Wheelchair Accessible:Modified vans with lift mechanisms serve mobility-impaired non-emergency demand.
Advanced Life Support commands margin concentration; Basic Life Support captures volume expansion.
Customer Type:
Contract duration and payment security diverge across buyer categories, with public procurement cycles and corporate risk management priorities shaping operator cash flow predictability.
- Public Health Agencies:Malaysia's Ministry of Health and Indonesia's Ministry of Health tender multi-year emergency service agreements with GPS tracking mandates and minimum crew certification requirements. Subscription-based fleet maintenance contracts with provincial departments generate recurring revenue that reduces customer acquisition costs for established operators.
- Private Hospitals:Consolidated procurement under outsourced emergency transport contracts across Indonesia, Thailand, and Vietnam compresses vendor fragmentation and elevates fleet certification standards.
- Insurance Companies:Third-party administrators negotiate per-incident rates for policyholder emergency transport.
- Corporate Clients:Mining and energy sector buyers specify guaranteed response-time retainers rather than per-trip pricing.
Public Health Agencies anchor contract stability; Corporate Clients drive pricing model innovation.
Technology:
Connectivity infrastructure investment separates compliance-driven baseline capabilities from competitive differentiation through real-time clinical integration.
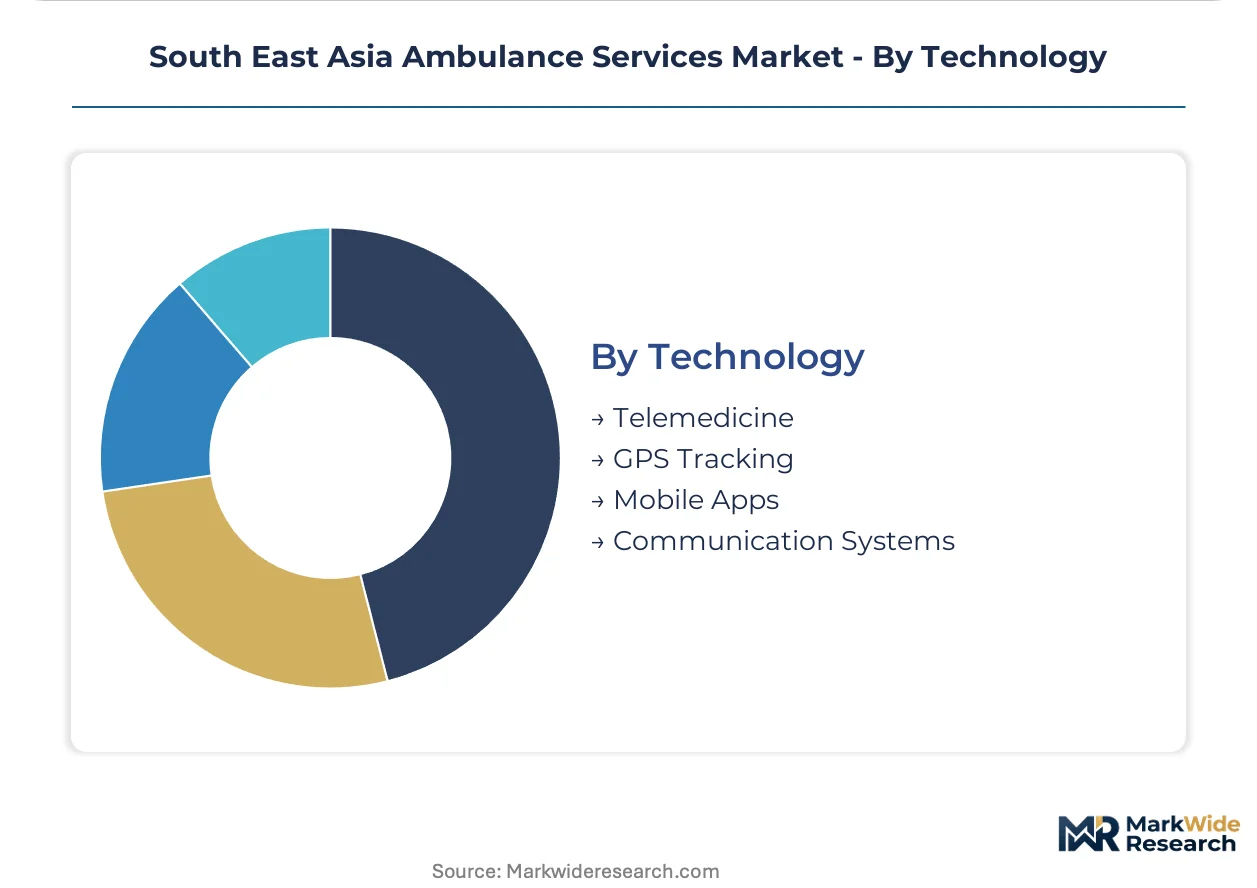
- Telemedicine:Pre-hospital diagnostic transmission and video consultation with emergency physicians compress treatment initiation timelines. Private hospital networks in Thailand deploy these platforms to reduce emergency department congestion and unify dispatch with bed management workflows.
- GPS Tracking:Indonesia's Ministry of Health mandates certified tracking hardware integration for all private ambulances serving public contracts, forcing Jakarta and Surabaya operators to retire non-compliant vehicles or accelerate retrofit capital deployment.
- Mobile Apps:Consumer-facing dispatch interfaces enable direct emergency requests bypassing traditional call centers.
- Communication Systems:Radio and cellular redundancy ensures connectivity across archipelago geographies with uneven infrastructure coverage.
GPS Tracking leads on regulatory compulsion; telemedicine leads on clinical value creation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping competitive positioning across South East Asia's ambulance services sector, with operators migrating fleet assets toward jurisdictions where certification costs remain lower while service premiums hold steady. Malaysia's tightening equipment mandates are accelerating capital flight toward Indonesian and Vietnamese markets where compliance timelines remain more permissive.
Indonesia
Archipelago geography and mining-sector evacuation contracts drive demand for rotary-wing platforms across Papua and Kalimantan. The Ministry of Health mandates GPS tracking integration for all private ambulances serving public contracts, forcing Jakarta and Surabaya operators into accelerated fleet modernization cycles. Provincial procurement authority decentralization is creating district-level contract opportunities outside Java's dominant metros.
Thailand
Bangkok's traffic congestion patterns amplify rapid-response capability requirements, elevating motorcycle-based first-responder deployment and dedicated ambulance lane infrastructure. The National Institute for Emergency Medicine enforces paramedic licensing tiers that extend hiring timelines for new market entrants. Private hospital networks in Greater Bangkok consolidate emergency transport procurement under multi-year service agreements.
Malaysia
The Ministry of Health's ambulance certification standards are tightening vehicle equipment requirements, creating replacement demand for GPS-integrated units and advanced life-support platforms. Kuala Lumpur's private operators face compressed compliance deadlines that accelerate capital deployment toward connected vehicle platforms. Subscription-based fleet maintenance contracts with provincial health departments generate recurring revenue for established providers.
Vietnam
Emergency procurement authority shifting to municipal governments creates entry points for regional operators to secure district-level service contracts. Ho Chi Minh City and Hanoi anchor demand concentration, though decentralization is opening secondary urban corridors. Provincial health departments negotiate bulk-rate agreements for basic life support contracts as municipal autonomy expands.
Philippines
Manila's metropolitan congestion patterns mirror Bangkok's rapid-response infrastructure challenges, driving investment in traffic-bypass capabilities. The Department of Health maintains fragmented regulatory oversight across island provinces, creating compliance cost differentials that attract cross-border operators. Cebu and Davao emerge as secondary demand clusters where private hospital networks consolidate outsourced emergency transport procurement.
South East Asia Ambulance Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated emergency service providers commanding premium positioning against fragmented regional operators. Market structure exhibits moderate consolidation at the top tier where multi-service networks control metropolitan corridor contracts, while provincial and rural markets sustain numerous single-city operators. Three archetypes dominate: vertically integrated hospital-affiliated fleets, standalone emergency service specialists, and air-ambulance operators serving remote-resource extraction sites. Competitive dynamics center on multi-year service agreement capture and fleet certification compliance rather than price-based rivalry.
Within the integrated service tier, Ziqitza Healthcare and Hope Ambulances exemplify operators anchoring market position through long-term provincial health department relationships. Asia Medvac Services occupies a distinct niche representing the air-ambulance specialist archetype, with corporate retainers from remote Indonesian operations sustaining premium pricing power. These three entities collectively illustrate how technology integration and contract duration serve as the primary vectors for competitive differentiation across South East Asia's emergency transport sector.
| Leading Market Players |
|---|
| Medical Air Services |
| Emsos Medicals |
| Hope Ambulances |
| MUrgency |
| Red Ambulance Services |
| Asia Medvac Services |
| First Ambulance |
| Ziqitza Healthcare |
| Prime Air Ambulances |
| Others |
Value Network & Pricing Analysis
European and Japanese commercial vehicle chassis costs cascade through three distinct pricing tiers as specialized ambulance modifications compound import duty exposure and extend delivery timelines for Southeast Asian fleet operators.
Pricing Analysis
Distributor margins on European chassis imports absorb 12-18% of landed vehicle costs before provincial health departments negotiate multi-year service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under Malaysia's Ministry of Health mandates and crew training tier requirements. Pricing pressure stems from telemedicine reimbursement uncertainty constraining technology adoption budgets. Public health agencies exhibit highest price sensitivity due to fixed provincial budget allocations, while corporate mining clients in Indonesian archipelagos accept premium retainers for guaranteed response-time contracts.
Supply Chain Analysis
Paramedic workforce availability in Thailand, Indonesia, and Vietnam constrains fleet expansion velocity as training program output lags Ministry of Health licensing requirements. Specialized vehicle chassis production draws from Germany, Japan, and South Korea, with oxygen delivery systems and defibrillation equipment sourced from US and EU medical device manufacturers. Single-source vulnerability concentrates in European chassis suppliers where extended order-to-delivery timelines expose operators to contract fulfillment risk. Distribution runs through hospital network procurement committees and provincial health department tender processes, with air ambulance operators maintaining direct corporate relationships in remote resource extraction zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Southeast Asian ambulance services hinges on subscription-based fleet maintenance contracts that convert capital-intensive vehicle replacement cycles into predictable recurring revenue streams.
For Market Incumbents: Deploy telemedicine integration as the primary defensive lever against emerging digital health platforms. Ziqitza Healthcare's dispatch software advantage demonstrates how real-time patient data transmission compresses response-to-treatment timelines and locks in hospital network loyalty. Incumbents should accelerate GPS tracking retrofit programs ahead of Indonesia's Ministry of Health compliance deadlines to capture competitor fleet obsolescence. Certification investment in advanced life-support platforms creates switching costs that defend municipal contract renewals against regional challengers.
For New Entrants and Emerging Players: Vietnam's provincial decentralization of emergency procurement authority opens a window for district-level contract capture outside Ho Chi Minh City and Hanoi saturation. Municipal governments now negotiate bulk-rate basic life support agreements with reduced certification barriers compared to national tenders. Target secondary urban corridors where traffic congestion patterns mirror Bangkok's rapid-response infrastructure gaps but competitor density remains thin. A go-to-market angle anchored on motorcycle-based first-responder units addresses metropolitan corridor congestion where traditional ambulance deployment fails.
For Investors and Strategic Acquirers: Consolidation pressure builds where provincial procurement fragmentation meets tightening equipment mandates that elevate capital requirements beyond standalone operator capacity. Long-term viability favors vertically integrated networks controlling dispatch software, fleet maintenance capabilities, and multi-province contract portfolios. Acquisition targets should display established relationships with Malaysia's Ministry of Health or Indonesia's Ministry of Health alongside scalable telemedicine platforms. Watch for provincial reimbursement policy clarity on remote patient monitoring as the signal indicating technology adoption acceleration and valuation multiple expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Platform Deployment | Thailand's private hospital networks reduce emergency department congestion through unified dispatch-bed management workflows. |
| Subscription Fleet Maintenance Contracts | Hope Ambulances locks recurring revenue with provincial health departments while reducing customer acquisition costs. |
| Air Ambulance Retainer Expansion | Asia Medvac Services captures premium pricing in Papua and Kalimantan through outcome-based availability metrics. |
| GPS Tracking Compliance Acceleration | Jakarta and Surabaya operators retire non-compliant vehicles ahead of Indonesia's Ministry of Health deadlines. |
| Provincial Decentralization Entry | Vietnam's municipal governments create district-level contract opportunities beyond Ho Chi Minh City and Hanoi dominance. |
Research Methodology
Multiple input streams — ambulance fleet operator interviews, provincial health department procurement officers, hospital network contracting leads, and medical device distribution channel partners — were reconciled against regulatory filings from Malaysia's Ministry of Health, Indonesia's Ministry of Health, and Thailand's National Institute for Emergency Medicine. Secondary validation incorporated emergency services tender databases, hospital procurement records, and commercial vehicle import customs data. Bottom-up fleet capacity estimates and top-down healthcare expenditure allocations were triangulated to constrain projection variance.
Data-stream reconciliation across service type, vehicle specification tier, customer category, and technology integration intensity enabled segmented growth trajectory modeling over the projection horizon. CAGRs were derived from historical contract value analysis and forward-looking procurement pipeline assessment. Forecast inputs included paramedic workforce expansion rates, chassis delivery timeline projections, and provincial decentralization implementation schedules across Vietnam and Indonesia.
Revisions become necessary when telemedicine reimbursement protocols crystallize, provincial procurement authority shifts accelerate, or European chassis supply disruptions materialize. Forecasts reflect documented assumptions regarding regulatory compliance timelines and municipal budget allocation stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Urgent Care Centers Market