
 Resuscitation Trolley Market | 2026-2036
Resuscitation Trolley Market Size, Share, and Industry Trends Forecast 2026-2036
Resuscitation Trolley Market Analytics
Preventive maintenance contracts and software-enabled fleet tracking is pivoting vendor revenue models from one-time equipment sales toward recurring service agreements. Stryker Corporation leverages its direct hospital service infrastructure to lock in multi-year maintenance bundles. Medline Industries, Inc. anchors its competitive stance through scale advantages in distribution and private-label consumable pairing. Capsa Healthcare differentiates via specialized medication-cart integration that extends trolley utility beyond resuscitation scenarios.
A resuscitation trolley is a mobile medical cart engineered for emergency cardiac and respiratory intervention, typically fabricated from aluminum or composite materials with breakaway wheels and lockable drawer configurations to secure defibrillators, airway kits, and emergency pharmaceuticals. Electric trolleys command premium positioning due to motorized height adjustment and integrated power systems, while manual variants retain volume dominance in cost-sensitive clinic environments. Emergency Medical Services represents the fastest-growing end-user channel as pre-hospital care systems upgrade mobile intervention capabilities.
The FDA enforces Unique Device Identification requirements that compel manufacturers to embed traceable digital identifiers, while ISO 13485 quality management standards govern design and production protocols for medical device classification. Health system procurement officers must evaluate total cost-of-ownership metrics that incorporate software licensing, calibration cycles, and regulatory re-certification intervals rather than acquisition price alone.
Market Dynamics
Hospital emergency departments are expanding trolley fleets to meet stricter crash-cart readiness protocols, while the FDA's Unique Device Identification mandate pushes manufacturers toward integrated digital tracking modules. This dual pressure is compressing product lifecycles and elevating software-enabled service contracts as the dominant revenue architecture.
Growth Catalysts
- FDA UDI Mandate:The Unique Device Identification requirement compels embedded traceable digital identifiers, forcing hospital systems to refresh legacy fleets and creating replacement demand across acute care networks.
- Pre-hospital Care Upgrades:Emergency Medical Services represents the fastest-growing end-user channel as mobile intervention capabilities expand beyond traditional hospital walls into ambulance and field deployment.
- Health System Consolidation:Multi-hospital networks in the United States are driving standardized procurement, concentrating purchase volumes and favoring vendors with fleet-management software platforms.
Market Restraints
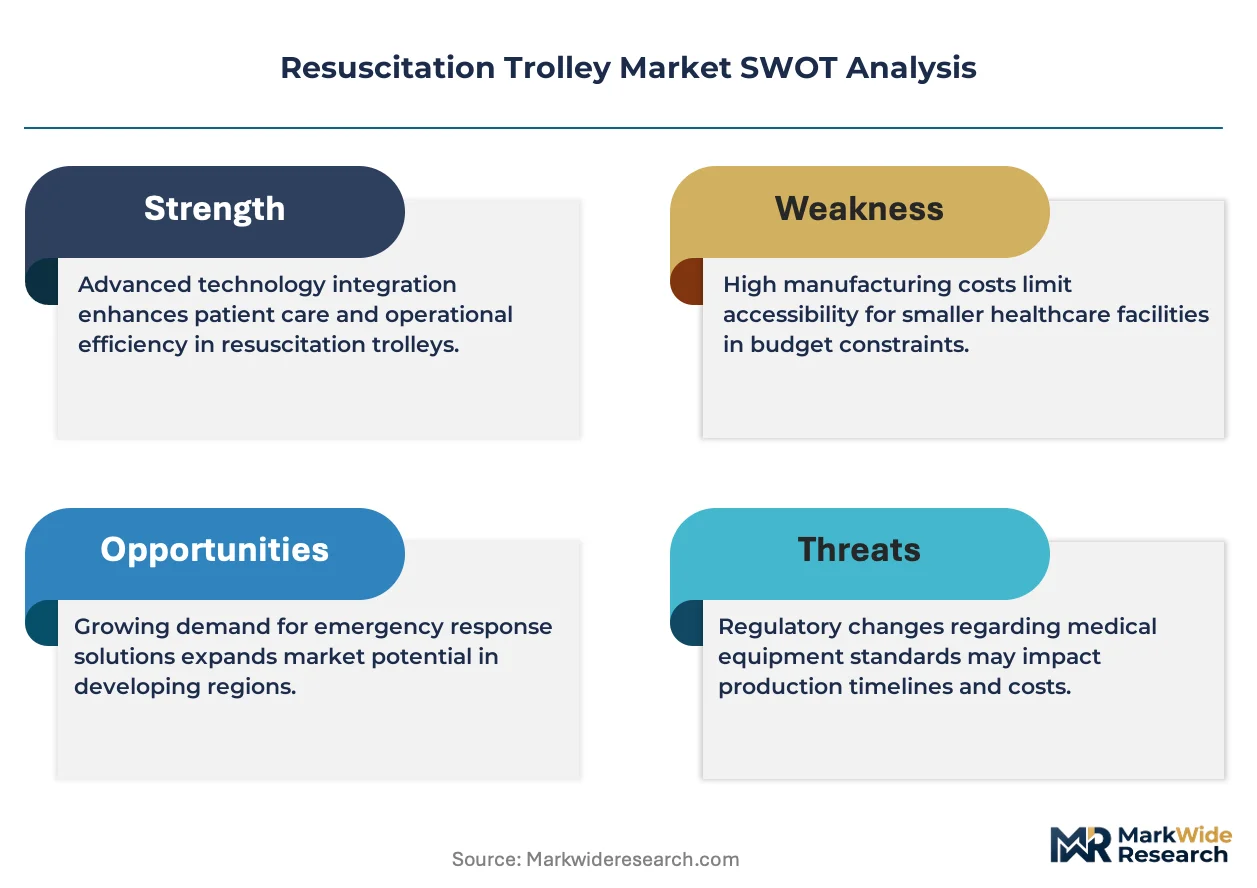
- Aluminum Input Volatility:Primary trolley fabrication materials face commodity price swings that compress manufacturer margins on fixed-price contract bids.
- ISO 13485 Certification Burden:Quality management compliance for medical device classification extends development timelines and elevates fixed regulatory costs for new market entrants.
- Manual Trolley Substitution:Cost-sensitive clinic environments retain volume dominance of non-electric variants, capping premium product penetration in ambulatory settings.
Strategic Opportunities
- Medication-Cart Convergence:Specialized integration extending trolley utility beyond resuscitation into anesthesia and pharmacy workflows opens adjacent revenue streams.
- Preventive Maintenance Contracts:Recurring service agreements pivot vendor economics from one-time equipment sales toward multi-year revenue visibility.
- Electric Trolley Premiumization:Motorized height adjustment and integrated power systems command price premiums in tertiary hospital emergency departments.
Industry Challenges
- Calibration Cycle Management:Health system procurement officers must evaluate total cost-of-ownership metrics incorporating software licensing and regulatory re-certification intervals.
- Legacy System Integration:Digital tracking modules face interoperability friction with existing hospital asset management platforms, extending deployment timelines.
- Service Infrastructure Scaling:Direct hospital service networks require capital-intensive geographic expansion to support multi-year maintenance bundle commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resuscitation Trolley Market |
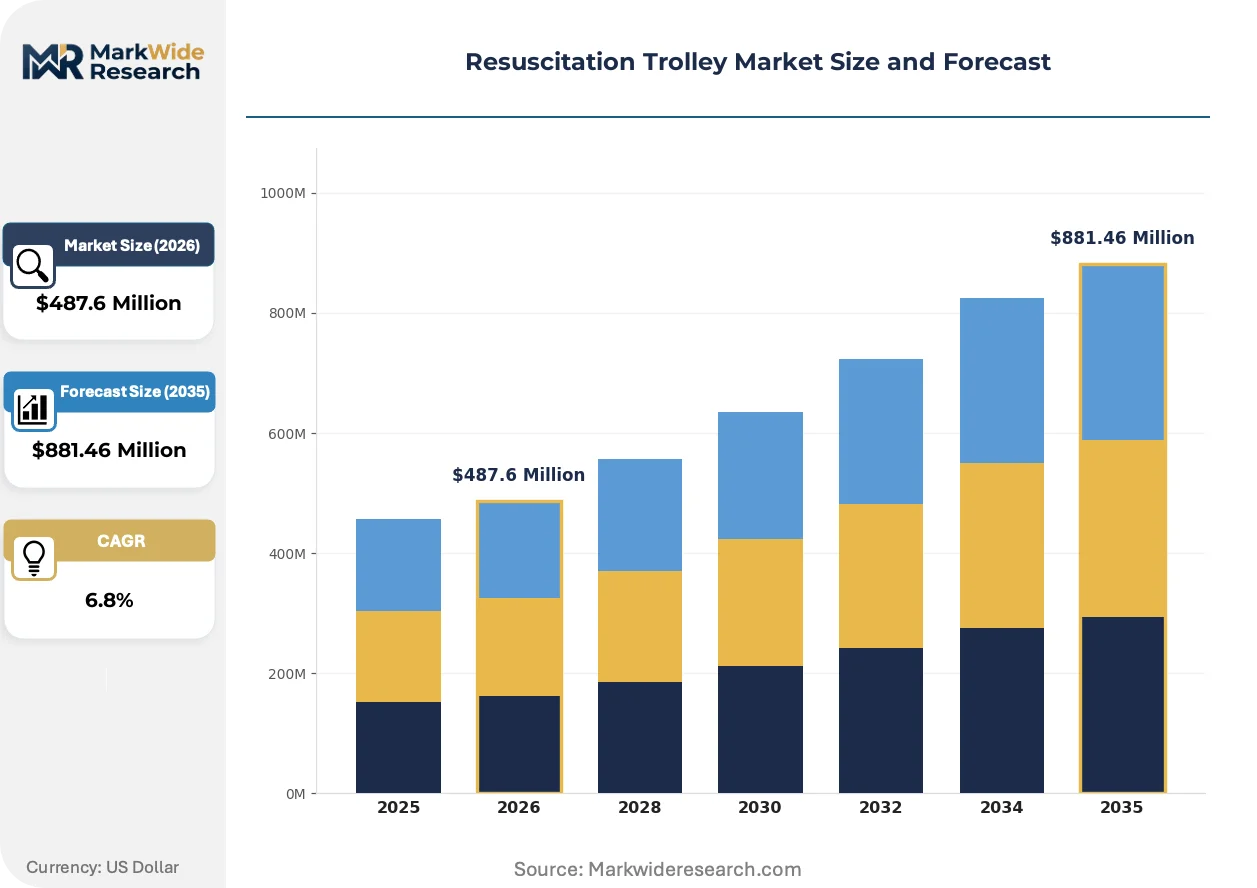
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Trolley, Electric Trolley, Custom Trolley, Mobile Trolley End User: Hospitals, Clinics, Emergency Medical Services, Medical Training Centers Material: Steel, Aluminum, Plastic, Composite Features: Breakaway Wheels, Lockable Drawers, Adjustable Height, Compact Design |
| Companies Covered | Capsa Healthcare, Harloff Manufacturing Co., Medline Industries, Inc., Arjo, Haeberle, Malvestio, Allibert Medical, Stryker Corporation, Electro Kinetic Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resuscitation Trolley Market Evolving Landscape
Digital traceability and modular utility are reshaping how resuscitation trolleys are specified, purchased, and deployed across acute care environments. Three distinct vectors are compressing traditional equipment refresh cycles.
RFID-enabled asset tracking is integrating with fleet management software to automate location monitoring and maintenance scheduling. Hospital systems adopting these modules are compressing equipment search times and reducing compliance audit preparation. The technology is integrating preventive maintenance workflows directly into clinical operations, elevating software vendors to strategic supplier status.
The FDA enforces Unique Device Identification requirements that embed machine-readable identifiers on every device. This industrial consequence eliminates anonymous equipment in hospital inventories and mandates digital pedigree documentation. Emergency departments and surgical suites face the most acute compliance pressure, responding with accelerated replacement of non-compliant legacy trolleys.
Acute care buyers now unbundle equipment acquisition from ongoing service obligations, evaluating vendors on calibration responsiveness and software update cadence. Traditional distributor relationships face displacement by manufacturers with captive service infrastructure. This pattern concentrates in United States health systems where consolidation has centralized procurement authority.
Resuscitation Trolley Market Segmentation
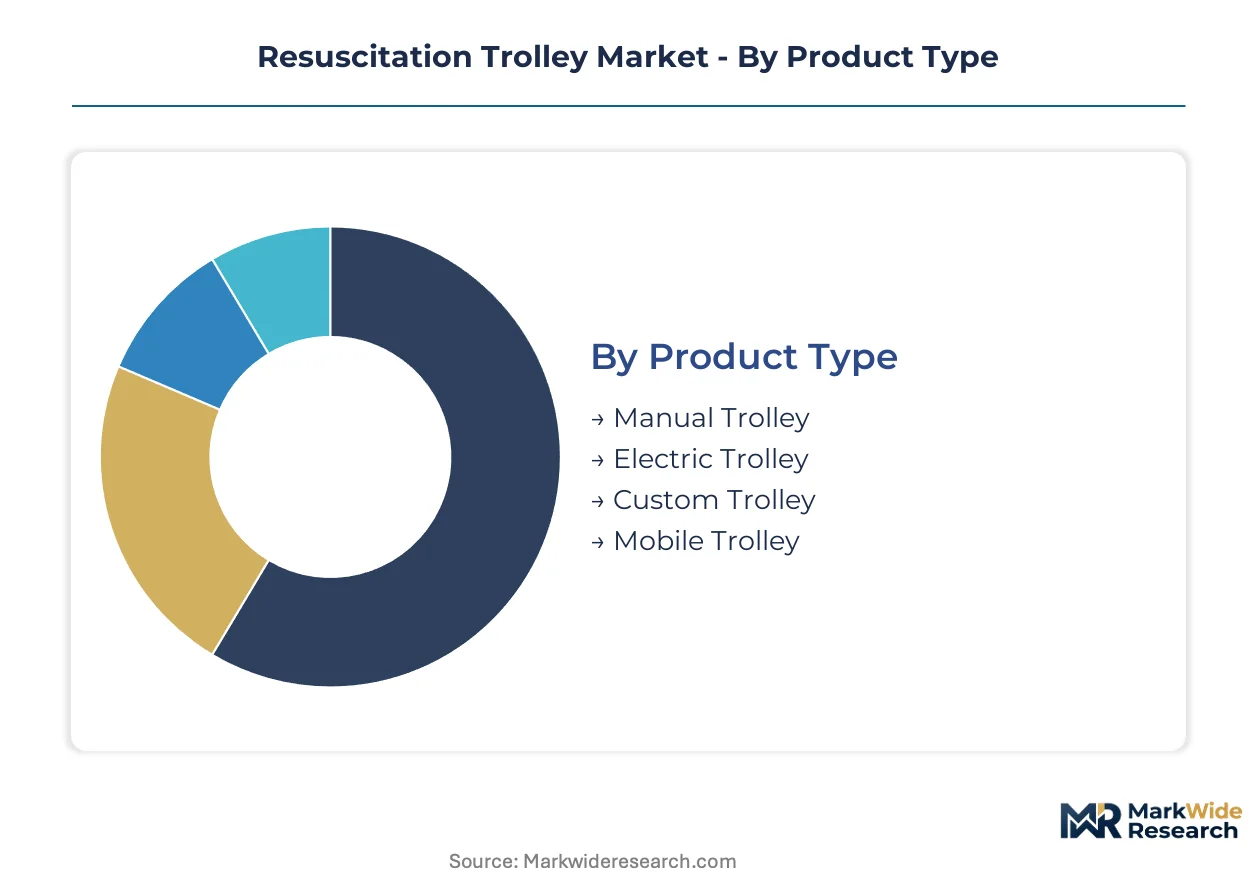
Resuscitation trolley procurement varies sharply by clinical setting and operational intensity. Product specifications diverge between stationary hospital emergency departments and mobile pre-hospital deployment, while material selection trades off durability against weight constraints for rapid maneuverability.
Product Type:
Standalone trolleys dominate acute care installations, while embedded or integrated systems serve specialized anesthesia and pharmacy workflows requiring seamless equipment convergence.
- Manual Trolley:Non-motorized units fabricated from aluminum or steel with mechanical height adjustment and caster-based mobility. Cost-sensitive clinic environments in the United States retain volume dominance of this variant, though fixed-price contract exposure to aluminum commodity swings compresses manufacturer margins.
- Electric Trolley:Motorized platforms with integrated power systems enabling push-button height adjustment and battery-backed device charging. Tertiary hospital emergency departments command premium positioning here, driven by stricter crash-cart readiness protocols and staff ergonomics requirements.
- Custom Trolley:Purpose-built configurations tailored to specific department workflows or equipment combinations. Bespoke fabrication extends lead times but addresses non-standard spatial constraints in older hospital infrastructure.
- Mobile Trolley:Lightweight variants optimized for rapid deployment across multiple clinical zones within a facility. Rapid-response teams favor these for flexibility during mass-casualty events or code-blue scenarios.
Volume placements concentrate in Manual Trolley configurations; the faster expansion belongs to Electric Trolley systems as health systems consolidate procurement around standardized premium fleets.
End User:
Procurement authority clusters differently across customer types, with consolidated health networks driving standardized fleet decisions while fragmented ambulatory settings favor distributor relationships.
- Hospitals:Acute care institutions with emergency departments, surgical suites, and intensive care units requiring 24/7 crash-cart readiness. Multi-hospital networks in the United States are driving standardized procurement, concentrating purchase volumes and elevating software-enabled fleet management platforms to strategic supplier status.
- Clinics:Outpatient and ambulatory settings with lower intervention intensity and tighter capital constraints. Manual variants retain dominance here, capping premium product penetration outside tertiary care environments.
- Emergency Medical Services:Pre-hospital care systems including ambulance fleets and field response units. This channel is climbing the fastest as mobile intervention capabilities expand beyond traditional hospital walls, with lightweight materials and compact designs prioritized for vehicle integration.
- Medical Training Centers:Educational institutions and simulation facilities requiring replicated clinical environments for student instruction. These buyers prioritize durability under repeated use and compatibility with standardized training curricula.
Revenue concentration sits with Hospitals; Emergency Medical Services delivers the steepest expansion trajectory as regional ambulance authorities modernize equipment.
Material:
Supply-side input costs and clinical weight requirements create divergent margin profiles across fabrication choices, with commodity-exposed metals facing pricing volatility.
- Steel:High-strength ferrous alloys offering maximum structural durability and load capacity. Heavy-duty hospital installations favor this material for defibrillator and ventilator support, though weight penalties limit mobility applications.
- Aluminum:Lightweight non-ferrous metal with favorable strength-to-weight ratios and corrosion resistance. Primary fabrication material facing commodity price swings that compress manufacturer margins on fixed-price contract bids, particularly affecting high-volume clinic supply.
- Plastic:Polymer-based construction for cost-minimized or single-use scenarios. Limited to training and simulation environments where sterilization cycles are less frequent.
- Composite:Engineered material blends combining fiber reinforcement with resin matrices. Emerging preference for Emergency Medical Services applications demanding maximum strength at minimum weight for field deployment.
Steel captures the largest installed base; Composite materials are gaining share fastest in pre-hospital segments.
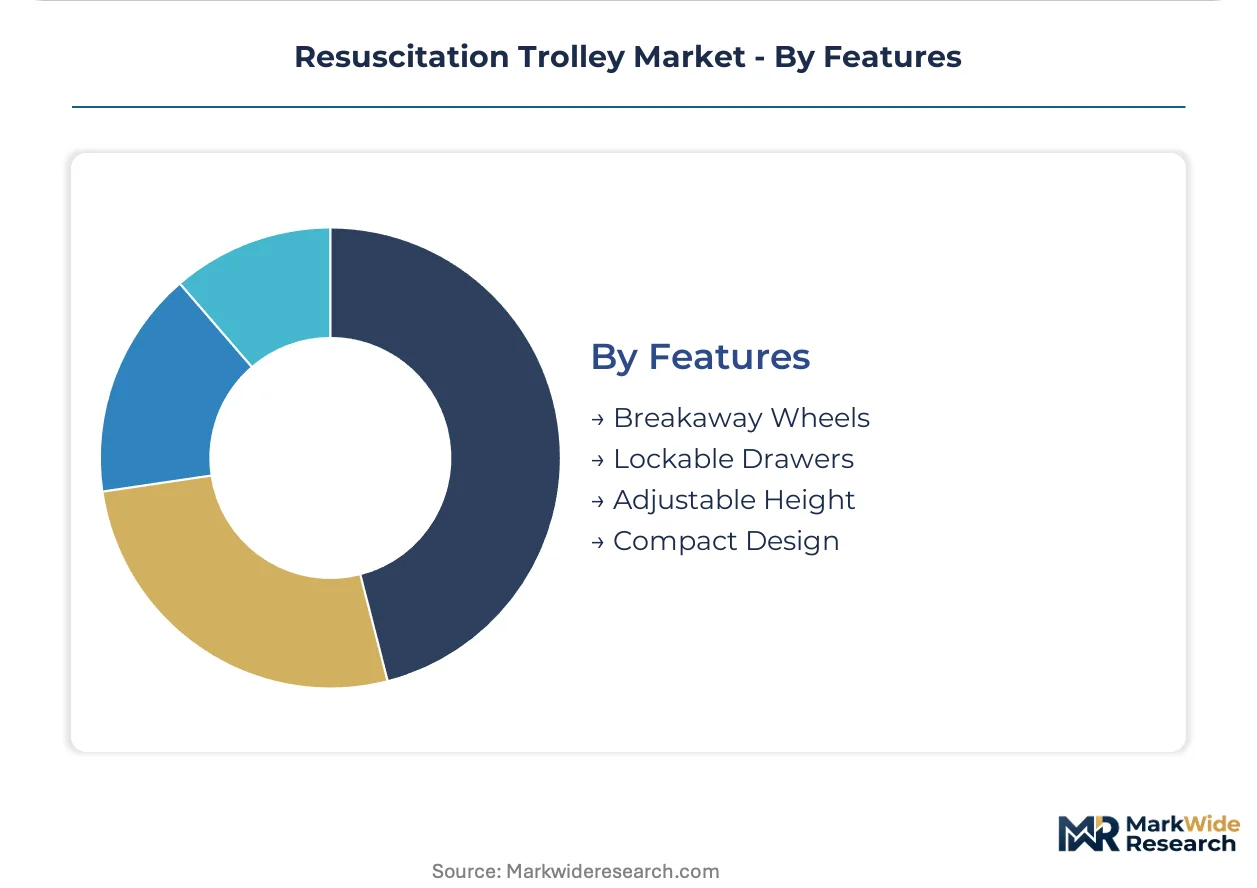
Features:
Regulatory mandates and clinical workflow integration determine which capability bundles command procurement priority, with digital traceability requirements reshaping specification standards.
- Breakaway Wheels:Quick-release caster systems enabling rapid trolley detachment from wall mounts or charging stations. Emergency departments prioritize this feature for code-blue response velocity.
- Lockable Drawers:Secured compartmentalization for controlled substances, airway equipment, and emergency pharmaceuticals. The FDA's Unique Device Identification mandate pushes manufacturers toward integrated digital tracking modules within these storage systems.
- Adjustable Height:Variable working surface elevation to accommodate clinician stature and procedure requirements. Electric actuation commands premium pricing; manual crank systems serve cost-constrained settings.
- Compact Design:Reduced footprint configurations for space-constrained clinical environments. Favored in older hospital infrastructure and ambulance vehicle integration where spatial optimization is paramount.
Lockable Drawers constitute the baseline specification; Compact Design is expanding most quickly as facility retrofit and mobile deployment accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's medical technology corridor anchors North American resuscitation trolley innovation, with Massachusetts General Hospital and affiliated research institutions driving clinical specification standards that diffuse nationally.
United States
Multi-hospital network consolidation concentrates procurement authority in regional health systems spanning California, Texas, and the Northeast corridor. The FDA's Unique Device Identification mandate compels fleet refresh cycles across acute care networks. Minneapolis-based distribution infrastructure supports standardized rollout of digitally-enabled trolleys to consolidated systems.
Germany
Tertiary hospital emergency departments in Bavaria and North Rhine-Westphalia prioritize motorized height-adjustment systems for crash-cart readiness. The EU Medical Device Regulation (MDR) elevates documentation burdens for imported equipment. Stuttgart's precision engineering cluster supplies actuator systems for premium electric trolley variants.
United Kingdom
NHS England's centralized procurement framework drives standardized fleet specifications across hospital trusts. The Medicines and Healthcare products Regulatory Agency (MHRA) enforces post-Brexit device traceability requirements. London's biomedical engineering sector develops RFID-enabled asset tracking modules for trolley integration.
Japan
Super-aging demographics accelerate emergency department automation investments in Tokyo and Osaka metropolitan hospitals. The Pharmaceuticals and Medical Devices Agency (PMDA) mandates JIS-standard compatibility for clinical equipment. Nagoya's automotive supply base pivots toward medical device component fabrication.
Australia
State-based ambulance authorities in New South Wales and Victoria modernize pre-hospital equipment fleets for expanded mobile intervention scope. The Therapeutic Goods Administration (TGA) aligns device registration with ISO 13485 quality protocols. Melbourne's medical device distribution hub coordinates Pacific regional supply.
Resuscitation Trolley Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated vendor landscape. Integrated hospital service infrastructure distinguishes full-stack competitors from equipment-only suppliers. Three archetypes dominate: diversified medical device conglomerates with captive distribution networks, specialized clinical furniture fabricators with regional manufacturing footprints, and consumables distributors leveraging private-label assembly relationships. Consolidation pressure favors M&A-driven portfolio expansion and multi-year maintenance contract anchoring.
Among diversified medical device conglomerates, Stryker Corporation and Arjo exemplify the service-integrated archetype through direct hospital infrastructure deployment. Specialized fabricators including Capsa Healthcare and Harloff Manufacturing Co. occupy positions emphasizing workflow-specific customization. Medline Industries, Inc. anchors the distribution-leveraged tier, pairing private-label equipment with consumables procurement consolidation. Electro Kinetic Technologies and Haeberle represent mid-scale specialists focused on motorized mobility systems and European clinical environments respectively.
| Leading Market Players |
|---|
| Capsa Healthcare |
| Harloff Manufacturing Co. |
| Medline Industries, Inc. |
| Arjo |
| Haeberle |
| Malvestio |
| Allibert Medical |
| Stryker Corporation |
| Electro Kinetic Technologies |
| Others |
Value Network & Pricing Analysis
Aluminum commodity benchmarks on the London Metal Exchange cascade directly through resuscitation trolley fabrication costs, splitting procurement into three distinct tiers that align with health system consolidation patterns and FDA compliance readiness.
Pricing Analysis
Cost-down pressure on manual trolley tiers accelerates because aluminum input volatility compresses manufacturer margins on fixed-price clinic contracts. Pricing stratifies across premium electric systems with integrated power modules, standard ISO 13485-certified fleets for hospital networks, and economy manual variants for ambulatory settings. Brand premiums attach to vendors with captive service infrastructure, while customization levels drive variance within each tier. Hospital procurement committees demonstrate lowest price sensitivity due to total cost-of-ownership evaluation frameworks, whereas independent clinics retain acute sensitivity to acquisition price alone.
Supply Chain Analysis
Actuator systems and precision-machined aluminum extrusions rest on specialized producers in Germany, China, and the United States. Raw material feeds draw from bauxite refining clusters in Australia and Guinea, with secondary smelting concentrated in China and the Gulf states. Single-source vulnerability concentrates in motorized height-adjustment mechanisms sourced from Stuttgart's engineering cluster. Distribution runs through medical device distributors and direct hospital service networks, with consolidated health systems bypassing traditional channels for manufacturer-direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into software-enabled fleet management and preventive maintenance infrastructure has become the decisive competitive lever, separating full-stack service providers from equipment-only suppliers.
For Market Incumbents: Deploy multi-year maintenance bundles to lock in hospital system relationships against emerging software-native competitors. Backward integration into aluminum extrusion and actuator production defends margin position against commodity price swings. ISO 13485 certification investments create regulatory moats that extend development timelines for new entrants. For New Entrants and Emerging Players: Begin with lightweight composite trolley designs for Emergency Medical Services channels where incumbent service infrastructure offers weaker coverage. Target state-based ambulance authorities in Australia and regional EMS networks in the United States with compact, vehicle-integrated configurations. Pursue direct-to-authority sales models that bypass established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized clinical furniture fabricators with regional manufacturing footprints in Germany and the United States. Mid-scale motorized mobility specialists offer acquisition targets with technology transfer potential into premium electric trolley segments. Watch FDA enforcement intensity on Unique Device Identification compliance as the inflection signal for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA UDI Compliance Pathway | Embedded digital tracking modules satisfy traceability mandates and accelerate fleet refresh cycles. |
| Hospital System Partnership | Direct service infrastructure locks in multi-year procurement agreements across consolidated networks. |
| Software Companion Development | Fleet management platforms elevate equipment vendors to strategic supplier status with recurring revenue. |
| Backward Integration into Components | In-house actuator and aluminum fabrication reduces exposure to commodity price volatility. |
| CE Marking Pathway | EU MDR documentation compliance opens tertiary hospital access in Germany and the United Kingdom. |
Research Methodology
Multi-period observation of hospital procurement volumes, aluminum price indices, and FDA compliance deadlines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and EMS equipment coordinators. Secondary validation drew from FDA Unique Device Identification registration databases, hospital capital expenditure disclosures, ISO 13485 certification records, and medical device trade flow data. Bottom-up installation counts across acute care networks were triangulated against top-down health system consolidation metrics.
Segment-weighting applied product type, end user channel, material composition, and feature bundles across the projection horizon. CAGRs derived from modeled replacement cycles incorporating regulatory compliance deadlines and technology refresh patterns. Electric trolley adoption curves and EMS fleet modernization timelines served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; hospital emergency department placements carry tighter precision than fragmented clinic procurement. Forecasts reflect assumptions on health system consolidation velocity, regulatory enforcement intensity, and aluminum commodity stability. A small set of triggers—FDA audit frequency, aluminum price spike magnitude, and EMS budget allocation shifts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
South East Asia Ambulance Services Market