
 Neonatal Ventilators Market | 2026-2036
Neonatal Ventilators Market Size, Share, and Industry Trends Forecast 2026-2036
Neonatal Ventilators Market Analysis
Hospital procurement is tilting toward bundled service contracts that pair device placement with multi-year technical support. Hamilton Medical leverages its Swiss manufacturing base to sustain premium positioning in European NICU networks. Medtronic competes through its integrated critical care portfolio that anchors hospital-wide purchasing decisions. Drägerwerk AG & Co. KGaA specializes in ventilation-workstation ecosystems that dominate German-speaking clinical markets.
Neonatal ventilators are precision life-support systems engineered to deliver calibrated tidal volumes as low as two milliliters per kilogram for premature infants with underdeveloped pulmonary architecture. These devices integrate heated humidification, continuous airway pressure modulation, and synchronized intermittent mandatory ventilation to stabilize respiratory function in neonates weighing under fifteen hundred grams. High-frequency ventilators command the steepest price tiers due to their oscillatory flow mechanisms and jet-valve engineering for severe respiratory distress syndrome. Conventional ventilators retain the broadest installed base across mid-tier hospitals where invasive technology serves standard NICU admissions. Non-invasive modalities are gaining fastest in homecare settings where parents receive training for nasal continuous positive airway pressure administration.
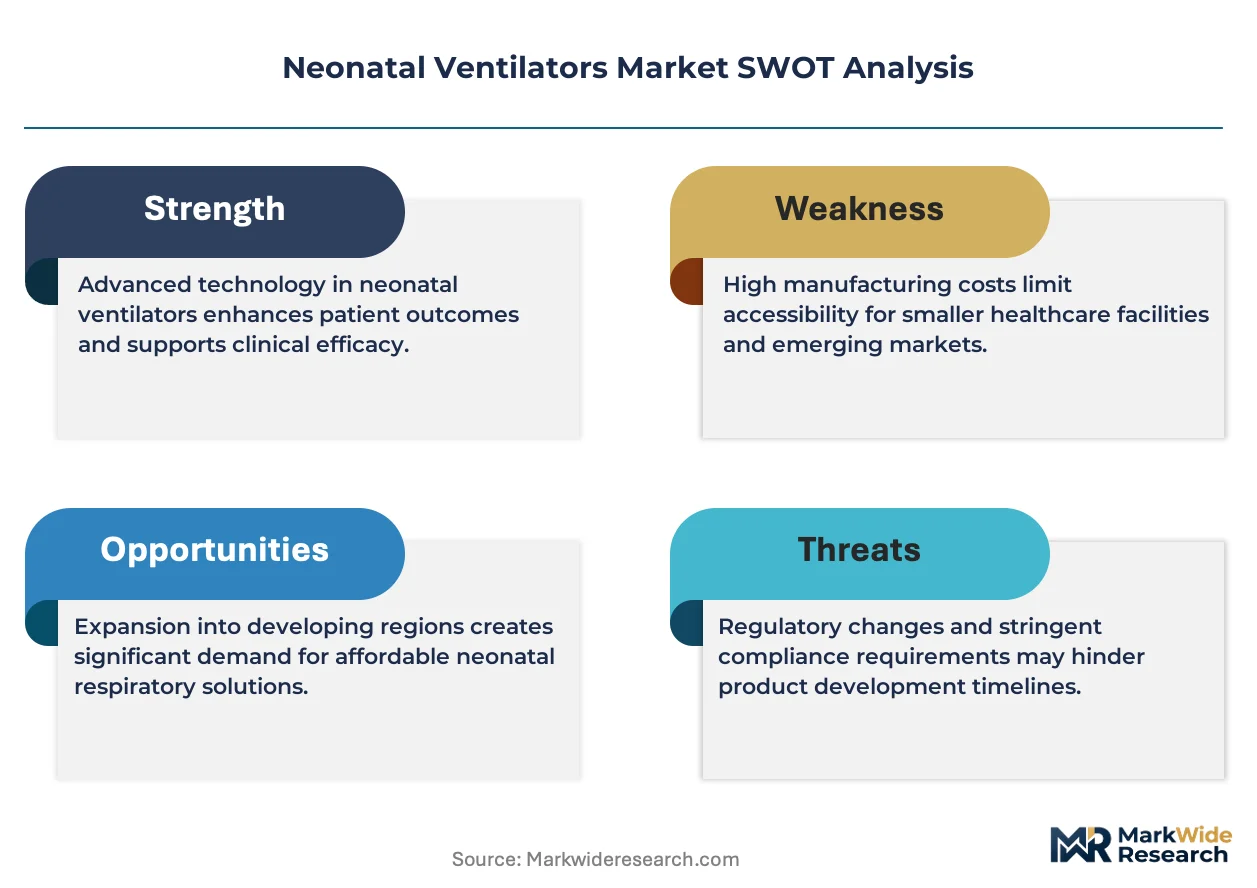
FDA premarket notification pathways and CE marking under the EU Medical Device Regulation shape product development timelines and clinical evidence requirements for manufacturers seeking dual-territory approval. ISO 80601-2-80 standards for respiratory ventilator safety establish baseline electromagnetic compatibility and alarm-system protocols that national regulators reference for type-testing acceptance. Stakeholders must monitor how FDA's evolving software-as-medical-device guidance applies to artificial intelligence-driven ventilation modes now entering development pipelines.
Market Dynamics
Hospital procurement committees now prioritize device interoperability with electronic health record systems, forcing manufacturers to engineer open-architecture platforms that integrate with Epic and Cerner deployments across NICU networks.
Growth Catalysts
- National Health Mission NICU expansion:India's Ministry of Health and Family Welfare funds level-III neonatal units in district hospitals, creating device demand in secondary cities previously served by basic resuscitation equipment.
- EU Medical Device Regulation clinical evidence requirements:Post-market surveillance mandates under MDR Article 83 accelerate manufacturer investment in real-world performance databases for premature infant ventilation outcomes.
- High-frequency oscillatory ventilation:Jet-valve engineering for severe respiratory distress syndrome commands premium placement in academic medical centers managing micropremie populations under 28 weeks gestation.
Market Restraints
- Precision sensor supply concentration:German and Swiss flow-sensor manufacturers control 80% of heated-wire anemometer supply for tidal volume measurement below 5 mL.
- FDA 510(k) substantial equivalence pathways:Predicate device requirements for novel ventilation modes extend development timelines by 18-24 months compared with EU technical file routes.
- Biocompatible polymer cost volatility:Medical-grade polycarbonate and silicone membrane prices fluctuate with petrochemical feedstock indices, compressing gross margins on conventional ventilator platforms.
Strategic Opportunities
- Homecare non-invasive ventilation:Nasal continuous positive airway pressure training programs for parents of premature infants discharged from NICU create aftermarket service revenue streams.
- Artificial intelligence-driven weaning protocols:Machine learning algorithms analyzing respiratory mechanics data promise automated extubation readiness scoring, differentiating next-generation platforms.
- Brazilian SUS procurement modernization:ANVISA's streamlined registration for Class III devices with prior FDA or CE approval opens federal hospital purchasing to imported ventilation systems.
Industry Challenges
- Pediatric respiratory therapist certification gaps:Specialized neonatal ventilation training programs remain concentrated in academic medical centers, limiting safe device deployment in community hospital NICUs.
- Legacy device cybersecurity patching:FDA post-market guidance for networked medical devices requires manufacturers to support software updates for ventilator platforms with 10-15 year installed lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neonatal Ventilators Market |
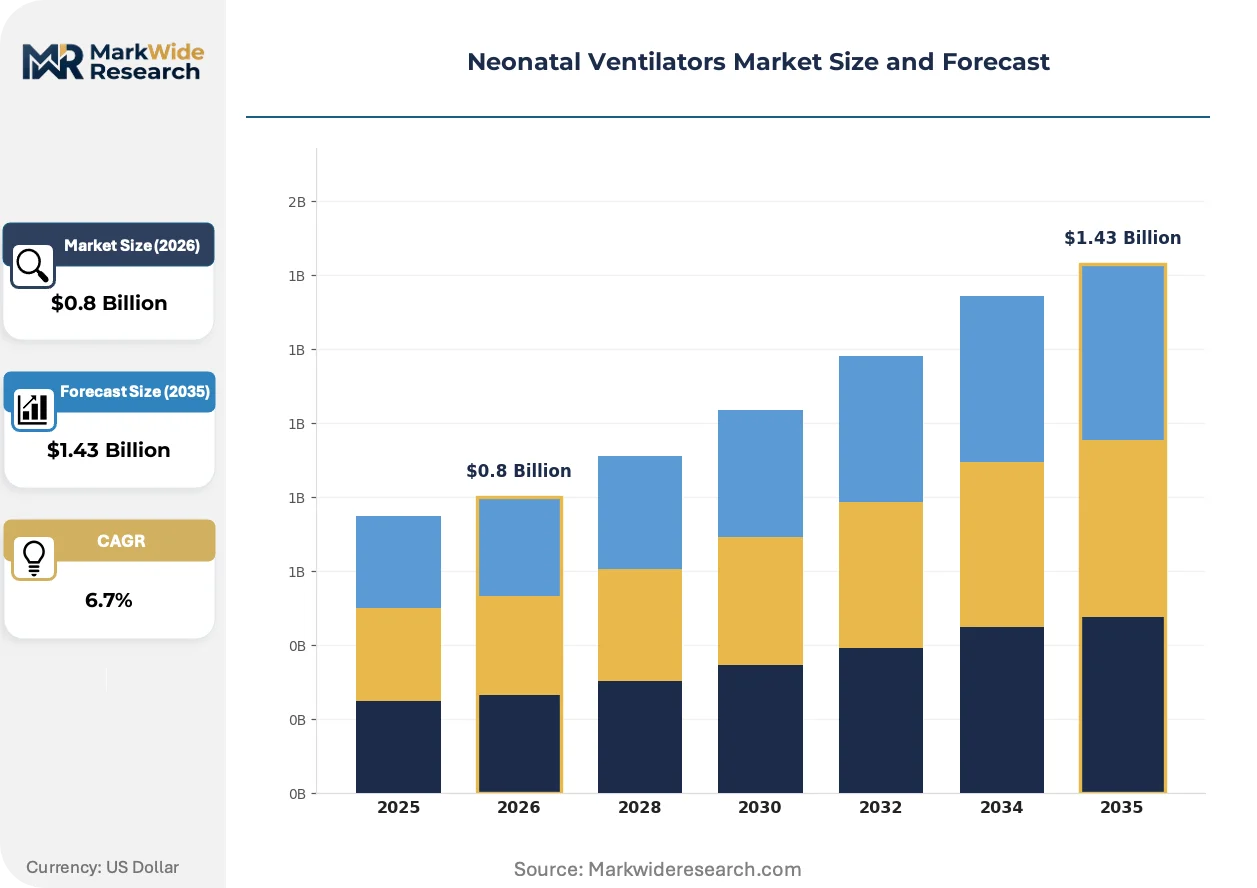
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.43 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Frequency, Conventional, Transport, Hybrid End User: Pediatrics, Neonatal Intensive Care Units, Hospitals, Homecare Technology: Invasive, Non-Invasive, Electronic, Mechanical Application: Respiratory Support, Surgery, Emergency Care, Long-term Care |
| Companies Covered | Hamilton Medical, Getinge AB, Medtronic, Smiths Group, Vyaire Medical, Drägerwerk AG & Co. KGaA, Koninklijke Philips N.V., Fisher & Paykel Healthcare, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neonatal Ventilators Market Emerging Trajectories
Neonatal ventilation engineering is pivoting from standalone mechanical systems toward integrated physiological feedback loops that synchronize gas delivery with spontaneous respiratory effort.
Volume-targeted ventilation with leak compensation is collapsing the clinical distinction between invasive and non-invasive support modalities. Level-III maternity hospitals in Shanghai and Beijing adopt these hybrid platforms for seamless transition between nasal CPAP and intubated ventilation. The technology compresses device procurement decisions into single-platform purchases rather than separate capital allocations.
CE marking under EU MDR Annex IX now requires clinical evaluation reports with post-market clinical follow-up data for Class IIb respiratory devices. Manufacturers serving German-speaking markets invest in multi-center registries tracking bronchopulmonary dysplasia incidence. Swissmedic-aligned technical documentation standards in Switzerland create parallel compliance pathways that smaller EU notified bodies struggle to match.
Hospital purchasing committees increasingly unbundle device acquisition from multi-year service contracts, treating preventive maintenance as separately negotiable spend. Independent service organizations in India's private hospital sector now compete with manufacturer-direct technical support for calibration and preventive maintenance. This fragmentation appears most pronounced in Maharashtra and Karnataka states where corporate hospital chains centralize biomedical engineering functions.
Neonatal Ventilators Market Segmentation
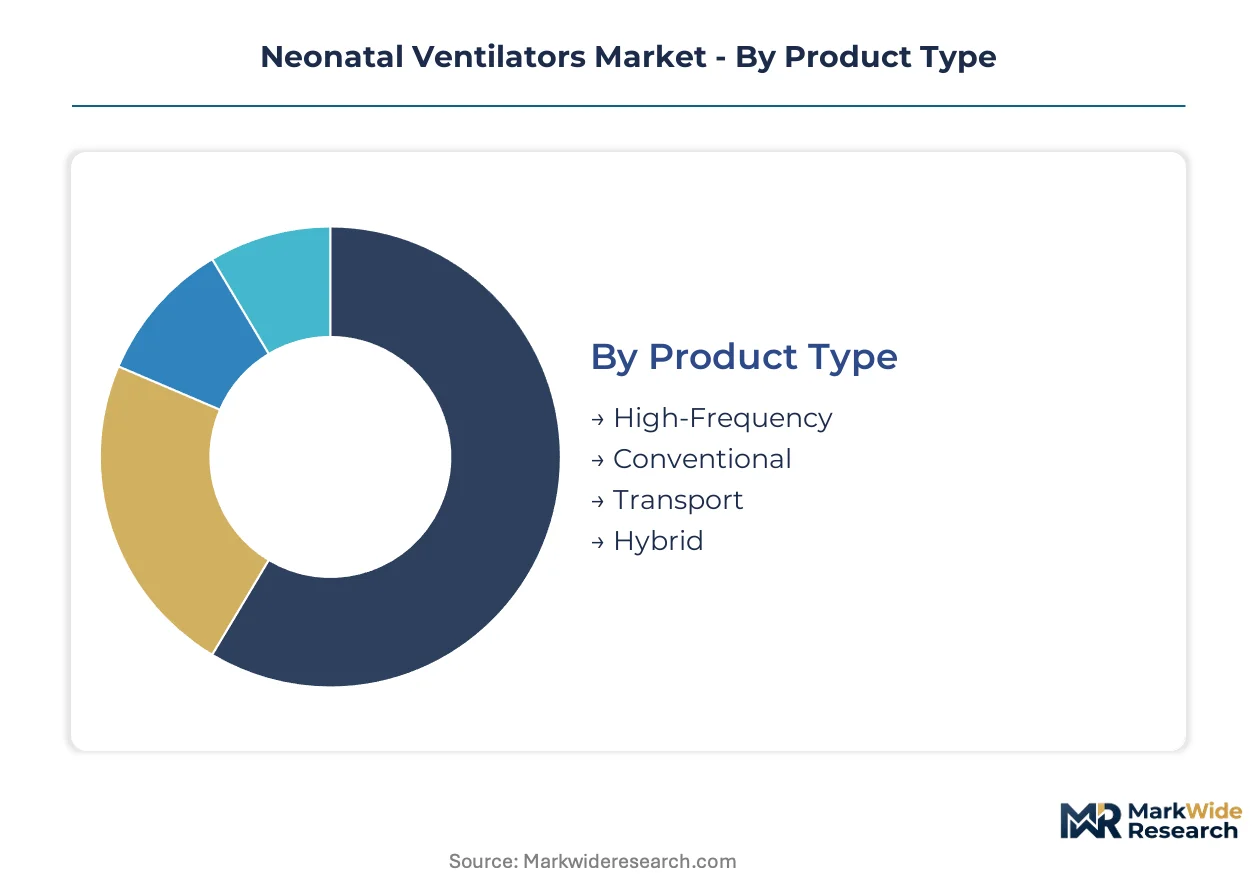
Neonatal ventilator procurement varies sharply by care setting and clinical acuity, with device replacement cycles stretching from 7-10 years in tertiary hospitals to 3-5 years in transport and homecare environments. Understanding segment-level turnover patterns helps manufacturers align service contract structures with actual utilization intensity.
Product Type:
Replacement velocity diverges dramatically across this category, with transport ventilators cycling fastest due to mechanical wear from ambulance deployment while hybrid platforms enjoy extended lifecycles through modular upgrade pathways.
- High-Frequency:Oscillatory flow mechanisms with jet-valve engineering deliver tidal volumes below 2 mL for micropremies under 28 weeks gestation. Academic medical centers in Shanghai and Beijing concentrate demand as municipal health commissions fund level-III perinatal centers with severe respiratory distress syndrome capabilities.
- Conventional:Time-cycled, pressure-limited ventilation modes retain the broadest installed base across mid-tier hospitals where invasive technology serves standard NICU admissions. India's National Health Mission expansion into district hospitals drives procurement of these platforms as baseline respiratory support infrastructure.
- Transport:Battery-powered, ruggedized designs withstand ambulance vibration and temperature extremes during inter-facility transfers of unstable neonates.
- Hybrid:Volume-targeted platforms with seamless invasive-non-invasive switching reduce capital duplication for hospitals consolidating vendor relationships.
Conventional ventilators dominate installed base. Hybrid platforms are where expansion concentrates.
End User:
Capital allocation authority and clinical training depth separate this category, with pediatric departments controlling distinct budgets from dedicated NICU operations and homecare representing a direct-to-patient revenue channel.
- Pediatrics:General pediatric wards outside dedicated neonatal units manage older infants transitioning from intensive care, requiring simpler interfaces without micro-volume precision.
- Neonatal Intensive Care Units:Level-III units with 24-hour neonatologist coverage demand the full spectrum of ventilation modalities plus integrated physiological monitoring. German-speaking European markets concentrate the highest device density per bed due to Swissmedic-aligned technical standards and rigorous preventive maintenance protocols.
- Hospitals:Secondary maternity hospitals in India's Karnataka and Maharashtra states represent the fastest-climbing demand segment as corporate hospital chains centralize biomedical engineering functions and standardize on single-vendor platforms.
- Homecare:Nasal CPAP systems with parent training protocols create recurring revenue through consumable circuits and remote monitoring subscriptions.
NICU departments command premium pricing tiers. Homecare is gaining share fastest.
Technology:
Engineering complexity and regulatory burden stratify this category, with electronic feedback systems requiring FDA software-as-medical-device documentation while mechanical platforms face lighter post-market surveillance obligations.
- Invasive:Endotracheal intubation with heated humidification and closed suction systems addresses respiratory failure in infants under 1500 grams. Academic medical centers managing bronchopulmonary dysplasia risk concentrate demand for these platforms with real-time respiratory mechanics monitoring.
- Non-Invasive:Nasal continuous positive airway pressure and high-flow nasal cannula reduce intubation trauma in moderate prematurity. China's tier-one cities drive adoption as level-III maternity hospitals prioritize gentler ventilation strategies for infants above 32 weeks gestation.
- Electronic:Microprocessor-controlled feedback loops synchronize breath delivery with spontaneous effort, requiring electromagnetic compatibility testing under ISO 80601-2-80.
- Mechanical:Pneumatic timing circuits without software components serve backup ventilation roles and markets with limited technical support infrastructure.
Invasive technology anchors revenue per unit. Non-Invasive modalities show the steepest expansion trajectory.
Application:
Clinical outcome metrics and reimbursement pathways differentiate this category, with emergency applications demanding rapid deployment features while long-term care emphasizes energy efficiency and noise reduction.
- Respiratory Support:Primary indication encompassing surfactant deficiency, apnea of prematurity, and transient tachypnea. India's government hospital procurement under the National Health Mission concentrates volume in this segment as NICU capacity expands beyond metropolitan centers.
- Surgery:Anesthesia-compatible ventilation with scavenging interfaces serves congenital diaphragmatic hernia and esophageal atresia repairs in pediatric surgical suites.
- Emergency Care:Resuscitation trolleys with immediate availability requirements prioritize alarm clarity and rapid parameter adjustment over advanced monitoring integration.
- Long-term Care:Chronic ventilation for neuromuscular conditions and bronchopulmonary dysplasia sequelae emphasizes portable designs with extended battery autonomy.
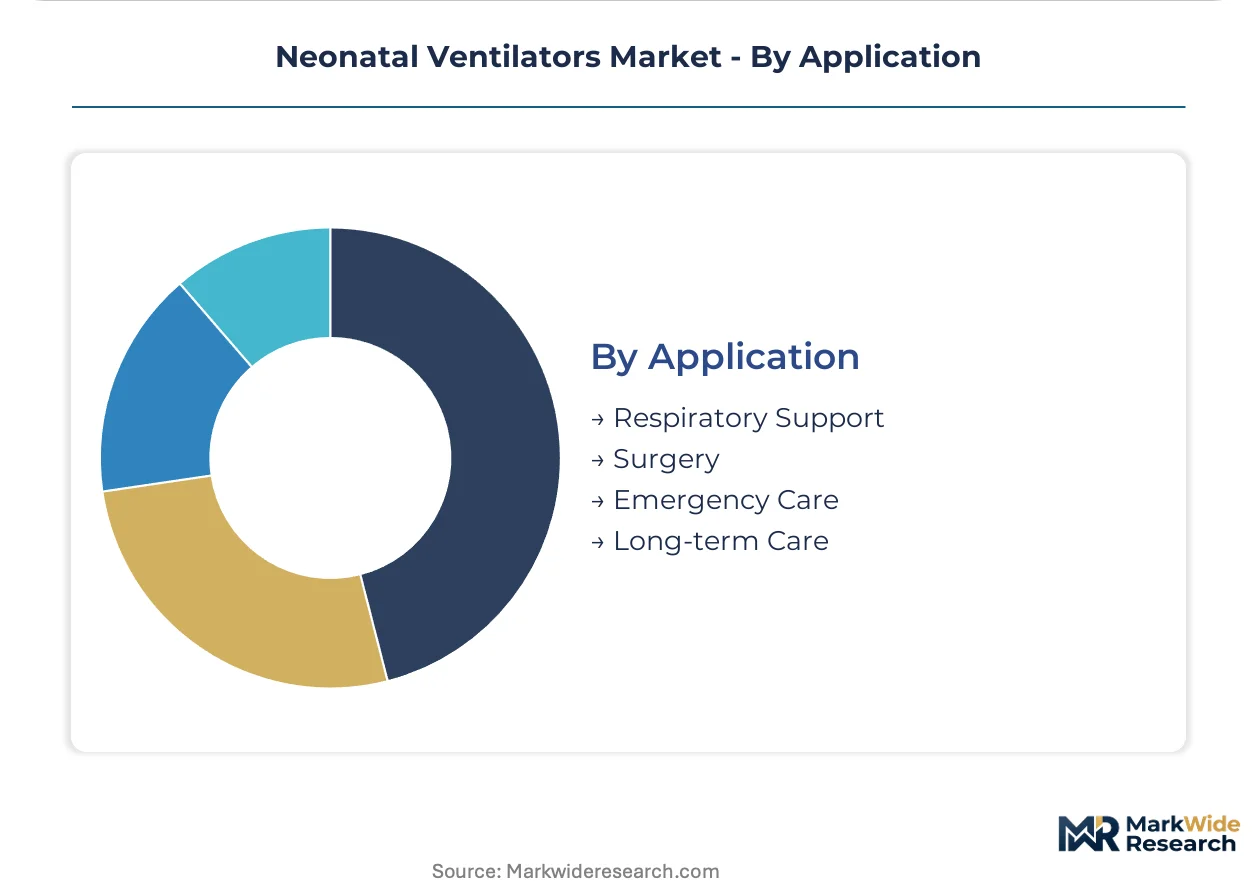
Respiratory Support dominates installed base. Long-term Care is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium ventilator pricing in Swiss and German NICU networks contrasts sharply with procurement constraints facing India's district hospital expansion, creating divergent margin environments for manufacturers serving each tier.
United States
FDA 510(k) substantial equivalence pathways and software-as-medical-device guidance shape product development timelines for manufacturers targeting academic medical centers. The agency's post-market cybersecurity mandates for networked respiratory devices extend manufacturer support obligations across 10-15 year installed lifecycles. Boston and Philadelphia hospital clusters concentrate demand for high-frequency oscillatory platforms managing micropremie populations.
Germany
Drägerwerk AG & Co. KGaA anchors domestic manufacturing of ventilation-workstation ecosystems serving German-speaking clinical markets. CE marking under EU MDR Annex IX requires clinical evaluation reports with post-market follow-up data for Class IIb respiratory devices. Bavarian and North Rhine-Westphalian perinatal centers maintain the highest device density per bed due to Swissmedic-aligned technical standards.
China
NMPA registration pathways for Class III respiratory devices prioritize domestic innovation in volume-targeted ventilation platforms. Municipal health commissions in Shanghai and Beijing fund level-III maternity hospitals with advanced perinatal capabilities. Yangtze River Delta hospital procurement concentrates demand for hybrid invasive-non-invasive systems.
India
National Health Mission NICU expansion into Karnataka and Maharashtra district hospitals creates device demand in secondary cities previously served by basic resuscitation equipment. CDSCO import licensing requirements for Class C respiratory devices align with FDA or CE approvals to accelerate market entry. Corporate hospital chains in Mumbai and Bangalore centralize biomedical engineering functions and standardize on single-vendor platforms.
Switzerland
Hamilton Medical leverages Swiss manufacturing to sustain premium positioning in European NICU networks. Swissmedic technical documentation standards create parallel compliance pathways that smaller EU notified bodies struggle to match. Zurich and Geneva academic medical centers concentrate demand for precision flow-sensor integration in micro-volume ventilation.
Neonatal Ventilators Market Vendor Landscape
Integrated critical care conglomerates and specialized ventilation-workstation developers split the market between hospital-wide purchasing leverage and clinical-ecosystem depth. The vendor base concentrates around three strategic archetypes: diversified medical technology portfolios, dedicated respiratory device specialists, and regional manufacturing champions with regulatory home-field advantage. Dominant competitive moves include strategic partnerships for electronic health record interoperability and modular platform upgrades that extend installed-base lifecycles.
Within the diversified portfolio tier, Medtronic and GE Healthcare occupy positions anchoring hospital-wide procurement decisions across critical care categories. Hamilton Medical and Drägerwerk AG & Co. KGaA exemplify the specialized ventilation-workstation archetype, with geographic naming conventions indicating Swiss and German origins respectively. These five entities collectively represent the competitive core against which mid-cap specialists and emerging market entrants define differentiation strategies.
| Leading Market Players |
|---|
| Hamilton Medical |
| Getinge AB |
| Medtronic |
| Smiths Group |
| Vyaire Medical |
| Drägerwerk AG & Co. KGaA |
| Koninklijke Philips N.V. |
| Fisher & Paykel Healthcare |
| GE Healthcare |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's domestic ventilator manufacturing base is compressing export pricing while simultaneously accelerating R&D migration toward AI-driven weaning protocols. This utilization squeeze forces European precision-sensor suppliers to defend margin structures through exclusive supply contracts with tier-one device manufacturers.
Pricing Analysis
The customization-premium spread between configured-to-order high-frequency oscillatory platforms and standard conventional ventilators now exceeds three-to-one in German-speaking NICU networks. Contract-based long-term offtake agreements dominate procurement, with price differentiation resting on FDA 510(k) clearance tier and integrated electronic health record interoperability. Pricing pressure stems from India's National Health Mission volume tenders that bundle device placement with multi-year service obligations. Corporate hospital chains in Maharashtra and Karnataka demonstrate the highest price sensitivity, while academic medical centers in Zurich and Boston absorb premiums for precision flow-sensor integration.
Supply Chain Analysis
Export-control regimes limiting semiconductor lithography equipment flows to Chinese fabs have redirected NMPA-registered ventilator manufacturers toward domestic microcontroller sourcing. Component concentration centers on German and Swiss heated-wire anemometer production, Japanese precision pressure transducers, and Chinese medical-grade polycarbonate molding. Single-source vulnerability in flow-sensor supply creates procurement risk for manufacturers targeting EU MDR compliance. Distribution runs through hospital group purchasing organizations in North America, direct municipal health commission contracts in China's tier-one cities, and centralized biomedical engineering functions in India's corporate hospital chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital system consolidation and centralized procurement functions, particularly in India's corporate chains and China's municipal health commission purchasing.
For Market Incumbents: Pre-empt software-as-medical-device regulatory complexity by embedding FDA 510(k) predicate strategies into next-generation AI ventilation mode development. Consolidate position through backward integration into precision flow-sensor manufacturing or exclusive supply partnerships with German and Swiss component specialists. Defend against emerging Chinese volume-targeted platform competitors by accelerating CE marking timelines under EU MDR Annex IX clinical evidence requirements. For New Entrants and Emerging Players: Build out homecare non-invasive ventilation service capabilities targeting premature infant discharge protocols in North American and Western European markets. The segment's consumable circuit recurring revenue model offers the most penetrable entry point against entrenched hospital-capital incumbents. Pursue ANVISA streamlined registration pathways for Brazilian SUS federal hospital procurement as a beachhead for Latin American expansion. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap ventilation-workstation specialists with established CE marking databases and dormant FDA 510(k) submission pipelines. Long-term viability hinges on software-as-medical-device regulatory navigation capabilities across the analysis window. Watch for inflection signals in NMPA domestic innovation policy shifts that would redirect procurement preference toward indigenous Chinese manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market entry for novel ventilation modes in academic medical center networks. |
| CE Marking Pathway | Unlocks German-speaking NICU procurement governed by Swissmedic-aligned technical standards. |
| Hospital System Partnership | Secures multi-year bundled service contracts with India's corporate hospital chains. |
| Software Companion Development | Enables AI-driven weaning protocol differentiation against conventional mechanical platforms. |
| Reimbursement Strategy | Aligns homecare nasal CPAP training programs with CMS and NHS coverage frameworks. |
Methodological Framework
Cross-validation between primary interviews with neonatologists, biomedical engineers, hospital procurement committee members, and GPO contracts managers anchors the qualitative findings against secondary validation from FDA 510(k) filings, EMA CE marking databases, NMPA registration records, and hospital procurement contract repositories. Bottom-up installed base modeling triangulates with top-down health expenditure allocation analysis across the analysis window.
Calibration against historical replacement cycles and regulatory approval timelines shapes the projection framework across product type, end user, technology, and application segments. CAGRs derive from segment-level demand elasticity modeling incorporating National Health Mission expansion trajectories, EU MDR post-market surveillance investment requirements, and NMPA domestic innovation policy shifts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese manufacturers or disruptive AI-native entrants would shift outcomes. Material shifts in FDA software-as-medical-device guidance or EU MDR notified body capacity constraints would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Japan Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal and Infant Care Equipment Market
Neonatal Care
Asia-Pacific Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
North America Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal and Prenatal Devices Market
Neonatal Care
Global Preterm Birth and PROM Testing Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Neonatal Infant Care Market
Neonatal Care
Umbilical Market
Neonatal Care
Neonatal Phototherapy Devices Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Infant Resuscitators Market