
 Adrenal Crisis Management Market | 2026-2036
Adrenal Crisis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Adrenal Crisis Management Market Outlook
Specialized endocrinology nursing capacity is reorganizing how hospitals deploy adrenal crisis response protocols across emergency and inpatient settings. Pfizer Inc. leverages its manufacturing scale to maintain reliable supply chains for injectable hydrocortisone formulations used in acute presentations. Eton Pharmaceuticals differentiates through focused development of proprietary drug-device combinations targeting the adrenal insufficiency patient population. Takeda Pharmaceutical Company Limited anchors its position through deep therapeutic expertise in rare disease and emergency hormonal replacement portfolios.
Adrenal crisis management encompasses the clinical systems, pharmaceutical interventions, and diagnostic workflows designed to identify and reverse acute adrenal insufficiency, typically requiring intravenous or intramuscular hydrocortisone administration at doses of 100 mg followed by continuous infusion or repeated boluses to restore hemodynamic stability. Injectable steroids dominate current product volumes due to their necessity in acute hypotensive crises, while emergency kits represent the fastest-expanding category as patient self-administration protocols gain clinical acceptance. Home care settings are capturing growing share as subcutaneous and intramuscular auto-injector technologies reduce emergency department dependency for known adrenal insufficiency patients.
FDA orphan drug designations and EMA's incentives for pediatric investigation plans shape development priorities for novel hydrocortisone delivery systems, while WHO inclusion of adrenal insufficiency in essential medicines lists influences procurement standards across national health systems. The EU MDR and FDA's updated combination product regulations are tightening quality system requirements for emergency drug-device kits. Stakeholders must monitor evolving payer evidence requirements for outpatient crisis prevention versus inpatient rescue therapy as care models shift toward risk stratification and patient-controlled intervention.
Market Dynamics
Injectable hydrocortisone formulations are supplanting oral alternatives in emergency protocols as hospital systems prioritize rapid hemodynamic stabilization over traditional administration routes.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate development timelines for novel hydrocortisone delivery systems targeting rare adrenal insufficiency populations.
- Subcutaneous Auto-Injector Technology:Patient-administered emergency kits reduce emergency department dependency and expand addressable patient populations beyond acute hospital settings.
- Specialist Endocrinology Infrastructure:Germany, Japan, and the United States are concentrating investment in dedicated adrenal crisis response protocols across tertiary care networks.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for corticosteroids concentrates among a limited set of European and Indian suppliers, creating vulnerability to geopolitical or quality disruptions.
- EU MDR Compliance Burden:Emergency drug-device combination products face tightened quality system requirements and extended certification timelines under updated medical device regulations.
- Reimbursement Fragmentation:Outpatient crisis prevention therapies encounter heterogeneous payer evidence requirements across national health systems, limiting standardized access.
Strategic Opportunities
- Pediatric Investigation Plans:EMA incentives for child-specific formulations create development pathways for weight-based dosing auto-injectors currently underserved by adult-centric devices.
- Home Care Channel Expansion:Subcutaneous administration protocols enable direct-to-patient distribution models that bypass traditional hospital pharmacy procurement.
- WHO Essential Medicines Inclusion:Adrenal insufficiency listing shapes procurement standards across national health systems in lower-income markets previously reliant on emergency imports.
Industry Challenges
- Specialized Nursing Capacity:Acute adrenal insufficiency protocols require trained endocrinology nursing staff that hospital systems struggle to recruit and retain across emergency and inpatient rotations.
- Combination Product Integration:Drug-device kit manufacturers face technical complexity harmonizing drug stability requirements with mechanical reliability standards for emergency use.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adrenal Crisis Management Market |
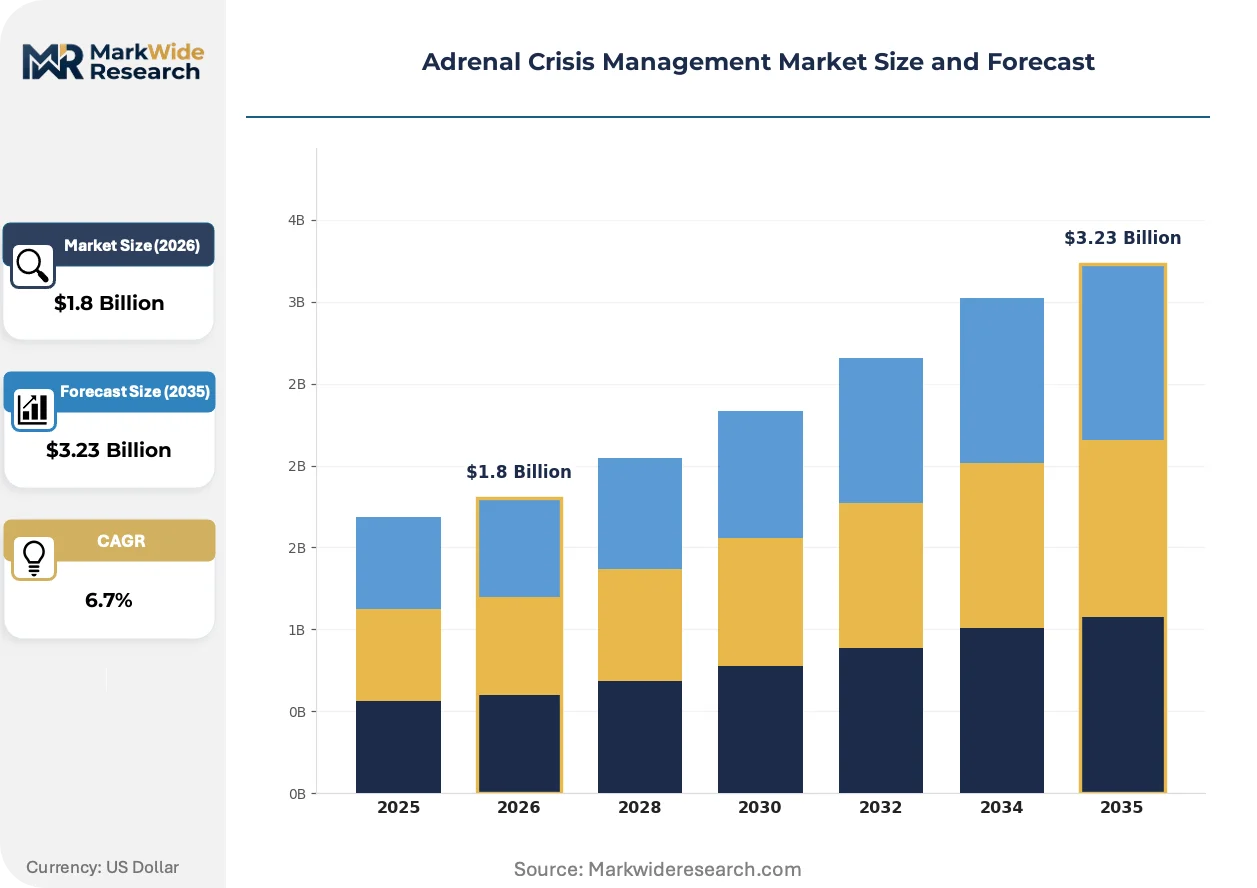
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Steroids, Oral Steroids, Emergency Kits, Diagnostic Tests End User: Hospitals, Clinics, Home Care, Pharmacies Administration Route: Intravenous, Intramuscular, Subcutaneous, Oral Care Setting: Emergency Rooms, Outpatient Facilities, Inpatient Wards, Urgent Care Centers |
| Companies Covered | Pfizer Inc., Eton Pharmaceuticals, Takeda Pharmaceutical Company Limited, Antares Pharma, Sandoz International GmbH, Merck KGaA, Novartis AG, Bristol-Myers Squibb Company, Mallinckrodt Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adrenal Crisis Management Market Strategic Shifts
Patient-controlled intervention models are compressing traditional emergency response timelines. Technology convergence, regulatory pathway evolution, and procurement realignment are restructuring competitive positioning across acute and preventive care segments.
Subcutaneous hydrocortisone auto-injectors are supplanting intramuscular emergency kits in patient self-administration protocols. Endocrinology practices in the United States and Germany are adopting these devices for stable adrenal insufficiency patients with established crisis recognition capacity. This shift enables home-based crisis prevention that reduces emergency department utilization and associated hospital admission costs.
EMA's pediatric investigation plan requirements are mandating age-appropriate formulation development alongside adult indications. Manufacturers must generate safety and efficacy data across pediatric weight bands, extending development timelines but creating defensible market positions in rare disease categories. European hospital systems are prioritizing suppliers with completed PIP submissions in tender evaluations.
After-sales service unbundling is fragmenting traditional device-and-training bundled contracts. Home care patients are accessing device training through telemedicine endocrinology consultations rather than in-person hospital education programs. This pattern concentrates in Germany and Japan where specialist telehealth reimbursement frameworks support remote patient monitoring for chronic adrenal conditions.
Adrenal Crisis Management Market Segmentation
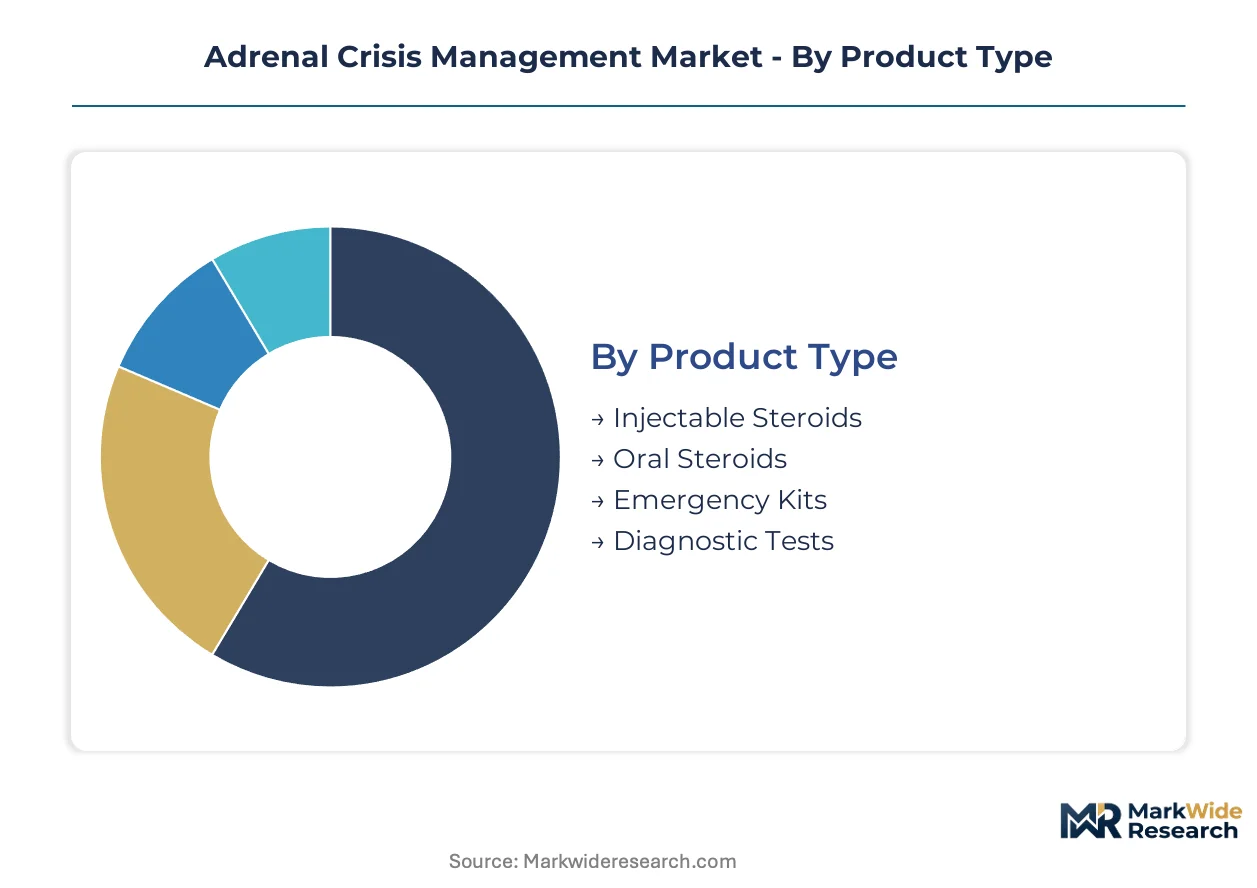
Adrenal crisis management products flow through distinct procurement channels shaped by urgency, reimbursement, and patient acuity. Channel economics dictate which segments concentrate in hospital formularies versus retail pharmacy or direct-to-patient distribution.
Product Type:
Hospital procurement channels favor acute intervention formats, while home care expansion is redistributing volume toward patient-controlled formats.
- Injectable Steroids:Hydrocortisone sodium succinate formulations deliver 100 mg rapid bolus capability for hypotensive emergencies. Demand concentrates in United States tertiary emergency departments where FDA-cleared injectable protocols anchor adrenal insufficiency response workflows.
- Emergency Kits:Auto-injector combinations enable subcutaneous self-administration outside clinical settings. Germany's specialist endocrinology networks are adopting these for stable patients, reducing emergency department utilization.
- Oral Steroids:Prednisone and hydrocortisone tablets serve maintenance therapy and taper protocols. Pharmacies in Japan handle the bulk of outpatient dispensing under PMDA-regulated distribution.
- Diagnostic Tests:ACTH stimulation assays and cortisol immunoassays identify adrenal insufficiency prior to crisis onset. Hospital laboratory procurement in the United States dominates current volume.
Injectable steroids dominate installed base. Emergency kits are where expansion concentrates.
End User:
Cost tier stratification separates acute rescue reimbursement from preventive home care coverage.
- Hospitals:Emergency and inpatient wards command premium pricing for crisis rescue interventions. United States hospital systems absorb the highest per-patient costs for unmanaged adrenal crisis admissions.
- Home Care:Subcutaneous auto-injector protocols enable direct-to-patient distribution bypassing traditional pharmacy procurement. Germany's telemedicine reimbursement frameworks support remote patient monitoring for these deployments.
- Clinics:Endocrinology specialty practices manage dose optimization and crisis prevention education. Japan's clinic density supports high-touch patient monitoring.
- Pharmacies:Oral maintenance therapy dispensing concentrates in retail channels with established corticosteroid distribution.
Hospitals capture the highest value per intervention. Home care is climbing the fastest.
Administration Route:
Application urgency determines route selection, with hemodynamic collapse mandating vascular access.
- Intravenous:Direct vascular delivery achieves therapeutic cortisol levels within minutes for hypotensive shock. Emergency rooms in the United States mandate IV capability for adrenal crisis protocols.
- Subcutaneous:Auto-injector technology enables patient-controlled administration with absorption rates suitable for pre-crisis intervention. German endocrinology practices are standardizing these for outpatient risk stratification.
- Intramuscular:Traditional emergency kit format requires caregiver or patient training for proper injection technique. United States home care protocols retain IM as backup when subcutaneous devices fail.
- Oral:Gastrointestinal absorption limits utility in acute vomiting or shock states, relegating this route to maintenance and taper regimens.
Intravenous administration anchors acute care revenue. Subcutaneous delivery is gaining share fastest.
Care Setting:
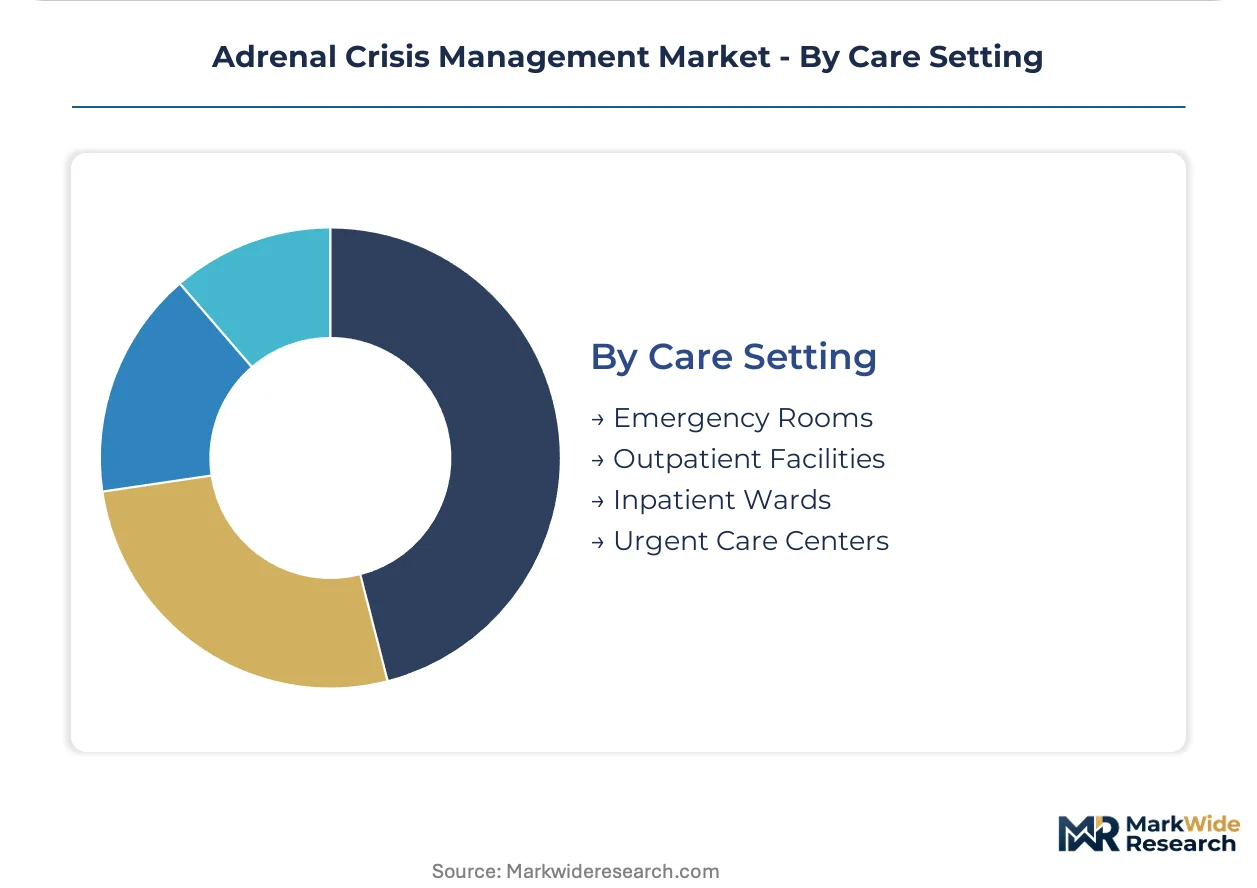
Patient volume and intervention complexity vary sharply across settings, with emergency response commanding premium reimbursement.
- Emergency Rooms:Unscheduled crisis presentations require immediate IV hydrocortisone and hemodynamic stabilization. United States emergency departments bear the highest costs for delayed diagnosis.
- Inpatient Wards:Post-crisis monitoring and secondary prevention occupy endocrinology nursing capacity. Japan's hospital-centered specialist infrastructure concentrates these admissions.
- Outpatient Facilities:Scheduled crisis risk assessment and auto-injector training occur in controlled environments. Germany's ambulatory endocrinology networks are expanding these services.
- Urgent Care Centers:Intermediate acuity settings handle suspected crisis presentations when emergency departments are distant. United States rural markets rely on these for geographic coverage.
Emergency rooms dominate acute intervention volume. Outpatient facilities are where preventive service expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug incentives and emergency use authorization pathways anchor United States market leadership. Specialist endocrinology infrastructure and reimbursement frameworks concentrate demand across three developed markets.
United States
Hospital systems in the United States are expanding dedicated adrenal crisis response protocols across tertiary emergency departments. FDA emergency use authorization pathways accelerate review timelines for novel hydrocortisone delivery systems targeting acute presentations. The Greater Boston cluster anchors specialist endocrinology nursing capacity development for acute hormonal replacement therapy.
Germany
German ambulatory endocrinology networks are standardizing subcutaneous auto-injector protocols for stable adrenal insufficiency patients. EMA pediatric investigation plan requirements mandate age-appropriate formulation development alongside adult indications. The Rhine-Ruhr metropolitan region concentrates specialist telemedicine reimbursement frameworks supporting remote patient monitoring for chronic adrenal conditions.
Japan
Japan's clinic density supports high-touch patient monitoring for adrenal insufficiency crisis prevention. PMDA-regulated distribution channels handle outpatient corticosteroid dispensing under established pharmacy frameworks. The Kanto region surrounding Tokyo anchors hospital-centered specialist infrastructure for post-crisis inpatient monitoring and secondary prevention admissions.
United Kingdom
United Kingdom hospital systems are adopting standardized adrenal crisis recognition training across emergency nursing rotations. NHS England rare disease funding frameworks support procurement of emergency drug-device combination products for patient self-administration. The Greater London cluster concentrates tertiary endocrinology referral centers managing complex adrenal insufficiency cases.
Adrenal Crisis Management Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the adrenal crisis management market. Large pharmaceutical manufacturers leverage manufacturing scale and distribution networks to maintain reliable supply chains for injectable hydrocortisone formulations. Specialist developers concentrate on proprietary drug-device combinations and pediatric-appropriate delivery systems. Competitive moves center on strategic partnerships for combination product development and geographic expansion into markets with established rare disease reimbursement frameworks.
Within the integrated pharmaceutical tier, Pfizer Inc. and Takeda Pharmaceutical Company Limited exemplify scale-driven supply chain anchoring for acute care formulations. Eton Pharmaceuticals occupies a position among specialist developers focused on the adrenal insufficiency patient population. These three entities represent contrasting strategic archetypes: manufacturing scale concentration, rare disease therapeutic expertise, and targeted drug-device innovation respectively.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eton Pharmaceuticals |
| Takeda Pharmaceutical Company Limited |
| Antares Pharma |
| Sandoz International GmbH |
| Merck KGaA |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Mallinckrodt Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
FDA orphan drug designation and EU MDR certification requirements gate both supplier qualification and price differentiation simultaneously, concentrating pricing power among manufacturers with completed combination product submissions while excluding uncertified competitors from tender participation.
Pricing Analysis
United States emergency departments pay premium multiples over German ambulatory networks for equivalent hydrocortisone formulations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared auto-injector kits from basic vial-and-syringe formats and unbranded generic injectables. Price differentiation hinges on certification tier and after-sales training bundling. Cost compression in standard-tier injectables is intensifying because Indian API suppliers are expanding corticosteroid production capacity. Hospital procurement committees demonstrate lowest price sensitivity; home care patients accessing direct-to-patient channels show highest.
Supply Chain Analysis
Six-to-nine month lead times for EU MDR-certified auto-injector components force manufacturers to carry elevated safety stock of mechanical subassemblies. Active pharmaceutical ingredient production concentrates in India, Italy, and the United States. Finished drug-device combination assembly draws from Chinese electronics suppliers for auto-injector sensors and German precision molding for needle shield components. Single-source vulnerability in hydrocortisone sodium succinate API creates concentration risk at three European manufacturing sites. Distribution runs through hospital group purchasing organizations in the United States and specialist pharmacy wholesalers in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
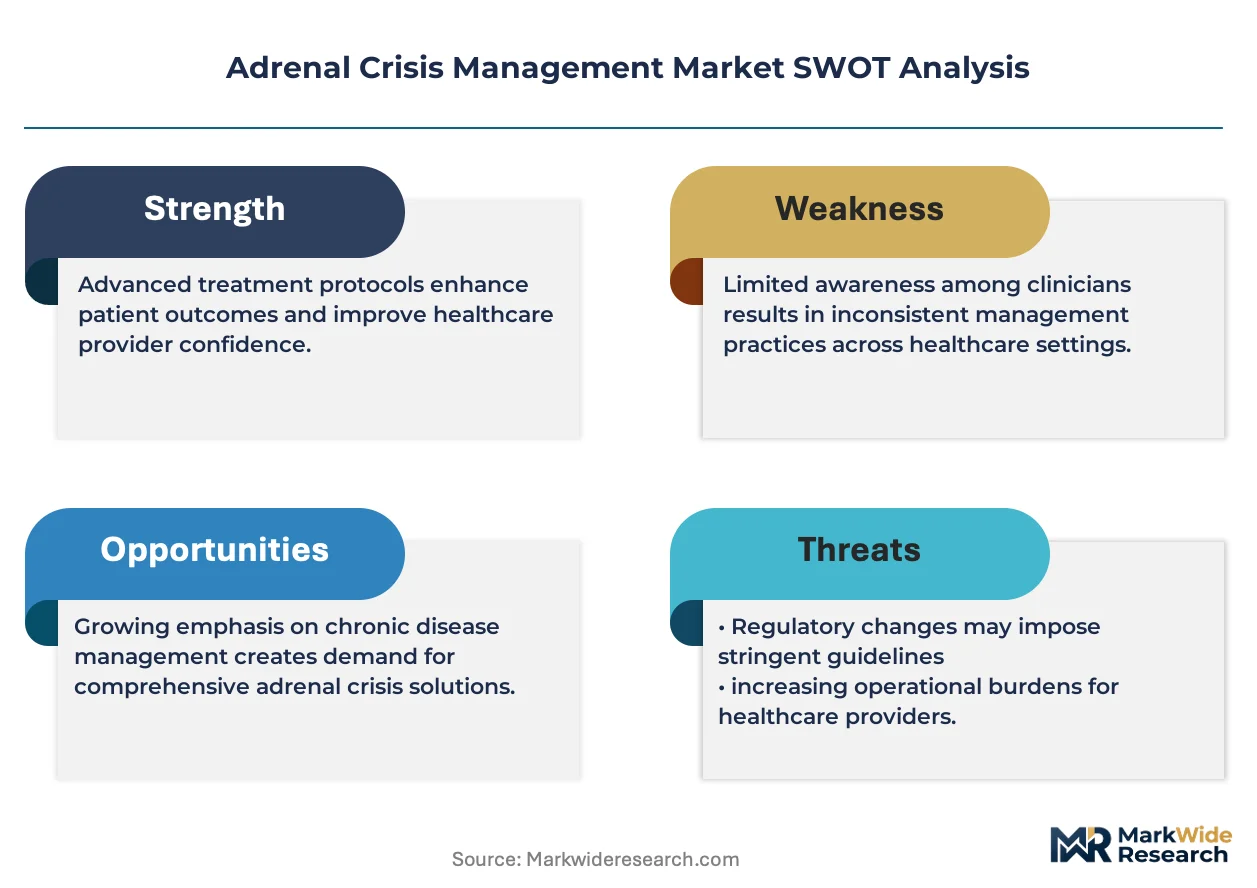
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantages. EMA pediatric investigation plan completion and FDA combination product clearance erect multi-year barriers to competitive replication.
For Market Incumbents: Secure backward integration into API manufacturing to reduce exposure to Indian and Italian supplier concentration. Lock in exclusive supply contracts with German precision molding houses for auto-injector mechanical components before EU MDR certification backlogs extend lead times further. Patent cliff pressure on oral corticosteroid franchises threatens margin contribution from maintenance therapy segments.
For New Entrants and Emerging Players: Telemedicine-enabled patient training represents a service-layer gap where incumbents under-serve home care patients with suboptimal remote onboarding protocols. Target United States urgent care networks in rural markets lacking emergency department proximity for geographic white-space penetration. Pursue partnership-based entry with endocrinology telehealth platforms rather than direct hospital formulary competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across drug-device combination product development due to EU MDR quality system investments and pediatric investigation plan requirements. Five-to-ten year viability favors developers with completed regulatory submissions over pre-clinical stage entrants. Acquisition target archetype: specialist auto-injector manufacturers with FDA 510(k) clearances in adjacent emergency medicine categories. Monitor EMA PIP completion timelines as inflection signal for competitive positioning durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Investigation Plan Completion | EMA submission unlocks European tender eligibility and creates multi-year exclusivity in weight-based dosing segments. |
| Combination Product FDA Submission | 510(k) pathway for auto-injector formats secures hospital formulary access ahead of generic vial competition. |
| API Manufacturing Scale-Up | Captive hydrocortisone sodium succinate production reduces supply vulnerability to Italian and Indian supplier disruptions. |
| Telemedicine Training Partnership | Remote patient onboarding agreements with German and Japanese endocrinology networks accelerate home care channel penetration. |
| WHO Essential Medicines Listing Advocacy | Inclusion drives procurement standardization across lower-income national health systems previously reliant on emergency imports. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinology nursing directors, hospital pharmacy procurement managers, emergency medicine clinicians, and regulatory affairs specialists at combination product manufacturers. Secondary validation drew from FDA 510(k) filings, EMA pediatric investigation plan submissions, hospital GPO contract databases, and WHO essential medicines list documentation. Bottom-up patient population estimates and top-down pharmaceutical market sizing were triangulated to anchor volume forecasts.
Across the projection horizon, the analytical framework modeled segmentation across product type, administration route, care setting, and regional regulatory cluster. CAGRs were derived from patient prevalence epidemiology, treatment protocol adoption curves, and reimbursement expansion trajectories. Forecast inputs incorporated specialist endocrinology nursing capacity expansion rates and telemedicine reimbursement framework evolution in Germany and Japan.
Underlying assumptions cover stable FDA orphan drug incentive continuity and EU MDR certification timeline normalization, with deviation risk concentrated in API supply disruptions and pediatric investigation plan requirement changes. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
First Aid Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Emergency Medical Supplies Market