
 Patient Transport Services Market | 2026-2036
Patient Transport Services Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Transport Services Market Analytics
Electric drivetrains are rebalancing fleet economics for ground-based patient transport operators, cutting fuel expenditure and maintenance intervals against diesel-powered legacy vehicles. American Medical Response leverages its national scale to electrify urban fleets across multiple metropolitan networks. Falck A/S anchors its competitive position through specialized aeromedical operations in Scandinavia and emerging markets. Air Methods Corporation dominates the US air ambulance landscape with hospital-based partnerships covering underserved mountainous and rural territories.
Patient transport services encompass the organized movement of individuals requiring medical supervision between healthcare facilities, emergency scenes, and residential locations, utilizing vehicles equipped with stretcher mounting systems, oxygen delivery apparatus, cardiac monitoring devices, and trained clinical personnel. The primary commercial purpose centers on ensuring continuity of care during geographic transitions while reducing adverse events through real-time physiological surveillance. Ambulance services command the largest revenue share within service type segmentation due to emergency call volume and higher reimbursement rates, while non-emergency medical transport exhibits faster structural expansion as health systems pursue readmission reduction and post-acute care integration. GPS tracking technology within the technology dimension has shifted from optional fleet management to mandatory operational infrastructure, with telemedicine solutions emerging as the fastest-growing technology category as pre-hospital consultation protocols expand.
The US Department of Health and Human Services and CMS shape demand through reimbursement rate-setting and prior authorization requirements for non-emergency transport, while the Federal Aviation Administration governs air ambulance crew qualifications and aircraft equipment standards. State-level emergency medical services agencies impose additional licensing conditions that create fragmented market access barriers across jurisdictions. Stakeholders must monitor evolving Medicare Advantage plan coverage determinations and state Medicaid expansion patterns to anticipate reimbursement trajectory shifts.
Market Dynamics
Reimbursement compression from CMS rate adjustments is forcing operators to restructure fleet economics around electric drivetrains and telemedicine-enabled pre-hospital protocols, compressing margins for legacy diesel-dependent providers while rewarding technology-forward platforms.
Growth Catalysts
- Medicare Advantage expansion:Private plan growth across the United States is broadening covered transport categories beyond traditional fee-for-service limits, particularly for post-discharge transfers.
- Telemedicine protocols:Real-time video consultation during ambulance transit is expanding into rural networks, enabling specialist-guided interventions before hospital arrival.
- Aging demographics:The 65-plus population concentration in Florida, Arizona, and rural Appalachia is sustaining non-emergency medical transport volume growth.
Market Restraints
- Jet fuel volatility:Air ambulance operators face margin erosion from aviation fuel price swings that CMS reimbursement formulas do not index adequately.
- Certificate-of-need laws:State-level CON restrictions in New York, Kentucky, and North Carolina block new ground ambulance entrants in oversaturated urban corridors.
- Specialist crew scarcity:Critical care paramedic certification pipelines cannot match air ambulance fleet expansion timelines, particularly in the Mountain West.
Strategic Opportunities
- Rural hospital closures:Defunct facility catchment zones in Mississippi Delta and Texas Panhandle regions create whitespace for mobile integrated healthcare units.
- IRA clean vehicle credits:Federal tax incentives for commercial EV procurement are accelerating fleet electrification timelines for municipal contract bidders.
- AI dispatch optimization:Machine learning routing platforms are converging with electronic health record integration to compress response intervals.
Industry Challenges
- Interoperability gaps:Legacy CAD systems resist seamless data exchange with hospital admission platforms, forcing manual handoffs during patient transfers.
- FAA Part 135 compliance:Night vision goggle certification requirements for helicopter EMS crews extend training timelines and elevate labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Transport Services Market |
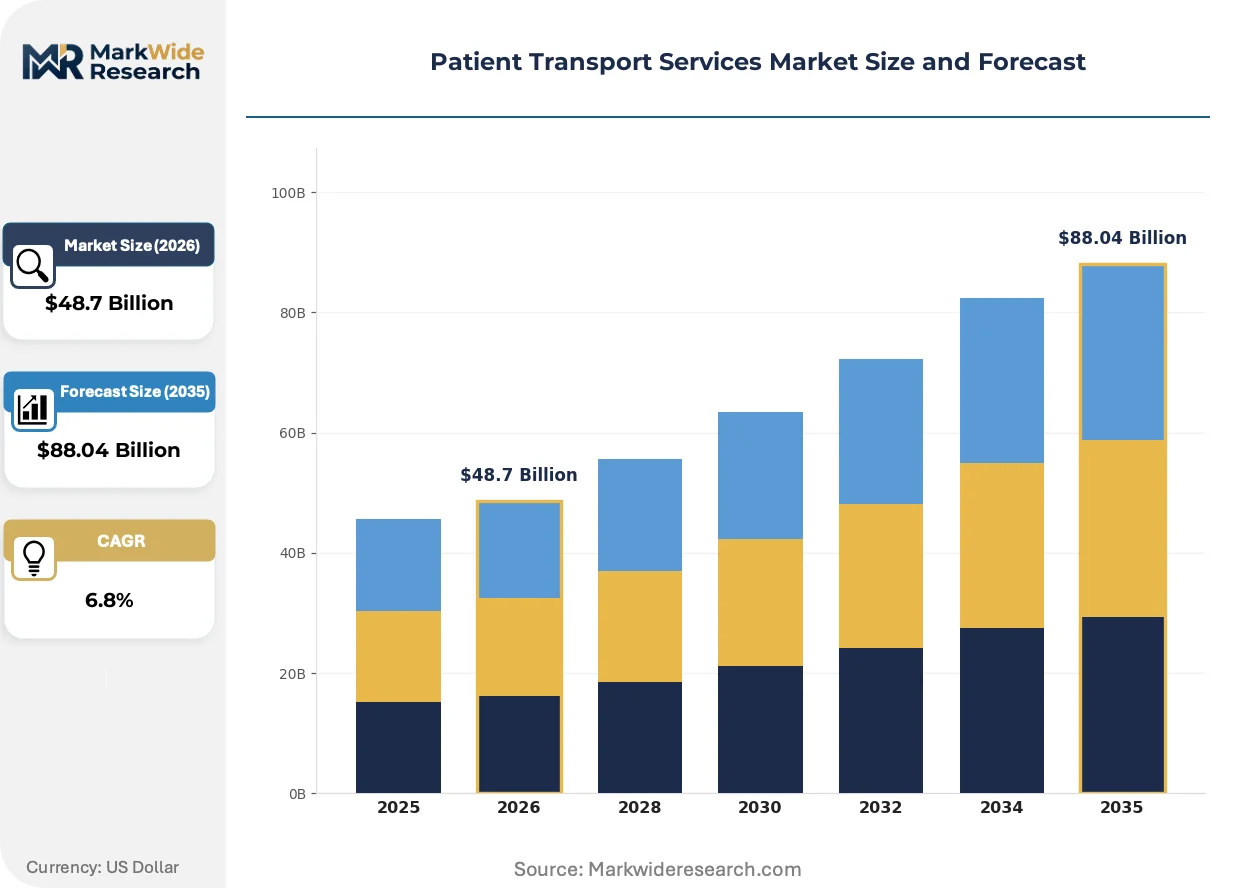
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ambulance Services, Non-Emergency Medical Transport, Stretcher Transport, Wheelchair Transport End User: Hospitals, Rehabilitation Centers, Residential Care Facilities, Home Health Agencies Delivery Mode: Ground Transport, Air Transport, Water Transport, Telehealth Services Technology: GPS Tracking, Communication Systems, Telemedicine Solutions, Patient Monitoring Systems |
| Companies Covered | Global Medical Response, American Medical Response, Falck A/S, Acadian Ambulance Service, Air Methods Corporation, Lifeguard Ambulance Service, Envision Healthcare, REVA Air Ambulance, St John Ambulance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Transport Services Market Evolving Landscape
Pre-hospital care models are converging with digital health infrastructure, transforming ambulances from passive transport vessels into active treatment nodes capable of diagnostic workup and specialist consultation en route.
Telemedicine platforms are expanding into ground-based emergency vehicles, equipping paramedics with real-time cardiology and neurology consult access. Hospital systems in the Upper Midwest are deploying these capabilities fastest, driven by stroke network certification requirements. The technology is compressing door-to-needle times by enabling pre-hospital triage decisions.
CMS prior authorization mandates for non-emergency medical transport are tightening documentation requirements for repetitive dialysis and wound care transfers. The policy is forcing operators to invest in predictive analytics for eligibility verification. Medicaid managed care organizations in the Southeast are responding with dedicated transport liaison staff.
Subscription-based membership models for air ambulance transport are displacing traditional fee-for-service billing in rural mountain communities. Families in Colorado, Wyoming, and Montana are enrolling in annual plans that cap out-of-pocket exposure for emergency rotor-wing evacuation. The shift is visible most acutely in counties where median household income falls below air ambulance median charges.
Patient Transport Services Market Segmentation
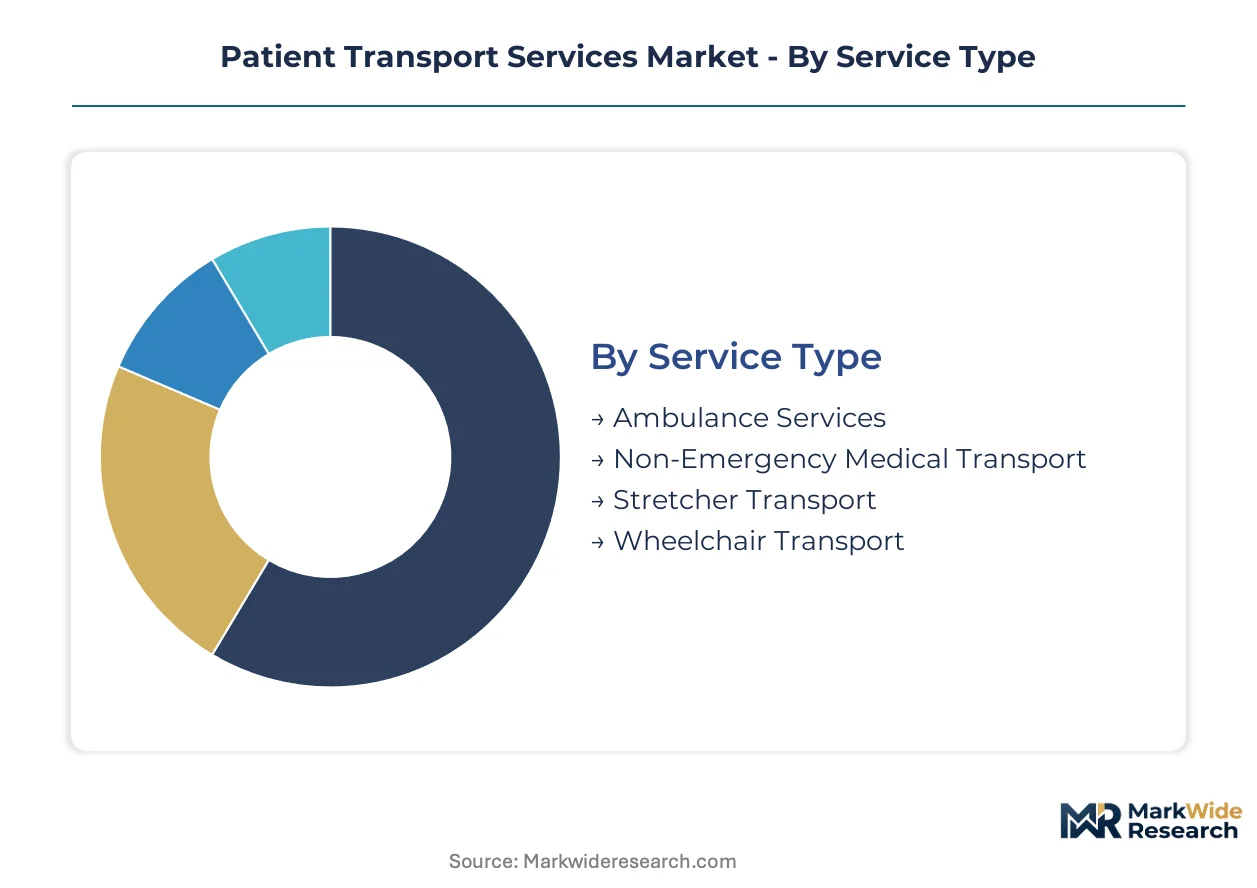
Patient transport operators structure service portfolios around reimbursement tiers and clinical acuity gradients. Segment boundaries determine capital deployment, crew certification requirements, and contracting leverage with health systems.
Service Type:
Volume concentrates in emergency response networks while premium economics shift toward scheduled mobility solutions.
- Ambulance Services:Advanced life support vehicles carry cardiac monitors, ventilators, and drug inventories for critical interventions. Demand clusters around Level I trauma centers in Houston, Phoenix, and Atlanta where 911 call density justifies dedicated fleet positioning. CMS emergency reimbursement rates sustain higher per-trip margins than non-emergency categories.
- Non-Emergency Medical Transport:Scheduled stretcher and wheelchair vans serve dialysis, chemotherapy, and post-acute discharge routes. Medicaid managed care expansion in Florida and Texas is accelerating enrollment in these programs. This segment is gaining share fastest as health systems pursue readmission reduction contracts.
- Stretcher Transport:Bariatric-capable vehicles with hydraulic lift systems serve immobile patients between skilled nursing facilities and hospitals. State Medicaid prior authorization requirements create administrative friction.
- Wheelchair Transport:Paratransit-compliant vans with securement tracks dominate urban cores where Americans with Disabilities Act mandates guarantee service minimums. Municipal contracts in Chicago, Los Angeles, and New York City anchor revenue stability.
Today's leader: Ambulance Services. Tomorrow's challenger: Non-Emergency Medical Transport.
End User:
Contract concentration varies by care setting reimbursement complexity and patient throughput predictability.
- Hospitals:Emergency departments generate unscheduled demand spikes requiring 24/7 fleet readiness. Academic medical centers in Boston and Baltimore are consolidating transport vendor relationships under single-source agreements. Discharge planning departments increasingly bundle non-emergency transport into bundled payment contracts.
- Rehabilitation Centers:Inpatient rehabilitation facilities require predictable daily shuttle schedules for therapy appointments and specialist consultations. Medicare Part A coverage determinations directly influence trip authorization volumes.
- Residential Care Facilities:Skilled nursing and assisted living communities generate recurring transport needs for physician visits and hospital transfers. Staffing shortages in these facilities are extending advance scheduling windows.
- Home Health Agencies:Home-based care expansion is creating last-mile transport requirements for patients without caregiver vehicle access. Rural home health networks in Appalachia and the Mississippi Delta present geographic dispersion challenges.
Hospital contracts deliver volume concentration. Home health relationships promise steepest expansion trajectory.
Delivery Mode:
Modal selection tracks population density, infrastructure topology, and clinical time sensitivity.
- Ground Transport:Road-based fleets dominate urban and suburban corridors where ambulance response time standards mandate proximity positioning. Electric drivetrain conversion is restructuring total cost of ownership calculations for municipal contract bidders.
- Air Transport:Helicopter and fixed-wing services cover territories where ground transit exceeds the golden hour for trauma or stroke intervention. FAA Part 135 operational specifications govern crew rest, maintenance intervals, and weather minimums. Mountain West and Alaska networks depend entirely on rotor-wing accessibility.
- Water Transport:Marine ambulance services serve coastal archipelagos and riverine communities in Puget Sound, the Florida Keys, and coastal Maine. Vessel certification requirements add regulatory layers absent from land-based operations.
- Telehealth Services:Virtual consultation platforms are displacing physical transport for low-acuity behavioral health and chronic disease management encounters. CMS expanded telehealth reimbursement during the public health emergency and has maintained several flexibilities.
Ground operations anchor current revenue. Telehealth modalities are displacing lowest-acuity transport demand.
Technology:
Technology deployment separates compliance-grade infrastructure from competitive differentiation.
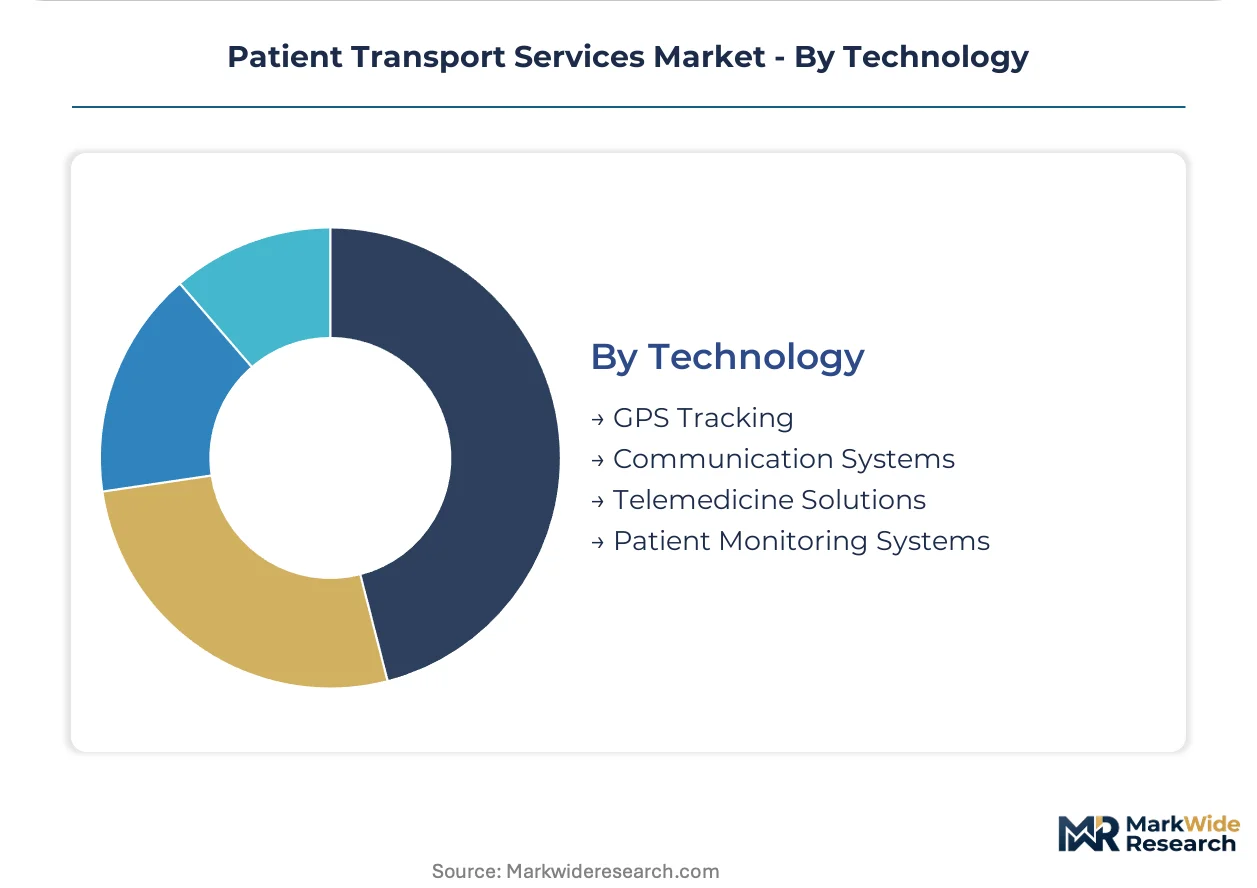
- GPS Tracking:Real-time location systems have shifted from fleet management convenience to mandatory operational infrastructure. Dispatch centers in Dallas and Seattle use predictive routing algorithms to compress response intervals.
- Communication Systems:Radio networks and cellular data links connect field crews with hospital emergency departments and medical control physicians. FirstNet priority access is becoming standard for public-safety-integrated operators.
- Telemedicine Solutions:Video consultation platforms enable cardiology and neurology specialists to guide paramedic interventions during ambulance transit. Stroke network certification requirements in Minnesota and Wisconsin are accelerating deployment.
- Patient Monitoring Systems:12-lead ECG transmission, capnography, and pulse oximetry data streaming allow pre-hospital notification of catheterization lab or operating room teams. Device interoperability with hospital electronic health records remains fragmented.
GPS tracking represents table stakes. Telemedicine solutions command premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US patient transport sector anchors worldwide market development through CMS reimbursement frameworks and air ambulance network density. Medicare Advantage expansion and rural hospital closure patterns concentrate demand in specific metropolitan and frontier corridors. Electric fleet conversion and telemedicine integration are advancing fastest where regulatory clarity meets capital availability.
United States
The aging population in Florida and Arizona sustains non-emergency medical transport volume growth. CMS prior authorization mandates for repetitive dialysis transfers are tightening documentation requirements. Houston and Phoenix operate the densest Level I trauma center catchment zones, driving 911 call density and dedicated ALS fleet positioning.
Germany
Regional hospital networks in Bavaria and Baden-Württemberg are consolidating transport vendor relationships under single-source agreements. The country's national healthcare regulator enforces strict emergency medical services licensing conditions across federal states. Berlin-Brandenburg clusters academic medical centers that are deploying telemedicine-enabled pre-hospital stroke protocols.
United Kingdom
NHS England ambulance response time standards mandate proximity positioning for road-based fleets across London and the Southeast. The Care Quality Commission imposes additional licensing conditions that create fragmented market access barriers. St John Ambulance anchors voluntary sector provision in rural Wales and Northern England where commercial density remains insufficient.
Canada
Provincial health authority contracting in Ontario and Quebec is shifting toward bundled payment models for post-acute discharge transport. Health Canada governs air ambulance crew qualifications and aircraft equipment standards for remote northern territories. Alberta's mountain and prairie networks depend entirely on rotor-wing accessibility where ground transit exceeds golden hour thresholds.
Australia
State-based ambulance services in New South Wales and Victoria are electrifying urban fleets through commercial EV procurement incentives. The Therapeutic Goods Administration regulates patient monitoring device interoperability with hospital electronic health records. Queensland's coastal archipelagos and remote interior sustain marine and fixed-wing ambulance operations absent road infrastructure.
Patient Transport Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as operators seek to secure hospital-based contracts and municipal agreements. The vendor base organizes around three tiers: national-scale integrated networks, regional specialist operators, and single-mode air or ground pure-plays. Two archetypes predominate: technology-forward platforms investing in electric drivetrains and telemedicine infrastructure, and legacy operators defending position through established reimbursement relationships. M&A activity and fleet electrification timelines represent the dominant competitive vectors reshaping positioning.
Among US-based national networks, American Medical Response and Global Medical Response exemplify scale-driven consolidation strategies. Falck A/S anchors European specialist positioning through its Danish corporate structure and Scandinavian operational concentration. Air Methods Corporation occupies the premium-tier air ambulance vector with hospital-based partnership models. These three entities represent distinct archetypes: integrated national scale, regional specialist depth, and vertical air transport focus.
| Leading Market Players |
|---|
| Global Medical Response |
| American Medical Response |
| Falck A/S |
| Acadian Ambulance Service |
| Air Methods Corporation |
| Lifeguard Ambulance Service |
| Envision Healthcare |
| REVA Air Ambulance |
| St John Ambulance |
| Others |
Value Network & Pricing Analysis
CMS reimbursement concentration among Medicare Advantage plans and state Medicaid managed care organizations anchors pricing power toward contract-based long-term offtake models rather than spot-market variability. Fleet operators serving these consolidated buyers negotiate multi-year municipal agreements that embed fuel escalation clauses and technology upgrade allowances.
Pricing Analysis
Aviation fuel and lithium-ion battery pack costs pass through to service rates via CMS reimbursement formulas and municipal contract escalation mechanisms. Three-tier pricing structure across air ambulance, advanced life support ground, and basic non-emergency transport separates clinical acuity levels with corresponding crew certification requirements. Pricing pressure stems from reimbursement compression as CMS adjusts fee schedules downward for repetitive non-emergency dialysis transfers. Medicaid managed care organizations exhibit highest price sensitivity due to per-member-per-month budget constraints, while air ambulance subscription members demonstrate lowest sensitivity given catastrophic exposure protection.
Supply Chain Analysis
Single-source vulnerability sits with FAA-certified airframe manufacturers in the United States and specialized aeromedical equipment suppliers in Germany and Switzerland. Critical components include night vision goggle systems, cardiac monitor-defibrillator units, and electric drivetrain battery modules. Supply chain risk centers on regulatory restriction as FAA Part 135 compliance extends lead times for replacement aircraft. Distribution runs through hospital-based partnership networks and municipal emergency services procurement departments rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where telemedicine-enabled pre-hospital protocols and electric fleet specifications command premium contract positioning against legacy diesel-dependent competitors.
For Market Incumbents: Lock in multi-year hospital system partnerships before Medicare Advantage plan consolidation reduces vendor slots in metropolitan markets. Accelerate backward integration into electric vehicle maintenance capabilities to capture IRA clean vehicle credit benefits and reduce third-party service dependency. Falck A/S and Air Methods Corporation demonstrate how specialized aeromedical depth defends position against national-scale ground transport roll-ups. For New Entrants and Emerging Players: Launch via mobile integrated healthcare units targeting rural hospital closure catchment zones in the Mississippi Delta and Texas Panhandle where incumbent presence has dissolved. White-space concentration sits with Medicaid managed care transport liaison services in Southeastern states where prior authorization complexity creates administrative friction. Stroke network certification requirements in the Upper Midwest present the most penetrable technology entry point for telemedicine platform specialists. For Investors and Strategic Acquirers: Private equity firms with healthcare services portfolios are the most active acquirer in this space, consolidating regional ground ambulance operators into platform-scale networks. Long-term viability hinges on reimbursement rate trajectory and fleet electrification capital efficiency rather than volume growth alone. Acquisition target archetype: regional operators with municipal contract concentration and nascent telemedicine deployment. The signal to watch is CMS Medicare Advantage coverage determination expansions for post-acute transport categories.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Conversion | IRA clean vehicle credits restructure total cost of ownership for municipal contract bidders against diesel legacy. |
| Telemedicine Platform Deployment | Stroke network certification requirements in Minnesota and Wisconsin accelerate pre-hospital specialist consultation adoption. |
| Hospital System Partnership Consolidation | Academic medical centers in Boston and Baltimore are reducing vendor counts under single-source transport agreements. |
| Air Ambulance Subscription Model Expansion | Annual membership plans in Colorado and Montana cap out-of-pocket exposure where median household income falls below median charges. |
| Mobile Integrated Healthcare Unit Launch | Rural hospital closures in Mississippi Delta and Texas Panhandle create whitespace for preventive transport-replacement services. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down fleet capacity tracking forms the analytical core of this study. Primary interviews with EMS directors, hospital discharge planners, Medicare Advantage contracting officers, and municipal procurement managers combined with secondary validation from CMS reimbursement databases, FAA Part 135 operator registries, and state emergency medical services licensing records. Triangulation across these sources isolates volume and value estimates from reporting bias inherent in single-source data.
Historical trendline analysis of ambulance response volume, air ambulance flight hours, and non-emergency medical transport trip frequency established baseline growth patterns. Segmentation modeling across service type, delivery mode, end-user setting, and technology deployment generated discrete forecast trajectories. CAGRs were derived from regression analysis of reimbursement rate changes, demographic shift projections, and fleet replacement cycles. Key inputs included CMS Medicare Advantage enrollment patterns and electric vehicle procurement incentive availability.
Several conditions sit outside the modeled scope, including unforeseen FAA regulatory changes to crew rest requirements, catastrophic aviation fuel price spikes beyond historical volatility bands, and state-level certificate-of-need law repeals that would alter market entry barriers. Forecasts reflect assumptions about reimbursement stability and technology adoption curves that external shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Global Ambulance Stretchers Market