
 North America Ambulance Services Market | 2026-2036
North America Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ambulance Services Market Intelligence
Market Context
The capital-intensity divergence between air medical operators and ground-based fleet providers is reorganizing competitive tiers across North America. Air Methods Corporation leverages its rotary-wing infrastructure to dominate mountainous and rural territories where hospital access times exceed clinical thresholds. American Medical Response sustains municipal contracts through scale advantages in metropolitan 911 dispatch systems. Falck A/S competes by specializing in hybrid public-private operating models that reduce taxpayer burden while maintaining response-time compliance.
Technical Definition and Segment Structure
Ambulance services encompass the pre-hospital emergency and non-emergency transport of patients via ground vehicles and rotary-wing aircraft, staffed by paramedics or emergency medical technicians certified to administer medications, airway management, and cardiac monitoring during transit. The primary commercial purpose is to bridge the spatial and temporal gap between incident sites and definitive care facilities while stabilizing patients en route. Emergency Medical Services generates the dominant revenue pool due to 911 dispatch mandates and insurance reimbursement guarantees, while Air Ambulance commands premium pricing for inter-facility transfers across vast rural geographies. Non-Profit operating models occupy a structural niche in underserved counties where pure private returns fail to justify fleet deployment.
Regulatory Framework
The Centers for Medicare and Medicaid Services, the Federal Aviation Administration, and state-level EMS regulatory boards collectively shape reimbursement schedules, aircraft certification requirements, and crew licensing standards across the United States and Canada. FAA Part 135 operational specifications dictate pilot duty limits and equipment minimums for air medical providers, while CMS fee schedules determine whether advanced life support calls qualify for higher reimbursement tiers. Stakeholders must monitor state Medicaid expansion decisions and cross-border airworthiness reciprocity agreements as these frameworks directly alter fleet investment viability and service area profitability.
Market Dynamics
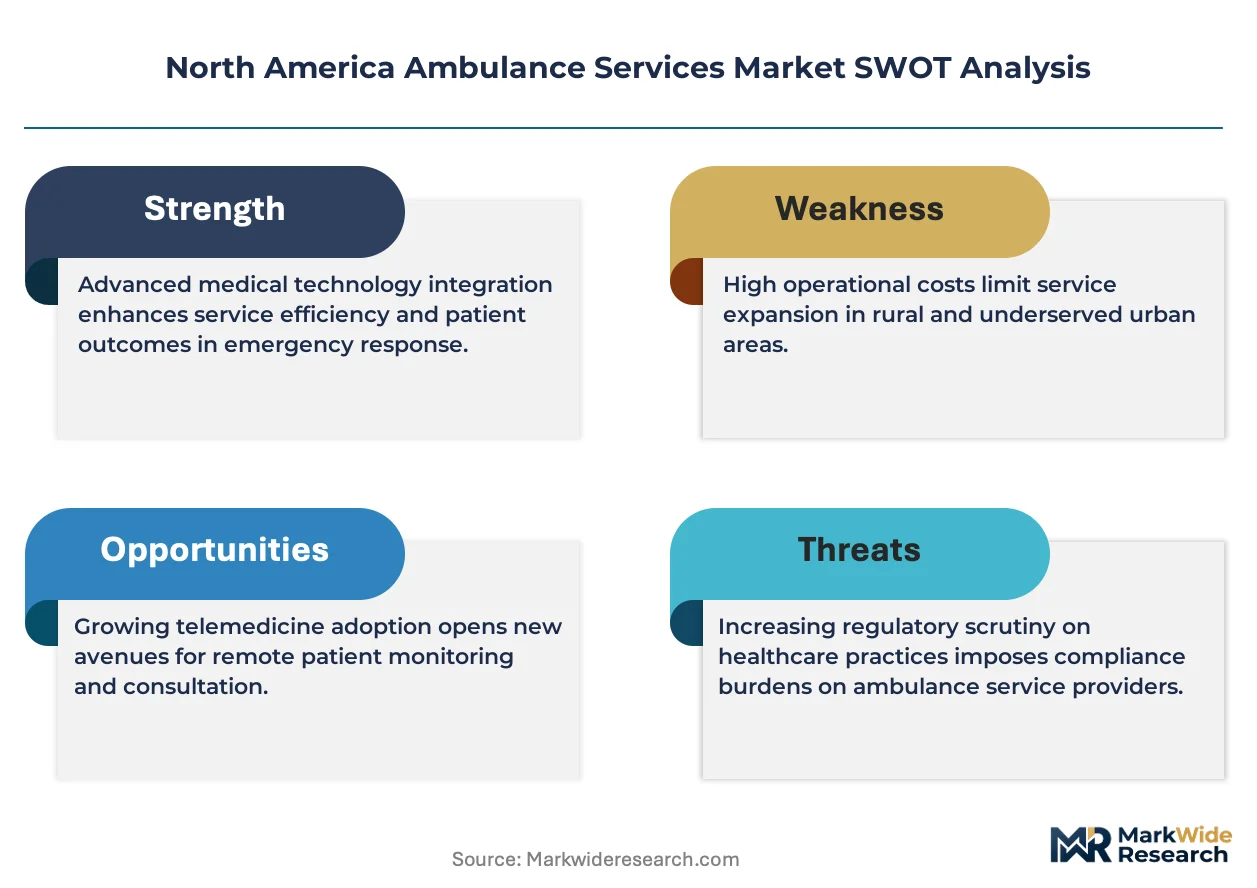
Rural hospital closures across the southeastern United States are extending ground-based emergency coverage gaps, forcing municipal governments to outsource ambulance contracts to private fleet operators capable of maintaining response-time compliance across dispersed populations.
Growth Catalysts
- CMS Reimbursement Tiers:Medicare's advanced life support fee schedules reward providers deploying cardiac-capable ground fleets, incentivizing equipment upgrades across county-level EMS systems.
- Aging Demographics:Florida's 65-plus population concentration generates sustained 911 call volume for stroke and cardiac emergency response, expanding municipal contract pools.
- FAA Part 135 Infrastructure:Rotary-wing certification standards for air medical operators enable inter-facility transfers across mountainous terrain where ground transport exceeds clinical windows.
Market Restraints
- Fuel Cost Volatility:Jet fuel and diesel price swings compress margins for air ambulance operators maintaining 24/7 rotary-wing readiness across vast service areas.
- Paramedic Labor Scarcity:Certification bottlenecks in Texas and Arizona limit crew availability, constraining fleet expansion regardless of capital deployment.
- Substitution by Telemedicine:Virtual emergency triage systems divert low-acuity calls from physical transport, reducing non-emergency revenue streams.
Strategic Opportunities
- Medicaid Expansion States:North Carolina's 2023 eligibility expansion creates insured patient pools previously served by uncompensated emergency response.
- Hybrid Public-Private Models:Canadian provincial health authorities are piloting performance-based ambulance contracts that reduce taxpayer burden while preserving service levels.
- Electric Ground Fleet Transition:California's Advanced Clean Trucks regulation is accelerating battery-electric ambulance trials for municipal 911 systems.
Industry Challenges
- EMT-Paramedic Pipeline Collapse:Community college training program closures in rural Georgia and Alabama are constraining crew replacement rates below attrition.
- Legacy Dispatch Integration:Proprietary CAD systems in legacy municipal contracts resist interoperability with next-generation fleet management platforms, delaying consolidation efficiencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ambulance Services Market |
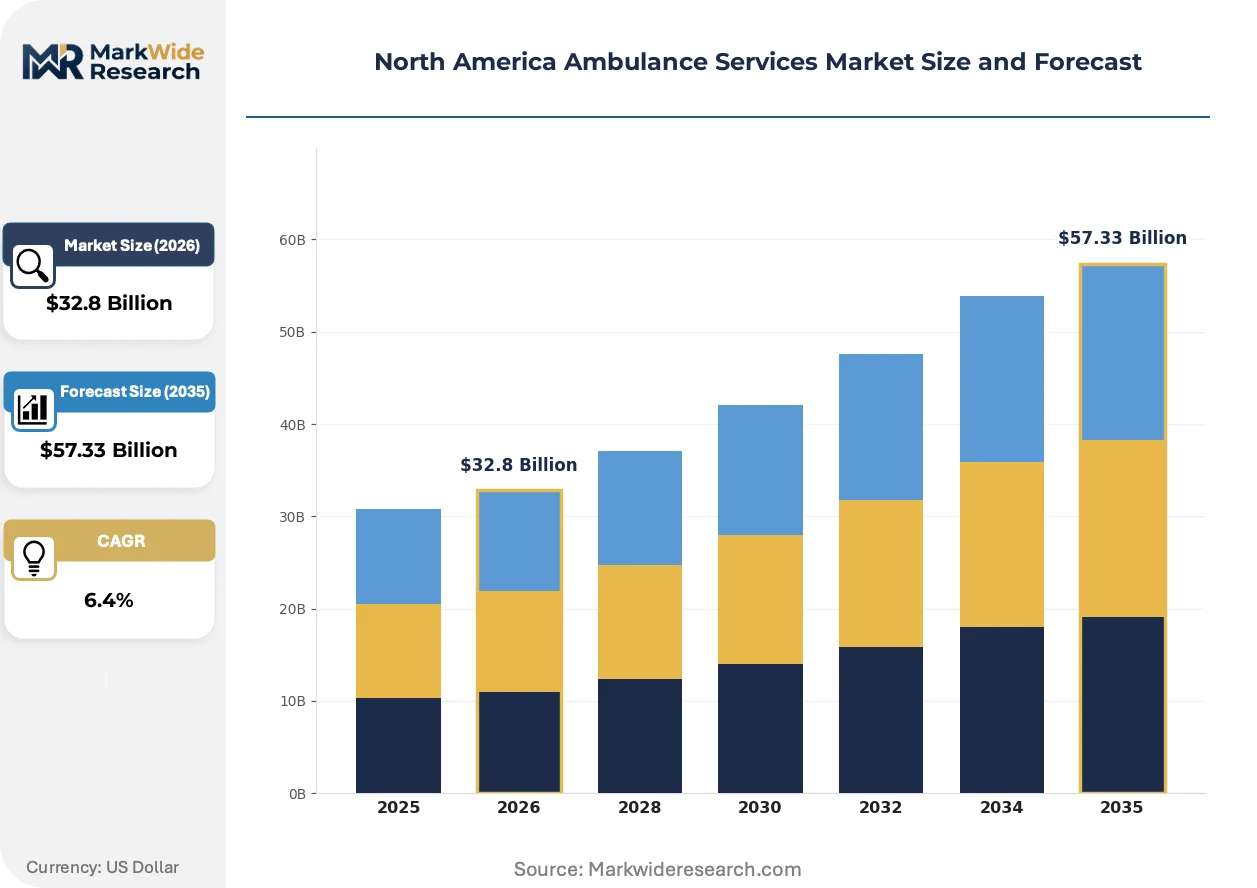
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $57.33 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Medical Services, Non-Emergency Transportation, Air Ambulance, Ground Ambulance End User: Hospitals, Private Clinics, Rehabilitation Centers, Homecare Providers Vehicle Type: ALS Vehicles, BLS Vehicles, Wheelchair Vans, Helicopters Operating Model: Public, Private, Hybrid, Non-Profit |
| Companies Covered | Air Methods Corporation, American Medical Response, Acadian Ambulance Service, PHI Air Medical, Global Medical Response, Envision Healthcare, Falck A/S, Air Medical Group Holdings, Babcock International Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ambulance Services Market Strategic Shifts & Innovations
Telemedicine integration and predictive dispatch algorithms are compressing response-time windows while regulatory pressure on emissions and crew safety reshapes fleet procurement criteria across North American EMS systems.
Telemedicine-enabled ambulance platforms are fragmenting traditional emergency response workflows. Advanced life support vehicles now incorporate real-time video consultation with emergency physicians, enabling field treatment decisions that previously required transport. Hospital systems in Colorado and Utah are deploying these units for stroke assessment, reducing unnecessary transfers. The technology is fragmenting the historical binary of treat-and-release versus transport-to-ED, creating intermediate clinical pathways that alter reimbursement capture.
CMS ambulance fee schedule reform proposals are restructuring provider economics. The proposed ground emergency medical transport quality reporting program ties reimbursement to response-time and clinical outcome metrics. Air ambulance operators face parallel scrutiny through the No Surprises Act's independent dispute resolution process for out-of-network billing. Rural providers in Montana and Wyoming are consolidating dispatch contracts to meet reporting infrastructure requirements.
Subscription-based membership models are displacing traditional fee-for-service emergency billing. Air Methods Corporation and regional cooperatives are marketing annual household memberships that cap out-of-pocket costs for air medical transport. Employer groups in the oil and gas sector across Texas and North Dakota are adopting these programs as recruitment tools. The shift is most visible in extractive industry corridors where helicopter evacuation coverage influences workforce retention.
North America Ambulance Services Market Segmentation
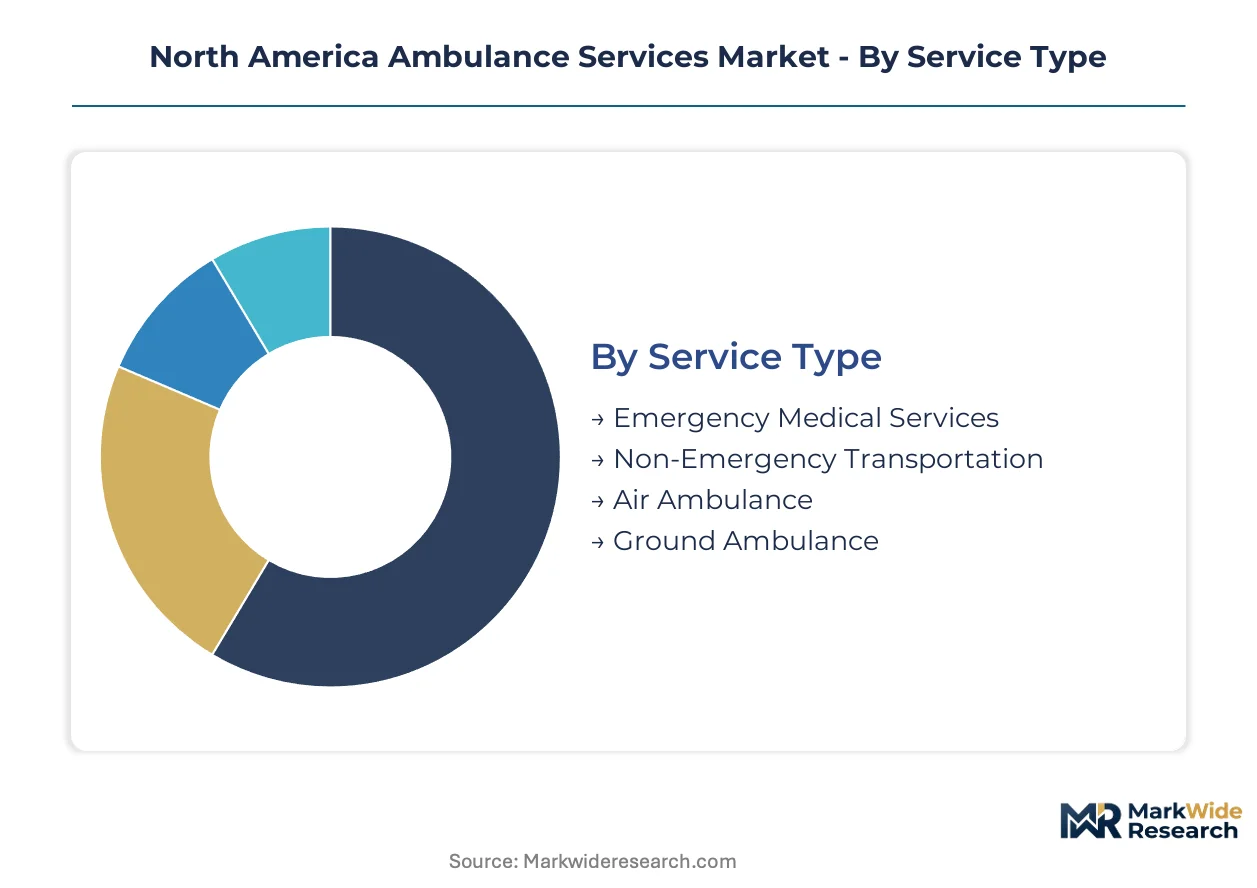
Segmentation reveals how reimbursement structures and fleet economics concentrate profitability across distinct operational modes. Understanding these divisions exposes where capital deployment generates sustainable returns versus where municipal contracts compress margins.
Service Type:
Margins cluster in premium-response tiers where clinical capability justifies elevated fee schedules.
- Emergency Medical Services:911-dispatch systems with cardiac-capable crews and advanced airway equipment. Florida's stroke-response corridors and Arizona's trauma deserts generate sustained call volume where Medicare ALS reimbursements exceed operational costs.
- Air Ambulance:Rotary-wing platforms certified under FAA Part 135 for inter-facility transfers across mountainous terrain. Montana and Wyoming providers capture premium pricing where ground transport exceeds the golden hour threshold for trauma and STEMI cases.
- Non-Emergency Transportation:Scheduled dialysis and discharge transfers reimbursed at lower BLS tiers.
- Ground Ambulance:Municipal 911 contracts with county-level EMS boards.
The dominant share belongs to Emergency Medical Services, while Air Ambulance is closing the gap fastest.
End User:
Contract stability varies sharply by purchaser sophistication and payment guarantee structures.
- Hospitals:Health systems with dedicated transfer agreements and in-house dispatch coordination. Southeast hospital closures are forcing remaining facilities to outsource emergency coverage to private fleet operators.
- Private Clinics:Outpatient surgical centers requiring standby ambulance presence for sedation complications.
- Rehabilitation Centers:Post-acute facilities managing recurring patient mobility needs.
- Homecare Providers:Hospice agencies arranging palliative transport for terminal patients.
Hospitals command the largest contract volume, though Private Clinics are expanding standby agreements most rapidly.
Vehicle Type:
Capital intensity and crew certification requirements create distinct competitive moats across fleet categories.
- ALS Vehicles:Advanced life support units with 12-lead ECG, medication refrigerators, and intubation capability. Texas and Arizona counties are upgrading BLS fleets to meet CMS quality reporting thresholds for cardiac emergency reimbursement.
- Helicopters:Twin-engine rotary-wing platforms with IFR certification for night and weather operations. Colorado and Utah health systems deploy these for stroke assessment, reducing unnecessary transfers through field telemedicine consultation.
- BLS Vehicles:Basic life support transport with EMT-level staffing.
- Wheelchair Vans:Non-emergency mobility vehicles for ambulatory patients.
ALS Vehicles retain the largest installed base, while Helicopters are gaining share fastest in rural coverage gaps.
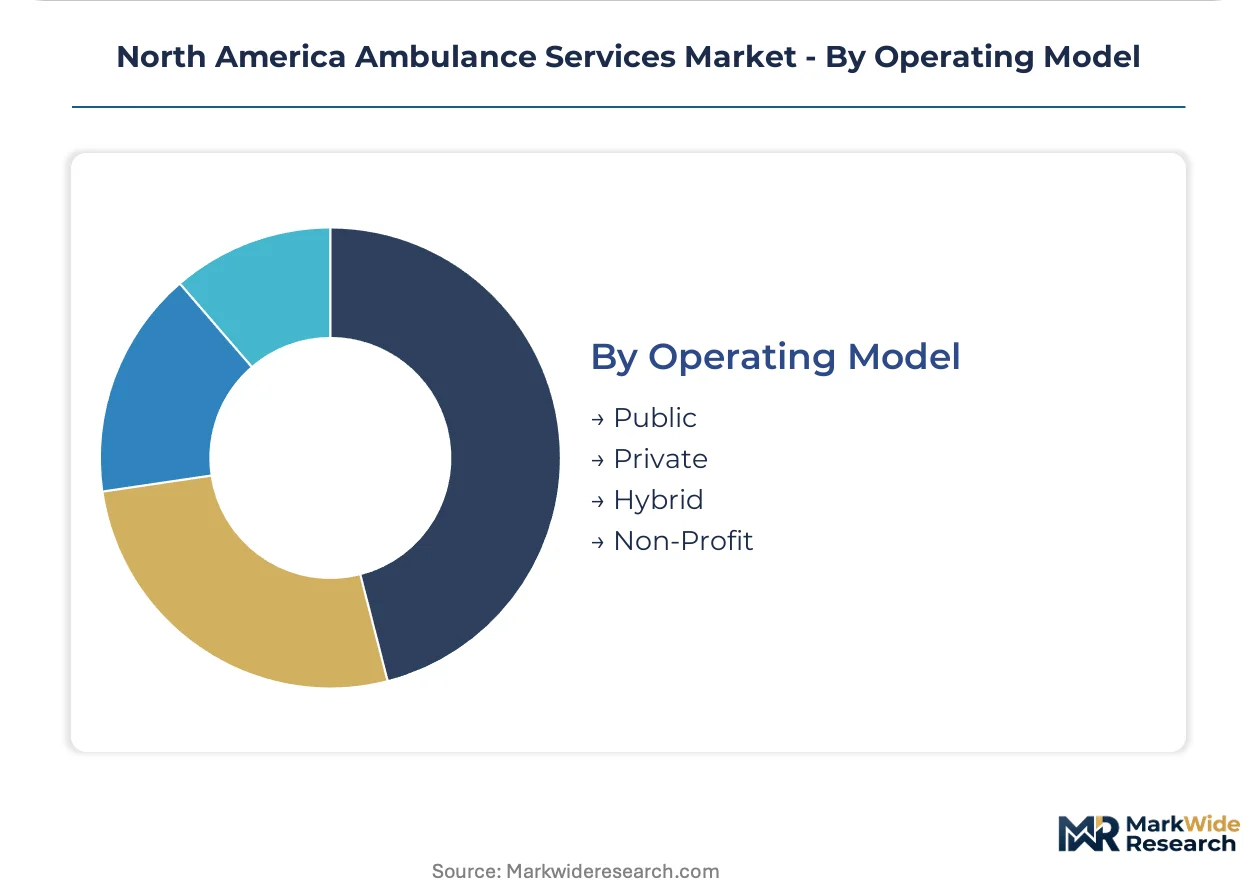
Operating Model:
Reimbursement capture and taxpayer burden tradeoffs define competitive positioning across ownership structures.
- Private:Investor-owned operators bidding municipal contracts through scale advantages in dispatch technology and fleet maintenance. American Medical Response sustains metropolitan 911 systems through consolidated regional operations.
- Hybrid:Public-private partnerships where county authorities retain oversight while private operators manage crew deployment and vehicle maintenance. Canadian provincial health authorities are piloting performance-based contracts that preserve service levels while reducing fiscal exposure.
- Public:Municipal fire-department-based EMS with civil service staffing.
- Non-Profit:Community cooperatives serving counties where pure private returns fail to justify fleet deployment.
Private operators hold the dominant contract share, though Hybrid models are expanding most quickly across Canadian provinces and US counties seeking budget relief.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates regional service volume while Canada maintains a modest export surplus in air medical training and certification services. Cross-border fleet reciprocity agreements under FAA-Transport Canada harmonization protocols facilitate equipment standardization. Mexico's emerging private ambulance sector attracts capital from US operators seeking lower-cost dispatch infrastructure.
United States
Rural hospital closures across Georgia and Alabama stretch emergency coverage into transport deserts. CMS advanced life support reimbursement tiers incentivize cardiac-capable fleet upgrades in Texas counties. Florida's stroke-response corridors concentrate municipal contract awards around Tampa and Miami metropolitan dispatch systems.
Canada
Provincial health authorities in Ontario and Quebec pilot performance-based ambulance contracts reducing direct taxpayer burden. Transport Canada Part VII commercial air regulations govern rotary-wing medical certification standards. Calgary and Edmonton health systems deploy hybrid public-private models for inter-facility transfers across Alberta's vast northern territories.
Mexico
Private clinic expansion in Mexico City and Monterrey generates standby ambulance demand for outpatient surgical complications. The country's federal health secretariat maintains basic EMS licensing frameworks while state-level jurisdictions experiment with municipal outsourcing. Baja California border corridors attract US-based operators seeking cross-border patient transfer agreements.
North America Ambulance Services Market Key Industry Players
Concentration sits with diversified emergency services conglomerates controlling metropolitan 911 dispatch contracts and air medical infrastructure simultaneously. The vendor base spans three tiers: integrated national operators sustaining scale advantages in fleet maintenance, regional specialists dominating rural coverage gaps through rotary-wing certification, and municipal fire-department-based systems resisting privatization. Strategic moves center on dispatch technology consolidation and cross-border airworthiness reciprocity negotiations.
Within the integrated emergency services tier, Global Medical Response and Envision Healthcare exemplify scale-driven operators with diversified service portfolios spanning ground and air platforms. Air Methods Corporation occupies a distinct position as a rotary-wing specialist leveraging mountainous terrain coverage where ground transport fails clinical thresholds. American Medical Response anchors metropolitan contract concentration through consolidated regional dispatch systems.
| Leading Market Players |
|---|
| Air Methods Corporation |
| American Medical Response |
| Acadian Ambulance Service |
| PHI Air Medical |
| Global Medical Response |
| Envision Healthcare |
| Falck A/S |
| Air Medical Group Holdings |
| Babcock International Group |
| Others |
Cost & Logistics Intelligence
Ninety-day lead times for FAA Part 135 rotary-wing airframes concentrate pricing power with certified air medical operators while squeezing ground-based fleet providers competing on municipal contract bids. This inventory compression shapes how American Medical Response and Air Methods Corporation negotiate reimbursement tiers with CMS and county-level EMS boards.
Pricing Analysis
The customization-premium spread between configured-to-order ALS vehicles and standard BLS fleet configurations runs through equipment certification levels and cardiac-capable crew training. Contract-based long-term municipal agreements dominate, with price differentiation anchored in CMS advanced life support reimbursement tiers and FAA rotary-wing certification. Pricing pressure stems from fuel cost volatility compressing air ambulance margins. Municipal 911 systems show highest price sensitivity due to taxpayer budget constraints, while hospital systems exhibit lowest sensitivity due to guaranteed Medicare pass-through mechanisms.
Supply Chain Analysis
Ninety-day lead times for specialized air medical platforms and stretched paramedic training pipelines constrain fleet expansion regardless of capital deployment. Manufacturing concentrates in the United States for ground ambulance chassis, Canada for rotary-wing airframe components, and Mexico for basic life support vehicle assembly. Supply chains draw from jet fuel and diesel distributors, medical equipment OEMs, and EMT-paramedic training institutions. Single-source vulnerability sits with FAA-certified pilot training programs. Distribution runs through municipal procurement offices, hospital system GPOs, and provincial health authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as Medicaid expansion states generate insured patient pools previously served by uncompensated emergency response, accelerating addressable market penetration across the southeastern United States.
For Market Incumbents: Compound dispatch technology consolidation advantages by acquiring proprietary CAD systems in legacy municipal contracts, resisting interoperability with next-generation fleet management platforms. Deepen backward integration into paramedic training pipelines through community college partnerships in Texas and Arizona, countering certification bottlenecks that constrain crew replacement rates below attrition. For New Entrants and Emerging Players: State-level EMS licensing fast-tracks in North Carolina and Canadian provincial health authority pilot programs create accessible entry points. Target hybrid public-private operating models in Canadian provinces and US counties seeking budget relief, where performance-based contracts reduce taxpayer burden while preserving service levels. Pursue employer-group subscription models in extractive industry corridors as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified emergency services conglomerates seeking to divest non-core rotary-wing assets or rural ground fleet operations. Long-term viability favors operators controlling both metropolitan 911 dispatch contracts and mountainous terrain air medical infrastructure. Monitor CMS ambulance fee schedule reform proposals and state Medicaid expansion decisions as the critical inflection signal for reimbursement capture rates.| Strategic Initiative | Industry Significance |
|---|---|
| Dispatch Technology Consolidation | Proprietary CAD system acquisition locks in municipal contract renewals across Florida stroke-response corridors. |
| Backward Integration into Training | Community college paramedic program partnerships in Texas and Arizona secure crew pipeline against certification bottlenecks. |
| Hybrid Public-Private Partnership | Performance-based contracts with Canadian provincial health authorities reduce taxpayer exposure while preserving response-time compliance. |
| Subscription Membership Model | Annual household memberships cap out-of-pocket costs for air medical transport in North Dakota oil and gas corridors. |
| Electric Fleet Transition | Battery-electric ambulance trials under California's Advanced Clean Trucks regulation position operators for emissions compliance. |
Research Approach
Operator-level perspectives from EMS dispatch directors, county-level EMS board administrators, hospital system transfer coordinators, and FAA Part 135 compliance officers anchored the qualitative base. Secondary validation drew from CMS Medicare reimbursement databases, FAA operational specifications filings, state EMS regulatory board records, and municipal procurement contract archives. Bottom-up fleet deployment modeling triangulated with top-down reimbursement flow analysis across the analysis window.
Sensitivity analysis tested forecast outputs against paramedic labor scarcity scenarios, fuel cost volatility bands, and telemedicine substitution rates. Segmentation dimensions modeled include service type, vehicle platform, operating model, and end-user contract structure. CAGRs derived from equipment replacement cycles, reimbursement schedule adjustments, and demographic call-volume projections. Forecast inputs incorporated rural hospital closure trajectories and FAA-Transport Canada harmonization protocols.
The analysis sits within stated boundaries; outcomes outside sustained CMS advanced life support reimbursement tiers or accelerated telemedicine adoption would require recalibration. Forecasts reflect documented assumptions regarding state Medicaid expansion timing and rotary-wing certification pipeline capacity. Specific risk factors include EMT-paramedic training program closures in rural Georgia and Alabama, and FAA Part 135 pilot duty limit revisions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
US Hospital Emergency Department Market