
 Aerospace and Life Sciences TIC Market | 2026-2036
Aerospace and Life Sciences TIC Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace and Life Sciences TIC Market Intelligence
Asset-light leasing models for advanced analytical equipment is fragmenting capital barriers among testing providers. SGS leverages its geographic density to sustain multi-site accreditation networks across aerospace supply chains. Bureau Veritas anchors its position through specialized composite materials testing for next-generation aircraft programs.
Aerospace and Life Sciences TIC encompasses technical inspection, certification, and testing services governed by material traceability protocols, sterile manufacturing validation, and non-destructive evaluation methods such as ultrasonic phased-array and computed radiography. These services verify structural integrity of turbine alloys and biologic drug purity against pharmacopeial standards. Inspection services dominate revenue flow due to mandatory airworthiness directives and batch release requirements, while chromatography-based testing captures expanding margin pools from complex biologics and gene therapy analytics. Supply chain management applications are maturing as manufacturers integrate vendor qualification into enterprise quality systems.
FAA airworthiness regulations, FDA Current Good Manufacturing Practice frameworks, and EASA Part 21 design approval standards collectively mandate third-party verification before market authorization. REACH chemical substance registration in Europe and EPA emission testing protocols in the United States further extend compliance scope into materials sourcing. Stakeholders must monitor convergence between aerospace digital thread requirements and life sciences data integrity standards as both sectors advance toward continuous verification models.
Market Dynamics
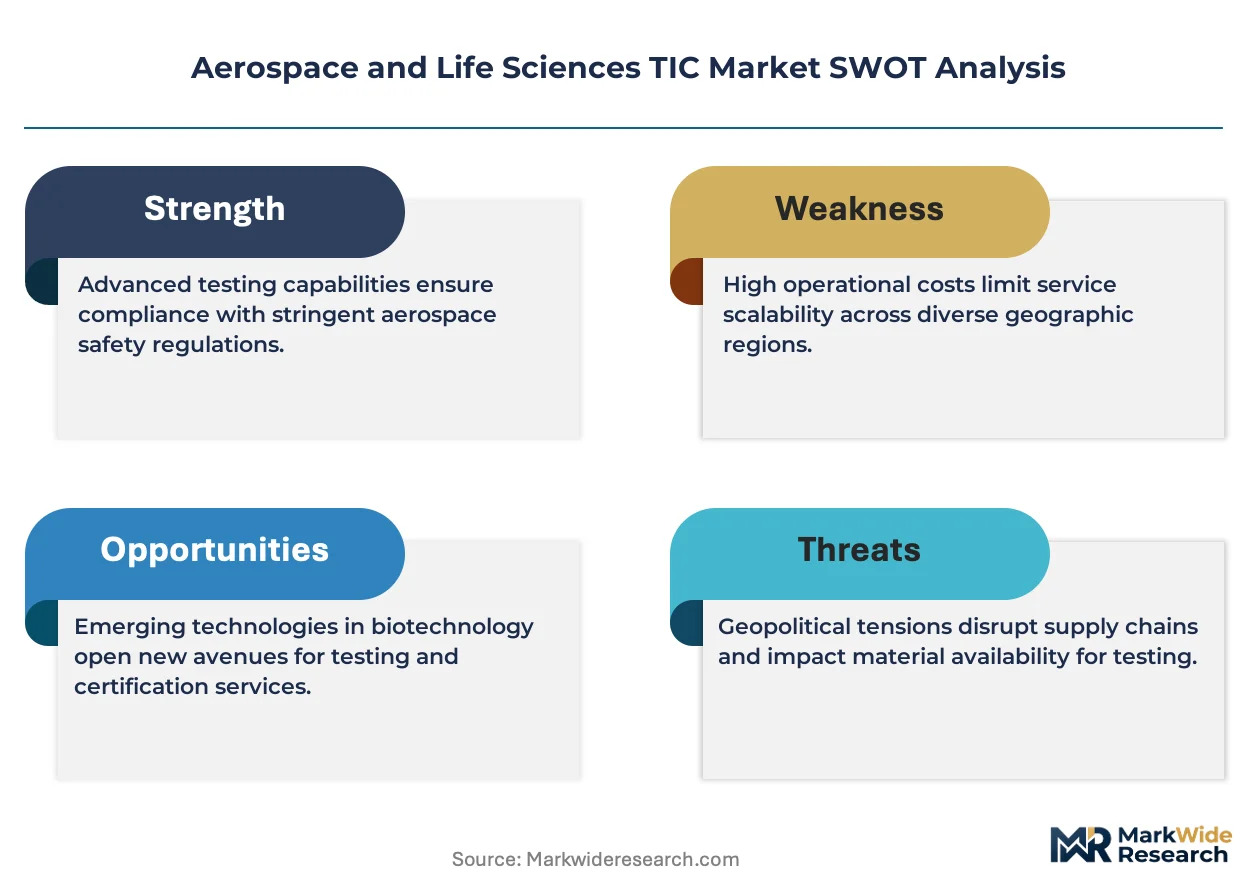
Continuous manufacturing mandates from FDA and EMA are compressing batch release timelines, forcing TIC providers to embed real-time analytics into sterile production lines rather than perform post-hoc verification.
Growth Catalysts
- EU Medical Device Regulation:MDR's expanded clinical evidence requirements for Class III devices are extending third-party notified body engagement durations, deepening revenue per engagement.
- Gene therapy commercialization:Viral vector manufacturing scale-up is generating demand for chromatographic purity testing and endotoxin validation services.
- Composite airframe adoption:Boeing and Airbus next-generation programs require specialized non-destructive evaluation for carbon fiber layup integrity, anchoring testing demand in Wichita and Hamburg industrial clusters.
Market Restraints
- Helium supply concentration:Mass spectrometry and leak detection depend on helium sourced primarily from Qatar and Algeria, exposing testing labs to price volatility and allocation constraints.
- Accreditation scarcity:ISO/IEC 17025 multi-site certification requires 18-24 month lead times, capping expansion velocity for mid-tier providers.
- Phased-array equipment costs:Ultrasonic testing systems for turbine blade inspection carry six-figure capital requirements, fragmenting capability distribution toward asset-heavy incumbents.
Strategic Opportunities
- India CDSCO alignment:India's pharmaceutical export growth is creating demand for US FDA and EU GMP pre-certification services within domestic testing infrastructure.
- Digital thread convergence:Aerospace model-based definition standards are fusing with life sciences ALCOA+ data integrity requirements, opening integrated compliance platforms.
- Continuous bioprocessing:Perfusion cell culture systems require novel in-line analytics for critical quality attributes, displacing traditional at-line testing workflows.
Industry Challenges
- ASNT Level III certification gaps:Advanced non-destructive testing disciplines including phased-array ultrasonics and digital radiography face acute technician shortages across North American aerospace corridors.
- LIMS integration complexity:Laboratory information management systems must reconcile 21 CFR Part 11 electronic records with AS9100 configuration management, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace and Life Sciences TIC Market |
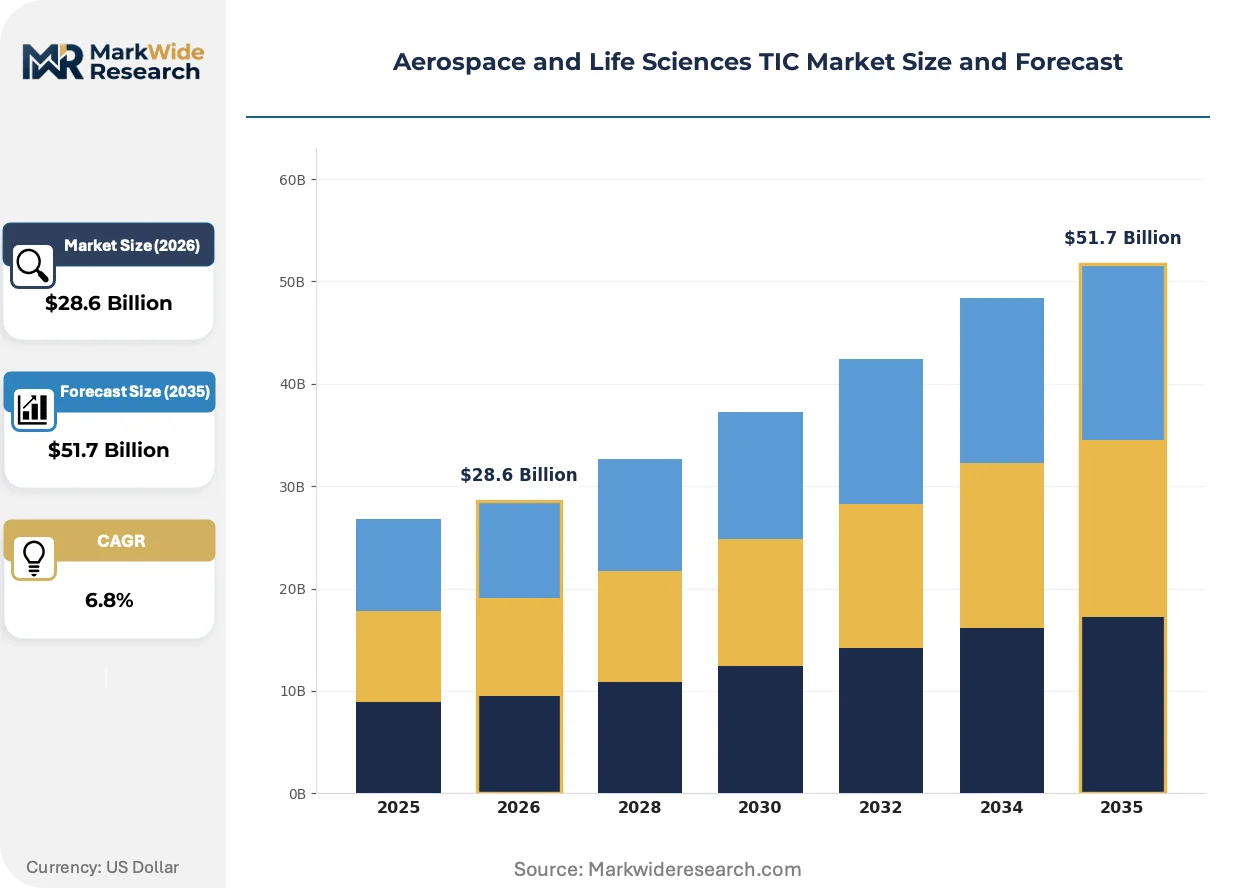
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Inspection, Certification, Testing, Auditing, Consulting Technology: Non-Destructive Evaluation, Chromatography, Spectroscopy, Microscopy, Biochemical Assays Application: Supply Chain Management, Quality Assurance, Regulatory Compliance, Risk Assessment, Product Validation End User: Manufacturers, Research Institutions, Regulatory Agencies, Contract Research Organizations, Quality Laboratories |
| Companies Covered | SGS, Bureau Veritas, Intertek Group, TÜV SÜD, Eurofins Scientific, TÜV Rheinland, Element Material Technology, UL, MISTRAS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace and Life Sciences TIC Market Strategic Shifts & Innovations
Digital verification architectures are displacing document-based compliance, with blockchain-anchored certificates and machine-readable audit trails compressing regulatory review cycles across both aerospace supply chains and pharmaceutical release workflows.
Process analytical technology is collapsing the distinction between manufacturing and quality operations. PAT sensors for real-time potency and purity monitoring enable parametric release of biologic batches, eliminating quarantine inventory holding. Biopharmaceutical manufacturers in Massachusetts and North Carolina are deploying PAT at commercial scale, compressing working capital requirements by 30-40% relative to traditional batch release.
EMA's Annex 1 revision on sterile manufacturing mandates barrier isolation and automated environmental monitoring, extending validation scope into facility airflow modeling and gloveless robotic aseptic processing. Fill-finish contractors in Ireland and Belgium are retrofitting isolator lines, deepening demand for smoke study visualization and continuous particle monitoring calibration services.
Vendor qualification consolidation is compressing TIC provider rosters at major pharmaceutical and medical device manufacturers. Procurement functions are mandating single-source master service agreements covering analytical testing, audit services, and regulatory consulting, displacing fragmented multi-vendor arrangements. This concentration is most visible among top-20 biopharmaceutical companies headquartered in New Jersey and Basel.
Aerospace and Life Sciences TIC Market Segmentation
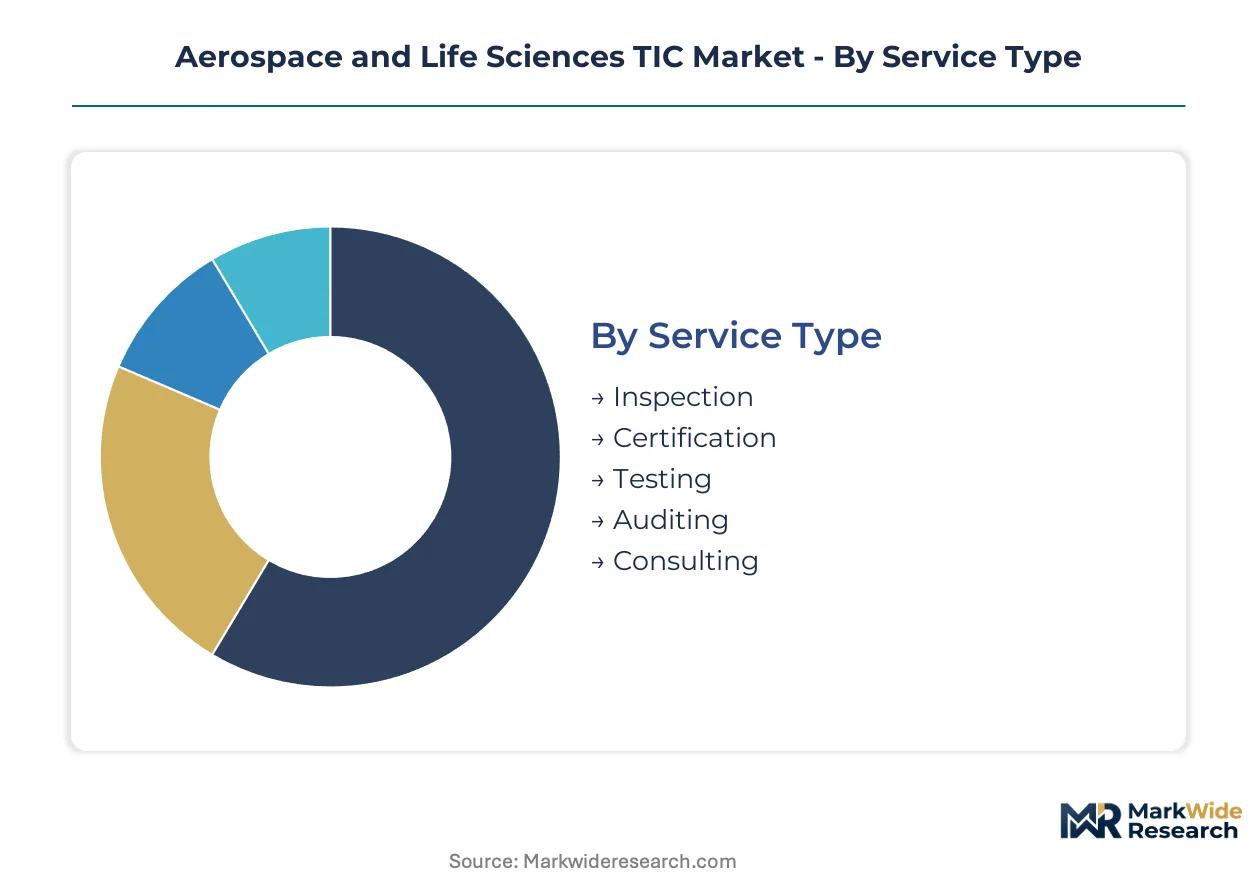
Segmentation in Aerospace and Life Sciences TIC reveals divergent margin structures and capital intensity across service delivery modes. Inspection and testing cycles compress under continuous manufacturing mandates while certification engagements lengthen under stricter evidentiary standards. Technology deployment varies sharply between asset-heavy analytical platforms and knowledge-intensive advisory functions.
Service Type:
Inspection contracts turn over fastest on turbine blade and airframe audit cycles, while certification engagements stretch across multi-year design approval processes. Consulting engagements pulse with regulatory deadline clustering.
- Inspection:Mandatory airworthiness directives and batch release protocols drive recurring turbine alloy and sterile manufacturing line audits. Demand concentrates in Wichita's aviation cluster and Ireland's fill-finish pharmaceutical corridor under FAA and EMA jurisdiction.
- Certification:Extended design approval timelines under EASA Part 21 and FDA quality system regulations anchor multi-year revenue streams. German composite airframe programs and Swiss medical device manufacturers sustain the longest engagement durations.
- Testing:Chromatographic purity and non-destructive evaluation cycles align with production batch frequency.
- Auditing:Vendor qualification and GMP compliance reviews follow annual or biennial regulatory calendars.
- Consulting:Regulatory strategy and submission preparation spike around FDA guidance finalization and EMA opinion publication.
Inspection dominates installed base. Certification is where expansion concentrates.
Technology:
Capital deployment stratifies sharply between six-figure ultrasonic systems and portable biochemical assays. Non-destructive evaluation requires the heaviest infrastructure while spectroscopy benefits from leasing model proliferation.
- Non-Destructive Evaluation:Phased-array ultrasonics and computed radiography verify carbon fiber layup integrity and turbine blade microstructure. Boeing and Airbus next-generation programs in Hamburg and Wichita anchor equipment utilization rates.
- Chromatography:Viral vector purity testing and gene therapy analytics command premium pricing. Massachusetts and North Carolina biopharmaceutical manufacturers deploy high-resolution liquid chromatography at commercial scale.
- Spectroscopy:Mass spectrometry faces helium supply constraints from Qatar and Algeria sourcing concentration.
- Microscopy:Environmental monitoring and particle characterization support isolator validation under revised EMA Annex 1.
- Biochemical Assays:Endotoxin and sterility testing align with batch release velocity requirements.
Non-Destructive Evaluation captures the steepest expansion trajectory. Biochemical Assays maintain the broadest installed footprint.
Application:
Supply chain management applications mature fastest as enterprise quality systems integrate vendor qualification. Risk assessment functions elongate under complex biologics and composite material uncertainty.
- Supply Chain Management:Multi-tier supplier auditing and material traceability protocols now embed directly into ERP platforms. Procurement consolidation at New Jersey and Basel headquartered manufacturers compresses provider rosters.
- Quality Assurance:Process analytical technology deployment collapses traditional at-line testing into real-time release decisions. PAT sensor validation in Massachusetts biologics facilities eliminates quarantine inventory holding.
- Regulatory Compliance:EU MDR clinical evidence requirements and FDA continuous manufacturing guidance extend verification scope.
- Risk Assessment:Gene therapy viral vector safety and composite airframe fatigue modeling demand specialized actuarial expertise.
- Product Validation:Sterile barrier isolation and robotic aseptic processing validation deepens in Belgium and Ireland contract manufacturing.
Quality Assurance commands the highest margin expansion. Supply Chain Management shows the widest adoption curve.
End User:
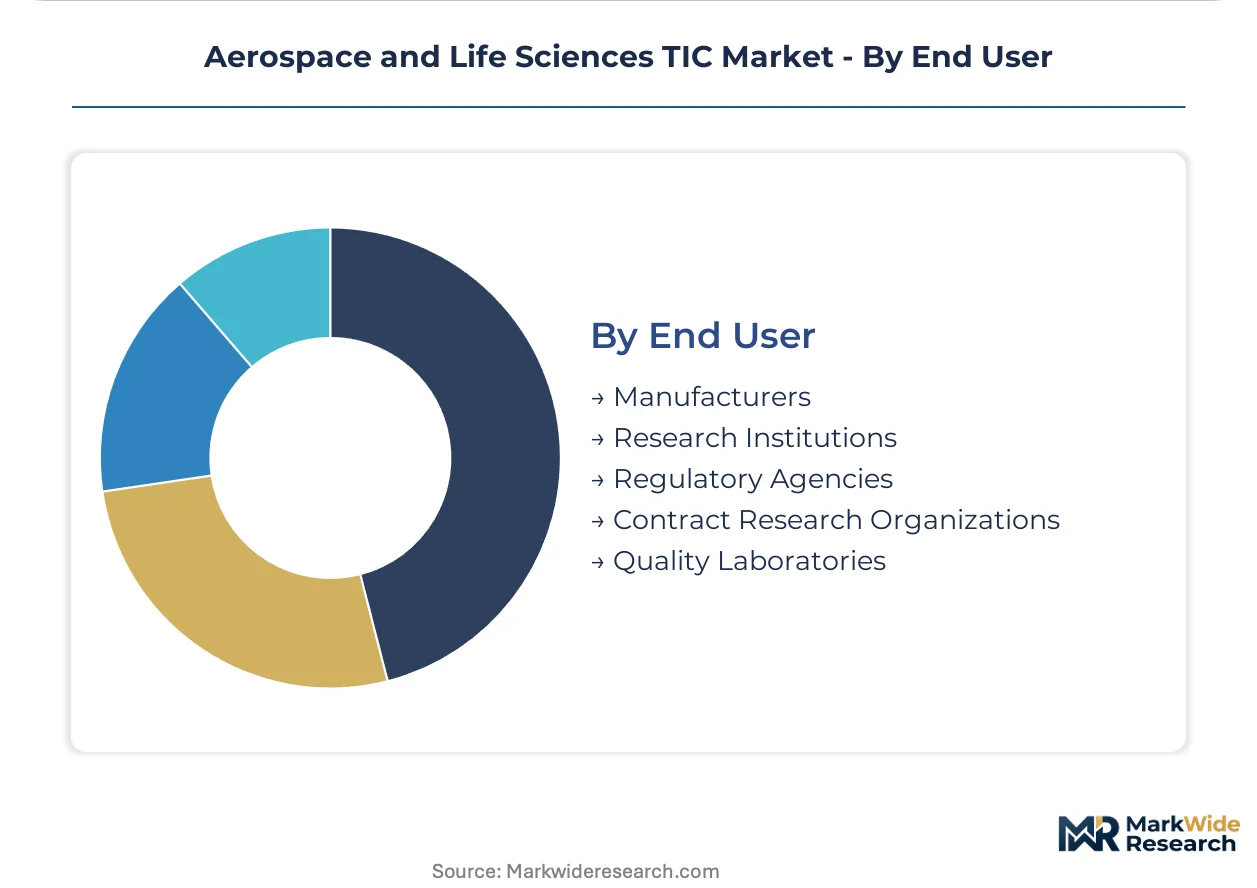
Manufacturer procurement cycles drive volume concentration while regulatory agency outsourcing creates episodic demand spikes. Research institution spending fluctuates with grant award timing.
- Manufacturers:Biopharmaceutical and aerospace OEMs consolidate testing spend under single-source master service agreements. Top-20 pharmaceutical companies in New Jersey and Basel mandate unified analytical, audit, and consulting contracts.
- Contract Research Organizations:CDMO quality laboratories in India seek US FDA and EU GMP pre-certification for export market access.
- Research Institutions:Academic medical centers and national laboratories pilot novel gene therapy analytics.
- Regulatory Agencies:FDA and EMA third-party inspection outsourcing creates qualified body capacity constraints.
- Quality Laboratories:Independent testing facilities compete on ISO/IEC 17025 multi-site accreditation density.
Manufacturers concentrate revenue volume. Contract Research Organizations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturers and aerospace OEMs cluster their quality validation spend in jurisdictions with stringent regulatory enforcement and dense supplier ecosystems. FDA-regulated corridors in the United States, EASA-governed industrial zones in Germany, and emerging CDSCO-aligned testing infrastructure in India concentrate procurement decisions for third-party verification services.
United States
Massachusetts and North Carolina biopharmaceutical manufacturers deploy process analytical technology at commercial scale, eliminating quarantine inventory holding through real-time batch release. FDA continuous manufacturing guidance tightens verification timelines for sterile production lines. Wichita's aviation cluster sustains phased-array ultrasonic testing demand for turbine blade integrity validation under FAA airworthiness directives.
Germany
Composite airframe programs in Hamburg and Bavaria anchor non-destructive evaluation equipment utilization for carbon fiber layup verification. EASA Part 21 design approval standards extend certification engagement durations across multi-year timelines. REACH chemical substance registration extends compliance scope into materials sourcing for aerospace supply chains.
Switzerland
Basel-headquartered pharmaceutical manufacturers consolidate testing spend under single-source master service agreements covering analytical, audit, and consulting functions. Swissmedic oversight aligns with EU GMP standards for export market access. The Lake Geneva corridor concentrates gene therapy viral vector manufacturing, driving chromatographic purity testing demand.
India
CDSCO-aligned quality laboratories in Maharashtra and Gujarat seek US FDA and EU GMP pre-certification for pharmaceutical export market access. Domestic biopharmaceutical manufacturing scale-up generates demand for endotoxin validation and sterility testing services. Hyderabad and Bangalore clusters attract multi-site ISO/IEC 17025 accreditation investments from international TIC providers.
United Kingdom
EMA Annex 1 revision on sterile manufacturing drives isolator line retrofitting among fill-finish contractors in England and Ireland. MHRA recognition agreements sustain post-Brexit market access verification requirements. Cambridge and Oxford medical research corridors pilot novel gene therapy analytics for commercial manufacturing transfer.
Aerospace and Life Sciences TIC Market Key Industry Players
Channel-controlling players compete with product-specialist players across accreditation density and equipment asset bases. The vendor base stratifies between asset-heavy incumbents sustaining multi-site ISO/IEC 17025 networks and mid-tier providers leasing advanced analytical platforms to bypass capital barriers. Three archetypes dominate: geographic density specialists anchoring aerospace supply chain verification, composite materials testing specialists serving next-generation aircraft programs, and chromatography-focused operators capturing gene therapy analytics margins. Competitive moves concentrate on strategic partnerships for digital thread convergence and selective capacity expansion in India and Switzerland.
Within the geographic density tier, SGS exemplifies multi-site accreditation network sustainability across aerospace supply chains. Bureau Veritas occupies a position as composite materials testing specialist for next-generation aircraft programs. Eurofins Scientific sits within the chromatography-focused archetype, representing premium pricing capture from complex biologics and gene therapy analytics. These three anchors illustrate divergent capital deployment strategies: SGS through network breadth, Bureau Veritas through materials specialization, Eurofins through analytical platform intensity.
| Leading Market Players |
|---|
| SGS |
| Bureau Veritas |
| Intertek Group |
| TÜV SÜD |
| Eurofins Scientific |
| TÜV Rheinland |
| Element Material Technology |
| UL |
| MISTRAS |
| Others |
Cost & Logistics Intelligence
Hamburg-Wichita aerospace freight corridors transmit helium price volatility from Qatar and Algeria directly into chromatography testing rates, while CDSCO-aligned laboratories in India arbitrage cost spreads between domestic accreditation and FDA pre-certification premiums. This logistics-cost passthrough concentrates pricing power among asset-heavy incumbents with captive gas reserves and multi-site ISO/IEC 17025 networks.
Pricing Analysis
Cost-plus contracts with helium indexation dominate mass spectrometry and leak detection services, anchoring rates to spot markets in Doha and Algiers. Price differentiation separates ISO/IEC 17025 multi-site accredited providers from single-facility competitors, with ASNT Level III technician density commanding additional premiums. Pricing pressure stems from mid-tier providers leasing phased-array equipment to bypass six-figure capital barriers, compressing margins in ultrasonic turbine blade inspection. Contract research organizations in India exhibit highest price sensitivity due to CDSCO export compliance cost burdens, while Basel-headquartered pharmaceutical manufacturers prioritize accreditation density over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in Qatar and Algeria exposes testing laboratories to helium allocation constraints and price spikes that propagate through mass spectrometry workflows. Critical inputs include phased-array ultrasonic transducers sourced from German precision manufacturers, viral vector reference standards from Massachusetts biopharmaceutical suppliers, and composite layup verification equipment anchored in Hamburg industrial clusters. Single-source vulnerability concentrates in noble gas supply chains, with distribution running through specialty gas distributors serving ISO/IEC 17025 networks. Regional accreditation bodies in India and Switzerland are expanding domestic calibration infrastructure to reduce import dependency for critical analytical consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as vendor qualification consolidation at top-20 biopharmaceutical manufacturers displaces fragmented multi-vendor arrangements, opening niches for specialized chromatography and composite materials testing operators.
For Market Incumbents: Insulate multi-site accreditation networks against mid-tier leasing competitors by deepening technician certification pipelines in ASNT Level III disciplines. Anchor position through backward integration into helium storage and recovery systems, mitigating feedstock volatility that threatens margin stability in mass spectrometry services.
For New Entrants and Emerging Players: India's CDSCO-aligned quality laboratories in Maharashtra and Gujarat represent the most penetrable geography, with domestic pharmaceutical export growth outpacing accredited testing capacity. Target gene therapy viral vector analytics as the fastest-expanding service white-space, leveraging partnerships with Massachusetts and North Carolina biopharmaceutical manufacturers seeking India-based pre-certification for FDA market access.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized aerospace testing divisions, particularly those holding EASA Part 21 certification capabilities in German composite manufacturing clusters. Long-term viability rests on exposure to continuous manufacturing mandates and digital thread convergence between aerospace and life sciences compliance platforms. Monitor FDA guidance finalization on real-time release testing as the inflection signal for PAT sensor validation service demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Accreditation Expansion | ISO/IEC 17025 network density in India and Switzerland captures vendor qualification consolidation spend. |
| Helium Recovery Infrastructure Investment | Captive gas recycling systems insulate chromatography margins from Qatar supply volatility. |
| PAT Sensor Validation Partnership | Real-time analytics integration with Massachusetts biopharmaceutical manufacturers displaces traditional batch release. |
| ASNT Level III Technician Pipeline | Certification capacity in Wichita and Hamburg aviation clusters sustains phased-array utilization rates. |
| Digital Thread Platform Development | ALCOA+ data integrity convergence with aerospace model-based definition standards opens integrated compliance revenue. |
Research Approach
Desk research of EASA airworthiness directives, FDA guidance documents, and REACH chemical registration databases preceded structured interviews with quality laboratory directors, regulatory affairs leads at biopharmaceutical manufacturers, aerospace procurement officers in Wichita and Hamburg, and CDSCO compliance specialists in India. Secondary validation drew from ISO/IEC 17025 accreditation registries, helium trade flow data, and patent filings in process analytical technology. Bottom-up service line sizing and top-down regulatory spend estimates were triangulated against disclosed contract values at major TIC providers.
Assumptions held helium supply concentration in Qatar and Algeria at current levels, with regulatory enforcement intensity in FDA and EMA jurisdictions maintaining trajectory across the analysis window. Segmentation modeling incorporated service type, technology platform, application function, and end-user procurement pattern dimensions. CAGRs were derived from regression against historical accreditation expansion rates and disclosed capital expenditure patterns in gene therapy manufacturing capacity. Forecast inputs included viral vector commercialization timelines and composite airframe program ramp schedules at Boeing and Airbus.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by CDSCO-aligned laboratories or disruptive leasing platform entrants would shift outcomes beyond modeled ranges. Cross-checking against disclosed multi-year service agreements at Basel and New Jersey headquartered pharmaceutical manufacturers is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Americas Sterility Testing Market
Testing Services
Service Laboratory Market
Testing Services
US Viral Clearance Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
India GMP Testing Service Market
Testing Services
Global Endocrine Testing Market
Testing Services
Candida Vaginitis Rapid Testing Market
Testing Services
Active B12 Test Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market