
 Urgent Care Market | 2026-2036
Urgent Care Market Size, Share, and Industry Trends Forecast 2026-2036
Urgent Care Market Outlook
The urgent care sector is repositioning around a widening split between premium full-service centers with advanced diagnostics and commodity walk-in clinics handling basic acute complaints. American Family Care leverages its multi-state footprint to sustain volume-driven operations across suburban markets. GoHealth Urgent Care anchors its network through hospital system partnerships that extend clinical credibility and referral pathways. Carbon Health differentiates via proprietary technology integration that controls scheduling, billing, and telehealth access through unified platforms.
Urgent care denotes ambulatory medical facilities delivering immediate, non-emergency treatment for acute illnesses and minor injuries without scheduled appointments, typically operating extended hours with on-site diagnostic capabilities including X-ray, rapid laboratory testing, and EKG monitoring. Walk-in clinics and dedicated urgent care centers dominate service delivery, with telehealth platforms representing the fastest-expanding channel as synchronous video consultation replaces traditional intake for low-acuity presentations. Electronic health records and remote monitoring tools concentrate margin pools where interoperability reduces redundant testing and captures longitudinal patient data across fragmented encounters.
The US Food and Drug Administration governs diagnostic equipment and point-of-care testing devices deployed in urgent care settings, while the Centers for Medicare and Medicaid Services reimbursement frameworks shape site-of-service economics and steer patient volume between emergency departments and lower-cost alternatives. State-level certificate-of-need regulations and scope-of-practice laws for nurse practitioners and physician assistants determine market access and operating model flexibility across jurisdictions. Stakeholders must monitor evolving site-neutral payment policies and workforce licensure compacts that will determine competitive positioning and network economics.
Market Dynamics
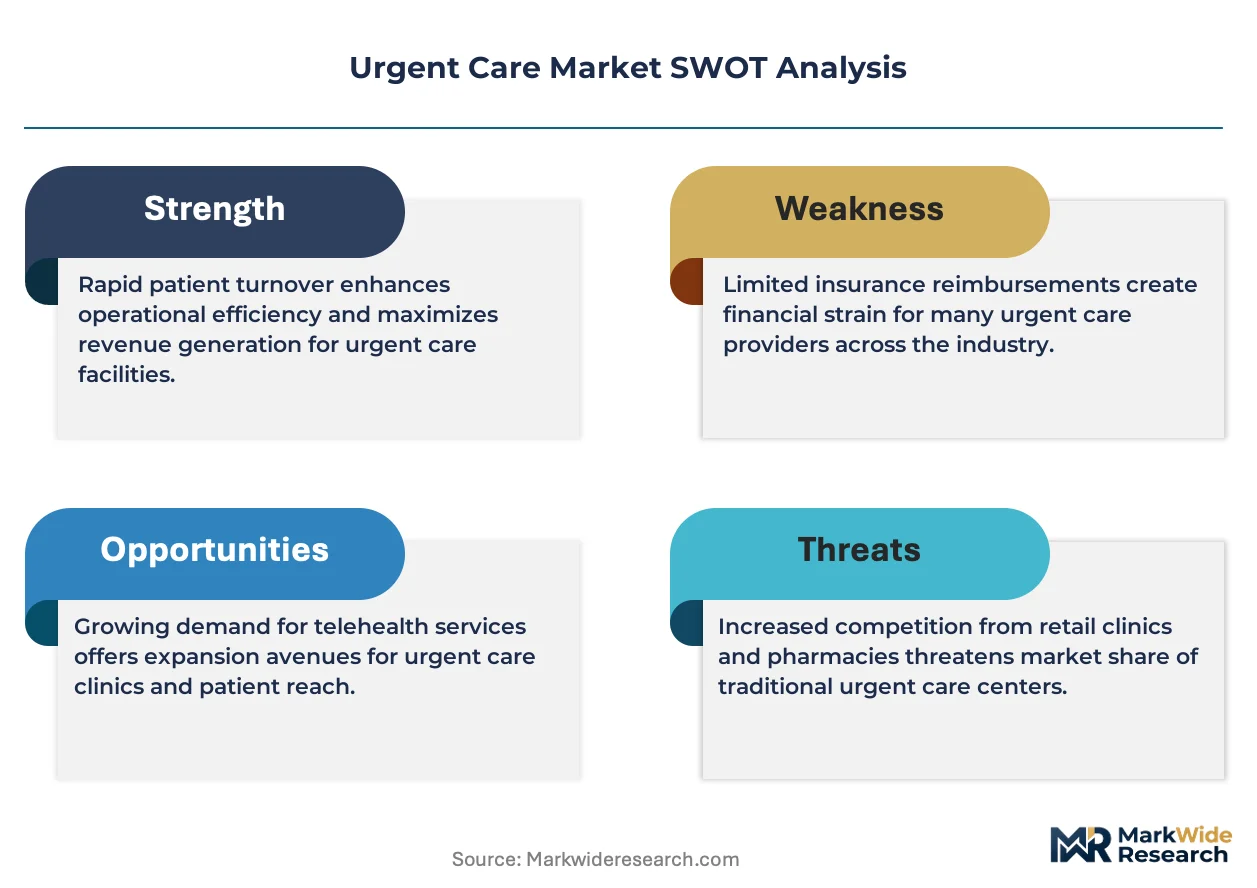
Site-neutral payment policies from CMS are compressing reimbursement differentials between hospital-based and freestanding urgent care sites, forcing operators to optimize throughput and labor substitution models to preserve margin.
Growth Catalysts
- OSHA workplace health mandates:Employer investment in on-site occupational health clinics accelerates as federal standards require documented preventive care infrastructure for high-risk industries.
- Nurse practitioner scope expansion:State-level licensure compacts in Florida and Texas enable autonomous practice, reducing physician labor costs and extending clinic operating hours.
- Telehealth platform integration:Synchronous video triage channels capture low-acuity volume before physical presentation, improving capacity utilization across suburban networks.
Market Restraints
- Certificate-of-need regulations:State-level CON laws in 35 states restrict new clinic entry, protecting incumbent positions but limiting competitive density in underserved counties.
- Diagnostic equipment capex cycles:Point-of-care testing devices and digital X-ray systems require 5-7 year replacement horizons, straining balance sheets of mid-scale operators.
- Emergency department substitution limits:CMS reimbursement frameworks maintain ED preference for higher-acuity presentations, capping urgent care addressable volume.
Strategic Opportunities
- Underserved rural corridors:Texas and Florida panhandle regions lack urgent care density within 30-minute drive times, creating first-mover positioning for retail clinic formats.
- Medicare Advantage penetration:Value-based contracts with MA plans reward preventive care capture, aligning urgent care incentives with longitudinal patient management.
- Interoperability mandates:ONC 21st Century Cures Act requirements for data exchange create competitive advantage for operators with unified EHR-telehealth-billing platforms.
Industry Challenges
- Physician assistant recruitment bottlenecks:Competitive labor markets in southeastern metropolitan areas extend time-to-fill for clinical staff beyond 90 days.
- Legacy EHR integration friction:Hospital system partnerships require bidirectional data flows with proprietary systems, delaying network expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urgent Care Market |
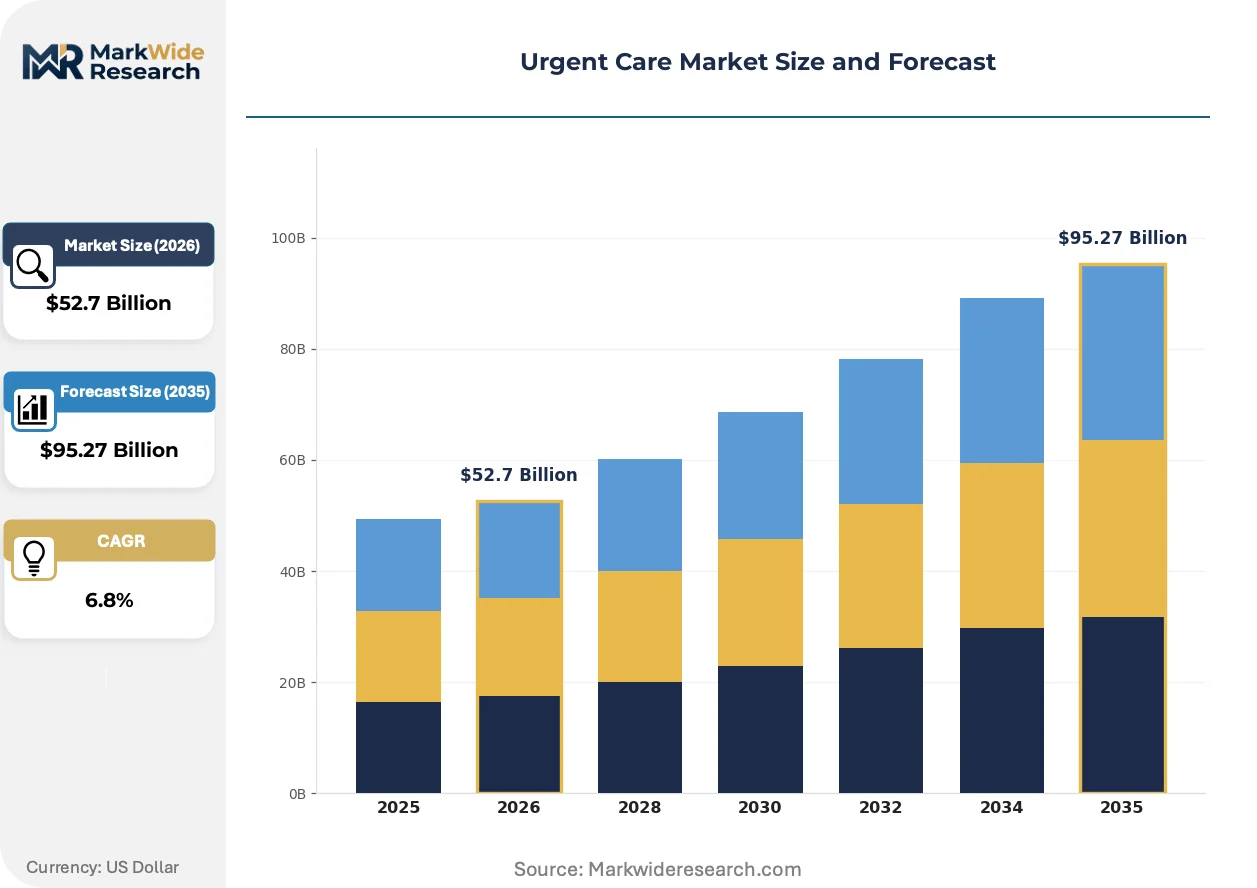
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Walk-in Clinics, Retail Clinics, Urgent Care Centers, Telehealth Services End User: Patients, Employers, Insurers, Healthcare Providers Technology: Electronic Health Records, Telemedicine Platforms, Diagnostic Equipment, Remote Monitoring Tools Application: Acute Illness Treatment, Minor Injuries, Preventive Care, Immunizations |
| Companies Covered | Carbon Health, American Family Care, GoHealth Urgent Care, Novant Health, CityMD Urgent Care, HCA Healthcare Urgent Care, Concentra, WellStreet Urgent Care, FastMed Urgent Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urgent Care Market Strategic Shifts
Artificial intelligence triage protocols and remote patient monitoring tools are restructuring how urgent care operators allocate clinical labor and capture recurring revenue from episodic encounters.
Clinical decision support algorithms embedded in intake workflows is automating acuity scoring and differential diagnosis suggestions. Multi-site operators in Texas and Florida deploy these tools to standardize care protocols across 50-plus locations. The technology is automating physician documentation burden, compressing encounter times from 45 minutes to 28 minutes average.
CMS site-neutral payment proposals for off-campus hospital outpatient departments reshape capital deployment decisions. Freestanding urgent care sites gain cost advantage as reimbursement parity eliminates hospital facility fees. Southeastern states with high Medicare Advantage penetration see accelerated de novo development away from hospital campuses.
Patients increasingly self-triage through mobile scheduling platforms before selecting between telehealth, urgent care, or emergency department venues. Younger demographics in Florida metropolitan corridors bypass traditional primary care referrals entirely. This behavioral shift concentrates volume with operators offering real-time wait transparency and same-day appointment guarantees.
Urgent Care Market Segmentation
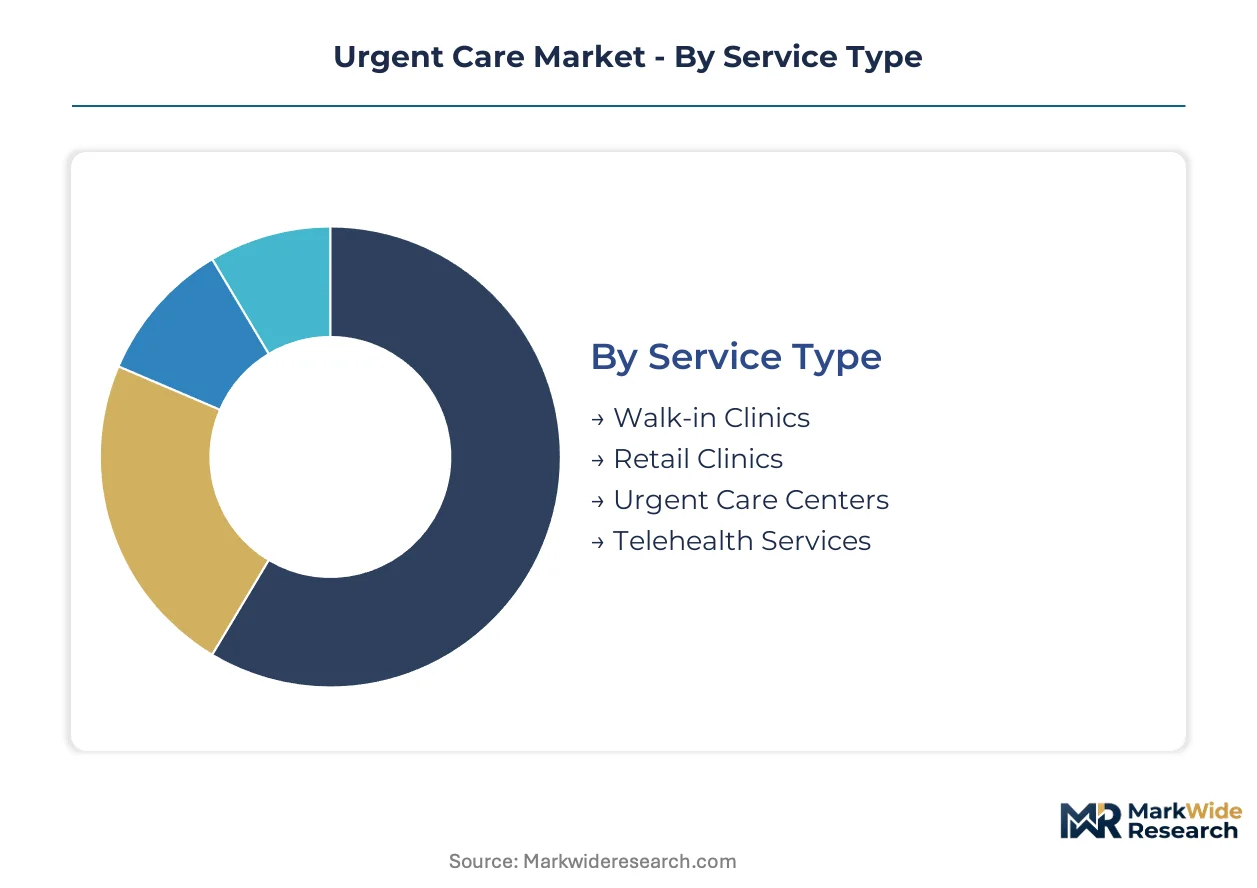
Service configuration determines capital deployment and margin structure across the urgent care sector. Operators must match facility investment to patient acuity profiles and reimbursement pathways.
Service Type:
Capital intensity varies sharply across delivery formats, with full-service urgent care centers requiring diagnostic suites and extended-hour staffing while telehealth platforms demand software infrastructure over physical plant.
- Walk-in Clinics:Basic acute care facilities with minimal diagnostic capability, typically co-located in retail corridors. Demand concentrates among uninsured and underinsured populations in Florida's suburban counties where appointment access to primary care remains constrained.
- Retail Clinics:Pharmacy-anchored sites offering limited acute and preventive services. Texas markets see heavy concentration as CVS MinuteClinic and Walgreens Healthcare scale formats optimized for 15-minute encounters.
- Urgent Care Centers:Full-service facilities with on-site X-ray, laboratory, and procedure capabilities. These sites require the heaviest upfront investment in equipment and physician staffing.
- Telehealth Services:Synchronous video consultation platforms for low-acuity triage and follow-up.
Most installed capacity flows through urgent care centers. Expansion is steepest in telehealth services.
End User:
Payer mix shapes site selection and service bundling, with employer-sponsored programs driving occupational health investment and Medicare Advantage steering preventive care capture.
- Patients:Individual consumers seeking immediate access without scheduled appointments. Southeastern metropolitan corridors show concentration where high-deductible health plans push price-sensitive volume toward transparent retail formats.
- Employers:Corporate purchasers of on-site or near-site occupational health services. OSHA compliance mandates in construction and manufacturing sectors accelerate clinic deployment at Texas industrial facilities.
- Insurers:Payers directing members toward lower-cost sites of service through narrow networks and prior authorization protocols.
- Healthcare Providers:Hospital systems and physician groups using urgent care as referral intake and emergency department diversion.
Patient volume dominates throughput. Employer-sponsored programs are gaining share fastest.
Technology:
Technology stack differentiation separates scaled operators from commodity competitors, with unified platforms capturing margin through reduced administrative burden and improved capacity utilization.
- Electronic Health Records:Patient data systems enabling care coordination across fragmented encounters. Interoperability mandates from ONC 21st Century Cures Act requirements concentrate procurement with vendors supporting bidirectional hospital system integration.
- Telemedicine Platforms:Video consultation infrastructure with scheduling and billing integration. Florida operators deploy these tools to extend rural reach without physical facility investment.
- Diagnostic Equipment:Point-of-care testing devices and digital imaging systems requiring 5-7 year replacement cycles.
- Remote Monitoring Tools:Wearable-connected platforms for post-acute surveillance and chronic condition tracking.
Diagnostic equipment absorbs the largest capital share. Remote monitoring tools are climbing the fastest.
Application:
Service mix determines staffing ratios and reimbursement rates, with preventive and immunization services offering higher margins under value-based contracts but requiring different clinical workflows than acute treatment.
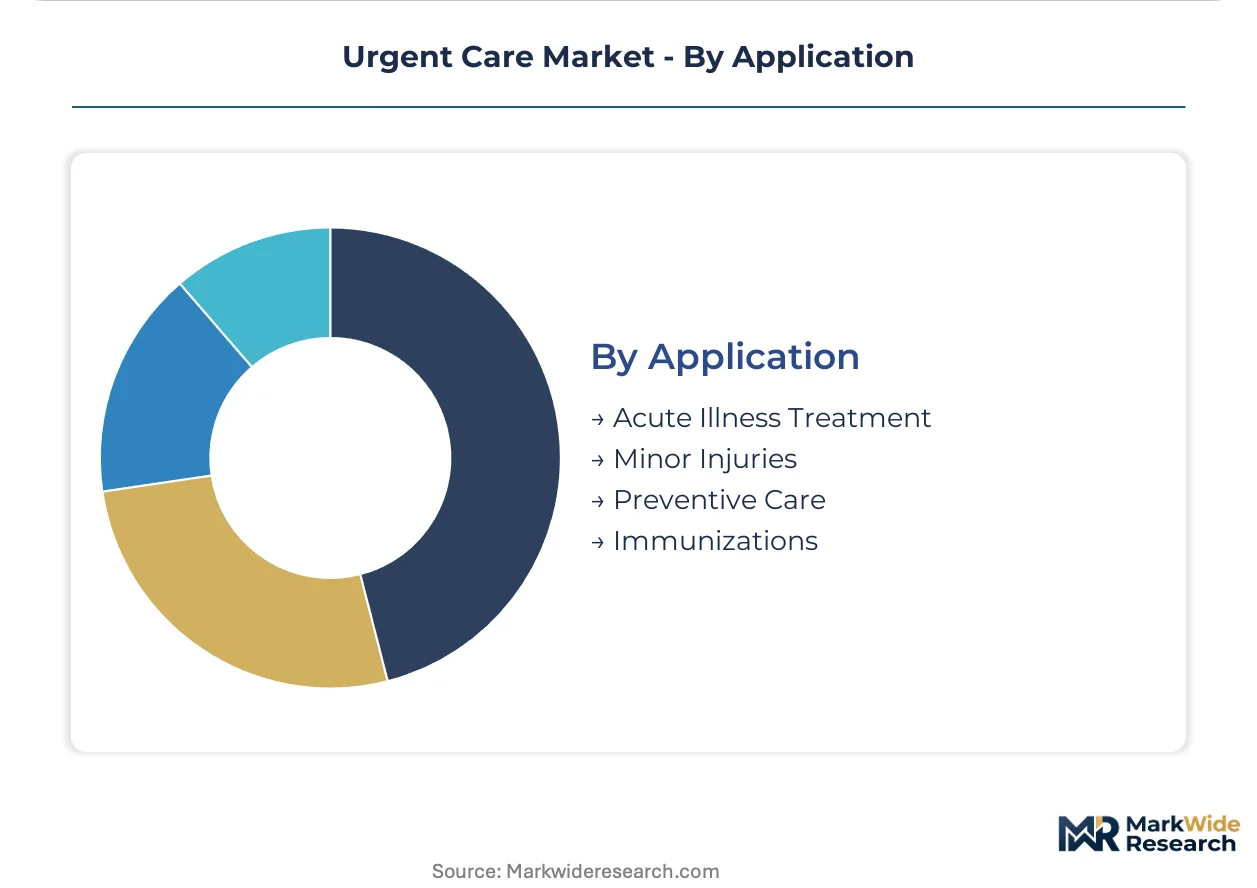
- Acute Illness Treatment:Immediate care for infections, respiratory conditions, and gastrointestinal complaints. Volume concentrates in winter months across southeastern states where seasonal migration patterns concentrate susceptible populations.
- Minor Injuries:Fracture stabilization, laceration repair, and sprain management. Texas construction and oilfield employers drive occupational injury volume to employer-contracted sites.
- Preventive Care:Screenings and wellness visits capturing longitudinal patient relationships.
- Immunizations:Vaccine administration for travel, occupational requirements, and seasonal protection.
Acute illness treatment handles the highest encounter volume. Preventive care is expanding most quickly under Medicare Advantage penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled nurse practitioners and physician assistants cluster in southeastern states where autonomous practice laws enable lean staffing models. Texas and Florida lead clinic network expansion as certificate-of-need restrictions ease in select counties. Metropolitan corridors in both states concentrate employer-sponsored occupational health investment.
United States
OSHA workplace health mandates drive employer investment in on-site clinics across high-risk industries. The Centers for Medicare and Medicaid Services steers patient volume through site-neutral payment proposals that compress reimbursement differentials. Texas industrial corridors see accelerated deployment of employer-contracted urgent care facilities at construction and oilfield sites.
Germany
Regional physician networks integrate ambulatory care centers to reduce emergency department crowding in dense urban markets. The country's national pharmaceutical regulator governs point-of-care diagnostic equipment deployment. Bavarian metropolitan clusters anchor multi-site operator expansion as value-based contracts reward preventive care capture.
United Kingdom
NHS England directs patients toward urgent treatment centers through 111 triage protocols and same-day access guarantees. The Medicines and Healthcare products Regulatory Agency oversees device certification for rapid diagnostic platforms. London and Southeast England concentrate private urgent care investment as wait-time transparency tools reshape patient routing behavior.
Australia
Medicare Benefits Schedule reforms expand bulk-billing eligibility for after-hours primary care services in suburban corridors. The Therapeutic Goods Administration regulates point-of-care testing devices deployed in retail clinic formats. New South Wales and Victoria lead network development as state health departments pilot urgent care alternatives to emergency department presentation.
Canada
Provincial health authorities contract private operators to address emergency department diversion targets in underserved rural zones. Health Canada governs medical device licensing for diagnostic imaging equipment. Ontario and Quebec anchor multi-province operator strategies as interprovincial licensure compacts ease workforce mobility for nurse practitioners.
Urgent Care Market Competitive Environment
Capital-heavy operators with diagnostic suites and extended-hour staffing compete with asset-light telehealth platforms that capture low-acuity volume through software infrastructure. The market structures around three tiers: hospital-affiliated networks leveraging referral pathways, multi-state retail formats optimizing suburban density, and technology-integrated challengers unifying scheduling with virtual care. Dominant competitive moves include strategic partnerships with health systems for clinical credibility and geographic expansion into certificate-of-need jurisdictions where incumbent protection limits new entry.
Within the hospital-affiliated tier, HCA Healthcare Urgent Care and Novant Health exemplify operators leveraging system integration for patient flow management. Among independent multi-state formats, American Family Care and GoHealth Urgent Care occupy positions emphasizing suburban accessibility and volume-driven throughput. Carbon Health represents the technology-integrated archetype, anchoring competitive positioning through proprietary platform control over scheduling, billing, and telehealth access.
| Leading Market Players |
|---|
| Carbon Health |
| American Family Care |
| GoHealth Urgent Care |
| Novant Health |
| CityMD Urgent Care |
| HCA Healthcare Urgent Care |
| Concentra |
| WellStreet Urgent Care |
| FastMed Urgent Care |
| Others |
Value Chain & Pricing Dynamics
Skilled nurse practitioner concentrations in Texas and Florida create labor-cost differentials that widen pricing-tier spreads between physician-staffed premium centers and mid-level practitioner clinics. These geographic staffing disparities enable leaner operators to undercut full-service competitors while maintaining margin.
Pricing Analysis
Bundled episode-based contracts compete against unbundled fee-for-service billing across urgent care networks. Three-tier pricing structure across premium diagnostic-equipped centers, standard extended-hours clinics, and economy retail formats separates service levels by equipment depth and staffing credentials. Pricing pressure stems from CMS site-neutral payment compression that eliminates hospital facility fee advantages. Uninsured and high-deductible plan holders exhibit highest price sensitivity, routing toward transparent retail formats with published visit costs.
Supply Chain Analysis
Logistics and freight costs for refrigerated vaccines and point-of-care testing consumables concentrate margin pressure on rural site economics. Diagnostic equipment manufacturing centers on Germany, Japan, and the United States for digital X-ray and laboratory analyzer systems. Supply chains draw from semiconductor fabrication in Taiwan for imaging sensor components and Mexican assembly for disposable medical supplies. Single-source vulnerability runs through sole-approved vendors for CLIA-waived testing platforms. Distribution runs through regional medical equipment distributors with hospital system purchasing consortiums capturing volume discounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The urgent care market represents a late-cycle quality story as patient routing behavior shifts toward premium centers with guaranteed access and real-time transparency tools. This demand migration favors operators with unified technology platforms over commodity walk-in formats.
For Market Incumbents: Anticipate telehealth platform entrants capturing low-acuity volume through synchronous video triage. Defensive moves require deepening hospital system partnership density to secure referral pathways and accelerating proprietary EHR-telehealth integration to meet ONC interoperability mandates. Vertical integration into remote patient monitoring tools creates recurring revenue attachment to episodic encounters.
For New Entrants and Emerging Players: Direct-to-employer digital health platforms offer the lowest competitive friction for new entrant positioning. White-space targets include underserved rural corridors in the Texas and Florida panhandles lacking 30-minute drive-time coverage, plus Medicare Advantage value-based contracts rewarding preventive care capture. Go-to-market execution should anchor through occupational health compliance sales to construction and manufacturing employers facing OSHA mandate pressure.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional operators with legacy EHR systems requiring capital-intensive interoperability upgrades. Long-term viability across the next decade hinges on technology platform control rather than physical site density. Acquisition targets with unified scheduling-billing-telehealth architecture command scarcity premiums. The signal to watch is CMS finalization of site-neutral payment parity rules that would accelerate freestanding site development away from hospital campuses.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures referral pathways and clinical credibility through formal affiliation with HCA Healthcare or Novant Health networks. |
| Proprietary Platform Development | Unifies EHR, scheduling, and telehealth access to capture margin through reduced administrative burden. |
| Nurse Practitioner Autonomous Practice | Leverages Florida and Texas licensure compacts to reduce physician labor costs and extend operating hours. |
| Medicare Advantage Contracting | Aligns urgent care incentives with longitudinal patient management under value-based reimbursement frameworks. |
| Rural Corridor Expansion | Captures first-mover positioning in Texas and Florida panhandle regions with acute care access gaps. |
Study Parameters
Multiple input streams — urgent care operator executives, hospital system strategy officers, nurse practitioner licensure boards, and CMS policy specialists — were reconciled against secondary validation from FDA device filings, state certificate-of-need databases, and Medicare cost report data. Primary fieldwork with clinic network administrators and occupational health purchasers informed operating model economics. Bottom-up encounter volume modeling and top-down reimbursement flow analysis were triangulated to anchor market sizing.
Cross-referencing historical encounter growth patterns against panel-based input from payer network directors and GPO contracting managers shaped the analytical framework. Segmentation dimensions modeled include service configuration, payer mix, and technology stack sophistication across the projection horizon. CAGRs were derived from regression analysis of site development velocity and reimbursement rate trajectories. Forecast inputs incorporated OSHA compliance mandate timelines and state-level scope-of-practice legislative calendars.
The model assumes a particular technology adoption path for AI-enabled triage protocols; alternative pathways for clinical decision support automation would alter the outlook if FDA clearance timelines extend or provider liability frameworks shift. Forecasts reflect documented assumptions regarding site-neutral payment implementation and nurse practitioner autonomous practice expansion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
First Aid Market