
 Europe Ventilator Market | 2026-2036
Europe Ventilator Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ventilator Market Intelligence
Remote monitoring subscriptions for post-operative patient management is consolidating the value proposition beyond the initial hardware sale in the European market. Drägerwerk AG & Co. KGaA leverages its extensive hospital network to bundle service contracts with its ICU ventilator sales. Philips differentiates through its integrated patient monitoring platforms that connect ventilators to broader hospital IT systems. Hamilton Medical specializes in intelligent ventilation technologies, offering advanced features for critical care environments across Europe.
A ventilator is a medical machine designed to provide mechanical ventilation by moving breathable air into and out of the lungs for patients with respiratory insufficiency. These systems operate on technologies like pressure-controlled or volume-controlled modes to deliver a specific tidal volume to a patient. ICU ventilators continue to constitute a large segment due to their necessity in critical care. The market for portable ventilators for use in homecare settings represents the fastest-growing segment, driven by decentralization of patient care.
The European market operates under the stringent EU Medical Device Regulation (MDR), which mandates rigorous clinical evidence and post-market surveillance. Compliance with CE marking is a non-negotiable prerequisite for market access, shaping product development and quality management for all manufacturers. Vendor success will depend on navigating these evolving regulatory pathways while innovating in device connectivity and patient data analytics for improved outcomes.
Market Dynamics
The central force shaping the European ventilator market is the stringent EU Medical Device Regulation. This framework elevates requirements for clinical evidence and post-market surveillance, directly influencing device design, quality management, and market access strategies for all manufacturers.
Growth Catalysts
- Chronic Disease Prevalence:The rising incidence of chronic respiratory conditions like COPD across Europe's aging population sustains demand for long-term ventilation, especially in homecare settings.
- Intelligent Ventilation:Advanced ventilation modes that automate weaning protocols and adapt to patient breathing patterns are being adopted in ICUs to improve outcomes and reduce clinician workload.
- German Hospital System:Germany's well-funded hospital infrastructure and its strong focus on intensive care medicine create a concentrated, high-volume demand center for advanced critical care ventilators.
Market Restraints
- MDR Compliance Costs:The high cost and complexity of generating the clinical evidence required for CE marking under the EU MDR create significant barriers for smaller manufacturers.
- System Integration:Interoperability challenges between new ventilators and diverse, often proprietary, electronic health record systems in European hospitals limit seamless data flow.
- Component Scarcity:The reliance on a concentrated global supply chain for critical electronic components, such as microprocessors and sensors, creates vulnerability to price volatility and shortages.
Strategic Opportunities
- Homecare Expansion:Underpenetrated homecare markets in Southern and Eastern Europe offer significant growth potential as healthcare systems seek to decentralize patient management for chronic conditions.
- AI and Predictive Analytics:Integrating artificial intelligence into ventilators to predict adverse events, such as extubation failure, presents a major opportunity for product differentiation and improved clinical outcomes.
- Service-Based Models:Shifting from pure hardware sales to subscription-based models that include remote monitoring, consumables, and software updates can create recurring revenue streams.
Industry Challenges
- Lengthy Certification Timelines:Navigating the extensive review process with Notified Bodies for CE marking under the MDR significantly extends the time-to-market for new ventilator innovations in Europe.
- Specialized Talent Gaps:A shortage of biomedical engineers and software developers with specific expertise in respiratory care and medical device connectivity hampers product development efforts.
- Legacy System Compatibility:Ensuring new connected ventilators can integrate with older patient monitoring platforms and hospital IT infrastructure remains a persistent operational challenge for vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ventilator Market |
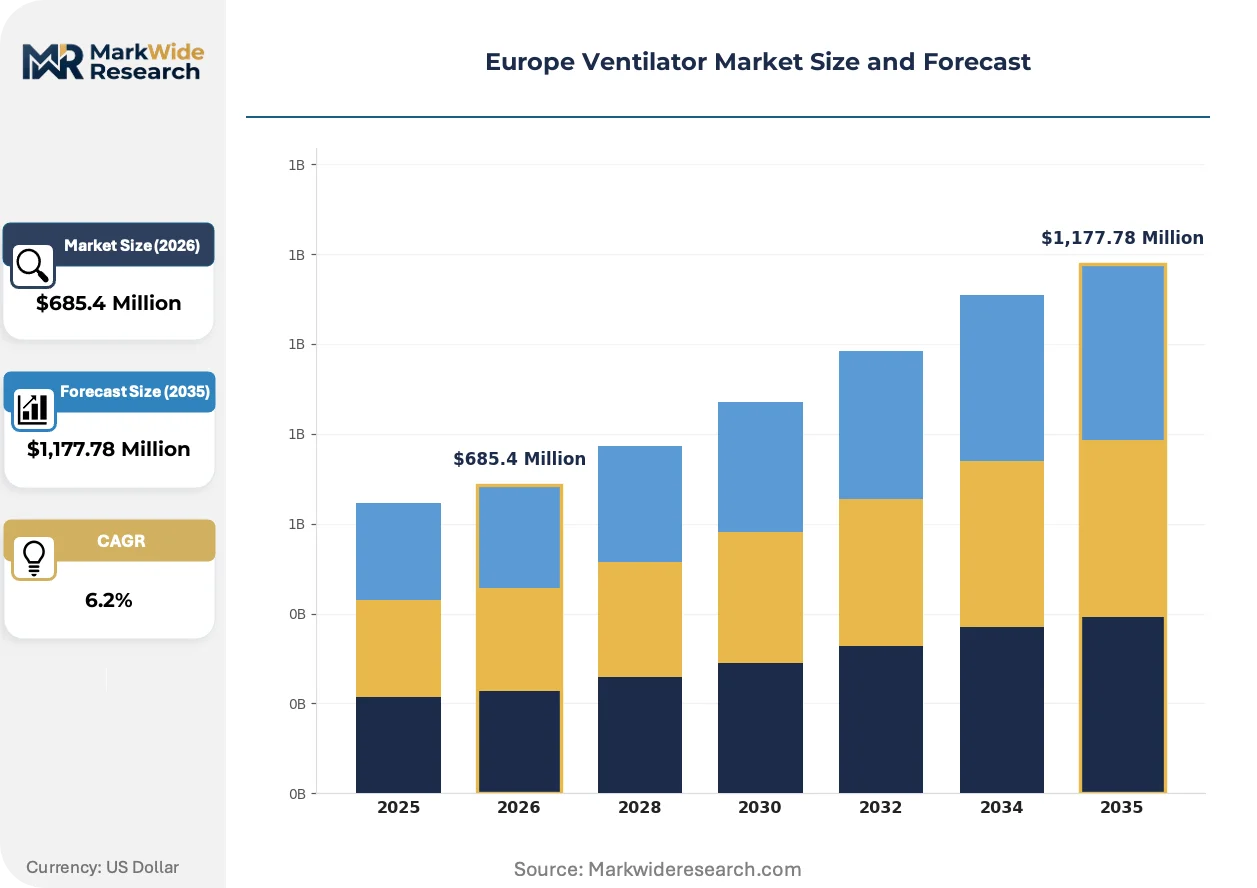
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Ventilators, Non-Invasive Ventilators, Portable Ventilators, ICU Ventilators, Neonatal Ventilators Technology: Pressure-Controlled, Volume-Controlled, Dual-Controlled, Intelligent Ventilation, High-Frequency Ventilation Application: Respiratory Failure, Chronic Obstructive Pulmonary Disease, Pneumonia Management, Post-Surgical Care, Emergency Treatment End User: Hospitals, Ambulatory Surgery Centers, Homecare Settings, Intensive Care Units, Specialty Clinics |
| Companies Covered | Drägerwerk AG & Co. KGaA, Getinge AB, Philips, Medtronic, Hamilton Medical, ResMed, Smiths Group, Fisher & Paykel Healthcare, Air Liquide, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ventilator Market Strategic Shifts & Innovations
Data integration and device connectivity are fundamentally altering the operational fabric of respiratory care in Europe. The market is shifting from standalone hardware to networked systems that support clinical decision-making and enable new care models outside traditional hospital walls.
Adaptive ventilation algorithms represent a significant product evolution, automatically adjusting pressure and volume based on real-time patient lung mechanics. Intensive care units across Europe, particularly in university hospitals, are adopting these systems. This automated, patient-specific support is rewriting the standard of care from intermittent manual adjustments to continuous, optimized therapy.
The European Union's Medical Device Regulation (MDR) is a defining policy shift for the industry. It mandates more rigorous clinical data and continuous post-market surveillance for all devices to maintain market access. Ventilator manufacturers, especially those with higher-risk devices, must now invest heavily in updated technical documentation and clinical studies for CE marking.
Hospital procurement is moving beyond single-unit capital purchases toward comprehensive service and subscription contracts. This model disrupts traditional sales channels by bundling hardware with ongoing software updates, maintenance, and remote monitoring services. The shift is most prominent within large hospital consortia in Germany and the UK seeking to control long-term operational costs.
Europe Ventilator Market Segmentation
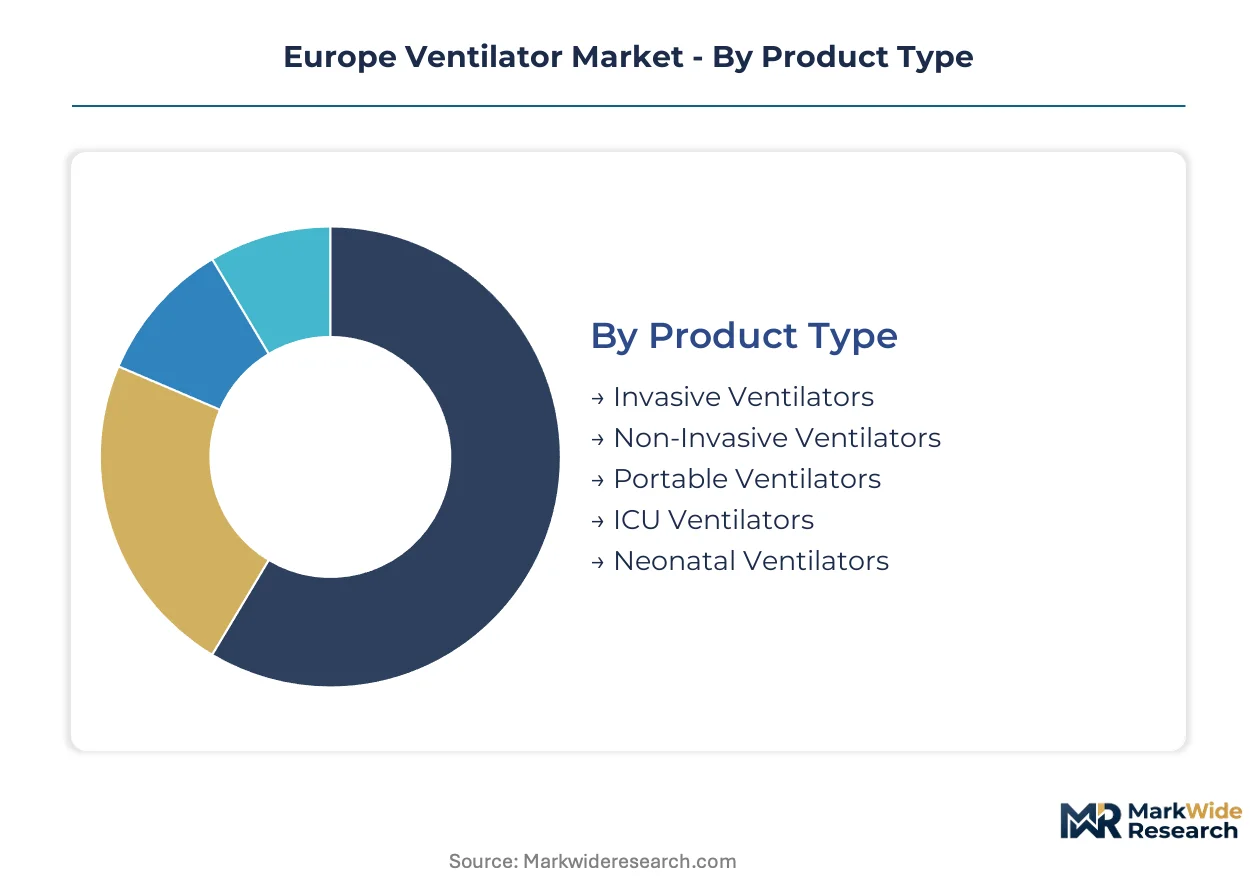
The Europe ventilator market's intricate structure necessitates detailed segmentation to understand demand patterns and technological adoption across diverse clinical environments. Analyzing these distinct categories reveals how specific product types and technological advancements address varied patient needs. This granular view helps manufacturers align product development and market strategies with evolving healthcare priorities within the European Union.
Product Type:
Ventilator product types are differentiated by their operational delivery mechanisms and intended use, influencing design specifications.
- ICU Ventilators:These advanced systems provide comprehensive respiratory support for critically ill patients within hospital intensive care units. Demand concentrates in Germany's well-funded hospital system, driven by its focus on intensive care medicine.
- Portable Ventilators:Designed for mobility, these compact devices facilitate patient care outside traditional hospital settings, including homecare. Their expansion is fueled by healthcare decentralization and rising chronic respiratory conditions across Europe.
- Invasive Ventilators:These devices deliver breath directly into the lungs via an endotracheal tube, essential for severe respiratory failure.
- Non-Invasive Ventilators:Providing ventilatory support through a mask, these systems are preferred for less severe respiratory distress.
- Neonatal Ventilators:Specialized for infants, these offer precise control over small tidal volumes to protect delicate lung tissue.
ICU Ventilators lead on scale due to their critical hospital role; Portable Ventilators lead on momentum, driven by homecare shifts.
Technology:
Ventilator technologies are categorized by their operational principles and how they manage gas delivery to optimize patient respiratory mechanics.
- Intelligent Ventilation:These sophisticated systems incorporate adaptive algorithms to automatically adjust ventilation parameters, responding to real-time patient lung mechanics. Adoption is significant in university hospitals, improving outcomes and reducing clinician workload.
- Pressure-Controlled:This mode delivers a set inspiratory pressure, allowing tidal volume to vary, commonly used to protect fragile lungs. Demand remains consistent in critical care units for precise pressure support.
- Volume-Controlled:Delivering a predetermined tidal volume with variable pressure, this mode ensures consistent minute ventilation for patients.
- Dual-Controlled:These hybrid modes combine features of both pressure and volume control, offering adaptive ventilation strategies.
- High-Frequency Ventilation:Utilizing very small tidal volumes at rapid rates, this specialized technique is employed for severe acute respiratory distress.
Intelligent ventilation technologies are increasingly adopted across Europe for optimized patient outcomes.
Application:
Ventilator applications are defined by specific medical conditions and patient cohorts requiring mechanical respiratory support.
- Chronic Obstructive Pulmonary Disease:This widespread chronic respiratory condition necessitates long-term ventilation support, particularly in homecare settings across Europe. The rising incidence sustains demand for non-invasive and portable devices.
- Respiratory Failure:A critical indication for mechanical ventilation, this application involves patients unable to maintain adequate gas exchange. Demand for ICU ventilators concentrates in acute care hospitals where advanced life support is essential.
- Pneumonia Management:Ventilators assist patients with severe pneumonia by supporting lung function and ensuring adequate oxygenation.
- Post-Surgical Care:Mechanical ventilation is routinely used to support patient breathing immediately following major surgeries affecting respiratory function.
- Emergency Treatment:Ventilators are vital in emergency medicine for patients experiencing acute respiratory distress from trauma or sepsis.
The prevalence of chronic respiratory conditions drives consistent demand for ventilation support.
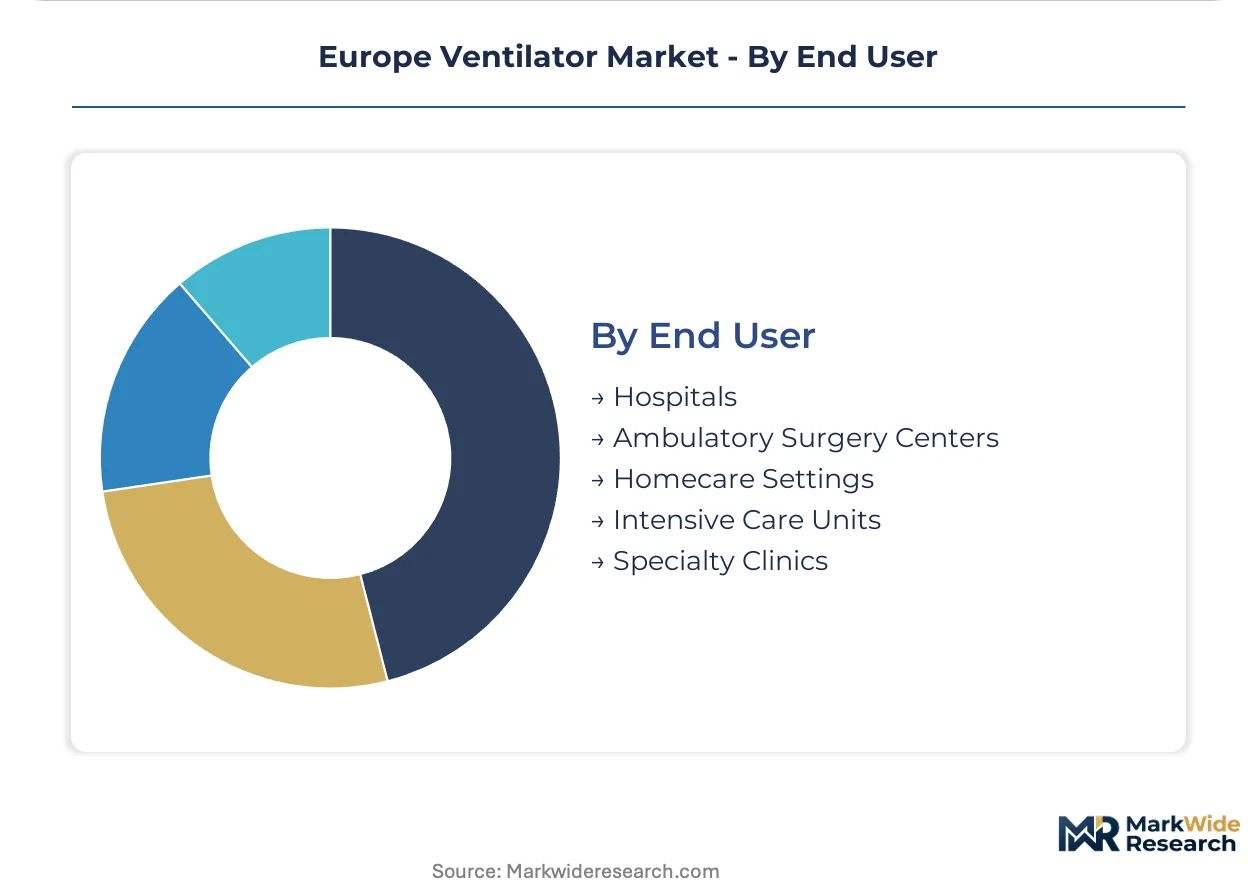
End User:
End-user segments delineate where ventilators are deployed, reflecting varying operational scales and patient acuity levels.
- Homecare Settings:This segment involves ventilator use in a patient's residence, enabling long-term management of chronic respiratory conditions. Its expansion is driven by healthcare decentralization and efforts to reduce hospital readmissions.
- Hospitals:General hospitals represent a foundational end-user, deploying ventilators across various departments, including emergency rooms. Procurement in large consortia shifts towards comprehensive service and subscription contracts.
- Intensive Care Units:ICUs are specialized hospital departments focused on critically ill patients, necessitating advanced, high-performance ventilator systems.
- Ambulatory Surgery Centers:These facilities use ventilators for short-term respiratory support during and after minor surgical procedures.
- Specialty Clinics:Respiratory clinics and sleep disorder centers utilize ventilators for diagnostic purposes and managing chronic conditions.
Homecare settings represents the fastest-growing segment for ventilator deployment in Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced hospital system contrasts with Southern and Eastern European regions, where homecare expansion drives ventilator demand. The European ventilator market exhibits varied adoption patterns shaped by national healthcare priorities and regulatory landscapes. Localized infrastructure and funding mechanisms significantly influence device procurement and deployment strategies across the continent.
Germany
Germany's well-funded hospital system and strong focus on intensive care medicine sustain a high demand for advanced critical care ventilators. The country's strict adherence to EU MDR ensures device quality and safety standards for all market participants. Major medical technology clusters in cities like Munich and Berlin foster innovation in respiratory support solutions.
United Kingdom
The United Kingdom's National Health Service (NHS) modernization efforts prioritize efficient patient management and chronic respiratory care. Adherence to EU MDR, even post-Brexit, remains crucial for medical device market access. Innovation hubs in Oxford and Cambridge contribute to developing new respiratory technologies, supporting patient outcomes.
France
France experiences rising demand for homecare ventilators, driven by an aging population and efforts to decentralize chronic disease management. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) enforces rigorous medical device regulations. The Paris region serves as a significant center for medical device companies, including ventilator manufacturers.
Italy
Italy's healthcare system focuses on expanding homecare settings to manage chronic respiratory conditions more effectively. Compliance with the EU MDR is a fundamental requirement for all ventilator products sold within the country. The Lombardy region, with its robust medical device manufacturing base, supports local and regional supply chains.
Spain
Spain's public healthcare system increasingly invests in ventilators for both acute care and long-term management of chronic respiratory diseases. The country aligns with EU MDR requirements for medical device certification and post-market surveillance. Major urban centers like Barcelona and Madrid are key hubs for medical technology distribution and adoption.
Europe Ventilator Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with established players dominating critical care. The market structure is tiered, featuring large, diversified healthcare technology companies alongside specialized critical care providers and homecare-focused innovators. Strategic partnerships for system integration and portfolio diversification into software and services represent dominant competitive moves.
Among the established European players, Drägerwerk AG & Co. KGaA, a German AG & Co. KGaA, represents a long-standing provider of critical care solutions. Philips, a Dutch multinational, exemplifies a diversified healthcare technology company with integrated patient monitoring platforms. Hamilton Medical, a Swiss company, occupies a strong position in intelligent ventilation technologies for critical care environments.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Getinge AB |
| Philips |
| Medtronic |
| Hamilton Medical |
| ResMed |
| Smiths Group |
| Fisher & Paykel Healthcare |
| Air Liquide |
| Others |
Cost & Logistics Intelligence
Microprocessor unit pricing, influenced by global semiconductor indices, cascades through the European ventilator market. This affects the final device cost and the value proposition for advanced critical care systems versus more basic homecare models.
Pricing Analysis
Capacity additions in Asian manufacturing hubs are reshaping price floors for core electronic components. The market operates on a hybrid pricing model, combining transactional hardware sales with subscription-based service contracts for remote monitoring and software. Price differentiation stems from device connectivity, advanced intelligent ventilation features, and stringent EU MDR compliance. Cost compression in homecare segments intensifies due to public health system procurement aiming for efficiency. Hospitals prioritize advanced functionality, making homecare settings the most price-sensitive buyer segment.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of microprocessors and sensors. The supply chain for critical electronic components concentrates in East Asia, particularly Taiwan, South Korea, and China. Ventilator production heavily depends on these microprocessors, sensors, and medical-grade plastics. Commodity price volatility for these electronic components represents a significant structural risk. Distribution runs primarily through direct sales to large hospital groups and specialized medical device distributors for homecare settings.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe ventilator market operates as a stable compounder, driven by the persistent demand from an aging population and chronic respiratory conditions. This ensures consistent, long-term growth for established players.
For Market Incumbents: Deepen existing hospital network relationships by bundling comprehensive service and subscription contracts. Integrate proprietary ventilator platforms with broader hospital IT systems to create sticky ecosystems, mitigating the threat from new entrants focusing solely on hardware. Invest strategically in R&D for AI-driven predictive analytics to maintain a technological edge and address the increasing complexity of patient care. This approach reinforces channel control against potential regulatory shifts like MDR.
For New Entrants and Emerging Players: Direct-to-consumer digital platforms for remote monitoring subscriptions represent a viable market entry point. Target underpenetrated homecare markets in Southern and Eastern Europe, focusing on chronic respiratory conditions where decentralization of care is a priority. Offer intelligent ventilation solutions with value-based pricing models tailored to long-term patient management. This strategy allows penetration into segments with lower incumbent saturation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized software and AI firms developing predictive analytics for respiratory care. This market offers long-term growth potential over the next five to ten years, driven by chronic disease prevalence and healthcare decentralization. Target niche homecare providers with established patient networks or technology companies enhancing device connectivity. The signal to watch is the increasing adoption rates of AI-powered weaning protocols in critical care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secure long-term procurement contracts and integration pathways within major European healthcare providers. |
| Software Companion Development | Enhance ventilator functionality with AI-driven predictive analytics for improved patient outcomes. |
| CE Marking Pathway Optimization | Streamline regulatory approval processes under EU MDR for new and updated medical devices. |
| Remote Monitoring Service Launch | Expand recurring revenue streams beyond initial hardware sales through digital health offerings. |
| Supply Chain Diversification | Mitigate reliance on single-source electronic component suppliers to ensure production stability. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. This involved detailed discussions with biomedical engineers, hospital purchasing committee members, respiratory therapists, and homecare providers. Secondary data sources included EU MDR guidance documents, national health statistics, medical device registries, and company annual reports. Bottom-up data aggregation and top-down market sizing provided comprehensive triangulation.
Segment-weighting approaches were applied to project market trajectories across the analysis window. The analytical framework modeled growth along product type, technology, application, end-user, and regional regulatory compliance dimensions. Compound Annual Growth Rates were derived through regression analysis on historical data and projected market drivers. Key forecast inputs included chronic disease prevalence rates and healthcare decentralization initiatives in Europe.
The model assumes a particular technology adoption path; alternative pathways for AI-driven ventilation would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and component supply chain resilience. Unforeseen changes to EU MDR or global component disruptions could revise projections. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Canada Insulin Delivery Devices Market
Medical Devices
Artificial Disc Market
Medical Devices
Medical Electrodes Market
Medical Devices
Europe Surgical Microscopes Market
Medical Devices
Cervical Artificial Discs Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Intraosseous Infusion Device Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Global Embolization Particle Market
Medical Devices
General Surgery Devices Market
Medical Devices
Global Cranial Implants Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Medical Device Technologies Market
Medical Devices
Global Endodontic Reparative Cement Market
Medical Devices
Neurotech Devices Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market