
 Global Emergency Medical Apps Market | 2026-2036
Global Emergency Medical Apps Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emergency Medical Apps Market Foresight
Mobile app distribution for emergency medical services is fragmenting across specialized healthcare marketplaces, carrier-integrated platforms, and direct enterprise procurement channels. Pulsara leverages hospital network partnerships to anchor its position in inter-facility care coordination. RapidSOS competes through embedded location intelligence that integrates directly with public safety answering points. Zipline sustains its differentiation by controlling drone-based emergency supply delivery as a proprietary fulfillment layer.
Emergency medical apps are software platforms engineered to facilitate real-time clinical communication, patient data transmission, and care coordination between pre-hospital providers and receiving facilities, typically operating with sub-60-second alert latency and HIPAA-compliant encryption protocols. Their primary commercial purpose is to compress time-to-treatment intervals for acute medical events. Deployment mode selection reveals structural divergence: cloud-based SaaS architectures dominate among EMS providers seeking minimal IT overhead, while hybrid deployments gain traction in corporate safety teams managing sensitive workforce health data across jurisdictional boundaries. Platform segmentation shows iOS and Android capturing individual consumer volumes, whereas proprietary OS installations concentrate in dedicated public safety hardware ecosystems where interoperability mandates override consumer convenience.
FDA Software as a Medical Device guidance shapes product validation requirements for apps delivering clinical decision support, while HIPAA compliance frameworks dictate data architecture investments across all US-facing deployments. EU MDR and GDPR jointly constrain European market entry, requiring CE-marked clinical evidence packages alongside privacy-by-design data governance. Stakeholders must monitor evolving FDA enforcement discretion boundaries between wellness and diagnostic functionalities, as reclassification would trigger premarket submission obligations and reshape competitive economics for emerging entrants.
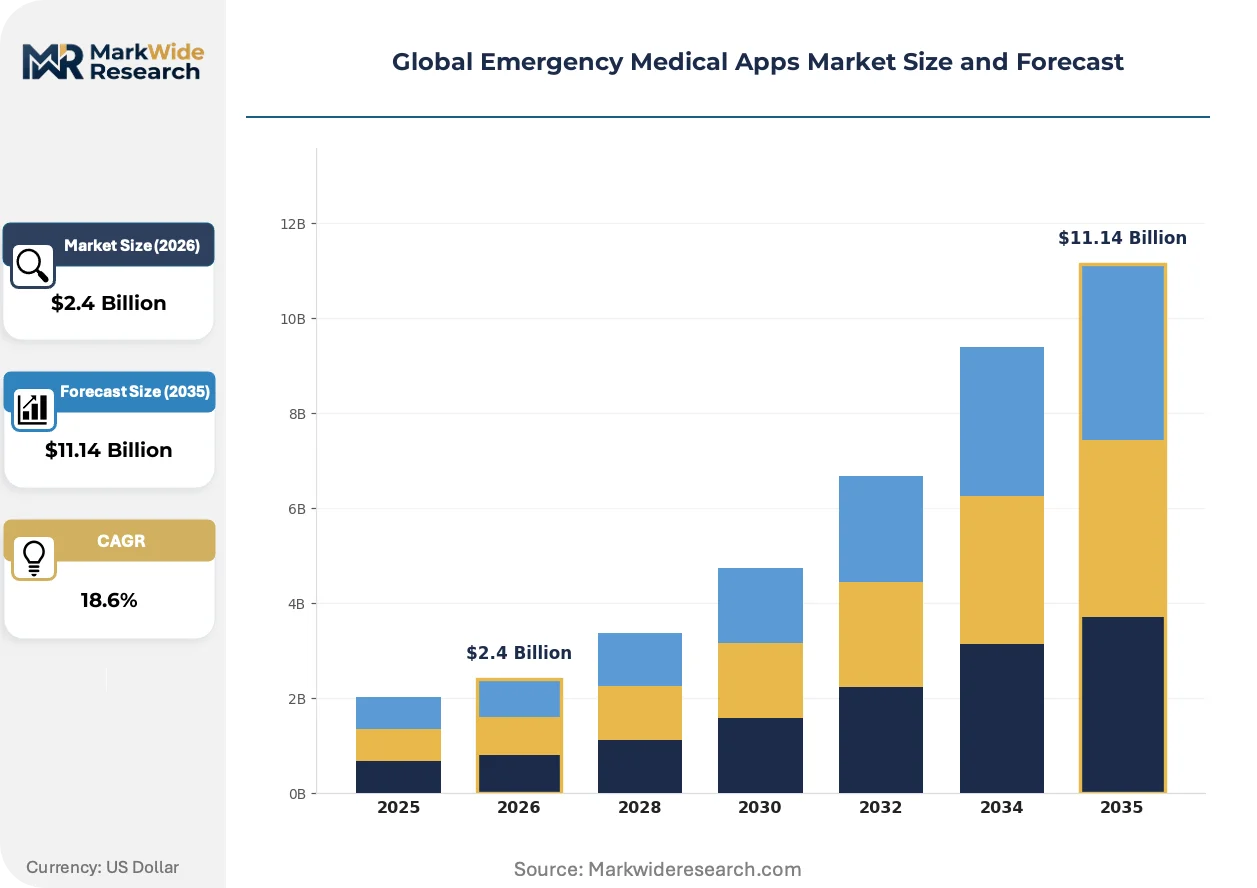
Market Dynamics
Real-time data interoperability mandates are compressing alert latency thresholds across emergency medical networks, forcing platform architectures toward sub-30-second transmission benchmarks.
Growth Catalysts
- FDA Software as a Medical Device guidance:Validation requirements for clinical decision support tools are elevating product credibility and accelerating hospital procurement cycles for compliant platforms.
- Regional trauma network integration:US health systems are embedding emergency apps into coordinated care protocols, creating anchor demand for inter-facility coordination software.
- 5G network deployment:Ultra-reliable low-latency communication is enabling video-assisted pre-hospital triage and expanding the functional scope of field-deployed applications.
Market Restraints
- HIPAA compliance architecture costs:End-to-end encryption and audit infrastructure impose substantial ongoing operational expenditure on smaller platform developers.
- EU MDR clinical evidence requirements:CE-marking mandates for diagnostic functionalities create protracted market entry timelines for non-European vendors.
- Legacy EMS dispatch system fragmentation:Proprietary CAD protocols in municipal emergency services obstruct seamless API integration and delay deployment.
Strategic Opportunities
- Germany's digital health infrastructure:The DiGA fast-track approval pathway creates expedited reimbursement access for emergency clinical decision support applications.
- Drone-integrated supply logistics:Aerial fulfillment networks for emergency pharmaceuticals and blood products represent an unclaimed service layer adjacent to core communication platforms.
- Corporate safety team procurement:Hybrid deployment models for workforce health monitoring across jurisdictional boundaries remain underpenetrated relative to EMS saturation.
Industry Challenges
- Interoperability certification backlog:NEMSIS version 3.5 data standard compliance testing creates bottlenecks for multi-state deployment authorizations.
- Cybersecurity talent scarcity:HITRUST certification expertise commands premium compensation, constraining vendor security roadmap velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emergency Medical Apps Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.14 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Accident Alert, Medical History Access, Emergency Contact, SOS Signaling, First Aid Guidance, Medication Reminders Platform: iOS, Android, Web-Based, Wearable Devices, Cross-Platform, Proprietary OS End User: EMS Providers, Elderly Care Coordinators, Corporate Safety Teams, Individual Consumers, School Safety Officers, Public Safety Agencies Deployment Mode: Cloud-Based, On-Premise, Hybrid, SaaS, Mobile-Only, Enterprise Solutions |
| Companies Covered | Zipline, Pulsara, RapidSOS, Vmedo, ESO, DispatchHealth, Element Science, Active911, Carbyne, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emergency Medical Apps Market Shifts & Advancements
Platform architectures are bifurcating between lightweight consumer-grade interfaces and hardened public safety hardware ecosystems, with middleware layers emerging to bridge functional gaps.
Edge computing for field-based patient monitoring is migrating from cloud-dependent architectures toward localized processing nodes. Rural EMS agencies in Australia and Canada are piloting these deployments to maintain functionality during cellular network degradation. The structural consequence is a compression in single points of failure for critical alert pathways.
EU MDR Article 10 clinical evidence requirements are forcing emergency app developers to construct prospective validation studies for diagnostic modules. This industrial consequence elevates barriers for wellness-adjacent platforms seeking clinical reclassification. German and French vendors are responding by pre-positioning CE-marked evidence packages ahead of enforcement discretion shifts.
Subscription pricing for enterprise safety deployments is displacing perpetual licensing in corporate procurement cycles. Risk management departments in energy and logistics verticals are driving this transition through preference for operational expenditure treatment. This pattern is most visible in US-based Fortune 500 facility safety programs.
Global Emergency Medical Apps Market Segmentation
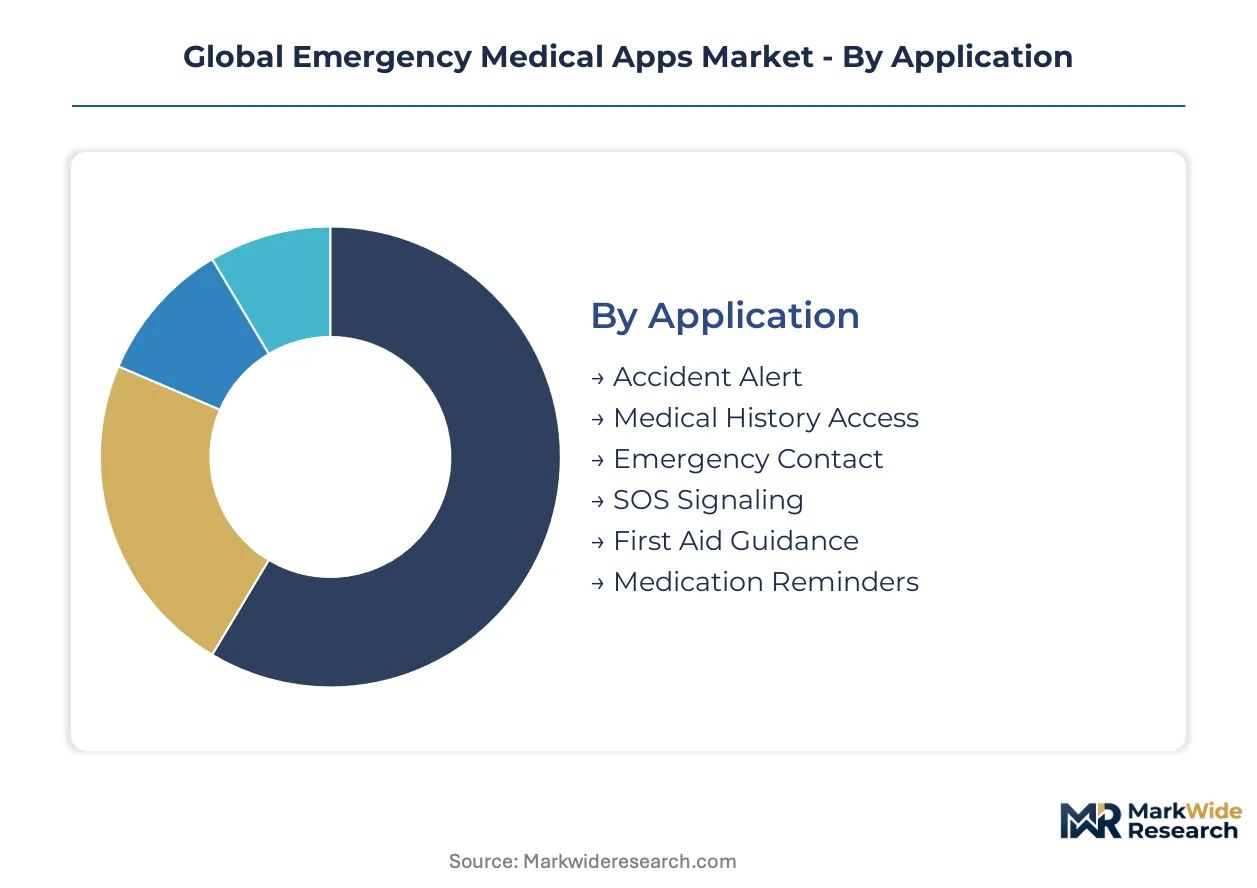
Emergency medical apps serve divergent operational contexts—from pre-hospital trauma networks to individual consumers—requiring segmentation that captures functional, technical, and procurement dimensions. Each category reveals distinct vendor strategies and buyer priorities that shape platform development roadmaps.
Application:
After-sales service intensity varies sharply across emergency app functionalities, with clinical decision support modules demanding continuous algorithm validation and regulatory maintenance compared to consumer alert tools.
- Accident Alert:Real-time crash detection using smartphone accelerometers and gyroscopes triggers automated emergency service notifications. Demand concentrates in automotive fleet operators across Germany and the United States, driven by corporate liability mitigation mandates and integration with vehicle telematics platforms.
- Medical History Access:Cloud-aggregated patient records enable field clinicians to retrieve allergies, medications, and conditions during emergencies. Hospital networks in California and Texas anchor procurement, compelled by regional trauma protocol standardization and FDA Software as a Medical Device compliance requirements for clinical data presentation.
- Emergency Contact:Automated notification cascades alert designated family members and physicians during critical events. Individual consumers and elderly care facilities in Japan represent the primary demand base.
- SOS Signaling:One-touch distress broadcasts combine GPS coordinates with pre-recorded medical profiles to dispatch services. Wilderness recreation and lone-worker safety programs in Australia and Canada drive specialized deployments.
- First Aid Guidance:Step-by-step instructional modules for bystander intervention during cardiac arrest, choking, or bleeding events. School districts and workplace safety officers constitute the core procurement segment.
- Medication Reminders:Scheduled alerts for chronic disease management with emergency escalation pathways for missed doses. Elderly care coordinators and home health agencies in France and Italy represent concentrated demand.
Accident Alert holds the largest share; momentum sits with Medical History Access.
Platform:
Platform selection directly shapes development cost structures, with proprietary OS installations requiring dedicated hardware partnerships while cross-platform architectures maximize addressable user bases.
- iOS:Apple's closed ecosystem delivers standardized device performance and streamlined HIPAA-compliant encryption implementations. Individual consumers in the United States and United Kingdom dominate volume, attracted by native HealthKit integration and consistent emergency service API reliability across carrier networks.
- Android:Open-source flexibility enables deep customization for EMS hardware manufacturers and regional carrier bundles. Municipal emergency services in India and Brazil leverage Android's lower device cost thresholds for field-deployed tablets.
- Web-Based:Browser-accessible platforms eliminate app store dependencies for enterprise safety dashboards. Corporate safety teams with bring-your-own-device policies favor this deployment mode.
- Wearable Devices:Smartwatch-native applications exploit continuous biometrics for automated fall detection and arrhythmia alerts. Elderly care markets in Japan and South Korea show concentrated adoption.
- Cross-Platform:Unified codebases reduce maintenance overhead for vendors serving heterogeneous user populations. Mid-size EMS agencies with mixed device fleets represent key demand.
- Proprietary OS:Dedicated public safety operating systems from Motorola Solutions and Harris Corporation prioritize interoperability mandates over consumer convenience. Federal and state-level agencies in the United States constitute the exclusive addressable market.
iOS captures the greatest revenue concentration; Android is climbing the fastest in emerging market EMS procurement.
End User:
Procurement authority fragmentation across end users creates divergent sales cycles, with public safety agencies requiring multi-year pilot programs while individual consumers convert through app store discovery.
- EMS Providers:Pre-hospital agencies demand sub-60-second alert latency, NEMSIS-compliant data transmission, and direct CAD system integration. Regional trauma networks in Florida, Arizona, and Ohio anchor North American procurement, pressured by CMS reimbursement incentives for care coordination documentation.
- Elderly Care Coordinators:Assisted living facilities and home health agencies prioritize fall detection, medication adherence, and family notification workflows. Japan's super-aged municipalities and Germany's DiGA reimbursement pathway accelerate platform adoption.
- Corporate Safety Teams:Energy, logistics, and manufacturing verticals deploy workforce monitoring for isolated or hazardous duty personnel. Fortune 500 facility safety programs in Texas and Alberta favor operational expenditure treatment through subscription pricing.
- Individual Consumers:Direct-to-user downloads serve health-conscious populations and family caregivers seeking personal emergency response capabilities. Urban professionals in South Korea and the United States represent concentrated demographics.
- School Safety Officers:K-12 districts require mass notification, reunification protocol management, and medical emergency response tools. State-level mandates in California and New York drive standardization.
- Public Safety Agencies:Police, fire, and consolidated dispatch centers demand hardened security certifications and mutual aid interoperability. Federal interoperability grants in the United States shape procurement priorities.
EMS Providers command the highest contract values; Corporate Safety Teams represent the steepest expansion trajectory as hybrid workforce models proliferate.
Deployment Mode:
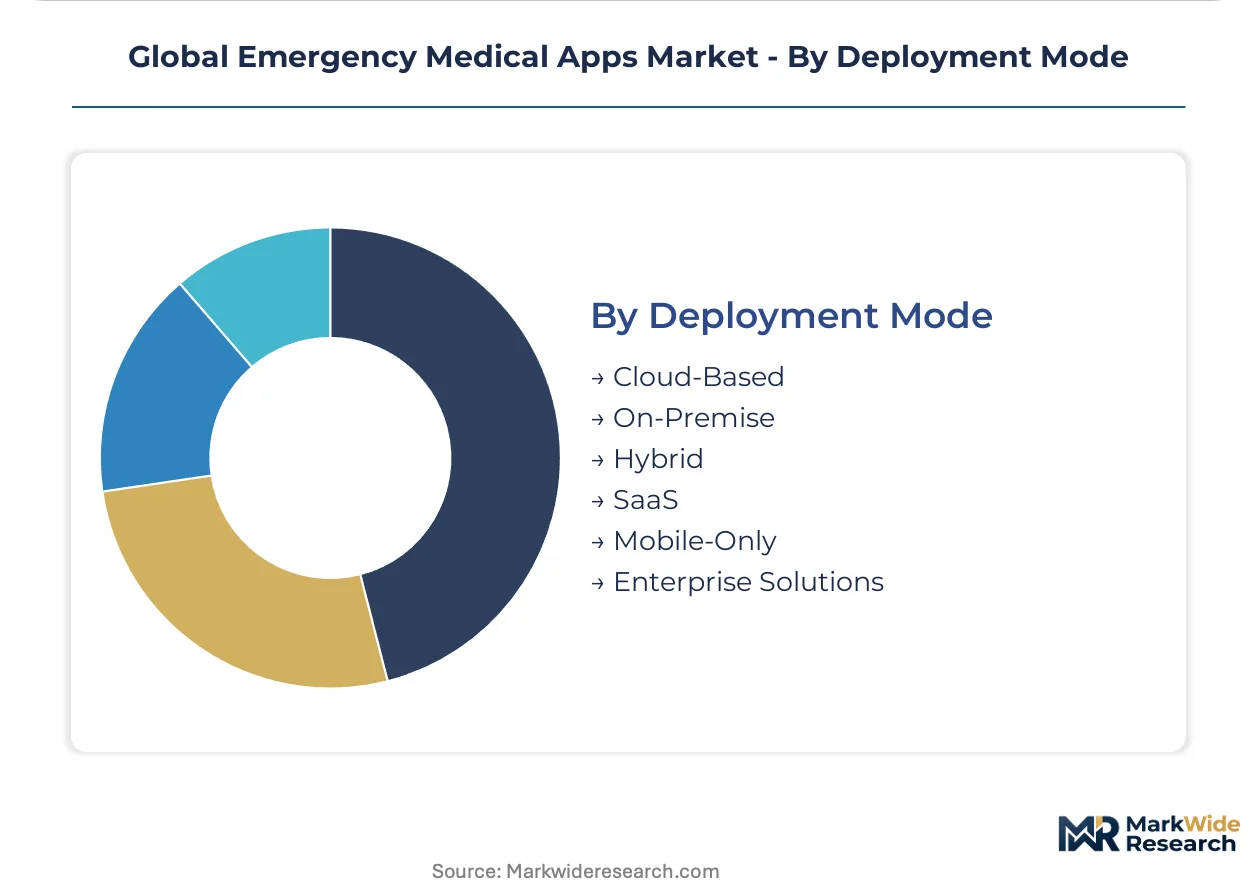
Deployment architecture selection reflects IT resource availability and data sovereignty requirements, with cloud-native solutions dominating resource-constrained agencies while hybrid models address cross-border workforce monitoring.
- Cloud-Based:Fully managed SaaS architectures eliminate server maintenance burdens for rural and volunteer EMS agencies. Small-to-mid-size providers across Australia's remote territories and Canada's prairie provinces favor this model for rapid deployment without capital expenditure.
- On-Premise:Local server installations satisfy data residency mandates and air-gapped security requirements. Defense and critical infrastructure sectors in the United States and United Kingdom mandate this architecture.
- Hybrid:Mixed cloud-edge configurations enable sensitive workforce health data processing within jurisdictional boundaries while leveraging centralized analytics. Multinational corporate safety programs with operations spanning EU GDPR and US HIPAA regimes require this flexibility.
- SaaS:Subscription-licensed platforms with automatic feature updates dominate municipal procurement cycles. US county-level EMS districts increasingly specify SaaS in RFPs.
- Mobile-Only:Smartphone-dependent deployments without backend infrastructure serve consumer wellness and basic alert functions. Developing market individual consumers represent the addressable base.
- Enterprise Solutions:Custom-integrated platforms with dedicated implementation teams serve large health system networks. Integrated delivery networks in Pennsylvania and Michigan anchor demand.
Cloud-Based deployments hold the largest installed base; Hybrid models are gaining share fastest among multinational corporate safety programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The 5G network rollout across the United States underwrites North America's emergency medical app infrastructure, while Germany's DiGA fast-track pathway and Japan's super-aged municipal networks anchor demand concentration elsewhere.
United States
Regional trauma networks in Florida, Arizona, and Ohio drive procurement volume as CMS reimbursement incentives reward care coordination documentation. FDA Software as a Medical Device guidance tightens validation requirements for clinical decision support tools. The Texas corporate safety corridor anchors Fortune 500 subscription deployments for workforce health monitoring.
Germany
The DiGA fast-track approval pathway accelerates reimbursement access for emergency clinical decision support applications. EU MDR Article 10 clinical evidence requirements force developers to construct prospective validation studies for diagnostic modules. Bavaria's digital health infrastructure clusters vendor pre-positioning ahead of enforcement discretion shifts.
Japan
Super-aged municipalities concentrate demand for elderly care coordination platforms with fall detection and medication adherence workflows. METI standards for medical device software shape domestic certification timelines. Tokyo's assisted living facility networks pilot smartwatch-native applications exploiting continuous biometrics.
Australia
Rural EMS agencies in Queensland and Western Australia pilot edge computing deployments to maintain functionality during cellular network degradation. The Therapeutic Goods Administration regulates clinical decision support modules under software as a medical device frameworks. The remote territories favor cloud-based SaaS architectures for rapid deployment without capital expenditure.
India
Municipal emergency services in Maharashtra and Karnataka leverage Android's lower device cost thresholds for field-deployed tablets. CDSCO guidance on software as a medical device creates compliance baselines for diagnostic functionalities. Bangalore's health-tech startup ecosystem concentrates middleware development bridging consumer and public safety hardware gaps.
Global Emergency Medical Apps Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying location intelligence, communication protocols, and fulfillment infrastructure. The vendor base arranges across three tiers: hospital network partners anchoring inter-facility coordination, embedded location platforms integrating with public safety answering points, and proprietary fulfillment layers controlling drone-based supply logistics. Dominant competitive moves include strategic partnerships with regional trauma networks and portfolio diversification into adjacent corporate safety verticals.
Within the platform integrator tier, Pulsara and RapidSOS occupy positions exemplifying divergent anchoring strategies—one through hospital network partnerships, the other through embedded location intelligence—while Zipline represents the proprietary fulfillment archetype controlling aerial logistics infrastructure. These three companies illustrate how competitive positioning fragments across communication, location, and supply chain vectors rather than consolidating around unified platforms.
| Leading Market Players |
|---|
| Zipline |
| Pulsara |
| RapidSOS |
| Vmedo |
| ESO |
| DispatchHealth |
| Element Science |
| Active911 |
| Carbyne |
| Others |
Supply & Pricing Matrix
Cloud infrastructure concentration in the United States and Ireland concentrates margin capture among hyperscale providers, forcing emergency medical app vendors to absorb escalating compute costs or pass through to enterprise subscribers. This upstream dynamic compresses profitability for mid-tier SaaS platforms while anchoring pricing power with hospital network integrators who negotiate volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates enterprise procurement, with premium tiers commanding multiples for HITRUST certification and dedicated implementation teams while economy tiers serve volunteer EMS agencies with stripped-down alert functionality. Price differentiation hinges on regulatory validation depth—FDA Software as a Medical Device compliance tiers separate hospital-grade clinical decision support from wellness-adjacent consumer tools—and geographic deployment scope, with multi-state trauma network licenses carrying substantial premiums. Cost compression in the mid-market tier is intensifying because NEMSIS compliance testing delays are extending sales cycles and inflating customer acquisition expenditure. Individual consumers exhibit highest price sensitivity, converting through freemium entry points, whereas integrated delivery networks demonstrate lowest sensitivity given CMS reimbursement incentives for care coordination documentation.
Supply Chain Analysis
Export-control regimes limiting encryption technology flows constrain supply chain configuration for emergency medical apps serving defense and critical infrastructure sectors, particularly affecting vendors seeking to deploy HIPAA-compliant architectures across jurisdictional boundaries. Component sourcing draws from Taiwan for semiconductor fabrication, the United States for encryption module design, and Ireland for cloud infrastructure hosting. Raw material dependencies center on advanced lithography for edge computing chips, rare earth elements for GPS-accurate location hardware, and specialized optical components for video-assisted triage systems. Single-source vulnerability concentrates in Taiwan's foundry capacity for low-power wearable processors. Distribution runs through direct enterprise sales teams for hospital network contracts, carrier-integrated platforms for municipal EMS procurement, and specialized healthcare marketplaces for mid-size agency subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment modes, end-user archetypes, and regulatory jurisdictions creates niche entry points for specialized vendors. The shift from perpetual licensing to subscription pricing in corporate safety procurement is segmenting buyer expectations and opening white-space for flexible commercial models.
For Market Incumbents: Build regulatory certification moats by pre-positioning CE-marked clinical evidence packages ahead of EU MDR enforcement discretion shifts. Pursue backward integration into edge computing hardware partnerships to reduce hyperscale cloud dependency. Defend against emerging middleware developers by locking exclusive regional trauma network partnerships in Florida, Arizona, and Ohio. For New Entrants and Emerging Players: Pursue Germany's DiGA fast-track pathway as the most penetrable reimbursement environment for clinical decision support modules. Target Australia's rural EMS agencies with cloud-native SaaS architectures that eliminate capital expenditure barriers. Attack the corporate safety team segment through hybrid deployment models addressing cross-border GDPR-HIPAA compliance requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed platform integrators holding hospital network anchor contracts but lacking drone logistics or wearable-native capabilities. Five-to-ten year viability favors vendors controlling proprietary fulfillment layers or embedded location intelligence rather than pure communication plays. Watch FDA reclassification of wellness-to-diagnostic functionalities as the critical inflection signal triggering premarket submission obligations and reshaping competitive economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Validation investment separates hospital-grade clinical decision support from wellness-adjacent competitors. |
| CE Marking Pathway Construction | Prospective evidence packages satisfy EU MDR Article 10 requirements ahead of enforcement discretion shifts. |
| Hospital System Partnership Anchoring | Regional trauma network integration in Florida, Arizona, and Ohio creates recurring subscription revenue bases. |
| Wearable-Native Application Development | Smartwatch exploitation for continuous biometrics addresses Japan's super-aged municipal demand concentration. |
| Drone Logistics Integration | Aerial fulfillment networks for emergency pharmaceuticals represent unclaimed service layer adjacent to core platforms. |
Research Methodology
A spread of perspectives from EMS agency operations directors, hospital purchasing committee members, biomedical engineers specializing in pre-hospital systems, and GPO contracts managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and NEMSIS compliance certification registries. Bottom-up triangulation across platform deployment metrics and top-down reconciliation against health system IT expenditure patterns anchored volume estimates.
Demand-supply balance framing shaped the analytical approach across the projection horizon, with modeled segmentation spanning deployment architecture, end-user archetype, platform ecosystem, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to documented procurement cycles and reimbursement pathway adoption rates. Forecast inputs incorporated 5G network rollout timelines, DiGA approval velocity, and trauma network integration mandates.
Sensitivities concentrate around FDA enforcement discretion boundaries, EU MDR clinical evidence requirement timing, and NEMSIS version 3.5 compliance testing backlog resolution. Forecasts reflect documented assumptions regarding reimbursement incentive durability and interoperability certification velocity. Material shifts in FDA Software as a Medical Device classification criteria or hyperscale cloud pricing architecture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Emergency Medical Services Market