
 US Emergency Medical Transportation Market | 2026-2036
US Emergency Medical Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
US Emergency Medical Transportation Market Analytics
Hospital system consolidation across the US is expanding the bargaining leverage of large integrated delivery networks when negotiating ambulance service contracts. Global Medical Response leverages its national fleet footprint to sustain preferential rate agreements with major health systems. Falck USA anchors its competitive position through specialized fire-based EMS partnerships in municipalities. Acadian Ambulance differentiates via deep operational coverage across the Gulf Coast corridor.
Emergency medical transportation encompasses the pre-hospital movement of critically ill or injured patients using medically staffed vehicles equipped with life-support systems, cardiac monitors, and ventilatory assistance devices. These services bridge the gap between incident scenes and definitive care facilities, with response-time thresholds often mandated at eight minutes or less for advanced life support dispatch. Ground ambulance operations still dominate total service volume, though air ambulance segments command disproportionate margin pools due to specialized crew certification and aircraft maintenance overhead. Private EMS service models are gaining contract share from municipal providers as county budgets tighten and outsourcing pressures mount.
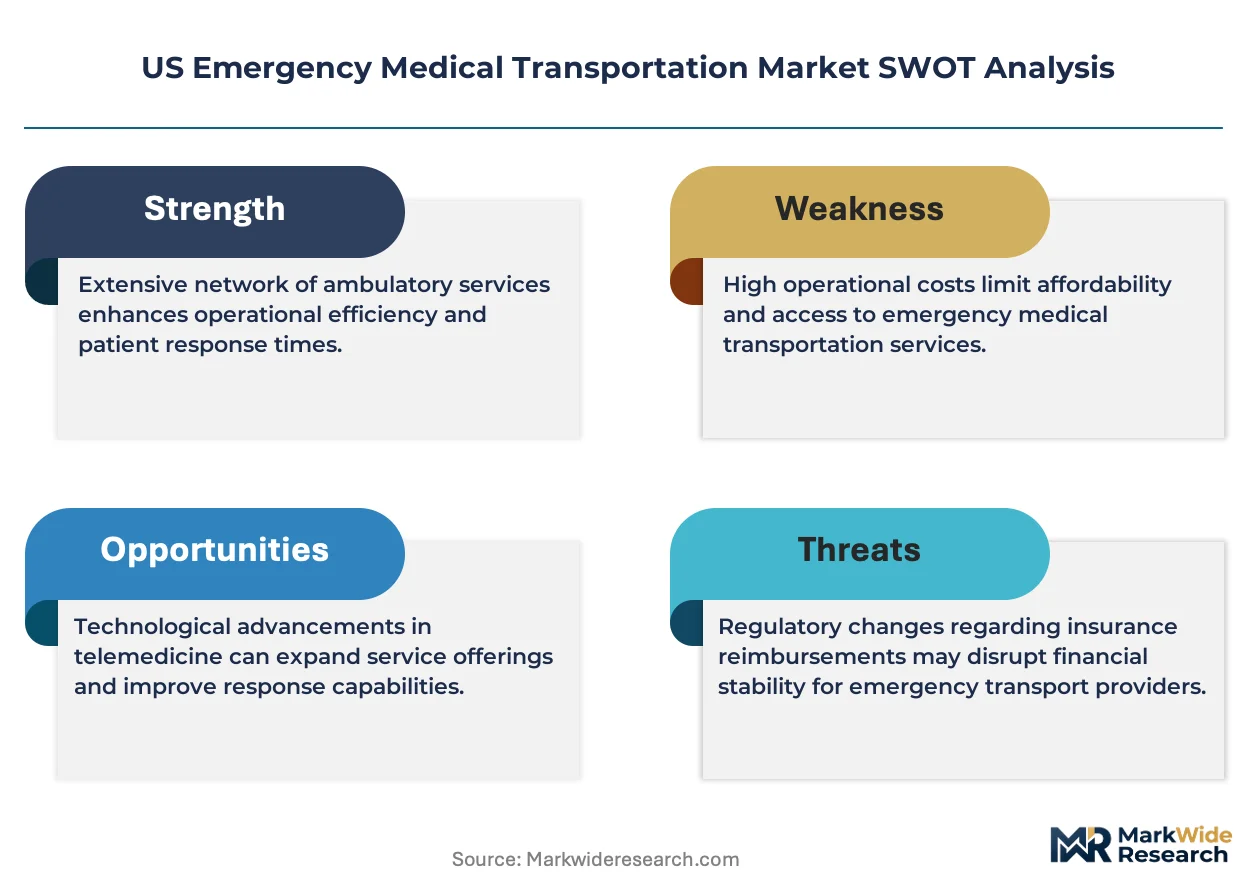
Federal oversight from CMS shapes reimbursement ceilings for both emergency and non-emergency transports, while FAA regulations govern air ambulance flight operations and pilot duty limits. State-level EMS agencies enforce staffing ratios, vehicle equipment mandates, and response-time reporting requirements that vary considerably across jurisdictions. Stakeholders must monitor how proposed Medicare fee schedule adjustments and emerging telemedicine integration standards will alter dispatch protocols and capital allocation priorities.
Market Dynamics
CMS reimbursement reforms are compressing revenue per transport while rural hospital closures force longer dispatch distances, fundamentally restructuring how providers optimize fleet positioning and crew utilization across service territories.
Growth Catalysts
- CMS Medicare Fee Schedule Adjustments:Reimbursement rate recalibrations for air ambulance services are incentivizing investments in rotary-wing assets and specialized crew training programs.
- Southwest Demographic Concentration:Retiree migration into Arizona and New Mexico corridors is expanding non-emergency medical transport volumes for dialysis and specialist appointments.
- Telemedicine Dispatch Integration:Real-time video triage protocols are expanding appropriate utilization of advanced life support resources and reducing unnecessary emergency responses.
Market Restraints
- Jet Fuel Price Volatility:Air ambulance operators face margin compression from aviation fuel cost swings that CMS reimbursement rates do not dynamically adjust to capture.
- Pilot Certification Bottlenecks:FAA commercial rotorcraft license requirements and duty-time restrictions constrain available flight crew supply during peak demand windows.
- Ground Ambulance Fleet Replacement Cycles:Extended capital equipment lifecycles for municipal providers delay technology refresh and telematics upgrades.
Strategic Opportunities
- Texas Rural Hospital Desert Coverage:Underserved counties in West Texas present contract white space for dedicated air ambulance stationing and rapid response networks.
- Subscription-Based Membership Models:Direct-to-consumer transport insurance products are emerging as alternative revenue streams independent of traditional payer contracts.
- Electric Ground Ambulance Pilots:California and New York fleet electrification mandates are creating early-mover advantages for zero-emission vehicle deployment in urban corridors.
Industry Challenges
- Paramedic Workforce Attrition:Burnout and compensation gaps in high-call-volume metros are elevating recruitment costs and overtime dependency for private operators.
- Interoperable Data Standards:Fragmented electronic health record integration between dispatch centers and receiving hospitals delays pre-hospital care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Emergency Medical Transportation Market |
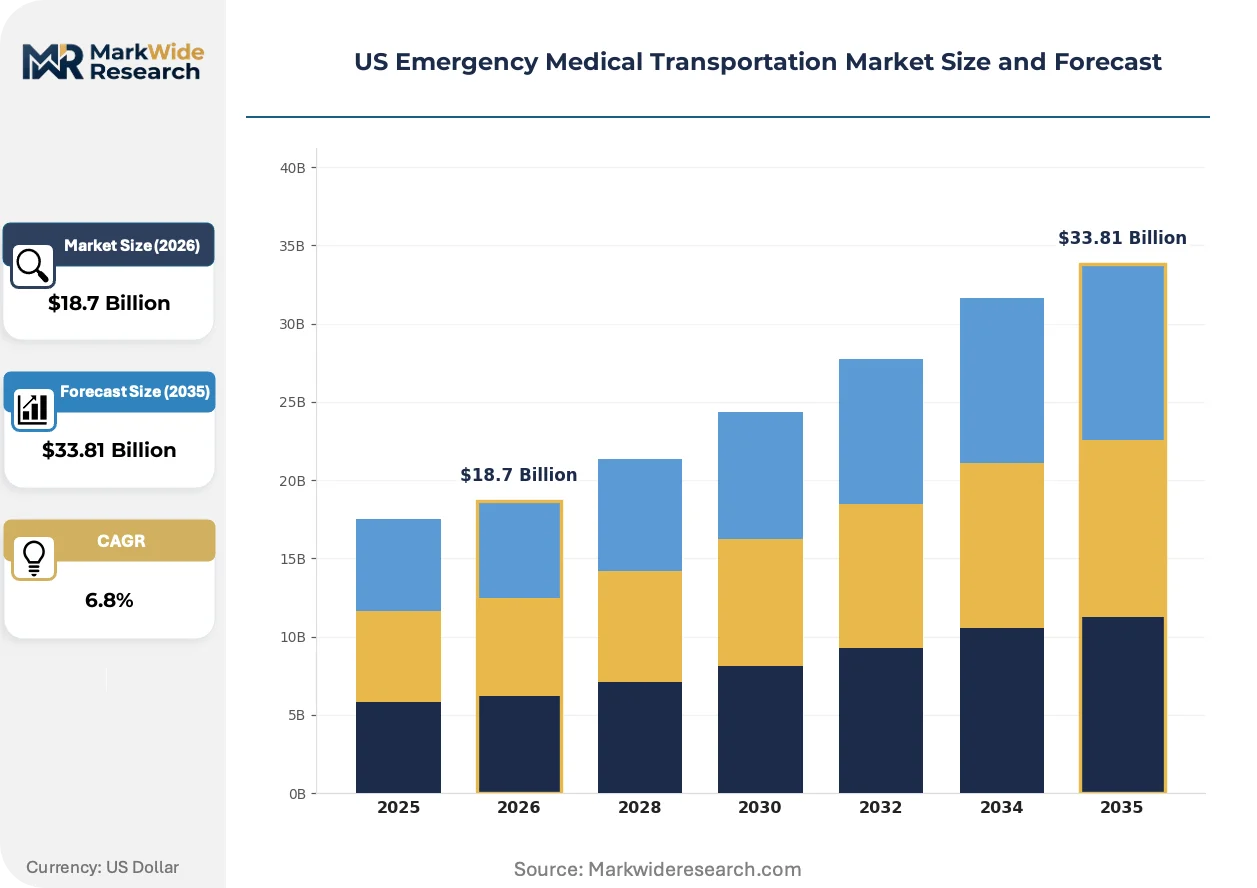
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Ground Ambulance, Air Ambulance, Water Ambulance, Non-Emergency Transport Service Model: Public EMS, Private EMS, Hospital-based Transport, Volunteer Services End User: Hospitals, Nursing Facilities, Clinics, Rehabilitation Centers Technology: GPS Tracking, Telemedicine, Patient Monitoring Systems, Communication Tools |
| Companies Covered | Global Medical Response, Inc., Falck USA Inc., Acadian Ambulance Service, LLC, American Medical Response, Medtronic plc, GE Healthcare, Stryker Corporation, Cardinal Health, Inc., Philips Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Emergency Medical Transportation Market Evolving Landscape
Telemedicine-enabled dispatch protocols and predictive analytics are compressing response-time windows while reshaping how emergency medical services allocate resources across urban-rural gradients. These shifts are altering capital deployment priorities and contract structures.
Artificial intelligence triage algorithms are decentralizing initial patient assessment from centralized dispatch centers to field-based paramedic decision support. Regional EMS authorities in Florida and Georgia are piloting machine-learning models that recommend transport destination based on real-time hospital capacity and specialty availability. This capability is reducing ambulance diversion incidents and improving patient throughput at Level I trauma centers.
FAA regulations governing extended-range twin-engine operations are expanding air ambulance service radii for inter-facility transfers. The regulatory change permits longer over-water and mountainous corridor flights without alternate airport requirements. Critical access hospitals in the Rocky Mountain states are leveraging this flexibility to maintain specialty care access for remote populations.
Hospital system consolidation is compressing ambulance contract renewal cycles and elevating performance-based pricing clauses. Integrated delivery networks in the Southeast are unbundling emergency and non-emergency transport procurement, creating distinct vendor pools for each service tier. This bifurcation is visible across Carolinas HealthCare and Baylor Scott & White service territories.
US Emergency Medical Transportation Market Segmentation
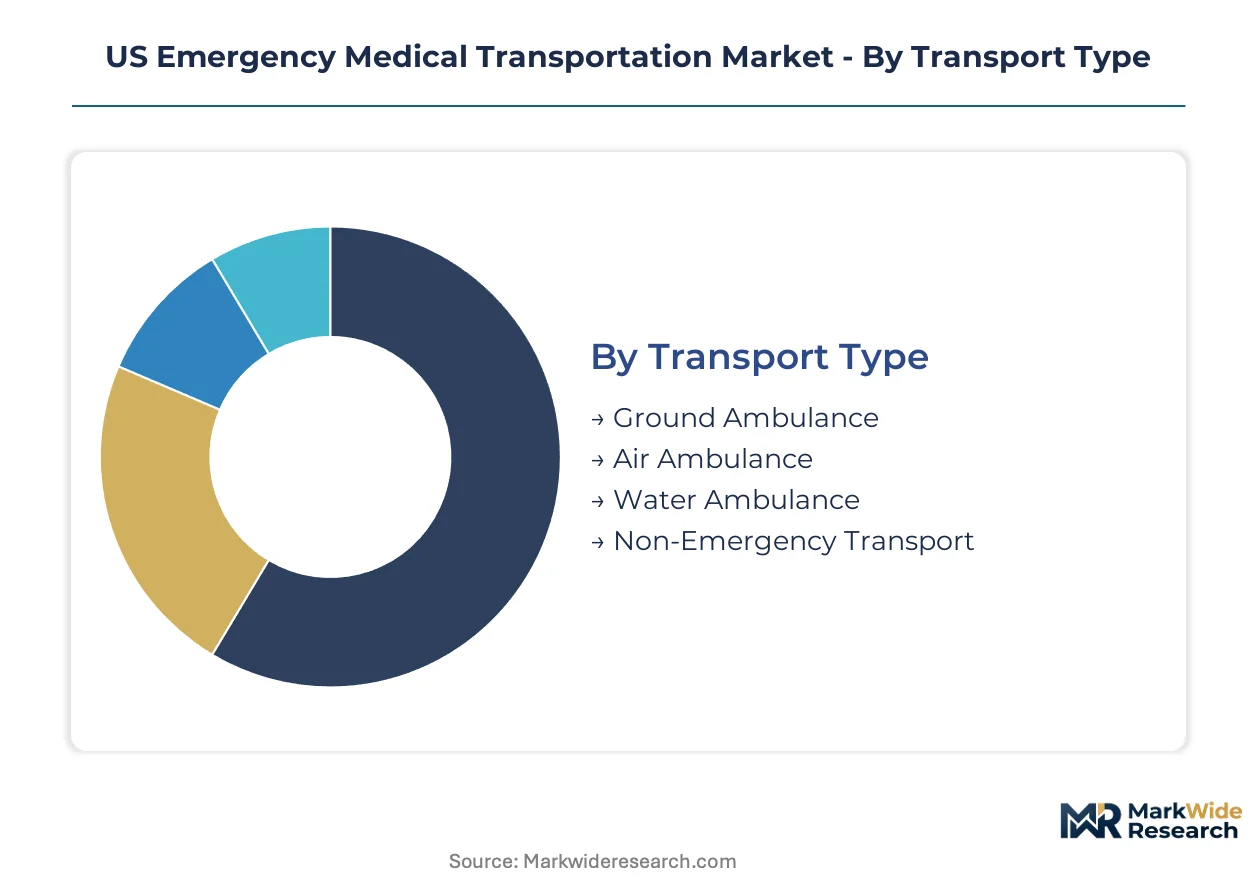
Segmentation reveals how regulatory requirements, operational costs, and reimbursement structures fragment competitive positioning across the US emergency medical transportation landscape. Each dimension carries distinct certification burdens and capital intensity profiles that shape provider specialization.
Transport Type:
FAA rotorcraft certification requirements impose the steepest regulatory burden on air ambulance operators, while ground ambulance segments navigate NHTSA vehicle safety standards and state-level EMS licensing.
- Ground Ambulance:Wheel-based emergency vehicles equipped with cardiac monitors, ventilators, and advanced life support kits dominate call volume across urban and suburban corridors. CMS reimbursement rates for ground transport face compression from Medicare fee schedule adjustments, though volume concentration in the Southeast and Southwest offsets per-trip margin pressure.
- Air Ambulance:Rotary-wing and fixed-wing aircraft staffed by critical care paramedics and flight nurses command premium reimbursement for inter-facility transfers and trauma scene evacuations. Rural hospital closures in West Texas and the Rocky Mountain states are extending dispatch radii and elevating utilization for time-critical cases.
- Water Ambulance:Maritime evacuation vessels serve coastal populations and island communities with specialized dive-medicine capabilities.
- Non-Emergency Transport:Scheduled mobility services for dialysis, chemotherapy, and specialist appointments operate under lower acuity thresholds with reduced crew certification requirements.
Ground ambulance sits at the top of the volume ranking, with air ambulance climbing the fastest.
Service Model:
Cost tier differentiation separates capital-intensive hospital-based fleets from leaner private EMS contractors competing on municipal outsourcing contracts.
- Public EMS:Fire department and county-operated services maintain statutory coverage obligations with pension-backed staffing structures. Budget constraints in municipalities across the Gulf Coast are accelerating privatization of non-emergency transport functions.
- Private EMS:Investor-owned operators leverage scale economies across multi-state footprints to secure preferred provider agreements with consolidated health systems. Acadian Ambulance and Falck USA anchor regional dominance through exclusive municipal contracts and specialized crew training programs.
- Hospital-based Transport:Integrated delivery networks operate captive fleets to control referral leakage and optimize bed turnover. Baylor Scott & White and Carolinas HealthCare have unbundled emergency and non-emergency procurement, creating distinct vendor tiers.
- Volunteer Services:Community-funded squads supplement coverage in rural counties with limited tax bases, though recruitment challenges are elevating reliance on paid standby arrangements.
Private EMS commands the widest geographic footprint, while hospital-based transport is gaining share fastest among integrated delivery networks.
End User:
Application intensity varies sharply across acute care facilities versus post-acute settings, with nursing facilities driving disproportionate non-emergency volume.
- Hospitals:Level I trauma centers and critical access hospitals generate the highest-acuity emergency transports with advanced life support crew requirements. Diversion reduction protocols in Florida and Georgia are reshaping destination decisions through real-time capacity monitoring.
- Nursing Facilities:Long-term care operators contract for recurring dialysis and wound care transfers, creating predictable revenue streams with lower per-trip margins. Retiree migration into Arizona and New Mexico corridors is expanding this segment's addressable base.
- Clinics:Outpatient surgery centers and urgent care sites generate scheduled discharge transports with intermediate acuity profiles.
- Rehabilitation Centers:Post-acute facilities require specialized bariatric and mobility-assistance equipment for patient movement.
Hospitals anchor the highest-value emergency segment, with nursing facilities expanding most quickly on demographic tailwinds.
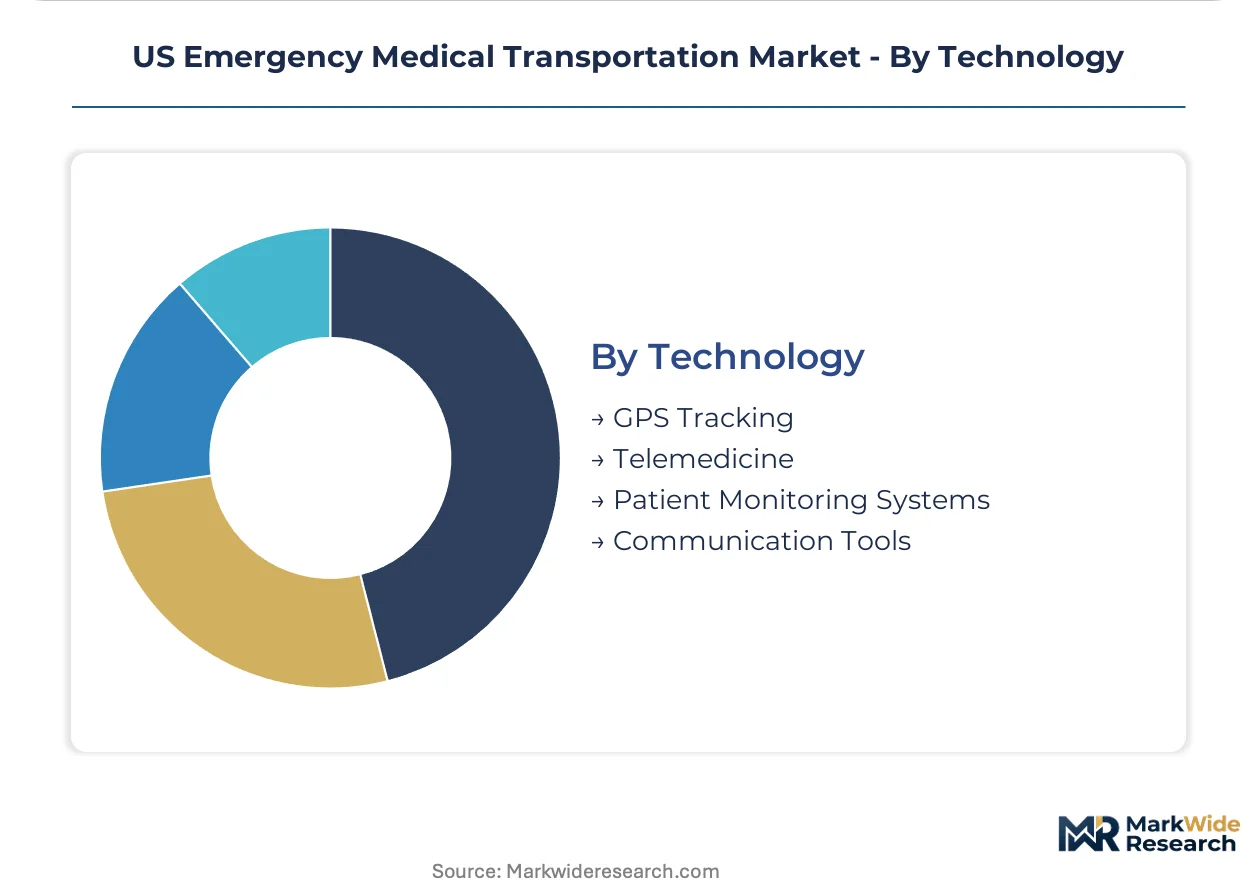
Technology:
Margin structure separates capital-heavy patient monitoring hardware from software-based telemedicine platforms with recurring subscription economics.
- GPS Tracking:Real-time fleet positioning systems optimize dispatch algorithms and reduce response-time variance across sprawling service territories. Southwest corridor operators leverage geographic data to pre-position assets ahead of predicted demand spikes.
- Telemedicine:Video triage protocols enable paramedics to consult emergency physicians before transport commitment, reducing unnecessary emergency responses. CMS reimbursement reforms are accelerating adoption as payers demand utilization verification.
- Patient Monitoring Systems:Continuous vital sign transmission to receiving hospitals improves handoff continuity and trauma team activation timing.
- Communication Tools:Interoperable radio and data networks bridge dispatch centers with hospital emergency departments, though fragmented electronic health record standards delay full integration.
GPS tracking holds the deepest installed base, with telemedicine gaining share fastest on payer pressure for appropriate utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates higher air ambulance utilization per capita than Canada, while Mexico's emergency transport infrastructure remains concentrated around major metropolitan corridors with limited rural penetration.
Southwest Corridor
Retiree migration into Arizona and New Mexico expands non-emergency medical transport volumes for dialysis and specialist appointments. CMS reimbursement reforms under the Medicare fee schedule reshape billing protocols for both emergency and non-emergency services. Phoenix and Tucson anchor expanding air ambulance networks addressing hospital desert coverage gaps across rural counties.
Southeast Corridor
Aging demographics in Florida and Georgia intensify call volumes for advanced life support dispatch with mandated eight-minute response thresholds. State-level EMS agencies enforce varying staffing ratios and vehicle equipment mandates across jurisdictions. Atlanta and Miami-Dade serve as hubs for integrated delivery networks unbundling emergency and non-emergency transport procurement.
Texas Rural Networks
Critical access hospital closures in West Texas extend dispatch radii and elevate utilization for time-critical trauma cases. FAA regulations govern rotorcraft certification requirements and pilot duty limits for inter-facility transfers. Dallas-Fort Worth and Houston anchor dedicated air ambulance stationing serving rapid response networks across underserved counties.
Rocky Mountain States
Mountainous terrain and sparse population density drive disproportionate reliance on rotary-wing assets for scene evacuations. FAA extended-range twin-engine operation rules permit longer flights without alternate airport requirements. Denver and Salt Lake City anchor critical care transport networks connecting remote populations to Level I trauma centers.
Gulf Coast Corridor
Coastal populations and island communities require specialized maritime evacuation capabilities alongside traditional air and ground assets. Municipal budget constraints accelerate privatization of non-emergency transport functions. New Orleans and Mobile anchor operational coverage for hurricane response and offshore medical evacuation services.
US Emergency Medical Transportation Market Competitive Landscape
National-scale operators anchor one tier; regional specialists hold municipal contracts through fire-based EMS partnerships. The vendor base separates into consolidated national fleets, regional coverage anchors, and equipment suppliers. Three strategic archetypes dominate: integrated transport networks, specialized municipal contractors, and medical device manufacturers. M&A activity concentrates among private EMS operators acquiring county contracts, while technology partnerships reshape fleet telematics capabilities.
Within the national network tier, Global Medical Response, Inc. and American Medical Response exemplify scale-driven operators leveraging multi-state footprints for health system agreements. Falck USA Inc. occupies a position among municipal specialists through fire-based EMS partnerships. Acadian Ambulance Service, LLC anchors regional dominance across Gulf Coast corridors. Equipment manufacturers including Medtronic plc, GE Healthcare, and Stryker Corporation sit within the medical technology supply tier serving fleet operators with patient monitoring and life-support systems.
| Leading Market Players |
|---|
| Global Medical Response, Inc. |
| Falck USA Inc. |
| Acadian Ambulance Service, LLC |
| American Medical Response |
| Medtronic plc |
| GE Healthcare |
| Stryker Corporation |
| Cardinal Health, Inc. |
| Philips Healthcare |
| Others |
Value Network & Pricing Analysis
Jet fuel price volatility cascades through air ambulance operator cost structures, compressing margins on rotary-wing transports while CMS reimbursement floors remain fixed, forcing ground ambulance segments to absorb equipment inflation through extended fleet replacement cycles.
Pricing Analysis
Capacity additions in Texas and Arizona are reshaping price floors for emergency medical transport contracts as new entrants bid aggressively for rural hospital network agreements. Three-tier pricing structure across premium air ambulance, standard advanced life support ground, and economy non-emergency medical transport segments dominates procurement. Price differentiation hinges on FAA rotorcraft certification tier and geographic coverage radius, with Southwest corridor buyers exhibiting highest price sensitivity due to municipal budget constraints.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth and Phoenix anchor hub-and-spoke patterns for ground ambulance fleet parts, while air ambulance operators maintain captive maintenance hangars at tertiary hubs. Manufacturing concentration for patient monitoring systems rests on Minnesota and Massachusetts medical device clusters, with rotary-wing airframes sourced from Texas and Florida assembly facilities. Single-source vulnerability in FAA-certified avionics components poses structural risk, while distribution runs through integrated delivery network procurement consortia in the Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US emergency medical transportation market functions as a stable compounder, with demographic aging across the Southwest and Southeast corridors ensuring sustained call volume expansion regardless of macroeconomic cycles.
For Market Incumbents: Anchor fleet positioning in emerging hospital deserts across West Texas and rural New Mexico before competitors secure exclusive air ambulance stationing contracts. Deepen backward integration into telemedicine dispatch platforms to defend against technology-enabled new entrants seeking to disintermediate traditional dispatch relationships. CMS reimbursement compression demands operational excellence investments in predictive analytics and crew utilization optimization. For New Entrants and Emerging Players: Direct-to-consumer subscription channels offer the most penetrable route for bypassing consolidated health system procurement gatekeepers and establishing brand recognition among Medicare Advantage enrollees. Target non-emergency medical transport for dialysis and wound care transfers in Arizona retirement corridors, where incumbent coverage gaps persist and price sensitivity remains elevated. Partner with regional Medicare Advantage plans as the primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized air ambulance operators holding FAA extended-range twin-engine certifications and exclusive municipal contracts in underserved geographies. Long-term viability hinges on demographic tailwinds and regulatory moats rather than cyclical demand swings. Monitor CMS Medicare fee schedule rulemaking as the critical inflection signal for reimbursement trajectory and capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Air Ambulance Fleet Expansion | Rotary-wing stationing in West Texas hospital deserts captures time-critical trauma volume from closing critical access facilities. |
| Telemedicine Dispatch Integration | Real-time video triage protocols reduce unnecessary emergency responses and satisfy CMS utilization verification requirements. |
| Subscription Membership Model Launch | Direct-to-consumer transport insurance products bypass consolidated health system procurement and diversify revenue from payer contracts. |
| Electric Ground Ambulance Pilot | Zero-emission vehicle deployment in California urban corridors satisfies state fleet electrification mandates and generates early-mover positioning. |
| Municipal Contract Consolidation | Exclusive fire-based EMS partnerships in Gulf Coast municipalities lock out competitors through statutory coverage obligations. |
Research Methodology
Bottom-up nursing facility and hospital transport volume modeling reconciled against top-down CMS Medicare claims tracking forms the analytical core of this study. Primary interviews with EMS dispatch directors, air ambulance operations managers, hospital purchasing committee chairs, and Medicare Advantage plan contracting officers combined with secondary validation against FAA rotorcraft certification databases, CMS fee schedule filings, and state EMS agency staffing reports. Triangulation across these sources ensures segment-level accuracy for ground ambulance, air ambulance, and non-emergency medical transport categories.
Input-output matrices map transport type, service model, end-user facility, and technology adoption across the projection horizon, with CAGRs derived from historical Medicare claims growth rates adjusted for demographic migration patterns and hospital closure trajectories. Forecast inputs incorporate FAA regulatory changes affecting extended-range operations, CMS reimbursement rulemaking timelines, and telemedicine dispatch penetration curves.
The model assumes a particular technology adoption path for AI-enabled triage algorithms; alternative pathways for machine-learning dispatch integration would alter the outlook for advanced life support resource allocation. Forecasts reflect documented assumptions regarding Medicare fee schedule stability and rural hospital network consolidation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
US EMS Billing Services Market