
 Emergency Medical Services Market | 2026-2036
Emergency Medical Services Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Medical Services Market Intelligence
Modular equipment configurations is realigning procurement decisions across municipal and private ambulance fleets. Stryker Corporation leverages its integrated stretcher-monitor ecosystems to dominate North American critical care transport. Philips Healthcare sustains technology leadership through advanced defibrillation and patient monitoring platforms. ZOLL Medical Corporation specializes in automated CPR and temperature management devices for resuscitation workflows.
Emergency medical services encompass pre-hospital acute care, medical transport, and emergency response coordination delivered through ground and air vehicles staffed by trained personnel. Equipment specifications include ISO 13485-certified portable ventilators, biphasic defibrillators with joule-adjustable energy delivery, and satellite-linked telemetry systems transmitting real-time vital signs to receiving hospitals. Advanced Life Support commands premium reimbursement rates due to paramedic-administered medications and invasive airway procedures, while Air Ambulance segments face capacity constraints from pilot shortages and helicopter fleet aging. Critical Care Transport is expanding fastest as inter-facility transfers of ECMO and ICU patients require specialized mobile intensive care units.
The FDA governs premarket clearance of Class II and III emergency devices, while NHTSA sets ambulance design and crashworthiness standards under KKK-1822F specifications. State EMS offices implement scope-of-practice regulations that determine whether paramedics may perform surgical airways or administer blood products. Stakeholders must monitor reimbursement parity between ground and air medical transport, as CMS rate adjustments directly influence fleet investment cycles and service area coverage decisions.
Market Dynamics
Hospital outsourcing of pre-hospital care contracts is restructuring fleet procurement priorities across municipal and private ambulance operators, forcing equipment vendors to reconfigure service models around modular platform architectures rather than standalone device sales.
Growth Catalysts
- Pre-hospital care outsourcing:Hospital-based emergency departments are expanding contracted ambulance services to reduce fixed costs, creating sustained equipment refresh cycles across third-party fleet operators.
- FDA 510(k) pathway acceleration:The premarket notification framework for portable defibrillators compresses regulatory timelines, enabling faster deployment of next-generation resuscitation devices.
- Rural hospital closures:Facility shutdowns across underserved regions amplify reliance on advanced life support transport networks to bridge geographic care gaps.
Market Restraints
- Helicopter fleet aging:Air ambulance capacity faces structural constraints from pilot shortages and maintenance-intensive rotorcraft platforms nearing operational limits.
- Reimbursement parity gaps:CMS rate differentials between ground and air medical transport distort investment cycles and service area coverage decisions.
- Paramedic scope-of-practice fragmentation:State-level regulatory variation prevents standardized advanced procedure deployment across jurisdictions.
Strategic Opportunities
- Inter-facility critical care transport:ECMO and ICU patient transfers are driving demand for specialized mobile intensive care units with integrated life-support ecosystems.
- Satellite-linked telemetry integration:Real-time vital sign transmission to receiving hospitals enables pre-arrival preparation and improved handoff efficiency.
- Automated CPR device penetration:Mechanical compression systems represent underdeployed resuscitation technology with expansion potential across BLS and ALS fleets.
Industry Challenges
- Paramedic workforce attrition:Burnout and compensation gaps in emergency medical services are intensifying staffing shortages across high-volume metropolitan systems.
- ISO 13485 certification complexity:Portable ventilator manufacturers face extended quality management system audits that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Medical Services Market |
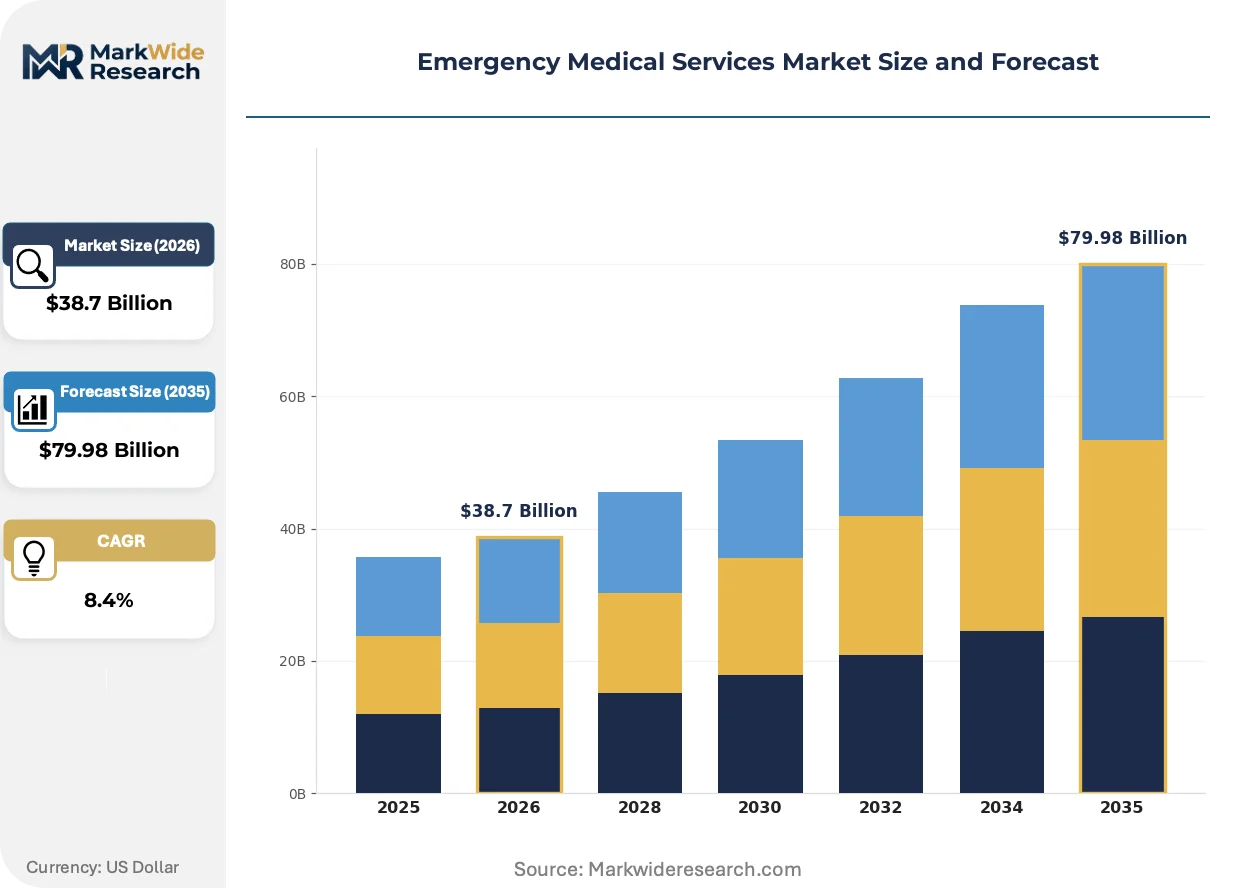
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Basic Life Support, Advanced Life Support, Critical Care Transport, Non-Emergency Transport Response Time: Under 5 Minutes, 5-10 Minutes, 10-20 Minutes, Over 20 Minutes Vehicle Type: Ambulance, Air Ambulance, Motorcycle, Mobile Clinic End User: Government Health Departments, Private Healthcare Providers, Fire Departments, Search & Rescue Units |
| Companies Covered | GE Healthcare, Medtronic plc, Stryker Corporation, Philips Healthcare, Cardinal Health, Inc., McKesson Corporation, BD, ZOLL Medical Corporation, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Medical Services Market Strategic Shifts & Innovations
Telemedicine integration and autonomous dispatch algorithms are redefining emergency response coordination, compressing time-to-treatment metrics while redistributing clinical decision-making authority from hospital settings to mobile platforms.
Point-of-care ultrasound is decentralizing diagnostic capability within ambulance environments, enabling paramedics to identify internal bleeding, cardiac tamponade, and pneumothorax during transport rather than upon hospital arrival. ALS units across trauma-heavy metropolitan systems are adopting handheld devices at accelerating rates. This capability shift is decentralizing clinical triage authority from emergency physicians to pre-hospital teams.
The FDA's evolving software-as-a-medical-device framework is tightening validation requirements for AI-enabled dispatch and diagnostic tools, extending development timelines for algorithm-driven emergency response platforms. Manufacturers must now demonstrate clinical validation across diverse patient populations. Cardiac monitoring segments face the steepest compliance burden as predictive arrhythmia algorithms attract heightened scrutiny.
Public-safety answering points are consolidating across regional boundaries, replacing fragmented municipal dispatch with centralized emergency communication centers that pool call volume and specialist resources. This restructuring eliminates redundant infrastructure but creates integration friction with legacy CAD systems. Consolidation is most visible across Midwestern and Southeastern states where fiscal pressures have accelerated intergovernmental cooperation agreements.
Emergency Medical Services Market Segmentation
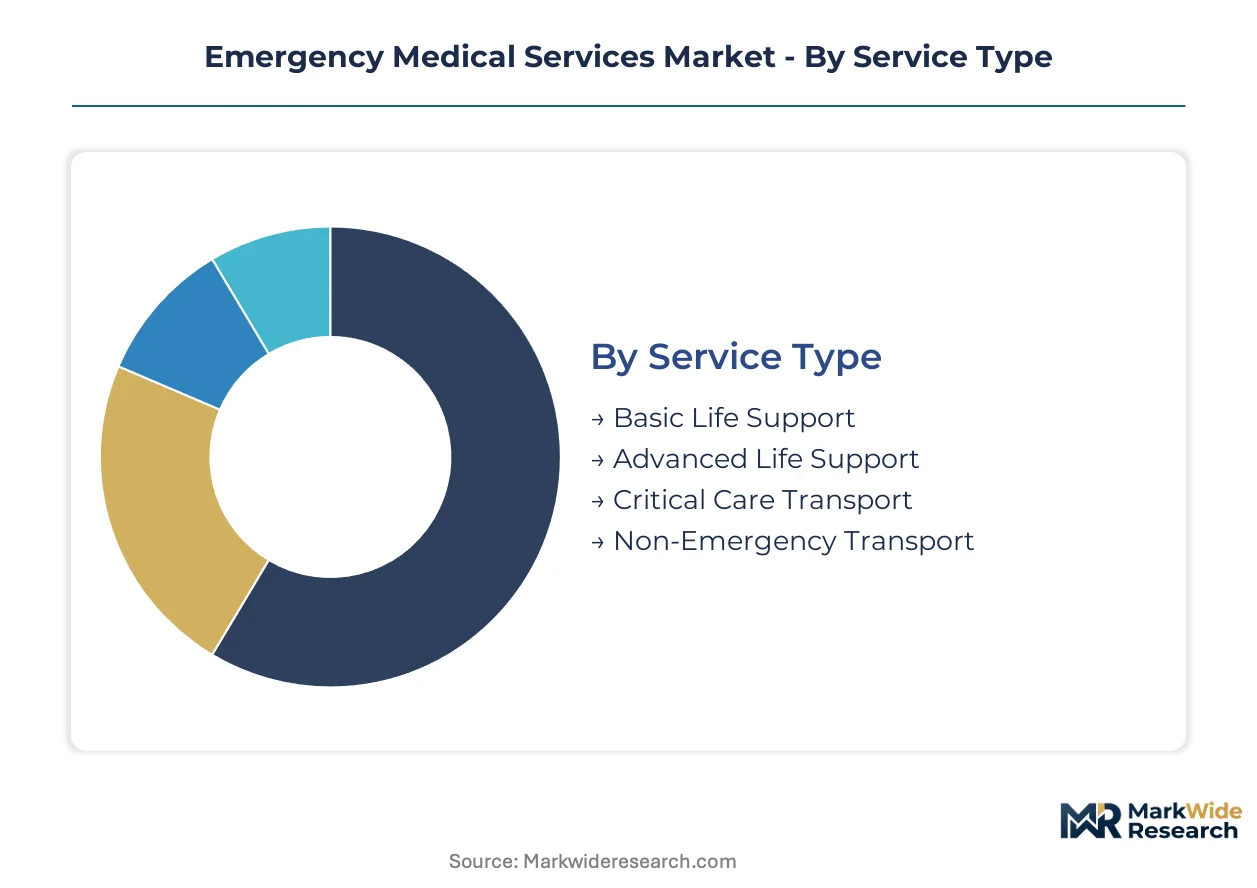
Emergency medical services segmentation reveals distinct procurement patterns across service tiers and response modalities. Equipment specifications, reimbursement rates, and regulatory requirements vary sharply between basic transport and critical care missions.
Service Type:
Supply concentration clusters around Advanced Life Support and Critical Care Transport as hospital outsourcing drives premium equipment procurement.
- Basic Life Support:Non-invasive interventions including oxygen administration, basic airway management, and automated external defibrillation. Demand concentrates in municipal fleets across rural counties where paramedic scope-of-practice restrictions limit procedure authorization.
- Advanced Life Support:Paramedic-administered medications, invasive airways, and cardiac monitoring with biphasic defibrillation capability. Urban hospital systems in the United States expand outsourced ALS contracts to reduce fixed emergency department staffing costs.
- Critical Care Transport:Specialized mobile intensive care for ECMO and ventilator-dependent patients. Supply concentrates with integrated stretcher-monitor ecosystem vendors serving inter-facility transfer networks.
- Non-Emergency Transport:Scheduled medical transfers for dialysis, chemotherapy, and post-acute care. Medicaid reimbursement rates shape fleet composition toward cost-minimized vehicle configurations.
Today's leader: Advanced Life Support. Tomorrow's challenger: Critical Care Transport.
Response Time:
Vehicle deployment economics stratify sharply across time-to-patient thresholds, with sub-5-minute zones commanding specialized rapid-response assets.
- Under 5 Minutes:Motorcycle and rapid-response car deployments in dense urban corridors. Fire department-based EMS in major metropolitan areas maintains this coverage tier through cross-trained personnel.
- 5-10 Minutes:Standard ambulance dispatch for urban and suburban zones. Private healthcare providers dominate this segment through dedicated fleet positioning near hospital clusters.
- 10-20 Minutes:Rural and exurban coverage requiring air ambulance backup. Pilot shortages and helicopter fleet aging constrain capacity expansion in this tier.
- Over 20 Minutes:Frontier and wilderness response relying on search and rescue coordination. Satellite-linked telemetry becomes essential for pre-hospital clinical handoff.
Urban fire-EMS integration commands the Under 5 Minutes tier. Private operators are gaining share fastest in the 5-10 Minutes band.
Vehicle Type:
Platform selection reflects mission profile, with air assets carrying disproportionate capital intensity and regulatory burden.
- Ambulance:Ground-based Type I, II, and III configurations under NHTSA KKK-1822F crashworthiness standards. Modular equipment mounting systems enable rapid reconfiguration between BLS and ALS missions.
- Air Ambulance:Helicopter and fixed-wing platforms for inter-facility critical care and scene response. FAA Part 135 operating certificates and pilot retention challenges limit fleet growth.
- Motorcycle:Rapid-response units navigating congested urban corridors. European and Asian metropolitan systems deploy these for first-responder arrival ahead of ambulance transport.
- Mobile Clinic:Expanded-capability units for mass casualty and disaster response. Government health departments acquire these for surge capacity and rural health screening missions.
Ground ambulances retain volume dominance. Air platforms face the steepest expansion constraints.
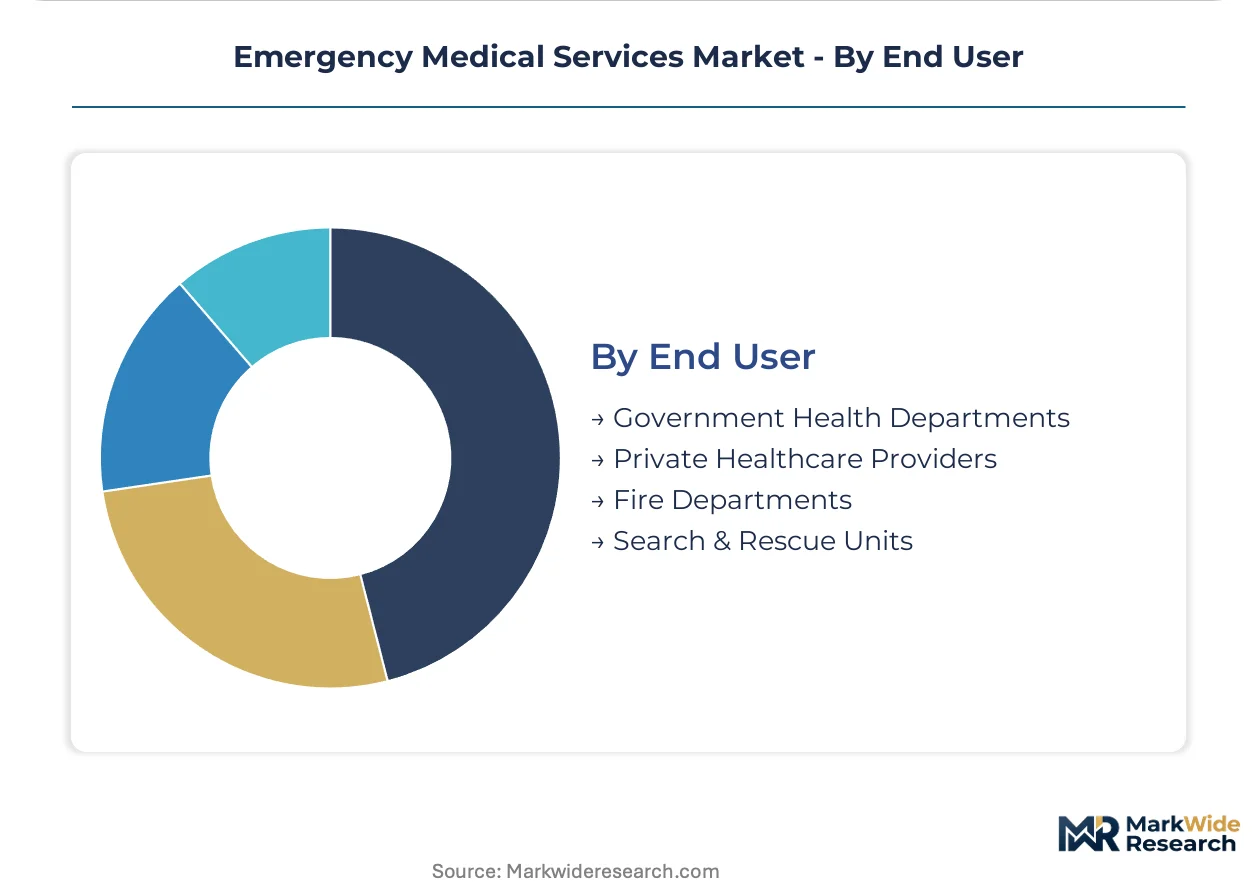
End User:
Procurement authority fragmentation across public and private entities creates divergent equipment specification pathways.
- Government Health Departments:County and state-level EMS authorities setting regional scope-of-practice standards. Medicare and Medicaid reimbursement policies directly influence their fleet investment cycles.
- Private Healthcare Providers:Hospital-owned and contracted ambulance services optimizing for inter-facility revenue. These operators lead adoption of satellite-linked telemetry and automated CPR devices.
- Fire Departments:Cross-trained firefighter-paramedic models dominating urban rapid response. Consolidation of public safety answering points is restructuring their dispatch integration requirements.
- Search & Rescue Units:Specialized wilderness and technical rescue operations requiring extended-care protocols. ISO 13485-certified portable ventilators support their prolonged transport missions.
Private providers drive technology adoption. Fire-EMS integration remains the largest public-sector procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern emergency medical services trace their standardized form to military battlefield medicine innovations of the mid-20th century, with civilian adoption accelerating through hospital-based systems in the United States and Western Europe. Today's procurement patterns reflect divergent healthcare financing models, regulatory frameworks, and infrastructure maturity across major national markets.
United States
Rural hospital closures across the Great Plains and Southeast amplify reliance on advanced life support transport networks bridging geographic care gaps. The FDA's 510(k) premarket notification pathway compresses regulatory timelines for portable defibrillators and patient monitoring devices. Equipment procurement concentrates around Dallas-Fort Worth and Phoenix metropolitan clusters where private ambulance operators maintain large centralized fleets.
Germany
Fire department-based EMS models dominate urban rapid response, with cross-trained personnel covering sub-5-minute arrival zones in Berlin, Hamburg, and Munich. The KBA enforces ambulance design standards under EU Whole Vehicle Type Approval frameworks, while CE marking requirements govern portable medical device certification. Manufacturing clusters in Baden-Württemberg produce ISO 13485-certified ventilators for domestic and export markets.
Japan
Aging demographics in rural prefectures drive demand for inter-facility critical care transport as local hospitals reduce emergency capabilities. METI coordinates disaster medical response standardization, including mobile clinic deployment protocols for earthquake and tsunami scenarios. Tokyo and Osaka metropolitan fire departments operate integrated dispatch centers linking ground ambulances with helicopter assets.
United Kingdom
NHS ambulance trusts face consolidation pressure as regional commissioning groups merge procurement authority across England. The MHRA governs medical device registration under retained EU MDR provisions, with post-Brexit divergence emerging in software-as-a-medical-device validation. London's air ambulance network serves as the primary critical care transport model replicated in Manchester and Birmingham corridors.
India
Highway trauma corridors connecting Delhi, Mumbai, and Bangalore drive demand for basic and advanced life support fleets as private hospital chains expand pre-hospital networks. CDSCO regulates portable defibrillator and patient monitor imports, with domestic manufacturing incentives under PLI schemes targeting ambulance body fabrication. State-level EMS offices in Maharashtra and Tamil Nadu implement divergent paramedic scope-of-practice standards.
Emergency Medical Services Market Key Industry Players
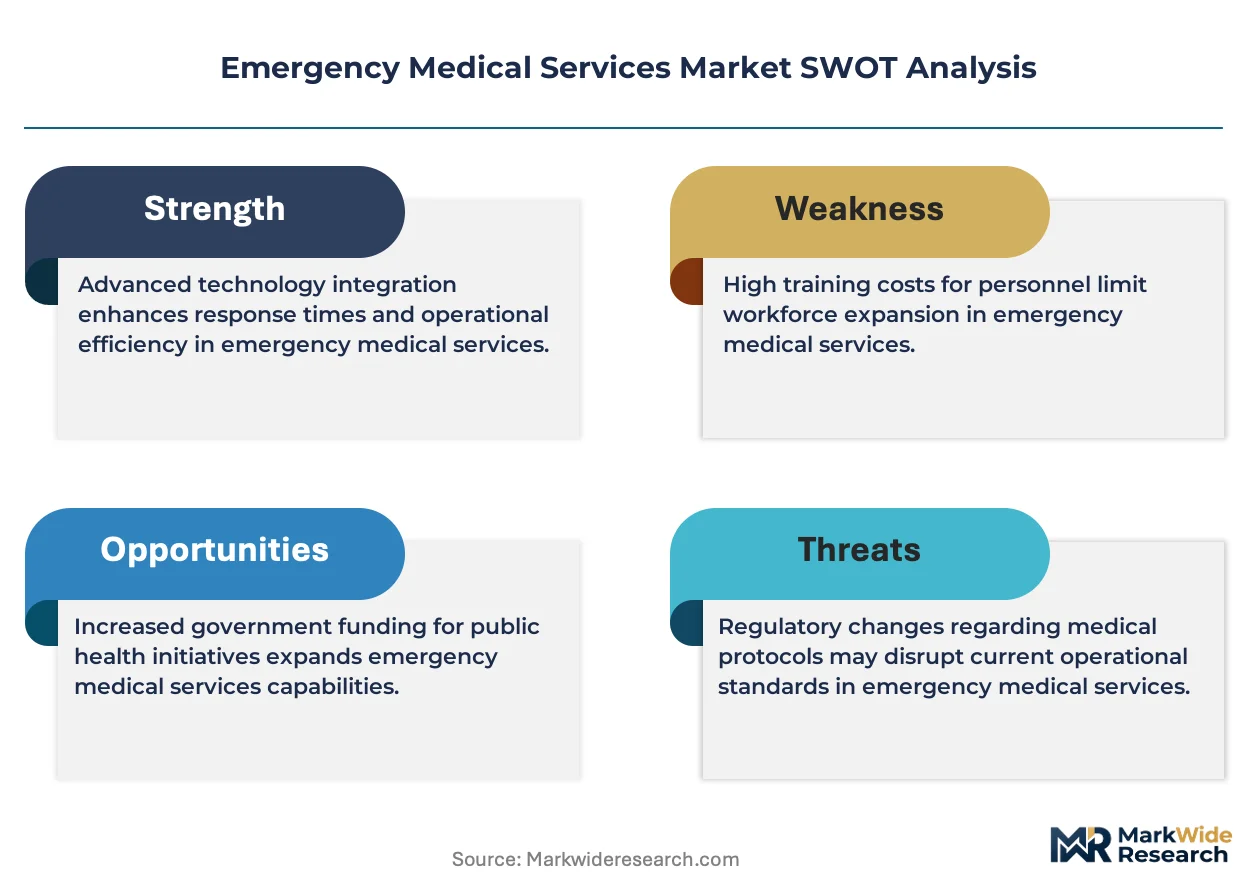
The competitive structure tilts toward diversified medical technology conglomerates with established hospital supply relationships. Three to five multinational corporations capture dominant share in defibrillation, patient monitoring, and emergency ventilation segments, while specialized resuscitation device manufacturers occupy niche positions in automated CPR and temperature management. Two strategic archetypes prevail: integrated critical care transport ecosystem vendors and standalone emergency device specialists. Competitive dynamics center on hospital outsourcing contract capture and modular platform architectures that enable rapid fleet reconfiguration.
Among diversified healthcare technology groups, GE Healthcare and Philips Healthcare exemplify the integrated device-and-software archetype spanning diagnostic imaging through emergency care workflows. Medtronic plc occupies a position in therapeutic device segments adjacent to acute cardiac intervention. Stryker Corporation represents the critical care transport ecosystem approach through stretcher-monitor integration. ZOLL Medical Corporation sits within the resuscitation specialist tier focused on mechanical compression and temperature management technologies. Cardinal Health, Inc. and McKesson Corporation anchor the medical distribution and supply chain services vector, while BD exemplifies the medication delivery and infection prevention archetype in emergency settings.
| Leading Market Players |
|---|
| GE Healthcare |
| Medtronic plc |
| Stryker Corporation |
| Philips Healthcare |
| Cardinal Health, Inc. |
| McKesson Corporation |
| BD |
| ZOLL Medical Corporation |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up ambulance fleet operators now dominate municipal contract bidding across the United States, concentrating procurement leverage while compressing equipment margins through multi-year service agreements that bundle vehicle, device, and maintenance costs into single negotiated rates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs emergency medical equipment procurement, with ISO 13485-certified ventilators and FDA-cleared defibrillators commanding substantial premiums over uncertified alternatives. Price differentiation hinges on regulatory clearance tier and after-sales service bundling, particularly telemetry integration and fleet-wide training programs. Cost compression in economy-tier basic life support fleets is intensifying because Medicaid reimbursement rate stagnation forces municipal operators toward lowest-compliant specifications. Private hospital networks exhibit least price sensitivity, prioritizing interoperability with existing electronic health record systems.
Supply Chain Analysis
Lithium-ion battery cell supply rests on South Korean and Japanese specialty chemical producers, with semiconductor fabrication for patient monitoring chipsets concentrated in Taiwan and South Korea. Raw material dependencies span medical-grade polymers for device housings, precision sensors for vital sign acquisition, and rare earth elements for defibrillator capacitor assemblies. Single-source vulnerability in satellite telemetry modem supply creates exposure to aerospace component allocation disruptions. Distribution runs through group purchasing organizations serving hospital networks and direct OEM relationships with large private ambulance operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as hospital outsourcing accelerates demand for integrated critical care transport ecosystems with seamless electronic health record connectivity.
For Market Incumbents: Deploy modular platform architectures to defend against standalone device specialists encroaching on ambulance fleet contracts. Deepen backward integration into patient monitoring software development to capture recurring telemetry subscription revenue. Counter paramedic workforce attrition through automated CPR device penetration that reduces labor intensity per transport. For New Entrants and Emerging Players: Fire department-based EMS authorities in Midwestern and Southeastern states represent the most penetrable procurement channel as public safety answering point consolidation creates integration friction with legacy vendors. Target automated CPR device white space in basic life support fleets where mechanical compression technology remains underdeployed. Pursue software-as-a-medical-device pathways for AI-enabled dispatch algorithms ahead of tightened FDA validation requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among resuscitation device specialists lacking stretcher-monitor ecosystem integration. Long-term viability hinges on hospital outsourcing contract renewal rates and CMS reimbursement parity adjustments between ground and air transport. Watch FAA Part 135 operating certificate issuance velocity as the signal indicating air ambulance capacity expansion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker Corporation leverages integrated stretcher-monitor ecosystems to capture inter-facility transfer contracts. |
| FDA 510(k) Submission | Premarket notification pathway acceleration compresses regulatory timelines for portable defibrillator deployment. |
| Software Companion Development | Satellite-linked telemetry integration enables real-time vital sign transmission to receiving hospitals. |
| CE Marking Pathway | EU MDR provisions govern medical device registration for European ambulance fleet procurement. |
| Reimbursement Strategy | CMS rate adjustments directly influence fleet investment cycles and service area coverage decisions. |
Research Approach
Multiple input streams — ambulance fleet operator interviews, hospital procurement committee discussions, and biomedical engineer consultations — were reconciled against secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, and NHTSA KKK-1822F compliance records. Bottom-up equipment shipment data from ISO 13485-certified manufacturers was triangulated with top-down healthcare expenditure estimates across municipal, private, and fire department end-user segments.
Historical volume trajectories were cross-referenced against panel input from GPO contracts managers and state EMS office regulators to anchor growth assumptions across the analysis window. Segmentation modeling incorporated service type, vehicle platform, response time tier, and end-user procurement authority. CAGRs were derived from equipment refresh cycle analysis and hospital outsourcing contract velocity, with specific inputs from air ambulance pilot shortage projections and rural hospital closure geographic clustering.
Revisions become necessary when FAA Part 135 regulatory changes, CMS reimbursement parity adjustments, or paramedic scope-of-practice standardization efforts materialize differently than baseline assumptions. Forecasts reflect documented expectations regarding FDA software-as-a-medical-device framework evolution and satellite telemetry bandwidth cost trajectories. A small set of named triggers — pilot retention rates, Medicaid rate negotiations, and ISO 13485 audit backlogs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
US Hospital Emergency Department Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Global Ambulance Services Market