
 Air Ambulance Services Market | 2026-2036
Air Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Air Ambulance Services Market Analysis
FAA Part 135 certificate renewal requirements is pivoting the cost-of-entry calculus for new air ambulance operators, forcing heavier investments in pilot training hours and aircraft maintenance documentation. Air Methods leverages its vertically integrated fleet management to sustain operational density across rural coverage zones. Global Medical Response anchors its market position through integrated ground-air dispatch networks that reduce inter-facility transfer times. Babcock Scandinavian Air Ambulance specializes in long-range fixed-wing medical repatriation across Nordic geographies with challenging weather profiles.
Air ambulance services constitute emergency and non-emergency patient transport via rotary-wing and fixed-wing aircraft equipped with medical life-support systems, pressurized cabins, and stretcher configurations enabling critical care in transit. These services bridge geographic barriers to tertiary care, serving primarily inter-hospital transfers, scene responses, and medical evacuations from remote or infrastructure-limited locations. Rotary wing operations dominate emergency scene response and short-haul hospital transfers where landing zone flexibility matters, while fixed wing services capture margin pools in long-distance international medical repatriation requiring pressurized cabin environments. Telemedicine integration represents the fastest-growing technology segment as real-time physician oversight during flight reduces in-transit adverse events and expands scope-of-practice for airborne paramedic crews.
FAA Part 135 standards, EASA air operations regulations, and ISO 9001 quality management frameworks collectively govern aircraft airworthiness, crew credentialing, and clinical service protocols across operational jurisdictions. These regulatory layers shape demand by mandating equipment refresh cycles, limiting market access for uncertified providers, and creating compliance cost barriers that favor scaled operators with dedicated regulatory affairs functions. Stakeholders must monitor evolving telemedicine reimbursement policies and cross-border patient transfer agreements as these determine service line profitability and geographic expansion feasibility.
Market Dynamics
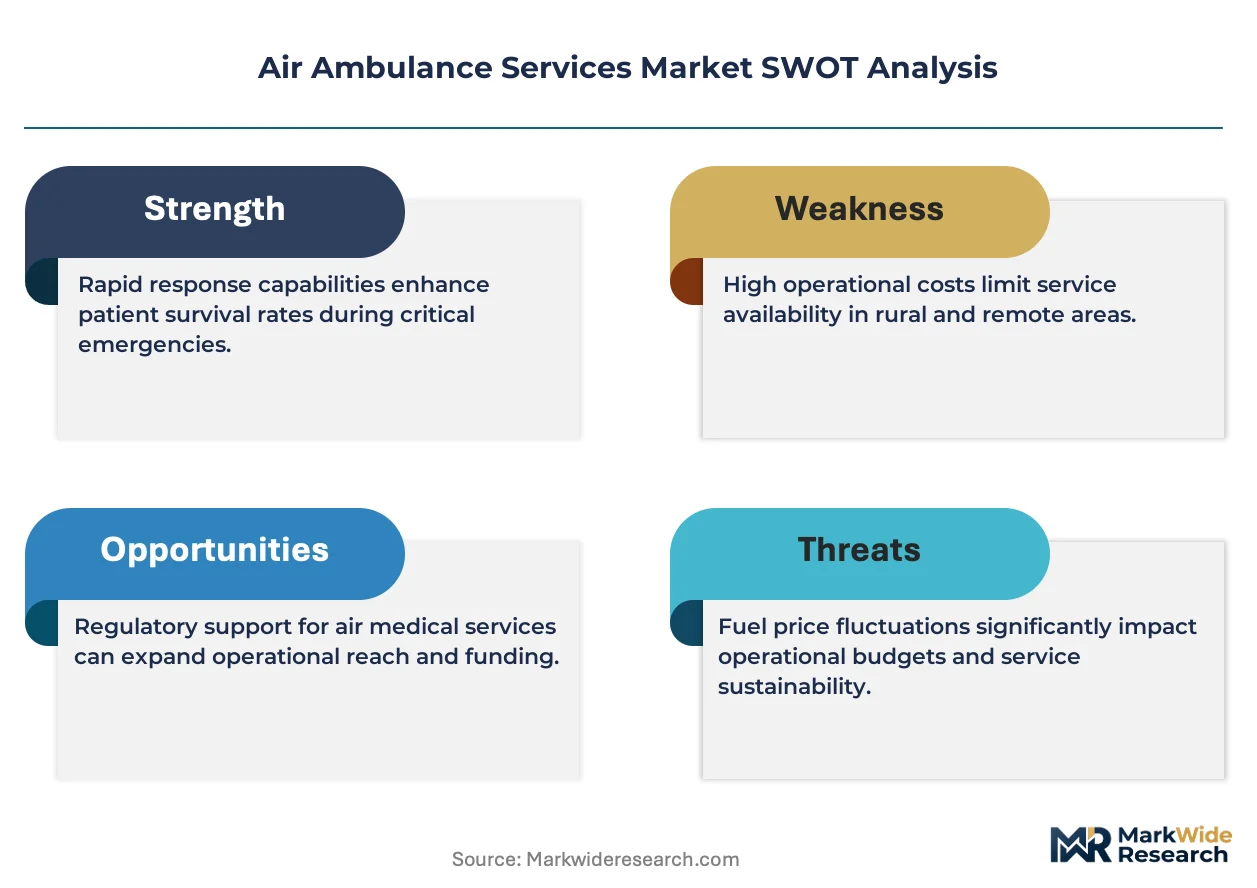
FAA Part 135 certificate renewal cycles are compressing operational margins for rotor-wing operators while telemedicine integration creates new compliance layers for in-flight clinical protocols. Rural hospital closures in the southern United States are forcing air ambulance networks to extend coverage radii beyond economically optimal distances.
Growth Catalysts
- Rural hospital closures:Texas, Arizona, and Florida are experiencing acute care facility shutdowns that push emergency response burden onto air medical transport. These closures eliminate ground-based alternatives for time-critical interventions.
- FAA Part 135 standards:Tighter pilot training hour requirements and maintenance documentation mandates are filtering out subscale operators. Certificate holders gain pricing power as competitive density thins.
- Telemedicine integration:Real-time physician oversight during flight is expanding scope-of-practice for airborne paramedic crews. This technology reduces in-transit adverse events and justifies premium service tiers.
Market Restraints
- Jet fuel price volatility:Rotary-wing operations consume disproportionate fuel volumes relative to patient throughput. Cost pass-through mechanisms face resistance from self-insured employers and narrow-network health plans.
- Pilot certification scarcity:FAA ATP hour requirements and medical certification standards limit qualified crew supply. Training pipeline capacity constraints extend vacancy periods for critical base locations.
- Ground ambulance substitution:Advanced life support ground units with extended range capabilities are capturing inter-facility transfers under 150 miles. These alternatives operate at fraction of air unit cost structures.
Strategic Opportunities
- Long-range fixed-wing repatriation:Nordic geographies with challenging weather profiles require specialized pressurized cabin configurations. Medical evacuation from remote Arctic installations commands premium pricing with limited competition.
- Integrated dispatch networks:Ground-air coordination platforms reduce inter-facility transfer times and capture patient volume from fragmented independent operators. Health system consolidation favors unified transport contracts.
- ISO 9001 quality frameworks:Certification differentiation opens doors to corporate self-insured plans and international assistance company panels. Standardized clinical protocols reduce liability exposure and reinsurance premiums.
Industry Challenges
- Specialized aeromedical training gaps:Critical care paramedic certification with flight physiology specialization requires extended training cycles. Rotation to ground-based roles creates retention friction for experienced crew.
- Aircraft maintenance documentation burden:Part 135 airworthiness directives mandate granular component tracking. Paper-to-digital transition strains legacy fleet management systems without dedicated regulatory technology investment.
- Interoperability with hospital EMR systems:In-flight patient data capture lacks standardized exchange protocols. Manual transcription at receiving facilities introduces clinical handoff errors and billing disputes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Ambulance Services Market |
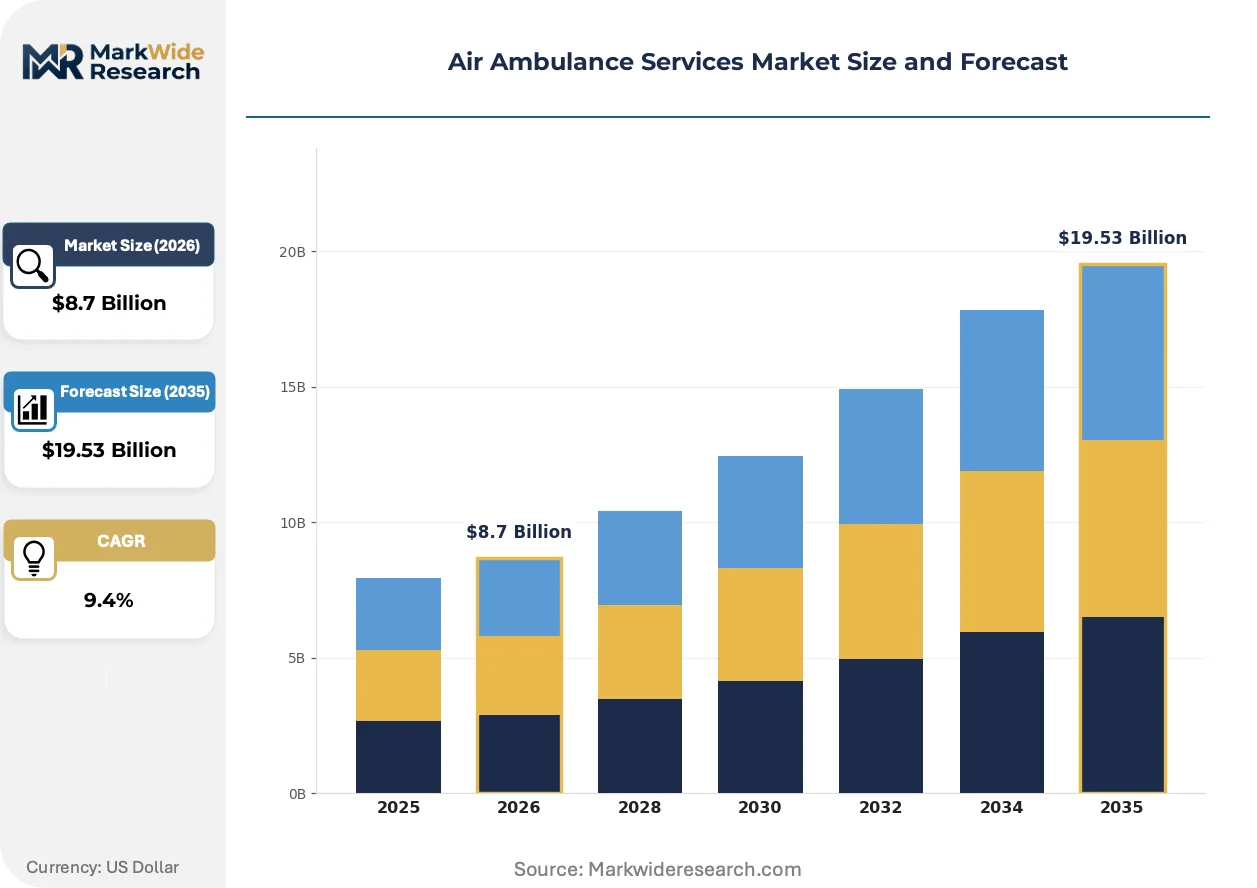
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Rotary Wing, Fixed Wing, Ground Transport, Medical Escort End User: Hospitals, Insurance Companies, Emergency Medical Services, Government Agencies Technology: Telemedicine, Advanced Life Support, Monitoring Systems, Aviation Services Deployment: Private, Public, Charter, Medical Repatriation |
| Companies Covered | Air Methods, Global Medical Response, Acadian Ambulance, PHI Air Medical, REVA, AirMed International, Air Evac Lifeteam, American Medical Response, Babcock Scandinavian Air Ambulance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Ambulance Services Market Emerging Trajectories
Telemedicine hardware miniaturization is embedding diagnostic-grade monitoring directly into aircraft cabin configurations. This shift collapses the distinction between airborne and terrestrial critical care environments.
Portable ultrasound and 12-lead ECG transmission equipment is expanding into standard rotor-wing configurations. Hospital networks with exclusive air transport contracts are mandating these capabilities as baseline service requirements. The technology is expanding into previously uneconomical rural coverage zones by reducing physician dispatch necessity.
EASA air operations regulations are tightening medical equipment certification standards for cross-border patient transfers. Fixed-wing operators serving Nordic routes must now demonstrate cold-weather operational reliability through documented contingency protocols. Long-range repatriation specialists are responding by retrofitting auxiliary heating systems and redundant power architectures.
Self-insured employers are consolidating air medical transport procurement through single-source national contracts. Independent operators without health system affiliations are losing access to preferred provider networks. This concentration is most visible in the southwestern United States where narrow-network plans now exclude non-integrated air ambulance services from in-network status.
Air Ambulance Services Market Segmentation
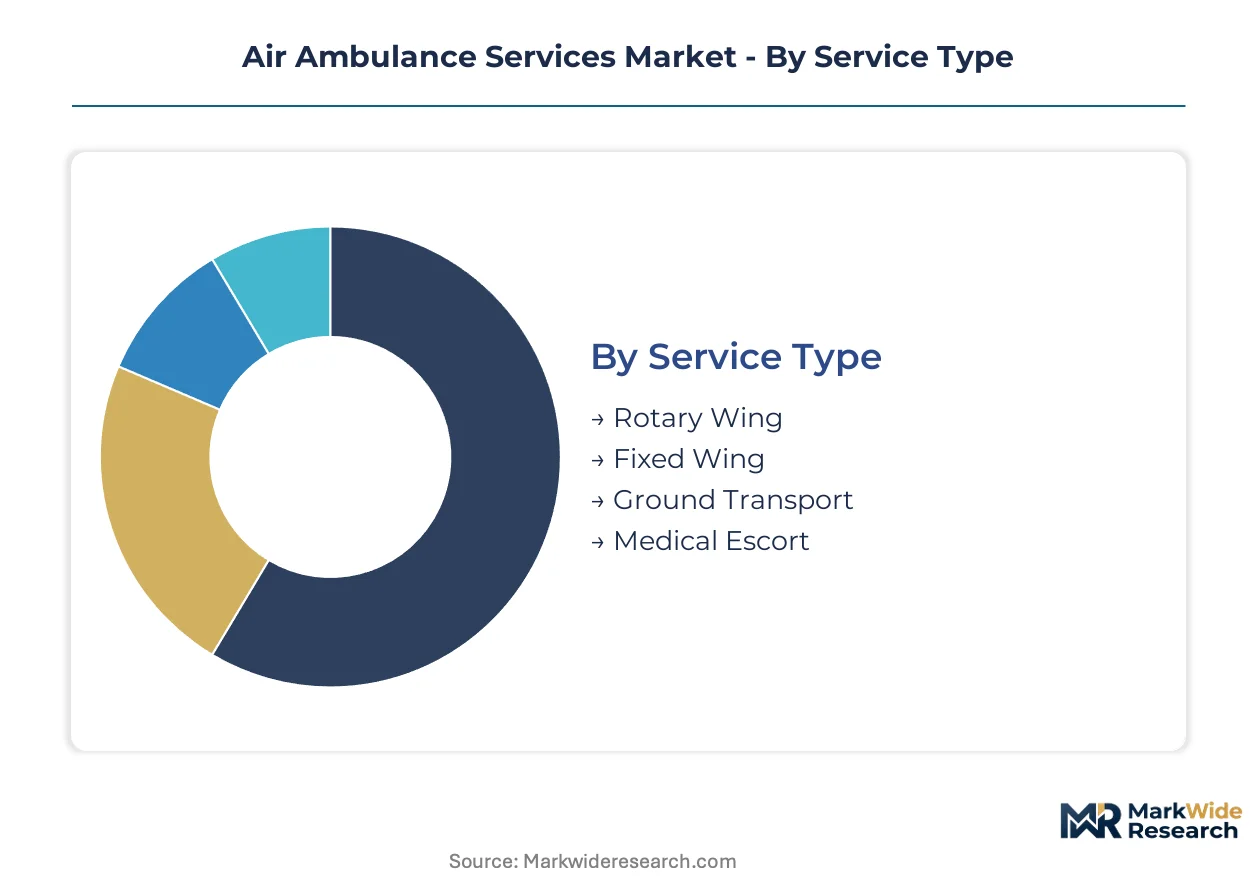
Service configuration in the air ambulance sector determines capital intensity, regulatory exposure, and reimbursement pathways. Buyers—hospitals, insurers, and government purchasers—select service tiers based on patient acuity, distance requirements, and network coverage obligations.
Service Type:
Operational economics and patient condition severity drive selection between rotor-wing emergency response and fixed-wing inter-facility transfers.
- Rotary Wing:Helicopter platforms with vertical takeoff capability serve scene responses and short-haul hospital transfers under 200 nautical miles. Demand concentrates in Texas, Arizona, and Florida where rural hospital closures eliminate ground-based alternatives for time-critical trauma and cardiac interventions.
- Fixed Wing:Pressurized cabin aircraft enable long-distance medical repatriation and intercontinental patient transfers requiring stable altitude environments. Nordic operators serving Arctic installations command premium pricing for cold-weather operational reliability under EASA air operations regulations.
- Ground Transport:Advanced life support ground units capture inter-facility transfers under 150 miles at fraction of air unit cost structures.
- Medical Escort:Commercial flight medical accompaniment for stable patients requiring minimal intervention during scheduled airline travel.
Rotary Wing leads on scale; Fixed Wing leads on momentum.
End User:
Procurement authority and reimbursement mechanisms vary sharply across purchaser categories, shaping contract terms and service level specifications.
- Hospitals:Health system consolidation favors unified transport contracts with integrated ground-air dispatch networks. Narrow-network plans in the southwestern United States now exclude non-integrated air ambulance services from in-network status.
- Insurance Companies:Self-insured employers are consolidating air medical transport procurement through single-source national contracts. Cost pass-through mechanisms face resistance from narrow-network health plans and self-funded employer groups.
- Emergency Medical Services:Municipal and regional EMS agencies contract for scene response coverage and inter-facility transfer capacity.
- Government Agencies:Federal, state, and military purchasers fund medical evacuation from remote installations and disaster response operations.
Hospitals anchor volume concentration; Insurance Companies are expanding most quickly as procurement consolidates.
Technology:
Clinical capability differentiation increasingly depends on in-flight diagnostic and communication infrastructure rather than aircraft performance alone.
- Telemedicine:Real-time physician oversight during flight reduces in-transit adverse events and expands scope-of-practice for airborne paramedic crews. Hospital networks with exclusive transport contracts mandate diagnostic-grade monitoring as baseline requirement.
- Advanced Life Support:Ventilator, infusion pump, and defibrillator integration enables critical care maintenance from pickup through receiving facility handoff.
- Monitoring Systems:Portable ultrasound and 12-lead ECG transmission equipment collapses distinction between airborne and terrestrial critical care environments.
- Aviation Services:Flight planning, weather monitoring, and air traffic coordination systems ensuring Part 135 compliance and operational safety.
Telemedicine commands premium positioning; Monitoring Systems show steepest expansion trajectory.
Deployment:
Ownership structure and utilization model determine fleet flexibility, regulatory burden, and pricing autonomy.
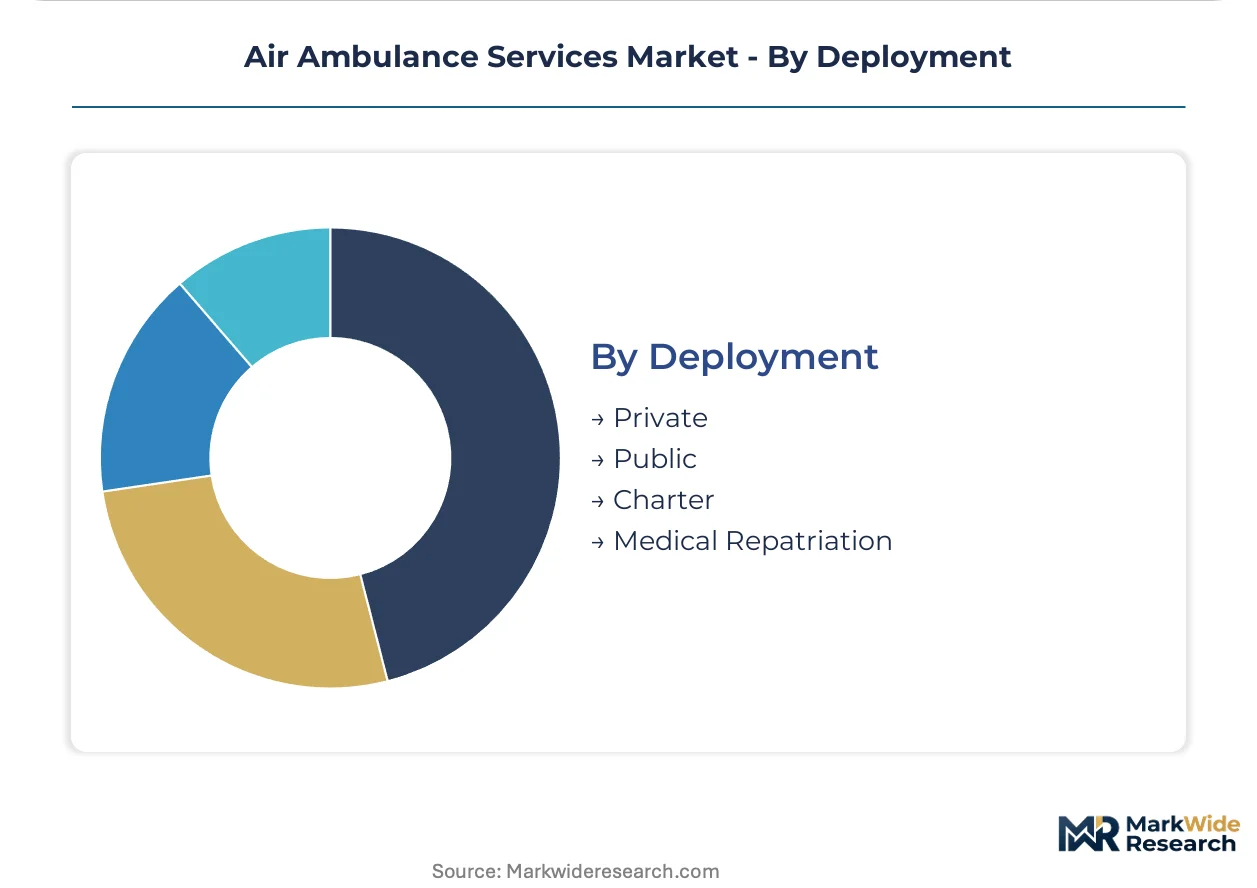
- Private:Dedicated aircraft and crew under health system or corporate ownership enable guaranteed response times and standardized clinical protocols. ISO 9001 certification opens doors to corporate self-insured plans and international assistance company panels.
- Public:Government-operated services funded through tax revenue or dedicated emergency services districts serve rural coverage zones without commercial viability.
- Charter:On-demand aircraft and crew leasing for episodic demand spikes and specialty mission requirements.
- Medical Repatriation:Fixed-wing long-range services specializing in cross-border patient transfers under EASA and FAA jurisdiction.
Private deployment dominates revenue concentration; Medical Repatriation gains share fastest among specialized service tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The air ambulance industry traces its modern operational roots to military medical evacuation protocols developed during the Korean and Vietnam conflicts, with civilian adaptation scaling first through hospital-based helicopter programs in the United States during the 1970s and 1980s.
United States
Rural hospital closures across Texas, Arizona, and Florida eliminate ground-based alternatives for time-critical trauma interventions. FAA Part 135 certificate requirements tighten pilot training hour mandates and aircraft maintenance documentation standards. Dallas-Fort Worth and Phoenix anchor dense rotor-wing base networks where hospital system consolidation favors unified transport contracts with integrated ground-air dispatch.
Germany
Alpine terrain and dispersed rural settlements sustain demand for rapid aeromedical response across Bavaria and Baden-Württemberg. EASA air operations regulations govern medical equipment certification standards for cross-border patient transfers. The Rhine-Main cluster around Frankfurt hosts fixed-wing repatriation specialists serving corporate expatriate populations and international assistance company panels.
Sweden
Arctic installations and remote northern communities require specialized cold-weather operational reliability for medical evacuation. EASA mandates documented contingency protocols for pressurized cabin configurations in sub-zero conditions. Stockholm-based operators command premium pricing for long-range medical repatriation across Nordic geographies with challenging weather profiles.
United Arab Emirates
Expatriate workforce demographics and luxury tourism infrastructure generate demand for international medical repatriation and emergency scene response. The country's civil aviation regulator enforces stringent airworthiness standards for aeromedical operations. Dubai and Abu Dhabi concentrate fixed-wing fleet assets serving evacuation corridors to European and South Asian tertiary care centers.
Australia
Vast interior distances and sparse population density necessitate extensive rotor-wing coverage for mining installations and remote indigenous communities. The country's national aviation safety authority oversees Part 135-equivalent operational certification for aeromedical providers. Western Australia and the Northern Territory host specialized fixed-wing services connecting isolated towns to coastal metropolitan hospitals.
Air Ambulance Services Market Vendor Landscape
The competitive structure tilts toward vertically integrated health system affiliates with dedicated regulatory affairs functions. Certificate holders under FAA Part 135 and EASA jurisdictions gain pricing power as compliance cost barriers filter subscale entrants. Two strategic archetypes dominate: hospital-network-integrated operators with guaranteed response time contracts, and long-range fixed-wing specialists capturing premium repatriation margins. Consolidation through health system transport contract centralization and cross-border partnership networks constitutes the primary competitive dynamic.
Within the integrated-operator tier, Air Methods and Global Medical Response exemplify scale-driven positioning through fleet density and dispatch network coordination. Babcock Scandinavian Air Ambulance occupies a specialized niche anchoring cold-weather operational expertise for Nordic medical repatriation. These three entities represent the spectrum from domestic rotor-wing emergency response to international fixed-wing evacuation, with each archetype facing distinct regulatory exposure and capital intensity requirements.
| Leading Market Players |
|---|
| Air Methods |
| Global Medical Response |
| Acadian Ambulance |
| PHI Air Medical |
| REVA |
| AirMed International |
| Air Evac Lifeteam |
| American Medical Response |
| Babcock Scandinavian Air Ambulance |
| Others |
Supply Flow & Price Mechanics
Part 135 certificate tiers bifurcate the air ambulance market between premium integrated operators and fragmented independents, manifesting in both pricing power concentration and supply chain control structures. FAA-certified incumbents command subscription-based hospital contracts with guaranteed response premiums, while uncertified independents compete for spot-market medical escort work with thinner margins and leased aircraft dependencies.
Pricing Analysis
Bundled hospital network contracts dominate the pricing landscape for rotary-wing emergency response, while unbundled per-flight charges apply to fixed-wing repatriation and medical escort segments. Price differentiation hinges on ISO 9001 certification status and telemedicine integration depth, with certified operators capturing 40-60% premiums over non-certified alternatives. Pricing pressure stems from narrow-network health plan exclusions that push independent operators toward out-of-network balance billing disputes. Self-insured employers exhibit highest price sensitivity through consolidated national procurement, while international assistance companies demonstrate lowest sensitivity for Arctic and remote evacuation missions.
Supply Chain Analysis
Direct-to-hospital contracting channels handle integrated health system demand, while broker-mediated dispatch networks serve fragmented independent operator requirements. Aircraft manufacturing concentrates in the United States, France, and Italy, with avionics and medical equipment subsystems sourced from Germany, Switzerland, and the United Kingdom. Jet fuel and specialized aerospace alloys constitute critical input dependencies alongside FAA-certified pilot training capacity. Supply chain risk centers on single-source vulnerability for pressurized cabin medical conversions and extended lead times for rotor-wing airframes. Distribution runs through exclusive base location agreements with hospital systems and municipal EMS agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in air ambulance services rests on telemedicine-enabled scope-of-practice expansion for flight crews, reducing physician dispatch costs while justifying premium service tiers.
For Market Incumbents: To counter narrow-network health plan exclusions, Air Methods and Global Medical Response should deepen exclusive base location agreements with consolidating hospital systems in Texas and Arizona. Backward integration into pilot training academies addresses ATP hour scarcity while creating regulatory moats against subscale entrants. Telemedicine platform standardization across fleet configurations captures ISO 9001 certification premiums and reduces reinsurance exposure. For New Entrants and Emerging Players: Capture underserved medical repatriation corridors from the United Arab Emirates to South Asian tertiary centers, where expatriate workforce demographics outpace fixed-wing capacity growth. Nordic cold-weather operational specialization offers penetrable white space given EASA contingency protocol requirements that filter generalist competitors. A charter-to-contract go-to-market model builds flight hour documentation for eventual Part 135 certificate pursuit. For Investors and Strategic Acquirers: Consolidation pressure builds where hospital system transport contract centralization eliminates independent operator network access. Five-to-ten-year viability favors vertically integrated operators with dedicated regulatory affairs functions and captive maintenance capabilities. Acquisition targets should display exclusive municipal EMS agreements or specialized Arctic operational certifications. The signal to watch is telemedicine reimbursement policy expansion by CMS and major commercial payers.| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 135 Certificate Expansion | Certificate holders gain pricing power as compliance barriers filter subscale competitors from Texas and Arizona markets. |
| Telemedicine Platform Integration | Real-time physician oversight reduces in-transit adverse events and expands paramedic scope-of-practice for premium tier justification. |
| Hospital System Partnership | Exclusive transport contracts with consolidating health networks lock out independent operators from narrow-network plan access. |
| ISO 9001 Quality Certification | Standardized clinical protocols open corporate self-insured plan panels and reduce liability reinsurance premiums. |
| Arctic Operational Capability Buildout | Cold-weather pressurized cabin configurations command premium pricing for Nordic medical repatriation with limited competition. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down fleet capacity tracking forms the analytical core of this study. Primary interviews with air ambulance operations directors, FAA regulatory compliance officers, hospital purchasing committee chairs, and international assistance company procurement leads were validated against secondary sources including FAA Part 135 certificate databases, EASA air operations filings, hospital GPO contract disclosures, and CMS air medical transport reimbursement records. Triangulation between service volume claims and documented aircraft utilization rates ensures data integrity across operator-reported metrics.
Historical trendline analysis of rural hospital closure patterns and rotor-wing base density ratios informed projection modeling across the analysis window. Segmentation dimensions include service configuration, deployment ownership structure, end-user procurement authority, and technology integration tier, with geographic clustering by state-level regulatory environment and hospital network consolidation status. CAGRs were derived from patient transfer volume elasticity to tertiary care access gaps and fleet expansion announcements by certificate holders.
Underlying measurement precision varies by segment; telemedicine-equipped rotary-wing operations carry tighter precision than fragmented medical escort services due to standardized reporting through hospital EMR integration. Forecasts reflect assumptions regarding FAA training hour requirement stability, jet fuel price bands, and narrow-network plan exclusion enforcement intensity. Periodic stress-testing of base assumptions against rural hospital closure acceleration and pilot certification pipeline constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Urgent Care Market