
 Emergency Medical Services (EMS) Vehicle Market | 2026-2036
Emergency Medical Services (EMS) Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Medical Services (EMS) Vehicle Market Foresight
Subscription-based fleet telematics and predictive maintenance software is restructuring how EMS operators procure vehicle capabilities, shifting capital expenditure toward operational models. Ford Motor Company leverages its commercial chassis dominance to anchor ambulance upfit partnerships across North American municipalities. Mercedes-Benz AG sustains premium positioning through proprietary emergency vehicle architectures that integrate advanced driver-assistance systems. REV Group specializes in purpose-built ambulance bodies that occupy distinct niches in both public and private service channels.
An emergency medical services vehicle constitutes a road-certified transport platform engineered to patient-bearing specifications, incorporating stretcher mounting systems, oxygen delivery infrastructure, electrical load capacity exceeding 300 amps, and modular interior configurations for clinical intervention during transit. These vehicles serve the primary commercial purpose of reducing time-to-treatment intervals while sustaining patient physiological stability through regulated environmental control. Ambulance configurations command the largest share of current production volume, though electric and hybrid fuel types are gaining fastest as fleet operators confront total cost-of-ownership pressures and municipal decarbonization mandates. Patient transport applications generate recurring revenue streams through dedicated service contracts, while emergency medical response units concentrate margin pools in specialized quick-response vehicle segments.
The National Highway Traffic Safety Administration enforces Federal Motor Vehicle Safety Standards that govern ambulance structural integrity and occupant protection, directly shaping manufacturer design commitments and upfitter certification requirements. The National Fire Protection Association publishes NFPA 1917 standards specifying ambulance construction, testing, and performance criteria that filter into municipal procurement specifications and insurance underwriting. The Environmental Protection Agency tailpipe emissions regulations are forcing powertrain transitions that ripple through chassis supply agreements and upfitter engineering timelines. Stakeholders must monitor how evolving zero-emission mandates interact with the extended duty cycles and rapid-deployment requirements that define emergency vehicle operational profiles.
Market Dynamics
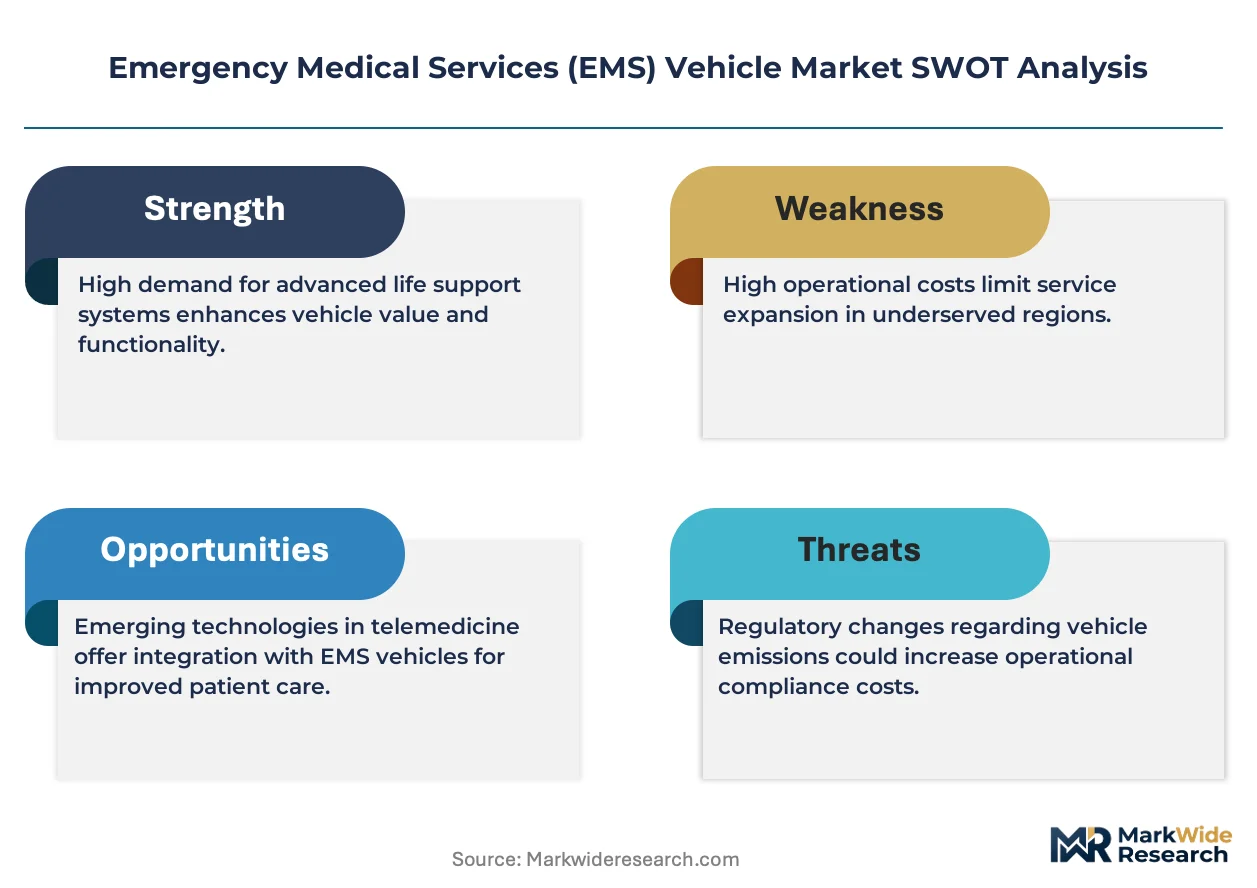
EPA tailpipe emissions regulations and NFPA 1917 ambulance construction standards are compressing powertrain transition timelines while forcing chassis-upfitter coordination that reshapes procurement economics across municipal and hospital-based fleets.
Growth Catalysts
- Zero-emission mandates:Municipal decarbonization targets in Germany, California, and Japan are accelerating electric-hybrid chassis procurement timelines for aging emergency vehicle fleets.
- Telematics integration:Predictive maintenance software is absorbing capital expenditure into operational expenditure models, restructuring how EMS operators contract vehicle capabilities.
- NFPA 1917 standards:Tighter ambulance construction specifications are mandating modular interior configurations that support clinical intervention during transit.
Market Restraints
- Chassis supply concentration:Ford Motor Company's commercial chassis dominance in North America creates single-source vulnerability for upfitter engineering timelines.
- Battery thermal management:Extended duty cycles and rapid-deployment requirements expose electric platforms to performance degradation under emergency load profiles.
- NHTSA structural compliance:Federal Motor Vehicle Safety Standards certification timelines extend 18-24 months, delaying fleet modernization programs.
Strategic Opportunities
- Quick-response vehicle segments:Specialized rapid-deployment units concentrate margin pools outside traditional ambulance configurations.
- Subscription service models:Fleet telematics platforms enable recurring revenue capture through dedicated service contracts rather than discrete vehicle sales.
- Advanced driver-assistance convergence:Integration of emergency-specific ADAS with proprietary vehicle architectures differentiates premium positioning.
Industry Challenges
- Upfitter certification complexity:NFPA 1917 testing requirements and NHTSA structural integrity standards demand parallel engineering tracks that strain smaller body manufacturers.
- Electrical load engineering:Oxygen delivery infrastructure and climate control systems exceeding 300 amps require powertrain redesigns that compress development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Medical Services (EMS) Vehicle Market |
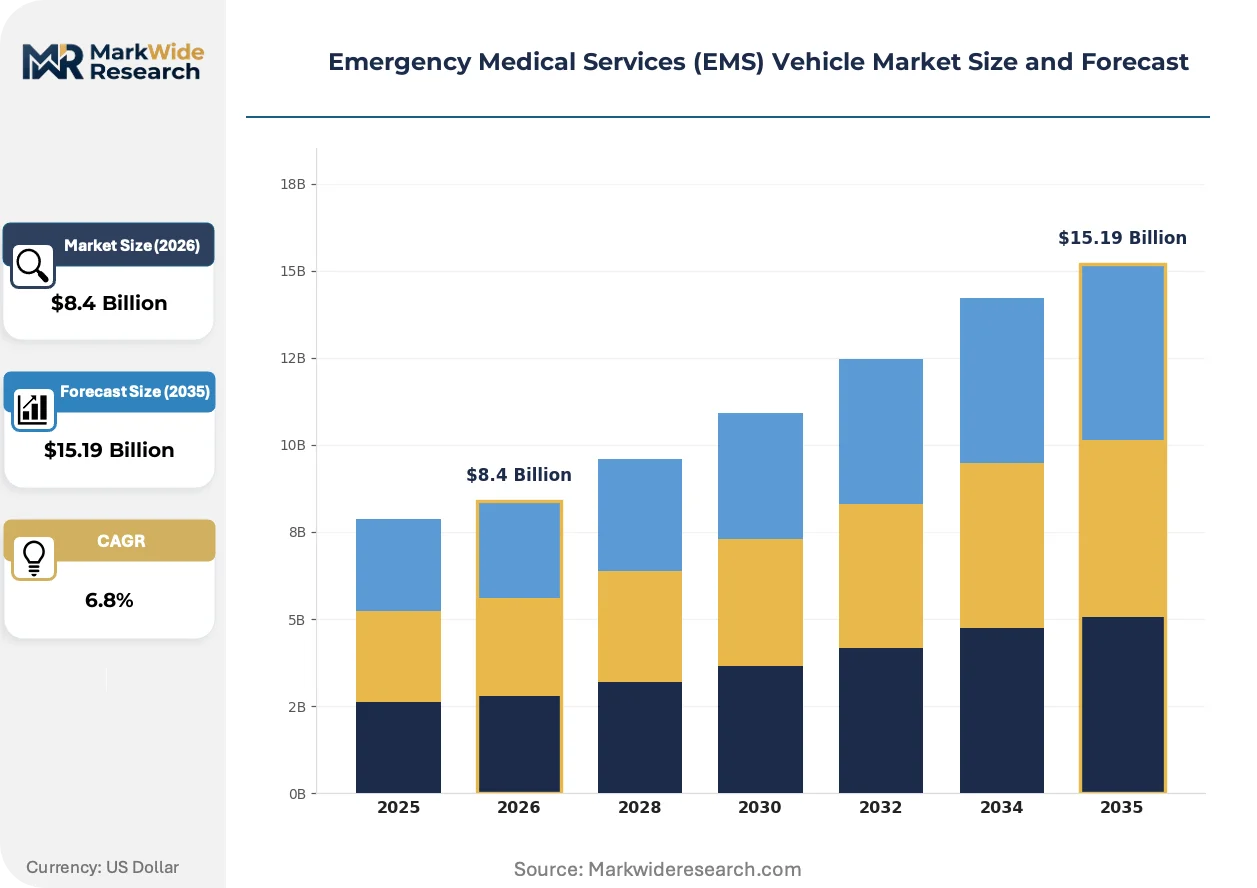
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Ambulance, Fire Rescue, Non-Emergency Medical Transport, Quick Response Vehicle Fuel Type: Diesel, Gasoline, Electric, Hybrid Application: Emergency Medical Response, Patient Transport, Fire Fighting, Rescue Operations Service Type: Public Services, Private Services, Hospital Services, Others |
| Companies Covered | Ford Motor Company, Mercedes-Benz AG, General Motors Company, REV Group, Toyota Motor Corporation, Volkswagen AG, AB Volvo, Braun Industries, Wheeled Coach Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Medical Services (EMS) Vehicle Market Shifts & Advancements
Powertrain electrification is absorbing engineering resources while telematics platforms restructure ownership economics. Regulatory pressure on emissions and safety standards is forcing coordination between chassis suppliers and body upfitters that previously operated independently.
Electric-hybrid fuel types are absorbing capital allocation from municipal procurement offices confronting total cost-of-ownership pressures. Hospital-based fleets in Germany and Japan are adopting these platforms at accelerated rates to meet decarbonization commitments. The technology is absorbing margin compression from battery thermal management requirements while enabling longer service intervals that offset upfront chassis premiums.
EPA emissions regulations are forcing powertrain transitions that ripple through chassis supply agreements and upfitter engineering timelines. The standards compress development cycles for electric platforms that must simultaneously satisfy NFPA 1917 ambulance construction criteria. North American municipalities are responding by consolidating procurement specifications to reduce certification duplication across overlapping federal and state requirements.
Subscription-based fleet capabilities are restructuring how EMS operators acquire vehicle functionality. Municipal fire departments are displacing capital-intensive ownership with operational contracts that bundle telematics, maintenance, and mid-life refurbishment. This shift is most visible in United States metropolitan systems where budget constraints favor predictable expenditure profiles over discrete asset purchases.
Emergency Medical Services (EMS) Vehicle Market Segmentation
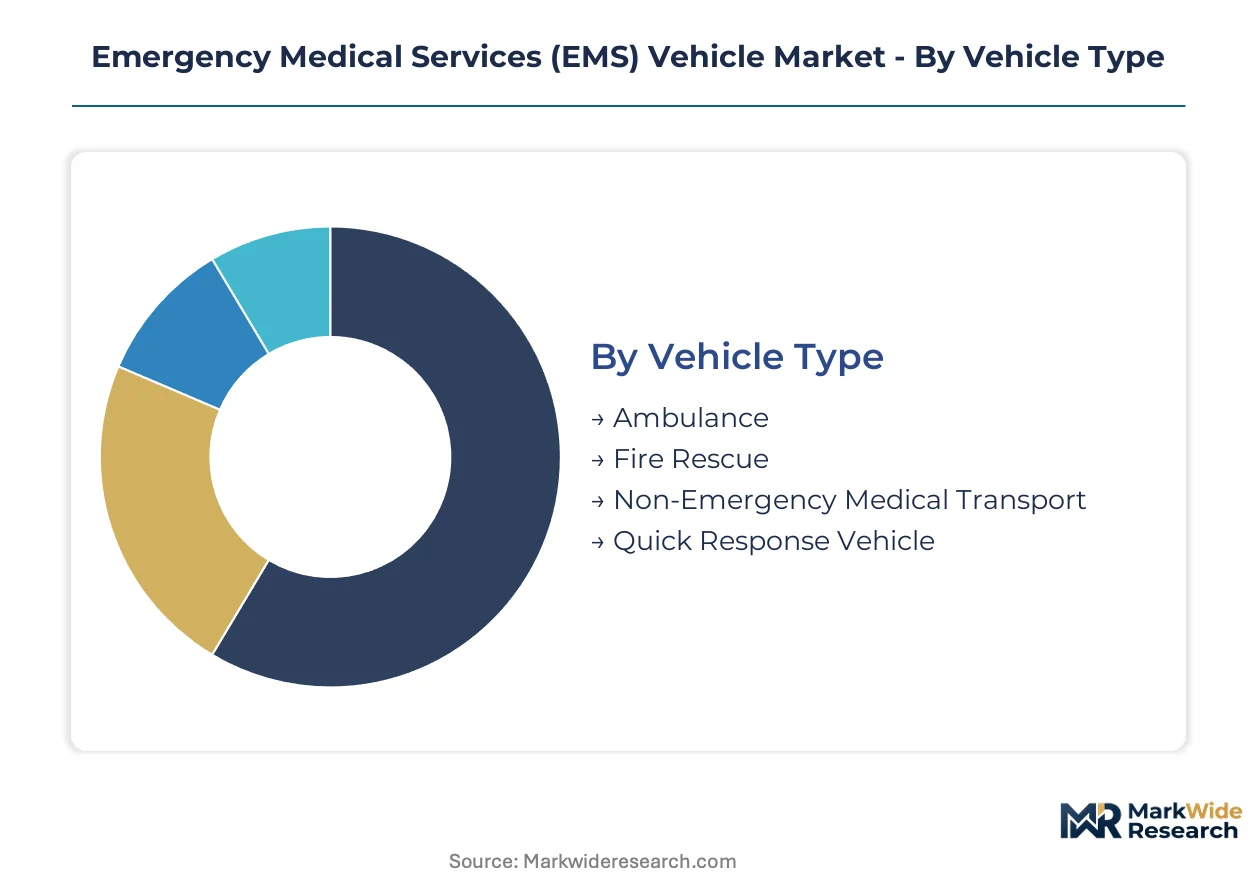
EMS vehicle procurement patterns diverge sharply between high-volume municipal contracts and premium specialized configurations. Understanding where margin pools concentrate across chassis types, fuel technologies, and service models enables targeted positioning for manufacturers and fleet operators.
Vehicle Type:
Ambulance configurations dominate unit volume while quick-response vehicles command premium pricing per chassis.
- Ambulance:Purpose-built patient-bearing platforms incorporate stretcher mounting systems, oxygen delivery infrastructure, and electrical load capacity exceeding 300 amps. Municipal fire departments in the United States and hospital-based fleets in Germany are modernizing aging units under tightening NFPA 1917 specifications.
- Quick Response Vehicle:Compact rapid-deployment units sacrifice patient transport capacity for speed and maneuverability in dense urban corridors. Private emergency services in Japan are expanding procurement of these specialized platforms to reduce time-to-treatment intervals in metropolitan Tokyo and Osaka.
- Fire Rescue:Multi-casualty incident platforms integrate extrication equipment and hazmat containment systems.
- Non-Emergency Medical Transport:Bariatric and wheelchair-accessible configurations serve dialysis and inter-facility transfers with lower electrical load requirements.
Mature deployment sits with Ambulance. Newer deployment is concentrated in Quick Response Vehicle.
Fuel Type:
Powertrain selection now hinges on total cost-of-ownership calculations rather than upfront chassis pricing alone.
- Hybrid:Electric-hybrid architectures balance zero-emission operational modes with extended range for rural response corridors. Municipalities in California are accelerating procurement timelines to meet state decarbonization mandates while preserving rapid-deployment capability.
- Electric:Battery-electric platforms eliminate tailpipe emissions but require thermal management systems for extended duty cycles. Hospital-based fleets in Germany are adopting these units at accelerated rates to satisfy EPA-aligned municipal sustainability commitments.
- Diesel:Compression-ignition powertrains retain dominance in heavy-duty ambulance configurations requiring sustained high electrical loads.
- Gasoline:Spark-ignition engines persist in lighter quick-response and non-emergency transport applications where payload demands remain modest.
Established fleet composition favors Diesel. Steepest expansion trajectory belongs to Hybrid.
Application:
Clinical intervention requirements during transit determine interior modularity and electrical infrastructure specifications.
- Emergency Medical Response:Advanced life support platforms require regulated environmental control and modular configurations for invasive procedures during transport. United States metropolitan systems are consolidating procurement specifications to reduce NHTSA certification duplication.
- Patient Transport:Basic life support and inter-facility transfer units generate recurring revenue through dedicated service contracts rather than discrete emergency dispatch.
- Fire Fighting:Wildland and structural response vehicles integrate patient transport with fire suppression equipment for multi-casualty incidents.
- Rescue Operations:Technical rescue platforms incorporate rope access, confined space, and trench rescue capabilities alongside medical treatment bays.
Contracted revenue streams concentrate in Patient Transport. Discretionary capital allocation flows toward Emergency Medical Response.
Service Type:
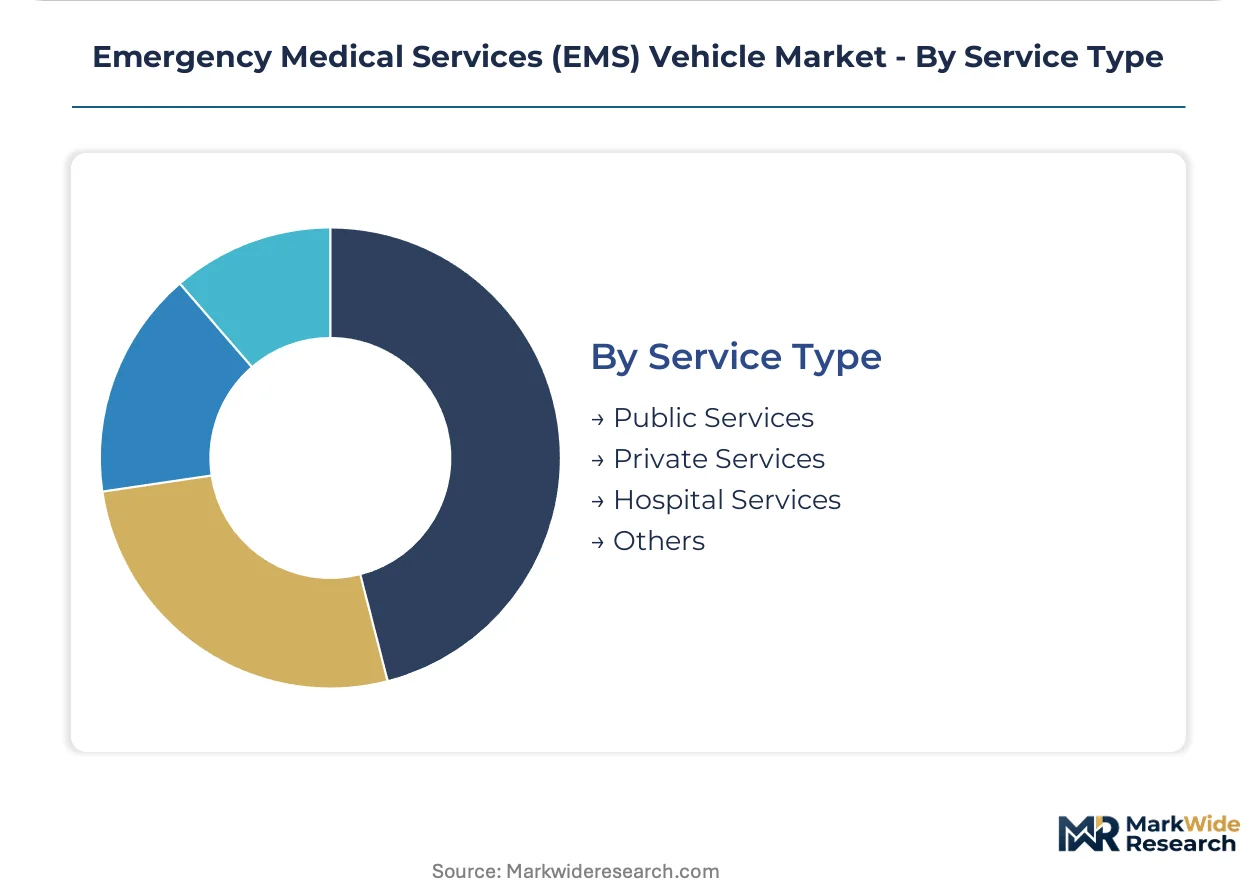
Ownership structure shapes procurement economics from capital-intensive acquisition to operational expenditure models.
- Public Services:Municipal fire departments and county emergency management agencies operate under budget constraints favoring predictable expenditure profiles. Subscription-based fleet telematics are displacing discrete vehicle purchases in United States metropolitan systems.
- Hospital Services:Health system fleets prioritize proprietary branding and standardized equipment configurations across multi-site networks.
- Private Services:Investor-owned emergency medical service providers concentrate margin pools in specialized quick-response segments and dedicated service contracts.
- Others:Industrial on-site medical services and event medicine operators represent fragmented demand with irregular procurement cycles.
Institutional procurement maturity rests with Public Services. Operational model innovation is expanding fastest in Private Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors chassis engineering concentration for emergency vehicle platforms, with upfitter clusters radiating through the Great Lakes manufacturing corridor. Municipal procurement specifications in the United States, Germany, and Japan are driving fleet modernization timelines. Regulatory divergence across these markets is forcing manufacturers to maintain parallel certification tracks.
United States
Municipal fire departments in California and Texas are accelerating electric-hybrid procurement to satisfy state decarbonization mandates. NHTSA enforces Federal Motor Vehicle Safety Standards that govern ambulance structural integrity and extend certification timelines. The Detroit-Windsor corridor concentrates chassis production and upfitter coordination for North American fleet operators.
Germany
Hospital-based fleets in Bavaria and North Rhine-Westphalia are adopting battery-electric platforms to meet municipal sustainability commitments. KBA vehicle type approval requirements filter into ambulance construction specifications that shape manufacturer design commitments. The Stuttgart industrial cluster anchors Mercedes-Benz proprietary emergency vehicle architectures with integrated driver-assistance systems.
Japan
Private emergency services in metropolitan Tokyo and Osaka are expanding quick-response vehicle procurement to reduce urban time-to-treatment intervals. METI industrial policy supports domestic powertrain transitions for emergency vehicle applications. The Nagoya manufacturing belt concentrates Toyota commercial chassis production for regional fleet operators.
United Kingdom
NHS ambulance trusts in London and the Midlands are consolidating procurement specifications to reduce certification duplication across overlapping requirements. The DVSA enforces Whole Vehicle Type Approval that integrates NFPA-aligned safety criteria into national standards. The West Midlands automotive cluster supports specialized upfitter engineering for emergency vehicle body configurations.
Canada
Provincial health authorities in Ontario and Quebec are modernizing aging fleets under federal emissions alignment with EPA standards. Transport Canada Motor Vehicle Safety Standards govern ambulance structural integrity and occupant protection for cross-border procurement. The Greater Toronto Area concentrates fleet management services that bundle telematics with vehicle acquisition.
Emergency Medical Services (EMS) Vehicle Market Competitive Landscape
Capital-heavy chassis producers compete with asset-light body upfitters across fragmented procurement channels. The vendor base organizes around three strategic tiers: integrated automotive OEMs with commercial vehicle divisions, specialized ambulance body manufacturers, and regional upfitters serving municipal contracts. Consolidation pressure concentrates in chassis supply agreements, while body manufacturing retains geographic fragmentation. Dominant competitive moves include strategic partnerships between chassis suppliers and upfitters, plus portfolio diversification into subscription-based fleet services.
Among integrated automotive OEMs, Ford Motor Company and Mercedes-Benz AG anchor distinct positioning vectors. Ford leverages commercial chassis dominance to secure municipal procurement relationships across North American metropolitan systems. Mercedes-Benz occupies premium positioning through proprietary emergency vehicle architectures. REV Group exemplifies the specialized body manufacturer archetype, occupying distinct niches in public and private service channels without captive chassis production.
| Leading Market Players |
|---|
| Ford Motor Company |
| Mercedes-Benz AG |
| General Motors Company |
| REV Group |
| Toyota Motor Corporation |
| Volkswagen AG |
| AB Volvo |
| Braun Industries |
| Wheeled Coach Industries |
| Others |
Supply & Pricing Matrix
Specialized chassis-upfitter engineering talent concentrated in the Detroit-Windsor corridor creates labor-cost differentials that widen pricing-tier spreads between integrated OEM platforms and regional body manufacturers. Municipal procurement offices exploit this dispersion through consolidated fleet contracts that compress margin pools for smaller upfitters lacking captive chassis supply.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for subscription fleet telematics platforms that bundle predictive maintenance with vehicle acquisition. Three-tier pricing structure across premium, standard, and economy levels separates Mercedes-Benz proprietary architectures from Ford commercial chassis partnerships and regional upfitter offerings. Price differentiation hinges on NFPA 1917 certification grade and after-sales service bundling. Cost compression in economy-tier diesel configurations is intensifying because EPA emissions compliance extends engineering timelines. Hospital-based fleets in Germany exhibit lowest price sensitivity; municipal fire departments in United States metropolitan systems face acute budget constraints.
Supply Chain Analysis
Direct-to-municipality channels handle hyperscale procurement demand for standardized ambulance configurations, while dealer networks manage fragmented private-service orders. Chassis production concentrates in the United States, Germany, and Japan through Ford, Mercedes-Benz, and Toyota commercial vehicle divisions. Battery-electric powertrains and aluminum-intensive body structures draw from lithium processing hubs and primary metals markets. Single-source vulnerability pervades North American upfitter engineering timelines tethered to Ford chassis allocation. Distribution runs through municipal procurement offices, hospital system fleet managers, and private emergency service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as NFPA 1917 certification complexity and NHTSA structural compliance timelines force smaller body manufacturers toward acquisition or exit.
For Market Incumbents: Lock in chassis supply agreements through long-term procurement partnerships that secure allocation priority during powertrain transition bottlenecks. Deepen backward integration into proprietary emergency vehicle architectures to differentiate from Ford-dependent upfitters facing margin compression. Battery thermal management R&D investment represents the critical defensive lever against electric-platform performance degradation. For New Entrants and Emerging Players: Digital fleet-management platforms offer the most penetrable entry vector for subscription-based revenue capture without capital-intensive manufacturing. Target quick-response vehicle segments in Japanese metropolitan markets where private emergency services prioritize speed over patient transport capacity. Pursue hospital-based fleet contracts in Germany through battery-electric platform specialization aligned with municipal decarbonization mandates. For Investors and Strategic Acquirers: Re-rating potential sits with specialized body manufacturers possessing NFPA 1917 certification infrastructure and established municipal relationships given accelerating fleet modernization timelines. Five-to-ten-year viability favors asset-light upfitters with diversified chassis supplier relationships over single-source-dependent competitors. Monitor EPA zero-emission mandate acceleration as the decisive inflection signal for electric-hybrid platform adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| Chassis Supply Agreement | Ford commercial platform allocation secures municipal procurement relationships across North American metropolitan systems. |
| NFPA 1917 Certification Investment | Parallel NHTSA testing tracks reduce certification duplication delays for fleet modernization programs. |
| Battery Thermal Management Development | Extended duty cycle engineering addresses electric-platform performance degradation under emergency load profiles. |
| Subscription Telematics Launch | Predictive maintenance software absorbs capital expenditure into operational expenditure models for budget-constrained municipalities. |
| Quick-Response Vehicle Specialization | Compact rapid-deployment configurations concentrate margin pools in dense urban corridors beyond traditional ambulance markets. |
Research Methodology
Document review covered NFPA 1917 construction standards, NHTSA Federal Motor Vehicle Safety Standards, and EPA emissions regulations, complemented by interviews with municipal fleet procurement officers, hospital system logistics directors, ambulance body manufacturing engineers, and commercial chassis platform managers. Secondary validation drew from NHTSA certification databases, NFPA technical committee filings, and municipal procurement contract records. Bottom-up unit demand modeling triangulated against top-down fleet modernization expenditure analysis.
Historical fleet replacement cycles cross-referenced against expert panel input on electrification transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include vehicle type, fuel architecture, service model ownership structure, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement rates and policy-mandated procurement acceleration scenarios. Battery cost trajectory and NFPA 1917 testing capacity constraints served as industry-specific forecast inputs.
The model holds under stable EPA emissions enforcement and NFPA 1917 adoption continuity; deviation in zero-emission mandate acceleration or NHTSA structural standard revision would shift replacement timing assumptions. Forecasts reflect documented base-case assumptions regarding powertrain transition feasibility and chassis supplier allocation capacity. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty and battery supply chain volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Global Ambulance Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
Emergency Medical Supplies Market
Emergency Medical Services
US Hospital Emergency Department Market