
 Emergency Medical Supplies Market | 2026-2036
Emergency Medical Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Medical Supplies Market Analysis
ISO 13485 certification is reorganizing competitive access across the emergency medical supplies sector, forcing smaller distributors to upgrade quality management systems or exit hospital procurement channels. Stryker Corporation leverages its trauma device portfolio to dominate North American emergency room supply contracts. Cardinal Health sustains broad distribution reach through wholesale networks spanning acute care and ambulatory settings. Medtronic anchors its position in resuscitation equipment through proprietary defibrillator and patient monitoring technology.
Emergency medical supplies encompass sterile and non-sterile products designed for immediate patient stabilization, including latex-free bandages with specified tensile strength, resuscitation bags with pressure-limiting valves, and pre-filled syringes containing epinephrine or atropine for cardiac emergencies. These products serve first responders, emergency departments, and disaster medical assistance teams requiring rapid deployment capability. First aid kits and resuscitation equipment command the largest revenue pools within product type segmentation, reflecting their non-discretionary placement in regulated settings. Hospital settings and field response applications generate the highest throughput volumes, while disaster relief channels exhibit episodic but premium pricing during surge events. Emergency services and healthcare providers represent the most consolidated end user segments, concentrating purchasing power through group procurement organizations and centralized hospital networks.
FDA 510(k) clearance requirements and EU MDR technical documentation obligations impose substantial compliance costs that filter marginal participants from hospital and government contract bidding. The EPA regulates sterilization gas emissions from ethylene oxide processing facilities, constraining domestic manufacturing capacity for sterile disposable supplies. WHO Emergency Use Listing procedures govern international disaster relief procurement, creating a parallel regulatory pathway for humanitarian stockpile suppliers. Stakeholders must monitor evolving MDR transition deadlines and FDA quality system inspection priorities to anticipate supply chain bottlenecks and certification backlogs.
Market Dynamics
Hospital emergency departments are consolidating procurement through group purchasing organizations while FDA 510(k) clearance backlogs and EU MDR recertification deadlines compress supplier certification timelines, forcing manufacturers to prioritize quality management system upgrades over price competition.
Growth Catalysts
- EU MDR Recertification:The Medical Device Regulation's stricter technical documentation requirements are filtering marginal manufacturers from European hospital contracts, concentrating volume among certified suppliers with established notified body relationships.
- India:The country's expansion of emergency care infrastructure under Ayushman Bharat is driving stockpile procurement for trauma centers and disaster medical assistance teams across tier-2 and tier-3 cities.
- Sterile Disposable Automation:Advanced ethylene oxide sterilization monitoring systems are reducing batch rejection rates and enabling domestic manufacturers to meet surge capacity requirements during mass casualty events.
Market Restraints
- Ethylene Oxide Capacity:EPA emissions regulations on sterilization gas processing have constrained domestic manufacturing capacity for sterile bandages and resuscitation equipment, creating supply bottlenecks during demand spikes.
- Raw Material Concentration:Medical-grade latex and synthetic rubber supply chains concentrate in Southeast Asian processing facilities, exposing North American and European manufacturers to shipping disruption risks.
- Biocompatibility Testing:Extended ISO 10993 cytotoxicity evaluation timelines for novel wound dressing materials delay product launches by 12-18 months, compressing effective patent windows.
Strategic Opportunities
- German Trauma Network:The country's regional trauma center certification program is mandating standardized equipment configurations, creating bulk procurement opportunities for integrated resuscitation system suppliers.
- Pre-Hospital Telemetry:Convergence of portable patient monitors with cellular connectivity is enabling real-time data transmission from ambulance to emergency department, opening subscription revenue models for device manufacturers.
- WHO Emergency Use Listing:The streamlined procurement pathway for humanitarian stockpile suppliers is reducing regulatory friction for manufacturers targeting disaster relief channels in low-income countries.
Industry Challenges
- Notified Body Capacity:EU MDR designation bottlenecks have created 18-month certification queues, forcing manufacturers to delay product launches or maintain legacy CE mark products through transition periods.
- Sterilization Validation:Complex ethylene oxide residual testing protocols require specialized analytical chemistry capabilities that smaller contract manufacturers struggle to maintain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Medical Supplies Market |
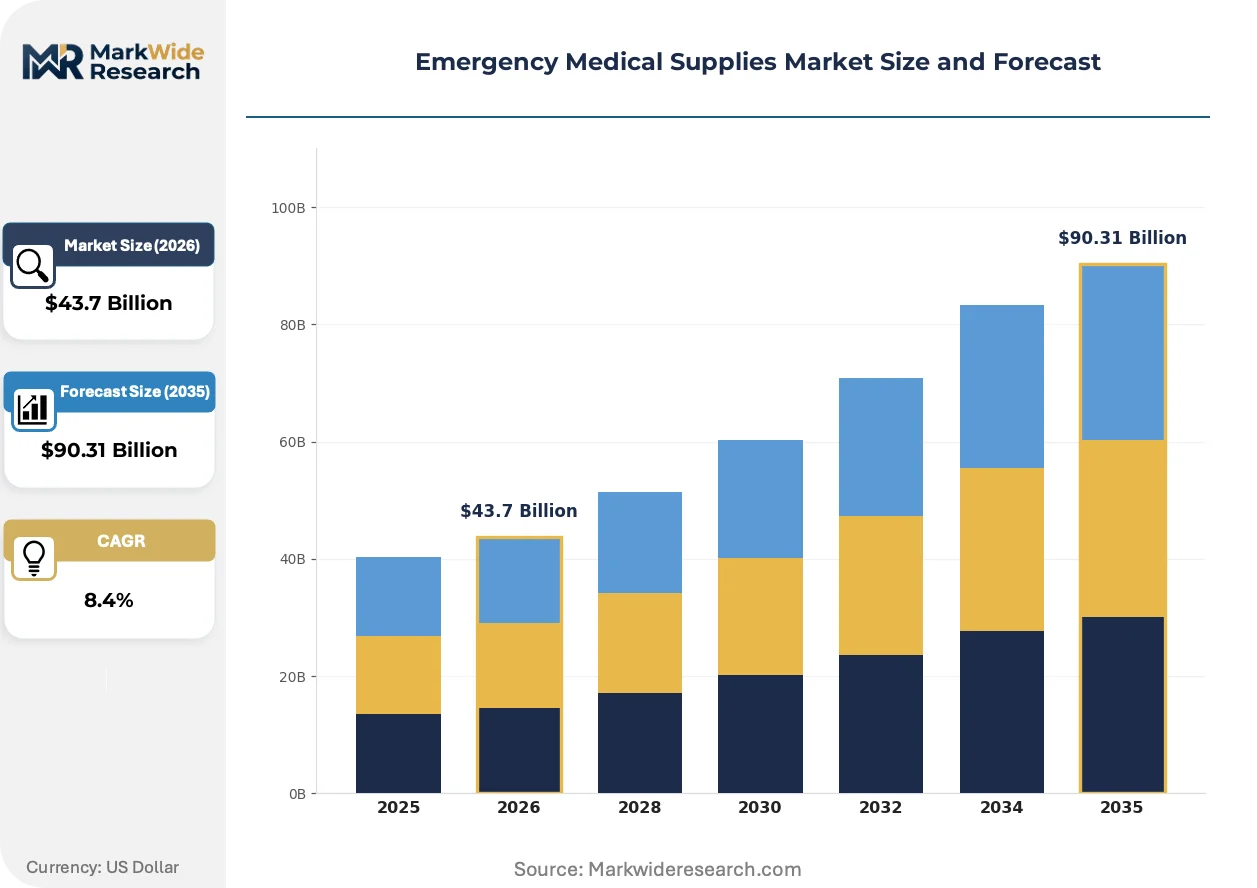
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $90.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First Aid Kits, Bandages, Resuscitation Equipment, Emergency Medications Application: Field Response, Home Care, Hospital Settings, Disaster Relief End User: Emergency Services, Healthcare Providers, Government Agencies, Non-Profit Organizations Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Stryker Corporation, Cardinal Health, Medtronic, GE Healthcare, Johnson & Johnson, 3M, Bound Tree Medical, Henry Schein, McKesson Medical-Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Medical Supplies Market Emerging Trajectories
Digital connectivity and regulatory harmonization are restructuring how emergency medical supplies are specified, procured, and deployed across acute care networks, with particular pressure on manufacturers to integrate traceability and remote monitoring capabilities.
Smart resuscitation bags with integrated pressure sensors and Bluetooth connectivity are bifurcating the manual ventilation device category. Emergency medical services in the United States and Germany are adopting these systems to capture ventilation waveform data for quality assurance review. The technology is compressing price competition in the premium segment while economy-tier manual devices face commoditization in price-sensitive procurement channels.
EU MDR Article 10 technical documentation requirements are mandating clinical evidence for all class IIa and above devices, including legacy products previously cleared under the Medical Device Directive. Manufacturers must retrospectively compile post-market surveillance data or conduct new clinical investigations to maintain market access. German and French notified bodies are prioritizing trauma device and resuscitation equipment reviews, creating geographic variation in certification speed.
Group purchasing organizations are consolidating hospital emergency department supply contracts into multi-year enterprise agreements with strict compliance metrics. Cardinal Health and McKesson are capturing these relationships through integrated distribution networks that bundle logistics, inventory management, and regulatory documentation services. This concentration is most visible in United States health systems with more than ten affiliated emergency departments, where standardization incentives override product-specific preferences.
Emergency Medical Supplies Market Segmentation
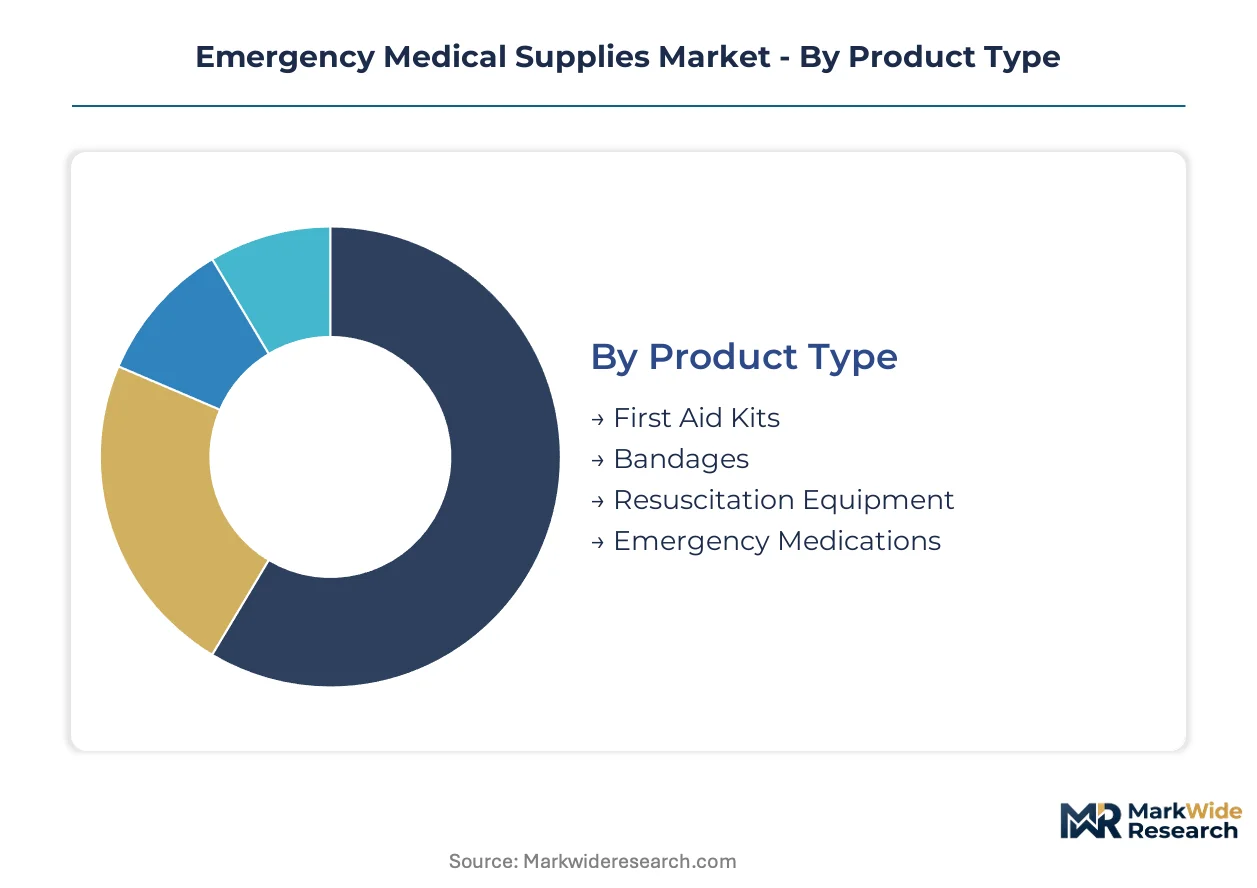
Emergency medical supplies segmentation reflects divergent regulatory burdens and procurement pathways across clinical and non-clinical settings. Product categories face distinct substitution pressures from adjacent medical device classes, while distribution channels consolidate around compliance capabilities.
Product Type:
Resuscitation equipment faces the most acute substitution threat from integrated patient monitoring systems, while bandage categories confront displacement from advanced wound closure technologies.
- First Aid Kits:Pre-configured collections containing sterile dressings, antiseptic solutions, and basic airway management tools. Demand concentrates in United States workplace safety compliance programs and German occupational health mandates, with procurement tightening around ISO 13485-certified suppliers.
- Bandages:Latex-free elastic wraps and adhesive dressings with specified tensile strength and fluid absorption rates. Hospital emergency departments in India drive volume through trauma center expansion under national health infrastructure programs, though raw material concentration in Southeast Asian rubber processing creates supply vulnerability.
- Resuscitation Equipment:Manual ventilation bags with pressure-limiting valves, oropharyngeal airways, and suction units. FDA 510(k) clearance requirements filter marginal manufacturers from United States hospital contracts.
- Emergency Medications:Pre-filled syringes containing epinephrine, atropine, or naloxone for cardiac and overdose emergencies. Cold chain logistics requirements constrain distribution to specialized pharmaceutical wholesalers.
First aid kits retain volume leadership; emergency medications hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive hospital installations from disposable-heavy field deployment models.
- Field Response:Portable supplies configured for ambulance and first responder deployment, emphasizing weight reduction and environmental durability. German emergency medical services drive adoption of smart resuscitation bags with telemetry integration.
- Home Care:Consumer-oriented first aid and emergency medication storage for chronic condition management. United States retail channels dominate through pharmacy chain distribution.
- Hospital Settings:High-throughput emergency department configurations with standardized trauma bay equipment arrays. Group purchasing organizations in the United States consolidate procurement into multi-year enterprise agreements.
- Disaster Relief:Surge-capacity stockpiles maintained by government agencies and humanitarian organizations. WHO Emergency Use Listing procedures govern international procurement, enabling faster regulatory pathways for certified suppliers.
Hospital settings command the highest revenue per unit; disaster relief exhibits the most volatile demand spikes.
End User:
Customer type determines pricing leverage, with consolidated healthcare networks extracting volume discounts unavailable to fragmented non-profit channels.
- Emergency Services:Fire departments, ambulance operators, and search-and-rescue units requiring rapid deployment capability. United States municipal procurement cycles drive replacement demand for legacy equipment.
- Healthcare Providers:Hospital networks and acute care facilities with centralized supply chain management. Cardinal Health and McKesson capture these relationships through integrated distribution and inventory services.
- Government Agencies:Federal, state, and local stockpile authorities with mandated surge capacity requirements. India's disaster medical assistance teams expand procurement across tier-2 and tier-3 cities.
- Non-Profit Organizations:Humanitarian relief agencies and community health programs with constrained procurement budgets. WHO certification unlocks access to pooled procurement mechanisms.
Healthcare providers dominate absolute spending; government agencies show the most aggressive stockpile expansion.
Distribution Channel:
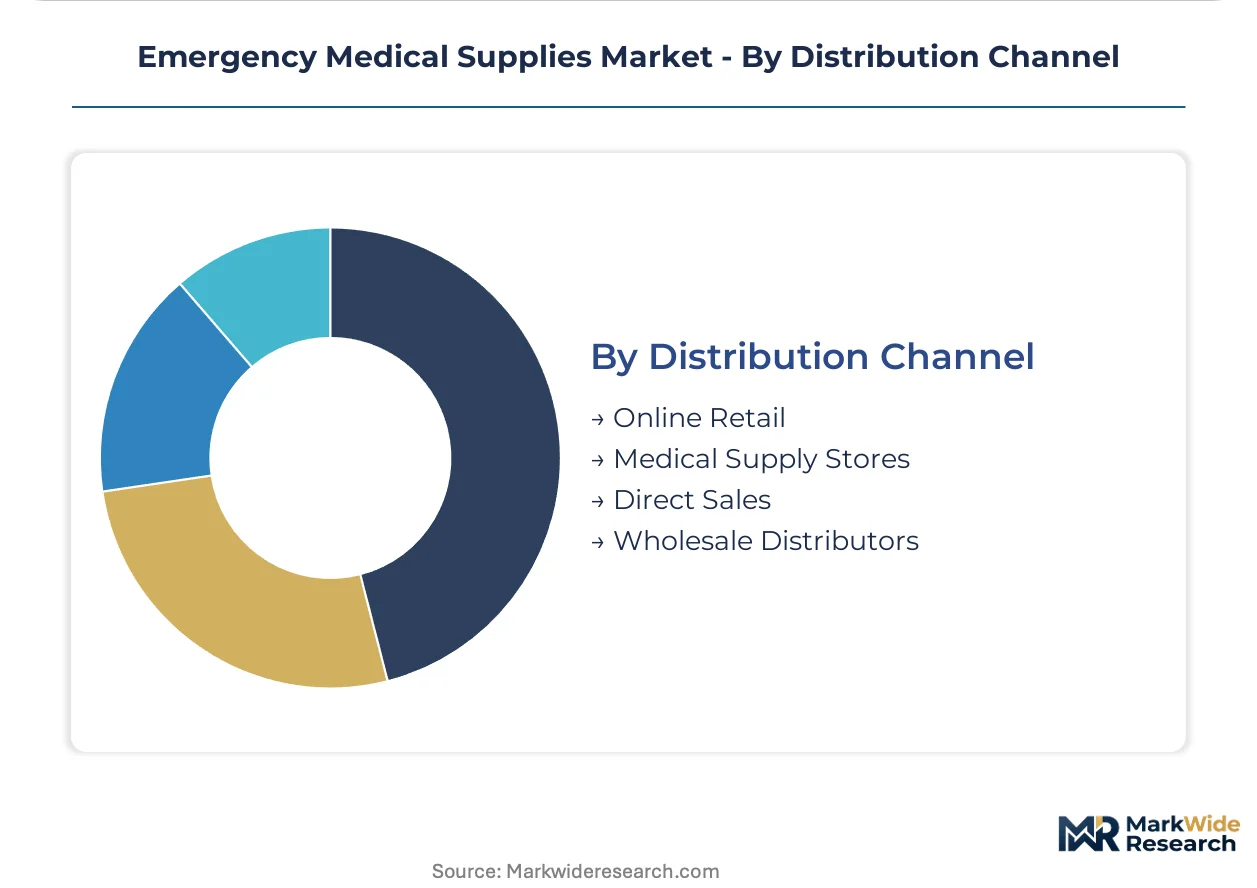
Supply concentration favors wholesale distributors with regulatory documentation capabilities, pressuring direct sales models.
- Online Retail:E-commerce platforms serving consumer and small-practice segments with standardized first aid products. United States pharmacy chains integrate digital channels with physical pickup.
- Medical Supply Stores:Specialized distributors offering product training and technical support for complex resuscitation equipment. German trauma network certification programs drive regional consolidation.
- Direct Sales:Manufacturer-to-institution relationships for high-value capital equipment and customized configurations. EU MDR technical documentation requirements increase sales cycle complexity.
- Wholesale Distributors:National and regional networks bundling logistics, inventory management, and regulatory compliance services. Group purchasing organization alignment determines competitive positioning in the United States.
Wholesale distributors capture the largest revenue share; online retail gains traction fastest in consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's medical logistics hub underwrites Europe's emergency supply distribution, while Mumbai's JNPT anchors Indian import channels for trauma equipment. These infrastructure assets concentrate procurement flows and regulatory compliance burdens across three continents.
United States
Hospital emergency departments drive resuscitation equipment procurement through group purchasing organizations. FDA 510(k) clearance requirements filter marginal manufacturers from federal stockpile contracts. The Boston-Cambridge medical device cluster concentrates defibrillator and patient monitoring R&D.
Germany
The regional trauma center certification program mandates standardized equipment configurations across Bavaria and North Rhine-Westphalia. EU MDR recertification deadlines compress supplier timelines through notified bodies in Berlin and Munich. The Baden-Württemberg industrial corridor hosts sterilization equipment manufacturers serving Central European hospitals.
India
Ayushman Bharat expansion drives stockpile procurement for tier-2 and tier-3 city trauma centers. CDSCO medical device rules impose quality management system requirements on domestic manufacturers. The Hyderabad-Visakhapatnam corridor concentrates sterile disposable production for government hospital networks.
Japan
Aging demographics accelerate automated external defibrillator placement in public spaces and transportation hubs. PMDA quality system inspections prioritize resuscitation device manufacturers in the Kansai region. Osaka-based distributors coordinate pre-hospital equipment supply chains across East Asian markets.
United Kingdom
NHS emergency department consolidation drives standardized procurement for trauma bays and ambulance fleets. MHRA post-Brexit device regulations create parallel conformity assessment pathways. The Greater Manchester health innovation cluster tests connected resuscitation equipment for national rollout.
Emergency Medical Supplies Market Vendor Landscape
Listed leaders compete with private specialists across certification capabilities and distribution reach. The market structures around three tiers: diversified conglomerates with hospital system relationships, wholesale distributors bundling logistics and compliance services, and regional specialists targeting pre-hospital and disaster relief channels. Dominant competitive moves include strategic partnerships with group purchasing organizations and portfolio diversification into connected device platforms.
Within the diversified conglomerate tier, Stryker Corporation and Medtronic exemplify archetypes anchored in trauma and resuscitation technology. Cardinal Health occupies a position representing wholesale distribution scale, bundling regulatory documentation with inventory management across acute care networks.
| Leading Market Players |
|---|
| Stryker Corporation |
| Cardinal Health |
| Medtronic |
| GE Healthcare |
| Johnson & Johnson |
| 3M |
| Bound Tree Medical |
| Henry Schein |
| McKesson Medical-Surgical |
| Others |
Supply Flow & Price Mechanics
Ethylene oxide sterilization capacity utilization above eighty percent in domestic facilities creates scale thresholds that marginal manufacturers cannot cross, compressing supply-side competition and establishing price floors for sterile resuscitation equipment and trauma kits. This concentration of validated sterilization infrastructure permits certified incumbents to sustain margin structures while smaller competitors face forced exit from hospital procurement channels.
Pricing Analysis
Certification level creates the primary spread between premium and economy tiers, with ISO 13485 and FDA 510(k)-cleared products commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by quality grade and after-sales service bundling. Cost compression in the economy tier is intensifying because group purchasing organizations consolidate contract volumes with fewer suppliers. Emergency services represent the most price-sensitive buyer segment, while hospital networks with enterprise agreements exhibit lower sensitivity due to standardization mandates.
Supply Chain Analysis
Sixty-day inventory buffers for medical-grade latex and synthetic rubber have become standard practice as Southeast Asian processing facilities face shipping disruption risks. Raw material dependencies center on Malaysian rubber plantations, Thai synthetic polymer processors, and Chinese component manufacturers. Single-source vulnerability concentrates in ethylene oxide sterilization gas supply, where EPA emissions regulations constrain domestic production alternatives. Distribution runs through wholesale distributors bundling logistics with regulatory documentation services, though direct sales persist for high-value capital equipment configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Emergency medical supplies sit in early-cycle expansion as pre-hospital telemetry adoption accelerates real-time data transmission capabilities from ambulance to emergency department. This technology tailwind creates new revenue architecture for connected device platforms beyond traditional equipment sales.
For Market Incumbents: Consolidate hospital system relationships through multi-year enterprise agreements with embedded compliance services, defending against wholesale distributor encroachment. Deepen backward integration into ethylene oxide sterilization capacity to secure supply continuity as EPA regulations tighten. Prioritize notified body relationship investment in Berlin and Munich to navigate EU MDR recertification queues.
For New Entrants and Emerging Players: Post-market surveillance data compilation services present an underserved layer where incumbents under-serve smaller manufacturers struggling with EU MDR Article 10 technical documentation requirements. Target tier-2 and tier-3 Indian cities for trauma center equipment procurement under Ayushman Bharat expansion. Pursue WHO Emergency Use Listing certification as the go-to-market angle for disaster relief channel access.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected device platforms with software subscription potential over pure hardware manufacturers. Long-term viability rests on defensible data integration capabilities across pre-hospital and emergency department workflows. Acquisition target archetype: regional specialists with established notified body relationships and trauma device portfolios. Monitor FDA 510(k) clearance backlog duration as the inflection indicator for supplier consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Unlocks hospital procurement contracts and federal stockpile eligibility in the United States. |
| CE Marking Pathway | Maintains European market access through notified body relationships in Germany and France. |
| Hospital System Partnership | Secures multi-year enterprise agreements with group purchasing organizations. |
| Software Companion Development | Enables telemetry subscription revenue from smart resuscitation bags. |
| Reimbursement Strategy | Aligns product specifications with CMS Medicare coverage determinations. |
Methodological Framework
Cross-validation between primary interviews with hospital purchasing committees and secondary validation through FDA 510(k) filings anchors the qualitative findings. Stakeholder roles include GPO contracts managers, biomedical engineers, emergency department clinicians, and sterilization facility operators. Secondary sources encompass hospital procurement databases, EU MDR notified body registries, and customs trade data for medical-grade rubber imports. Bottom-up product category sizing triangulates against top-down healthcare expenditure allocation models.
Sensitivity analysis across sterilization capacity constraints and raw material price scenarios tests forecast robustness. Segmentation dimensions include product type, application setting, end user category, and distribution channel. CAGRs derive from regression analysis of historical procurement volumes against infrastructure investment indicators. Industry-specific inputs incorporate trauma center certification timelines and disaster relief stockpile replenishment cycles.
Underlying assumptions cover sustained EPA emissions regulation enforcement and EU MDR transition completion, with deviation risk concentrated in notified body capacity bottlenecks and shipping disruption frequency. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
US EMS Billing Services Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
US Urgent Care Centers Market
Emergency Medical Services
Europe Ambulance Services Market