
 Global Ambulance Services Market | 2026-2036
Global Ambulance Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulance Services Market Foresight
Paramedic workforce shortages is bifurcating market growth between established markets and expansion corridors. Falck A/S leverages its integrated training academies to sustain staffing levels across Scandinavian operations. Global Medical Response anchors North American coverage through consolidated regional contracts. Ziqitza Healthcare Limited dominates India's fragmented emergency response landscape with technology-enabled dispatch systems.
Ambulance services encompass pre-hospital emergency medical care, inter-facility patient transport, and specialized mobile intensive care delivered via road vehicles, rotorcraft, and fixed-wing aircraft equipped with life-support systems such as ventilators, cardiac monitors, and defibrillators. The primary purpose is stabilizing patients during transit while bridging geographic gaps between incident sites and definitive care facilities. Emergency Response commands the largest revenue share due to statutory obligations and unpredictable call volume, while Air Ambulance generates premium margins despite smaller scale. Patient Transport segments face margin compression from insurance reimbursement caps, whereas Neonatal Transport commands specialized pricing tied to equipment intensity.
FDA device clearance requirements govern onboard medical equipment, while FAA regulations structure air ambulance operational certificates and flight crew qualifications. The EU AI Act is beginning to shape automated dispatch and triage algorithm deployments across European fleets. Stakeholders must weigh capital allocation between fleet electrification mandates and advanced life support technology upgrades as regulatory timelines tighten.
Market Dynamics
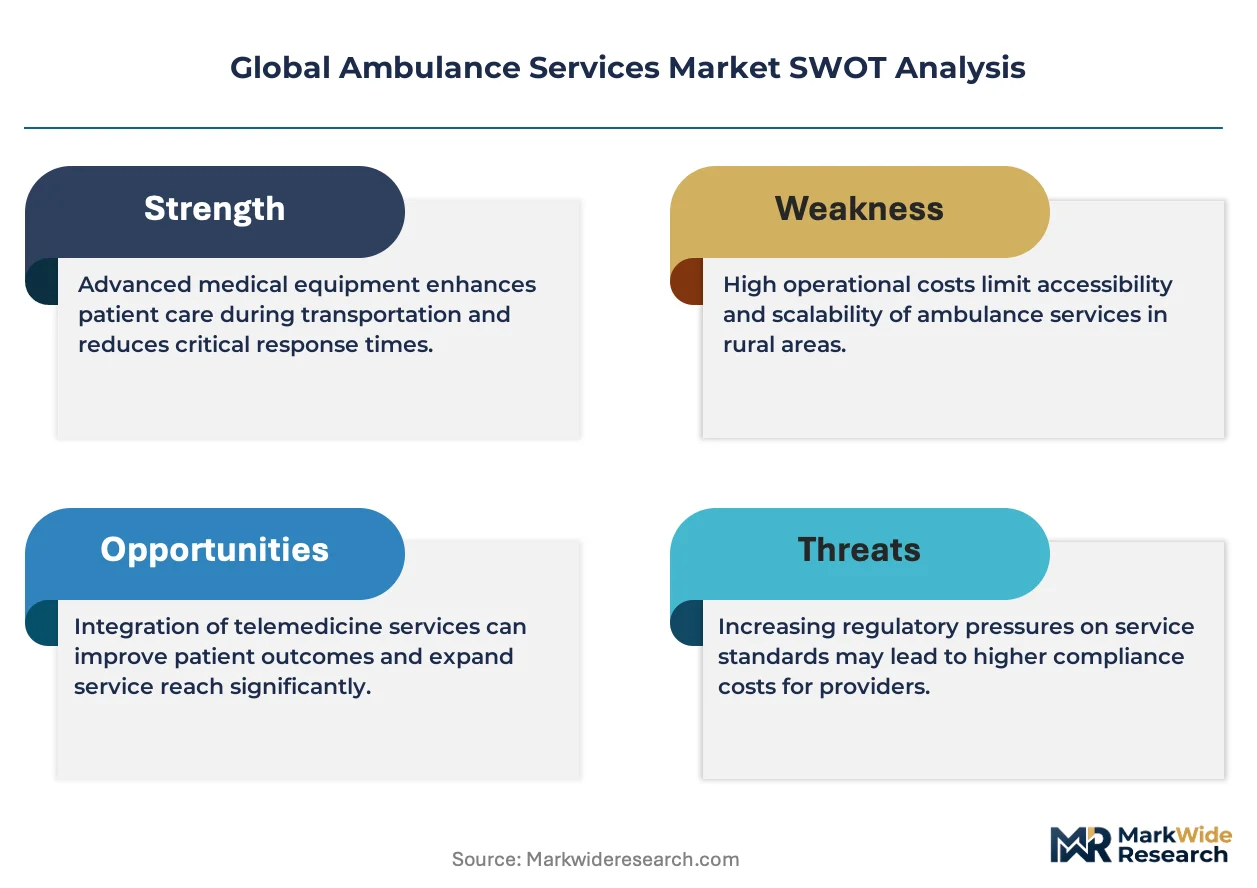
Fleet electrification mandates under the EU Green Deal are forcing capital reallocation from life-support equipment upgrades to zero-emission vehicle procurement, compressing margins for operators managing dual compliance timelines.
Growth Catalysts
- EU Green Deal Fleet Mandates:Emergency vehicle electrification requirements are accelerating replacement cycles and opening tender opportunities for integrated e-ambulance providers across Germany, France, and the Netherlands.
- India's Emergency Response Infrastructure:Government-funded 108/102 helpline expansion is creating dedicated revenue streams for private ambulance networks in rural districts previously served by informal transport.
- Telemedicine-Enabled Dispatch:Real-time video triage algorithms are reducing unnecessary emergency department transfers and expanding addressable patient populations for mobile intensive care units.
Market Restraints
- Lithium-Ion Battery Supply Concentration:Cathode material processing dominance by Chinese refiners exposes European and North American fleet operators to input cost volatility and geopolitical supply interruptions.
- FAA Airworthiness Certification:Rotorcraft medical equipment retrofit approvals require 18-24 month validation timelines, structurally limiting air ambulance fleet expansion regardless of demand signals.
- Paramedic Workforce Pipeline Collapse:Training program capacity constraints in the United States and United Kingdom are capping service expansion below population growth rates in metropolitan corridors.
Strategic Opportunities
- Indonesia's Archipelago Geography:Maritime emergency response gaps between Java, Sumatra, and Sulawesi create first-mover potential for amphibious ambulance and seaplane medical evacuation services.
- EU AI Act Automated Triage:Regulatory clarity on machine-learning dispatch algorithms enables differentiated subscription models for predictive emergency response in Scandinavian smart cities.
- Blockchain-Verified Medical Records:Integration of distributed ledger patient data with ambulance telemetry is enabling seamless handoff billing and reducing insurance claim disputes for inter-facility transfers.
Industry Challenges
- Legacy Dispatch System Interoperability:Municipal 911 infrastructure using analog radio protocols creates integration friction with cloud-based fleet management platforms, delaying real-time resource optimization.
- Advanced Life Support Certification Lags:Cardiac monitor and ventilator operator credentials require recurring clinical hours that clash with 24/7 shift scheduling, elevating training costs and compliance risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulance Services Market |
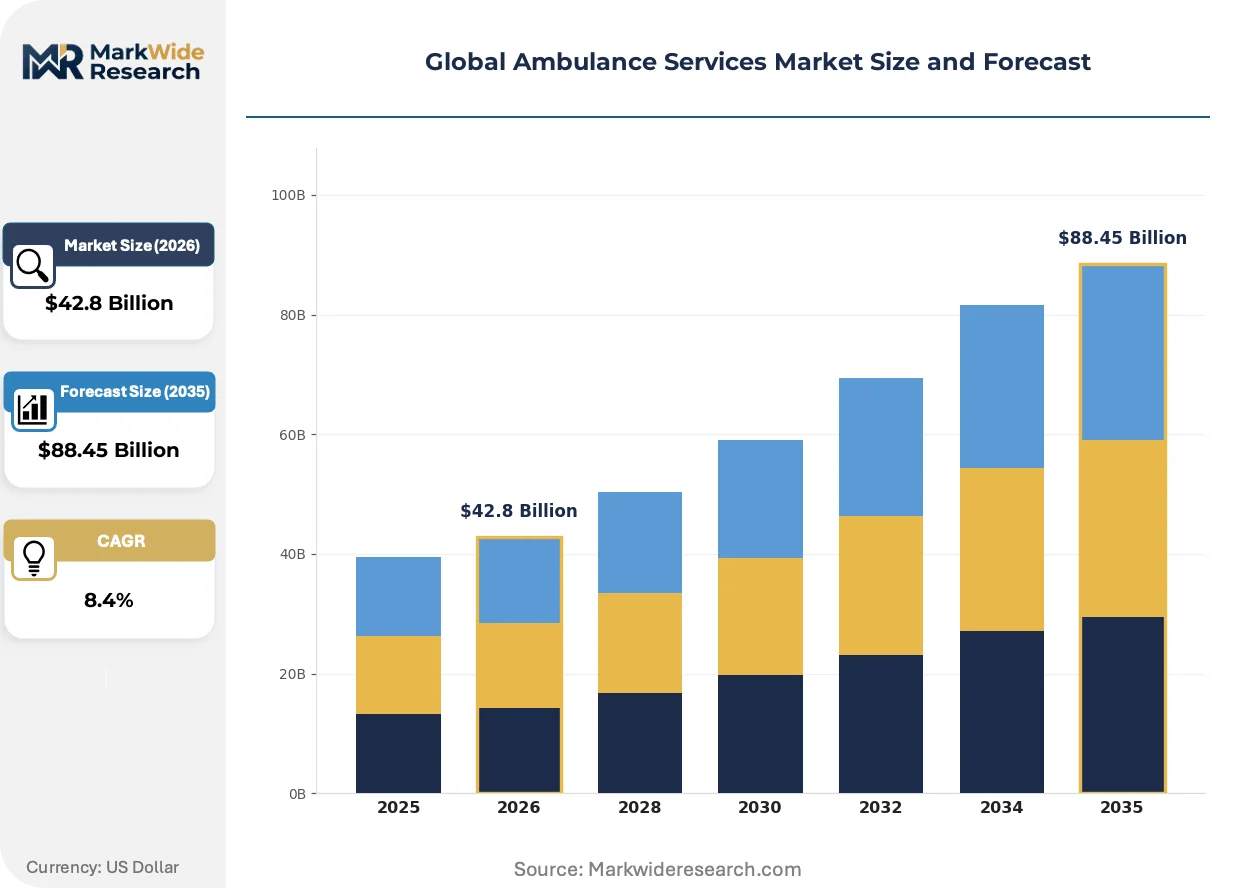
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $88.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Response, Patient Transfer, Neonatal Transport, Air Ambulance, Event Medical Coverage Vehicle Type: Basic Life Support, Advanced Life Support, Critical Care Transport, Patient Transport, Specialty Care Equipment Technology: Ventilators, Cardiac Monitors, Infusion Pumps, Defibrillators, Portable Ultrasound Customer Type: Hospitals, Insurance Providers, Government Agencies, Corporate Clients, Non-Governmental Organizations |
| Companies Covered | Acadian Ambulance Service, Falck A/S, Global Medical Response, Air Methods Corporation, Envision Healthcare Corporation, Ziqitza Healthcare Limited, London Ambulance Service NHS Trust, Babcock International Group, America Ambulance Service, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulance Services Market Shifts & Advancements
Digitization of emergency medical dispatch is compressing response time benchmarks while fragmenting traditional service boundaries between public, private, and hospital-based operators.
Electric drivetrain adoption is fragmenting fleet procurement strategies across European operators. Battery-electric ambulances from Dutch and German manufacturers are penetrating municipal contracts despite 40% range limitations versus diesel equivalents. Hospital systems in Copenhagen and Amsterdam are piloting battery-swap infrastructure to circumvent charging downtime, creating spatial competitive advantage in dense urban cores.
The EU AI Act's risk classification framework for medical decision-support algorithms is reshaping dispatch software procurement. Automated triage systems must now demonstrate explainability and human oversight protocols before deployment in France, Germany, and Italy. Air ambulance operators in Switzerland and Austria are delaying AI integration pending national implementation guidance, creating temporary competitive divergence between early adopters and cautious incumbents.
Subscription-based emergency response memberships are displacing per-use billing in Australian and Canadian markets. Rural households in Queensland and Alberta are prepaying annual fees for guaranteed air ambulance activation, transferring financial risk from insurers to service providers. This model concentrates revenue predictability with operators while exposing them to adverse selection from high-risk enrollees in remote mining and agricultural communities.
Global Ambulance Services Market Segmentation
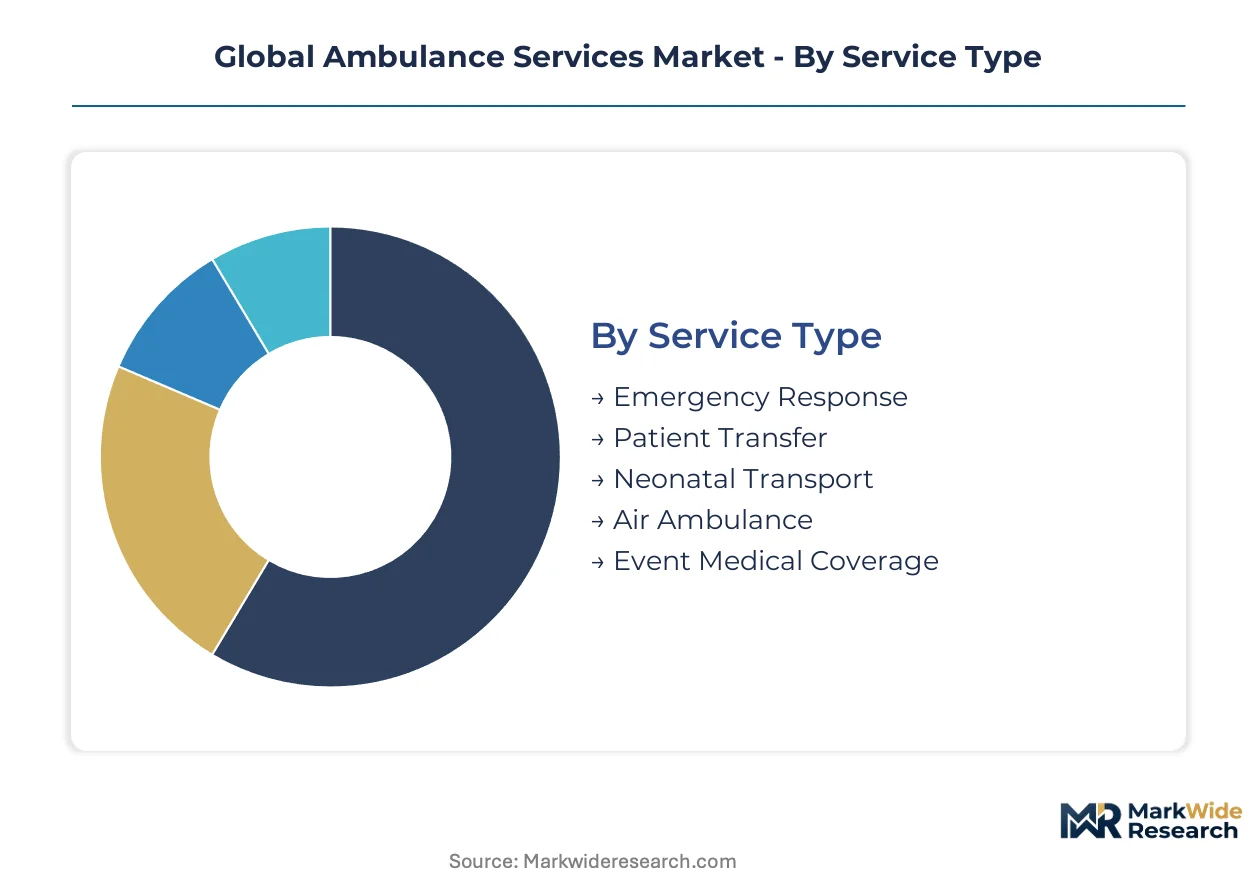
Segmentation in ambulance services reveals divergent margin structures across service intensity tiers. Equipment configuration and contracting authority determine pricing power more than geographic coverage alone.
Service Type:
Emergency Response commands premium reimbursement rates tied to statutory response obligations and unpredictable demand curves.
- Emergency Response:Statutory-mandated pre-hospital care with unpredictable call volumes drives the highest reimbursement rates. Municipal contracts in Germany and the Netherlands concentrate demand where EU Green Deal fleet mandates are accelerating electrification procurement.
- Air Ambulance:Rotorcraft and fixed-wing medical evacuation services generate superior margins through specialized crew certification and FAA airworthiness requirements. Rural districts in Alberta and Queensland are shifting toward subscription models that transfer financial risk to operators.
- Patient Transfer:Scheduled inter-facility transport faces margin compression from insurance reimbursement caps.
- Neonatal Transport:Specialized mobile intensive care for infants commands equipment-intensive pricing tied to ventilator and incubator specifications.
- Event Medical Coverage:Outsourced standby services for mass gatherings operate on fixed-fee contracts with limited upside.
Emergency Response holds installed capacity. Air Ambulance is rotating up the share rankings.
Vehicle Type:
Life support capability tiers separate capital intensity and crew certification requirements across fleet procurement decisions.
- Advanced Life Support:Vehicles equipped with cardiac monitors, ventilators, and defibrillators require paramedic specialists and command municipal premium pricing. Copenhagen hospital systems are piloting battery-swap infrastructure to maintain ALS fleet uptime during electrification transitions.
- Critical Care Transport:Mobile intensive care units bridge geographic gaps between incident sites and definitive care facilities. Demand concentrates in India's 108/102 helpline expansion districts where Ziqitza Healthcare Limited deploys technology-enabled dispatch.
- Basic Life Support:Standard emergency vehicles with first-aid capabilities serve high-volume, lower-acuity calls.
- Patient Transport:Non-emergency stretcher vehicles face rate pressure from per-mile reimbursement schedules.
- Specialty Care:Bariatric, psychiatric, and infectious disease transport vehicles address niche compliance requirements.
Advanced Life Support dominates fleet depreciation schedules. Critical Care Transport is expanding most quickly in emerging markets.
Equipment Technology:
FDA device clearance timelines and battery supply concentration shape procurement risk for onboard medical systems.
- Ventilators:Portable mechanical ventilation systems require 510(k) premarket notification and dominate equipment capital allocation in neonatal and critical care segments. Chinese cathode material processing concentration exposes European operators to input cost volatility.
- Cardiac Monitors:Multi-parameter patient monitoring with telemetry integration enables real-time hospital handoff. Recurring clinical hour requirements for operator credentials clash with 24/7 shift scheduling in US and UK markets.
- Defibrillators:Automated external and manual units are standard across all vehicle tiers.
- Infusion Pumps:Programmable drug delivery systems face software validation requirements under EU MDR.
- Portable Ultrasound:Point-of-care imaging is penetrating air ambulance fleets for in-flight diagnostic capability.
Ventilators anchor equipment replacement cycles. Cardiac Monitors are gaining share fastest through telemetry integration.
Customer Type:
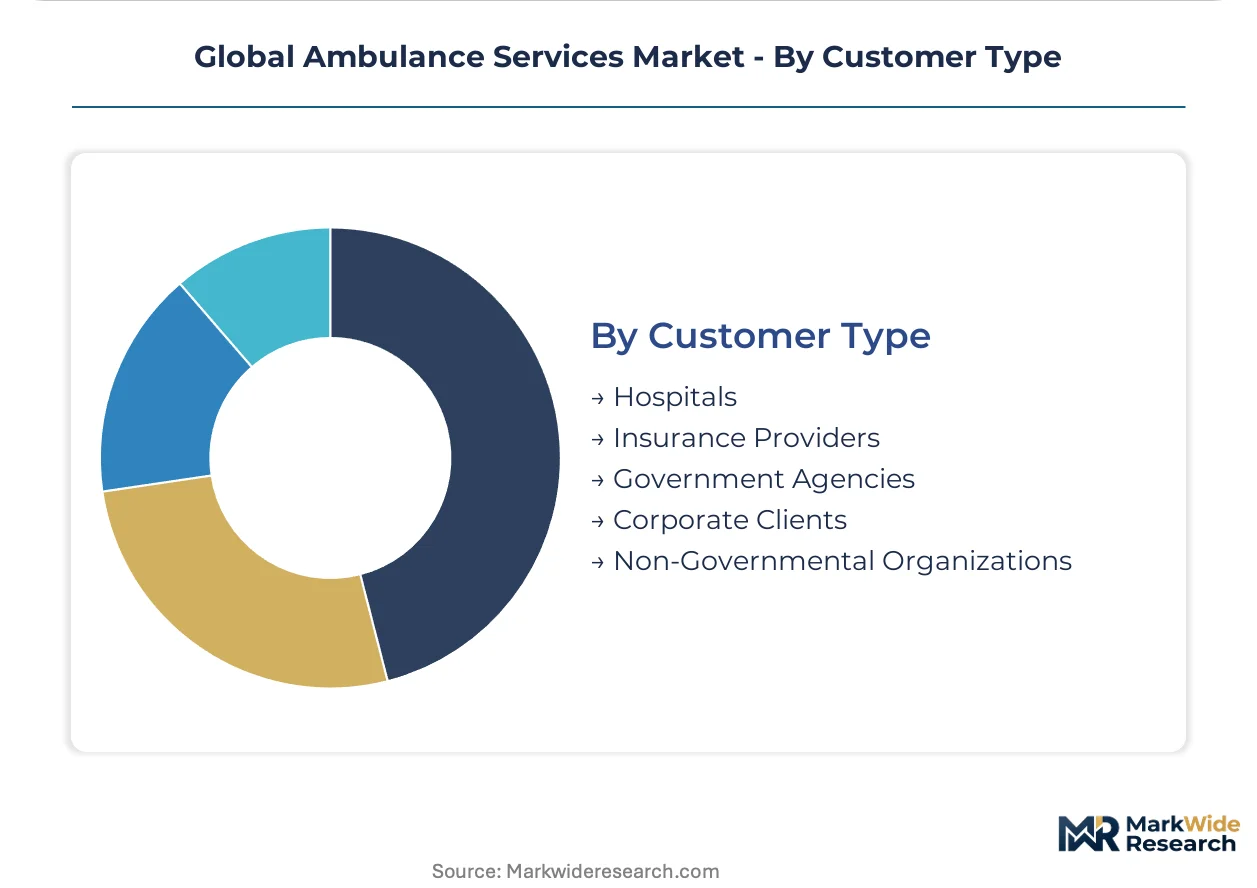
Contracting authority and reimbursement mechanism determine pricing structure and revenue predictability across buyer segments.
- Government Agencies:Municipal and national health service contracts provide volume visibility through multi-year tenders. India's government-funded 108/102 helpline expansion is creating dedicated revenue streams for private networks in rural districts.
- Insurance Providers:Prepaid emergency response memberships in Australian and Canadian markets are displacing per-use billing and concentrating adverse selection risk with operators.
- Hospitals:Outsourced emergency medical coverage contracts are expanding as health systems prioritize capital allocation toward clinical infrastructure over fleet ownership.
- Corporate Clients:Industrial site medical services and executive transport contracts operate on retainer-based pricing.
- Non-Governmental Organizations:Humanitarian and disaster response procurement follows grant-funded cycles with irregular payment timelines.
Government Agencies anchor contract backlogs. Insurance Providers are climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations govern medical device standards in the United States, the world's largest ambulance services market, while EU Green Deal mandates are reshaping fleet procurement across Germany, France, and the Netherlands. India's government-funded 108/102 helpline expansion is creating dedicated revenue streams for private operators in rural districts previously served by informal transport.
United States
Municipal 911 contracts and hospital system outsourcing are consolidating emergency medical coverage under regional operators. FAA airworthiness certification requirements for rotorcraft medical equipment impose 18-24 month validation timelines, structurally limiting air ambulance fleet expansion. The Southwest corridor from Phoenix to Houston anchors subscription-based emergency response membership growth in rural mining and agricultural communities.
Germany
EU Green Deal fleet electrification mandates are accelerating replacement cycles for municipal emergency vehicle tenders. KBA type-approval processes for battery-electric ambulances are compressing procurement timelines for integrated e-ambulance providers. The Ruhr industrial cluster and Bavarian hospital networks are piloting battery-swap infrastructure to circumvent charging downtime in dense urban cores.
India
Government-funded 108/102 helpline expansion is creating dedicated revenue streams for private ambulance networks in rural districts previously served by informal transport. CDSCO medical device registration requirements govern onboard cardiac monitors and ventilators deployed across state-level contracts. Maharashtra and Karnataka host technology-enabled dispatch operations that bridge geographic gaps between incident sites and definitive care facilities.
Australia
Subscription-based emergency response memberships are displacing per-use billing in Queensland and Alberta rural markets. TGA medical device standards structure equipment procurement for air ambulance rotorcraft serving remote mining communities. The Pilbara iron ore region and Darling Downs agricultural belt concentrate prepaid annual fee enrollment, transferring financial risk from insurers to service providers.
Switzerland
Swissmedic regulations and EU AI Act risk classification frameworks are reshaping dispatch software procurement for automated triage systems. Alpine air ambulance operators are delaying AI integration pending national implementation guidance on explainability and human oversight protocols. The Zurich-Geneva corridor anchors premium-tier medical evacuation services for cross-border inter-facility transfers.
Global Ambulance Services Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the ambulance services ecosystem. Integrated training academies and consolidated regional contracts define competitive positioning more than fleet scale alone. Three archetypes dominate: vertically integrated emergency response networks with captive training pipelines, technology-enabled dispatch platforms targeting fragmented emerging markets, and air ambulance specialists with FAA-certified rotorcraft operations. M&A consolidation among municipal contractors and strategic partnerships for battery-swap infrastructure represent the dominant competitive moves.
Among North American regional operators, Global Medical Response anchors consolidated coverage contracts across metropolitan corridors. Falck A/S exemplifies the integrated training academy model sustaining staffing levels across Scandinavian operations. Ziqitza Healthcare Limited occupies a distinctive position in India's fragmented emergency response landscape, representing the technology-enabled dispatch archetype with government-funded helpline contracts.
| Leading Market Players |
|---|
| Acadian Ambulance Service |
| Falck A/S |
| Global Medical Response |
| Air Methods Corporation |
| Envision Healthcare Corporation |
| Ziqitza Healthcare Limited |
| London Ambulance Service NHS Trust |
| Babcock International Group |
| America Ambulance Service |
| Others |
Supply & Pricing Matrix
Long-term municipal contracts with take-or-pay structures lock in fleet procurement commitments and stabilize revenue visibility for ambulance operators navigating EU Green Deal electrification timelines and lithium-ion battery cost volatility.
Pricing Analysis
German municipal tenders command 15-20% premiums over Indian state-level contracts for comparable advanced life support configurations. Pricing stratifies across premium, standard, and economy tiers based on crew certification intensity and equipment telemetry integration. Cost compression in patient transfer segments is intensifying because insurance reimbursement caps lag fleet electrification capital requirements. Government agencies exhibit lowest price sensitivity due to statutory response obligations, while corporate industrial site contracts face renegotiation pressure.
Supply Chain Analysis
Critical component lead times for cardiac monitors and ventilators now extend 14-18 months due to FDA 510(k) backlog accumulation. Manufacturing concentrates in China for lithium-ion cathode processing, Germany for specialized vehicle chassis, and the United States for FDA-cleared medical devices. Single-source vulnerability in Chinese refined lithium compounds exposes European operators to geopolitical supply interruptions. Distribution runs through hospital system procurement committees and municipal tender boards with multi-year award cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ambulance services market is approaching a platform-economics inflection where dispatch algorithm interoperability will determine competitive survival, as EU AI Act implementation fragments software procurement across national regulatory interpretations.
For Market Incumbents: Fortify staffing pipelines through captive training academy investments to offset paramedic workforce shortages capping expansion in US and UK metropolitan corridors. Deepen backward integration into battery-swap infrastructure to secure fleet uptime advantages during electrification transitions in Copenhagen and Amsterdam hospital networks.
For New Entrants and Emerging Players: Rural district dispatch technology gaps in India's 108/102 helpline expansion states present first-mover potential for cloud-based fleet management platforms. Penetrate Maharashtra and Karnataka through government-funded contract vehicles before incumbent dispatch system upgrades close the window. Lead with subscription-based membership models transferring financial risk from insurers to operators.
For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled dispatch platforms with proven government contract execution in fragmented emerging markets. Long-term viability hinges on regulatory compliance automation capabilities as EU AI Act risk classifications reshape software procurement. Watch for national implementation guidance divergence between early-adopter France and cautious Switzerland as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swap Infrastructure Partnership | Copenhagen hospital pilots demonstrate spatial competitive advantage in dense urban cores. |
| AI Dispatch Algorithm Certification | EU AI Act explainability requirements reshape procurement in France, Germany, and Italy. |
| Integrated Training Academy Acquisition | Falck A/S model sustains staffing levels across Scandinavian operations amid pipeline collapse. |
| Rural Helpline Contract Expansion | India's government-funded 108/102 expansion creates dedicated revenue streams in underserved districts. |
| Subscription Membership Model Launch | Queensland and Alberta rural households transfer financial risk from insurers to operators. |
Research Methodology
The analysis maps emergency response, air ambulance, patient transfer, and neonatal transport segments, each validated through ambulance fleet operators, municipal procurement officers, hospital system contracts managers, and biomedical equipment specialists. Primary interview data triangulates against secondary sources including FDA 510(k) device clearance databases, EU Green Deal implementation trackers, CDSCO medical device registrations, and municipal tender award disclosures. Bottom-up service volume estimates reconcile with top-down healthcare expenditure benchmarks.
Consistency checks against external regulatory filings and fleet procurement databases validated projection outputs across the analysis window. Segmentation dimensions include service intensity tier, vehicle life support capability, equipment technology class, and customer contracting authority. CAGRs derive from fitted growth curves incorporating electrification mandate compliance timelines and workforce pipeline constraints. Forecast inputs incorporate battery supply concentration risk and AI Act implementation trajectory assumptions.
Forecasts assume regulatory continuity in FDA device clearance, EU Green Deal fleet mandates, and EU AI Act risk classification regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
North America Ambulance Services Market
Emergency Medical Services
Global Ambulance Stretchers Market
Emergency Medical Services
Air Ambulance Market
Emergency Medical Services
Europe Air Ambulance Services Market
Emergency Medical Services
US Freestanding Emergency Department Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Global Emergency Medical Apps Market
Emergency Medical Services
Chest Compressors Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Air Ambulance Services Market