
 Global Ambulance Stretchers Market | 2026-2036
Global Ambulance Stretchers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ambulance Stretchers Market Foresight
Multi-source procurement for hydraulic lifting mechanisms is repositioning how ambulance OEMs manage supplier relationships. Stryker leverages its integrated manufacturing footprint across North American production facilities to control component quality. Ferno-Washington, Inc. anchors its market presence through specialized emergency transport designs that dominate North American fire department channels. Narang Medical Limited competes on cost-optimized aluminum alloy frames that serve price-sensitive municipal buyers across South Asia and the Middle East.
An ambulance stretcher is a patient-bearing platform mounted on a wheeled or fixed frame, typically constructed from aluminum alloy or carbon fiber composites with load ratings between 350 and 700 pounds, designed to immobilize and transport injured persons during pre-hospital emergency care. Electric stretchers now command premium positioning as EMS agencies prioritize powered hydraulic systems that reduce provider back injuries during patient loading. Manual stretchers sustain volume leadership in developing markets where capital constraints favor simpler mechanical designs. Carbon fiber materials represent the fastest-growing material segment as manufacturers pursue weight reduction for air medical services applications.
The FDA enforces Class II medical device controls over powered stretcher systems, requiring 510(k) premarket notification for devices with active electronic components used in patient transport. The EU Medical Device Regulation mandates notified body conformity assessment for ambulance stretchers sold within European Economic Area member states, with specific requirements for biocompatibility of patient contact surfaces. ISO 13485 quality management certification functions as a de facto market access threshold for suppliers serving institutional procurement channels across OECD markets. Stakeholders must monitor evolving electrical safety standards for battery-powered stretcher systems as lithium-ion powertrains penetrate emergency services fleets.
Market Dynamics
Powered hydraulic systems are displacing manual stretcher fleets across municipal EMS departments, driven by OSHA injury reporting requirements and workers' compensation cost pressures on ambulance operators.
Growth Catalysts
- EU Medical Device Regulation:The MDR's tightened structural testing protocols are accelerating fleet replacement cycles across German, French, and Italian ambulance services as older units fail notified body conformity assessments.
- Carbon fiber composites:Air medical services operators in the United States, Japan, and Switzerland are specifying lightweight patient platforms to extend helicopter range and payload flexibility.
- Municipal fleet aging:Aging ambulance chassis in Japan and Germany are triggering synchronized stretcher replacement programs as cities modernize emergency response capabilities.
Market Restraints
- Lithium-ion battery supply concentration:Battery cell production for powered stretcher systems concentrates in Chinese and South Korean manufacturing hubs, exposing OEMs to geopolitical supply disruptions and export control risks.
- Aluminum alloy price volatility:Manual stretcher frames remain vulnerable to London Metal Exchange aluminum price swings that compress margins for cost-optimized product lines serving South Asian municipal buyers.
- FDA 510(k) timeline friction:Class II medical device premarket notification requirements for powered systems with active electronic components extend product launch cycles by 12-18 months versus manual equivalents.
Strategic Opportunities
- India's PLI scheme:The Production Linked Incentive scheme for medical devices is attracting contract manufacturing investment for aluminum frame production serving Middle East and African price-sensitive markets.
- Battery-swappable architectures:Interchangeable powertrain modules are enabling EMS agencies to maintain continuous fleet readiness without dedicated charging infrastructure downtime.
- Remote patient monitoring integration:Stretcher-embedded telemetry systems that transmit vital signs during transport are creating new revenue streams through data service subscriptions.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for new market entrants frequently encounter non-conformances in design control documentation, delaying European market access.
- Biocompatibility testing bottlenecks:Patient contact surface material validation under EU MDR requirements is compressing R&D schedules as notified body capacity constraints extend assessment durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ambulance Stretchers Market |
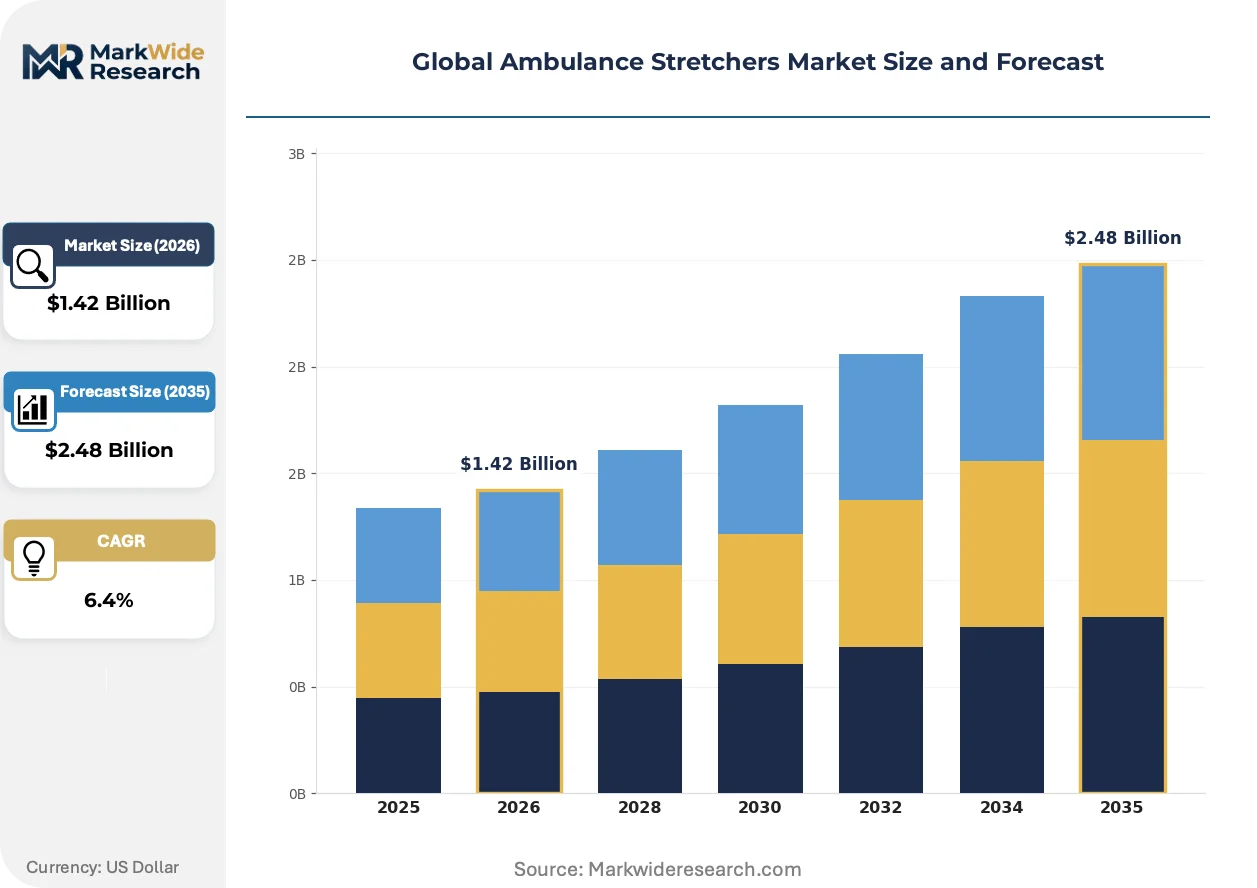
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Stretchers, Manual Stretchers, Wheeled Stretchers, Foldable Stretchers, Scoop Stretchers Material: Aluminum Alloy, Carbon Fiber, Steel, Plastic Composite, High-Density Foam Application: Emergency Medical Services, Patient Transport, Disaster Response, Military Evacuation, Tactical Rescue End User: Ambulance Operators, Fire Departments, Hospitals, Air Medical Services, Search & Rescue Units |
| Companies Covered | Baxter, FU SHUN HSING TECHNOLOGY CO., LTD, Stryker, ROYAX, Zhangjiagang New Fellow Med Co.,Ltd., Ferno-Washington, Inc., Narang Medical Limited, MAC Medical, Inc., Medline Industries, LP., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ambulance Stretchers Market Shifts & Advancements
Stretcher architecture is fragmenting into specialized configurations as distinct emergency transport modalities demand purpose-built patient platforms rather than universal designs.
Carbon fiber layup manufacturing is modularizing across air medical fleet procurement. Helicopter EMS operators in Switzerland, the United States, and Japan are specifying patient platforms below 85 pounds to maximize fuel range and medical equipment payload. This weight reduction is modularizing supplier relationships as airframe OEMs integrate stretcher structural elements directly into cabin engineering rather than sourcing standalone units.
The EU Medical Device Regulation's biocompatibility requirements for patient contact surfaces are forcing material substitutions across European production lines. Manufacturers serving German, French, and Italian markets are reformulating upholstery foams and coating systems to satisfy notified body assessments. Pediatric and bariatric stretcher segments face the steepest compliance costs due to extended skin contact duration specifications.
Subscription-based fleet refresh programs are displacing capital purchase models among US municipal EMS departments. Third-party equipment lessors are bundling stretcher maintenance, battery replacement, and technology upgrades into per-vehicle monthly fees. This financing shift is most visible in California, Texas, and Florida where municipal budget volatility favors operational expenditure treatment over bonded capital projects.
Global Ambulance Stretchers Market Segmentation
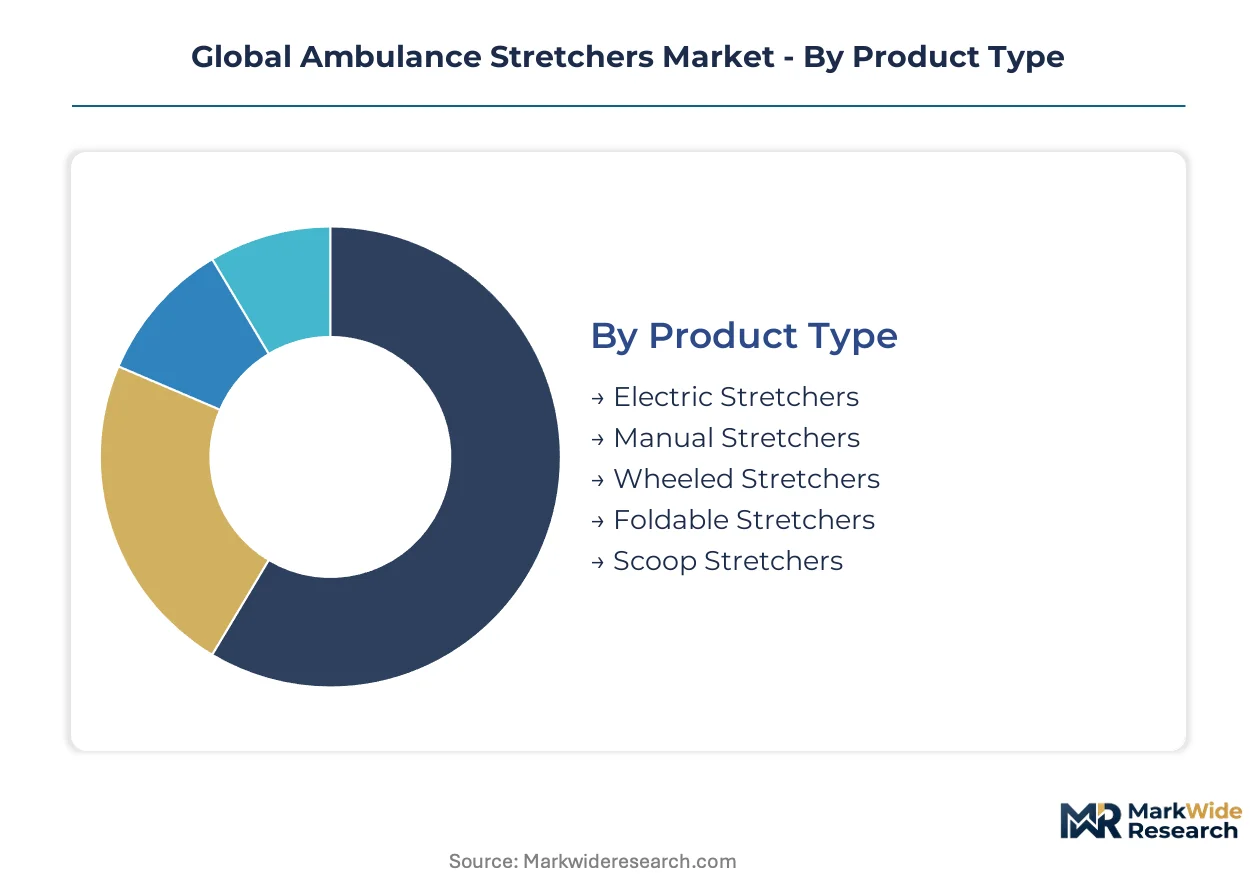
Stretcher procurement patterns fragment sharply across emergency transport modalities, with powered systems commanding premium positioning in municipal EMS fleets while manual configurations dominate price-sensitive municipal channels. Material selection and application context determine margin structures more than unit volume, creating distinct competitive arenas within what appears to be a unified product category.
Product Type:
Customization intensity varies from fully configurable powered platforms to standardized mechanical designs, with hydraulic sophistication driving the standardization spectrum.
- Electric Stretchers:Battery-powered hydraulic lifting systems with programmable height adjustment and powered loading mechanisms reduce provider musculoskeletal injuries during patient transfer. Demand concentrates in German and United States municipal EMS departments where OSHA injury reporting requirements and workers' compensation cost pressures justify capital expenditure premiums.
- Manual Stretchers:Mechanical lever and gas-spring assisted platforms constructed from aluminum tubing with manual height adjustment remain the volume standard across developing markets. Indian and Middle Eastern municipal buyers prioritize capital efficiency over ergonomic features, sustaining manufacturing scale for simplified mechanical architectures.
- Wheeled Stretchers:Fixed-frame transport platforms with integrated wheel systems designed for hospital corridor and ambulance bay movement rather than field deployment.
- Foldable Stretchers:Collapsible X-frame designs with fabric patient surfaces prioritize compact storage footprint for disaster response cache stockpiling and tactical medical kits.
- Scoop Stretchers:Split-platform designs that separate and rejoin beneath immobilized patients, minimizing spinal movement during transfer from confined spaces.
Leading the category by volume: Manual Stretchers. Growing fastest: Electric Stretchers.
Material:
Cost tier stratification separates aerospace-grade composites from commodity metal sourcing, with weight reduction commanding nonlinear price premiums in air medical applications.
- Aluminum Alloy:Extruded 6061-T6 or 7075-T6 aluminum tubing delivers strength-to-weight ratios adequate for 350-500 pound load ratings at moderate cost. Narang Medical Limited and similar suppliers serving South Asian and African markets anchor pricing competitiveness on optimized aluminum frame production under India's PLI scheme.
- Carbon Fiber:Pre-preg composite layup construction achieves patient platform weights below 85 pounds, extending helicopter fuel range and medical equipment payload capacity. Swiss and Japanese air medical operators specify carbon fiber platforms despite three-to-four-fold cost premiums over aluminum equivalents.
- Steel:Chromoly or stainless steel frames persist in bariatric applications exceeding 700-pound load ratings where deflection tolerance demands higher modulus materials.
- Plastic Composite:Glass-reinforced polymer structural elements reduce component count in scoop and foldable stretcher designs for mass-casualty cache applications.
- High-Density Foam:Patient contact surface cushioning materials face reformulation pressure under EU MDR biocompatibility requirements for extended skin contact duration.
Volume leadership: Aluminum Alloy. Steepest expansion trajectory: Carbon Fiber.
Application:
Customer type determines specification rigor, with regulated emergency medical services demanding certification depth that disaster response and tactical applications often bypass.
- Emergency Medical Services:Pre-hospital patient transport requiring ISO 13485-certified platforms with FDA 510(k) or EU MDR notified body conformity assessment. German, French, and Italian fleet replacement cycles dominate procurement volume as aging chassis trigger synchronized stretcher modernization.
- Patient Transport:Inter-facility non-emergency movement prioritizes cost efficiency over advanced features, with hospital-owned fleets favoring wheeled stretchers for corridor mobility.
- Disaster Response:Mass-casualty stockpiling favors foldable and scoop configurations that maximize unit density in strategic national reserves.
- Military Evacuation:Theater casualty transport specifications emphasize helicopter compatibility and rapid patient securing for combat medical evacuation.
- Tactical Rescue:Confined space and technical rescue applications demand compact collapsed dimensions and specialized patient immobilization features.
Dominant by procurement value: Emergency Medical Services. Accelerating most quickly: Disaster Response.
End User:
Procurement authority concentration varies from centralized municipal fleet management to fragmented hospital purchasing, reshaping vendor sales motion requirements.
- Ambulance Operators:Municipal and private EMS fleets with structured replacement cycles and subscription-based financing preferences in California, Texas, and Florida operational expenditure models.
- Fire Departments:North American fire-based EMS systems favor specialized emergency transport designs with rapid patient securing and extrication compatibility.
- Hospitals:Inpatient movement and emergency department intake platforms prioritize corridor maneuverability and infection control surface compatibility.
- Air Medical Services:Helicopter and fixed-wing operators in Switzerland, the United States, and Japan specify weight-optimized platforms with direct airframe integration.
- Search & Rescue Units:Wilderness and technical rescue teams prioritize compact packability and terrain portability over wheeled mobility.
Largest procurement volume: Ambulance Operators. Fastest specification evolution: Air Medical Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum alloy sourcing from Chinese and South Korean smelters underpins stretcher manufacturing economics across major demand centers. Battery cell production concentrates in East Asian manufacturing hubs, exposing OEMs to export control risks while European and North American fleets accelerate powered system adoption.
United States
Municipal EMS departments in California, Texas, and Florida are shifting toward subscription-based fleet financing models that treat stretcher procurement as operational expenditure. FDA Class II medical device controls enforce 510(k) premarket notification timelines that extend powered system launches by 12-18 months versus manual equivalents. Air medical operators in Arizona and Colorado specify carbon fiber platforms below 85 pounds to maximize helicopter payload capacity.
Germany
Aging municipal ambulance chassis across Bavaria and North Rhine-Westphalia are triggering synchronized stretcher replacement programs as cities modernize emergency response infrastructure. EU Medical Device Regulation notified body assessments are accelerating fleet turnover as older units fail tightened structural testing protocols. Stuttgart-based engineering clusters are integrating stretcher structural elements directly into helicopter cabin designs for air medical applications.
Japan
Metropolitan Tokyo and Osaka prefectures are replacing legacy manual stretcher fleets with powered hydraulic systems to address provider injury rates among aging EMS workforces. METI industrial standards align with ISO 13485 quality management requirements that function as de facto procurement thresholds for institutional buyers. Nagoya manufacturing corridors supply precision hydraulic components to domestic stretcher assemblers serving helicopter EMS operators in Hokkaido and Kyushu.
India
Price-sensitive municipal buyers in Maharashtra and Gujarat prioritize aluminum frame stretchers under the Production Linked Incentive scheme for medical devices. CDSCO medical device regulations are tightening quality benchmarks for export-oriented manufacturers serving Middle East and African markets. Chennai and Hyderabad production clusters are attracting contract manufacturing investment for cost-optimized frame fabrication.
Switzerland
Air medical services operators in the Alpine region command premium positioning for carbon fiber patient platforms that extend helicopter fuel range across mountainous terrain. Swissmedic conformity assessment requirements exceed baseline EU MDR standards for patient contact surface biocompatibility. Zurich and Geneva engineering centers are pioneering stretcher-embedded telemetry systems for vital sign transmission during high-altitude rescue operations.
Global Ambulance Stretchers Market Competitive Landscape
Global majors compete with regional champions across certification depth and manufacturing scale, producing a tiered structure where integrated North American players control premium municipal EMS channels while Asian fabricators dominate price-sensitive procurement. Three archetypes define competitive positioning: full-system integrators with captive hydraulic component production, specialized emergency transport designers with fire department channel dominance, and cost-optimized frame manufacturers leveraging government incentive schemes. Consolidation pressure is concentrating around backward integration into battery powertrain supply and geographic expansion through distributor partnerships in emerging markets.
Among North American-based integrators, Stryker and Ferno-Washington, Inc. exemplify divergent strategic postures within the premium tier. Stryker occupies a position anchored on integrated manufacturing footprints across domestic production facilities, while Ferno-Washington represents specialized emergency transport design heritage through fire department channel relationships. Narang Medical Limited sits within the cost-optimized archetype, leveraging Indian PLI scheme incentives to serve price-sensitive municipal buyers across South Asia and the Middle East.
| Leading Market Players |
|---|
| Baxter |
| FU SHUN HSING TECHNOLOGY CO., LTD |
| Stryker |
| ROYAX |
| Zhangjiagang New Fellow Med Co.,Ltd. |
| Ferno-Washington, Inc. |
| Narang Medical Limited |
| MAC Medical, Inc. |
| Medline Industries, LP. |
| Others |
Supply & Pricing Matrix
EU Medical Device Regulation biocompatibility mandates for patient contact surfaces are forcing material reformulations across European production lines, compelling manufacturers to absorb testing costs or pass through premiums while aluminum alloy sourcing from Indian PLI beneficiaries offers cost refuge for price-sensitive procurement.
Pricing Analysis
Warranty and battery replacement bundling separates subscription-based municipal fleet programs from transactional manual stretcher sales. Three-tier pricing structure across powered premium, ISO-certified standard, and economy aluminum tiers reflects certification depth and hydraulic sophistication. Cost compression in manual frames intensifies as Indian contract manufacturers scale under PLI incentives. Municipal EMS departments in Germany and the United States show lowest price sensitivity due to injury liability exposure, while South Asian municipal buyers anchor the economy tier.
Supply Chain Analysis
Precision machining workforce availability in Stuttgart and Nagoya corridors underpins hydraulic component quality for premium powered systems. Battery cell production draws from Chinese and South Korean manufacturing hubs, while aluminum extrusion feeds from Indian PLI clusters and Chinese smelters. Single-source vulnerability concentrates in lithium-ion powertrain supply for electric stretcher platforms. Distribution runs through specialized medical device distributors serving hospital purchasing committees and municipal fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powered hydraulic systems are displacing manual stretcher fleets across OECD markets, with battery-swappable architectures replacing legacy fixed-powertrain designs as the dominant technology transition.
For Market Incumbents: Deepen backward integration into battery powertrain supply to secure component availability against East Asian export control risks. Expand ISO 13485-certified production capacity in Germany and Japan to capture EU MDR-driven fleet replacement cycles. Ferno-Washington's fire department channel control and Stryker's captive hydraulic production illustrate defensive positioning against emerging Asian cost competitors. For New Entrants and Emerging Players: Battery-swappable modular architectures offer a technology-first wedge into municipal EMS subscription financing programs in California, Texas, and Florida. India's PLI scheme enables cost-optimized aluminum frame production for Middle East and African price-sensitive markets. Target air medical telemetry integration as a software service layer with lower certification barriers than hardware platforms. For Investors and Strategic Acquirers: The window for entry favors contract manufacturers with PLI scheme access and carbon fiber layup capabilities serving Swiss and Japanese helicopter EMS operators. Long-term viability hinges on regulatory certification depth rather than unit volume scale. Watch EU MDR notified body capacity constraints as the inflection signal for European market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell access against Chinese export control exposure for powered stretcher OEMs. |
| CE Marking Pathway | Unlocks German, French, and Italian municipal procurement under tightened EU MDR structural protocols. |
| Hospital System Partnership | Enables subscription fleet financing penetration in California, Texas, and Florida municipal EMS departments. |
| Software Companion Development | Creates telemetry revenue streams through stretcher-embedded vital sign transmission during transport. |
| Reimbursement Strategy | Aligns powered stretcher procurement with OSHA injury cost avoidance justification for municipal budget approval. |
Research Methodology
Trade data filings, EU Medical Device Regulation notified body assessment records, and municipal procurement databases formed the secondary backbone, cross-referenced with primary interviews involving EMS fleet managers, biomedical engineers, hospital purchasing committee members, and GPO contracts specialists. Bottom-up and top-down triangulation validated shipment volumes and pricing tiers across powered and manual product categories.
Bottom-up modeling anchored segment-level outputs to aluminum alloy sourcing costs and hydraulic component production capacity, while top-down constraints reflected regulatory approval timelines and fleet replacement cycle synchronization. Segmentation dimensions spanned product type, material grade, application context, and end-user procurement authority. CAGRs derived from installed base turnover rates and technology substitution curves, with air medical weight specifications and EU MDR compliance costs as key forecast inputs across the projection horizon.
Several conditions sit outside the modeled scope, including geopolitical trade disruption scenarios, raw material price spikes beyond historical volatility bands, and accelerated battery chemistry transitions. Forecasts reflect documented assumptions about regulatory stability and municipal budget continuity. A small set of named triggers warrants ongoing watch: EU MDR notified body capacity constraints, lithium-ion export control expansion, and Indian PLI scheme renewal terms.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency Medical Services
Adrenal Crisis Management Market
Emergency Medical Services
Global Ambulance Services Market
Emergency Medical Services
China First Aid Market
Emergency Medical Services
US Emergency Medical Transportation Market
Emergency Medical Services
South East Asia Ambulance Services Market
Emergency Medical Services
Patient Transport Services Market
Emergency Medical Services
Europe Ambulance Services Market
Emergency Medical Services
Air Ambulance Services Market
Emergency Medical Services
Urgent Care Market
Emergency Medical Services
Cardiopulmonary Resuscitation Market
Emergency Medical Services
Emergency Medical Services (EMS) Vehicle Market
Emergency Medical Services
Emergency Medical Services Market
Emergency Medical Services
Resuscitation Trolley Market
Emergency Medical Services
Global Fixed Wing Air Ambulance Service Market
Emergency Medical Services
First Aid Market
Emergency Medical Services
North America Ambulance Services Market