
 Wafer CMP Machine Market | 2026-2036
Wafer CMP Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Wafer CMP Machine Market Insights
Market Dynamics
Modular tool platforms that integrate polishing, cleaning, and metrology in single-footprint configurations is consolidating buyer preference as fabs prioritize throughput density over standalone unit flexibility. Applied Materials leverages its breadth in adjacent deposition and etch systems to anchor multi-process tool suites. Ebara Corporation sustains its position through specialized rotary table designs that dominate silicon wafer polishing. ACCRETECH competes on precision metrology integration that reduces wafer handling between process steps.
Technology and Segmentation
A wafer CMP machine performs chemical mechanical planarization, combining abrasive slurry chemistry with controlled mechanical pressure to achieve nanometer-level surface flatness on semiconductor substrates, typically operating at pressures of 1-10 psi and rotational speeds up to 150 rpm for 300mm wafers. Multi-Station CMP systems lead capital allocation as foundries adopt parallel processing architectures that boost wafer-per-hour throughput for advanced logic nodes. Silicon carbide CMP represents the fastest-growing material segment, driven by power electronics demand where substrate surface quality directly impacts device yield. Double-Side CMP occupies mature, stable demand from memory manufacturers polishing bulk silicon for 3D NAND stacks.
Regulatory Environment
EPA effluent guidelines in the United States and REACH chemical restrictions in Europe constrain slurry formulation choices, compelling equipment vendors to design compatible with lower-hazard chemistries. China's MEE enforces wastewater discharge limits that elevate demand for point-of-use slurry recycling modules. Japan's METI promotes domestic semiconductor reshoring through subsidies that favor capital equipment procurement. Stakeholders must monitor how regional chemical regulations fragment equipment specifications and whether modular platform designs can absorb compliance diversity without proliferating SKUs.
Market Dynamics
Foundry consolidation around 300mm advanced-node production is concentrating equipment procurement decisions into fewer hands, shifting bargaining power toward buyers who demand modular platforms with integrated metrology and cleaning functions.
Growth Catalysts
- Silicon carbide power electronics:Electric vehicle inverters and renewable energy converters require substrate surface quality that only precision CMP can deliver, pulling equipment orders from automotive and energy sectors.
- China's dual carbon goals:Stricter MEE effluent standards are compelling domestic fabs to retrofit closed-loop slurry recycling systems onto existing polishers.
- 3D NAND stacking:Memory manufacturers polishing bulk silicon for 128-layer and higher architectures are sustaining double-side CMP tool demand even as logic foundries migrate to multi-station architectures.
Market Restraints
- Specialized consumables concentration:Proprietary pad and slurry formulations lock fabs into single-source supply relationships, inflating lifetime ownership costs beyond initial equipment capex.
- EPA effluent guideline compliance:US-based manufacturers face restricted chemistry options that limit process window flexibility and slow recipe qualification timelines.
- Rotary table precision limits:Mechanical tolerances in conventional spindle designs create planarization non-uniformity at sub-7nm nodes, forcing premature equipment replacement cycles.
Strategic Opportunities
- India's semiconductor PLI scheme:Subsidized fab construction in Gujarat and Karnataka will create first-mover equipment installation opportunities as domestic manufacturing capacity scales from negligible baseline.
- Metrology-AI convergence:Real-time endpoint detection fused with machine learning algorithms enables predictive pad replacement and slurry dosing optimization.
- Aftermarket service unbundling:Third-party refurbishment and upgrade services for installed base machines are capturing margin previously retained by original manufacturers.
Industry Challenges
- Process engineer scarcity:The specialized knowledge required to tune slurry chemistry, pressure profiles, and pad conditioning for new materials outpaces technical training program output.
- Legacy tool integration:Brownfield fabs running 200mm equipment struggle to network older polishers with modern factory automation systems without custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wafer CMP Machine Market |
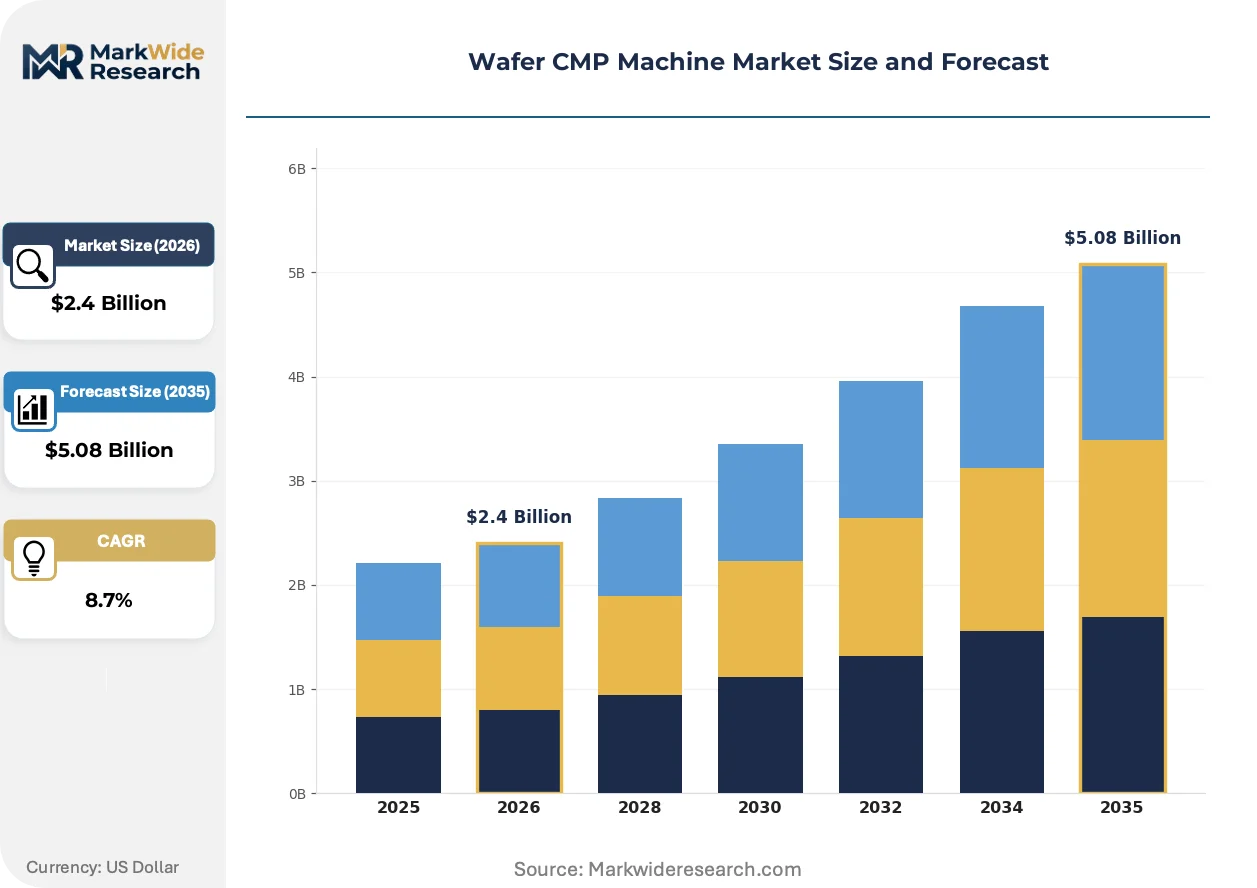
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Side CMP, Double-Side CMP, Multi-Station CMP, Advanced CMP Material: Silicon, Gallium Nitride, Sapphire, Silicon Carbide End User: Semiconductor Manufacturers, Electronics Firms, Research Institutions, Foundries Deployment: On-Premises, Cloud-Based, Hybrid, Mobile |
| Companies Covered | Applied Materials, Ebara Corporation, ACCRETECH, KC Tech, Revasum, DuPont, Logitech, Tianjin Huahaiqingke, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wafer CMP Machine Market Trends and Innovations
Equipment architectures are converging around single-footprint multi-function cells that compress wafer handling overhead, while regulatory chemistry constraints and AI-enabled process control are simultaneously reshaping how polishers operate and how fabs justify capital allocation.
Real-time spectroscopic endpoint detection is automating polish stop decisions that previously required operator judgment or fixed-time recipes. Leading-edge foundries in Taiwan and South Korea are deploying these systems across 300mm lines to reduce over-polish damage on fragile low-k dielectrics. This shift is automating yield protection while compressing the skill premium previously commanded by veteran process technicians.
REACH chemical restrictions in Europe are forcing slurry reformulation toward lower-hazard abrasives and oxidizers, compelling equipment vendors to redesign fluid handling systems for corrosivity and particle stability profiles that differ from legacy chemistries. Polishers destined for European fabs now ship with upgraded seal materials and redundant containment features that add cost but ensure compliance. Memory manufacturers with pan-regional footprints are responding by segmenting their chemistry supply chains rather than pursuing universal formulations.
Consolidated procurement by semiconductor super-majors is displacing fragmented buying patterns that previously sustained regional equipment distributors. Direct manufacturer relationships now dominate transactions above defined contract thresholds, with foundry engineering teams embedding into vendor roadmapping processes. This concentration is most visible in East Asian manufacturing clusters where three buyers account for the majority of annual multi-station CMP orders.
Wafer CMP Machine Market Segmentation
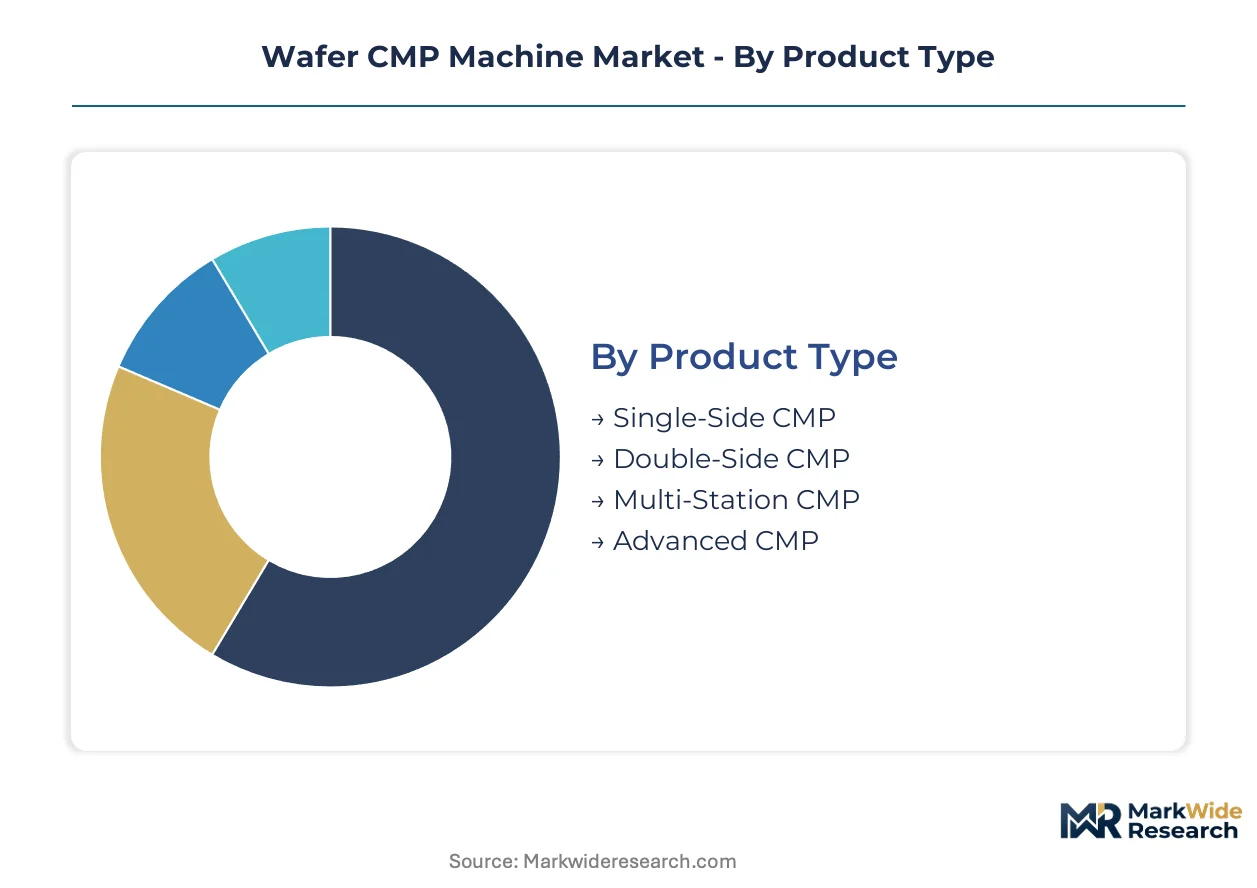
Equipment architectures diverge sharply between high-volume memory production and precision logic manufacturing, with substrate material choices now pulling specialized polishing configurations. Segmentation clarity enables fabs to match capital deployment against specific process windows rather than overspecifying generic platforms.
Product Type:
Volume throughput commands premium pricing in foundry procurement, while specialized configurations serve niche substrate requirements.
- Multi-Station CMP:Parallel processing architectures deploy multiple polishing heads on shared platen systems, compressing wafer-per-hour metrics for advanced logic nodes at Taiwan Semiconductor Manufacturing and Samsung Foundry. Leading-edge fabs in Hsinchu and Pyeongtaek concentrate procurement here as 3nm and 2nm ramp schedules accelerate.
- Double-Side CMP:Simultaneous front-and-back surface processing dominates bulk silicon preparation for 3D NAND memory stacks, where substrate thickness uniformity determines subsequent layer alignment precision. SK Hynix and Micron Technology sustain stable demand even as logic foundries migrate toward multi-station alternatives.
- Single-Side CMP:Entry-level configurations polish one wafer surface at a time for research prototyping and legacy node production.
- Advanced CMP:Integrated platforms combine polishing with in-situ metrology and cleaning modules for sub-7nm dielectric planarization.
Mature deployment sits with Double-Side CMP. Newer deployment is concentrated in Multi-Station CMP.
Material:
Substrate hardness and chemical reactivity dictate pad conditioning recipes, slurry abrasives selection, and endpoint detection algorithms.
- Silicon Carbide:Extreme hardness and chemical stability challenge conventional polishing mechanics, requiring diamond-abrasive slurries and specialized pad materials for power electronics substrates. Wolfspeed and ON Semiconductor fabs in Durham and Jeonju drive equipment orders as electric vehicle inverter demand climbs.
- Silicon:Decades of process refinement support mature consumables ecosystems and predictable removal rates across 300mm logic and memory lines.
- Gallium Nitride:RF device manufacturers polish epitaxy-ready surfaces for 5G base station amplifiers.
- Sapphire:LED substrate producers and specialty optical applications require alumina-based slurry formulations.
Silicon Carbide commands the steepest expansion trajectory as wide-bandgap power electronics displace silicon in automotive traction inverters.
End User:
Capital intensity and process sophistication stratify buyers into volume manufacturers versus specialized research operators.
- Foundries:Pure-play contract manufacturers like TSMC and GlobalFoundries consolidate the largest equipment procurement volumes, specifying modular platforms with rapid recipe changeover capabilities. Their multi-node production schedules demand polishers qualified across diverse material stacks from silicon to silicon-germanium.
- Semiconductor Manufacturers:Integrated device operators including Intel and Texas Instruments maintain captive polishing capacity for proprietary process flows.
- Electronics Firms:System houses with captive fab operations source limited configurations for internal component supply.
- Research Institutions:Universities and national laboratories acquire refurbished or entry-level systems for materials science exploration.
Foundries capture the majority of new equipment shipments. Research Institutions depend heavily on secondary market availability.
Deployment:
Physical equipment location versus remote process control architectures segment buyer preferences by fab automation maturity.
- On-Premises:Traditional installed-base configurations dominate semiconductor manufacturing where wafer handling robotics and cleanroom integration preclude remote operation. All leading-edge production occurs through locally controlled polishers with factory host connectivity.
- Hybrid:Some memory manufacturers pilot cloud-connected metrology data streams while retaining local control over polishing mechanics.
- Cloud-Based:Process recipe libraries and predictive maintenance algorithms reside on external servers, though actual polishing execution remains edge-located.
- Mobile:Containerized or trailer-mounted configurations serve temporary production needs and field demonstration purposes.
On-Premises deployment anchors current production. Hybrid architectures are gaining traction fastest among memory manufacturers modernizing legacy fabs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian fabs consume the majority of wafer CMP machine output, while equipment manufacturing concentrates among Japanese and American vendors. This geographic split between production and consumption shapes regional procurement patterns and regulatory compliance requirements.
Taiwan
TSMC and United Microelectronics Corporation drive multi-station CMP procurement for 3nm and 2nm logic ramps at Hsinchu and Tainan Science Parks. The island's EPA enforces wastewater discharge standards that elevate closed-loop slurry recycling adoption. Kaohsiung's emerging advanced packaging cluster is pulling additional polishing capacity for chiplet integration processes.
South Korea
Samsung Foundry and SK Hynix sustain dual demand vectors for logic multi-station systems and memory double-side configurations at Pyeongtaek and Icheon complexes. MFDS chemical safety regulations intersect with MEE-aligned effluent protocols at China-facing joint ventures. Seoul's equipment engineering ecosystem is deepening local service capabilities for Japanese and American tool vendors.
China
Domestic foundries including SMIC and Hua Hong Semiconductor are expanding 300mm capacity in Shanghai and Beijing despite technology access constraints. MEE wastewater discharge limits are compelling retrofits of point-of-use slurry recycling modules onto existing polishers. Yangtze River Delta manufacturing clusters are prioritizing energy-efficient polishers aligned with dual carbon goals.
United States
Intel's Arizona and Oregon fabs anchor captive polishing demand for advanced node development, while Wolfspeed's Durham, North Carolina facility drives silicon carbide CMP orders for automotive power electronics. EPA effluent guidelines constrain slurry formulation choices, limiting process window flexibility. Applied Materials maintains headquarters and R&D operations in Santa Clara, California.
Japan
Ebara Corporation and ACCRETECH anchor domestic equipment supply from Tokyo and Kanagawa prefectures. METI semiconductor reshoring subsidies favor capital equipment procurement for Kioxia's Yokkaichi and Kitakami memory fabs. Kyoto-Osaka industrial corridors concentrate precision component suppliers for rotary table and metrology module manufacturing.
Wafer CMP Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies between scale-driven integrated tool suite providers, precision component specialists, and regional fabrication houses serving emerging markets. Three archetypes dominate: diversified process equipment conglomerates leveraging cross-selling synergies; precision mechanics specialists with captive rotary table or metrology technologies; and regional challengers competing on localized service and pricing. Consolidation pressures favor M&A activity among mid-tier specialists, while technology licensing agreements proliferate as fabs demand interoperable modular platforms.
Among diversified equipment conglomerates, Applied Materials exemplifies the integrated tool suite archetype through its breadth across deposition, etch, and planarization systems. Ebara Corporation occupies a specialist position anchored in precision rotary table designs that dominate silicon wafer polishing applications. ACCRETECH represents the precision metrology integration tier, competing through reduced wafer handling between process steps. These three companies illustrate the competitive spectrum from broad platform breadth to deep component specialization.
| Leading Market Players |
|---|
| Applied Materials |
| Ebara Corporation |
| ACCRETECH |
| KC Tech |
| Revasum |
| DuPont |
| Logitech |
| Tianjin Huahaiqingke |
| 3M Company |
| Others |
Pricing and Supply Chain Analysis
Foundry consolidation around TSMC, Samsung, and SK Hynix concentrates procurement leverage into three buyer archetypes that command contract-based long-term offtake pricing with volume-scaled discounts. This buyer concentration forces equipment vendors to absorb chemistry compliance costs and extended service obligations into headline pricing, compressing margin buffers across multi-station and double-side CMP platforms.
Pricing Analysis
Margin tightening in standard-tier equipment reflects foundry demands for bundled slurry recycling modules and predictive maintenance software. Three-tier pricing structure across premium, standard, and economy levels segments by metrology integration depth and automation sophistication. Cost-down pressure on economy-tier polishers accelerates because Chinese domestic vendors compete aggressively on localized service coverage. Memory manufacturers exhibit highest price sensitivity due to cyclical capital allocation constraints, while advanced logic foundries prioritize throughput density over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale foundry demand, bypassing regional distributors that previously served fragmented procurement. Precision rotary table manufacturing concentrates in Japan, with specialized metrology module sourcing from Germany and South Korea. Fluid handling systems draw from Taiwan and United States component suppliers. Single-source vulnerability in diamond-abrasive slurry formulations for silicon carbide polishing creates chokepoint exposure as Wolfspeed and ON Semiconductor expand substrate capacity. Distribution runs through manufacturer-direct relationships with embedded engineering support teams at major fab complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wafer CMP equipment procurement functions as a cost-of-compliance story where China's MEE wastewater discharge limits and EPA effluent guidelines erect regulatory moats favoring vendors with pre-certified chemistry compatibility and closed-loop system integration.
For Market Incumbents: To counter emerging Chinese domestic vendors with subsidized pricing, Applied Materials and Ebara Corporation should deepen captive supply of proprietary pad conditioning hardware and endpoint detection algorithms. Certification investment for REACH-compliant and MEE-aligned slurry handling architectures preserves pricing power in European and Chinese tenders. Capacity addition in Taiwan and South Korea service hubs reinforces response-time advantages for multi-station CMP uptime guarantees. For New Entrants and Emerging Players: Cloud-connected predictive maintenance platforms offer a digital-channel route to penetrate memory manufacturer hybrid deployment architectures without challenging established foundry relationships. India's semiconductor PLI scheme creates the most penetrable geography for first-mover equipment installation. Targeting aftermarket refurbishment services for 200mm legacy tool installed bases avoids direct competition with integrated tool suite incumbents. For Investors and Strategic Acquirers: The window for entry favors precision metrology specialists with AI-enabled endpoint detection capabilities that foundries now specify as mandatory. Long-term viability centers on vendors capable of spanning silicon carbide, gallium nitride, and silicon substrate polishing with modular platform architectures. Watch for inflection signals in automotive power electronics capacity announcements from Wolfspeed and ON Semiconductor as silicon carbide CMP demand accelerators.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Slurry Recycling Integration | MEE wastewater compliance in Chinese fabs mandates point-of-use recycling module attachment to existing polishers. |
| AI-Enabled Endpoint Detection Deployment | Real-time spectroscopic polish stop automation protects fragile low-k dielectrics at TSMC and Samsung 3nm lines. |
| Silicon Carbide Polishing Platform Development | Diamond-abrasive slurry compatibility captures Wolfspeed and ON Semiconductor automotive inverter substrate orders. |
| Aftermarket Service Capability Buildout | Third-party refurbishment captures margin from installed base machines at brownfield memory fabs. |
| India Manufacturing Footprint Establishment | Gujarat and Karnataka PLI-subsidized fab construction creates first-mover equipment installation opportunities. |
Research Methodology
Document review covered SEC 10-K filings, equipment vendor technical specifications, and foundry capex disclosure reports, complemented by interviews with semiconductor process engineers, fab procurement directors, and slurry chemistry formulators. Secondary validation drew from Taiwan EPA discharge records, China's MEE environmental compliance databases, and Japan METI subsidy program documentation. Bottom-up triangulation against individual fab equipment procurement schedules and top-down reconciliation with aggregate capital expenditure forecasts ensured cross-verified outputs.
Unit shipment and revenue projections across the analysis window employed segmented modeling by product type, substrate material, and end-user category. The framework incorporated tool replacement cycles for sub-7nm node transitions, silicon carbide substrate polishing adoption curves in automotive power electronics, and regional regulatory compliance cost premiums. CAGRs were derived from equipment shipment visibility into announced foundry and memory fab construction timelines, with sensitivity testing for technology access restriction scenarios affecting Chinese domestic capacity expansion.
The model holds under sustained foundry capital intensity and stable chemical regulatory frameworks; deviation in export control regimes or abrupt node transition delays would shift replacement cycle timing. Forecasts reflect base-case assumptions regarding silicon carbide power electronics penetration and dual carbon policy enforcement stringency. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Unscrambling Machine Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
SMT Machine Market
Semiconductor Equipment
Global Semiconductor Etch Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
APAC Die Attach Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Global Semiconductor Wafer Polishing and Grinding Equipment Market
Semiconductor Equipment
Global Laser Dicing Systems Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
FOUP Cleaning System Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market