
 8-Inch Silicon Carbide (Sic) Wafer Market | 2026-2036
8-Inch Silicon Carbide (Sic) Wafer Market Size, Share, and Industry Trends Forecast 2026-2036
8-Inch Silicon Carbide (Sic) Wafer Market Insights
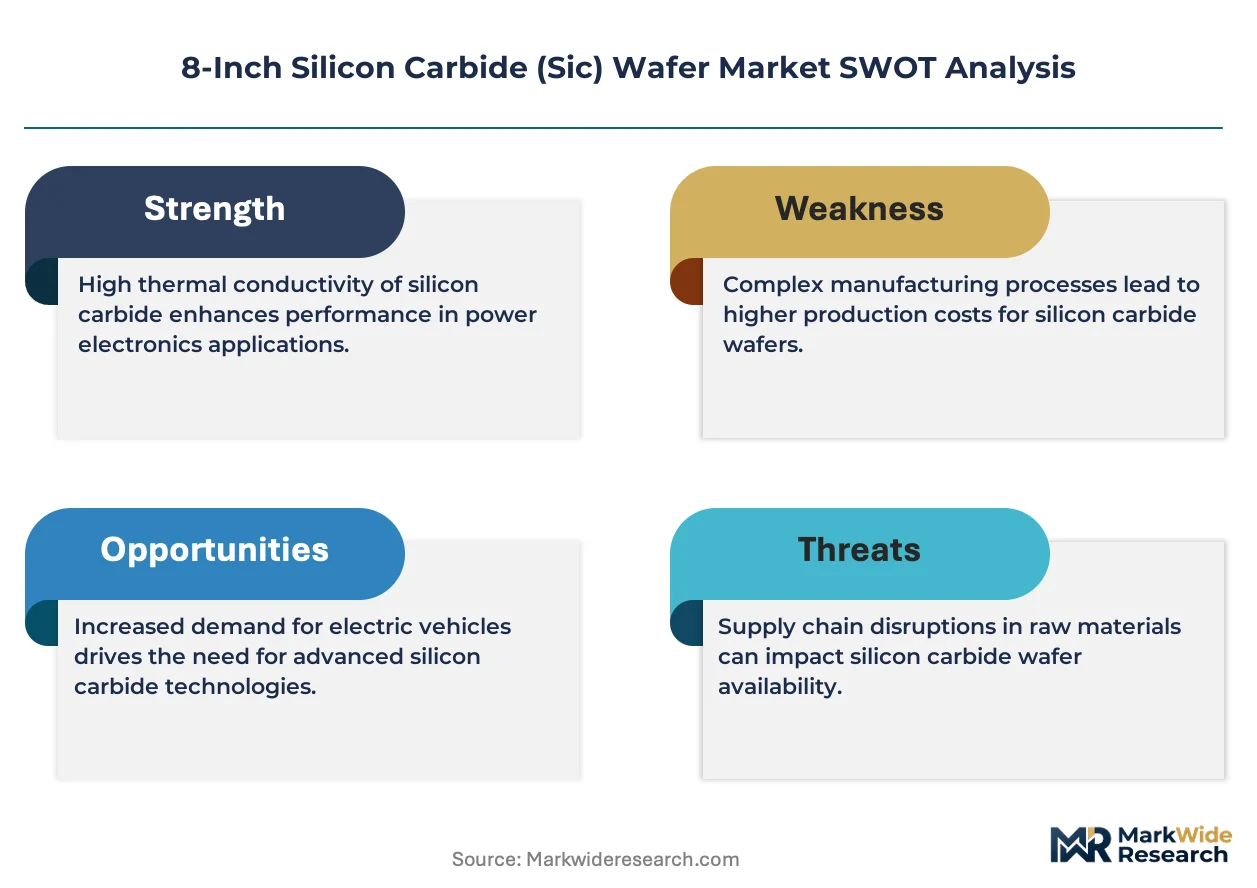
AEC-Q101 automotive qualification is reorganizing the competitive landscape for 8-inch SiC wafer suppliers, as only firms meeting this reliability standard gain design-in access to tier-one automotive semiconductor programs. Wolfspeed, Inc. leverages its vertically integrated materials-to-device architecture to sustain early-mover advantage in 8-inch substrate production. Infineon Technologies AG anchors European supply security through captive SiC crystal growth investments. Coherent Corp. specializes in materials science breadth spanning SiC, GaN, and optical substrates, differentiating its wafer offerings across multiple compound semiconductor platforms.
An 8-inch silicon carbide wafer is a single-crystal substrate 200 mm in diameter, typically grown through physical vapor transport from high-purity SiC powder and polished to epi-ready surface roughness below 0.5 nm RMS, serving as the foundation for fabricating high-voltage power devices operating above 600 V. Epitaxial wafers command the dominant value share within product type segmentation because device manufacturers require controlled doping profiles that only homoepitaxial growth on polished substrates can deliver. Power electronics applications absorb the largest volume of 8-inch SiC wafers, though renewable energy systems represent the fastest-growing demand pool as utility-scale solar inverters and wind converters adopt silicon carbide for efficiency gains.
The U.S. EPA and NHTSA coordinate fuel economy and emissions rules that effectively mandate SiC adoption in vehicle electrification, while China's MIIT sets GB standards for new energy vehicle components that specify wide-bandgap semiconductor performance benchmarks. REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor manufacturing, shaping material purity requirements and process chemistry choices across the supply chain. Stakeholders must monitor qualification timelines for automotive-grade 8-inch substrates, as the gap between substrate availability and device certification will determine which suppliers capture volume commitments from power module integrators.
Market Dynamics
The transition from 6-inch to 8-inch SiC wafer manufacturing is compressing unit economics for power device fabricators, as larger substrates yield more die per wafer and reduce edge-loss inefficiencies that have constrained cost parity with silicon IGBTs.
Growth Catalysts
- EU F-Gas Regulation:Phase-down schedules for fluorinated greenhouse gases are accelerating automotive OEM adoption of SiC-based inverters, as wide-bandgap semiconductors enable refrigerant-free thermal management systems in electric powertrains.
- China's dual carbon goals:Provincial manufacturing subsidies and grid modernization mandates are concentrating 8-inch wafer demand in domestic EV and solar inverter supply chains, with MIIT production quotas favoring local substrate producers.
- Physical vapor transport advances:Crystallization process improvements are reducing micropipe defect densities below 0.1 cm⁻², enabling AEC-Q101 qualification yields that meet automotive reliability thresholds.
Market Restraints
- High-purity SiC powder supply concentration:Sublimation-grade source material production clusters in Japan and the United States, creating input cost volatility and single-source dependency for emerging wafer manufacturers.
- Substrate thickness uniformity limitations:Bow and warp control across 200 mm diameters remains technically constrained, forcing device fabricators to accept higher polishing overhead or reduced active area utilization.
- Silicon superjunction MOSFET substitution:Mature silicon technology below 600 V applications continues to capture cost-sensitive industrial motor drive segments where SiC efficiency gains do not justify price premiums.
Strategic Opportunities
- India's PLI scheme for semiconductors:Production-linked incentives for compound semiconductor fabs are opening greenfield 8-inch SiC capacity opportunities for equipment and materials suppliers targeting BIS-certified domestic supply chains.
- Offshore wind converter applications:MW-scale turbine power electronics represent an emerging demand pool where 8-inch wafer scale enables integrated gate-driver modules that reduce converter footprint and cooling system mass.
- GaN-on-SiC RF convergence:Epitaxial wafer producers with multi-platform capability can cross-leverage 8-inch SiC substrate investments to serve 5G base station and radar applications with unified crystal growth infrastructure.
Industry Challenges
- AEC-Q101 certification timeline compression:Automotive qualification cycles spanning 18-24 months create revenue recognition delays for substrate suppliers racing to secure design-in commitments ahead of 2027-2028 EV platform launches.
- Epitaxial reactor technician scarcity:Homoepitaxial growth expertise for 8-inch diameter control is concentrated among a limited pool of process engineers, constraining rapid capacity scaling for new market entrants.
- Legacy 6-inch tool repurposing friction:Equipment compatibility gaps between substrate generations force capital-intensive greenfield investments rather than incremental capacity expansion at existing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 8-Inch Silicon Carbide (Sic) Wafer Market |
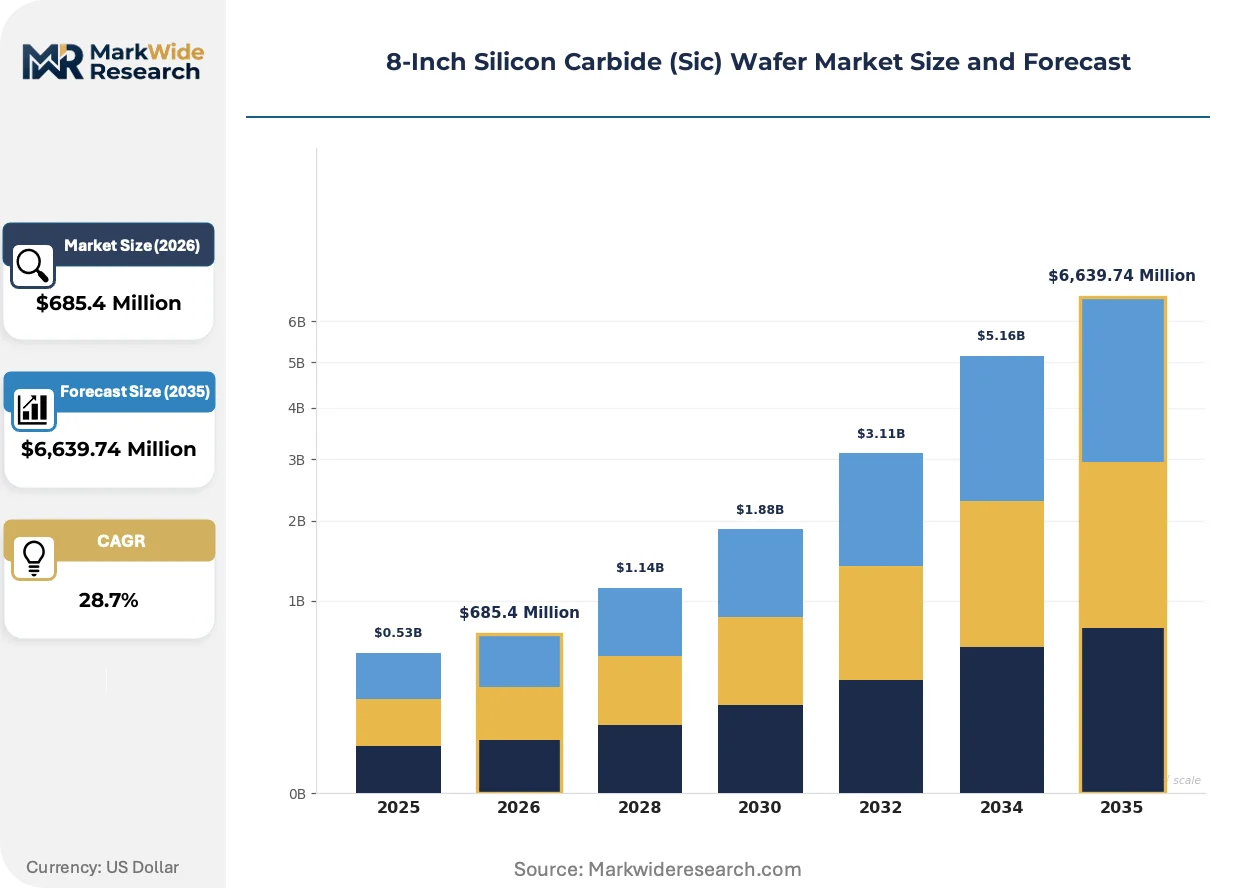
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $6,639.74 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Wafer, Double Side Polished Wafer, Epitaxial Wafer, Protective Wafer End User: Telecommunications, Automotive Electronics, Consumer Electronics, Industrial Equipment Application: Power Electronics, High Frequency Devices, LED Technology, Renewable Energy Systems Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Wolfspeed, Inc., Infineon Technologies AG, STMicroelectronics, onsemi, ROHM Co., Ltd., Coherent Corp., Sumitomo Electric Industries, Ltd., Hebei Synlight Crystal Co., Ltd., TankeBlue Semiconductor Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
8-Inch Silicon Carbide (Sic) Wafer Market Trends and Innovations
Wafer processing technology is bifurcating between established physical vapor transport methods and emerging liquid-phase growth techniques, with equipment suppliers and substrate manufacturers placing competing bets on which platform will dominate 8-inch volume production by decade's end.
Hot-wall chemical vapor deposition for thick epitaxial layers is fragmenting the equipment supply base, as device manufacturers demand 10-20 μm drift layers for 1200 V applications that exceed conventional single-wafer reactor throughput. Tier-one automotive semiconductor programs in Germany and Japan are qualifying multi-wafer planetary reactors that sacrifice some uniformity for 3x throughput gains. This technology is fragmenting vendor consolidation patterns that prevailed during the 6-inch era, enabling Asian equipment specialists to capture share from established European suppliers.
The EU F-Gas Regulation's 2030 phase-down targets are tightening refrigerant containment requirements for automotive thermal systems, indirectly mandating SiC inverter efficiency gains that reduce cooling loads. European OEMs are specifying 8-inch wafer provenance in supplier agreements to secure regulatory-compliant supply chains under REACH substance traceability rules. Power module integrators in Stuttgart and Munich are responding by consolidating qualified substrate sources to three or fewer approved vendors per program.
Direct procurement contracts between automotive powertrain divisions and substrate manufacturers are displacing merchant wafer distribution channels that mediated 6-inch supply. Device fabricators in China and South Korea are negotiating multi-year volume commitments with crystal growers to lock in 8-inch allocation ahead of competitor qualification. This pattern is most visible in the Yangtze River Delta, where domestic EV OEMs have established captive semiconductor procurement offices co-located with wafer production facilities.
8-Inch Silicon Carbide (Sic) Wafer Market Segmentation
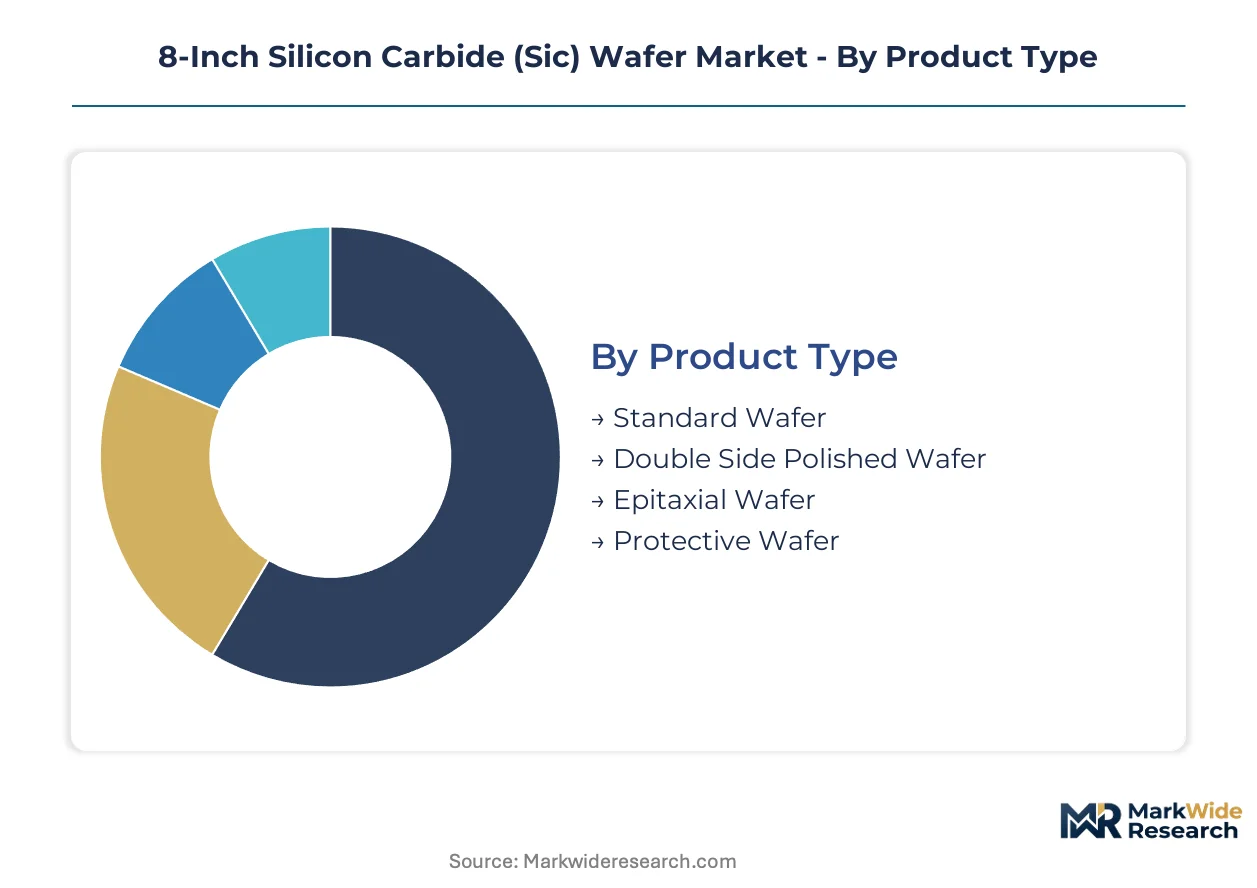
8-inch SiC wafer procurement patterns diverge sharply across product grades and end-use verticals. Device manufacturers select substrate specifications based on voltage class requirements and thermal management constraints, while distribution channels consolidate around direct relationships for automotive qualification programs.
Product Type:
Domestic Chinese fabs absorb the majority of standard and protective wafer volumes, whereas epitaxial wafer demand concentrates in export-led supply chains serving European and Japanese automotive semiconductor programs.
- Epitaxial Wafer:Homoepitaxial layers grown via chemical vapor deposition deliver controlled doping profiles essential for 1200 V power devices. German and Japanese power module integrators specify these wafers exclusively for traction inverter platforms, with AEC-Q101 qualification timelines driving procurement urgency.
- Standard Wafer:Polished single-crystal substrates without epitaxial coating serve cost-sensitive industrial motor drives and basic power conversion applications. Chinese domestic EV supply chains source these heavily from local Yangtze River Delta producers under MIIT production quota frameworks.
- Double Side Polished Wafer:Sub-micron surface roughness on both faces enables flip-chip packaging configurations for high-frequency RF modules.
- Protective Wafer:Sacrificial substrates shield active wafers during high-temperature processing steps in compound semiconductor foundries.
Epitaxial wafer commands the established base. The steepest expansion runs through standard wafer as Chinese capacity scaling accelerates.
End User:
Cost tier stratification separates premium automotive qualification programs from volume-driven consumer electronics procurement, with telecommunications occupying a mid-tier position on reliability requirements.
- Automotive Electronics:Traction inverters, onboard chargers, and DC-DC converters in battery electric vehicles demand AEC-Q101 qualified substrates with defect densities below 0.1 cm⁻². European OEMs in Stuttgart and Munich specify 8-inch provenance under REACH traceability rules.
- Telecommunications:5G base station power amplifiers and RF front-end modules utilize SiC's thermal conductivity for high-frequency operation. South Korean network equipment manufacturers source through direct procurement contracts rather than merchant distribution.
- Consumer Electronics:Premium laptop chargers and gaming power supplies adopt SiC for compact form factors, though silicon superjunction MOSFETs retain cost advantages below 600 V.
- Industrial Equipment:Motor drives, welding equipment, and uninterruptible power supplies represent mature demand with slower substrate size migration from 6-inch legacy tools.
Automotive electronics anchors revenue concentration. Telecommunications is climbing the fastest as 5G infrastructure deployment accelerates wide-bandgap semiconductor adoption.
Application:
Volume scale separates high-unit power electronics from emerging renewable energy systems, where project-based procurement creates lumpy demand patterns distinct from steady automotive consumption.
- Power Electronics:Inverters, converters, and rectifiers operating above 600 V constitute the dominant application, with device fabricators in China and South Korea negotiating multi-year volume commitments to lock substrate allocation.
- Renewable Energy Systems:Utility-scale solar inverters and offshore wind converters adopt SiC for efficiency gains that reduce cooling system mass. MW-scale turbine power electronics in the North Sea represent an emerging demand pool where 8-inch scale enables integrated gate-driver modules.
- High Frequency Devices:Radar systems and satellite communications exploit SiC's wide bandgap for microwave amplification.
- LED Technology:Solid-state lighting applications utilize SiC substrates for thermal management in high-power emitters.
Power electronics holds the volume base. Renewable energy systems is gaining share fastest as offshore wind capacity targets tighten converter efficiency requirements.
Distribution Channel:
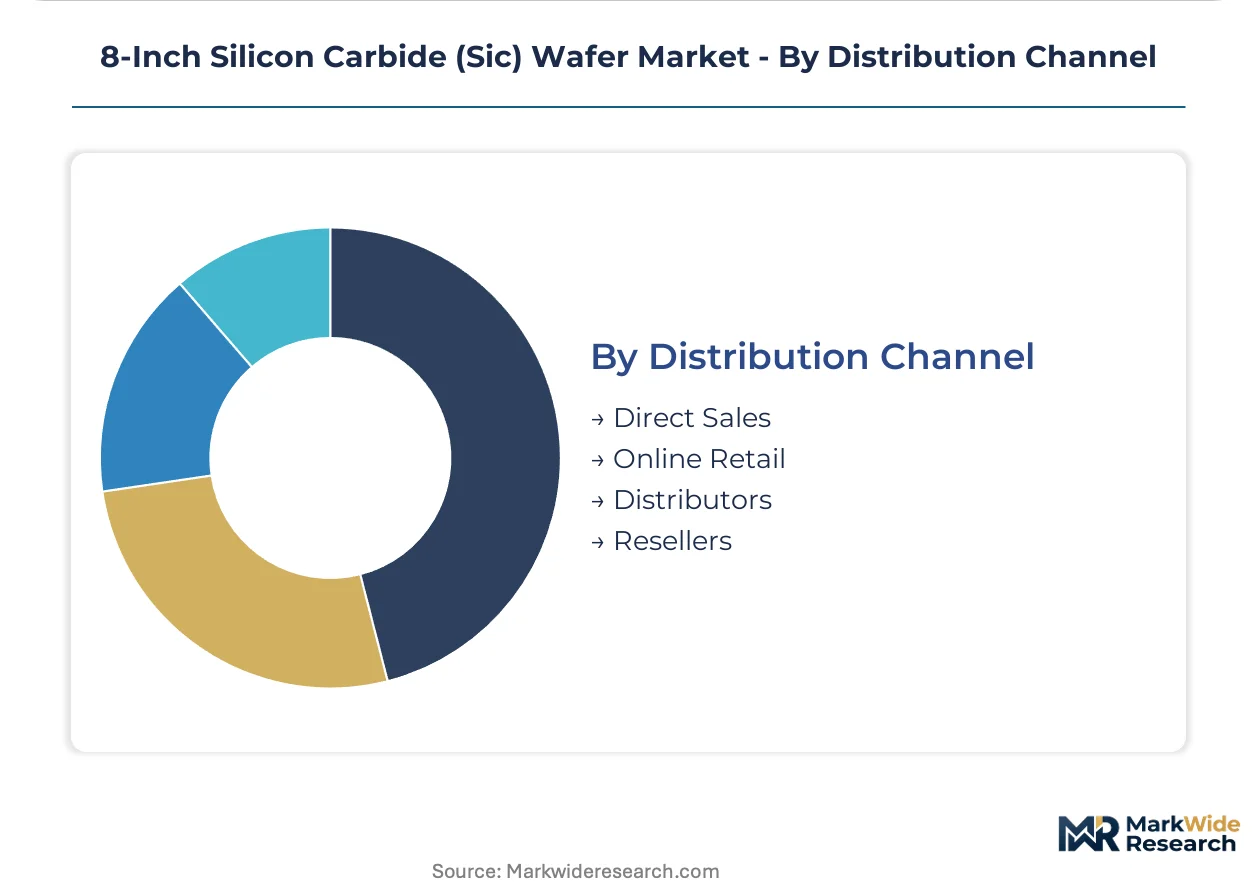
Customer type fragmentation drives channel bifurcation, with tier-one automotive programs demanding direct manufacturer relationships while smaller industrial buyers retain distributor intermediaries.
- Direct Sales:Substrate manufacturers negotiate long-term supply agreements directly with automotive powertrain divisions and power module integrators. This channel is displacing merchant wafer distribution that mediated 6-inch supply.
- Distributors:Authorized distributors maintain inventory positions for qualified industrial and consumer electronics customers requiring shorter lead times than direct contracts permit.
- Online Retail:Small-volume research institutions and prototype developers source samples through specialized semiconductor materials marketplaces.
- Resellers:Secondary market participants broker excess inventory and discontinued product lines for legacy equipment maintenance.
Direct sales commands the established base. Distributors is expanding most quickly as mid-tier industrial customers qualify 8-inch alternatives to silicon IGBTs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive powertrain procurement offices concentrate demand in three distinct geographies: China for volume scale, Germany for qualification rigor, and the United States for defense-adjacent supply security. Each market shapes substrate specifications through divergent regulatory frameworks and industrial cluster dynamics.
China
Domestic EV OEMs in the Yangtze River Delta drive the steepest capacity scaling globally, with provincial manufacturing subsidies under MIIT production quotas favoring local crystal growers. GB standards for new energy vehicle components mandate wide-bandgap semiconductor performance benchmarks that 8-inch substrates must meet. Shanghai and Suzhou host co-located procurement offices where automotive powertrain divisions negotiate multi-year volume commitments directly with wafer manufacturers.
Germany
Stuttgart and Munich anchor European demand through tier-one automotive semiconductor programs requiring REACH traceability compliance for substrate provenance. The EU F-Gas Regulation's phase-down schedules accelerate SiC inverter adoption by mandating refrigerant-free thermal management systems. Bavarian power module integrators consolidate qualified suppliers to three or fewer approved vendors per platform to secure regulatory-compliant supply chains.
United States
EPA and NHTSA coordinated fuel economy rules effectively mandate SiC adoption in vehicle electrification programs, while defense applications impose additional supply security requirements. Domestic crystal growth investments concentrate in North Carolina and New York state to reduce import dependency for sublimation-grade source material. Wolfspeed's vertically integrated materials-to-device architecture exemplifies the captive production model favored by procurement officers.
Japan
METI industrial policy supports SiC substrate development through joint research consortia linking automotive OEMs with crystal growth specialists. High-purity SiC powder production clusters in Osaka and Nagoya create input cost advantages for established wafer manufacturers. JIS standards for power semiconductor reliability shape qualification timelines that device fabricators must navigate for design-in access.
South Korea
Network equipment manufacturers in Seoul and Busan source 8-inch epitaxial wafers for 5G base station power amplifiers through direct procurement contracts rather than merchant distribution. MFDS semiconductor industry guidelines intersect with automotive export requirements as domestic EV platforms scale. Samsung and SK Group affiliates negotiate substrate allocation ahead of competitor qualification to secure supply for integrated device manufacturing.
8-Inch Silicon Carbide (Sic) Wafer Market Competitive Landscape
Player mix skews toward vertically integrated materials-to-device specialists and captive crystal growth investors. The market structure concentrates around firms controlling sublimation-grade powder supply and epitaxial reactor throughput. Three archetypes dominate: integrated device manufacturers with backward substrate control, pure-play crystal growers serving merchant demand, and diversified materials science platforms spanning multiple compound semiconductors. Competitive moves center on AEC-Q101 qualification racing and multi-year automotive supply agreement locking.
Among vertically integrated specialists, Wolfspeed, Inc. and Infineon Technologies AG occupy positions defined by captive crystal growth investments and automotive qualification depth. Coherent Corp. represents the diversified materials science archetype, leveraging substrate capabilities across SiC, GaN, and optical platforms. STMicroelectronics and onsemi exemplify device manufacturers deepening upstream control to secure 8-inch allocation ahead of 2027-2028 EV platform launches. These five firms anchor the competitive structure, with Chinese crystal growers including Hebei Synlight Crystal Co., Ltd. and TankeBlue Semiconductor Co., Ltd. scaling capacity to serve domestic procurement concentration.
| Leading Market Players |
|---|
| Wolfspeed, Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| onsemi |
| ROHM Co., Ltd. |
| Coherent Corp. |
| Sumitomo Electric Industries, Ltd. |
| Hebei Synlight Crystal Co., Ltd. |
| TankeBlue Semiconductor Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
200 mm substrate scale economies compress unit costs for AEC-Q101 qualified wafers while concentrating supply leverage among crystal growers with captive sublimation-grade powder production. This dynamic simultaneously elevates price floors for automotive-grade material and squeezes margins for merchant wafer vendors locked into long-term offtake agreements.
Pricing Analysis
Cost-plus contracts with high-purity SiC powder indexation dominate procurement between Japanese source material suppliers and wafer manufacturers. Pricing stratifies across AEC-Q101 automotive certification tiers, standard industrial grades, and unqualified development volumes. Cost compression in standard-grade wafers is intensifying because Chinese domestic capacity scaling under MIIT production quotas floods the merchant market. Industrial motor drive integrators exhibit the highest price sensitivity, while German automotive powertrain divisions accept premiums for REACH-traceable provenance.
Supply Chain Analysis
Inventory buffers for sublimation-grade powder rarely exceed eight weeks given batch-to-batch purity variability, forcing just-in-time coordination between Osaka-based chemical suppliers and crystal growth facilities. Supply concentrates in China, Japan, and the United States for finished wafers, with high-purity source material production anchored in Japan and the United States. The chain draws from silicon metal, carbon feedstock, and specialized graphite crucible inputs. Single-source vulnerability for powder supply creates qualification risk for emerging wafer manufacturers. Distribution runs through direct manufacturer relationships for automotive programs, with authorized distributors serving qualified industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Epitaxial reactor technician scarcity and AEC-Q101 qualification bottlenecks constrain capacity expansion faster than capital deployment, creating asymmetric returns for firms that secured process expertise early.
For Market Incumbents: Secure captive sublimation-grade powder supply through backward integration into Japanese or domestic chemical production, insulating against input cost volatility that threatens merchant competitors. Lock multi-year direct procurement agreements with Stuttgart and Munich automotive powertrain divisions before 2027-2028 EV platform launches consolidate supplier pools to three approved vendors per program. Prioritize hot-wall CVD reactor throughput expansion to capture thick epitaxial layer demand for 1200 V applications. For New Entrants and Emerging Players: Technical service gaps in 8-inch epitaxial process transfer and yield ramp support create white-space opportunities for equipment-software hybrid offerings targeting Chinese domestic fabs scaling under provincial subsidy programs. India's PLI scheme for compound semiconductors offers the most penetrable geography, with BIS certification requirements favoring greenfield entrants over legacy tool repurposing. Pursue joint development agreements with Yangtze River Delta procurement offices co-located with wafer production facilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diversified materials science platforms with multi-platform epitaxial capability spanning SiC, GaN, and optical substrates, enabling cross-leverage of crystal growth infrastructure. Long-term viability across the projection horizon rests on AEC-Q101 certification depth rather than substrate volume alone. Watch for inflection when direct procurement contracts displace the final merchant distribution channels in European automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sublimation-Grade Powder | Secures input cost stability against Japanese supply concentration for emerging wafer manufacturers. |
| Multi-Wafer Planetary Reactor Deployment | Captures 3x throughput gains for thick epitaxial layers demanded by German automotive programs. |
| AEC-Q101 Certification Acceleration | Unlocks design-in access to tier-one power module integrators in Stuttgart and Munich. |
| Direct Procurement Office Co-Location | Locks volume commitments from Yangtze River Delta EV OEMs ahead of competitor qualification. |
| GaN-on-SiC RF Platform Extension | Cross-leverages 8-inch substrate investments to serve South Korean 5G base station demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with epitaxial process engineers, automotive powertrain procurement managers, crystal growth facility directors, and power module integrators in Germany, China, and Japan. Secondary validation drew from MIIT production quota filings, EPA-NHTSA coordinated rulemaking dockets, EU F-Gas Regulation implementation reports, and SEC disclosures from vertically integrated device manufacturers. Bottom-up wafer demand modeling and top-down semiconductor capital expenditure tracking were triangulated to reconcile volume estimates.
Across the analysis window, the forecasting framework modeled segmentation by product type, end user vertical, application voltage class, and distribution channel structure. CAGRs were derived from installed base growth in battery electric vehicles, renewable energy inverter deployment, and substrate size transition timelines. Key inputs included AEC-Q101 qualification yield assumptions, epitaxial reactor capacity utilization rates, and provincial manufacturing subsidy disbursement patterns in China.
Underlying assumptions cover sustained automotive electrification program commitments, REACH and RoHS regulatory continuity, and high-purity powder supply stability, with deviation risk concentrated in tariff exposure for Japanese source material and faster-than-expected silicon superjunction MOSFET substitution below 600 V. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Thin Layer Deposition Market
Semiconductor Fabrication
Physical Vapor Deposition (PVD) Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Vapor Deposition Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Etchant for FPD Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Global Foundry Service Market
Semiconductor Fabrication
Diamond Semiconductor Substrates Market
Semiconductor Fabrication
Global Dry Etching Machine Market
Semiconductor Fabrication
Semiconductor Logistics Market