
 China Discrete Semiconductors Market | 2026-2036
China Discrete Semiconductors Market Size, Share, and Industry Trends Forecast 2026-2036
China Discrete Semiconductors Market Insights
The bifurcation between automotive-grade and consumer-grade discrete semiconductors is hardening in China. STMicroelectronics NV leverages its SiC MOSFET portfolio to anchor premium positioning in EV traction inverters. Silan Microelectronics competes aggressively on cost at the 8-inch foundry level for white-goods IGBT modules. Yangjie Electronic Technology specializes in rectifier diodes for LED lighting and small appliance segments.
Discrete semiconductors are individual circuit elements such as diodes, transistors, and thyristors fabricated from silicon or compound semiconductor substrates, typically handling voltage ratings from tens to thousands of volts and switching frequencies up to the megahertz range. Their primary purpose is power conversion, signal conditioning, and circuit protection across electronic systems. MOSFET and IGBT technology segments command the dominant margin pools due to EV and industrial motor control demand, while GaN devices represent the fastest-growing technology tier despite current volume limitations. The automotive end user segment leads absolute value generation, whereas power supply applications retain the broadest cross-industry footprint.
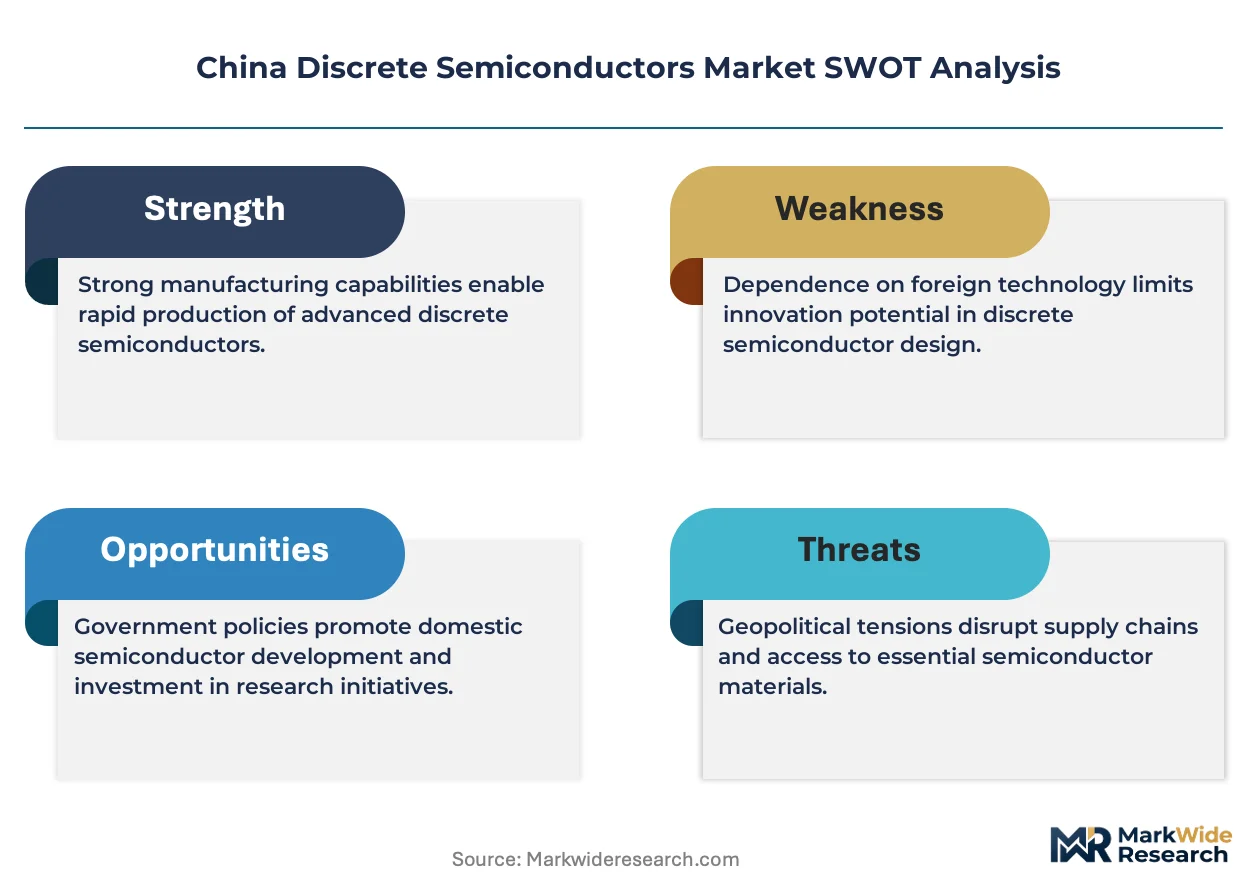
MIIT's dual carbon goals and GB standards for energy efficiency are tightening product certification requirements for power semiconductors sold into domestic markets. NMPA alignment with automotive functional safety protocols affects qualification timelines for vehicle-grade discrete components. SAMR enforcement of anti-monopoly provisions in semiconductor distribution channels is altering how foreign suppliers structure local partnerships. Stakeholders must monitor whether domestic substrate capacity expansion outpaces design house capabilities.
Market Dynamics
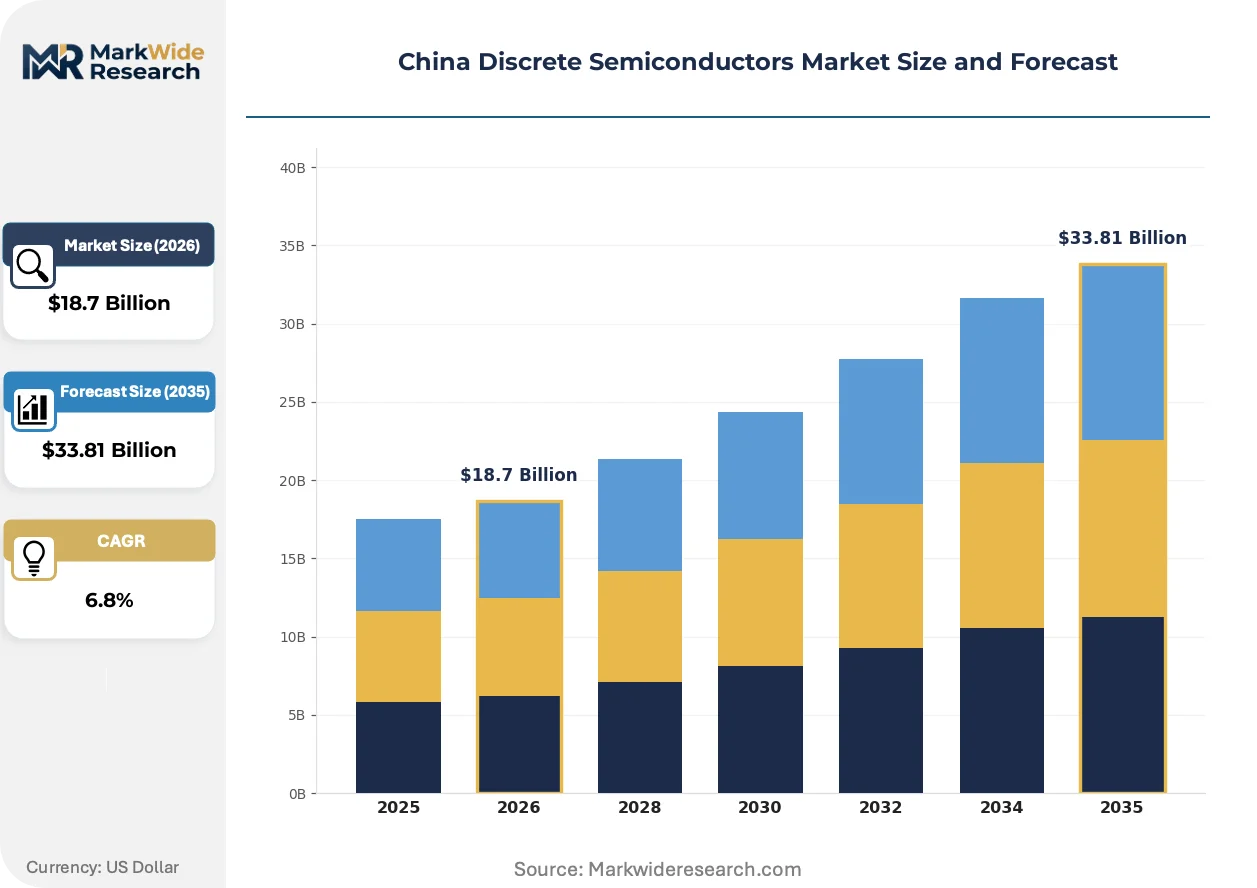
Domestic silicon carbide substrate capacity expansion is restructuring supplier-buyer power dynamics across China's discrete semiconductor value chain. MIIT's dual carbon mandates and NMPA automotive functional safety protocols are accelerating qualification timelines while compressing margins for non-compliant producers.
Growth Catalysts
- New energy vehicle powertrain electrification:Tier-1 automotive suppliers in the Yangtze River Delta cluster are expanding SiC MOSFET procurement for traction inverters and onboard chargers.
- MIIT dual carbon goals:GB standards for energy efficiency are mandating higher-performance power semiconductors across industrial motor drives and grid infrastructure.
- 8-inch foundry scaling:Domestic fabrication investments in Jiangsu and Zhejiang provinces are reducing cost structures for IGBT modules serving white-goods manufacturers.
Market Restraints
- Silicon carbide substrate supply concentration:Domestic 6-inch SiC wafer output remains insufficient for design house demand, forcing reliance on limited qualified suppliers.
- Technical limitation in epitaxy yield:Defect density in thick SiC epitaxial layers constrains high-voltage MOSFET die yields above 1200V ratings.
- SAMR anti-monopoly enforcement:Distribution channel restructuring requirements are increasing compliance costs for foreign suppliers structuring local partnerships.
Strategic Opportunities
- Underpenetrated renewable energy storage:Grid-scale battery inverters in western provinces present untapped demand for high-frequency GaN power devices.
- MIIT industrial internet initiative:Smart factory mandates are creating embedded power module demand for motor control and sensor interfaces.
- Technology convergence of SiC and GaN:Hybrid power stage architectures combining SiC diodes with GaN HEMTs are opening premium positioning in server power supplies.
Industry Challenges
- Automotive functional safety certification timeline:NMPA alignment with ISO 26262 protocols extends qualification cycles for vehicle-grade discrete components by 12-18 months.
- Capex intensity in test and burn-in infrastructure:Automotive-grade reliability screening requires capital deployment in high-temperature reverse bias and humidity testing equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Discrete Semiconductors Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diodes, Transistors, Thyristors, Rectifiers End User: Consumer Electronics, Automotive, Industrial, Telecommunication Technology: Bipolar, MOSFET, IGBT, GaN Application: Power Supply, Signal Processing, Motor Control, Radio Frequency |
| Companies Covered | STMicroelectronics NV, On Semiconductor Corporation, Vishay Intertechnology Inc., Infineon Technologies AG, Renesas Electronics Corporation, China Resources Microelectronics, Silan Microelectronics, Texas Instruments Inc., Yangjie Electronic Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Discrete Semiconductors Market Trends and Innovations
SiC MOSFET technology is compressing the performance gap between silicon and wide-bandgap semiconductors across voltage classes. Device architecture evolution and substrate quality improvements are enabling new application entry points previously blocked by cost or reliability constraints.
Silicon carbide MOSFETs handle voltage ratings from 650V to 1700V with switching frequencies exceeding 100kHz in hard-switched topologies. Tier-1 automotive suppliers in Shanghai and Jiangsu provinces are adopting these devices for 800V EV traction inverters at accelerated procurement cycles. This transition is electrifying the competitive landscape for incumbent silicon IGBT suppliers while compressing margin pools at legacy voltage nodes.
MIIT's GB standards for energy efficiency in power electronics are tightening minimum performance thresholds for semiconductors sold into domestic industrial markets. Manufacturers must now certify conduction and switching losses against benchmark curves to qualify for government procurement preference. The industrial motor drive segment faces the steepest compliance curve, with domestic suppliers accelerating R&D spending to meet 2025 implementation deadlines.
Direct sourcing relationships between automotive OEMs and discrete semiconductor foundries are displacing traditional distribution channels for high-volume programs. Tier-1 suppliers in Zhejiang province are negotiating wafer-level contracts with domestic 8-inch fabs, bypassing authorized distributors for IGBT and MOSFET procurement. This channel compression is most visible in the new energy vehicle supply chain, where annual volume commitments exceed 10 million units.
China Discrete Semiconductors Market Segmentation
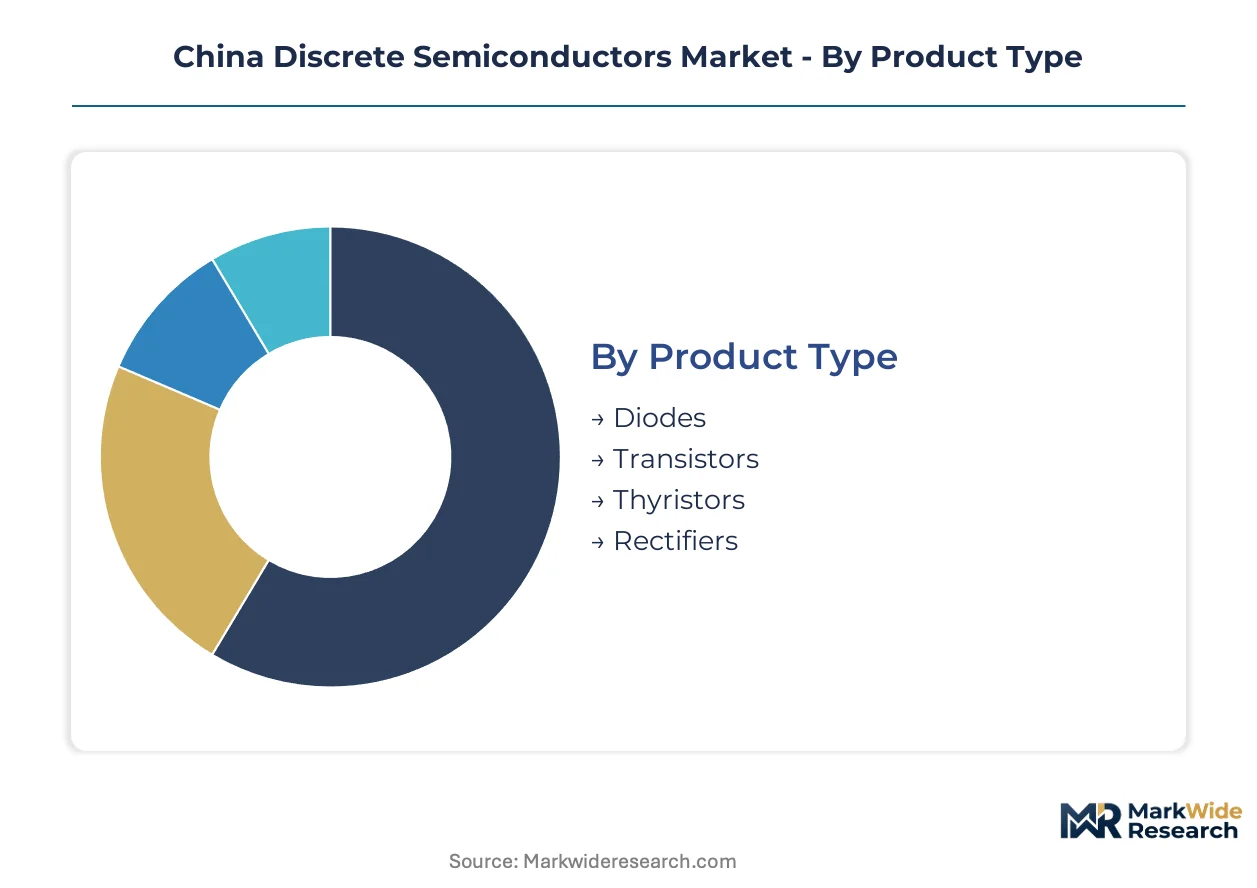
Discrete semiconductor procurement in China diverges sharply by voltage class, switching frequency, and certification grade. Buyers in the Yangtze River Delta cluster prioritize automotive-grade SiC devices, while cost-sensitive white-goods manufacturers dominate silicon IGBT volumes.
Product Type:
Cost tier separates commodity rectifiers from premium wide-bandgap switches in domestic procurement patterns.
- Diodes:Silicon and SiC junction devices handle rectification and freewheeling functions across voltage ratings from 600V to 1700V. LED lighting manufacturers in Guangdong province drive standardized rectifier diode demand, while EV onboard charger suppliers in Jiangsu specify SiC Schottky variants for efficiency gains.
- Transistors:Bipolar junction and field-effect architectures govern current flow in switching applications. MOSFET transistors for server power supplies in Shanghai data centers command premium pricing against commodity BJTs serving small appliance controllers in Zhejiang.
- Thyristors:Phase-controlled silicon devices manage high-current AC switching in industrial motor drives and traction systems.
- Rectifiers:Bridge and single-cell configurations convert AC to DC across consumer, industrial, and automotive auxiliary systems.
Diodes lead volumes today; transistors are gaining share fastest.
End User:
Application maturity determines whether buyers accept extended qualification cycles or demand immediate availability.
- Automotive:NMPA functional safety protocols and 800V platform proliferation are reshaping supplier qualification requirements. Tier-1 traction inverter manufacturers in the Yangtze River Delta cluster source SiC MOSFETs through direct foundry contracts, bypassing traditional distribution channels for high-volume programs.
- Industrial:MIIT GB standards for motor drive efficiency mandate upgraded power semiconductor specifications. Factory automation suppliers in Jiangsu province face compressed margins as compliance deadlines approach.
- Consumer Electronics:Smartphone charger and white-goods controller demand concentrates in cost-optimized silicon MOSFETs.
- Telecommunication:Base station power amplifiers and network infrastructure rely on RF-optimized discrete devices.
Industrial applications anchor current procurement volumes; automotive is climbing the fastest.
Technology:
Substrate material and bandgap properties create divergent margin structures across the supplier base.
- MOSFET:Silicon and silicon carbide metal-oxide-semiconductor field-effect transistors dominate switching applications below 200kHz. Domestic 8-inch foundries in Zhejiang province are scaling planar and trench silicon MOSFET output for white-goods IGBT module integration.
- IGBT:Insulated-gate bipolar transistors merge MOSFET input impedance with bipolar conduction losses for motor drives. Industrial equipment manufacturers in Jiangsu specify 1200V and 1700V modules for variable-frequency drives.
- Bipolar:Traditional junction transistors and Darlington configurations persist in cost-sensitive linear applications.
- GaN:Gallium nitride high-electron-mobility transistors enable megahertz switching in compact power supplies.
IGBT technology commands the largest installed base; GaN is expanding most quickly.
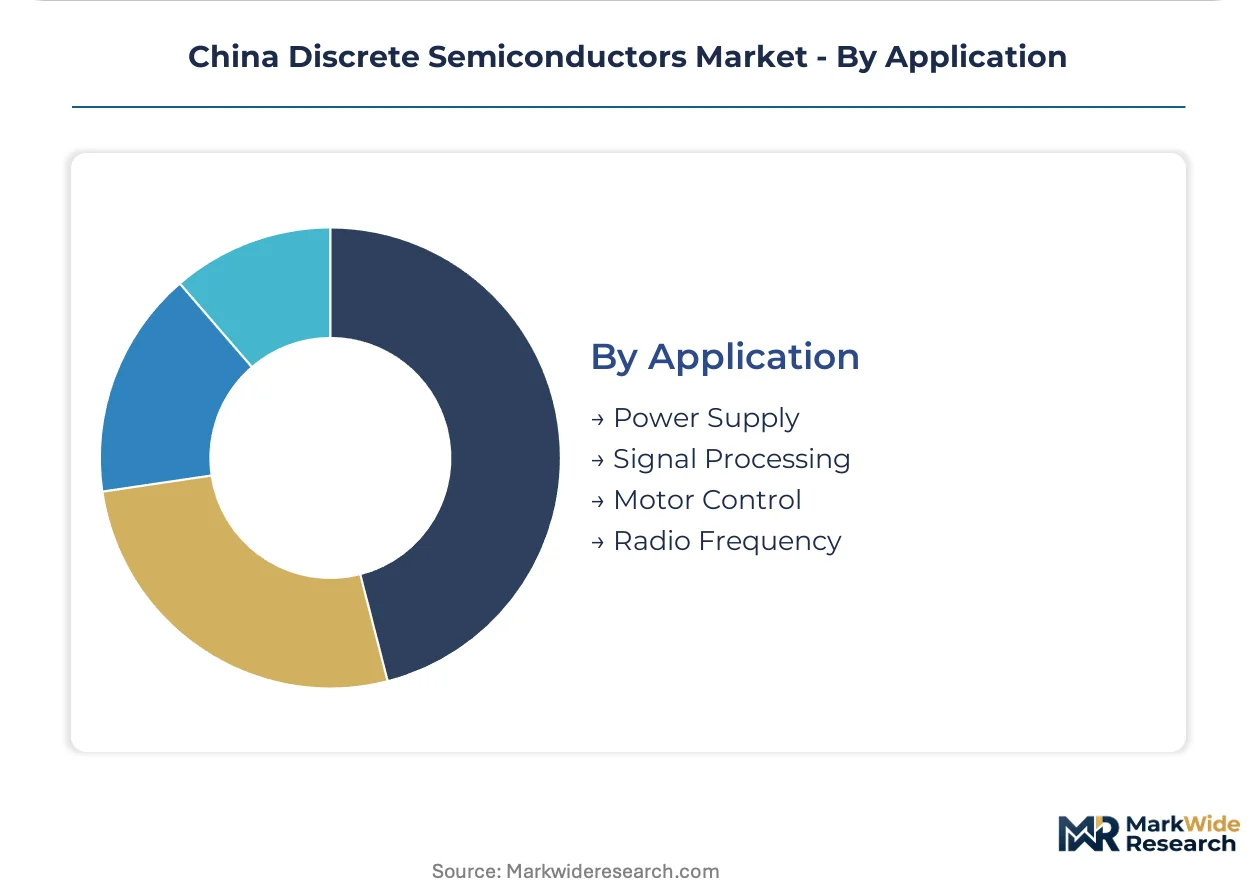
Application:
Voltage and frequency requirements segment buyers by thermal management complexity and system architecture.
- Power Supply:AC-DC and DC-DC conversion circuits span adapter, server, and EV charger topologies. Server PSU manufacturers in Shanghai are evaluating hybrid SiC-GaN power stages for titanium efficiency certification.
- Motor Control:Variable-speed drives for industrial and appliance motors depend on IGBT and SiC module performance. White-goods compressor manufacturers in Jiangsu province are transitioning from silicon IGBTs to hybrid SiC diode-IGBT modules.
- Signal Processing:Analog and digital signal conditioning employs small-signal transistors and diodes.
- Radio Frequency:Wireless infrastructure and radar systems utilize specialized RF transistors and diodes.
Power supply applications generate the broadest cross-industry footprint; motor control shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in the Yangtze River Delta anchor China's discrete semiconductor production networks. Domestic substrate investments and MIIT policy directives are redistributing procurement gravity across provincial manufacturing clusters.
Yangtze River Delta
EV traction inverter demand and 8-inch foundry scaling drive procurement intensity across Shanghai, Jiangsu, and Zhejiang provinces. MIIT dual carbon mandates accelerate SiC MOSFET qualification timelines for tier-1 automotive suppliers. Suzhou and Hangzhou manufacturing corridors host concentrated IGBT module packaging operations serving white-goods OEMs.
Pearl River Delta
LED lighting rectifier demand and consumer electronics charger volumes sustain silicon diode consumption in Guangdong province. GB standards for energy efficiency tighten certification requirements for power semiconductors entering government procurement channels. Shenzhen and Dongguan electronics corridors concentrate small-signal transistor demand from smartphone accessory manufacturers.
Beijing-Tianjin-Hebei
Industrial internet infrastructure and smart factory mandates generate embedded power module demand across Hebei manufacturing zones. SAMR anti-monopoly enforcement restructures distribution channel partnerships for foreign semiconductor suppliers. Tianjin port logistics and Beijing R&D centers coordinate qualification testing for automotive-grade discrete components.
Sichuan-Chongqing
Grid-scale renewable energy storage and western province battery inverter deployments create untapped demand for high-frequency power devices. Central government western development incentives subsidize domestic foundry construction in Chengdu-Chongqing economic zones. Local industrial parks attract packaging investments for power modules serving hydroelectric and solar grid infrastructure.
Shandong Peninsula
Industrial motor drive retrofit programs and factory automation upgrades sustain IGBT procurement across Qingdao and Jinan manufacturing bases. Provincial energy efficiency regulations align with national GB standards implementation deadlines. Shandong's heavy machinery sector generates consistent demand for thyristor and high-voltage rectifier components.
China Discrete Semiconductors Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's discrete semiconductor value chain. Domestic 8-inch foundries and international substrate specialists occupy differentiated tier positions. Three archetypes dominate: integrated IDMs with captive fabrication, fabless design houses leveraging domestic foundry partnerships, and foreign suppliers with established automotive qualification pathways. Competitive moves center on direct OEM contracting and qualification acceleration for NMPA-aligned functional safety protocols.
Within the premium-tier vector, STMicroelectronics NV exemplifies SiC MOSFET positioning for EV traction applications. Among domestic fabricators, Silan Microelectronics and Yangjie Electronic Technology occupy cost-optimized positions serving consumer and industrial segments. These three anchors illustrate the bifurcation between automotive-grade certification investments and volume-driven silicon device production.
| Leading Market Players |
|---|
| STMicroelectronics NV |
| On Semiconductor Corporation |
| Vishay Intertechnology Inc. |
| Infineon Technologies AG |
| Renesas Electronics Corporation |
| China Resources Microelectronics |
| Silan Microelectronics |
| Texas Instruments Inc. |
| Yangjie Electronic Technology |
| Others |
Pricing and Supply Chain Analysis
Epitaxy engineering talent clustering in the Yangtze River Delta creates labor-cost differentials that widen pricing-tier spreads between automotive-grade SiC devices and commodity silicon diodes. MIIT dual carbon mandates compress margins for non-compliant producers while rewarding certified suppliers with procurement preference premiums.
Pricing Analysis
Module-level versus die-level procurement splits dominate transactional structures across China's discrete semiconductor markets. Pricing stratifies across automotive-grade, industrial-grade, and consumer-grade certification tiers, with NMPA functional safety protocols commanding substantial premiums over standard commercial offerings. Cost compression in silicon IGBT modules intensifies as domestic 8-inch foundries in Zhejiang scale output for white-goods manufacturers. Consumer electronics buyers exhibit highest price sensitivity, whereas EV traction inverter programs prioritize qualification velocity over unit economics.
Supply Chain Analysis
Regional distribution centers in Shanghai and Suzhou coordinate hub-and-spoke logistics patterns for power module delivery across eastern manufacturing corridors. Domestic substrate expansion in Jiangsu and Zhejiang draws from silicon carbide wafer imports sourced from Japan and the United States. Raw material dependencies center on high-purity silicon feedstock, ceramic substrate materials, and copper lead frames. Single-source vulnerability concentrates in qualified SiC epitaxy services for automotive-grade MOSFETs. Distribution runs through direct foundry contracting for high-volume automotive programs, bypassing traditional authorized distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's discrete semiconductor market compounds steadily as EV powertrain electrification mandates sustained procurement expansion across tier-1 automotive suppliers.
For Market Incumbents: Deploy qualification acceleration as the primary defensive lever. Accelerate NMPA-aligned ISO 26262 certification timelines to outpace emerging domestic competitors seeking automotive entry. Secure captive silicon carbide substrate supply through backward integration into Jiangsu-based wafer partnerships before domestic capacity saturates. Channel control investments in direct OEM contracting protect margin pools against distribution compression from SAMR anti-monopoly enforcement. For New Entrants and Emerging Players: Begin with underpenetrated renewable energy storage applications in Sichuan and Chongqing grid infrastructure. Target western province battery inverter deployments where high-frequency GaN device demand outstrips qualified supplier availability. Pursue MIIT industrial internet initiative mandates for embedded power modules in smart factory motor control applications. Establish technical partnerships with domestic 8-inch foundries to bypass capital-intensive fabrication barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among fabless design houses lacking automotive qualification pathways but possessing strong domestic foundry relationships. Five-to-ten year viability favors suppliers with demonstrated NMPA functional safety track records and SiC MOSFET design capabilities. Monitor domestic 6-inch SiC substrate yield improvements as the critical inflection signal for supplier-buyer power rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Functional Safety Certification | NMPA-aligned ISO 26262 qualification unlocks tier-1 EV traction inverter procurement programs. |
| Silicon Carbide Substrate Partnership | Domestic 6-inch wafer supply agreements reduce foreign dependency for high-voltage MOSFET production. |
| Direct Foundry Contracting | Wafer-level OEM relationships bypass distribution channel compression from SAMR enforcement actions. |
| Hybrid Power Stage Development | Combining SiC diodes with GaN HEMTs opens premium server power supply positioning in Shanghai data centers. |
| Industrial Internet Module Integration | MIIT smart factory mandates create embedded power demand across Jiangsu manufacturing automation upgrades. |
Research Methodology
Bottom-up end-use demand modeling reconciled against top-down substrate supply tracking forms the analytical core of this study. Primary interviews with tier-1 automotive supplier procurement directors, domestic foundry operations managers, power module packaging engineers, and MIIT policy research fellows generated demand-side intelligence. Secondary validation drew from MIIT GB standard filings, NMPA automotive component registration databases, customs trade statistics for SiC wafer imports, and provincial industrial park investment disclosures. Triangulation between these sources established volume baselines and growth trajectory boundaries.
Input-output matrices map semiconductor device shipments across voltage class, substrate material, certification grade, and end-use application dimensions over the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against EV production forecasts and industrial motor drive retrofit timelines. Segmentation modeling incorporates technology substitution curves for SiC displacing silicon IGBTs, GaN penetration rates in server power supplies, and MIIT compliance deadline impacts on replacement demand.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, breakthrough substrate yield improvements beyond current technical roadmaps, and abrupt NMPA regulatory timeline accelerations. Forecasts reflect documented assumptions regarding domestic foundry scaling schedules and EV platform voltage architecture transitions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductors
Semiconductor IP Market
Semiconductors
Global Semiconductor Silicon Intellectual Property Market
Semiconductors
Global Copper Indium Gallium Selenide (CIGS) Solar Cells Market
Semiconductors
Logic Semiconductor Market
Semiconductors
China Semiconductor Market
Semiconductors
Resistive RAM Market
Semiconductors
South Korea Discrete Semiconductors Market
Semiconductors
Europe Semiconductor Diode Market
Semiconductors
Europe Semiconductor Market
Semiconductors
Asia-Pacific Semiconductor Market
Semiconductors
Aluminum Gallium Indium Phosphide Semiconductor Market
Semiconductors
Discrete Semiconductor Market
Semiconductors
East Asia Automotive Semiconductors Market
Semiconductors
Semiconductor Target Market
Semiconductors
Semiconductor Clock Market
Semiconductors
Global Automotive Semiconductor Market