
 Plasma Etching Equipment Market | 2026-2036
Plasma Etching Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Plasma Etching Equipment Market Analysis
Customer concentration among semiconductor foundries is consolidating as advanced node production shifts toward a handful of capital-intensive buyers with multi-billion-dollar fab commitments. Lam Research Corporation leverages its installed base dominance in conductor etch to sustain recurring revenue from service contracts and chamber upgrades. Applied Materials Inc. anchors its position through integrated materials engineering solutions that combine etch with deposition and metrology. Tokyo Electron Ltd differentiates via precision control systems for atomic-scale etch uniformity.
Plasma etching equipment utilizes ionized gas chemistries to selectively remove material from semiconductor wafers and substrates, operating at vacuum pressures with RF power delivery systems generating plasma densities exceeding 10^11 ions per cubic centimeter. The primary industrial purpose centers on pattern transfer for integrated circuit fabrication, where sub-nanometer critical dimension control determines device yield. Reactive ion etching systems command the largest installed base among technology categories, while deep reactive ion etching experiences the fastest growth trajectory driven by MEMS and 3D NAND applications. Multi-chamber architectures capture disproportionate margin pools by enabling sequential process integration without vacuum breaks.
EPA emissions standards in the United States and REACH chemical restrictions in Europe constrain fluorinated gas chemistries used in plasma etch processes, compelling equipment redesigns for abatement and alternative precursor adoption. Japan's METI coordinates domestic semiconductor supply chain resilience initiatives that directly influence procurement priorities for etch tool qualification. South Korea's environmental ministry enforces progressively stricter perfluorinated compound reporting thresholds that reshape process development roadmaps. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate compliance-driven equipment replacement cycles and chemistry transition timelines.
Market Dynamics
Advanced node migration below 3nm is compressing equipment replacement cycles as atomic-scale precision requirements render legacy etch chambers obsolete, forcing foundries into accelerated capital deployment regardless of macro conditions.
Growth Catalysts
- EU Chips Act capital allocation:Member states are unlocking facility construction subsidies that mandate European-sourced equipment qualification, creating localized demand pull for etch tool vendors with regional service infrastructure.
- Gate-all-around transistor architecture:The transition from FinFET to GAA at 2nm nodes requires multi-patterning etch sequences with atomic layer precision, expanding chamber counts per wafer start.
- Hsinchu-Taichung manufacturing corridor:Taiwan's concentrated foundry expansion is generating clustered procurement volumes that amortize vendor qualification costs across multi-fab deployments.
Market Restraints
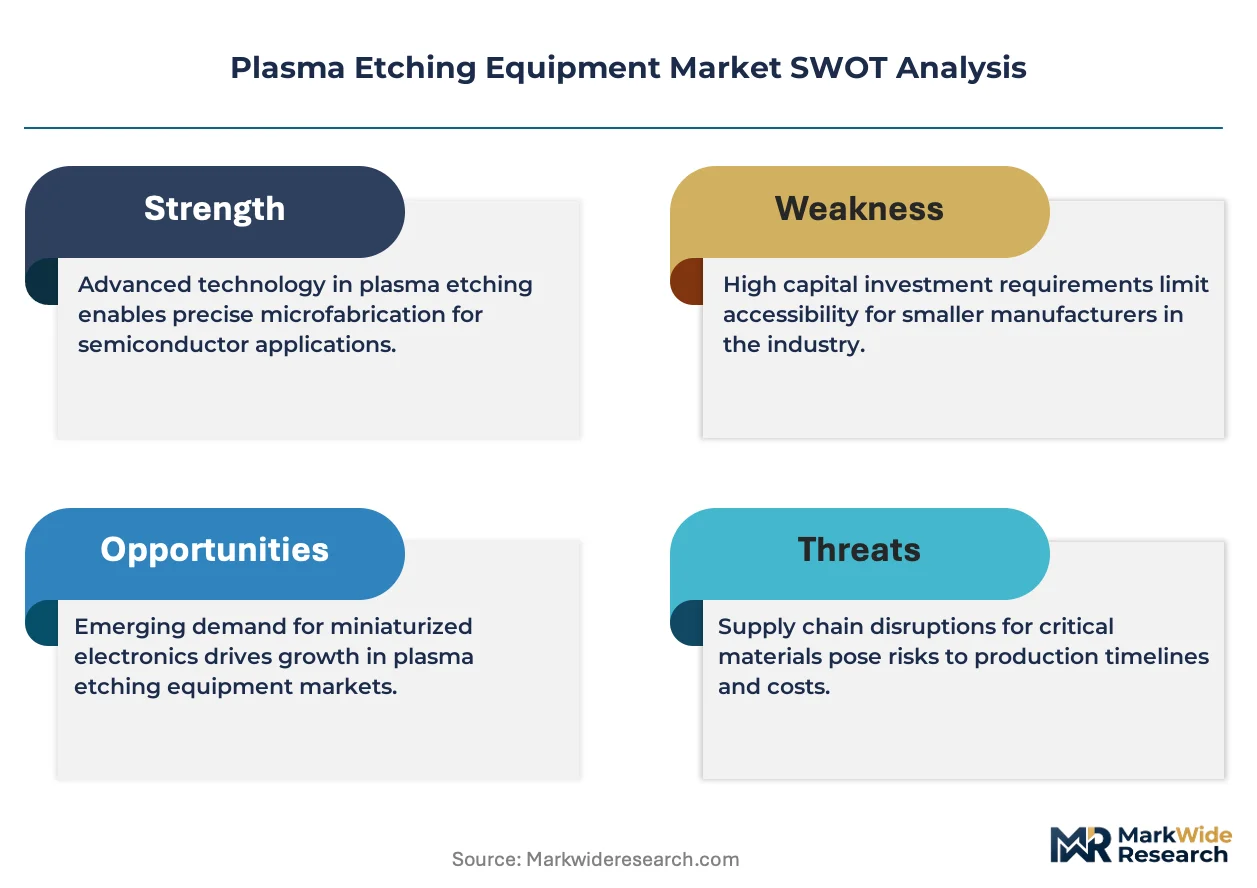
- Fluorinated gas supply concentration:Perfluorinated precursor production clusters in Japanese and Chinese chemical suppliers, exposing etch process roadmaps to export control volatility and input cost spikes.
- Chamber architecture lock-in:Proprietary gas delivery geometries and RF matching networks across Lam Research, Applied Materials, and Tokyo Electron systems prevent inter-vendor chamber swapping, raising switching costs.
- EPA fluorinated greenhouse gas mandates:New abatement requirements for NF3 and CF4 emissions are extending equipment qualification timelines and forcing chemistry reformulations that degrade etch selectivity.
Strategic Opportunities
- India semiconductor mission:The country's production-linked incentive scheme for fabs at Dholera and Assam is creating first-mover advantage for etch vendors willing to establish local service engineering ahead of volume procurement.
- Atomic layer etch-metrology convergence:Real-time ellipsometry integration with etch chambers enables closed-loop thickness control, opening premium pricing for process-intelligence bundles.
- Carbon-based precursor substitution:Fluorine-free chemistries using CO and C4F8 derivatives align with EU F-Gas Regulation phase-down schedules, positioning early chemistry developers for regulatory-mandated replacement cycles.
Industry Challenges
- Plasma physics specialist scarcity:Atomic-scale etch development requires combined expertise in RF engineering, gas-phase kinetics, and surface chemistry that outpaces university pipeline output.
- Multi-fab equipment synchronization:Foundries running identical processes across Taiwan, Arizona, and Germany facilities must maintain chamber-matched uniformity, complicating remote diagnostics and spare parts logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasma Etching Equipment Market |
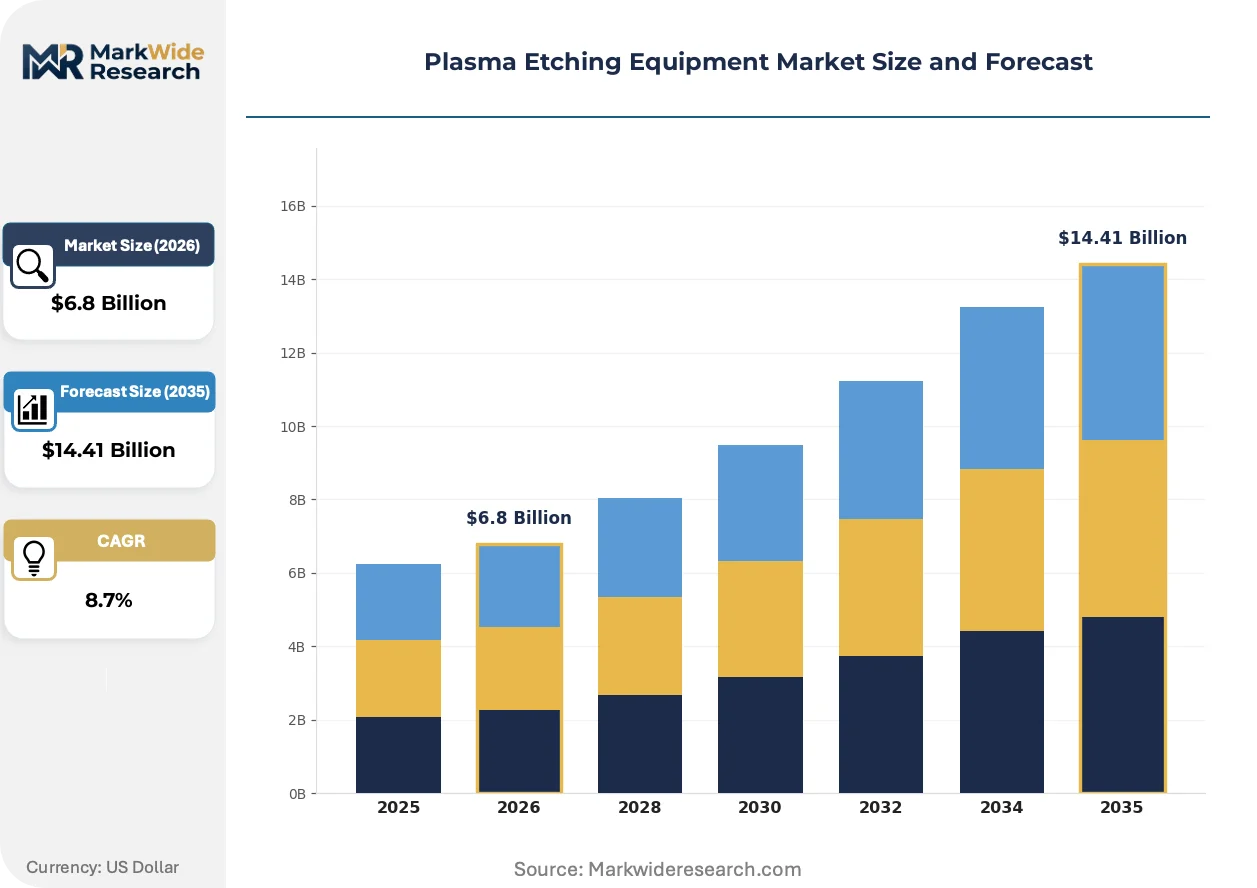
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Etching, Inline Etching, Tooling Systems, Multi-Chamber Systems Technology: Reactive Ion Etching, Deep Reactive Ion Etching, Plasma Enhanced Chemical Vapor Deposition, Microwave Plasma End User: Semiconductor Manufacturers, MEMS Fabricators, Solar Cell Producers, Display Manufacturers Application: Wafer Fabrication, Circuit Patterns, Microstructuring, Thin Film Transistors |
| Companies Covered | SPTS Technologies, Plasma-Therm LLC, Lam Research Corporation, NAURA Technology Group, Veeco Instruments, Applied Materials Inc., Oxford Instruments PLC, Advanced Micro-Fabrication Equipment Inc., Tokyo Electron Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasma Etching Equipment Market Emerging Trajectories
Equipment architectures are converging around in-situ process control and chemistry flexibility as foundries prioritize yield stability over raw throughput in advanced node production.
Hybrid pulsed-bias etch systems are unifying anisotropic and isotropic etch capabilities within single chamber platforms, eliminating vacuum breaks between profile shaping steps. Memory manufacturers deploying 3D NAND with 200+ layer stacks are adopting these platforms at replacement rates exceeding historical norms. The technology is unifying process sequences that previously required dedicated conductor and dielectric etch tools, compressing fab footprint requirements and vendor qualification scope.
Japan's METI semiconductor supply chain resilience initiatives are mandating domestic etch tool content thresholds for subsidized fab projects, redirecting procurement toward Tokyo Electron and domestic subcomponent suppliers. Equipment vendors are responding with localized sourcing certifications for RF generators and electrostatic chucks. Advanced logic foundries with Japan-based packaging operations face the most acute compliance pressure, accelerating joint development agreements with METI-designated preferred suppliers.
Foundry customers are consolidating maintenance contracts under multi-year outcome agreements that tie vendor payments to chamber uptime rather than discrete service events. This displaces transactional spare parts and field service revenue with performance-guarantee structures. The shift is most visible in Taiwan and South Korea, where Samsung and TSMC procurement teams have standardized uptime-based contracting for etch fleet management.
Plasma Etching Equipment Market Segmentation
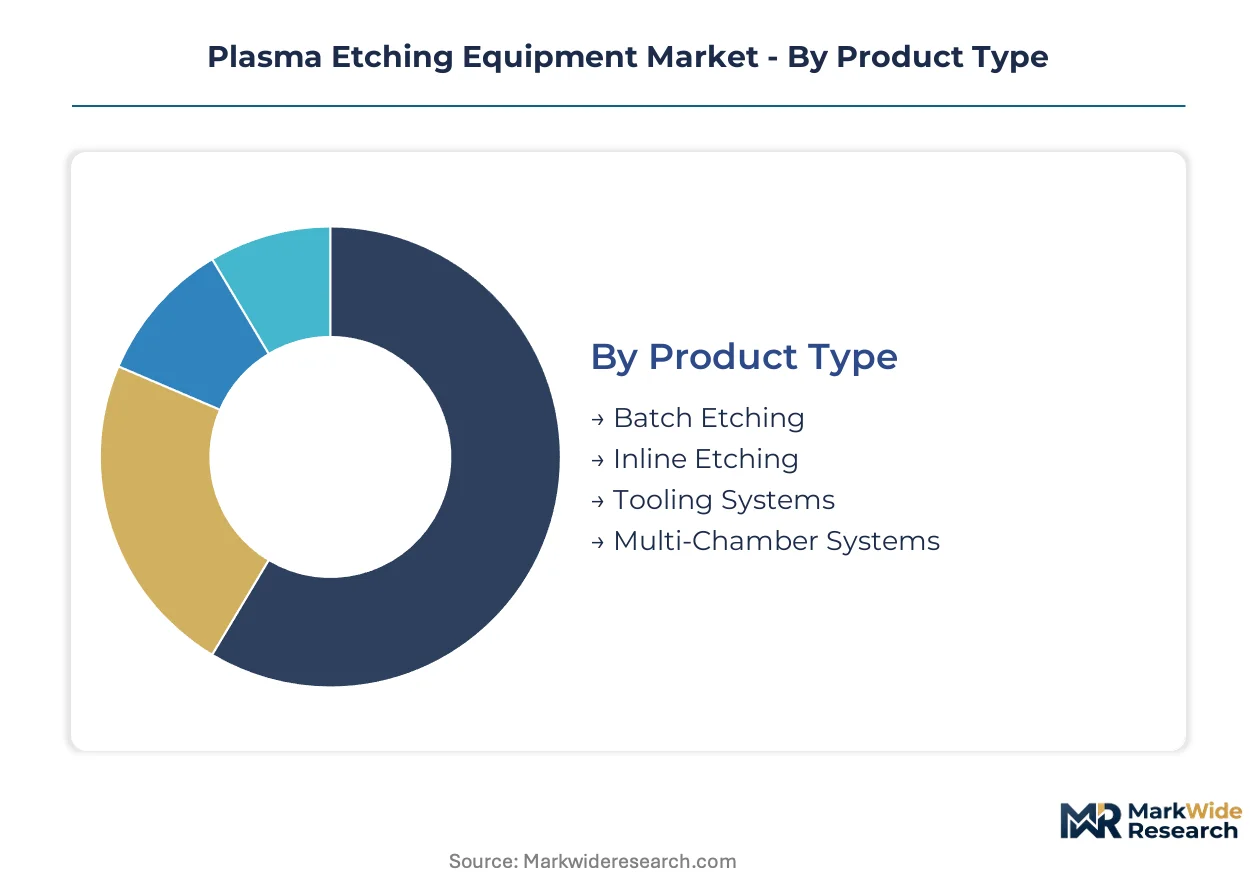
Equipment segmentation in plasma etching reflects divergent capital intensity, process control requirements, and regulatory compliance burdens across semiconductor fabrication tiers. Each category maps to distinct procurement patterns, vendor qualification pathways, and service contract structures.
Product Type:
Certification burdens vary sharply: batch systems face EPA emissions abatement mandates, while multi-chamber architectures trigger extended factory acceptance testing for vacuum integrity.
- Batch Etching:Processes multiple wafers simultaneously in shared plasma environments, sacrificing uniformity for throughput economics. Demand concentrates among legacy node producers in China's Yangtze River Delta, where capital constraints favor depreciated equipment acquisitions over greenfield multi-chamber deployments.
- Multi-Chamber Systems:Integrate sequential etch, deposition, and metrology modules without atmospheric exposure. Taiwan's Hsinchu-Taichung corridor drives procurement volumes as TSMC and United Microelectronics mandate these platforms for 3nm gate-all-around transistor fabrication.
- Inline Etching:Continuous-feed architectures for solar cell metallization patterning.
- Tooling Systems:Consumable chamber components and retrofit kits extending legacy platform lifecycles.
Leading the category by volume: Multi-Chamber Systems. Expanding most quickly: Inline Etching.
Technology:
Cost tier stratification separates mature reactive ion platforms from premium deep reactive ion systems commanding 3-4x chamber pricing.
- Reactive Ion Etching:Dominates installed base through capacitively coupled plasma architectures operating at 13.56 MHz RF frequency. Mature process libraries and standardized spare parts supply chains sustain adoption among second-tier foundries in Malaysia's Kulim Hi-Tech Park.
- Deep Reactive Ion Etching:Employs Bosch process cycling for high-aspect-ratio silicon features exceeding 50:1 depth-to-width ratios. MEMS accelerometer manufacturers in Germany's Saxony cluster drive replacement demand as automotive safety mandates expand inertial sensor content per vehicle.
- Plasma Enhanced Chemical Vapor Deposition:Hybrid etch-deposition platforms for conformal film engineering.
- Microwave Plasma:Electron cyclotron resonance sources for damage-sensitive compound semiconductor processing.
Highest margin capture: Deep Reactive Ion Etching. Steepest volume decline: Plasma Enhanced Chemical Vapor Deposition.
End User:
Customer type determines service model intensity, with semiconductor manufacturers demanding 99.5% uptime guarantees versus solar producers accepting lower availability thresholds.
- Semiconductor Manufacturers:Logic and memory foundries operating sub-5nm nodes require atomic-layer etch precision with real-time ellipsometry feedback. Samsung's Pyeongtaek campus and Intel's Ohio facilities anchor capital deployment, with procurement teams standardizing on outcome-based maintenance contracts.
- MEMS Fabricators:Bosch, STMicroelectronics, and TDK InvenSense drive deep reactive ion etch demand for gyroscope and pressure sensor cavities. Process development cycles extend 18-24 months for automotive qualification under AEC-Q100 standards.
- Solar Cell Producers:Heterojunction and TOPCon cell architectures require selective emitter etching.
- Display Manufacturers:OLED thin-film transistor backplane patterning in South Korea's Gyeonggi Province.
Dominant revenue share: Semiconductor Manufacturers. Fastest contract value growth: MEMS Fabricators.
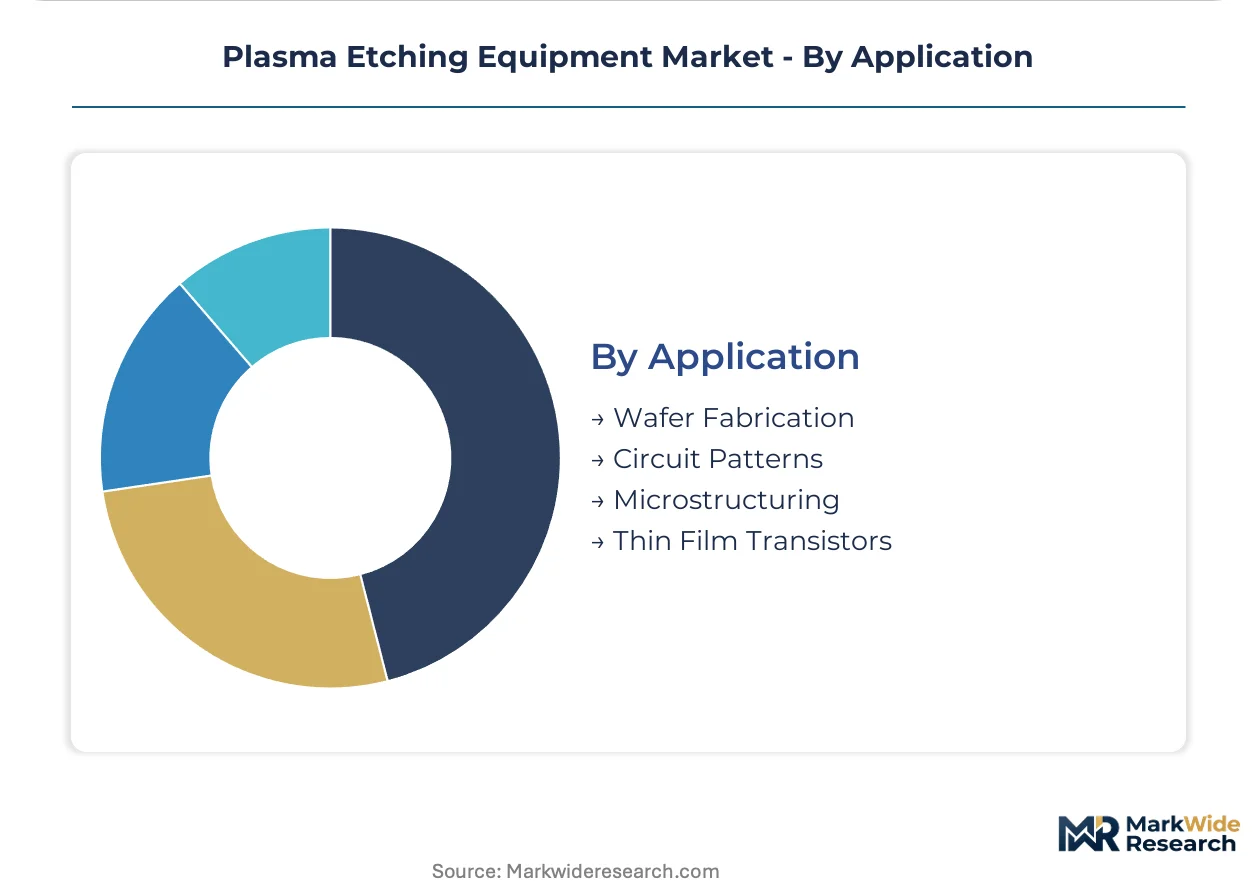
Application:
Geography shapes application priority, with East Asian clusters emphasizing wafer fabrication while European investments concentrate on power semiconductor microstructuring.
- Wafer Fabrication:Encompasses front-end-of-line transistor gate etch, back-end-of-line interconnect trenching, and through-silicon via formation for 3D integration. Taiwan's concentrated foundry expansion generates clustered demand that amortizes vendor qualification costs across multi-fab deployments.
- Microstructuring:Silicon photonics waveguide definition and biomedical MEMS cavity formation require sidewall roughness below 2nm RMS. IMEC's Leuven pilot line and CEA-Leti's Grenoble facilities drive European equipment qualification for beyond-CMOS research programs.
- Circuit Patterns:Printed circuit board and substrate etching for advanced packaging.
- Thin Film Transistors:Display backplane and flexible electronics patterning.
Largest equipment installed base: Wafer Fabrication. Gaining share fastest: Microstructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capital deployment clusters in three East Asian economies, with secondary demand emerging from European industrial policy mandates and North American reshoring incentives. Taiwan, South Korea, and Japan collectively absorb the majority of advanced node etch tool procurement.
Taiwan
TSMC's Hsinchu-Taichung corridor expansion drives concentrated multi-chamber system orders for 3nm gate-all-around production. The National Development Council coordinates semiconductor infrastructure subsidies that mandate domestic content thresholds. Kaohsiung's emerging fab cluster is attracting vendor qualification centers from Tokyo Electron and Applied Materials to localize service response times.
South Korea
Samsung's Pyeongtaek campus and SK Hynix's Yongin complex anchor memory-focused etch demand for 200+ layer 3D NAND stacks. The Ministry of Environment enforces tightening perfluorinated compound reporting thresholds that reshape process chemistry roadmaps. Seoul Capital Area procurement teams have standardized outcome-based maintenance contracts tying vendor payments to chamber uptime metrics.
Japan
Tokyo Electron's domestic installed base sustains recurring service revenue from Kioxia's Yokkaichi and Kitakami memory fabs. METI's supply chain resilience initiatives mandate domestic etch tool content for subsidized projects, redirecting procurement toward preferred subcomponent suppliers. Kyoto-Osaka precision manufacturing clusters are expanding RF generator and electrostatic chuck production capacity.
United States
Intel's Ohio and Arizona facilities anchor reshoring-driven capital deployment for advanced logic production. EPA fluorinated greenhouse gas mandates for NF3 and CF4 abatement are extending equipment qualification timelines. Greater Phoenix and Columbus metro areas are attracting vendor field service engineering centers to support multi-fab synchronization requirements.
Germany
Bosch's Reutlingen MEMS fab and Infineon's Dresden power semiconductor complex drive deep reactive ion etch demand for automotive sensor cavities. EU F-Gas Regulation phase-down schedules are compelling carbon-based precursor adoption for compliance. Saxony's silicon photonics research corridor at Fraunhofer IPMS is qualifying equipment for beyond-CMOS microstructuring applications.
Plasma Etching Equipment Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue localized service infrastructure and chemistry specialization. The vendor base stratifies across three tiers: integrated platform providers with multi-process portfolios, regional champions with government-backed qualification advantages, and specialists in MEMS or compound semiconductor niches. Dominant competitive moves include METI-mandated domestic sourcing certifications in Japan and multi-year outcome-based maintenance contract standardization in Taiwan and South Korea.
Among the integrated platform tier, Lam Research Corporation, Applied Materials Inc., and Tokyo Electron Ltd exemplify archetypes with differentiated positioning. Lam Research anchors the conductor etch segment through installed base dominance and recurring service revenue structures. Applied Materials occupies the materials engineering convergence position, combining etch with deposition and metrology in unified platform architectures. Tokyo Electron represents precision control specialization, with atomic-scale etch uniformity systems qualifying for Japan's domestic content mandates.
| Leading Market Players |
|---|
| SPTS Technologies |
| Plasma-Therm LLC |
| Lam Research Corporation |
| NAURA Technology Group |
| Veeco Instruments |
| Applied Materials Inc. |
| Oxford Instruments PLC |
| Advanced Micro-Fabrication Equipment Inc. |
| Tokyo Electron Ltd |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed equipment vendors in Japan and South Korea anchor supply-side discipline through METI-coordinated procurement mandates and domestic content thresholds, translating state-supported capacity into premium pricing power for advanced node systems while compressing margins for non-preferred suppliers.
Pricing Analysis
High-volume multi-chamber deployments for 3nm logic nodes command premium pricing with outcome-based uptime guarantees, while batch etching systems for legacy nodes face cost compression from Chinese depreciation markets. Price differentiation hinges on chamber-matched uniformity certification and geographic proximity to Taiwan's Hsinchu-Taichung corridor. Pricing pressure stems from EPA fluorinated gas abatement mandates extending qualification timelines. MEMS fabricators in Germany's Saxony cluster exhibit highest price sensitivity due to AEC-Q100 automotive qualification burdens, whereas Taiwan foundries prioritize performance over unit cost.
Supply Chain Analysis
Direct-to-foundry channels handle hyperscale procurement from TSMC and Samsung, bypassing distribution intermediaries for chamber-matched fleet synchronization. Supply concentration rests on Japanese RF generator and electrostatic chuck production, Taiwanese vacuum component integration, and South Korean process chemistry formulation. Key inputs include fluorinated precursors from Kanto Denka, ceramic chamber liners from Kyocera, and RF power delivery systems from MKS Instruments. Single-source vulnerability in perfluorinated gas supply exposes etch roadmaps to export control volatility. Distribution runs through vendor-managed inventory agreements at Arizona and Ohio fab sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma etching equipment supply is tightening around qualified chamber manufacturing capacity, with atomic-scale uniformity requirements and METI domestic content mandates propping pricing for preferred vendors regardless of macro demand fluctuations.
For Market Incumbents: Anchor recurring revenue through multi-year outcome-based maintenance contracts tied to chamber uptime metrics, displacing transactional spare parts revenue. Defend against emerging Chinese equipment vendors by deepening backward integration into RF matching network production. Prioritize certification investment for EPA fluorinated gas abatement compliance to extend qualification timelines as a competitive moat. For New Entrants and Emerging Players: India's Dholera and Assam fab projects represent an underserved buyer archetype with production-linked incentive procurement windows opening ahead of established vendor service infrastructure deployment. Target carbon-based precursor substitution development for EU F-Gas Regulation compliance cycles. Pursue joint development agreements with CEA-Leti and Fraunhofer IPMS for silicon photonics microstructuring qualification as a beachhead into European research-to-production pipelines. For Investors and Strategic Acquirers: Distressed-cycle entries favor MEMS-focused deep reactive ion etch specialists with automotive AEC-Q100 qualification and established Bosch process libraries in Germany's Saxony cluster. Long-term viability centers on atomic layer etch-metrology convergence capabilities. Watch for chamber architecture lock-in effects accelerating consolidation among vendors with proprietary gas delivery geometries.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Certification | METI-mandated sourcing thresholds redirect procurement toward Tokyo Electron and preferred Japanese subcomponent suppliers. |
| Outcome-Based Maintenance Contracting | TSMC and Samsung procurement teams standardize uptime-guarantee structures displacing transactional service revenue. |
| Carbon-Based Precursor Development | EU F-Gas Regulation phase-down schedules position early chemistry developers for regulatory-mandated replacement cycles. |
| Atomic Layer Etch-Metrology Integration | Real-time ellipsometry feedback enables closed-loop thickness control and premium process-intelligence bundling. |
| India Local Service Engineering | Dholera and Assam fab incentives create first-mover advantage for vendors establishing field response ahead of volume procurement. |
Methodological Framework
Document review covered SEC 10-K filings from Lam Research and Applied Materials, complemented by interviews with fab procurement directors at TSMC and Samsung, process development engineers at Tokyo Electron, and EPA regulatory compliance officers. Secondary validation drew from SEMI equipment market data, METI supply chain resilience initiative documentation, and EU F-Gas Regulation impact assessments. Bottom-up triangulation across chamber shipment volumes and top-down validation through foundry capex disclosures anchored market sizing.
Installed base projections and replacement cycle estimates emerged from modeling across the analysis window, segmenting by equipment architecture, technology node requirements, and regional regulatory cluster. Modeled dimensions included multi-chamber versus batch system deployment, reactive ion versus deep reactive ion etch technology, and semiconductor versus MEMS end-use application. CAGRs were derived from equipment shipment trajectories correlated with foundry capacity expansion announcements and process node migration timelines.
Revisions become necessary when fluorinated gas export controls tighten, EPA abatement mandates accelerate, or foundry capital deployment pauses materialize outside modeled scenarios. Forecasts reflect assumptions regarding chamber qualification timelines, chemistry transition roadmaps, and sovereign subsidy continuity. Periodic stress-testing of base assumptions against METI procurement directive changes and EU industrial policy shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Photoresist for Semiconductor Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Europe Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Consumable Parts for Semiconductor Equipment Market
Semiconductor Equipment
Global SMT Placement Equipment Market
Semiconductor Equipment
Wafer Grinding Machine Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Wafer CMP Machine Market
Semiconductor Equipment
United States Chip Mounter Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
X-Ray Lithography Equipment Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market