
 Machine Learning Chip Market | 2026-2036
Machine Learning Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Learning Chip Market Intelligence
Aftermarket service revenue for legacy inference hardware is narrowing as cloud providers shift toward subscription-based AI compute platforms. NVIDIA Corporation leverages its CUDA software ecosystem to sustain pricing power across training and inference workloads. Advanced Micro Devices competes aggressively in data center GPU deployments through its ROCm open software stack. Intel Corporation anchors its position with Gaudi accelerators aimed at enterprise AI pipelines.
Machine learning chips are semiconductor devices architected for matrix-intensive arithmetic operations, typically fabricated on sub-5nm process nodes with high-bandwidth memory integration and specialized tensor cores or systolic arrays. Their primary purpose is to accelerate neural network training and inference at throughput and energy efficiency levels unattainable by general-purpose processors. GPU products currently dominate training workloads due to massive parallelization capacity, while ASIC designs capture expanding share in hyperscale inference where power efficiency dictates total cost of ownership. Natural Language Processing applications are driving outsized demand for memory-bandwidth-optimized architectures, and data center end users command the largest procurement volumes as cloud providers build dedicated AI infrastructure.
The US CHIPS Act directs federal subsidies toward domestic advanced semiconductor fabrication, directly influencing where machine learning chip designers source leading-edge wafers. The EU AI Act imposes risk-tiered compliance obligations on AI systems, creating certification requirements that ripple back to chip-level performance documentation and traceability. ISO/IEC standards for AI system robustness are gaining traction among enterprise buyers, shaping procurement specifications. Stakeholders must monitor how export control regimes on advanced lithography equipment constrain foundry expansion timelines and alter competitive access to next-generation process nodes.
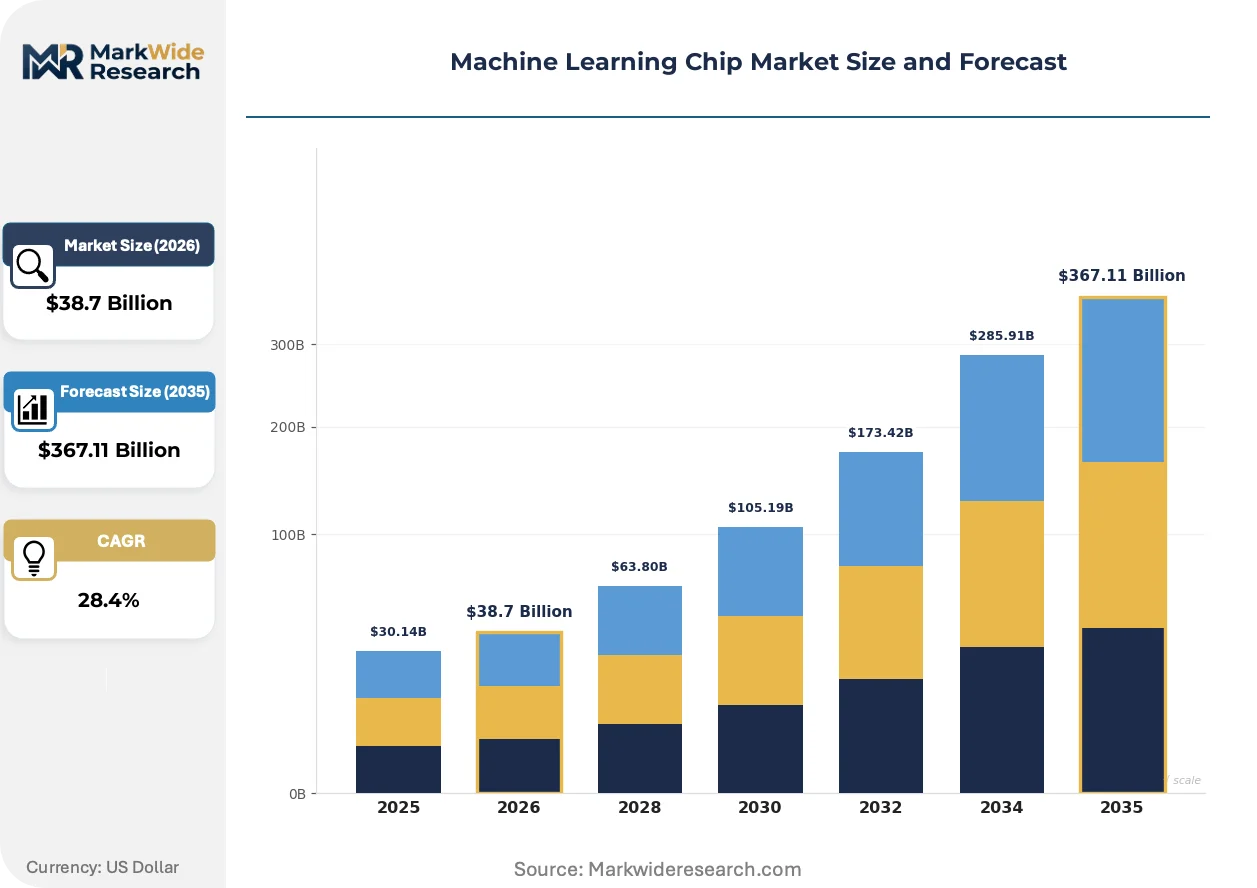
Market Dynamics
Foundry capacity concentration in Taiwan and South Korea is creating supply-side bottlenecks that reshape procurement timelines for machine learning chip designers, while the US CHIPS Act redirects fabrication investment toward domestic facilities.
Growth Catalysts
- Hyperscale data center buildouts:Cloud providers in the United States are deploying dedicated AI infrastructure at unprecedented scale, driving wafer starts for training accelerators and memory-bandwidth-optimized inference chips.
- EU AI Act compliance requirements:Risk-tiered documentation obligations for high-risk AI systems are mandating chip-level traceability and performance auditing, expanding demand for certified hardware.
- Sub-3nm process maturation:Leading-edge lithography advances are enabling transistor density gains that directly translate to training throughput improvements and energy efficiency gains for large language model workloads.
Market Restraints
- Advanced lithography equipment access constraints:Export control regimes on extreme ultraviolet systems are extending foundry expansion timelines and limiting second-tier designers' access to next-generation nodes.
- High-bandwidth memory supply concentration:HBM3 and HBM3E supply is dominated by three Korean suppliers, creating input cost volatility and allocation risk for AI accelerator production.
- Reticle-limited die size constraints:Physical photomask boundaries are capping single-chip compute density, forcing costly multi-die packaging approaches that inflate unit economics.
Strategic Opportunities
- Edge AI deployment in industrial automation:Manufacturing facilities in Germany and Japan are adopting on-premise inference accelerators to reduce latency for quality control and predictive maintenance applications.
- US CHIPS Act fabrication subsidies:Federal incentives for domestic leading-edge facilities are enabling captive wafer supply strategies for designers seeking supply chain resilience.
- Neuromorphic architecture convergence:Spiking neural network hardware is intersecting with conventional CMOS processes to enable ultra-low-power inference for always-on sensor applications.
Industry Challenges
- Packaging substrate and interposer shortages:CoWoS and EMIB capacity constraints are extending lead times for multi-chip AI accelerators and forcing designers to qualify alternative advanced packaging suppliers.
- Hardware-software co-optimization talent scarcity:The specialized skill set spanning compiler stacks, kernel optimization, and silicon architecture is concentrated among a small cohort of engineers, inflating compensation and slowing product cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Learning Chip Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $367.11 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ASIC, FPGA, GPU, CPU Application: Natural Language Processing, Image Recognition, Predictive Analytics, Robotics End User: Data Centers, SMEs, Enterprises, Research Institutions Technology: Neural Networks, Deep Learning, Reinforcement Learning, Transfer Learning |
| Companies Covered | NVIDIA Corporation, Advanced Micro Devices, Intel Corporation, Qualcomm Technologies, Samsung Electronics, Amazon Web Services, IBM Corporation, Cerebras Systems, Graphcore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Learning Chip Market Strategic Shifts & Innovations
Silicon architecture is fragmenting across divergent optimization targets for training versus inference, while regulatory pressure and procurement model evolution are rewriting how chip designers engage end customers.
Chiplet-based modular designs are enabling functional decomposition of AI accelerators into specialized compute, memory, and I/O dies. Hyperscale cloud providers are standardizing on multi-vendor chiplet ecosystems to reduce single-source dependency. This disaggregation is digitizing the traditional monolithic GPU supply chain into interchangeable component markets.
The EU AI Act's risk classification framework is mandating conformity assessment procedures for AI systems deployed in critical infrastructure. Chip manufacturers must now provide documented performance specifications, traceability matrices, and robustness testing for accelerators used in high-risk applications. European enterprise buyers are prioritizing vendors with pre-certified hardware to compress compliance timelines.
Cloud providers are unbundling AI compute from infrastructure leases into granular, API-consumable services. Enterprise buyers are shifting capital expenditure toward operational expenditure models that abstract hardware procurement entirely. This transition is most pronounced in North American financial services and healthcare verticals, where internal GPU cluster ownership is declining in favor of managed platform subscriptions.
Machine Learning Chip Market Segmentation
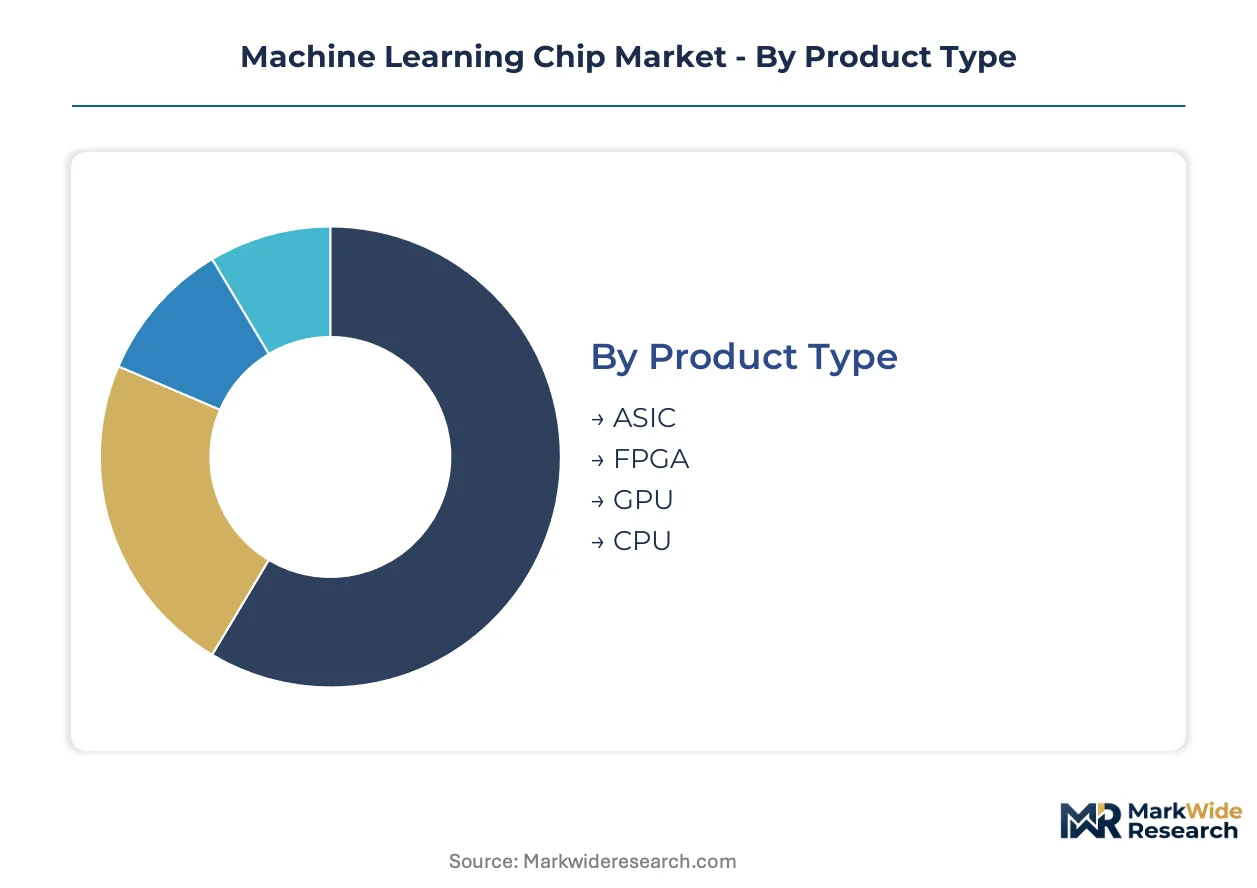
Machine learning chip architectures diverge sharply across workload requirements, with training versus inference demands dictating silicon topology, memory hierarchy, and power envelope specifications. Procurement patterns fragment across hyperscale data centers, industrial enterprises, and research consortia, each imposing distinct validation and integration constraints on accelerator vendors.
Product Type:
Cost tier stratification separates commodity inference engines from premium training accelerators, with silicon area and process node positioning determining unit economics and addressable market breadth.
- GPU:Massively parallel architectures with thousands of CUDA or stream processors, high-bandwidth memory stacks, and mature software ecosystems dominate neural network training workloads. Hyperscale cloud providers in the United States procure these at volume for large language model development, constrained by CoWoS packaging capacity and HBM supply allocation from Korean memory suppliers.
- ASIC:Application-specific designs sacrifice programmability for power efficiency and unit cost optimization in deployed inference pipelines. Google TPU and Amazon Trainium exemplify this trajectory, with demand concentrating in recommendation systems and search ranking where query volume justifies custom silicon investment.
- FPGA:Reconfigurable logic arrays enable algorithm-specific optimization without respin costs, appealing to defense contractors and financial trading firms requiring low-latency pattern matching with evolving model architectures.
- CPU:General-purpose processors with AVX-512 or AMX extensions handle sparse inference and preprocessing stages where flexibility outweighs throughput density, common in enterprise edge deployments with mixed workloads.
GPU commands the established base. The steepest expansion runs through ASIC.
Application:
Volume concentration varies dramatically across use cases, with transformer-based language models consuming orders of magnitude more compute than classical computer vision pipelines.
- Natural Language Processing:Transformer architectures with billions of parameters demand memory-bandwidth-optimized accelerators and extensive interconnect bandwidth for distributed training. Research institutions and cloud providers in Taiwan and South Korea are deploying dedicated clusters for foundation model development, driving reticle-limited multi-die packaging adoption.
- Image Recognition:Convolutional and vision transformer workloads require high-throughput integer arithmetic for edge inference in manufacturing quality control and autonomous vehicle perception. German automotive suppliers and Japanese electronics manufacturers are qualifying low-power accelerators for on-premise deployment.
- Predictive Analytics:Gradient-boosted and recurrent models for time-series forecasting run efficiently on modest accelerator configurations, with financial services firms in Singapore and Switzerland adopting subscription-based cloud inference to avoid capital expenditure.
- Robotics:Real-time sensor fusion and motion planning impose deterministic latency requirements, favoring neuromorphic and FPGA-based solutions in warehouse automation and surgical robotics applications.
Natural Language Processing captures the dominant compute allocation. The fastest volume gains are emerging in Robotics.
End User:
Customer type determines procurement modality, with hyperscalers negotiating direct foundry allocation while smaller entities depend on distributor and cloud intermediary channels.
- Data Centers:Hyperscale operators design custom accelerators and secure multi-year wafer supply agreements, with procurement concentrated in Taiwan, South Korea, and the United States where leading-edge fabrication clusters operate. The US CHIPS Act is redirecting some capacity investment toward domestic facilities.
- Enterprises:Fortune 500 manufacturers and healthcare systems are shifting from owned GPU clusters to managed platform subscriptions, prioritizing vendors with ISO/IEC AI system robustness documentation for EU AI Act compliance preparation.
- SMEs:Mid-market adopters access ML compute through API-consumable cloud services, with procurement decisions driven by per-inference pricing rather than hardware specifications.
- Research Institutions:Universities and national laboratories secure accelerators through government grants and consortium purchasing, with allocation priorities favoring open-science initiatives and climate modeling applications.
Data Centers anchor procurement volume. Enterprises are gaining share fastest as vertical AI adoption broadens.
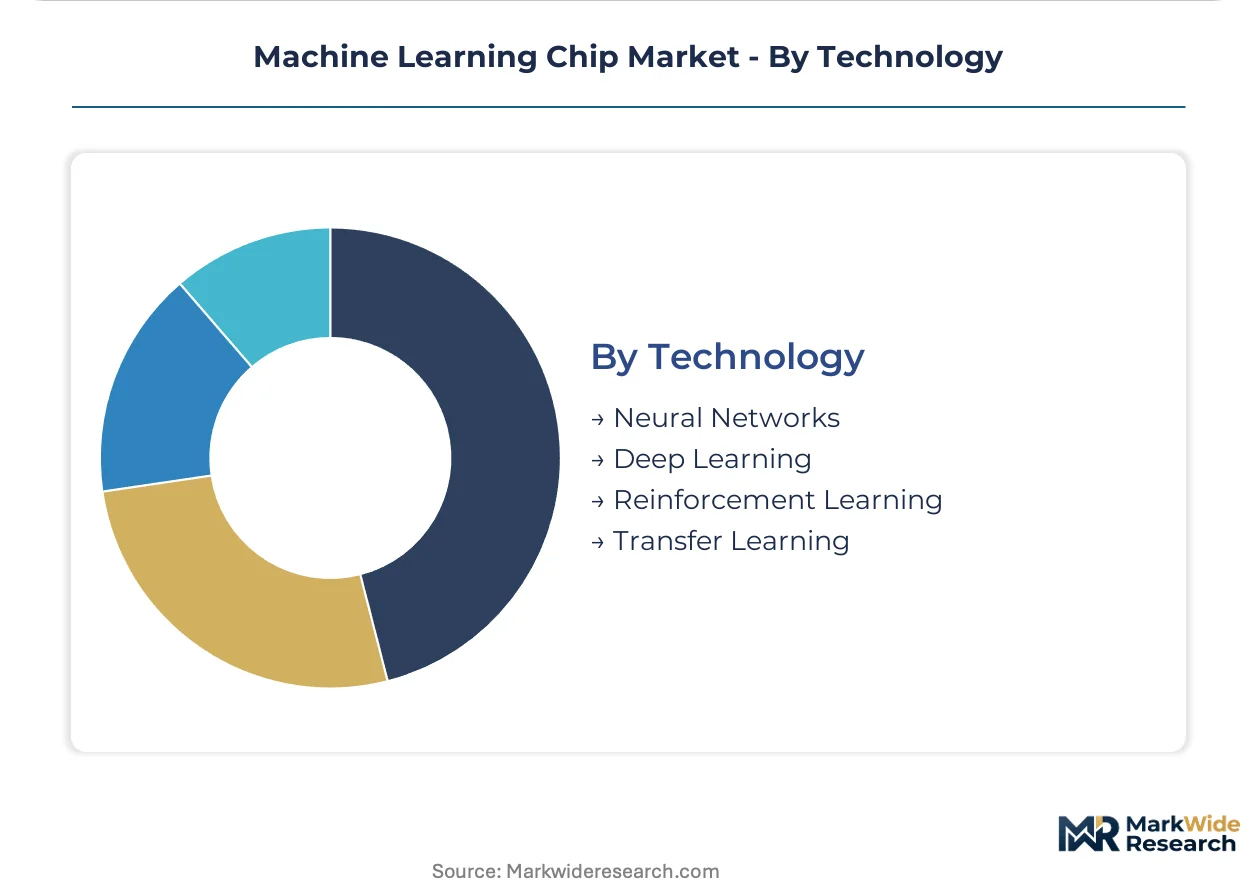
Technology:
Algorithm maturity shapes silicon validation requirements, with established methods enabling commodity hardware while frontier techniques demand experimental architectures.
- Deep Learning:Multi-layer neural networks with backpropagation training represent the dominant algorithmic paradigm, with GPU and TPU architectures optimized for dense matrix multiplication and tensor operations. Cloud providers standardize on this stack for general-purpose AI services.
- Neural Networks:Classical feedforward and recurrent architectures persist in industrial control and signal processing applications where interpretability requirements limit deep network adoption.
- Reinforcement Learning:Policy gradient and Q-learning methods for sequential decision-making require simulation-environment coupling, with robotics developers and game AI researchers driving specialized accelerator demand.
- Transfer Learning:Foundation model fine-tuning for domain-specific tasks enables enterprise AI deployment without massive training infrastructure, with pre-trained model marketplaces reducing hardware requirements for downstream adopters.
Deep Learning holds the incumbent position. Reinforcement Learning is climbing the fastest as autonomous systems multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise buyers in Germany demonstrate the lowest price elasticity, absorbing premium hardware costs for compliance-ready accelerators, while mid-market adopters in India exhibit acute sensitivity to per-inference pricing on cloud platforms.
United States
Hyperscale cloud providers in Washington State and Texas are commissioning dedicated AI infrastructure clusters with multi-year wafer supply agreements. The US CHIPS Act directs federal subsidies toward domestic leading-edge fabrication facilities in Arizona and Ohio. NVIDIA Corporation anchors its supply chain through Taiwan Semiconductor Manufacturing Company while qualifying Intel Foundry Services for diversification.
Taiwan
Foundry concentration creates procurement bottlenecks for machine learning chip designers seeking sub-3nm capacity for training accelerators. The National Development Council coordinates industrial policy to retain semiconductor ecosystem dominance amid geopolitical pressure. Hsinchu Science Park hosts the densest cluster of advanced packaging capacity, with CoWoS lines operating at full utilization for AI accelerator output.
South Korea
Memory suppliers in Icheon and Cheongju control global HBM3 and HBM3E allocation, dictating input costs for AI accelerator production. The Ministry of Trade, Industry and Energy administers K-Chips Act subsidies to expand domestic foundry capacity beyond memory into logic fabrication. Samsung Electronics integrates vertically from DRAM through advanced packaging to accelerate its foundry competitiveness.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg are qualifying low-power inference accelerators for manufacturing quality control and predictive maintenance. The EU AI Act imposes risk-tiered conformity assessment obligations that mandate chip-level traceability documentation. Dresden's Silicon Saxony cluster attracts EU Chips Act funding to establish European leading-edge fabrication capacity for AI hardware.
Japan
Electronics manufacturers in Kyushu and the Kanto region are deploying neuromorphic accelerators for always-on industrial sensor applications. METI coordinates national semiconductor strategy through the Rapidus consortium to reclaim leading-edge logic capability by 2027. Yokohama hosts concentrated advanced packaging R&D activity targeting chiplet-based modular AI accelerator designs.
Machine Learning Chip Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The machine learning chip market structures around a consolidated training accelerator segment and a fragmented inference optimization space. Three archetypes dominate: vertically integrated hyperscale designers with captive silicon programs, fabless specialists leveraging merchant foundry capacity, and cloud providers internalizing hardware development for infrastructure differentiation. Competitive moves center on multi-die packaging capacity capture and compiler ecosystem lock-in through proprietary software stacks.
Within the fabless accelerator tier, NVIDIA Corporation, Advanced Micro Devices, and Intel Corporation exemplify divergent strategic positioning. NVIDIA Corporation anchors the premium training segment through CUDA ecosystem dominance. Advanced Micro Devices occupies a challenger position with open-source software alternatives. Intel Corporation represents the integrated device manufacturer archetype pursuing foundry services alongside captive product development. Each occupies a distinct vector on the programmability-versus-efficiency spectrum that shapes procurement decisions among data center operators.
| Leading Market Players |
|---|
| NVIDIA Corporation |
| Advanced Micro Devices |
| Intel Corporation |
| Qualcomm Technologies |
| Samsung Electronics |
| Amazon Web Services |
| IBM Corporation |
| Cerebras Systems |
| Graphcore |
| Others |
Cost & Logistics Intelligence
CoWoS packaging lines at full utilization across Hsinchu Science Park are compressing gross margins for training accelerator vendors while amplifying pricing leverage for foundries and advanced packaging houses. This capacity scarcity feeds directly into procurement timelines and forces buyers toward multi-year supply agreements with escalating cost structures.
Pricing Analysis
Aftermarket service contracts for legacy inference hardware are narrowing as cloud providers shift toward subscription-based AI compute platforms. Three-tier pricing structure across premium training accelerators, standard inference chips, and economy edge processors stratifies by memory bandwidth and software ecosystem maturity. Cost compression in the standard tier is intensifying because hyperscalers are internalizing accelerator design and bypassing merchant silicon vendors. Mid-market enterprises exhibit acute price sensitivity to per-inference cloud pricing, while German automotive suppliers absorb premium hardware costs for EU AI Act compliance-ready accelerators.
Supply Chain Analysis
Foundry capacity concentration at Taiwan Semiconductor Manufacturing Company, Samsung Electronics, and Intel Foundry Services anchors global wafer supply for sub-5nm AI accelerators. High-bandwidth memory from Korean suppliers and advanced packaging substrates from Taiwanese providers constitute critical input dependencies. Single-source vulnerability in extreme ultraviolet lithography equipment access extends foundry expansion timelines and constrains second-tier designers. Distribution runs through direct foundry allocation for hyperscalers, distributor channels for industrial enterprises, and cloud intermediary platforms for SME adopters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
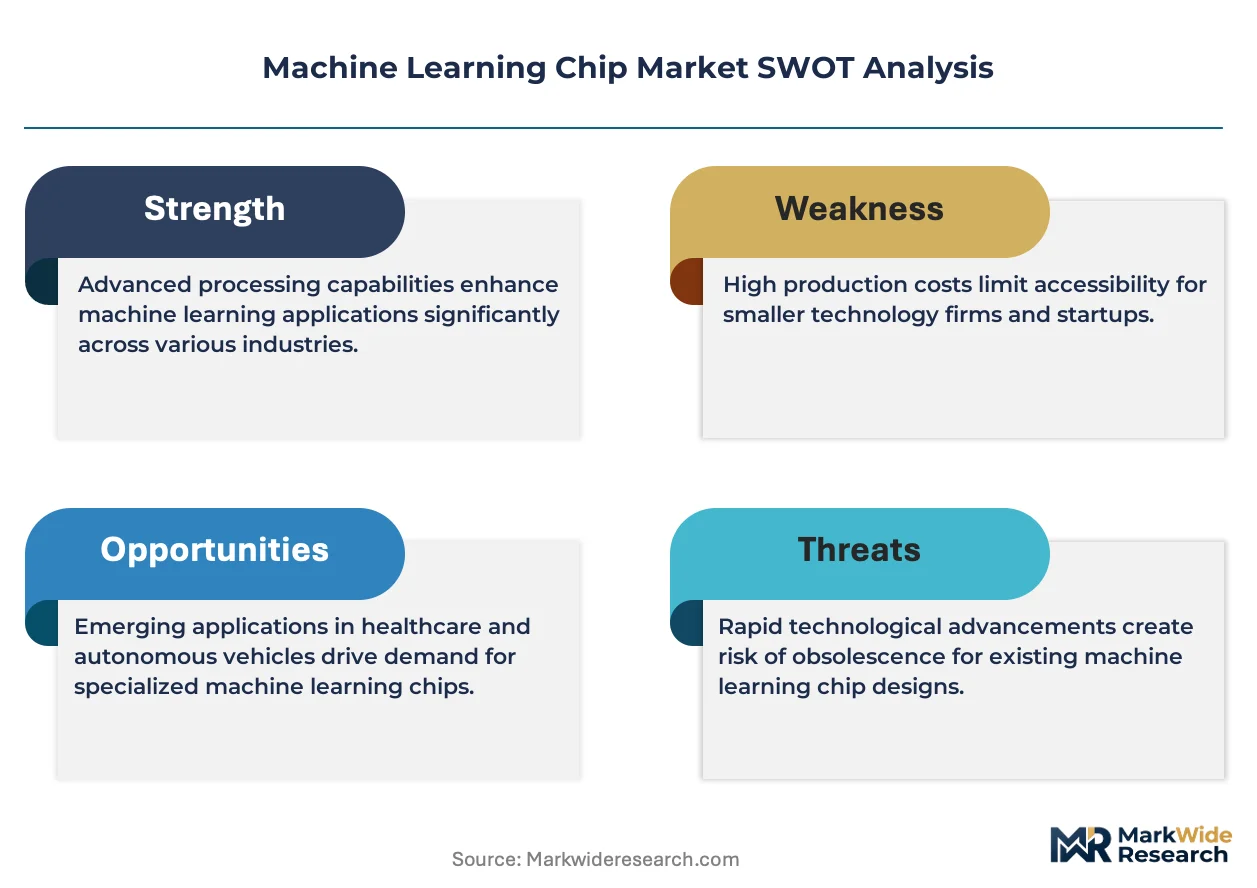
This market is emerging from a cyclical trough driven by hyperscale data center buildouts resuming after inventory correction. Capital expenditure normalization among cloud providers signals sustained procurement volume ahead.
For Market Incumbents: Insulate CUDA ecosystem dominance through compiler stack investments that raise switching costs for training workload customers. Secure multi-year CoWoS packaging allocation agreements to defend against supply-constrained competitors. Add captive wafer supply through US CHIPS Act facility partnerships to reduce Taiwan concentration risk.
For New Entrants and Emerging Players: Industrial edge deployment in German manufacturing facilities offers underpenetrated demand for low-power inference accelerators with deterministic latency specifications. Neuromorphic architecture development for always-on sensor applications in Japanese electronics manufacturing presents a second white-space target. Pursue qualification partnerships with automotive Tier 1 suppliers to bypass direct hyperscaler competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud providers with internal accelerator programs and subscription-based AI compute platforms. Long-term viability hinges on software ecosystem lock-in rather than transient silicon performance advantages. Target acquisition candidates with established compiler stacks and foundry relationships rather than pure-play hardware designers. Monitor hyperscaler capital expenditure guidance as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-die Packaging Capacity Capture | CoWoS line allocation from TSMC directly determines training accelerator output volumes. |
| Compiler Ecosystem Investment | CUDA and ROCm stack maturity shapes hyperscaler procurement decisions and switching costs. |
| Domestic Foundry Qualification | US CHIPS Act subsidies enable Intel Foundry Services as alternative to Taiwan supply. |
| HBM Supply Agreement | Long-term contracts with Samsung Electronics and SK Hynix secure memory bandwidth for accelerators. |
| EU AI Act Pre-certification | Documented traceability matrices from chip manufacturers compress compliance timelines for European buyers. |
Research Approach
A spread of perspectives from data center infrastructure planners, foundry account managers, AI accelerator architects, and enterprise IT procurement officers converged on the working assumptions for this analysis. Primary interviews with cloud provider hardware teams and semiconductor equipment suppliers combined with secondary validation from SEC filings, hyperscaler capital expenditure disclosures, and foundry utilization reports. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across the analysis window.
Demand-supply balance dynamics shaped the forecast framework, with hyperscale data center buildout trajectories, foundry capacity expansion schedules, and high-bandwidth memory allocation constraints as core inputs. Segmentation dimensions modeled include accelerator architecture type, workload application, end-user category, and technology maturity tier. CAGRs were derived from installed base growth and replacement cycle analysis rather than extrapolated from historical patterns. EU AI Act compliance timelines and US CHIPS Act subsidy disbursement schedules factored as regulatory inputs.
Practitioners should monitor export control regime adjustments on extreme ultraviolet equipment and hyperscaler inventory digestion rates for early signals of forecast revision. Quarterly review of foundry utilization reports and cloud provider capital expenditure guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Low-Power Wearable Chips Market
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
Audio Processor Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
ARM-Based Servers Market
Chipset and Processors
Cloud AI Chipsets Market
Chipset and Processors
Display Driver Market
Chipset and Processors
France Data Center Processor Market
Chipset and Processors
G Fast Chipset Market
Chipset and Processors
Optical Microcontrollers Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Netherlands Data Center Processor Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Europe Neuromorphic Chip Market