
 Middle East and Africa Image Sensors Market | 2026-2036
Middle East and Africa Image Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Image Sensors Market Foresight
A capital-intensity divergence between wafer-fabrication owners and fabless design houses is redrawing competitive boundaries across the Middle East and Africa Image Sensors Market. Sony Corporation leverages captive CMOS foundry capacity to anchor premium security and medical imaging contracts in the Gulf states. Samsung Electronics Co., Ltd competes through backward integration into display-driver ecosystems that bundle sensor modules for automotive OEMs. STMicroelectronics N.V differentiates via specialized time-of-flight architectures targeting industrial automation in South African mining corridors.
Image sensors are semiconductor devices that convert optical signals into electrical impulses, with CMOS architectures dominating due to lower power draw and on-chip integration of analog-to-digital conversion. These components serve as the optical front-end in cameras, machine vision systems, biometric scanners, and autonomous navigation platforms across commercial and industrial settings. CMOS product types command the widest deployment base, while infrared technology captures specialized defense and night-vision applications with concentrated margin pools. Security Systems applications outpace Consumer Electronics in absolute growth across the Middle East, driven by sovereign infrastructure spending and critical facility protection mandates.
The UAE's Telecommunications and Digital Government Regulatory Authority enforces data-localization standards for surveillance footage that dictate sensor-integrated encryption capabilities. Saudi Arabia's Saudi Standards, Metrology and Quality Organization mandates electromagnetic compatibility certification for imaging equipment deployed in smart city frameworks. South Africa's National Regulator for Compulsory Specifications governs safety compliance for medical imaging sensors entering clinical use. Stakeholders must monitor divergence between Gulf-state cybersecurity requirements and Sub-Saharan African import-certification pathways when configuring regional product portfolios.
Market Dynamics
Sovereign smart city mandates across the Gulf Cooperation Council are compressing procurement cycles for CMOS imaging modules, forcing suppliers to reconfigure certification pipelines around cybersecurity-hardened architectures before hardware deployment.
Growth Catalysts
- SFDA Medical Device Registration:Saudi Arabia's streamlined approval pathways for diagnostic imaging equipment are accelerating sensor adoption in private hospital networks.
- Mining automation protocols:South African platinum and gold operators are replacing manual shaft inspection with machine vision systems, creating sustained demand for ruggedized time-of-flight modules.
- MOHAP cybersecurity mandates:UAE surveillance infrastructure projects now require NIST-aligned encryption at the sensor level, favoring suppliers with integrated hardware-security capabilities.
Market Restraints
- Wafer fabrication concentration:Limited 300mm CMOS foundry capacity in the Middle East and Africa forces reliance on East Asian substrate suppliers, exposing procurement to shipping volatility.
- Import certification fragmentation:Divergent electromagnetic compatibility standards between Gulf states and Sub-Saharan markets inflate product adaptation costs for multi-territory deployments.
- Silicon carbide substrate pricing:Specialized sensor substrates for high-temperature industrial applications face input cost instability due to concentrated mining operations outside the region.
Strategic Opportunities
- Egyptian healthcare digitization:Government hospital modernization programs remain underpenetrated by premium imaging suppliers, creating first-mover potential for CMOS-based diagnostic equipment.
- Edge-AI convergence:On-chip neural processing integration with image sensors enables real-time defect detection without cloud dependency, opening industrial automation contracts.
- Direct procurement channels:Saudi smart city authorities are bypassing traditional distribution tiers for bulk security sensor orders, rewarding suppliers with localized technical support.
Industry Challenges
- Embedded firmware expertise gap:Regional system integrators lack depth in sensor-integrated encryption programming, slowing deployment timelines for cybersecurity-compliant installations.
- Multi-certification timelines:Simultaneous compliance with Saudi SASO electromagnetic standards and South African NRCS safety protocols extends product launch cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Image Sensors Market |
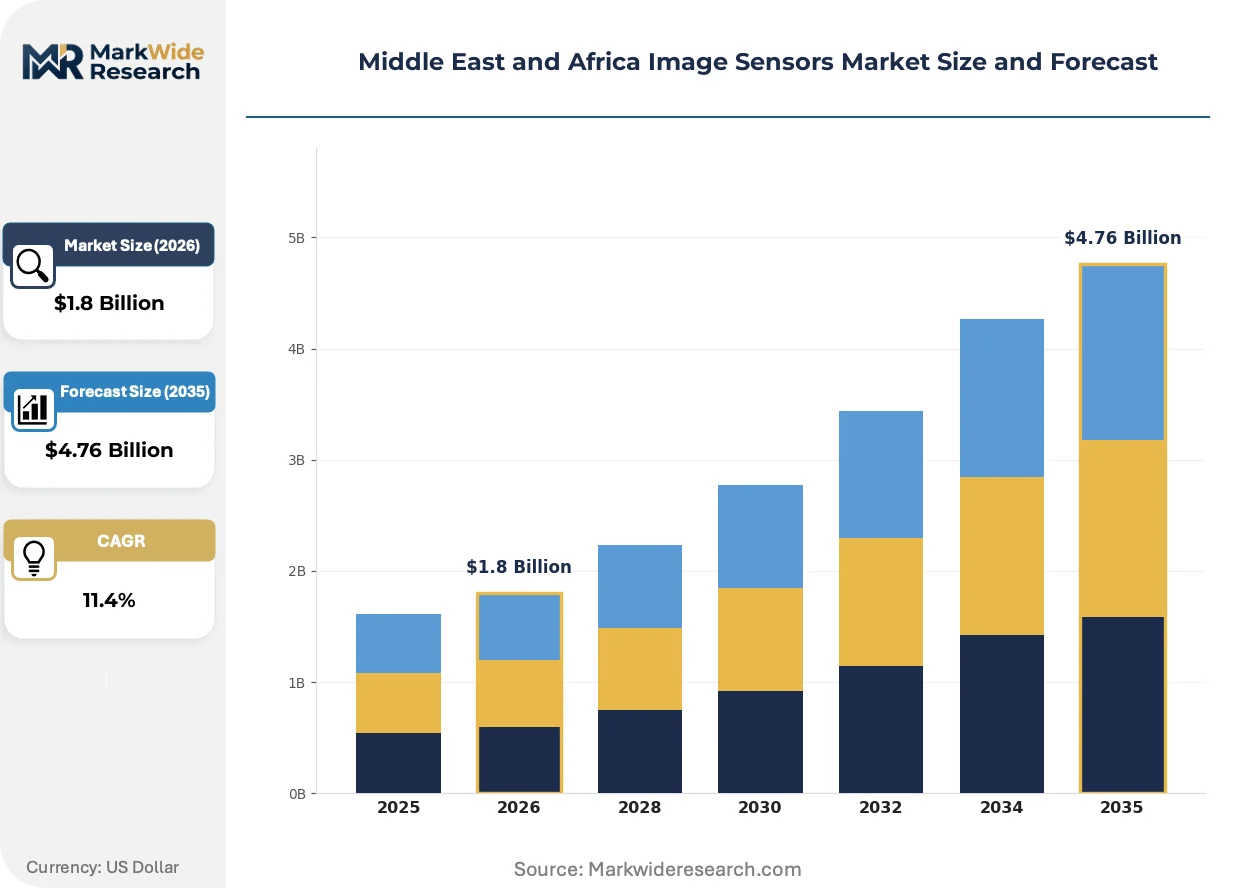
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CMOS, CCD, BSI, FSI Application: Consumer Electronics, Automotive Imaging, Security Systems, Medical Imaging End User: Retail, Healthcare, Automotive, Industrial Technology: Analog, Digital, Hybrid, Infrared |
| Companies Covered | Canon Inc., Omnivision Technologies, On Semiconductor Corporation, Deep Blue Sensor, Sony Corporation, Samsung Electronics Co., Ltd, STMicroelectronics N.V, Teledyne DALSA Inc., Toshiba Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Image Sensors Market Shifts & Advancements
Stacked CMOS architectures with backside illumination are displacing conventional front-illuminated designs across security and medical applications, compressing pixel pitch while preserving low-light sensitivity for Gulf state surveillance networks.
Backside-illuminated stacked CMOS sensors are miniaturizing pixel architectures below one micrometer without sacrificing quantum efficiency. Saudi security integrators are adopting these modules for high-density camera arrays in urban monitoring projects. The technology is miniaturizing optical form factors while maintaining resolution, enabling concealed deployment in heritage districts where visible infrastructure faces aesthetic restrictions.
UAE Telecommunications and Digital Government Regulatory Authority data-localization mandates now require surveillance footage encryption at the point of capture, not merely during transmission. This policy shift forces sensor manufacturers to embed hardware security modules within CMOS packages. Medical imaging equipment entering Dubai's healthcare procurement framework faces the strictest compliance timelines, with vendors accelerating firmware development to meet Q4 certification windows.
Consolidated tendering by Saudi sovereign wealth-backed infrastructure funds is concentrating purchasing power among fewer buyers with standardized technical specifications. Traditional distribution networks serving fragmented municipal security departments are losing share to direct manufacturer relationships. This pattern is most visible in Riyadh's smart city corridor, where single-source contracts for fifty-thousand-plus sensor deployments now bypass regional distributors entirely.
Middle East and Africa Image Sensors Market Segmentation
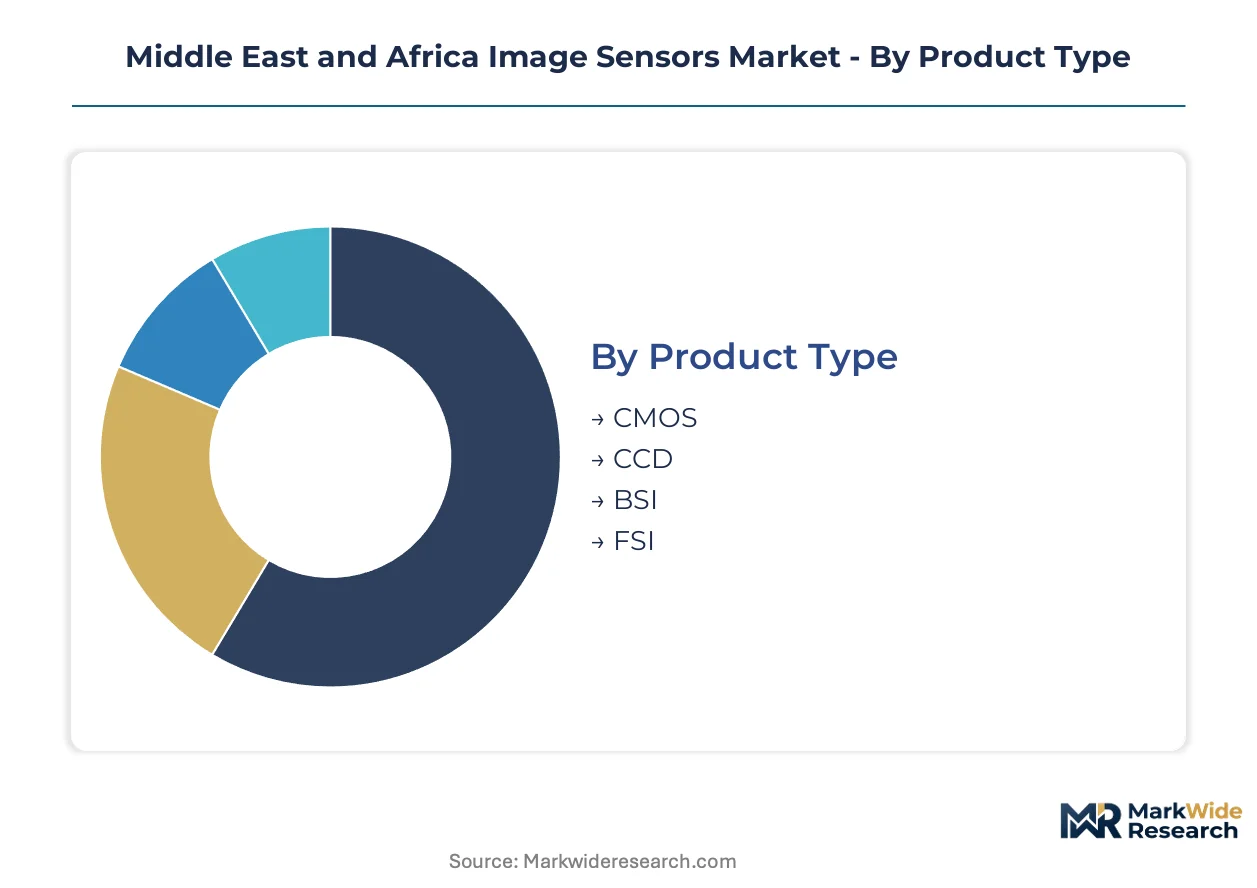
Image sensor procurement across the Middle East and Africa fragments across four distinct classification axes, each dictating divergent certification requirements and margin structures. Suppliers must configure product portfolios around technology type, application intensity, end-user procurement scale, and interface architecture to capture sovereign infrastructure spending.
Product Type:
Margin pools concentrate in backside-illuminated architectures and stacked CMOS designs serving premium security and medical applications across Gulf state smart city frameworks.
- CMOS:Complementary metal-oxide-semiconductor architectures integrate analog-to-digital conversion on-chip, enabling lower power draw and faster readout speeds. Saudi security integrators are standardizing on these modules for high-density urban surveillance arrays in Riyadh and Jeddah smart city corridors.
- BSI:Backside-illuminated sensors reposition photodiodes behind wiring layers, preserving quantum efficiency at sub-micrometer pixel pitches. UAE healthcare procurement frameworks specify these for diagnostic imaging equipment where low-light sensitivity determines clinical utility.
- CCD:Charge-coupled devices retain niche deployment in scientific instrumentation and legacy industrial inspection systems requiring uniform pixel response.
- FSI:Frontside-illuminated designs persist in cost-sensitive consumer electronics and entry-level security applications across North African markets.
CMOS holds installed capacity across commercial security networks. BSI is rotating up the share rankings in medical and high-performance imaging contracts.
Application:
Volume concentration tracks sovereign infrastructure mandates rather than consumer discretionary spending, inverting typical semiconductor demand patterns across the region.
- Security Systems:Surveillance networks in Saudi Arabia and the UAE require NIST-aligned encryption capabilities at the sensor level. SFDA procurement guidelines and MOHAP cybersecurity mandates are compressing vendor qualification timelines for hardware-secure modules.
- Medical Imaging:Diagnostic equipment in private hospital networks across Saudi Arabia and Egypt demands high-resolution CMOS modules with specialized color accuracy protocols. Streamlined SFDA registration pathways are accelerating sensor adoption in radiology and endoscopy systems.
- Consumer Electronics:Smartphone camera modules face margin compression from import tariff structures and fragmented distribution networks across Sub-Saharan Africa.
- Automotive Imaging:Advanced driver-assistance systems in South African vehicle assembly plants require ruggedized sensors meeting electromagnetic compatibility standards for harsh operating environments.
Security Systems anchors procurement volume through sovereign wealth-backed infrastructure funds. Medical Imaging is climbing the fastest as hospital digitization programs accelerate across Egypt and Saudi Arabia.
End User:
Procurement scale diverges sharply between centralized government health systems and fragmented retail distribution channels.
- Healthcare:Government hospital modernization programs in Egypt and diagnostic imaging networks in Saudi Arabia concentrate purchasing power among single-source contractors. SFDA registration requirements favor suppliers with localized technical support capabilities.
- Industrial:South African platinum and gold mining operators are replacing manual shaft inspection with machine vision systems, generating sustained demand for time-of-flight and ruggedized CMOS modules.
- Automotive:Vehicle OEMs and tier-one suppliers in South Africa specify imaging sensors for quality control and driver monitoring systems.
- Retail:Point-of-sale and inventory management applications face price sensitivity from fragmented SME procurement across North African markets.
Healthcare commands premium pricing through regulatory compliance requirements. Industrial is expanding most quickly as mining automation protocols standardize across South African extraction corridors.
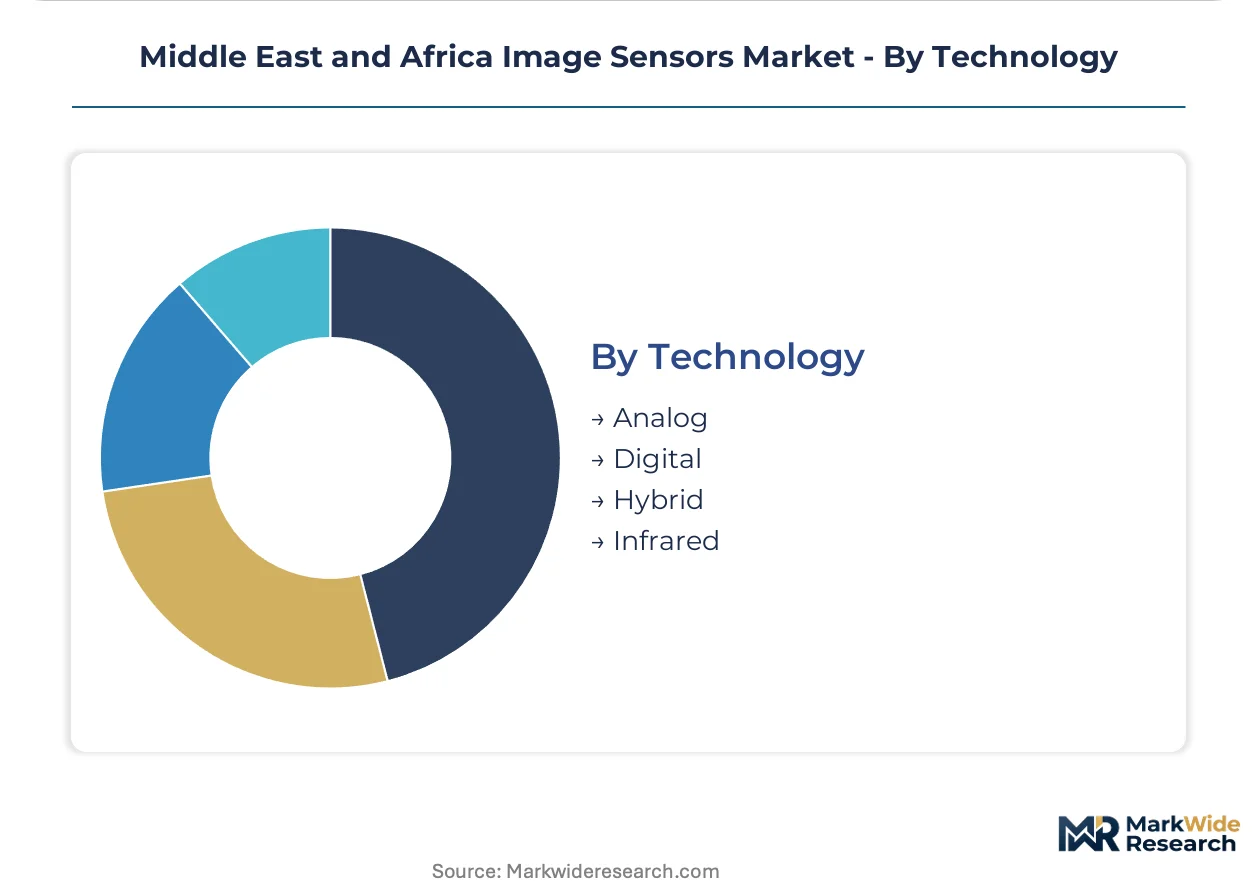
Technology:
Interface architecture determines system integration complexity and firmware development burden for regional system integrators.
- Digital:Native digital output eliminates external analog-to-digital conversion stages, reducing component count in space-constrained security camera housings. UAE smart city specifications increasingly mandate digital interfaces for encryption module integration.
- Infrared:Sensors optimized for near-infrared and thermal wavelengths serve night-vision security applications and industrial predictive maintenance in Saudi petrochemical facilities. Concentrated margin pools reflect specialized substrate requirements and limited supplier base.
- Analog:Legacy interface architectures persist in retrofit installations and cost-optimized consumer applications across price-sensitive North African markets.
- Hybrid:Mixed-signal designs combining analog front-ends with digital processing backends target medical imaging equipment requiring precise noise characterization.
Digital dominates new installation specifications across Gulf state infrastructure projects. Infrared is gaining share fastest in defense-adjacent and critical facility protection contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf state sovereign procurement corridors while Sub-Saharan African markets absorb cost-optimized modules through fragmented distribution channels.
Saudi Arabia
SFDA medical device registration pathways and smart city mandates compress vendor qualification timelines. SASO electromagnetic compatibility standards govern imaging equipment deployment in Riyadh's urban corridors. NEOM's northwest development zone sources bulk CMOS orders through direct manufacturer relationships, bypassing traditional distribution tiers.
United Arab Emirates
MOHAP cybersecurity mandates require NIST-aligned encryption at the sensor level for surveillance infrastructure. Dubai's healthcare procurement framework imposes strict compliance windows on diagnostic imaging equipment. Abu Dhabi's critical facility protection programs concentrate demand for hardware-secure modules among single-source contractors.
South Africa
Platinum and gold mining operators replace manual shaft inspection with machine vision systems, generating sustained demand for ruggedized time-of-flight modules. NRCS safety protocols govern medical imaging sensors entering clinical use. The Johannesburg-Pretoria corridor anchors industrial automation adoption across extraction and vehicle assembly operations.
Egypt
Government hospital modernization programs remain underpenetrated by premium imaging suppliers, creating first-mover potential for CMOS-based diagnostic equipment. The central health administration concentrates purchasing power among single-source contractors. Cairo's medical device distribution networks face certification bottlenecks that extend product launch cycles.
Israel
Defense-adjacent night-vision applications sustain concentrated margin pools for infrared sensor architectures. The national cybersecurity authority influences surveillance procurement specifications for critical infrastructure. Tel Aviv's technology corridor integrates edge-AI capabilities with imaging modules for autonomous navigation platforms.
Middle East and Africa Image Sensors Market Competitive Landscape
Concentration sits with integrated semiconductor conglomerates and specialized sensor design houses. Wafer-fabrication ownership separates premium-tier suppliers from fabless competitors dependent on East Asian foundry capacity. Two strategic archetypes dominate: captive foundry operators leveraging backward integration into substrate supply, and architecture specialists targeting time-of-flight and backside-illuminated niches. Competitive moves center on direct procurement channel cultivation with Gulf sovereign wealth funds and localized firmware development for cybersecurity-hardened deployments.
Among Asia-Pacific-based conglomerates, Sony Corporation and Samsung Electronics Co., Ltd exemplify the integrated archetype through captive CMOS foundry capacity and display-driver ecosystem bundling. STMicroelectronics N.V occupies a position within the European specialist tier, representing architecture-focused competition in industrial automation segments. These three anchors illustrate the divergence between wafer-fabrication ownership and fabless design strategies reshaping competitive boundaries.
| Leading Market Players |
|---|
| Canon Inc. |
| Omnivision Technologies |
| On Semiconductor Corporation |
| Deep Blue Sensor |
| Sony Corporation |
| Samsung Electronics Co., Ltd |
| STMicroelectronics N.V |
| Teledyne DALSA Inc. |
| Toshiba Corporation |
| Others |
Supply & Pricing Matrix
Silicon carbide substrate substitution for conventional silicon wafers in high-temperature industrial sensors simultaneously redraws procurement geography toward East Asian specialty foundries and compresses margin structures for Gulf state security integrators facing NIST-aligned cybersecurity mandates.
Pricing Analysis
The customization-premium spread between configured-to-order BSI modules and standard CMOS SKUs spans three-tier pricing structure across premium, standard, and economy levels. Project-based contract pricing dominates sovereign smart city tenders in Saudi Arabia and the UAE, where volume scale and certification grade drive price differentiation. Pricing pressure stems from consolidated tendering by Saudi sovereign wealth funds compressing supplier margins. Healthcare procurement shows least price sensitivity due to SFDA compliance requirements, while North African retail channels absorb maximum cost compression.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical logistics corridors for 300mm CMOS wafer shipments from Taiwan and South Korea to Gulf state assembly facilities. The regional supply chain draws from concentrated East Asian foundry capacity for silicon substrates, specialized glass for BSI architectures, and rare-earth dopants for infrared sensors. Single-source vulnerability concentrates in Taiwan Semiconductor Manufacturing substrate supply. Distribution runs through direct manufacturer relationships with Saudi NEOM and UAE smart city authorities, bypassing traditional tiered distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection arrives through edge-AI convergence with on-chip neural processing, where interoperability between sensor firmware and Gulf state cybersecurity frameworks determines contract viability.
For Market Incumbents: Fortify captive foundry utilization through backward integration into 300mm wafer supply, defending against fabless design houses penetrating Saudi healthcare digitization. Prioritize SASO electromagnetic compatibility pre-certification to compress Riyadh smart city vendor qualification timelines. Channel control through localized firmware development centers anchors premium security contracts. For New Entrants and Emerging Players: Differentiate on hardware-security module integration for UAE MOHAP surveillance mandates, where incumbent encryption capabilities lag regulatory requirements. Egyptian government hospital networks present the most penetrable geography, with centralized procurement and underdeveloped premium supplier presence. Pursue direct technical support partnerships with Cairo medical device distributors as primary go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European sensor design specialists possessing time-of-flight architectures but lacking Gulf state certification infrastructure. Long-term viability centers on regulatory compliance capabilities as sovereign cybersecurity mandates harden. Watch for SFDA registration pathway acceleration as inflection signal indicating premium healthcare sensor demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hardware Security Module Integration | UAE MOHAP mandates NIST-aligned encryption at sensor level for surveillance infrastructure compliance. |
| Direct Procurement Channel Cultivation | Saudi NEOM and smart city authorities bypass distributors for bulk CMOS orders exceeding fifty-thousand units. |
| Localized Firmware Development Centers | Regional system integrators lack embedded encryption expertise, creating service attachment opportunities. |
| SASO Pre-Certification Investment | Saudi electromagnetic compatibility standards compress vendor qualification timelines for Riyadh deployments. |
| Edge-AI Neural Processing Integration | On-chip defect detection without cloud dependency opens South African mining automation contracts. |
Research Methodology
A spread of perspectives from sensor design engineers, Gulf state procurement officers, South African mining automation directors, and medical device regulatory consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of integrated semiconductor conglomerates, SFDA medical device registration databases, and UAE Telecommunications and Digital Government Regulatory Authority policy disclosures. Bottom-up sensor shipment estimates and top-down semiconductor consumption models underwent triangulation across the analysis window.
Segmentation dimensions modeled span technology type, application intensity, end-user procurement scale, and interface architecture throughout the forecast period. CAGRs derive from regression analysis against sovereign infrastructure spending trajectories, with specific inputs including Saudi smart city procurement pipeline disclosures and South African mining automation protocol adoption curves. The analytical framework incorporates technology substitution curves for BSI displacement of FSI architectures.
The analysis sits within stated boundaries; outcomes outside sustained Gulf Cooperation Council infrastructure commitment or East Asian foundry capacity expansion would require recalibration. Forecasts reflect assumptions around regulatory timeline adherence and shipping corridor stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Cooled IR Camera Market
Imaging
Instant Digital Cameras Market
Imaging
North America Image Sensors Market
Imaging
Computational Photography Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Handheld Thermal Imaging Equipment Market
Imaging
Video Processing Solutions Market
Imaging
Global Automotive Imaging Market
Imaging
Photo Kiosk Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Hybrid Imaging Market
Imaging
Photography Equipment Market
Imaging
Webcam Market
Imaging
Asia Pacific Industrial Computed Tomography Market
Imaging
Machine Vision System and Services Market
Imaging
Industrial Computed Tomography Market