
 Americas Semiconductor Device Market | 2026-2036
Americas Semiconductor Device Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Semiconductor Device Market Insights
The U.S. CHIPS and Science Act is shifting capital allocation toward domestic wafer fabrication across the Americas. Intel Corporation anchors massive foundry investments in Arizona and Ohio, sustaining its vertical integration from design to packaging. NVIDIA Corporation dominates AI accelerator demand, leveraging its CUDA ecosystem to lock in data center customers. Texas Instruments Incorporated controls analog and embedded processing, competing through its 300-millimeter manufacturing scale.
A semiconductor device is an electronic component fabricated from crystalline silicon or compound semiconductors such as gallium nitride, engineered with doping concentrations measured in parts per billion to control electron flow. These devices perform switching, amplification, signal processing, and memory functions essential to all electronic systems. Integrated circuits command the largest value share due to their complexity and irreplaceability in computing, while discrete devices serve power management where discrete component reliability outperforms monolithic alternatives. RF technology is expanding fastest as 5G base stations and automotive radar multiply filter and amplifier demand.
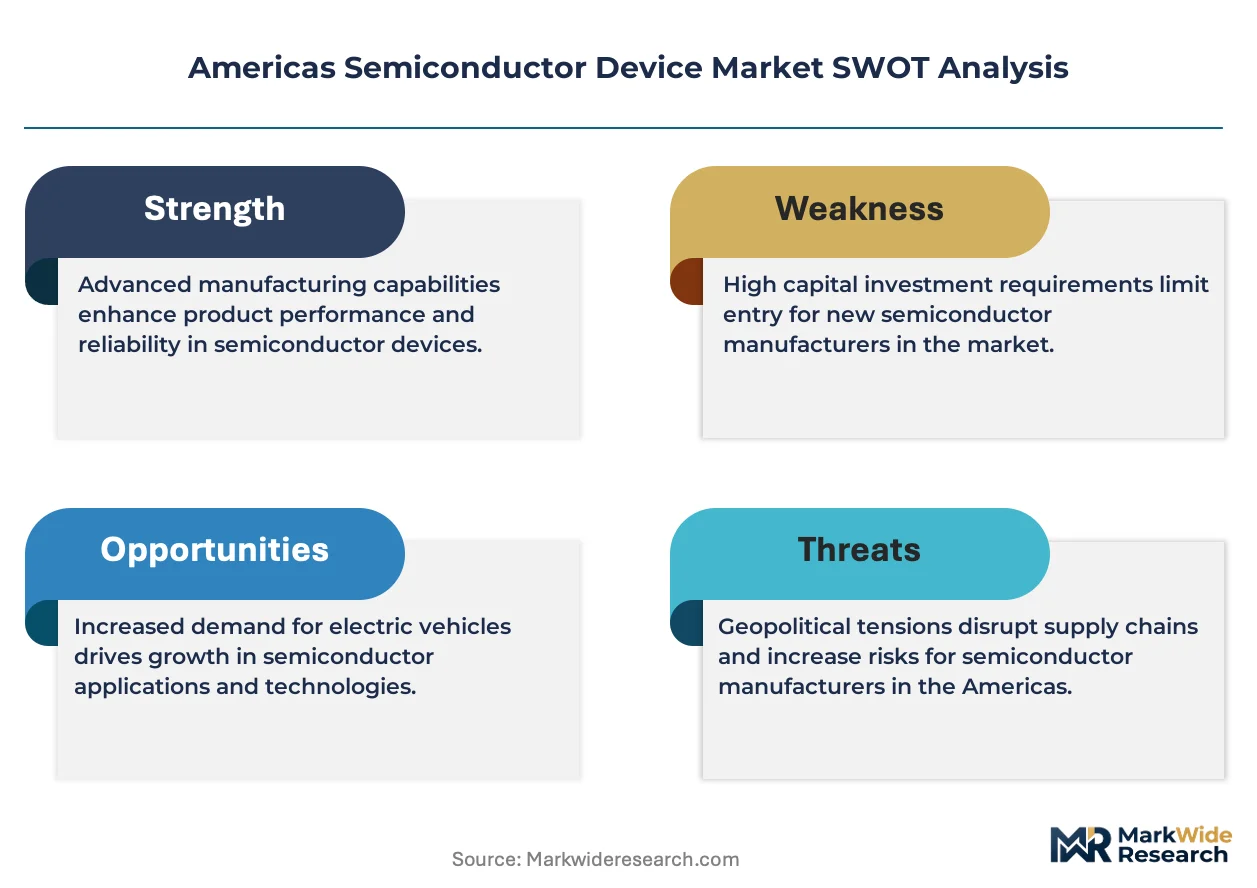
The U.S. Department of Commerce administers CHIPS Act funding disbursements, conditioning awards on domestic content thresholds and export control compliance. Mexico's Ministry of Economy coordinates nearshoring incentives for back-end assembly and test operations under USMCA rules of origin. The Federal Communications Commission spectrum auctions shape RF semiconductor specifications by defining bandwidth and power requirements. Stakeholders must monitor how Bureau of Industry and Security entity list updates redirect supply chains before committing to multi-billion-dollar fab investments.
Market Dynamics
Capital allocation across the Americas is pivoting toward captive wafer fabrication as the U.S. CHIPS and Science Act restructures subsidy eligibility around domestic content thresholds and export control alignment.
Growth Catalysts
- Electrification mandates:Automotive OEMs in the United States and Mexico are expanding silicon carbide inverter procurement for battery electric powertrains, pulling demand through the supply chain.
- CHIPS Act disbursements:The U.S. Department of Commerce conditions awards on domestic fabrication commitments, accelerating foundry construction timelines in Arizona and Texas.
- Nearshoring under USMCA:Mexico's Ministry of Economy coordinates back-end assembly incentives, redirecting Asian packaging capacity to Tijuana and Guadalajara clusters.
Market Restraints
- Equipment lead times:Extreme ultraviolet lithography systems from sole qualified suppliers stretch 18-24 months, constraining fab ramp schedules regardless of capital availability.
- Feedstock concentration:High-purity neon gas refining concentrates in Eastern European facilities, exposing Americas-based fabs to supply interruption cascades.
- Export control friction:Bureau of Industry and Security entity list updates force design rule modifications that fragment process development roadmaps.
Strategic Opportunities
- Advanced packaging:Heterogeneous integration of chiplets using 2.5D and 3D stacking opens margin expansion for U.S.-based OSATs serving AI accelerator customers.
- Brazilian industrial automation:Underpenetrated factory sensor deployment creates analog and embedded microcontroller demand as ANVISA certifies medical device manufacturing expansion.
- Canada clean tech:Federal investment tax credits for clean hydrogen production are pulling power semiconductor demand for electrolyzer inverters in Alberta and Quebec.
Industry Challenges
- Process engineer scarcity:300-millimeter fab operations in Ohio and Arizona compete for finite talent pools trained on legacy 200-millimeter equipment.
- Cleanroom construction bottlenecks:Specialized HVAC and vibration isolation contractors face capacity constraints that extend facility commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Semiconductor Device Market |
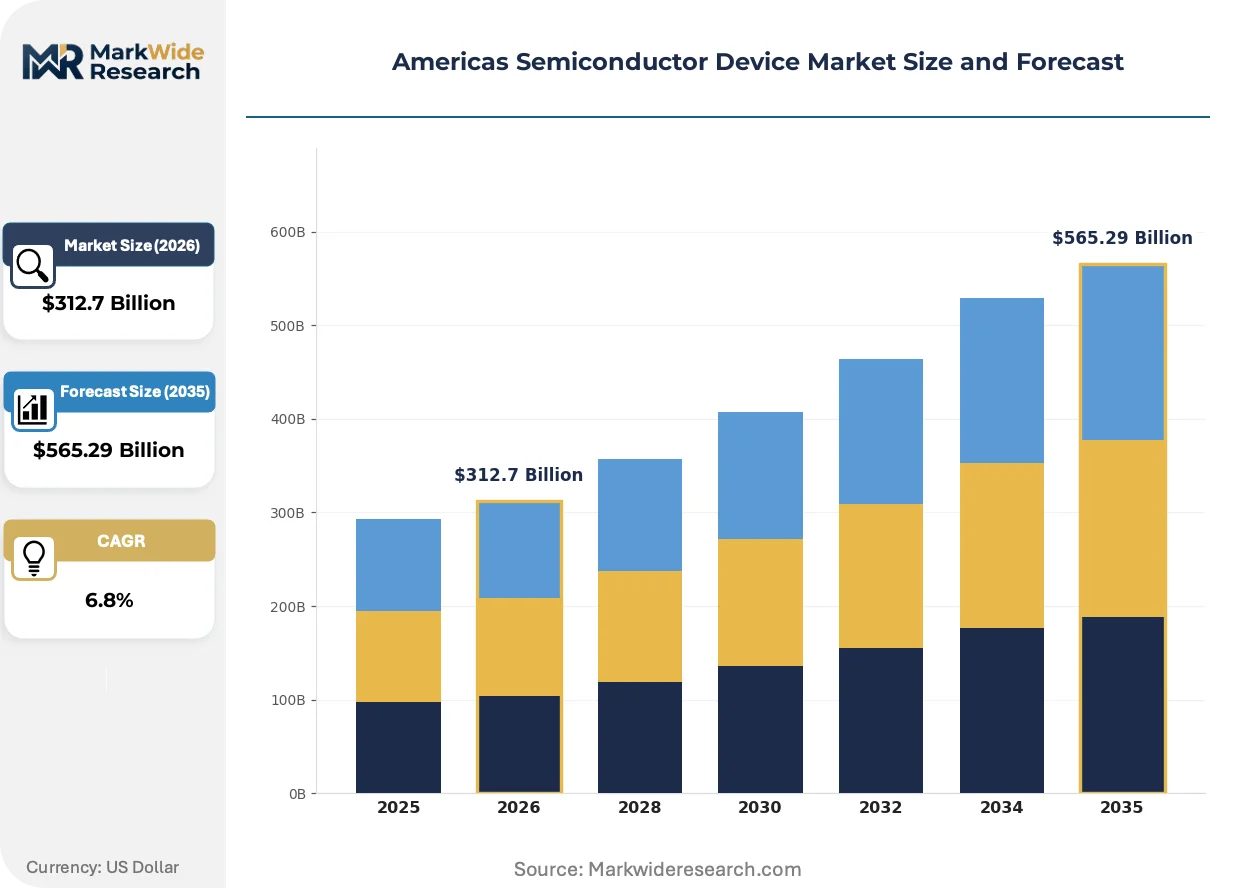
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $565.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Circuits, Discrete Devices, Optoelectronic Devices, Sensors Technology: Analog, Digital, Mixed-Signal, RF Application: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | Intel Corporation, NVIDIA Corporation, Qualcomm Incorporated, Texas Instruments Incorporated, Broadcom Inc., Advanced Micro Devices Inc., Micron Technology Inc., Analog Devices Inc., NXP Semiconductors N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Semiconductor Device Market Trends and Innovations
Process node migration and packaging architecture evolution are compressing competitive differentiation timelines across the Americas fabrication landscape.
Gallium nitride power devices are consolidating discrete component portfolios by merging switching and rectification functions into single die configurations. Electric vehicle drivetrain engineers at Tier 1 suppliers are adopting 650V and 900V GaN platforms for onboard chargers, collapsing the bill-of-materials count against silicon MOSFET alternatives. This consolidation is forcing analog incumbents to restructure product line profitability around integrated modules rather than discrete sales.
The U.S. Department of Commerce CHIPS Act disbursement rules are mandating domestic content thresholds that reshape supplier qualification protocols. Foundry operators must document wafer substrate provenance and equipment origin to maintain award eligibility, adding compliance overhead to process development cycles. Memory and logic segments with the most complex multi-national supply chains are responding by regionalizing chemical and gas sourcing to Arizona and Texas hub facilities.
Automotive OEM procurement teams are compressing qualification cycles for AEC-Q100 certified components from 18 months to 9 months to match platform development velocities. Tier 2 distributors are losing specification influence as direct foundry relationships replace catalog purchasing for high-volume powertrain semiconductors. This compression is most visible in Detroit and Stuttgart-aligned supply chains serving North American truck electrification programs.
Americas Semiconductor Device Market Segmentation
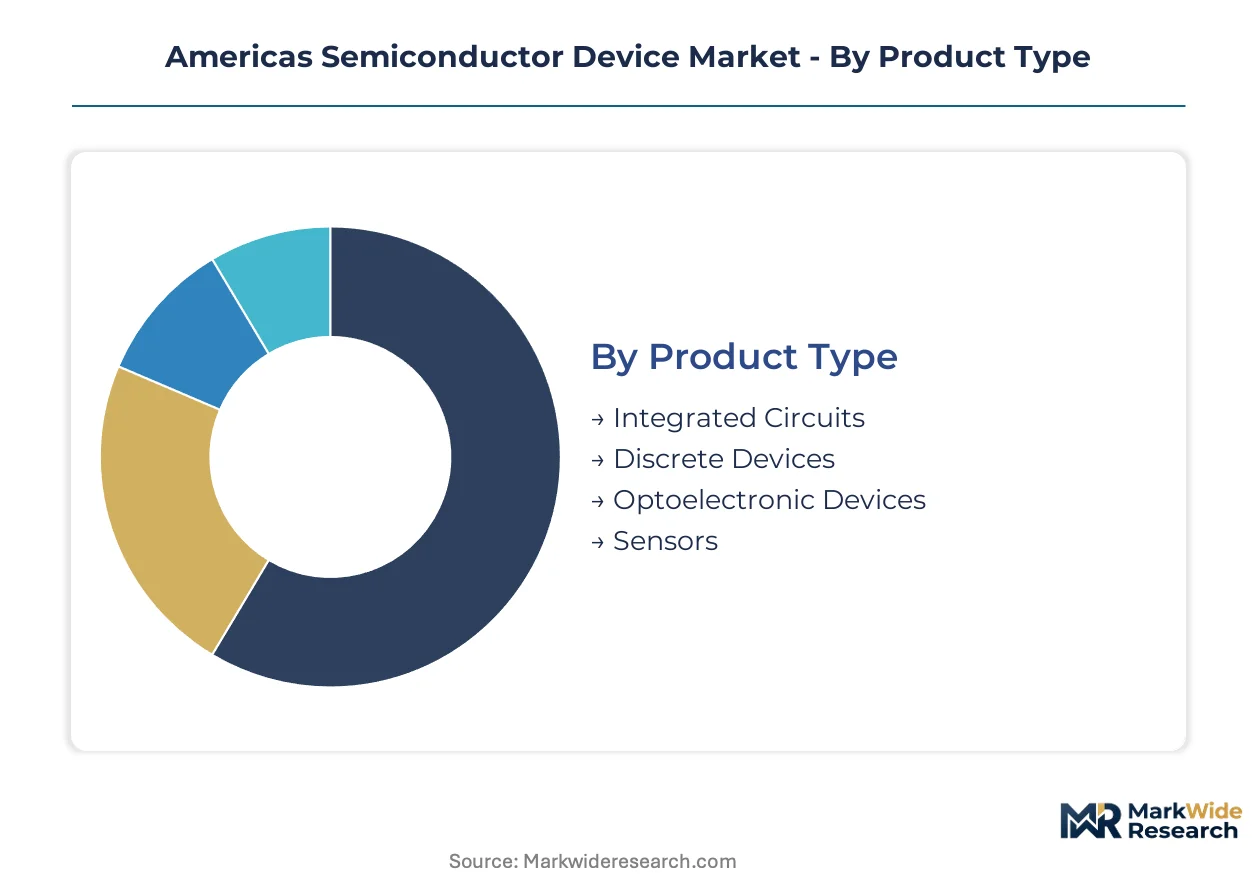
Semiconductor procurement in the Americas splits across technical specifications, supply chain tiers, and end-use reliability requirements. Buyers prioritize integration density for computing workloads, thermal performance for automotive powertrains, and RF precision for 5G infrastructure deployment.
Product Type:
Integration complexity drives cost-per-function economics and determines foundry process node selection.
- Integrated Circuits:Monolithic silicon dies containing billions of transistors fabricated at 7nm, 5nm, and 3nm nodes serve data center AI accelerators and mobile application processors. Arizona and Texas foundry clusters concentrate leading-edge logic production for hyperscale cloud customers under CHIPS Act domestic content rules.
- Discrete Devices:Individual transistors, diodes, and thyristors handle power switching above 100V where monolithic integration fails. Silicon carbide MOSFETs from Texas Instruments and Wolfspeed anchor electric vehicle inverter procurement in Detroit and Mexico City assembly plants.
- Optoelectronic Devices:LEDs, laser diodes, and photodetectors convert electrical signals to optical output for fiber communications and automotive LiDAR.
- Sensors:MEMS accelerometers, gyroscopes, and pressure transducers monitor vehicle dynamics and industrial equipment health.
Integrated Circuits leads on scale; Discrete Devices leads on momentum.
Technology:
Signal processing architecture determines design tool requirements and talent pool access.
- Analog:Continuous voltage and current manipulation circuits operate across temperature extremes without digital quantization. Texas Instruments dominates precision amplifiers and power management ICs for industrial automation in Brazil and medical devices under ANVISA certification pathways.
- Digital:Binary logic gates executing Boolean operations at gigahertz clock speeds form microprocessors, memory arrays, and AI accelerators. NVIDIA CUDA cores and AMD x86 architectures anchor hyperscale data center builds in Northern Virginia and Phoenix.
- Mixed-Signal:ADCs and DACs bridge analog sensors to digital processors in automotive engine control modules and factory automation controllers.
- RF:Radio frequency amplifiers, filters, and switches process electromagnetic waves from sub-6GHz to millimeter-wave bands. Qualcomm and Skyworks supply 5G base station components for FCC spectrum auction winners deploying C-band and mmWave infrastructure.
Digital technology commands the largest revenue base; RF technology expands most quickly.
Application:
End-use environmental specifications determine packaging, qualification, and margin structures.
- Consumer Electronics:Smartphones, laptops, and wearables prioritize die shrink and power efficiency over extended temperature ranges. Apple and Qualcomm procurement teams in Cupertino and San Diego drive 3nm adoption for mobile SoCs.
- Automotive Electronics:Powertrain controllers, ADAS sensors, and infotainment systems require AEC-Q100 qualification across -40°C to 150°C operating windows. Ford and General Motors direct sourcing teams in Detroit bypass distributors for silicon carbide MOSFET contracts.
- Industrial Automation:Programmable logic controllers, motor drives, and robotics demand 20-year supply continuity and extended temperature operation. Rockwell Automation and Siemens USA specify Texas Instruments C2000 microcontrollers for factory floor deployment.
- Telecommunications:Baseband processors, RF front-ends, and optical transceivers serve FCC-licensed spectrum holders building 5G networks. Ericsson and Nokia USA procurement concentrates in Dallas and Chicago for infrastructure rollout.
Automotive Electronics leads on momentum; Consumer Electronics leads on unit volume.
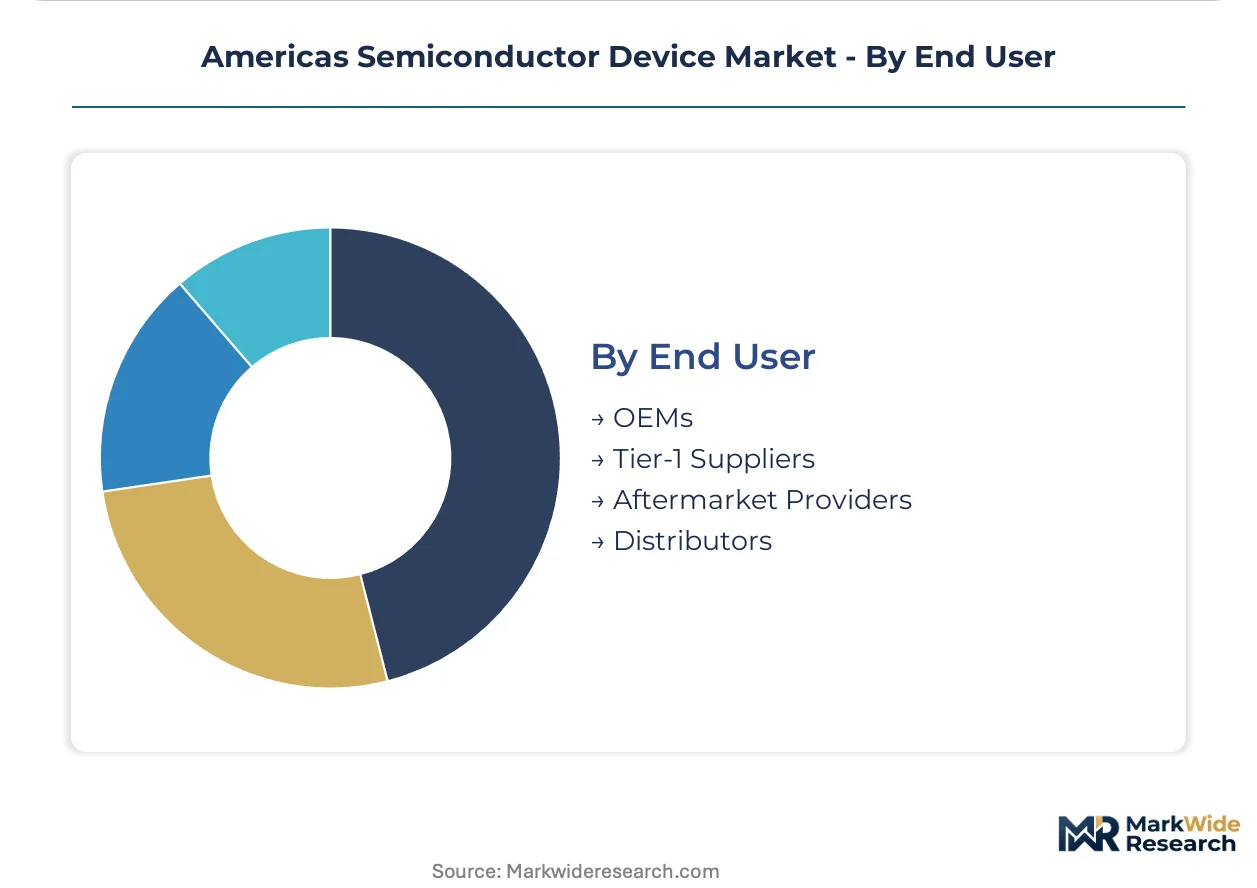
End User:
Supply chain position determines specification influence and inventory liability allocation.
- OEMs:Original equipment manufacturers with captive design teams specify die geometries and process nodes directly. Tesla and Rivian semiconductor engineering groups in Austin and Irvine negotiate foundry capacity allocation for autonomous driving compute platforms.
- Tier-1 Suppliers:Bosch, Denso, and Magna electronics divisions integrate semiconductors into subsystems for OEM vehicle platforms. These suppliers maintain buffer inventory and manage AEC-Q qualification documentation.
- Aftermarket Providers:Independent repair networks and refurbishment specialists source legacy node devices for extended vehicle and equipment service life.
- Distributors:Arrow Electronics and Avnet maintain inventory positions and technical support for mid-volume industrial and medical customers without direct foundry relationships.
OEMs lead on specification authority; Tier-1 Suppliers leads on procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The semiconductor device industry traces its modern origins to Silicon Valley's transistor manufacturing expansion during the 1950s and 1960s, establishing the United States as the foundational geography for integrated circuit design and fabrication before Asian manufacturing clusters emerged in subsequent decades.
United States
Federal CHIPS Act disbursements from the Department of Commerce are accelerating foundry construction timelines across Arizona and Texas, where Intel Corporation anchors massive fabrication investments. The Bureau of Industry and Security administers export control compliance conditions that reshape supplier qualification protocols for award recipients. Phoenix and Austin metropolitan areas concentrate leading-edge logic production capacity serving hyperscale cloud customers.
Mexico
Automotive OEM electrification programs in Mexico City and Monterrey are pulling silicon carbide inverter demand through North American supply chains as Tier 1 suppliers expand power electronics assembly. The Ministry of Economy coordinates nearshoring incentives for back-end packaging and test operations under USMCA rules of origin provisions. Tijuana and Guadalajara industrial corridors are absorbing redirected Asian packaging capacity for RF and power management devices.
Canada
Federal investment tax credits for clean hydrogen production are stimulating power semiconductor procurement for electrolyzer inverter systems in Alberta and Quebec. Health Canada and provincial energy regulators shape certification pathways for industrial automation components deployed in medical device manufacturing. Toronto-Waterloo technology corridor maintains design engineering talent pools serving AI accelerator and photonics applications.
Brazil
ANVISA certification expansion for medical device manufacturing is creating analog and embedded microcontroller demand as factory sensor deployment accelerates under industrial automation programs. The national development bank coordinates technology transfer incentives for semiconductor packaging joint ventures. São Paulo state concentrates industrial electronics procurement serving underpenetrated manufacturing automation markets.
Americas Semiconductor Device Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Americas fabrication ecosystem. The market structure concentrates around integrated device manufacturers with captive wafer capacity and specialized fabless designers outsourcing production to foundry partners. Three archetypes dominate: vertically integrated giants controlling design-through-packaging workflows, fabless specialists monetizing intellectual property through licensing, and pure-play foundries monetizing process technology at scale. Competitive intensity manifests through capacity expansion races for leading-edge nodes and strategic partnerships securing advanced packaging capacity.
Among integrated device manufacturers, Intel Corporation and Texas Instruments Incorporated occupy positions exemplifying divergent specialization strategies, while NVIDIA Corporation represents the fabless archetype leveraging ecosystem lock-in. Intel anchors vertical integration from Arizona and Ohio fabrication complexes. Texas Instruments maintains analog and embedded processing dominance through 300-millimeter manufacturing scale. NVIDIA exemplifies asset-light design supremacy in AI accelerators.
| Leading Market Players |
|---|
| Intel Corporation |
| NVIDIA Corporation |
| Qualcomm Incorporated |
| Texas Instruments Incorporated |
| Broadcom Inc. |
| Advanced Micro Devices Inc. |
| Micron Technology Inc. |
| Analog Devices Inc. |
| NXP Semiconductors N.V. |
| Others |
Pricing and Supply Chain Analysis
High-purity neon gas refining costs cascade from Eastern European facilities through Americas-based foundry pricing tiers, compressing margins at trailing-edge nodes while advanced packaging commands premium spreads. CHIPS Act domestic content thresholds force substrate provenance documentation that layers compliance overhead onto Arizona and Texas fab quotations.
Pricing Analysis
Contract-based long-term offtake agreements dominate hyperscale cloud procurement, separating AEC-Q100 automotive-grade premiums from consumer-tier spot purchasing. Price differentiation hinges on certification grade and volume scale, with Ford and General Motors direct sourcing teams extracting scale concessions unavailable to distributor-reliant industrial buyers. Cost compression in trailing-edge logic is intensifying because Mexican back-end assembly capacity is absorbing Asian packaging migration. Tier-1 suppliers exhibit lowest price sensitivity due to captive buffer inventory requirements, while aftermarket providers face acute margin pressure from legacy node scarcity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for leading-edge AI accelerators, while Arrow Electronics and Avnet intermediate mid-volume industrial flows. Raw silicon wafer supply concentrates in Taiwan, South Korea, and the United States, drawing from high-purity polysilicon feedstocks and photoresist chemical inputs. Single-source vulnerability in extreme ultraviolet lithography systems from sole qualified suppliers creates chokepoint exposure regardless of capital availability. Distribution runs through Detroit-aligned Tier-1 clusters for automotive powertrain semiconductors and Tijuana-Guadalajara corridors for RF device back-end operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas semiconductor device market reads as a late-cycle quality story, with automotive electrification and AI accelerator demand shifting procurement toward AEC-Q100 and leading-edge specifications that reward proven manufacturing scale.
For Market Incumbents: Hedge against gallium nitride displacement in onboard charging by accelerating silicon carbide module integration and securing captive wafer capacity in Ohio and Arizona before process engineer scarcity intensifies. Reinforce foundry relationships with hyperscale cloud customers through advanced packaging co-development, insulating against fabless AI accelerator designers capturing specification influence. For New Entrants and Emerging Players: Launch via direct OEM engagement in Brazilian industrial automation, where ANVISA-certified medical device manufacturing expansion is creating analog and embedded microcontroller white space underserved by established distributors. Target Canadian electrolyzer inverter demand in Alberta and Quebec, leveraging federal clean hydrogen investment tax credits to bypass entrenched power semiconductor incumbents. For Investors and Strategic Acquirers: Consolidation pressure builds where analog and mixed-signal specialists lack 300-millimeter manufacturing scale to match Texas Instruments cost structures. Long-term viability favors asset-light designers with CUDA-equivalent ecosystem lock-in or captive foundry operators with CHIPS Act award eligibility. Watch Bureau of Industry and Security entity list updates as inflection signals that redirect capital allocation before multi-billion-dollar fab commitments crystallize.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | Heterogeneous chiplet integration captures AI accelerator margin expansion in Arizona and Texas OSAT clusters. |
| Silicon Carbide Supply Agreement | Long-term offtake contracts with Detroit OEMs lock in powertrain inverter demand through battery electric platform ramps. |
| CHIPS Act Compliance Certification | Domestic content threshold documentation secures Department of Commerce award eligibility for foundry operators. |
| GaN Platform Standardization | 650V and 900V discrete consolidation collapses bill-of-materials count against silicon MOSFET alternatives in Tier-1 procurement. |
| Mexico Nearshoring Joint Venture | USMCA rules of origin alignment redirects Asian back-end capacity to Tijuana and Guadalajara packaging corridors. |
Research Methodology
Coverage spans the United States, Mexico, Canada, and Brazil, with primary inputs from each geography combining interviews with foundry operations executives, Tier-1 supplier procurement directors, automotive platform engineers, and semiconductor distribution channel managers. Secondary validation draws from SEC 10-K filings, Bureau of Industry and Security entity list updates, CHIPS Act award disbursement records, and USMCA trade flow databases. Bottom-up wafer shipment tallies triangulate against top-down OEM semiconductor content estimates.
Granularity-level modeling disaggregates revenue across product type, technology node, application vertical, and end-user supply chain position throughout the forecast period. CAGRs derive from wafer start projections, content-per-vehicle trajectories for battery electric powertrains, and hyperscale data center capex deployment patterns. Forecast inputs include foundry utilization rates, AEC-Q100 qualification cycle compression, and FCC spectrum auction bandwidth allocations shaping RF semiconductor specifications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export control escalation or neon gas supply interruption scenarios. Projections reflect assumptions regarding CHIPS Act disbursement timing, process node migration velocity, and automotive platform electrification adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
APAC Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Europe Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Global Vacuum Capacitors Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Europe Touch Screen Controllers Market
Semiconductor Devices
Japan Semiconductor Diode Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Field Effect General Purpose Transistors Market
Semiconductor Devices
Gan-On-Silicon Market
Semiconductor Devices
Graphene Electronics Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Spin Filters Market