
 North America Atomic Layer Deposition Market | 2026-2036
North America Atomic Layer Deposition Market Size, Share, and Industry Trends Forecast 2026-2036
North America Atomic Layer Deposition Market Analytics
Equipment leasing and project finance for ALD tools is reconfiguring competitive entry barriers, allowing mid-scale foundries to access deposition systems without full capital commitment. Applied Materials, Inc. leverages its vertical integration across deposition, etch, and metrology to bundle ALD offerings with broader fabrication suites. Lam Research Corporation anchors its position through R&D intensity in plasma-enhanced ALD architectures for 3D NAND production. Kurt J. Lesker Company specializes in smaller-batch research systems that occupy the university and national laboratory channel.
Atomic layer deposition is a thin-film manufacturing process that builds material one atomic layer per cycle through sequential, self-limiting precursor reactions, typically operating at temperatures between 150°C and 350°C with sub-nanometer thickness precision. The technique serves semiconductor fabrication by enabling conformal coating of high-aspect-ratio structures such as FinFET gates and 3D memory channels. Thermal ALD dominates current installed capacity due to its maturity in oxide and nitride dielectric applications, while plasma ALD captures fastest-growing demand for low-temperature metal and nitride films at advanced nodes. Multi-layer product configurations concentrate margin pools where alternating dielectric-metal stacks command premium pricing for gate-all-around transistor architectures.
EPA regulations govern precursor chemical emissions and waste handling from ALD operations, while OSHA standards mandate exposure limits for metalorganic compounds in fabrication facilities. The Department of Commerce export controls on advanced semiconductor manufacturing equipment shape which deposition technologies can deploy at foreign-owned facilities operating in North America. Foundries and equipment suppliers must monitor how BIS licensing requirements for critical precursor chemicals evolve alongside domestic content incentives in federal semiconductor funding programs.
Market Dynamics
Gate-all-around transistor architectures are forcing foundries to retool deposition capacity for atomic-scale conformality requirements, compressing equipment replacement cycles and concentrating procurement among vertically integrated suppliers.
Growth Catalysts
- CHIPS Act capital flows:Federal semiconductor manufacturing incentives in the United States are accelerating fab construction timelines and expanding ALD tool installation pipelines.
- 3D NAND layer stacking:Memory manufacturers are pushing vertical cell counts past 200 layers, multiplying ALD process steps per wafer.
- EPA emissions compliance:Stricter precursor handling mandates are phasing out older chemical vapor deposition systems that cannot meet containment standards.
Market Restraints
- Precursor supply concentration:High-purity metalorganic compounds rely on a limited base of specialty chemical suppliers concentrated in Germany and Japan.
- Equipment cost barriers:Single-wafer ALD systems require capital outlays exceeding $15 million per unit, restricting access for sub-300mm operations.
- Process temperature limitations:Thermal ALD cannot deposit certain metal nitrides below 300°C, excluding temperature-sensitive substrates.
Strategic Opportunities
- Mexico nearshoring corridor:Emerging backend packaging and test facilities in Guadalajara and Tijuana are creating demand for research-scale ALD systems.
- Plasma-enhanced convergence:Hybrid thermal-plasma architectures are opening low-temperature metal deposition for flexible electronics substrates.
- OSHA workplace safety mandates:Tightening exposure limits for trimethylaluminum and other precursors are accelerating replacement of open-loop chemical delivery systems.
Industry Challenges
- Process engineer scarcity:The intersection of surface chemistry, vacuum physics, and semiconductor device physics creates a shallow talent pool for ALD-specific roles.
- Legacy tool integration:Retrofitting 200mm-era facilities with ALD modules requires custom chamber interfaces and extended qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Atomic Layer Deposition Market |
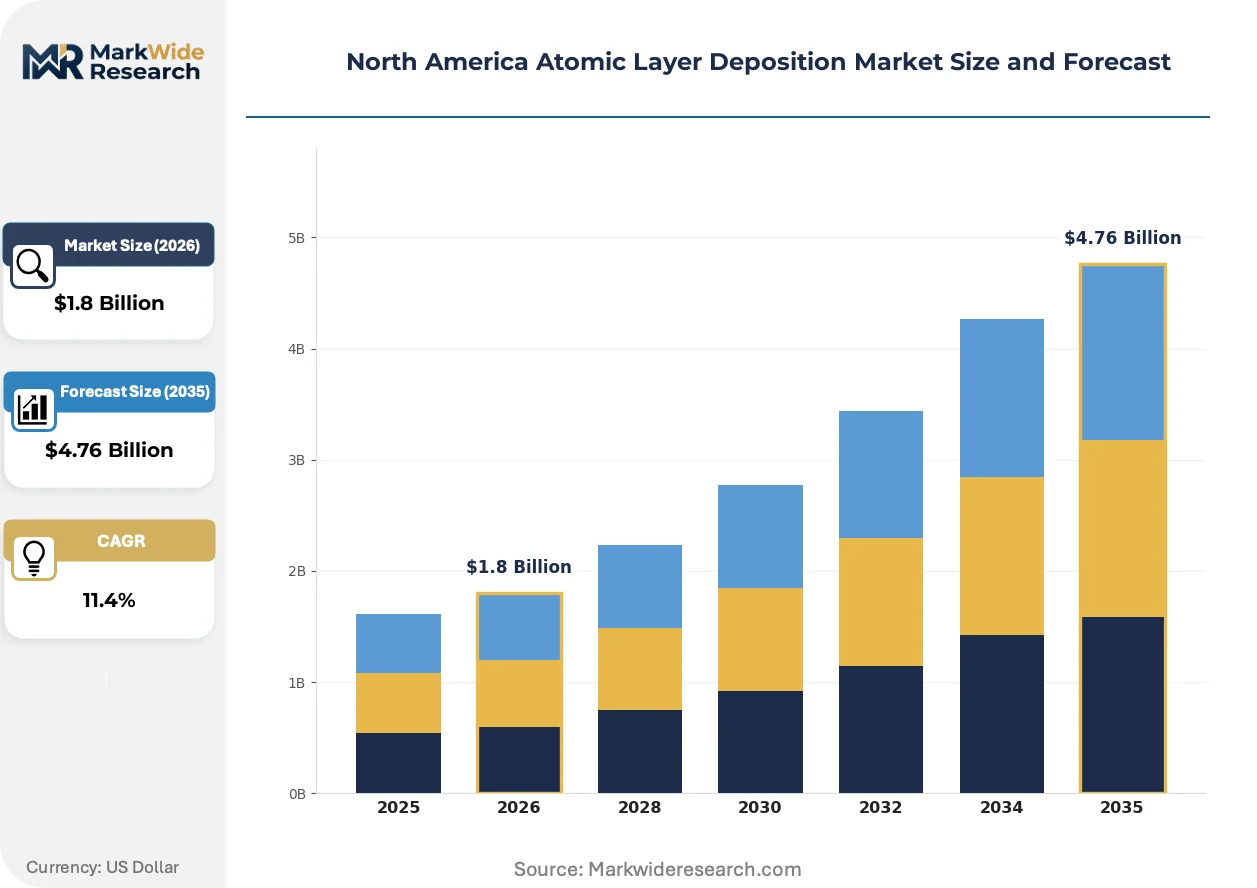
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Layer, Multi-Layer, Ultra-Fine Films, Others Technology: Plasma ALD, Thermal ALD, Catalytic ALD, Others End User: Semiconductors, Optoelectronics, Nanotechnology, Others Application: Coatings, Thin Films, Electronics, Solar Cells |
| Companies Covered | Applied Materials, Inc., Lam Research Corporation, ASM International, Tokyo Electron Limited, Veeco Instruments Inc., Kurt J. Lesker Company, Entegris, Picosun, ADEKA CORPORATION, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Atomic Layer Deposition Market Evolving Landscape
Equipment architectures are fragmenting between high-throughput production systems and flexible research platforms, while precursor chemistry and process control software become distinct competitive battlegrounds.
Spatial ALD is hybridizing wafer-scale throughput with atomic-layer precision by separating precursor exposure zones across moving substrates rather than time-sequenced pulses. Display manufacturers in South Korea and Taiwan are piloting spatial systems for OLED encapsulation, drawn by deposition rates tenfold faster than conventional temporal ALD. The technology is hybridizing cost structures in large-area coating applications previously dominated by sputtering or inkjet printing.
EPA New Source Performance Standards for semiconductor fabrication are tightening volatile organic compound capture requirements from ALD exhaust streams. Facilities in Texas and Arizona must now deploy point-of-use abatement for pyrophoric precursors rather than relying on centralized scrubbing infrastructure. Memory foundries with older exhaust architectures face retrofit investments exceeding $2 million per deposition bay.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale research operations and university cleanrooms. Lam Research and Applied Materials now offer throughput-guaranteed leases with bundled precursor supply and preventive maintenance, transferring obsolescence risk from capital-constrained buyers. The model concentrates most visibly in California's university corridor and Department of Energy national laboratories where federal grant cycles favor operational expenditure structures.
North America Atomic Layer Deposition Market Segmentation
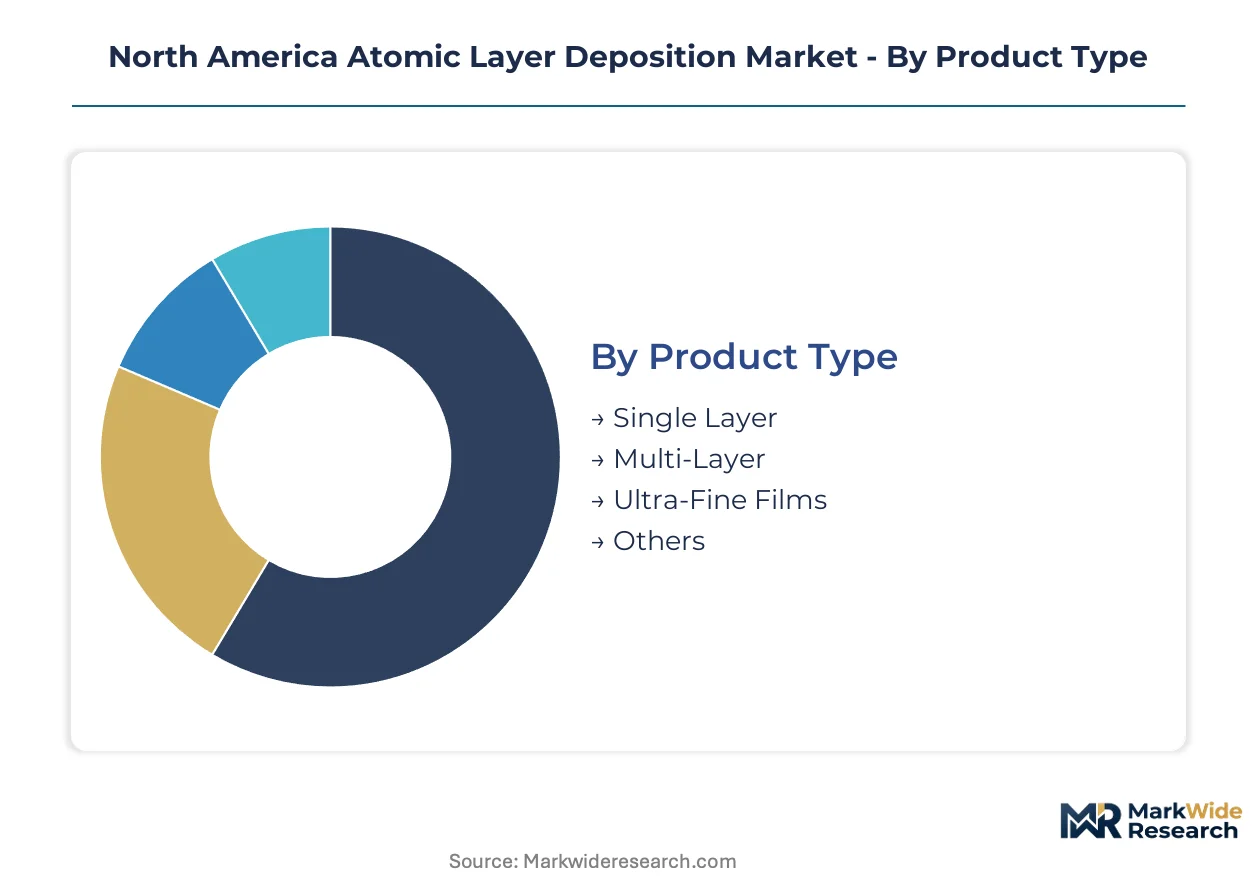
ALD market segmentation reveals how process requirements fragment across deposition complexity, energy delivery mechanisms, and end-use precision demands. Each dimension shapes equipment specifications, precursor chemistry portfolios, and service intensity.
Product Type:
Mature configurations dominate current fab installations, while emerging architectures address gate-all-around transistor roadmaps.
- Single Layer:Baseline dielectric deposition for oxide and nitride barrier films in mature logic nodes. Texas and Arizona foundries deploy these systems for 28nm and above manufacturing where conformality requirements remain modest.
- Multi-Layer:Alternating dielectric-metal stacks enabling gate-all-around transistor architectures. California's advanced node facilities concentrate procurement here as 2nm-class manufacturing ramps.
- Ultra-Fine Films:Sub-nanometer precision for quantum device fabrication.
- Others:Custom stack configurations for research applications.
Multi-layer handles the majority of throughput; ultra-fine films is the fastest mover on share.
Technology:
Cost tiers separate production-scale systems from flexible research platforms, with plasma architectures commanding premium positioning.
- Thermal ALD:Mature oxide and nitride deposition at 150-350°C operating windows. Installed base concentrates in legacy memory fabs across the United States where process stability outweighs temperature flexibility.
- Plasma ALD:Low-temperature metal and nitride deposition for advanced nodes. Canadian research institutes and U.S. national laboratories drive adoption for temperature-sensitive substrates.
- Catalytic ALD:Surface-reaction enhancement for selective deposition.
- Others:Emerging hybrid and spatial variants.
Thermal ALD carries the largest installed base; plasma ALD is expanding most quickly among new procurement.
End User:
Application concentration varies by customer type, with volume manufacturing separating from precision research on capital intensity.
- Semiconductors:Logic and memory fabrication driving multi-billion-dollar tool procurement. California's Silicon Valley and Texas's Austin-San Antonio corridor anchor demand for high-throughput production systems.
- Optoelectronics:Laser facet coatings and photonic device encapsulation. Arizona's optoelectronics cluster sources specialized systems for telecom and datacom component manufacturing.
- Nanotechnology:Research-scale deposition for quantum and 2D materials.
- Others:Medical device and aerospace coating applications.
Semiconductors handles the majority of throughput; optoelectronics is climbing the fastest on share.
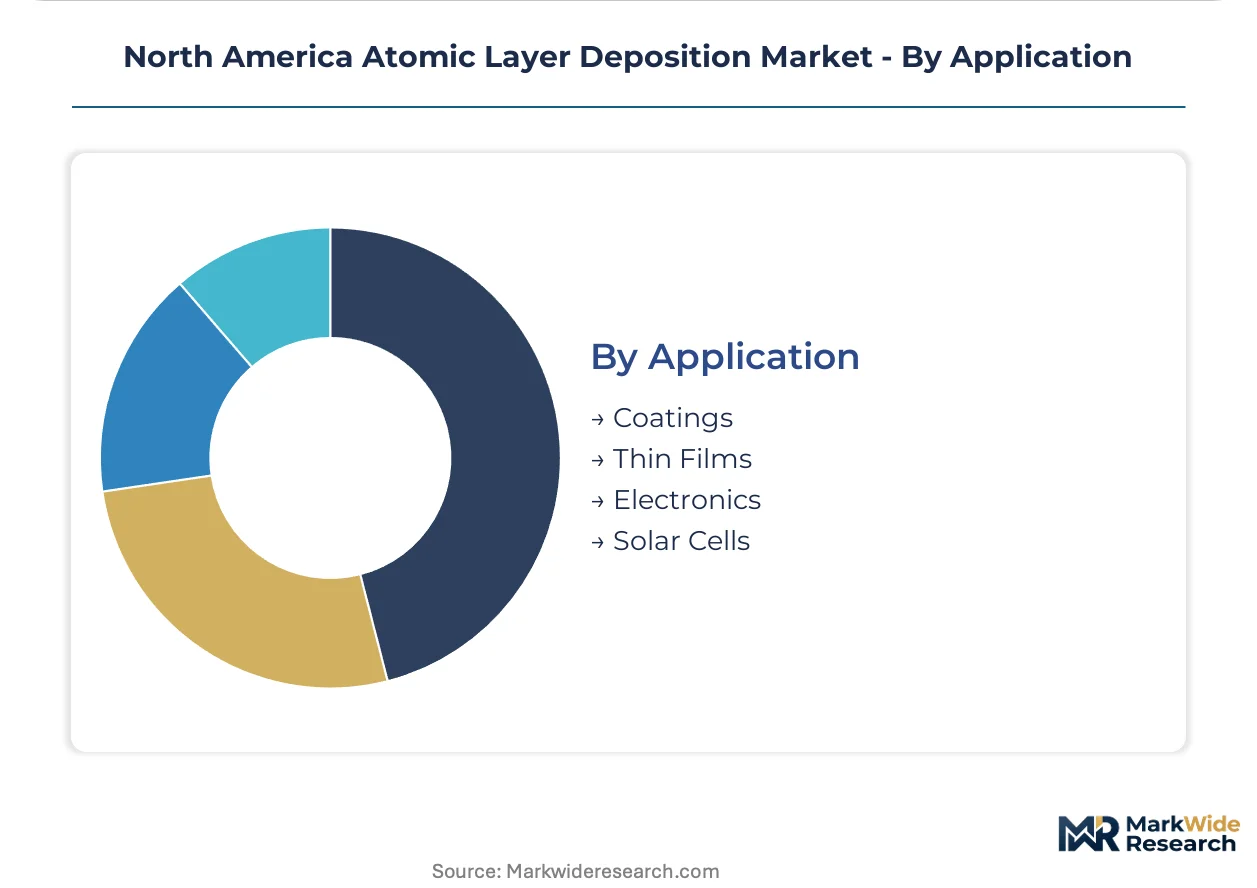
Application:
Volume scale separates wafer-level fabrication from specialized coating services, with electronics commanding the deepest tool penetration.
- Electronics:Transistor gate stacks, capacitor dielectrics, and interconnect barriers across logic and memory devices. EPA emissions compliance mandates in Texas and California fabs are accelerating replacement of legacy chemical vapor deposition with ALD.
- Coatings:Protective and functional layers for industrial components. Mexico's emerging packaging corridor in Guadalajara sources research-scale systems for pilot coating operations.
- Thin Films:Precision layers for MEMS and sensor applications.
- Solar Cells:Passivation layers for photovoltaic manufacturing.
Electronics handles the majority of throughput; coatings is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Atomic Layer Deposition market runs a structural trade deficit in high-purity metalorganic precursors, importing the majority of specialty chemicals from German and Japanese suppliers while exporting finished deposition equipment to Asian foundries. This imbalance shapes regional investment priorities and regulatory attention.
United States
CHIPS Act disbursements are accelerating fab construction in Arizona, Texas, and New York, with EPA New Source Performance Standards now mandating point-of-use abatement for pyrophoric precursor exhaust. OSHA workplace exposure limits for trimethylaluminum and tetrakis(dimethylamino)titanium are tightening chemical delivery system specifications. California's Silicon Valley concentrates advanced node procurement for gate-all-around transistor manufacturing at 2nm-class facilities.
Canada
National Research Council funding supports plasma-enhanced ALD development for temperature-sensitive substrates at institutes in Ontario and Quebec. Health Canada and PMRA jointly oversee precursor import licensing and environmental release assessments for fabrication facilities. Waterloo-Toronto corridor universities are deploying research-scale systems for quantum device fabrication, drawing equipment-as-a-service contracts from U.S. suppliers.
Mexico
Nearshoring momentum is building backend packaging and test capacity in Guadalajara and Tijuana, creating demand for smaller-batch research ALD systems. Mexican environmental regulations under SEMARNAT are adopting EPA-aligned emissions standards for semiconductor operations in border states. Guadalajara's emerging electronics cluster is piloting pilot coating operations for flexible substrate applications.
North America Atomic Layer Deposition Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated equipment suites that bundle deposition, etch, and metrology capabilities. Three strategic archetypes dominate: full-stack fabrication equipment conglomerates, specialized deposition technology pure-plays, and research-scale system specialists serving university and national laboratory channels. Competitive moves concentrate on equipment-as-a-service leasing structures and strategic partnerships with precursor chemical suppliers to secure supply chain positioning.
Within the full-stack tier, Applied Materials, Inc. and Lam Research Corporation exemplify integrated equipment strategies that span multiple fabrication steps. Kurt J. Lesker Company occupies the research-system specialist position, anchoring the university and national laboratory channel with smaller-batch configurations. These three entities represent distinct competitive postures without overlapping strategic territory.
| Leading Market Players |
|---|
| Applied Materials, Inc. |
| Lam Research Corporation |
| ASM International |
| Tokyo Electron Limited |
| Veeco Instruments Inc. |
| Kurt J. Lesker Company |
| Entegris |
| Picosun |
| ADEKA CORPORATION |
| Others |
Value Network & Pricing Analysis
German and Japanese precursor chemical clusters anchor North American ALD pricing power through concentrated high-purity metalorganic supply. Equipment manufacturers in California's Silicon Valley and Texas's Austin corridor pass through material cost volatility via long-term service contracts that bundle precursor supply with system leases.
Pricing Analysis
Industrial OEM buyers anchor equipment pricing through throughput-guaranteed leasing structures rather than capital purchase. Three-tier pricing structure across premium plasma-enhanced systems, standard thermal platforms, and economy research-scale units separates foundry procurement from university channel demand. Cost compression in thermal ALD segments is intensifying because Applied Materials and Lam Research bundle deposition tools with broader fabrication suites. Memory foundries exhibit lowest price sensitivity due to CHIPS Act capital subsidies, while mid-scale research operations face acute budget constraints driving equipment-as-a-service adoption.
Supply Chain Analysis
Department of Commerce export controls on advanced semiconductor manufacturing equipment limit flows of plasma-enhanced ALD systems to foreign-owned facilities operating in North America. High-purity metalorganic precursors draw from German and Japanese specialty chemical suppliers, while deposition equipment manufacturing rests on California and Texas production hubs. Single-source vulnerability concentrates in trimethylaluminum and tetrakis(dimethylamino)titanium supply where fewer than five qualified producers operate globally. Distribution runs through direct equipment sales for production-scale systems and regional distributor networks for research-scale configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
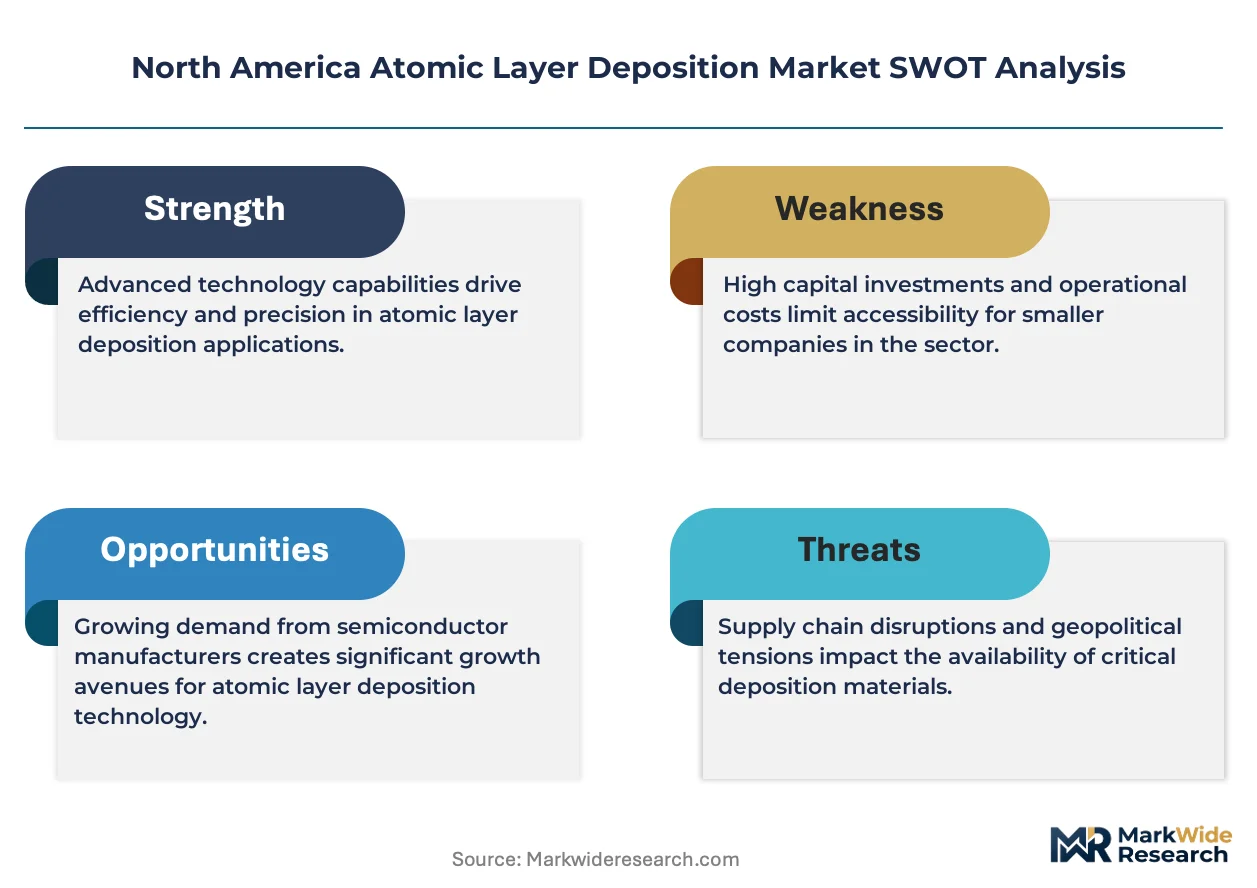
The North America ALD market presents a defensive moat built on regulatory entrenchment: EPA emissions compliance and OSHA workplace safety mandates create switching costs that lock foundries into validated equipment and precursor supply relationships.
For Market Incumbents: Pre-empt emerging spatial ALD competition by accelerating R&D investment in hybrid thermal-plasma architectures for flexible electronics substrates. Lock in foundry relationships through exclusive precursor supply agreements that satisfy tightening EPA point-of-use abatement requirements. Defend against Asian equipment pure-plays by deepening service intensity in CHIPS Act-funded fabs across Arizona and Texas. For New Entrants and Emerging Players: Establish a beachhead in Mexico's Guadalajara packaging corridor where nearshoring momentum creates demand for research-scale ALD systems without incumbent saturation. Target university and national laboratory channels in the Waterloo-Toronto corridor through equipment-as-a-service contracts that align with federal grant expenditure structures. Differentiate through specialized plasma-enhanced configurations for temperature-sensitive quantum device fabrication where Applied Materials maintains lighter presence. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers bundling preventive maintenance with precursor supply, offering superior cash flow predictability over transactional system sales. Long-term viability centers on suppliers with captive precursor chemistry capabilities that insulate margins from German and Japanese supply concentration. Watch for inflection signals in BIS licensing requirements for critical precursors, which would reshape competitive positioning for domestic chemical producers.| Strategic Initiative | Industry Significance |
|---|---|
| Precursor Supply Agreement | Locks in foundry relationships through EPA-compliant chemical delivery systems. |
| Plasma-Enhanced R&D Investment | Captures low-temperature metal deposition demand from gate-all-around transistor roadmaps. |
| Equipment-as-a-Service Expansion | Aligns with federal grant structures at Department of Energy national laboratories. |
| Mexico Channel Development | Positions for Guadalajara packaging corridor growth under SEMARNAT-aligned standards. |
| Hybrid Thermal-Platform Launch | Addresses flexible electronics substrates where thermal ALD temperature limits exclude. |
Research Methodology
A standing panel of fab operations directors, precursor chemical procurement leads, equipment R&D directors, and university cleanroom managers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC 10-K filings of publicly traded equipment manufacturers, EPA New Source Performance Standards documentation, BIS export control licensing records, and CHIPS Act disbursement disclosures. Bottom-up demand modeling triangulated against top-down equipment shipment data from semiconductor capital expenditure trackers.
Scenario bracketing anchored volume and value outputs across the projection horizon through sensitivity testing of CHIPS Act funding trajectories and EPA regulatory stringency pathways. Segmentation dimensions spanned product type complexity, technology energy delivery mechanism, end-user capital intensity, and application precision requirements. CAGRs derived from equipment installation pipeline analysis and foundry capacity expansion announcements. Industry-specific inputs incorporated gate-all-around transistor node migration timelines and 3D NAND layer stacking roadmaps.
Sensitivities concentrate around BIS licensing requirement shifts for critical precursors and OSHA exposure limit revisions for metalorganic compounds. Forecasts reflect assumptions regarding CHIPS Act disbursement continuity and EPA emissions standard phase-in schedules. Material shifts in export control scope or precursor supply chain regionalization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Fabrication
Semiconductor Advanced Substrate Market
Semiconductor Fabrication
Porous Silicon Substrates Market
Semiconductor Fabrication
Global Spark Plasma Sintering Market
Semiconductor Fabrication
Semiconductor Fab Water Reuse Systems Market
Semiconductor Fabrication
Global Dielectric Etchers Market
Semiconductor Fabrication
Mask Alignment Lithography Market
Semiconductor Fabrication
Global Atomic Layer Deposition Market
Semiconductor Fabrication
Ion Implanter Market
Semiconductor Fabrication
Global Micromachining Market
Semiconductor Fabrication
Solar Ingot Wafer Market
Semiconductor Fabrication
Semiconductor Etching Cleaner Market
Semiconductor Fabrication
Gan Substrate and Gan Wafer Market
Semiconductor Fabrication
Manual Wafer Aligner Market
Semiconductor Fabrication
Solar Grade Wafer Market
Semiconductor Fabrication
Photoresist Removal Market
Semiconductor Fabrication
Global Dry Etching Machine Market