
 Endovascular Aneurysm Repair Market | 2026-2036
Endovascular Aneurysm Repair Market Size, Share, and Industry Trends Forecast 2026-2036
Endovascular Aneurysm Repair Market Intelligence
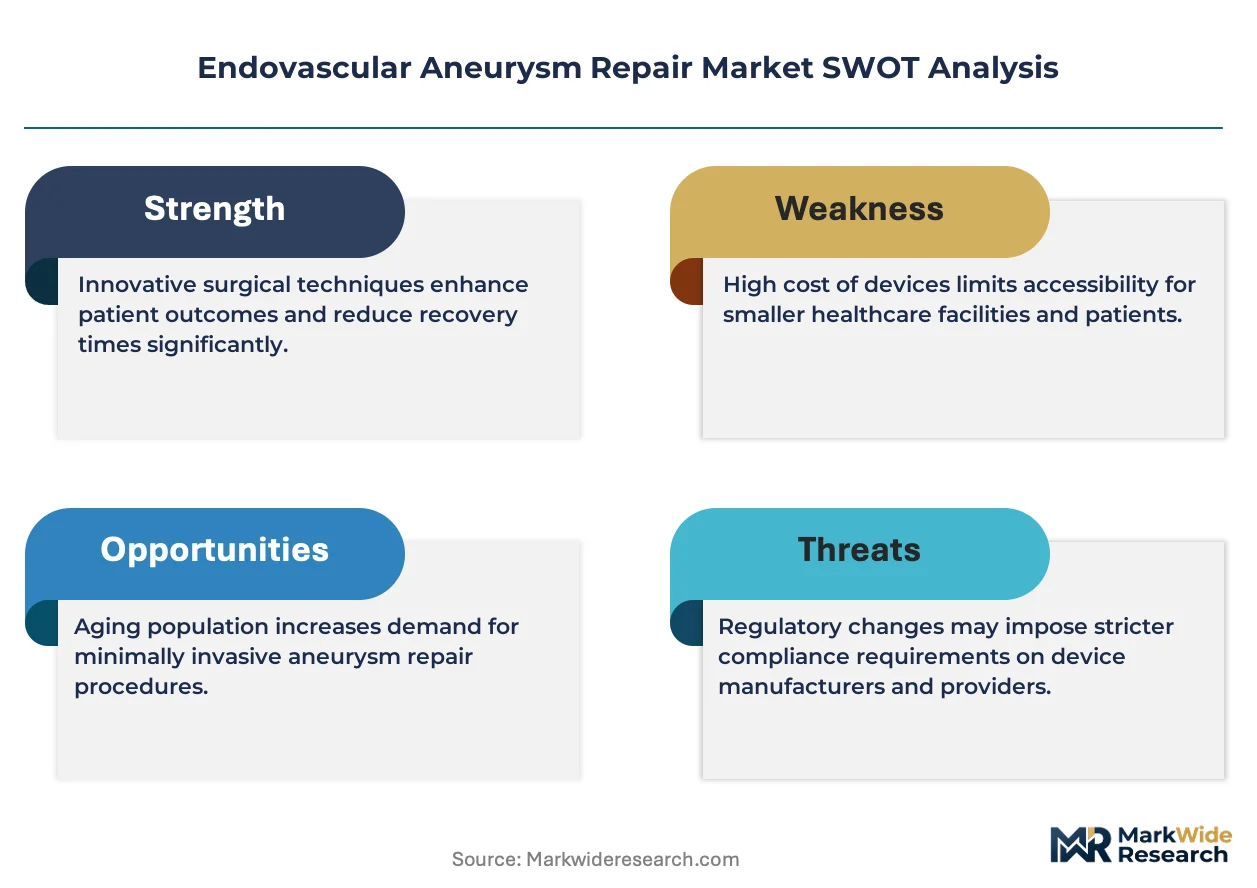
The EU Green Deal's push for sustainable manufacturing is broadening scrutiny of medical device supply chains, prompting nitinol and polymer suppliers to document carbon footprints. Medtronic leverages its integrated manufacturing footprint to control stent graft quality from alloy sourcing through final sterilization. W. L. Gore & Associates sustains its position through proprietary expanded polytetrafluoroethylene membrane technology that differentiates its graft sealing zones. Terumo Corporation anchors its competitiveness in Asia-Pacific through region-specific regulatory navigation and localized clinical training infrastructure.
Endovascular aneurysm repair deploys catheter-delivered stent graft systems to exclude aneurysmal aortic segments from arterial circulation without open surgical exposure, typically requiring femoral artery access and fluoroscopic guidance. Nitinol superelasticity enables graft self-expansion at body temperature while maintaining conformability to tortuous iliac anatomy. Stent grafts command the largest value share among product categories due to their complexity and recurring replacement cycles. Fenestrated repair procedures are expanding fastest as custom-manufactured grafts with visceral vessel preservation gain adoption for juxtarenal aneurysms that fall outside standard infrarenal indications.
FDA premarket approval and EU MDR notified body conformity assessments shape device commercialization timelines, with both regulators demanding long-term durability data from prospective registries. Japan's PMDA maintains distinct clinical evidence requirements that delay market entry relative to Western approvals. Stakeholders must monitor evolving evidence standards for branched and fenestrated systems, as these complex graft categories face intensifying scrutiny over their learning curves and center-of-excellence requirements.
Market Dynamics
Fenestrated and branched stent graft systems are compressing the addressable patient population for open surgical repair, forcing manufacturers to recalibrate clinical evidence generation and center-of-excellence certification programs around complex endovascular procedures.
Growth Catalysts
- EU MDR conformity assessments:The Medical Device Regulation's heightened scrutiny of long-term durability data is accelerating consolidation among manufacturers capable of funding prospective registry studies, privileging established players with integrated clinical affairs infrastructure.
- Japan's aging demographic:The Ministry of Health, Labour and Welfare's reimbursement frameworks for minimally invasive aortic interventions are expanding procedural volumes in tertiary cardiovascular centers across Tokyo, Osaka, and Nagoya.
- Nitinol superelasticity:This nickel-titanium alloy's shape-memory properties enable graft self-expansion at body temperature, eliminating the need for balloon deployment and reducing fluoroscopy exposure during infrarenal procedures.
Market Restraints
- Nitinol supply concentration:Specialized alloy production clusters in the United States and Germany create input vulnerability for stent graft manufacturers without backward integration into raw material sourcing.
- PMDA evidentiary requirements:Japan's Pharmaceuticals and Medical Devices Agency demands distinct clinical trial designs that extend commercialization timelines twelve to eighteen months beyond FDA premarket approval.
- Open surgical substitution:Younger patients with favorable anatomy and low surgical risk profiles continue to receive conventional aortic repair, limiting endovascular penetration in specific demographic segments.
Strategic Opportunities
- India's cardiovascular infrastructure:Greenfield endovascular suite installations in Delhi, Mumbai, and Hyderabad present first-mover advantages for manufacturers establishing localized clinical training programs.
- EU Green Deal carbon accounting:Sustainable manufacturing documentation requirements are creating differentiation opportunities for graft producers with verified supply chain emissions data from alloy sourcing through ethylene oxide sterilization.
- Physician-to-physician training platforms:Digital proctoring networks are compressing learning curves for fenestrated procedures, expanding addressable case volume beyond established academic medical centers.
Industry Challenges
- Center-of-excellence credentialing:Complex branched and fenestrated graft deployment requires institutional volume thresholds and multidisciplinary team certification that limit site activation speed.
- Sterilization reconfiguration:Transition from ethylene oxide to alternatives for nitinol-based devices demands validation cycles that disrupt manufacturing throughput without regulatory clarity on acceptable residuals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Endovascular Aneurysm Repair Market |
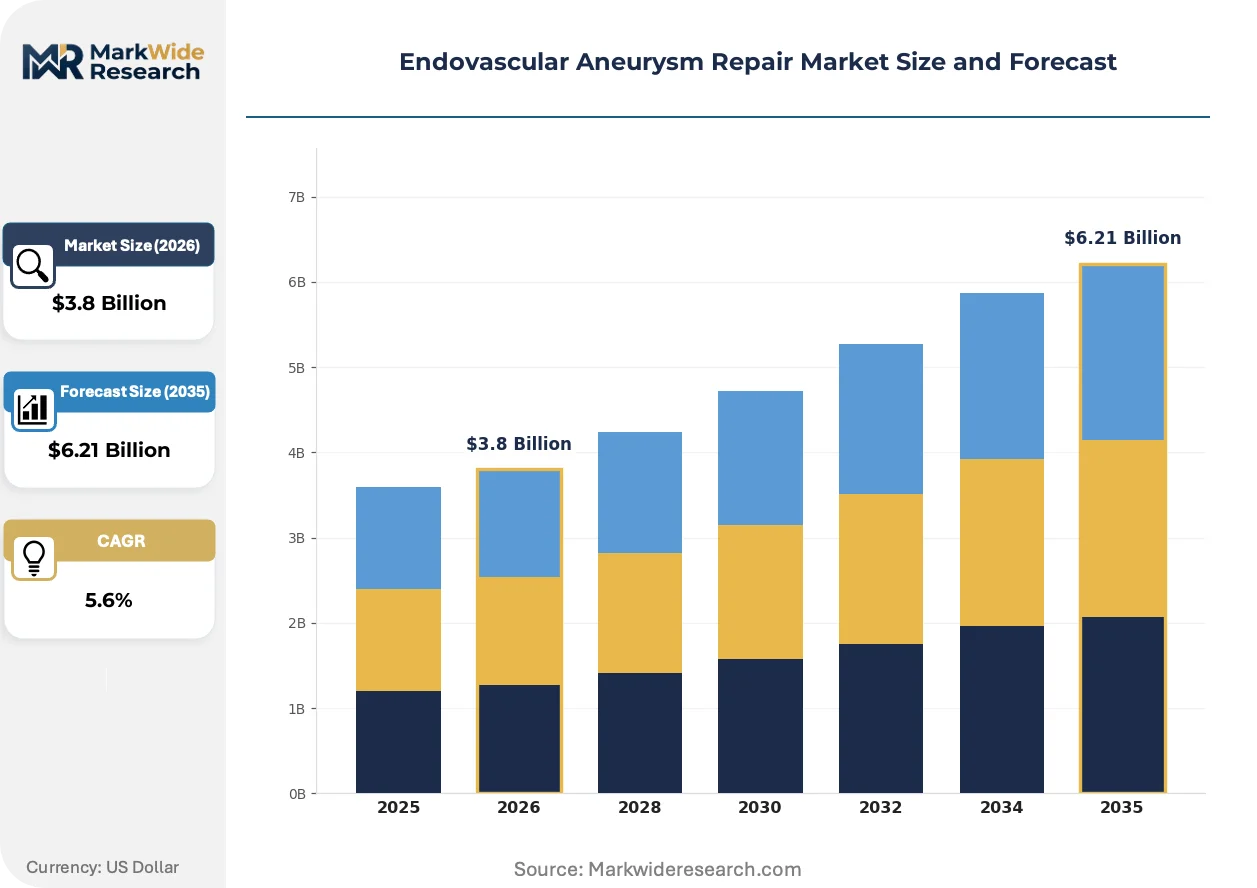
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Grafts, Balloon Catheters, Guidewires, Closure Devices Procedure Type: Elective Repair, Emergency Repair, Fenestrated Repair, Branched Repair End User: Vascular Surgery Centers, Interventional Radiology Units, Specialty Clinics, Ambulatory Surgery Centers Device Technology: Nitinol, Cobalt Chrome, Stainless Steel, Polymer Coated |
| Companies Covered | Medtronic, Cook Medical, W. L. Gore & Associates, Endologix, Terumo Corporation, Cardinal Health, Lombard Medical, Getinge Group, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Endovascular Aneurysm Repair Market Strategic Shifts & Innovations
Computational modeling and patient-specific graft design are converging to collapse the historical trade-off between anatomical customization and manufacturing lead times, compressing the interval from imaging to implantation.
Polymer-captured nitinol stent technology is unifying the previously separate functions of structural support and graft fixation within single-component designs. Academic medical centers in Germany and Japan are adopting these integrated platforms for juxtarenal anatomies that previously required custom-manufactured solutions. This unification is compressing inventory requirements for hospitals while expanding the treatable aneurysm morphology range beyond standard infrarenal indications.
EU MDR Article 10 post-market surveillance obligations are mandating systematic follow-up of implanted devices through fifteen-year registries. Manufacturers must now fund prospective data collection infrastructure that was previously optional, elevating operating costs disproportionately for smaller notified body clients. Fenestrated graft categories face the most intensive scrutiny given their procedural complexity and center-specific outcome variation.
Hospital procurement committees are consolidating vendor relationships around full-service contracts that bundle device supply with clinical training, proctoring access, and registry participation. This consolidation is displacing transactional purchasing models in United States health systems and Western European hospital networks. Germany's university hospitals and integrated delivery networks in Texas represent the most advanced manifestations of this bundled contracting evolution.
Endovascular Aneurysm Repair Market Segmentation
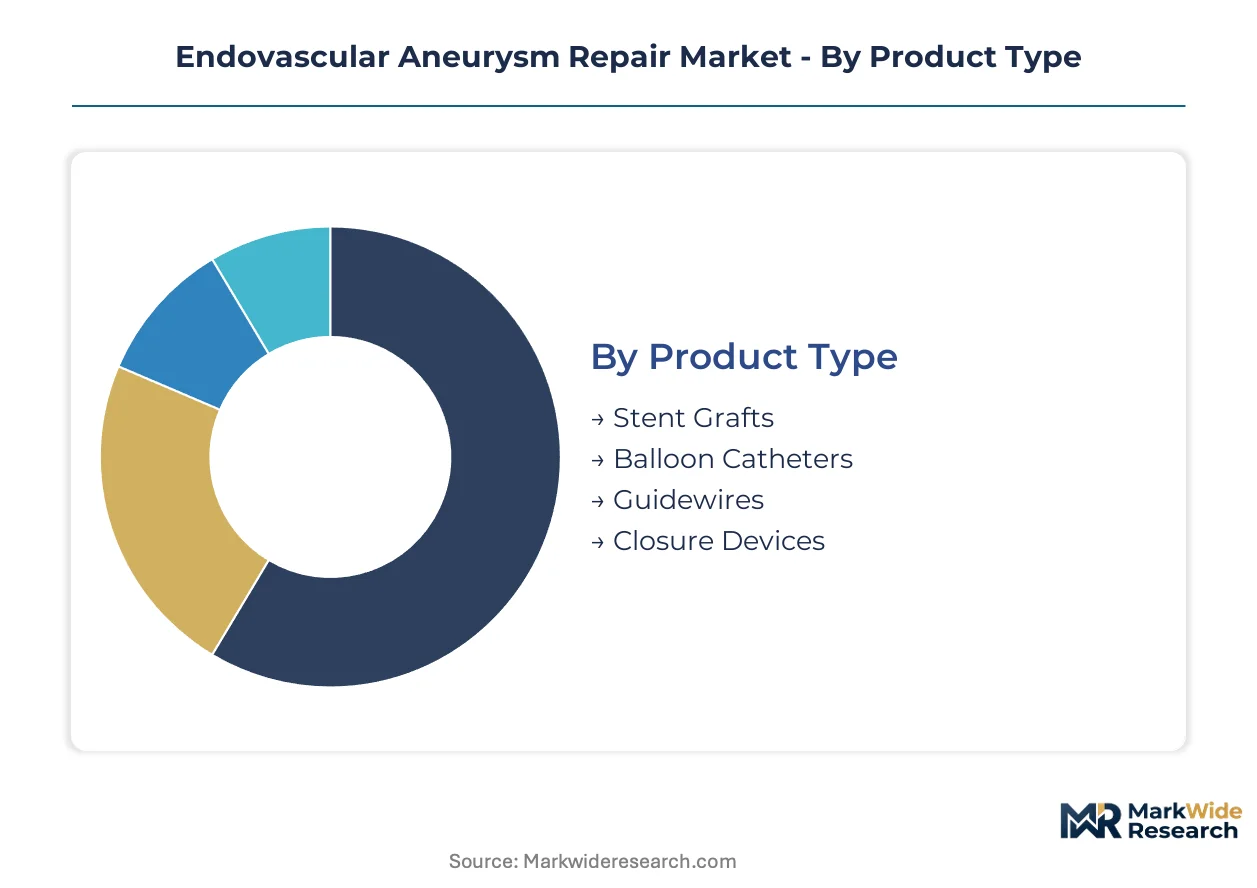
Endovascular aneurysm repair segmentation reflects divergent clinical workflows, reimbursement pathways, and supply chain configurations across product, procedure, site, and material dimensions. Manufacturers must align portfolio depth with institutional purchasing patterns and regulatory evidence requirements specific to each category.
Product Type:
Hospital procurement committees differentiate suppliers by total cost of ownership across the procedural bundle rather than unit pricing alone.
- Stent Grafts:These self-expanding nitinol-framed devices with woven polyester or ePTFE fabric exclude aneurysmal segments from arterial pressure. Demand concentrates in United States academic medical centers and German university hospitals where complex fenestrated inventory requirements strain working capital. Stent grafts absorb the majority of procedural value due to engineering complexity, sterilization validation burdens, and mandatory long-term durability registries under EU MDR Article 10.
- Balloon Catheters:Compliant and non-compliant inflation systems deploy or remodel stent grafts at target locations. Japanese cardiovascular centers in Tokyo and Osaka drive specification requirements for profile and trackability given tortuous iliac access challenges in elderly patient populations. PMDA conformity assessment timelines shape vendor selection criteria beyond Western regulatory approvals.
- Guidewires:Hydrophilic-coated and stiff exchange platforms enable catheter navigation through calcified access vessels.
- Closure Devices:Suture-mediated and plug-based systems achieve femoral artery hemostasis without surgical cutdown.
Volume sits with Stent Grafts; growth tilts toward Closure Devices as ambulatory shift accelerates.
Procedure Type:
Reimbursement intensity and evidence requirements stratify sharply between scheduled interventions and emergent presentations.
- Elective Repair:Scheduled infrarenal procedures in hemodynamically stable patients with adequate iliac access anatomy. United States Medicare severity-adjusted diagnosis-related groups and German DRG coding frameworks incentivize same-day discharge protocols that compress length-of-stay metrics. Elective volumes dominate procedural counts but face substitution pressure from surveillance programs that delay intervention until diameter thresholds are crossed.
- Emergency Repair:Ruptured aneurysm presentations requiring immediate endovascular conversion without custom-manufactured graft availability. Tertiary centers in Dallas and Houston maintain 24-hour operating team coverage and inventory depth to accommodate uncompensated transfers. Mortality differentials versus open repair sustain institutional investment despite lower reimbursement capture.
- Fenestrated Repair:Custom-manufactured grafts with scallops or fenestrations preserving renal and visceral perfusion in juxtarenal anatomies.
- Branched Repair:Thoracoabdominal applications with integrated side branches for celiac, superior mesenteric, and renal arteries.
Elective Repair generates institutional margin; Fenestrated Repair expands most quickly as manufacturing lead times compress.
End User:
Capital equipment requirements and case volume thresholds determine site-level device contracting structures.
- Vascular Surgery Centers:Hospital-integrated or independent facilities with dedicated endovascular suites and fixed imaging infrastructure. Texas Medical Center complexes in Houston and Dallas-Fort Worth anchor United States procedural volume through consolidated purchasing leverage and proctoring network access. These centers command preferential pricing through committed volume agreements and registry participation mandates.
- Interventional Radiology Units:Hybrid angiography suites staffed by radiologists with vascular surgery collaboration agreements. Japanese national health insurance reimbursement frameworks recognize interventional radiology as a distinct specialty with specific technical fee schedules that influence staffing models in Nagoya and Fukuoka.
- Specialty Clinics:Office-based or satellite facilities with limited procedure volume and referral relationships to tertiary centers.
- Ambulatory Surgery Centers:Standalone facilities pursuing same-day discharge protocols for uncomplicated infrarenal cases.
Procurement authority concentrates in Vascular Surgery Centers; site activation is climbing the fastest among Ambulatory Surgery Centers.
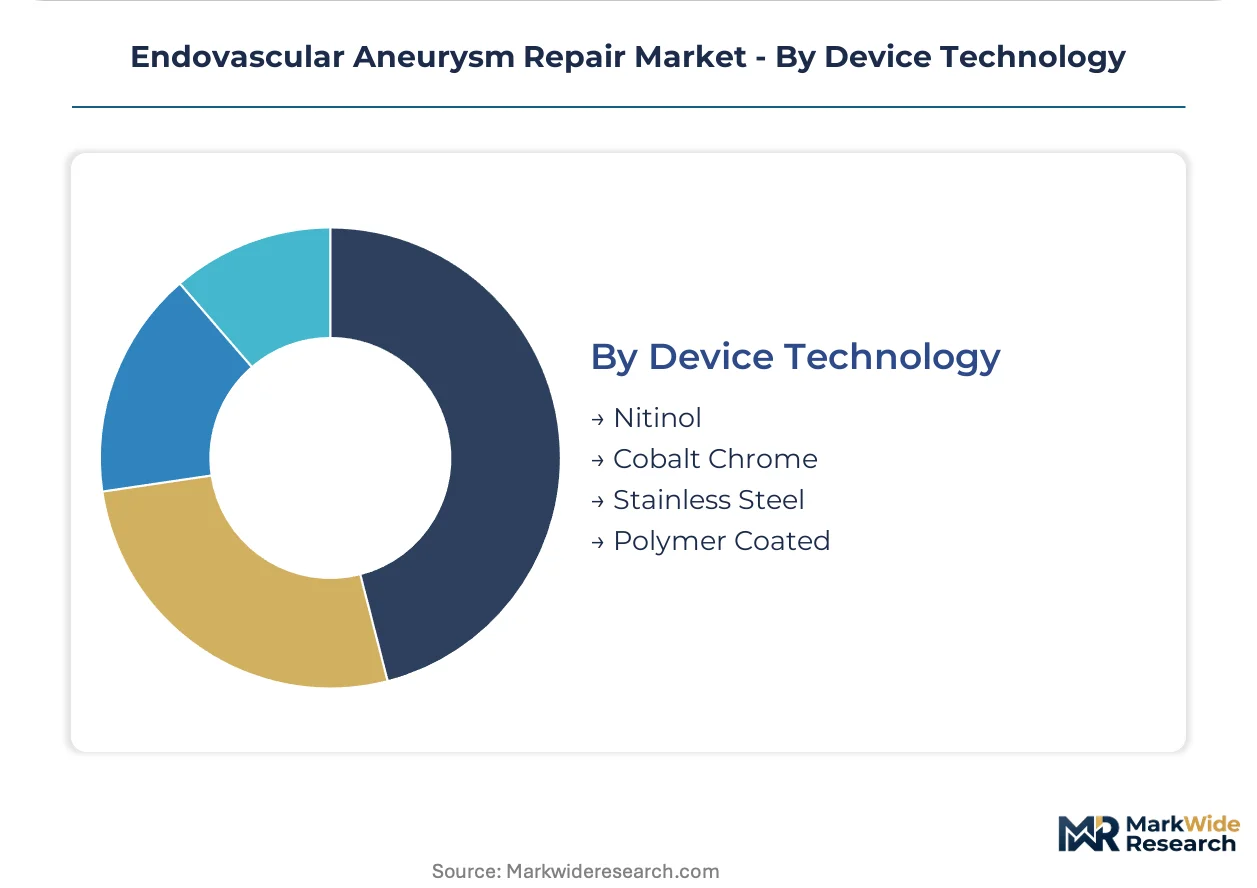
Device Technology:
Material science capabilities and supply chain positioning differentiate manufacturing economics across alloy and coating categories.
- Nitinol:Nickel-titanium superelastic alloy enabling self-expansion at body temperature without balloon deployment. Controlled thermal processing at United States and German production facilities determines transformation temperature ranges that govern conformability to tortuous anatomy. Nitinol sourcing concentration creates input vulnerability for manufacturers without backward integration into alloy melting and wire drawing.
- Cobalt Chrome:High-radial-force balloon-expandable stent platforms for proximal fixation zones in hostile neck anatomies. German metallurgical suppliers in the Ruhr region and United States specialty alloy producers serve distinct regulatory filing pathways that segment the supplier base.
- Stainless Steel:Lower-cost structural elements in delivery system components and accessory devices.
- Polymer Coated:Drug-eluting or passive barrier coatings addressing thrombogenicity and tissue integration.
Installed base tilts toward Nitinol; Cobalt Chrome applications are gaining share fastest in proximal fixation segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors procedural volume through Texas Medical Center complexes that consolidate purchasing leverage across multiple hospital systems. Dallas-Fort Worth, Austin, and San Antonio expand endovascular suite capacity to capture migration of elective cases from rural catchment areas.
United States
Medicare severity-adjusted diagnosis-related groups incentivize same-day discharge protocols that compress length-of-stay metrics for elective infrarenal procedures. FDA premarket approval pathways demand long-term durability data from prospective registries before commercialization. Texas Medical Center facilities in Houston maintain 24-hour operating team coverage for ruptured aneurysm presentations.
Germany
University hospitals in Munich, Heidelberg, and Berlin drive specification requirements for fenestrated graft inventory depth given complex juxtarenal anatomies. EU MDR notified body conformity assessments mandate fifteen-year post-market surveillance registries under Article 10 obligations. The Ruhr region hosts specialized cobalt chrome metallurgical suppliers that serve distinct regulatory filing pathways.
Japan
Tertiary cardiovascular centers in Tokyo, Osaka, and Nagoya expand procedural volumes under Ministry of Health, Labour and Welfare reimbursement frameworks for minimally invasive aortic interventions. PMDA evidentiary requirements demand distinct clinical trial designs that extend commercialization timelines twelve to eighteen months beyond FDA approvals. Japanese national health insurance recognizes interventional radiology as a distinct specialty with specific technical fee schedules.
India
Greenfield endovascular suite installations in Delhi, Mumbai, and Hyderabad present first-mover advantages for manufacturers establishing localized clinical training programs. CDSCO medical device registration requirements are tightening quality system expectations for imported stent graft systems. Apollo and Max Healthcare hospital networks in Delhi-NCR anchor cardiovascular infrastructure investment.
United Kingdom
NHS England specialized commissioning frameworks concentrate complex fenestrated and branched procedures into designated vascular networks with volume thresholds. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards while streamlining UKCA marking timelines. London teaching hospitals and Manchester vascular centers drive adoption of physician-to-physician digital proctoring platforms.
Endovascular Aneurysm Repair Market Key Industry Players
The competitive structure tilts toward integrated manufacturers with captive nitinol supply chains and dedicated clinical affairs infrastructure. Three archetypes dominate: diversified medical technology conglomerates with full vascular portfolios; specialized endovascular pure-plays with focused graft engineering capabilities; and diversified industrials with cardiovascular divisions serving regional markets. M&A activity concentrates on fenestrated graft technology acquisitions and digital proctoring platform roll-ups.
Among diversified conglomerates, Medtronic leverages integrated manufacturing from alloy sourcing through final sterilization, while W. L. Gore & Associates sustains position through proprietary membrane technology differentiation. Terumo Corporation anchors Asia-Pacific competitiveness through region-specific regulatory navigation. Cook Medical and Boston Scientific Corporation occupy positions across the stent graft and delivery system spectrum. These named entities exemplify the archetype spectrum without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| Medtronic |
| Cook Medical |
| W. L. Gore & Associates |
| Endologix |
| Terumo Corporation |
| Cardinal Health |
| Lombard Medical |
| Getinge Group |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Hospital procurement committees in Texas Medical Center complexes and German university hospitals are consolidating vendor relationships around full-service contracts that bundle device supply with clinical training and registry participation, forcing manufacturers to absorb upfront cost burdens and compressing margins for suppliers without integrated clinical affairs infrastructure.
Pricing Analysis
Value-based pricing anchored to procedural throughput and center-of-excellence certification dominates contracting structures. Pricing stratifies across premium fenestrated graft tiers with custom manufacturing lead times, standard infrarenal inventory, and economy accessory bundles for high-volume elective cases. Cost compression in standard infrarenal segments is intensifying because ambulatory surgery centers are gaining procurement authority and demanding same-day discharge protocols. Academic medical centers demonstrate the lowest price sensitivity due to complex inventory requirements and proctoring access dependencies.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EU MDR notified bodies mandate multi-supplier qualification for nitinol alloy and ePTFE membrane inputs, extending validation timelines. Nitinol production concentrates in United States and German metallurgical facilities, while polymer textile weaving clusters in Japan and Ireland supply graft sealing zones. Supply chain risk centers on single-source vulnerability for specialized thermal processing equipment that determines nitinol transformation temperatures. Distribution runs through hospital procurement committees and group purchasing organizations rather than direct manufacturer-to-site transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated manufacturers with captive alloy supply chains and dedicated registry infrastructure, as EU MDR Article 10 surveillance obligations and PMDA evidentiary requirements force smaller notified body clients toward exit.
For Market Incumbents: Cement market position through backward integration into nitinol melting and wire drawing capabilities, eliminating input vulnerability from United States and German alloy clusters. Expand physician-to-physician digital proctoring networks to accelerate center-of-excellence certification and displace competitors lacking clinical training infrastructure. Prioritize EU MDR notified body relationships with streamlined Article 10 registry pathways to compress commercialization timelines for fenestrated graft categories. For New Entrants and Emerging Players: Digital proctoring platforms offer the most penetrable route for specialized entrants lacking legacy graft manufacturing scale. Target India's greenfield endovascular suite installations in Delhi and Hyderabad with localized clinical training programs that established players have not yet saturated. Pursue reimbursement strategy consulting as a service wedge, bundling CDSCO registration support with hospital procurement navigation for Apollo and Max Healthcare networks. For Investors and Strategic Acquirers: The window for entry favors fenestrated graft technology specialists with proprietary patient-specific design platforms and established EU MDR technical documentation. Long-term viability hinges on fifteen-year durability data infrastructure that only prospective registry funding can sustain. Watch PMDA approval timeline compression as the signal for Asia-Pacific competitive inflection, as Japan's Ministry of Health, Labour and Welfare expands minimally invasive reimbursement frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Long-term durability registries satisfy FDA evidentiary thresholds before commercialization authorization. |
| EU MDR Notified Body Conformity Assessment | Article 10 post-market surveillance obligations mandate fifteen-year follow-up infrastructure funding. |
| Hospital System Partnership | Texas Medical Center complexes consolidate purchasing leverage across multiple integrated delivery networks. |
| Software Companion Development | Computational modeling platforms collapse manufacturing lead times for patient-specific fenestrated grafts. |
| Reimbursement Strategy | Medicare severity-adjusted DRG frameworks incentivize same-day discharge protocols for elective procedures. |
Research Approach
Document review covered FDA premarket approval filings, EU MDR technical documentation, and PMDA clinical trial registry entries, complemented by interviews with vascular surgeons, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Secondary validation drew from CMS Medicare claims data, German DRG coding frameworks, and Japanese national health insurance technical fee schedules. Bottom-up procedural volume estimates and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Cross-referencing historical implant registry data against panel input from clinical affairs executives and regulatory consultants informed the projection framework. Segmentation modeling spanned product type, procedure complexity, end-user facility tier, and device material technology. CAGRs were derived from fitted growth curves applied to elective versus emergent case mix shifts and fenestrated graft adoption trajectories. Nitinol supply constraints and sterilization reconfiguration timelines fed into capacity-adjusted supply side assumptions.
Inputs from FDA 510(k) and PMA databases were available through the study window; gaps in real-time EU MDR notified body approval velocity introduce uncertainty bands around commercialization timeline assumptions. Deviation in PMDA evidentiary requirement harmonization with FDA standards would shift the Asia-Pacific outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Vital Signs Monitoring Devices Market
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Cardiac Rhythm Management Devices Market
Cardiovascular Devices
Cardiovascular Stents Market
Cardiovascular Devices
Global Atrial Fibrillation Surgery Market
Cardiovascular Devices
Perfusion Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Global Non-Vascular Stents Market
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Cardiovascular Repair and Reconstruction Devices Market
Cardiovascular Devices
Arteriovenous (Av) Fistula Needle Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market