
 Global Cardiac Arrest Treatment Market | 2026-2036
Global Cardiac Arrest Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Arrest Treatment Market Foresight
Emergency medical services are redrawing procurement priorities toward portable, connected resuscitation platforms. ZOLL Medical Corporation leverages its proprietary Real CPR Help technology to anchor North American EMS contracts. Medtronic, Inc. sustains global manufacturing scale across implantable and external defibrillator lines. Koninklijke Philips N.V. differentiates through integrated response systems that span hospital and pre-hospital environments.
Cardiac arrest treatment encompasses the immediate clinical interventions, devices, and pharmacologic agents deployed to restore spontaneous circulation following sudden cessation of cardiac activity, typically requiring electrical defibrillation within three to five minutes to preserve neurologic function. The primary purpose spans emergency resuscitation in out-of-hospital settings through advanced critical care in tertiary facilities. Implantable cardioverter defibrillators occupy the deepest margin pools due to long-term implant service revenues and replacement cycles. Automated external defibrillators represent the fastest-expanding product category as municipalities and corporate wellness programs deploy public access units. CPR devices are gaining traction in hospital-based deployment models where mechanical compression ensures guideline-consistent perfusion during prolonged resuscitation.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation shape device design, post-market surveillance obligations, and market access timelines on both sides of the Atlantic. Japan's PMDA enforces rigorous clinical evidence standards for implantable devices that filter which manufacturers can compete in that jurisdiction. Stakeholders must monitor how reimbursement shifts toward value-based resuscitation outcomes will reshape capital allocation across product development and geographic expansion.
Market Dynamics
Public access defibrillation mandates are compressing deployment timelines and forcing manufacturers to redesign automated external defibrillators for untrained bystander use, fundamentally altering how resuscitation technology reaches end-users.
Growth Catalysts
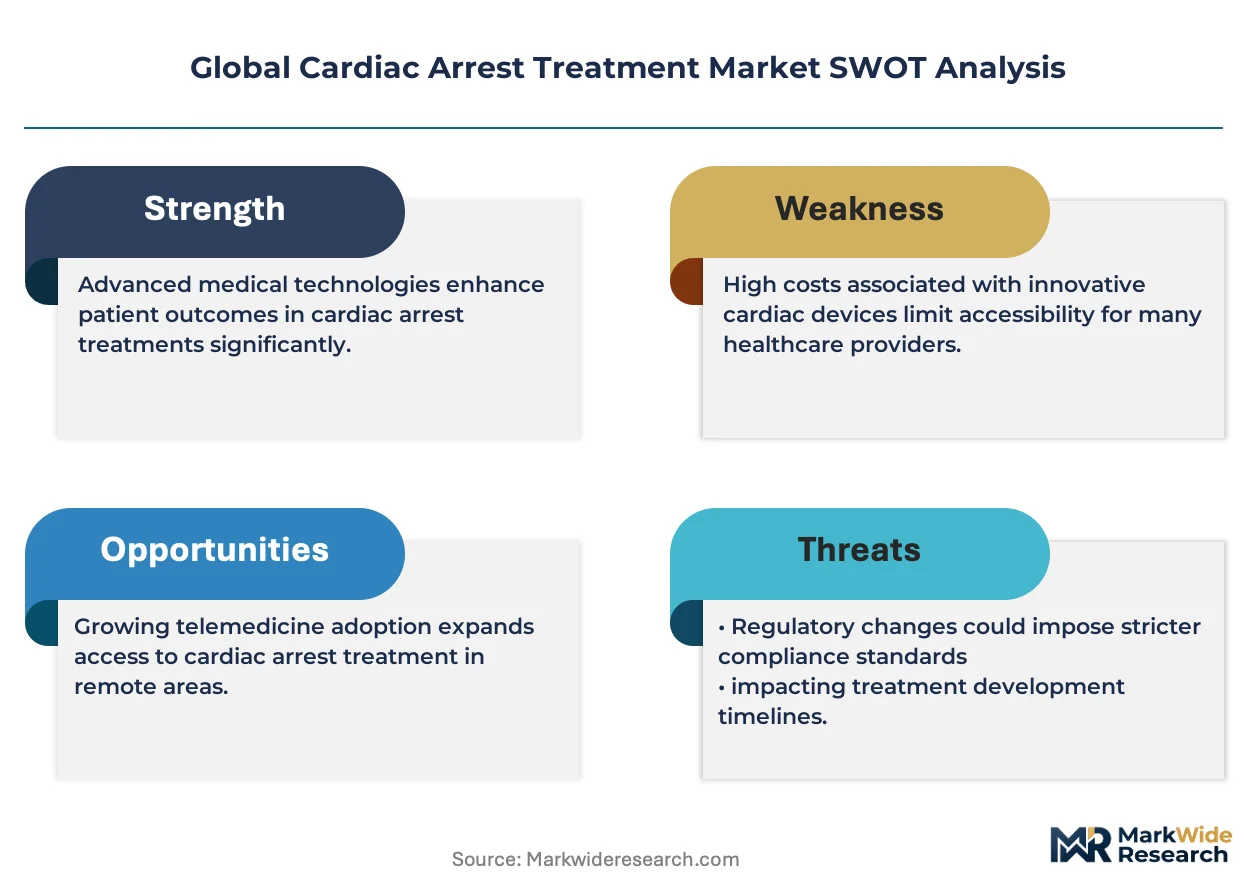
- EU Medical Device Regulation:The MDR's enhanced post-market surveillance requirements are filtering out marginal manufacturers and consolidating procurement toward certified suppliers with robust quality management systems.
- Mechanical CPR platforms:Hospital emergency departments are standardizing on automated compression devices to maintain guideline-consistent perfusion during prolonged resuscitation attempts.
- Japan:METI-funded public access defibrillation programs in Tokyo, Osaka, and Fukuoka are creating concentrated demand for bilingual-interface devices with integrated emergency response connectivity.
Market Restraints
- Implantable device supply concentration:Critical battery and capacitor inputs for implantable cardioverter defibrillators source from a narrow supplier base in South Korea and Taiwan, exposing lead times to geopolitical friction.
- FDA 510(k) pathway tightening:The FDA's enhanced scrutiny of automated external defibrillator predicate devices is extending clearance timelines and elevating clinical evidence requirements.
- Substitute intervention models:Advances in predictive cardiac monitoring and remote patient management are reducing the incident pool for acute cardiac arrest events in monitored populations.
Strategic Opportunities
- India:CDSCO's streamlined medical device registration pathway and expanding hospital infrastructure in Maharashtra and Karnataka create entry points for external defibrillator manufacturers.
- Drone-enabled AED delivery:Integration of automated external defibrillators with emergency medical drone networks is compressing response times in rural and suburban geographies.
- AI-augmented rhythm analysis:Machine learning-enhanced shock advisory algorithms are reducing false-positive rates and expanding deployment confidence in high-traffic public venues.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in resuscitation device firmware and signal processing is concentrating in Boston, Tel Aviv, and Eindhoven, creating recruitment bottlenecks for expansion programs.
- Legacy fleet interoperability:Hospital systems face integration complexity when connecting new resuscitation platforms to existing electronic health record architectures and code blue notification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Arrest Treatment Market |
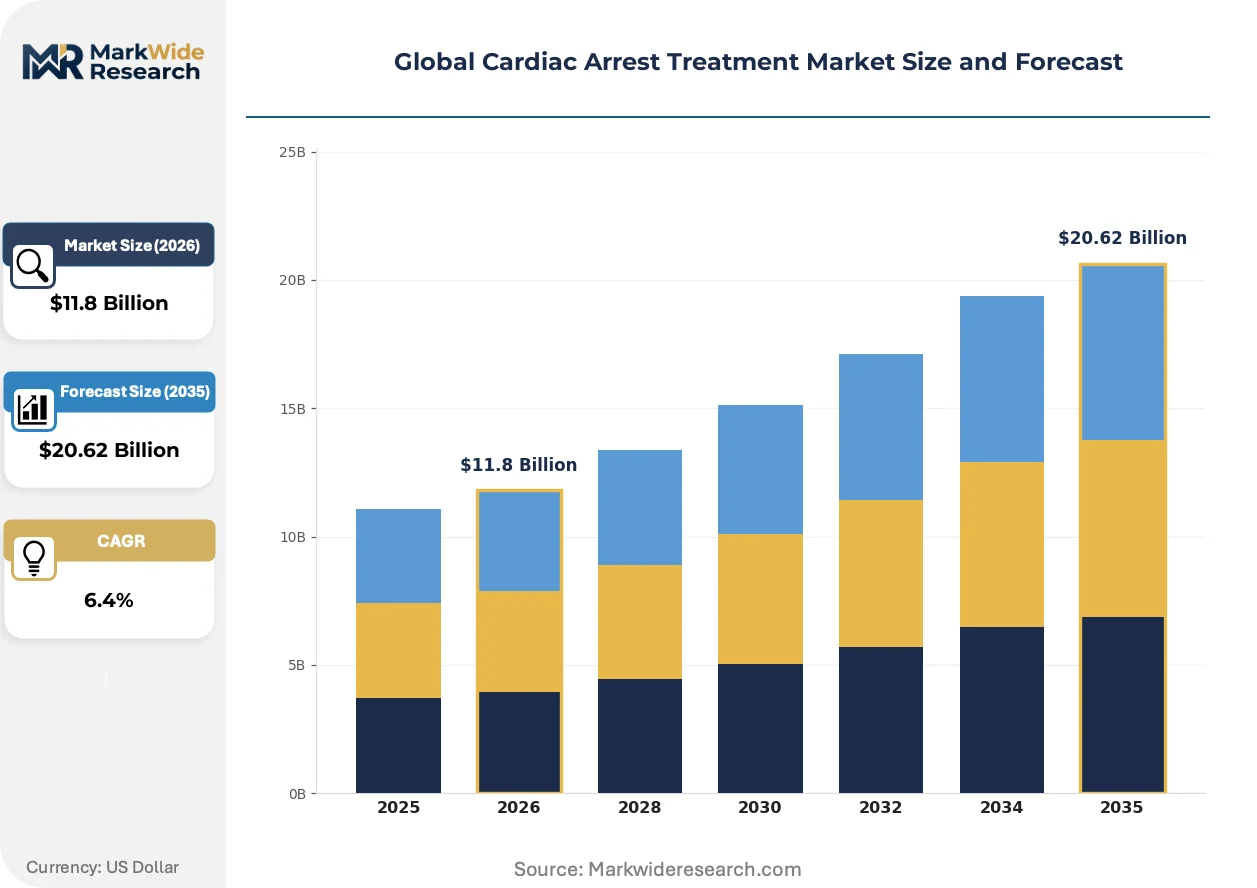
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated External Defibrillators, Implantable Cardioverter Defibrillators, Manual Defibrillators, CPR Devices, Cardiac Monitors Therapy Area: Ventricular Fibrillation, Pulseless Ventricular Tachycardia, Asystole, Pulseless Electrical Activity, Bradycardia End User: Emergency Medical Services, Ambulatory Surgical Centers, Cardiology Clinics, Trauma Centers, Rehabilitation Facilities Deployment Model: Hospital-Based, Community Health Programs, Homecare Settings, Corporate Wellness Centers, Mobile Units |
| Companies Covered | ZOLL Medical Corporation, GE HealthCare Technologies Inc., Abbott Laboratories, Edwards Lifesciences Corporation, Stryker Corporation, Medtronic, Inc., Koninklijke Philips N.V., Biotronik SE & Co. KG, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Arrest Treatment Market Shifts & Advancements
Real-time data telemetry is threading through every layer of cardiac arrest response, from bystander-initiated defibrillation through hospital-based mechanical resuscitation, compressing information latency and reshaping clinical workflow design.
Mechanical CPR devices with integrated impedance threshold valves and active compression-decompression mechanisms are displacing manual chest compression protocols in hospital emergency departments and advanced life support ambulance fleets. Critical care teams in Germany, the Netherlands, and Australia are adopting these platforms for witnessed arrests with prolonged resuscitation timelines. The shift is compressing training costs while standardizing perfusion quality across rotating clinical staff.
The FDA's 2023 guidance on automated external defibrillator cybersecurity and software validation is mandating encrypted firmware update channels and documented threat modeling for 510(k) submissions. Device manufacturers are re-engineering connectivity architectures to satisfy these requirements ahead of enforcement deadlines. Emergency medical services in the United States are prioritizing procurement of compliant units to avoid fleet obsolescence.
Subscription-based device monitoring and consumable replenishment contracts are displacing traditional capital purchase models for automated external defibrillator deployments. Corporate wellness programs and municipal health departments in France, Sweden, and Canada are adopting these arrangements to transfer obsolescence risk and ensure electrode pad currency. The shift is elevating lifetime value calculations and reshaping manufacturer revenue recognition patterns.
Global Cardiac Arrest Treatment Market Segmentation
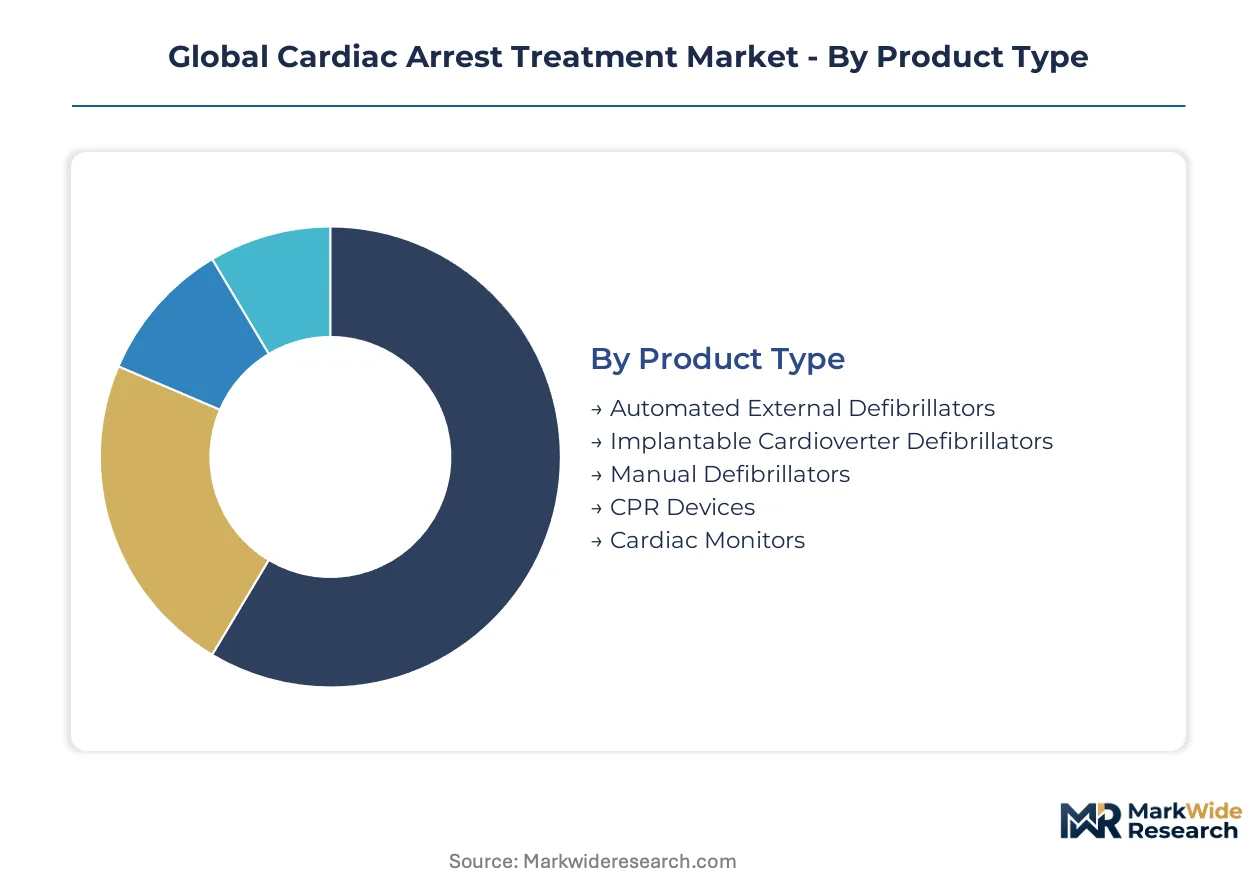
Cardiac arrest treatment markets fragment across intervention timing, clinical setting, and technological sophistication. Understanding these divisions exposes where predictive monitoring and preventive cardiology erode acute event volumes versus where immediate resuscitation remains irreplaceable.
Product Type:
Substitute pressure from remote patient monitoring and AI-enabled arrhythmia prediction weighs heaviest on segments serving monitored populations, while public access devices face minimal displacement risk.
- Automated External Defibrillators:Portable biphasic shock units designed for untrained bystander operation with integrated voice coaching and CPR feedback. Municipal procurement in the United States, Germany, and Japan concentrates demand as public access defibrillation mandates expand; subscription-based fleet management contracts are displacing capital purchase models in corporate deployments.
- Implantable Cardioverter Defibrillators:Transvenous and subcutaneous devices with long-term battery service revenues and replacement cycles generating sustained manufacturer margins. Japan's PMDA enforces rigorous clinical evidence standards that filter which suppliers compete in this high-value segment.
- Manual Defibrillators:Hospital-grade units requiring trained operator interpretation of cardiac rhythms.
- CPR Devices:Mechanical compression platforms with active compression-decompression mechanisms.
- Cardiac Monitors:Continuous rhythm surveillance systems with defibrillation backup capability.
Implantable cardioverter defibrillators retain volume leadership; automated external defibrillators hold the steepest expansion curve.
Therapy Area:
Clinical reimbursement patterns and outcome-based contracting favor segments with measurable restoration of spontaneous circulation rates over those with historically poor survival profiles.
- Ventricular Fibrillation:Disorganized electrical activity responsive to immediate defibrillation with the highest survival-to-discharge rates among arrest rhythms. Emergency medical services in the Netherlands and Australia prioritize rapid defibrillation protocols for witnessed VF events.
- Pulseless Ventricular Tachycardia:Rapid organized rhythm degenerating to VF without cardiac output, sharing defibrillation responsiveness with VF. Hospital emergency departments in Germany standardize on mechanical CPR adjuncts to maintain perfusion during prolonged VT resuscitation attempts.
- Asystole:Absence of ventricular electrical activity with minimal defibrillation utility.
- Pulseless Electrical Activity:Organized electrical rhythm without mechanical cardiac contraction.
- Bradycardia:Pathologically slow rhythm progressing to arrest.
Ventricular fibrillation commands the largest addressable patient volume; pulseless ventricular tachycardia is climbing the fastest as protocol standardization expands treatable incident identification.
End User:
Procurement sophistication and total cost of ownership calculations separate capital-constrained settings from those with integrated resuscitation quality programs.
- Emergency Medical Services:Pre-hospital providers requiring portable, connected platforms with real-time telemetry to receiving hospitals. ZOLL Medical Corporation's Real CPR Help technology anchors North American EMS contract awards through perfusion quality feedback.
- Ambulatory Surgical Centers:Outpatient facilities with intermittent resuscitation needs and limited on-site cardiac expertise.
- Cardiology Clinics:Specialized practices with diagnostic and preventive focus.
- Trauma Centers:Level I facilities managing polytrauma with concurrent hemorrhagic and cardiac arrest protocols.
- Rehabilitation Facilities:Post-acute settings with monitored exercise programs.
Emergency medical services dominate unit shipments; trauma centers are gaining share fastest as damage control resuscitation protocols integrate advanced cardiac support.
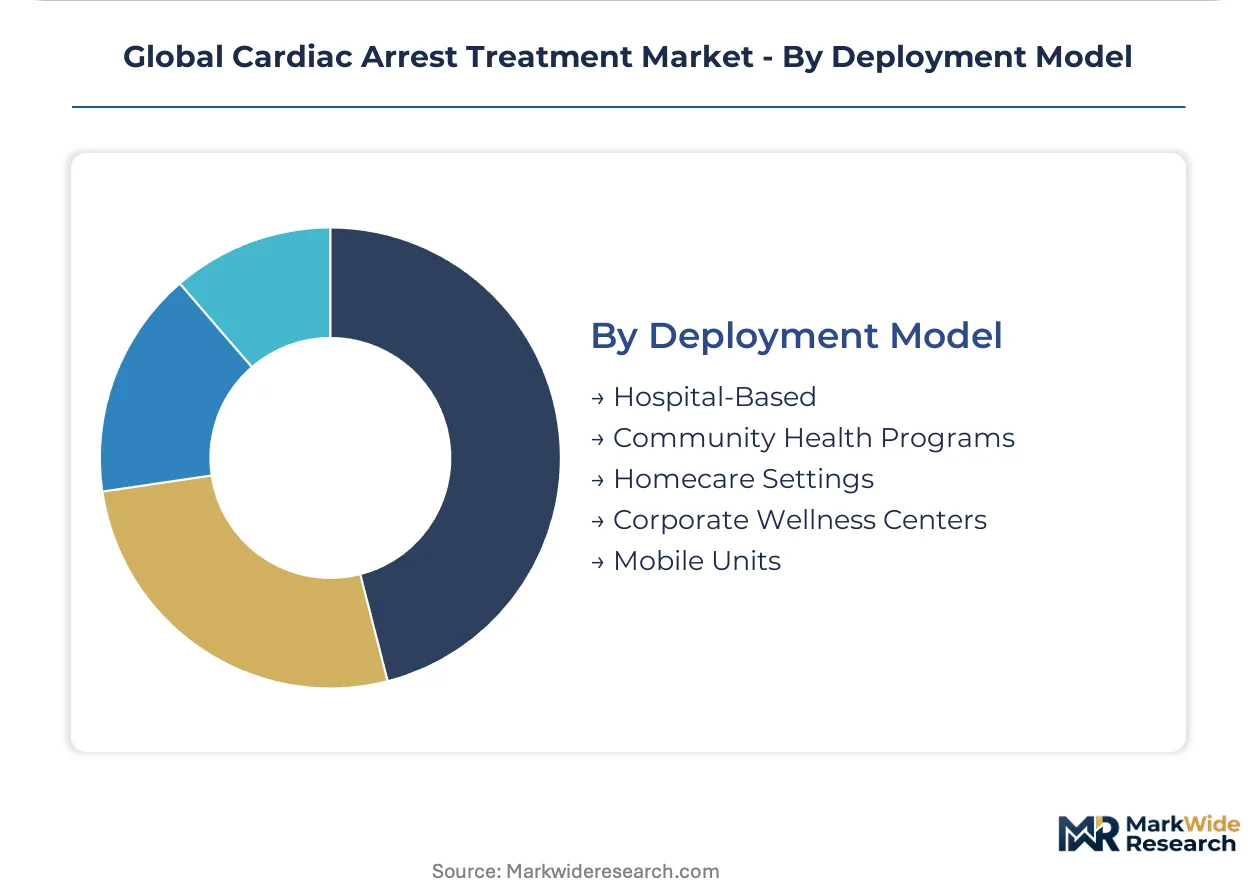
Deployment Model:
Capital allocation flexibility and risk transfer preferences determine whether settings adopt ownership, subscription, or shared-service arrangements for resuscitation infrastructure.
- Hospital-Based:Integrated code blue systems with mechanical CPR standardization and EHR connectivity. The FDA's 2023 cybersecurity guidance mandates encrypted firmware channels for new hospital fleet acquisitions.
- Community Health Programs:Public access networks with bilingual interfaces in METI-funded Japanese municipalities.
- Homecare Settings:Wearable defibrillator vests and caregiver training programs.
- Corporate Wellness Centers:Subscription-monitored AED fleets with automated electrode replenishment.
- Mobile Units:Drone-enabled AED delivery networks compressing rural response times.
Hospital-based deployment retains the largest installed base; mobile units are expanding most quickly as aviation regulators in the United States and European Union formalize beyond-visual-line-of-sight medical drone operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export advanced resuscitation systems to Japanese hospital networks, while United States-based device makers supply automated external defibrillators to municipal health departments across Western Europe. Trade corridors concentrate high-value implantable devices from Switzerland and Ireland into tertiary cardiac centers in the United States and Japan. Supply chain mapping reveals battery and capacitor inputs flowing from South Korean and Taiwanese component suppliers to final assembly facilities in Massachusetts, Minnesota, and Eindhoven.
United States
Hospital emergency departments in Texas, Florida, and California are expanding mechanical CPR platform procurement to standardize perfusion quality across rotating clinical staff. The FDA's 2023 cybersecurity guidance mandates encrypted firmware update channels for new automated external defibrillator acquisitions. Boston and Minneapolis-St. Paul anchor device development clusters where biomedical engineering talent concentrates in resuscitation firmware and signal processing.
Germany
Critical care teams in Bavaria and North Rhine-Westphalia are adopting automated compression-decompression devices for witnessed arrests with prolonged resuscitation timelines. The EU Medical Device Regulation's enhanced post-market surveillance requirements filter procurement toward certified suppliers with robust quality management systems. Eindhoven-based component engineering feeds into final assembly operations across the Dutch-German border region.
Japan
METI-funded public access defibrillation programs in Tokyo, Osaka, and Fukuoka create concentrated demand for bilingual-interface devices with integrated emergency response connectivity. The PMDA enforces rigorous clinical evidence standards for implantable cardioverter defibrillators that filter which manufacturers compete in this high-value segment. Nagoya and Yokohama host specialized cardiac device distribution hubs serving prefectural hospital networks.
India
CDSCO's streamlined medical device registration pathway and expanding hospital infrastructure in Maharashtra and Karnataka create entry points for external defibrillator manufacturers. Corporate hospital chains in Mumbai and Bangalore are piloting subscription-based fleet management contracts for automated external defibrillator deployments. Tamil Nadu's medical electronics manufacturing zone attracts component assembly investments from regional device suppliers.
Australia
Emergency medical services in New South Wales and Victoria are standardizing procurement of portable, connected resuscitation platforms with real-time telemetry to receiving hospitals. The TGA's alignment with FDA cybersecurity guidance accelerates compliance timelines for connected device submissions. Melbourne and Sydney anchor clinical trial networks evaluating drone-enabled automated external defibrillator delivery in rural and suburban geographies.
Global Cardiac Arrest Treatment Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and R&D horizon, with publicly traded device manufacturers sustaining global manufacturing scale while private firms concentrate in niche resuscitation technologies. The vendor base organizes into three strategic archetypes: diversified medical technology conglomerates with defibrillator divisions, pure-play resuscitation device specialists, and emerging connected-health platforms. Dominant competitive moves include strategic partnerships for emergency response system integration and portfolio diversification into predictive cardiac monitoring adjacent to acute resuscitation.
Within the diversified medical technology tier, Medtronic, Inc. and Koninklijke Philips N.V. occupy positions spanning implantable and external defibrillator lines across hospital and pre-hospital environments. ZOLL Medical Corporation exemplifies the resuscitation specialist archetype, anchoring North American emergency medical services contracts through proprietary real-time feedback technology. These three entities represent distinct competitive vectors: manufacturing scale, integrated response system breadth, and EMS-specific technology depth.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| GE HealthCare Technologies Inc. |
| Abbott Laboratories |
| Edwards Lifesciences Corporation |
| Stryker Corporation |
| Medtronic, Inc. |
| Koninklijke Philips N.V. |
| Biotronik SE & Co. KG |
| Boston Scientific Corporation |
| Others |
Supply & Pricing Matrix
Component-scale economies in battery and capacitor manufacturing concentrate margin leverage among suppliers serving implantable cardioverter defibrillator assembly lines, compressing price floors for finished devices while elevating procurement power for manufacturers with captive component volumes or long-term offtake arrangements.
Pricing Analysis
Next-generation automated external defibrillators with integrated AI rhythm analysis and encrypted telemetry command substantial premiums over prior-generation voice-coaching units, while economy-tier manual hospital defibrillators face sustained price erosion. Three-tier pricing structure across premium connected platforms, standard public access units, and economy manual devices reflects FDA cybersecurity certification tiers and after-sales service bundling. Pricing pressure stems from municipal procurement consolidation in the United States and Germany, where GPO-negotiated contracts compress margins for non-differentiated suppliers. Emergency medical services demonstrate highest price sensitivity due to fleet-scale purchasing, while Japanese tertiary cardiac centers exhibit lowest sensitivity given PMDA-filtered supplier pools and outcome-based reimbursement.
Supply Chain Analysis
South Korea and Taiwan anchor critical battery and capacitor production for implantable device manufacturers, with final assembly concentrating in Massachusetts, Minnesota, and Eindhoven. Critical inputs draw from concentrated semiconductor foundries and specialized medical-grade battery cell producers, exposing lead times to geopolitical friction and single-source vulnerability for high-reliability capacitors. Distribution runs through specialized cardiac device distributors serving hospital networks, with direct-to-health-system contracting displacing traditional medical supply intermediaries for high-value implantable lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as emergency response systems demand seamless interoperability between pre-hospital defibrillation, hospital mechanical resuscitation, and electronic health record integration, rewarding manufacturers with full-stack connectivity architectures.
For Market Incumbents: Consolidate firmware development capabilities in Boston and Eindhoven talent clusters to defend against AI-augmented rhythm analysis entrants, while securing long-term battery supply agreements with South Korean suppliers to mitigate single-source concentration risk in implantable device lines. For New Entrants and Emerging Players: CDSCO's streamlined registration pathway for Maharashtra and Karnataka hospital networks offers fastest market entry for external defibrillator specialists, with subscription-based fleet management contracts providing recurring revenue traction against capital-purchase incumbents in India's expanding corporate hospital sector. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected-health platforms with real-time telemetry integration over pure-play hardware manufacturers, with long-term viability hinging on FDA cybersecurity compliance and EHR interoperability certification; watch for enforcement of the FDA's 2023 guidance as inflection indicator separating compliant from obsolete fleet suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Cybersecurity Compliance Pathway | Encrypted firmware mandates reshape procurement criteria for hospital fleet acquisitions across Texas, Florida, and California systems. |
| Drone-Enabled AED Network Integration | Beyond-visual-line-of-sight aviation waivers in the United States and European Union compress rural response times for municipal health departments. |
| AI-Augmented Rhythm Analysis Development | Machine learning shock advisory algorithms reduce false-positive rates and expand deployment confidence in high-traffic Japanese transit venues. |
| Subscription Fleet Management Contracts | Automated electrode replenishment and remote monitoring transfer obsolescence risk from French and Swedish corporate wellness programs to manufacturers. |
| EU MDR Quality System Certification | Enhanced post-market surveillance requirements filter procurement toward certified suppliers in German critical care networks. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with emergency medical services procurement directors, hospital biomedical engineering leads, GPO contracts managers, and cardiac device regulatory affairs specialists; and secondary validation against FDA 510(k) filings, EU MDR notified body certifications, PMDA approval databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up demand modeling triangulated against top-down market sizing across manufacturer revenue disclosures.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, therapy area, end user archetype, and deployment model, with CAGRs derived from trend extrapolation of historical procurement patterns and regulatory enforcement timelines. Forecast inputs incorporated METI-funded public access program expansion in Japanese municipalities, CDSCO registration pathway efficiency in Indian states, and FAA aviation waiver progression for medical drone networks.
Decision-makers should treat outputs as directional under assumptions of sustained FDA cybersecurity enforcement and stable EU-UK regulatory equivalence; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in reimbursement policy toward value-based resuscitation outcomes and geopolitical disruption of South Korean component supply channels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Vascular Stents Market
Cardiovascular Devices
Australia Cardiovascular Devices Market
Cardiovascular Devices
Global Catheters Market
Cardiovascular Devices
Thoracic Vascular Stent Grafts Market
Cardiovascular Devices
Global Intravascular Catheters Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Asia Pacific Interventional Cardiology Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Global Coil Wound Devices Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
China Cardiovascular Devices Market
Cardiovascular Devices
Global Percutaneous Coronary Intervention (PCI) Devices Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market