
 Global Non-Vascular Stents Market | 2026-2036
Global Non-Vascular Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Vascular Stents Market Foresight
Hospital procurement networks is reconfiguring as ambulatory surgical centers expand interventional capabilities and direct sourcing relationships. Boston Scientific Corporation leverages its endoscopy channel density to sustain placement volumes across biliary and esophageal portfolios. Medtronic anchors gastrointestinal stent supply through integrated operating room contracts that span diagnostic and therapeutic procedures. Cook Medical differentiates via specialized airway and fistula management platforms that occupy niche procedural segments with limited direct competition.
Non-vascular stents are tubular prosthetic devices, typically fabricated from nitinol, stainless steel, silicone, or biodegradable polymers, designed to maintain luminal patency in ducts, airways, and hollow organs without entering the bloodstream; they deploy via endoscopic or fluoroscopic guidance and must withstand peristaltic motion, enzymatic exposure, and compressive tissue forces. Biliary stents dominate procedural volume due to established oncology and benign stricture protocols, while biodegradable materials represent the fastest-expanding material category as clinicians seek to reduce retrieval procedures and long-term complication rates. Metallic platforms still command the largest margin pools in esophageal and airway applications where structural radial force requirements limit polymer substitution.
FDA 510(k) clearance pathways govern United States market access, while CE marking under the EU Medical Device Regulation shapes European commercialization timelines and clinical evidence requirements; Japan's PMDA imposes additional biocompatibility and durability standards that filter out lower-tier manufacturers. Stakeholders must monitor evolving reimbursement thresholds for outpatient stent placement as payors in Germany, Japan, and the United States recalibrate site-of-service differentials between hospitals and ambulatory centers.
Market Dynamics
Ambulatory surgical centers are capturing stent placement volume from hospitals as site-of-service economics and dedicated interventional suites reshape procurement relationships across the United States, Germany, and Japan.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for polymeric and biodegradable stent materials compress time-to-market for novel constructs in the United States.
- Biodegradable Material Innovation:Elimination of retrieval procedures drives clinician preference shifts in oncology and benign stricture protocols across biliary applications.
- Japan PMDA Standards:Stringent biocompatibility and durability requirements filter lower-tier manufacturers, concentrating supply among qualified producers serving aging patient populations.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy cost fluctuations compress margins for metallic stent platforms where radial force requirements prevent polymer substitution.
- EU MDR Clinical Evidence Burden:Expanded documentation requirements under the Medical Device Regulation extend commercialization timelines and inflate regulatory compliance expenditure.
- Silicone Substitute Limitations:Lower structural integrity in airway and esophageal applications restricts material substitution despite favorable biocompatibility profiles.
Strategic Opportunities
- India CDSCO Pathway Expansion:Underpenetrated gastrointestinal and biliary stent markets present volume expansion potential as domestic manufacturing scales and reimbursement frameworks mature.
- Integrated OR Contracting:Bundled diagnostic-therapeutic supply agreements enable vendor lock-in across hospital networks seeking procurement simplification.
- Fluoroscopy-Endoscopy Convergence:Hybrid guidance platforms reduce procedure time and radiation exposure, creating differentiated positioning in outpatient settings.
Industry Challenges
- Interventional Gastroenterology Training Pipeline:Specialized endoscopist shortages constrain procedural capacity expansion in ambulatory centers despite installed suite infrastructure.
- CE Marking Technical Documentation:EU Medical Device Regulation compliance timelines delay product launches and require sustained clinical evidence investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Vascular Stents Market |
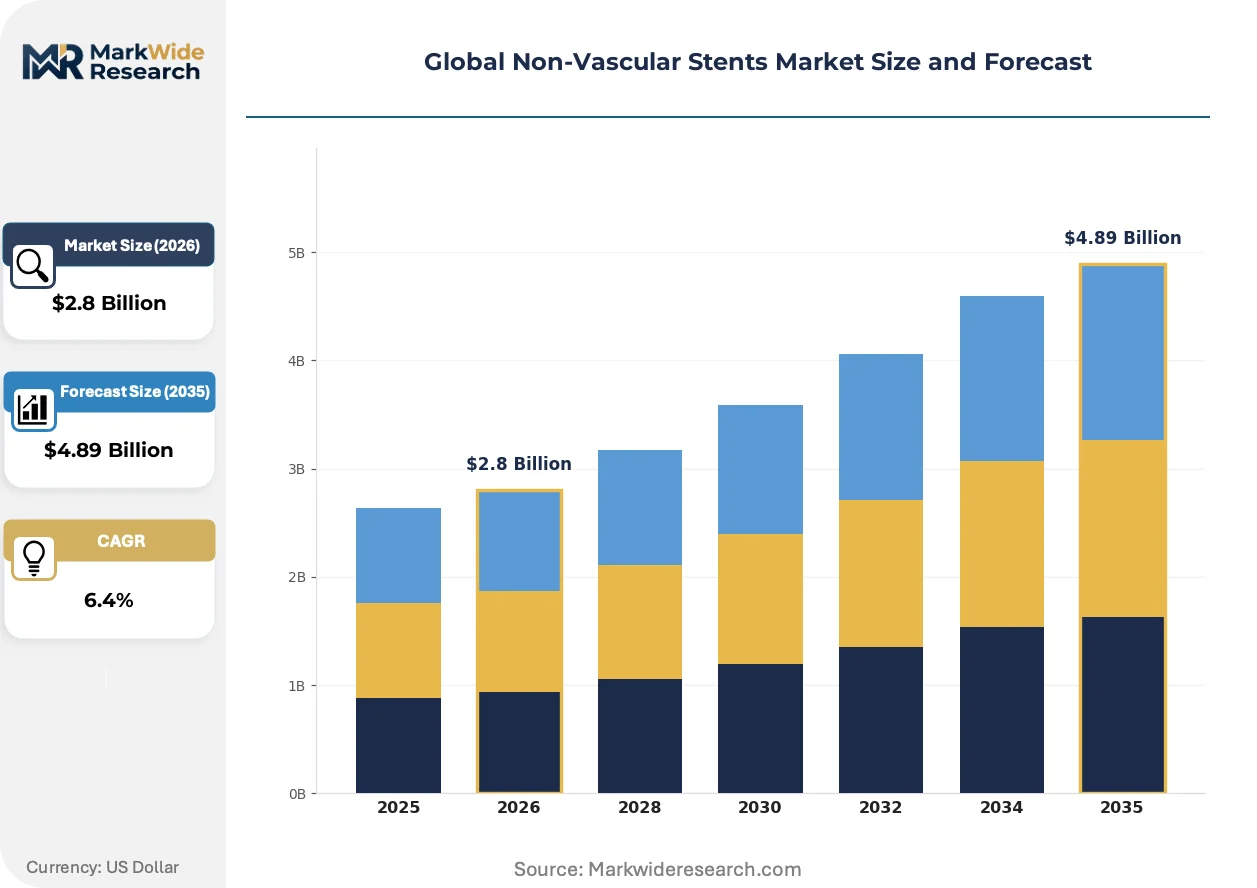
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biliary Stents, Esophageal Stents, Ureteral Stents, Airway Stents, Gastrointestinal Stents Material: Metallic, Polymeric, Biodegradable, Silicone, Hybrid Composite Application: Obstruction Relief, Structural Support, Tumor Palliation, Duct Patency, Fistula Management End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Ambulatory Surgical Centers |
| Companies Covered | Boston Scientific Corporation, Medtronic, Becton, Dickinson and Company, Cook Medical, CONMED Corporation, Taewoong Medical, ELLA - CS, s.r.o., Glaukos Corporation, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Vascular Stents Market Shifts & Advancements
Material science breakthroughs and regulatory pathway evolution are compressing traditional product lifecycles while procurement centralization reconfigures commercial access strategies.
Biodegradable polymer stents are collapsing the retrieval surgery market segment by eliminating scheduled removal procedures. Gastroenterology practices in the United States and Germany are adopting these platforms at accelerating pace for benign biliary strictures. The structural consequence is margin compression for metallic stent manufacturers dependent on replacement revenue cycles.
CE marking under the EU Medical Device Regulation imposes clinical evidence requirements that favor established manufacturers with robust post-market surveillance infrastructure. European commercialization timelines have extended substantially for novel constructs. Biliary and esophageal stent categories face the steepest compliance burden as notified bodies prioritize high-risk implantable reviews.
Hospital procurement networks are consolidating vendor relationships through integrated operating room contracts that span diagnostic and therapeutic device categories. Ambulatory surgical centers are disintermediating traditional distribution channels through direct sourcing relationships with manufacturers. Germany and Japan exhibit the most advanced procurement centralization, with United States health systems rapidly converging toward similar models.
Global Non-Vascular Stents Market Segmentation
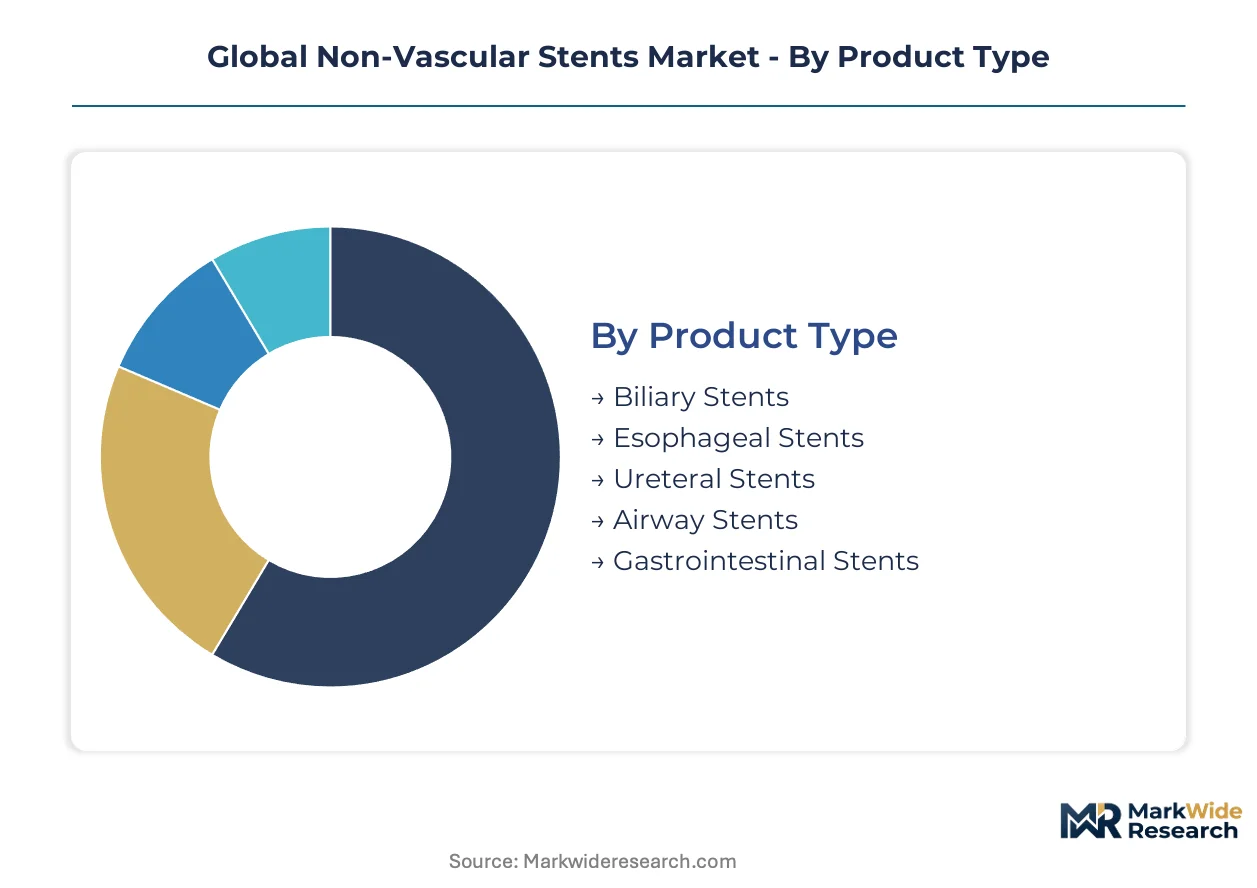
Non-vascular stent procurement decisions cascade through multiple technical and clinical filters. Product type determines procedural protocol compatibility. Material selection governs retrieval requirements and long-term complication profiles.
Product Type:
Use-case spectrum spans oncology palliation through benign stricture management across hepatobiliary, gastrointestinal, and respiratory anatomies.
- Biliary Stents:Self-expanding metallic or plastic constructs deployed via ERCP to relieve malignant and benign bile duct obstruction. Hospital networks in Germany and Japan prioritize these for pancreatic cancer protocols where drainage sustains chemotherapy eligibility.
- Gastrointestinal Stents:Covered and uncovered designs address esophageal, duodenal, and colonic strictures with varying radial force requirements. Ambulatory surgical centers in the United States are expanding placement volume as site-of-service economics favor outpatient deployment.
- Esophageal Stents:High radial force nitinol platforms resist compressive tumor loads and tracheoesophageal fistula formation.
- Ureteral Stents:Double-J configurations maintain ureteral patency following lithotripsy or tumor compression.
- Airway Stents:Silicone and hybrid designs address tracheobronchomalacia and malignant airway obstruction with specialized deployment instrumentation.
Established volume favors biliary platforms; emerging adoption favors gastrointestinal stents as ambulatory capacity expands.
Material:
Cost tier stratification separates premium biodegradable constructs from commodity metallic alternatives.
- Biodegradable:Polylactic acid and polycaprolactone polymers degrade via hydrolysis over 3-6 months, eliminating scheduled retrieval procedures. Clinicians in the United States and Germany are shifting preference toward these for benign biliary strictures where long-term implantation risks exceed retrieval morbidity.
- Metallic:Nitinol and stainless steel alloys deliver permanent radial force for malignant obstructions and airway applications where structural integrity cannot degrade. Nickel-titanium price volatility compresses margins for manufacturers locked into long-term hospital contracts.
- Polymeric:Polyethylene and polyurethane formulations offer lower-cost alternatives with defined replacement intervals.
- Silicone:Excellent biocompatibility profile constrained by lower radial force limits in compressive environments.
- Hybrid Composite:Multi-material constructs combine metallic scaffolding with polymeric or biodegradable coatings for targeted performance profiles.
Margin concentration favors metallic platforms; steepest expansion trajectory belongs to biodegradable materials as retrieval elimination drives protocol revision.
Application:
Customer type alignment separates emergency obstruction relief from elective structural support procedures.
- Obstruction Relief:Emergency decompression of malignant or benign strictures in biliary, esophageal, and ureteral anatomies. Diagnostic centers in Japan handle substantial pre-referral volume before transfer to interventional specialists.
- Tumor Palliation:Stenting as definitive therapy for unresectable malignancies where surgical candidacy is excluded. Outpatient clinics in Germany manage substantial oncology patient flows through dedicated interventional gastroenterology units.
- Structural Support:Maintenance of luminal integrity post-resection or in congenital malformations.
- Duct Patency:Prevention of restenosis following balloon dilation in benign stricture protocols.
- Fistula Management:Sealing of abnormal epithelial communications with covered stent designs.
Procedure volume concentrates in obstruction relief; fastest technology turnover occurs in tumor palliation as biodegradable options reduce intervention frequency.
End User:
Supply concentration favors hospital networks with integrated procurement systems over fragmented outpatient settings.
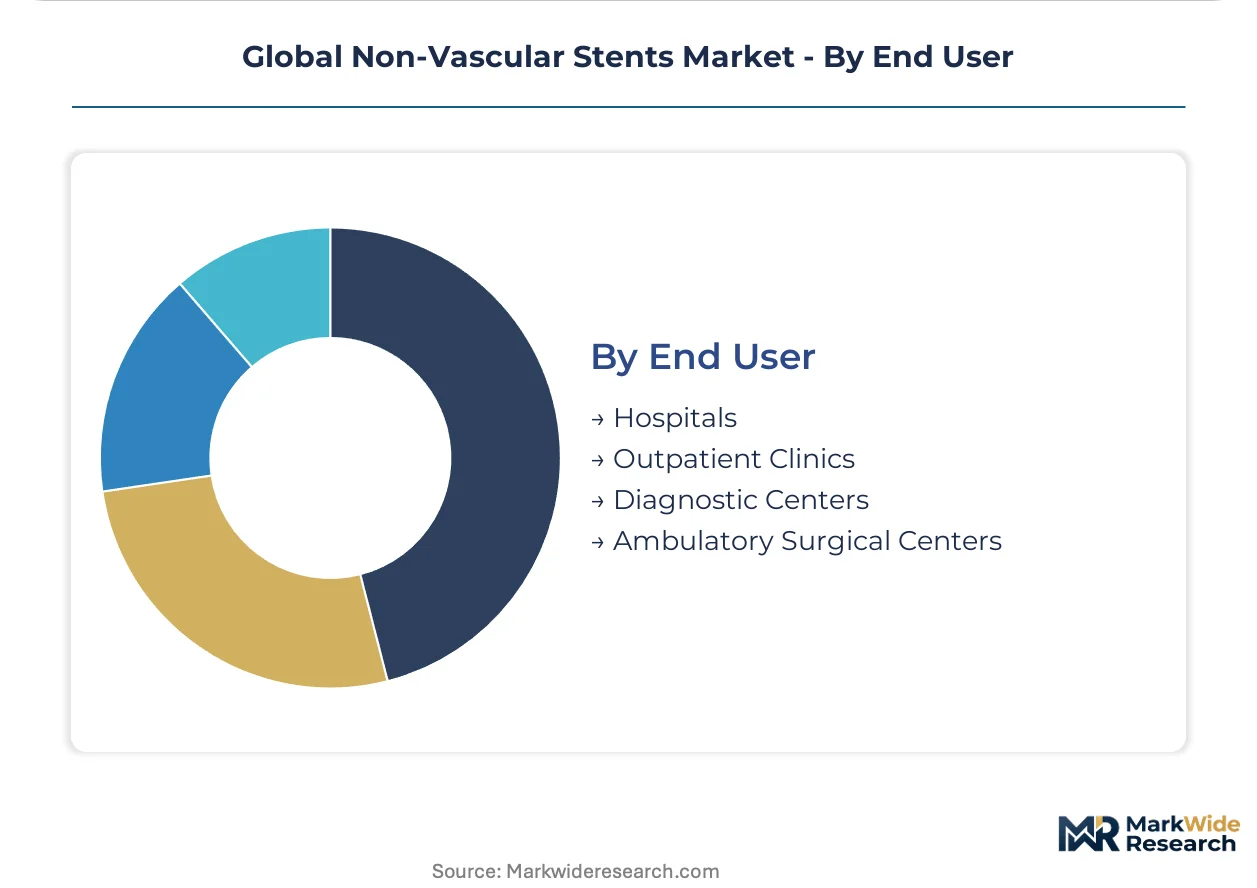
- Hospitals:Academic and community medical centers with 24-hour interventional coverage and complex case referral patterns. United States health systems are consolidating vendor relationships through bundled diagnostic-therapeutic contracts that span endoscopy and fluoroscopy suites.
- Ambulatory Surgical Centers:Dedicated interventional facilities capturing lower-acuity cases from hospital outpatient departments. Germany and Japan exhibit the most advanced procurement centralization, with direct manufacturer relationships displacing traditional distribution.
- Outpatient Clinics:Office-based gastroenterology and urology practices with limited procedural capabilities.
- Diagnostic Centers:Imaging facilities providing pre-interventional assessment and post-placement surveillance.
Installed base dominance favors hospitals; volume migration favors ambulatory surgical centers as reimbursement differentials widen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) pathways anchor commercial access in the United States, while PMDA standards in Japan and EU MDR requirements in Germany concentrate regulatory complexity among qualified manufacturers serving aging populations.
United States
Ambulatory surgical centers capture biliary and gastrointestinal stent volume from hospital outpatient departments as site-of-service reimbursement differentials widen. FDA 510(k) clearance timelines compress for polymeric and biodegradable materials, accelerating product introductions. Minneapolis and Boston anchor interventional device clusters where integrated OR contracting consolidates vendor relationships.
Germany
Hospital procurement networks centralize through bundled diagnostic-therapeutic supply agreements spanning endoscopy and fluoroscopy suites. EU MDR clinical evidence requirements extend commercialization timelines for novel stent constructs. The Rhine-Ruhr and Bavarian medical technology corridors concentrate manufacturing and R&D infrastructure for hepatobiliary applications.
Japan
PMDA biocompatibility and durability standards filter lower-tier manufacturers, concentrating supply among qualified producers. Aging demographics sustain clinical volume for pancreatic cancer protocols where drainage maintains chemotherapy eligibility. The Kanto region around Tokyo hosts the densest concentration of interventional gastroenterology training centers.
India
CDSCO pathway expansion opens underpenetrated gastrointestinal and biliary stent markets as domestic manufacturing scales. Reimbursement frameworks mature for minimally invasive procedures in tier-1 cities. Maharashtra and Gujarat medical device corridors attract contract manufacturing investments from multinational suppliers.
South Korea
MFDS regulatory alignment with international standards streamlines market access for imported and domestic stent platforms. Health system consolidation drives procurement centralization through group purchasing organizations. The Seoul Capital Area concentrates interventional capacity with dedicated suites in academic medical centers.
Global Non-Vascular Stents Market Competitive Landscape
Integrated device conglomerates and specialized interventional platforms split the market between scale-driven procurement leverage and niche procedural expertise. Tier-one manufacturers anchor hospital networks through bundled OR contracts. Tier-two specialists occupy fistula management and airway segments with limited direct competition. Dominant competitive moves include backward integration into nitinol supply chains and technology licensing for biodegradable polymer formulations.
Among US-based multinationals, Boston Scientific Corporation and Medtronic exemplify the integrated conglomerate archetype with endoscopy channel density and OR contracting scale. Cook Medical represents the specialized platform position with focused airway and fistula management portfolios. Taewoong Medical anchors Korean manufacturing capabilities for gastrointestinal applications. These three occupy distinct strategic positions without direct overlap in core procedural segments.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Becton, Dickinson and Company |
| Cook Medical |
| CONMED Corporation |
| Taewoong Medical |
| ELLA - CS, s.r.o. |
| Glaukos Corporation |
| Merit Medical Systems |
| Others |
Supply & Pricing Matrix
The Rotterdam-Antwerp medical device logistics corridor channels nitinol alloy shipments from European mills to German and Dutch sterilization facilities, with freight cost volatility feeding directly into configured-to-order pricing premiums for biliary stents and compressing margins on standard metallic platforms procured through hospital GPO contracts.
Pricing Analysis
The customization-premium spread separates configured-to-order biodegradable stents from standard metallic platforms by certification tier and volume scale. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, with CE-marked biodegradable constructs commanding highest placement fees. Cost compression in economy metallic tiers is intensifying because nickel-titanium spot price volatility erodes contract margins. Ambulatory surgical centers exhibit greatest price sensitivity; academic medical centers with bundled OR contracts show lowest sensitivity due to diagnostic-therapeutic integration.
Supply Chain Analysis
Upstream feedstock concentration in nitinol smelting draws from United States, Germany, and Japan specialty alloy producers serving medical-grade specifications. Polylactic acid and polycaprolactone polymer resins rest on German and South Korean chemical manufacturers, with silicone sourcing anchored in United States and Japanese suppliers. Single-source vulnerability in nitinol wire drawing creates exposure for metallic stent platforms. Distribution runs through hospital procurement networks and direct manufacturer relationships with ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-vascular stents market operates as a substitution defense against biodegradable polymer platforms that threaten to collapse retrieval procedure revenue cycles for metallic stent incumbents.
For Market Incumbents: Pre-empt biodegradable substitution by accelerating polylactic acid formulation R&D and securing backward integration into polymer resin supply through German chemical partnerships. Anchor hospital networks with integrated OR contracts spanning diagnostic endoscopy and therapeutic stent placement to lock out emerging polymer specialists. FDA 510(k) clearance velocity serves as the priority defensive lever against European biodegradable entrants. For New Entrants and Emerging Players: Ambulatory surgical center direct sourcing relationships in the United States represent the most penetrable entry point for biodegradable biliary platforms lacking established GPO contracts. India's CDSCO pathway expansion offers regulatory arbitrage for domestic manufacturing scale before reimbursement framework maturation. Target hybrid fluoroscopy-endoscopy guidance bundling as the go-to-market angle to differentiate against legacy metallic portfolios. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underoptimized gastrointestinal stent divisions lacking biodegradable pipelines. Long-term viability over the next decade hinges on material science transition completion and ambulatory site-of-service capture velocity. Monitor Japan PMDA biodegradable approval timelines as the inflection signal for Asia-Pacific demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed clearance timelines for biodegradable materials unlock United States ambulatory center penetration before competitor portfolio refresh. |
| CE Marking Pathway Investment | EU MDR clinical evidence infrastructure requirements filter out undercapitalized rivals in biliary and esophageal categories. |
| Hospital System Partnership | Bundled diagnostic-therapeutic contracts with United States health systems lock in metallic stent volume against polymer substitution. |
| Biodegradable Polymer R&D Expansion | Polylactic acid and polycaprolactone formulation advances eliminate retrieval surgery revenue dependence for oncology protocols. |
| Reimbursement Strategy Development | Site-of-service economics alignment with United States payor differentials between hospitals and ambulatory centers shapes procurement decisions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) databases, EU MDR notified body filings, and hospital GPO contract repositories. Interviews with interventional gastroenterologists, biomedical engineers, hospital purchasing committee chairs, and ambulatory center operations directors informed procedural volume and material preference assessments. Secondary sources include CMS Medicare reimbursement data, PMDA approval registers, and nitinol trade flow statistics. Bottom-up stent placement volume estimates triangulate against top-down manufacturer revenue segmentation.
Forecast inputs span product type, material category, application indication, and end-user facility type across the analysis window. Modeled dimensions include biliary versus gastrointestinal versus airway anatomies, biodegradable versus metallic versus polymeric material platforms, and hospital versus ambulatory surgical center site-of-service. CAGRs derive from procedural volume trajectory analysis calibrated to demographic aging patterns and reimbursement elasticity assumptions. Nitinol price volatility coefficients and PMDA approval lag estimates inform scenario-bound projections.
Practitioners should monitor Japan PMDA biodegradable stent approval timelines, United States site-of-service reimbursement recalibrations, and nitinol alloy spot price movements for early signals of forecast revision. Cross-checking against hospital procurement database placement volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Varicose Veins Treatment Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Cardiogenic Shock Treatment Market
Cardiovascular Devices
Vascular Prostheses Market
Cardiovascular Devices
Global Aortic Endografts Market
Cardiovascular Devices
Vascular Snare Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Arrhythmogenic Right Ventricular Dysplasia Treatment Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Global Embolotherapy Market
Cardiovascular Devices
US Hemostats Market
Cardiovascular Devices
Renovascular Hypertension Treatment Market
Cardiovascular Devices
Global Vascular Graft Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market