
 Pulmonary Artery Catheter Market | 2026-2036
Pulmonary Artery Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Pulmonary Artery Catheter Market Outlook
Software-enabled hemodynamic interpretation is rebalancing how pulmonary artery catheter value gets captured across the care continuum. Edwards Lifesciences Corporation leverages its integrated monitoring platforms to extend beyond hardware into continuous data analytics services. ICU Medical anchors its position through dedicated vascular access portfolios that bundle catheter maintenance protocols with disposable supply contracts. Becton Dickinson and Company competes by controlling distribution density across integrated delivery networks in North America.
A pulmonary artery catheter is a multi-lumen balloon-tipped catheter inserted into the pulmonary artery to measure intracardiac pressures, cardiac output via thermodilution, and mixed venous oxygen saturation using fiber-optic technology. Thermodilution catheters retain the largest installed base due to decades of clinical validation in cardiac output measurement, though automated delivery systems represent the fastest-expanding delivery mode segment as closed-loop inflation reduces operator variability. Hospitals dominate end-user demand because high-acuity settings require 24-hour invasive monitoring capabilities that surgical centers and specialty clinics rarely maintain.
FDA Class III premarket approval requirements govern device safety and efficacy submissions for new pulmonary artery catheter designs in the United States. The EU MDR demands expanded post-market clinical follow-up and notified body recertification, lengthening market access timelines for European launches. Japan's PMDA enforces QMS ministerial ordinances that align with international ISO 13485 standards while adding domestic clinical trial expectations. Stakeholders must weigh regulatory capital requirements against the limited pipeline of non-invasive alternatives when allocating R&D budgets for invasive hemodynamic monitoring.
Market Dynamics
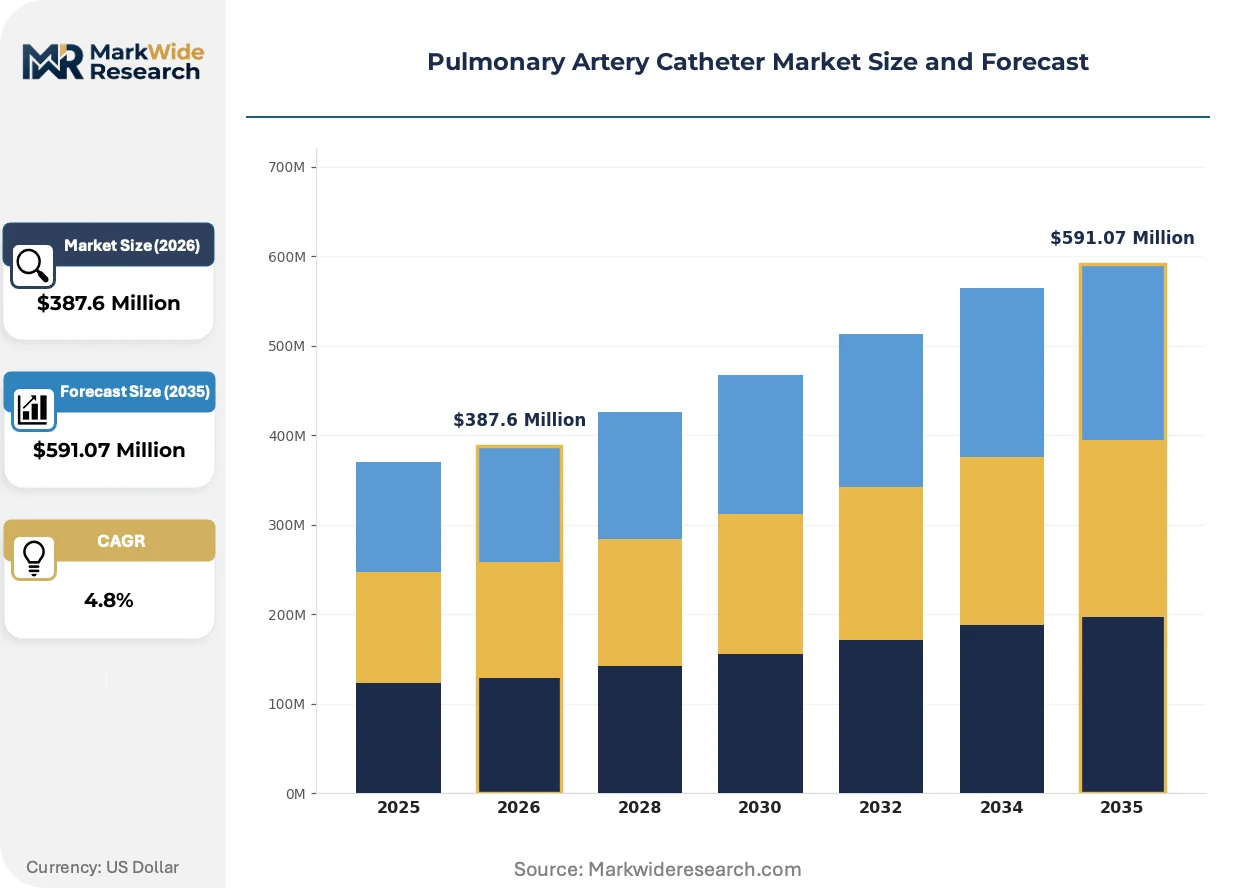
The Pulmonary Artery Catheter Market is restructuring around software-enabled hemodynamic interpretation that extracts recurring revenue from disposable hardware. Vendors now compete on analytics integration rather than catheter specifications alone.
Growth Catalysts
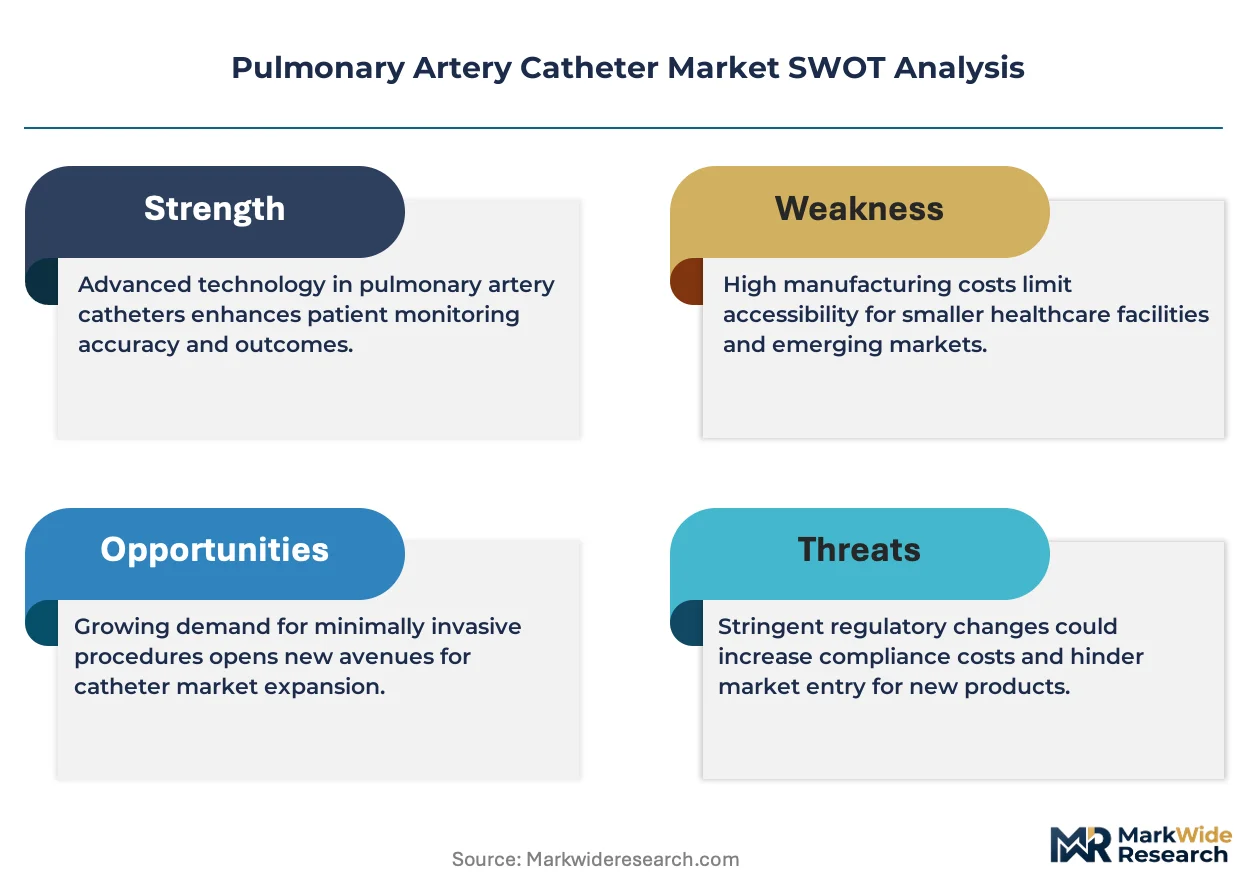
- EU MDR clinical evidence requirements:Stricter post-market surveillance mandates compel hospitals to upgrade to validated catheter platforms with documented safety profiles, accelerating replacement cycles in tertiary cardiac centers.
- Septic shock protocol standardization:Critical care units in the United States increasingly embed invasive hemodynamic monitoring into sepsis bundles, creating procedural pull-through for multi-lumen catheter systems.
- Fiber-optic oximetry miniaturization:Advances in optical sensor manufacturing enable continuous mixed venous oxygen saturation monitoring without additional blood draws, reducing nursing workload in high-acuity settings.
Market Restraints
- Polyurethane raw material concentration:Specialty medical-grade polymer supply chains cluster with German and Japanese chemical producers, exposing catheter manufacturers to input cost volatility and allocation risk.
- Non-invasive cardiac output alternatives:Arterial pressure waveform analysis and bioreactance monitoring systems displace invasive placement in intermediate-risk surgical populations, compressing addressable volume.
- FDA Class III PMA timelines:Premarket approval pathways for novel catheter designs extend development cycles, freezing design iterations while competitors iterate software overlays on cleared hardware platforms.
Strategic Opportunities
- Japan's aging surgical population:PMDA-registered catheter platforms face limited domestic competition in complex cardiac procedures, rewarding early QMS ministerial ordinance compliance.
- Closed-loop automated inflation systems:Integration of pressure-sensor feedback with balloon delivery mechanisms reduces operator-dependent measurement variability, opening differentiation in teaching hospitals.
- Integrated delivery network bundling:Vascular access maintenance protocols combined with disposable supply contracts lock in multi-year purchasing commitments across North American hospital systems.
Industry Challenges
- Interventional cardiology fellowship pipeline:Declining procedural training volume in right heart catheterization techniques constrains qualified operator availability for complex ICU placements.
- ISO 13485 harmonization gaps:Divergent notified body interpretations of risk management documentation create unpredictable certification timelines across European member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulmonary Artery Catheter Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $591.07 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Lumen, Dual-Lumen, Thermodilution, Balloon-Inflation Application: Critical Care, Cardiology, General Surgery, Anesthesia End User: Hospitals, Surgical Centers, Specialty Clinics, Research Institutions Delivery Mode: Manual, Automated, Portable, Reusable |
| Companies Covered | Edwards Lifesciences Corporation, ICU Medical, Argon Medical, B. Braun Melsungen AG, Becton Dickinson and Company, Medtronic, Terumo Corporation, Smiths Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulmonary Artery Catheter Market Strategic Shifts
Data analytics layers are electrifying how catheter value gets captured and delivered across the care continuum, shifting competitive advantage from hardware specifications to real-time interpretation capabilities.
Closed-loop balloon inflation systems are electrifying operator workflows by automating wedge pressure acquisition. Tertiary hospital ICUs in Germany and Japan adopt these platforms fastest, drawn to reduced inter-operator variability in cardiac output calculations. The technology is electrifying vendor business models toward per-patient monitoring subscriptions that decouple revenue from catheter replacement frequency.
The EU MDR's expanded post-market clinical follow-up obligations are compressing product lifecycle planning for catheter manufacturers. Device sponsors must now commit to multi-year safety registries before notified body recertification, diverting R&D capital from hardware innovation toward clinical evidence generation. Thermodilution catheter portfolios face the steepest compliance burden given their established installed base and longest market tenure.
Hospital procurement committees are consolidating hemodynamic monitoring vendor relationships to simplify service contracting and training standardization. Integrated delivery networks in the United States now specify single-source analytics platforms that normalize data across catheter, arterial line, and non-invasive sensors. This concentration rewards vendors with existing software footprints while marginalizing pure hardware suppliers lacking continuous monitoring infrastructure.
Pulmonary Artery Catheter Market Segmentation
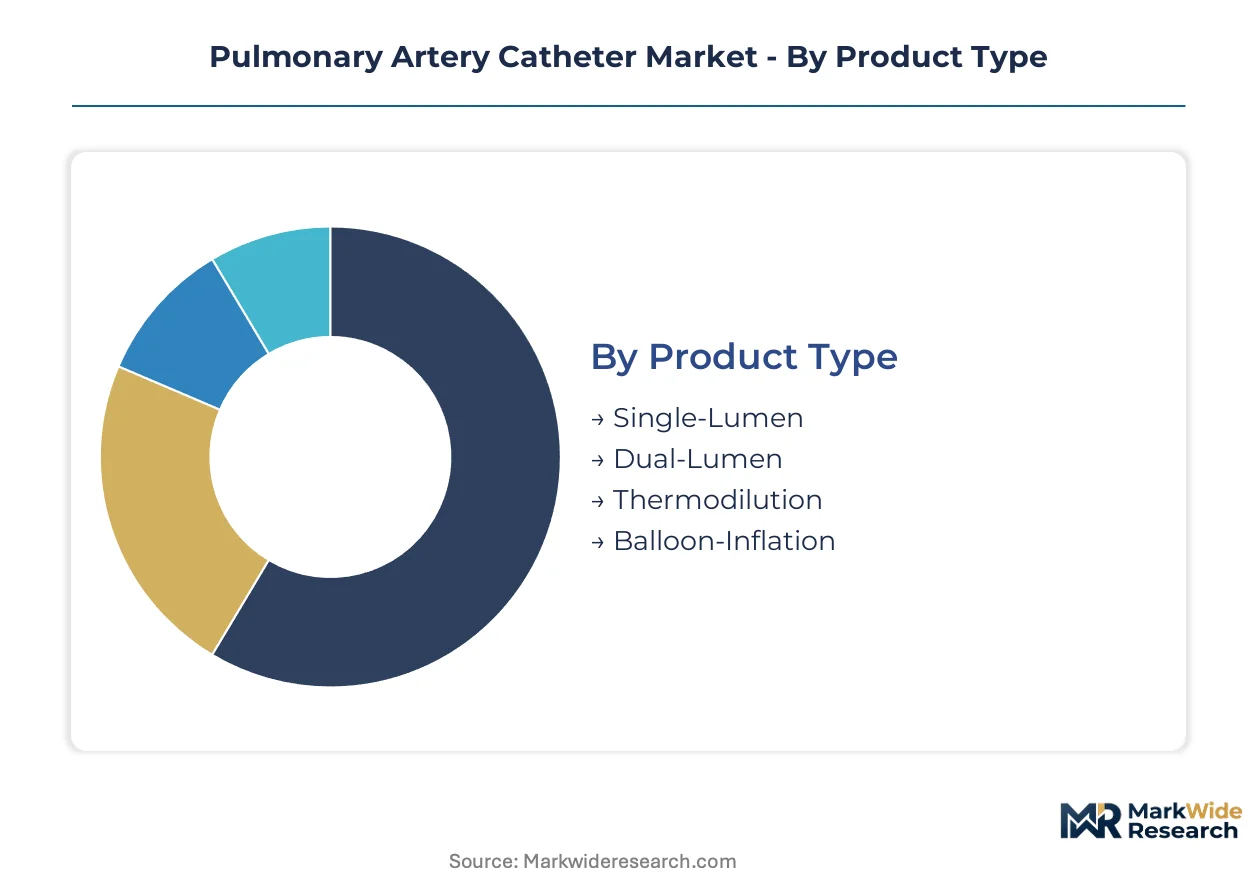
Pulmonary artery catheter segmentation reveals how clinical workflow requirements fragment procurement decisions across acute care settings. Product specifications, delivery mechanisms, and end-user capabilities create distinct commercial battlegrounds that vendors must navigate simultaneously.
Product Type:
Thermodilution catheters command premium positioning through decades of cardiac output validation, while single-lumen variants serve cost-constrained procedural volumes.
- Thermodilution:Multi-lumen design incorporating temperature-sensing filaments enables bolus-based cardiac output calculation via thermodilution curves. Tertiary cardiac centers in the United States specify these systems for post-surgical hemodynamic surveillance, driven by bundled payment incentives that reward accurate fluid management outcomes.
- Balloon-Inflation:Integrated balloon mechanisms facilitate wedge pressure acquisition and right heart navigation during catheter advancement. German and Japanese ICUs favor automated inflation variants that reduce inter-operator variability in critically ill patient populations.
- Dual-Lumen:Parallel channels permit simultaneous pressure monitoring and fluid administration without line exchanges.
- Single-Lumen:Simplified construction addresses intermittent monitoring needs in lower-acuity procedural settings.
Today's leader: Thermodilution. Tomorrow's challenger: Balloon-Inflation.
Application:
Critical care units generate disproportionate utilization intensity, whereas cardiology departments anchor technology upgrade cycles.
- Critical Care:Continuous hemodynamic monitoring in septic shock and acute respiratory distress syndrome demands multi-parameter catheter systems with fiber-optic oximetry capabilities. United States hospitals embed these devices into sepsis protocol bundles, creating procedural standardization that locks in recurring catheter consumption.
- Cardiology:Pre- and post-interventional hemodynamic assessment in complex valvular disease requires precise pressure waveform interpretation. Japanese cardiac surgery volumes sustain specialized catheter procurement despite demographic pressure on overall procedure counts.
- General Surgery:Perioperative fluid optimization in major abdominal procedures drives intermittent monitoring adoption.
- Anesthesia:High-risk non-cardiac surgery populations generate demand for rapid-deployment monitoring systems.
Critical care generates the steepest expansion trajectory as protocol standardization accelerates.
End User:
Hospital infrastructure investments determine addressable market boundaries, while surgical centers and specialty clinics capture procedure migration.
- Hospitals:24-hour ICU staffing and centralized sterile processing capabilities support invasive monitoring programs that smaller facilities cannot replicate. Integrated delivery networks in the United States consolidate purchasing across multiple hospital campuses, rewarding vendors with enterprise-level service contracts.
- Surgical Centers:Ambulatory cardiac and vascular procedures create demand for simplified catheter systems with rapid turnover protocols.
- Specialty Clinics:Heart failure management programs require intermittent right heart catheterization for hemodynamic profiling.
- Research Institutions:Academic medical centers drive protocol development and training curriculum standardization.
Hospitals dominate installed base economics. Research institutions shape next-generation adoption patterns.
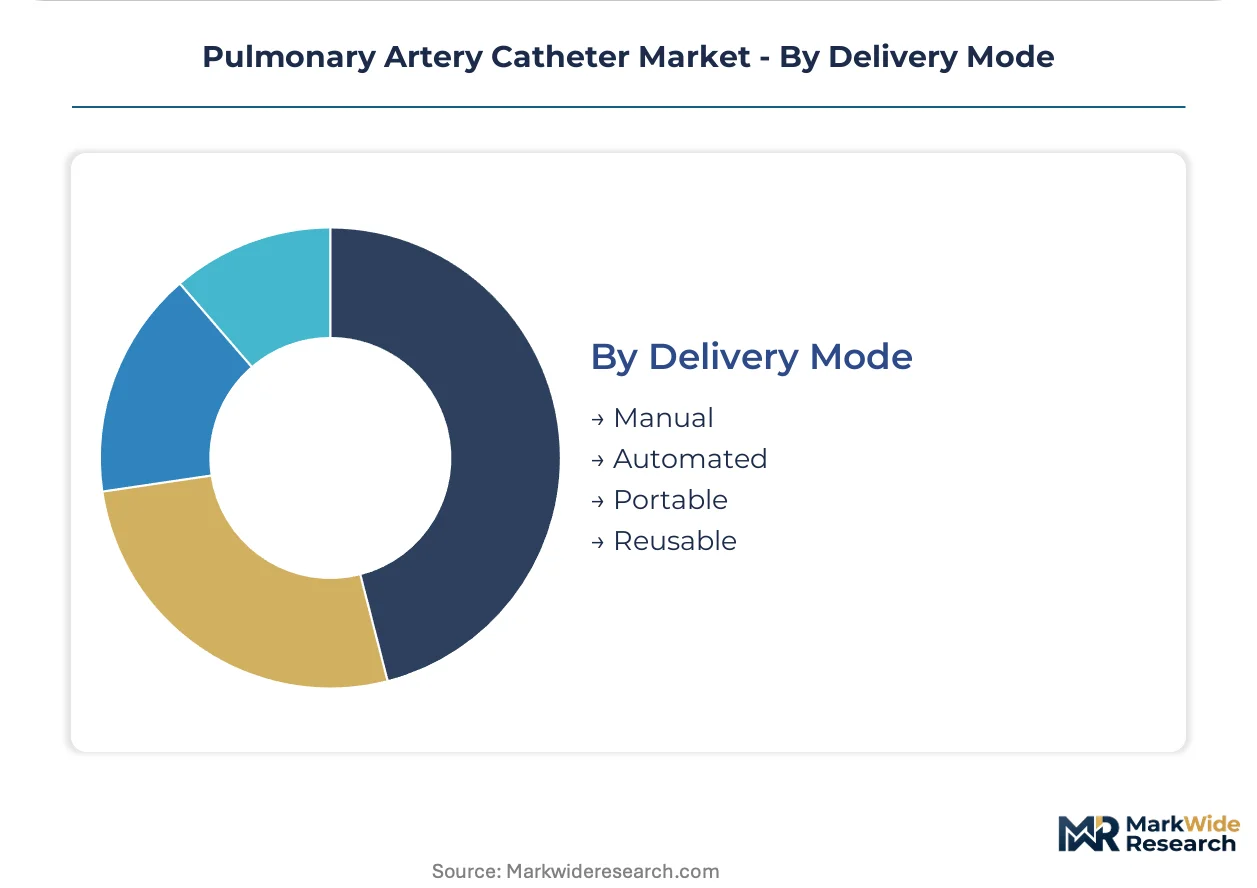
Delivery Mode:
Automation premiums reshape procurement calculations as closed-loop systems reduce training burden and measurement variability.
- Automated:Pressure-sensor feedback integrated with balloon inflation mechanisms standardizes wedge pressure acquisition across operator experience levels. Teaching hospitals in Germany adopt these platforms to reduce fellow-dependent measurement artifacts.
- Manual:Conventional syringe-based inflation retains cost advantages in price-sensitive procurement environments.
- Portable:Battery-powered monitoring consoles extend catheter utility to intra-hospital transport and emergency department stabilization.
- Reusable:Limited reprocessing acceptance outside research settings due to FDA and EU MDR single-use labeling requirements.
Automated systems gain share fastest as labor costs and liability exposure reshape ICU economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan sustain comparable catheter utilization intensity despite diverging regulatory pathways, while the United States generates the largest absolute procedural volume through integrated delivery network consolidation.
United States
Septic shock protocol standardization and bundled payment incentives for cardiac surgery drive multi-lumen catheter procurement across tertiary centers. FDA Class III premarket approval requirements govern new device submissions, extending development timelines for novel designs. The Cleveland Clinic and Mayo Clinic clusters anchor hemodynamic monitoring training curriculum standardization.
Germany
EU MDR post-market surveillance mandates accelerate replacement cycles toward validated catheter platforms with documented safety profiles. Notified body recertification obligations under the MDR lengthen European market access timelines. The Baden-Württemberg medical technology corridor concentrates catheter manufacturing and sterile processing infrastructure.
Japan
Aging surgical populations and sustained complex cardiac procedure volumes sustain specialized catheter demand despite demographic pressure. PMDA QMS ministerial ordinances align with ISO 13485 standards while adding domestic clinical trial expectations. Tokyo and Osaka metropolitan medical centers drive automated delivery system adoption.
United Kingdom
NHS procurement consolidation favors vendors with enterprise-level service contracts and continuous monitoring infrastructure. MHRA post-Brexit regulatory alignment with EU MDR clinical evidence requirements shapes product development planning. The Oxford-Cambridge-London research triangle shapes next-generation hemodynamic analytics protocols.
Pulmonary Artery Catheter Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated monitoring platforms commanding premium positioning over pure hardware suppliers. The vendor base concentrates around three strategic tiers: diversified cardiovascular device conglomerates, dedicated vascular access specialists, and regional catheter fabricators. Competitive positioning hardens through M&A activity targeting software-enabled analytics capabilities and strategic partnerships bundling disposable supply contracts with maintenance protocols.
Within the diversified cardiovascular tier, Edwards Lifesciences Corporation and Medtronic exemplify integrated platform strategies extending beyond hardware into continuous data analytics services. ICU Medical occupies a position among dedicated vascular access specialists anchoring procurement relationships through bundled catheter maintenance protocols. Terumo Corporation represents the Asia-Pacific fabrication archetype with domestic regulatory compliance advantages in PMDA-registered platforms.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| ICU Medical |
| Argon Medical |
| B. Braun Melsungen AG |
| Becton Dickinson and Company |
| Medtronic |
| Terumo Corporation |
| Smiths Medical |
| Merit Medical Systems |
| Others |
Value Chain & Pricing Dynamics
Interventional cardiology fellowship concentration in the United States Northeast and German Baden-Württemberg corridor drives labor-cost differentials that widen pricing spreads between premium automated systems and economy manual alternatives.
Pricing Analysis
Capacity additions in Chinese polymer processing are reshaping price floors for polyurethane catheter tubing, compressing margins on standard thermodilution models while preserving premiums on fiber-optic systems. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared automated platforms from CE-marked manual variants and unbundled single-lumen commodities. Cost compression in the standard tier is intensifying because GPO contracts consolidate purchasing volume. Academic medical centers show least price sensitivity due to bundled analytics subscriptions; ambulatory surgical centers exhibit highest sensitivity to per-unit catheter costs.
Supply Chain Analysis
Single-use catheter returns and reprocessing restrictions under EU MDR and FDA labeling requirements eliminate refurbishment flows, forcing manufacturers to absorb full material costs in each production cycle. German and Japanese chemical producers anchor specialty medical-grade polyurethane supply, with Chinese processors expanding commodity-grade capacity. Catheter fabrication draws from optical fiber bundles, precision-molded balloons, and temperature-sensing filaments. Single-source vulnerability concentrates in German polymer additive supply. Distribution runs through integrated delivery network contracting offices and hospital procurement committees rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story justified by critical care unit demand-shift toward continuous monitoring platforms with embedded analytics capabilities.
For Market Incumbents: Anticipate non-invasive cardiac output monitor substitution by locking hospital system relationships through multi-year disposable supply contracts bundled with vascular access maintenance protocols. Defend against software-enabled entrants by deepening in-house production of fiber-optic sensor modules to preserve margin on oximetry-capable catheters. For New Entrants and Emerging Players: Enter via Japan's PMDA-registered platform pathway where domestic clinical trial requirements limit foreign competition in complex cardiac procedures. Target automated delivery mode segment white space in German teaching hospitals seeking reduced inter-operator variability. Pursue strategic partnerships with established vascular access specialists to bypass GPO exclusion clauses. For Investors and Strategic Acquirers: Valuations sit cheapest among pure hardware suppliers lacking continuous monitoring infrastructure. Long-term viability favors vendors with software recurring revenue streams and FDA-cleared automated platforms. Watch FDA 510(k) clearance velocity for closed-loop inflation systems as inflection indicator for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Analytics layers extract recurring revenue from disposable catheter hardware across ICU networks. |
| Hospital System Partnership | Integrated delivery network contracts lock multi-year purchasing commitments and training standardization. |
| FDA Submission | Premarket approval pathways for novel designs extend competitive moats against software-only entrants. |
| CE Marking Pathway | EU MDR clinical evidence requirements accelerate replacement cycles toward validated platforms. |
| Reimbursement Strategy | Sepsis bundle inclusion and cardiac surgery bundled payments sustain procedural pull-through volume. |
Study Parameters
Direct dialogue with critical care physicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative findings, cross-checked against FDA 510(k) and PMA filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation validated segmentation outputs.
Bottom-up modeling anchored installed base estimates by catheter type and delivery mode against tertiary hospital ICU bed counts; top-down checks applied macro healthcare expenditure trends across the analysis window. Segmentation dimensions spanned product architecture, application acuity, end-user infrastructure tier, and automation level. CAGRs derived from procedure volume elasticity to sepsis protocol penetration and cardiac surgery demographic trends.
Inputs from regulatory filings and hospital contracting databases were available through the study window; gaps in real-time pricing transparency across private GPO negotiations introduce uncertainty bands around vendor revenue allocation estimates. Forecasts reflect assumptions about EU MDR recertification timelines and PMDA trial enrollment rates. Practitioners should monitor FDA guidance on closed-loop device software validation and CMS sepsis bundle reimbursement adjustments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Cardiovascular Ultrasound Imaging Systems Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Arterial Blood Sampling Systems Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Cardiovascular Needle Market
Cardiovascular Devices
Percutaneous Coronary Intervention Guidance Devices Market
Cardiovascular Devices
Disposable Blood Pressure Cuffs Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market