
 Perfusion Market | 2026-2036
Perfusion Market Size, Share, and Industry Trends Forecast 2026-2036
Perfusion Market Outlook
Aftermarket service revenue is tilting toward preventive maintenance contracts and remote monitoring subscriptions as hardware margins compress across the installed base. Getinge leverages its integrated service network to capture recurring revenue from ECMO platform upkeep across European hospital systems. Medtronic anchors its position through deep field engineering presence and long-term service agreements tied to its heart-lung machine deployments. LivaNova PLC differentiates by specializing in perfusion consumables that lock in repeat purchases from its hardware customers.
Perfusion denotes the extracorporeal circulation of blood through artificial organs or mechanical devices, typically operating at flow rates of 2-6 liters per minute with precise temperature control between 28°C and 37°C to maintain metabolic support during cardiac arrest or organ preservation. Its primary commercial purpose is sustaining patient viability during open-heart surgery, lung transplantation, and extended respiratory failure where native cardiopulmonary function is suspended or insufficient. Extracorporeal membrane oxygenation systems command the highest capital allocation due to their expanding use in acute respiratory distress syndrome and as bridges to transplant. Cardiac surgery remains the dominant application segment, though organ transplant perfusion is generating disproportionate R&D investment as normothermic machine perfusion extends viable preservation windows.
The FDA's PMA and 510(k) frameworks govern device clearance, while the EU MDR and ISO 13485 quality standards enforce design controls and post-market surveillance across European manufacturing and distribution channels. These regulatory structures elevate barriers for new entrants, consolidate compliance spending among established manufacturers, and directly shape product development roadmaps through clinical evidence requirements. Stakeholders must monitor how evolving MDR notified body capacity constraints and FDA breakthrough device designations redistribute competitive advantage between firms with robust quality management systems and those reliant on legacy certifications.
Market Dynamics
Cardiac surgery suites are consolidating purchasing power around integrated perfusion platforms while membrane oxygenation technology advances compress replacement cycles for legacy heart-lung machines.
Growth Catalysts
- EU MDR breakthrough pathway:Accelerated conformity assessment for novel oxygenation membranes is shortening time-to-market for next-generation ECMO circuits across German and French hospital systems.
- Japan's super-aging demographic:Patients over 75 now comprise the majority of complex cardiac procedures in Tokyo and Osaka medical centers, expanding addressable surgical volumes.
- Normothermic machine perfusion:Extended organ viability windows for lung and heart transplants are converting static cold storage protocols to active perfusion preservation at major US transplant centers.
Market Restraints
- Silicone membrane supply concentration:Three specialized polymer suppliers in Germany and Japan control medical-grade silicone sheet production for oxygenator fabrication.
- FDA PMA clinical evidence thresholds:Randomized controlled trial requirements for breakthrough device designation impose multi-year development timelines before commercial deployment.
- Perfusionist workforce scarcity:Certified clinical perfusion training programs in the United States graduate fewer than 150 specialists annually against replacement demand.
Strategic Opportunities
- Remote monitoring subscriptions:Cloud-connected ECMO platforms enable predictive maintenance revenue streams that decouple service income from hardware replacement cycles.
- India's tertiary hospital expansion:Greenfield cardiac institutes in Delhi, Mumbai, and Bangalore are specifying perfusion equipment for first-time open-heart surgery programs.
- Portable ECMO miniaturization:Ambulatory extracorporeal circuits are opening inter-hospital transport and emergency field deployment applications previously served by mechanical ventilation.
Industry Challenges
- Biocompatibility validation complexity:ISO 10993 hemocompatibility testing for novel surface coatings extends development timelines by 18-24 months.
- Legacy device interoperability:Proprietary data protocols between competing heart-lung machines and patient monitoring systems force costly interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perfusion Market |
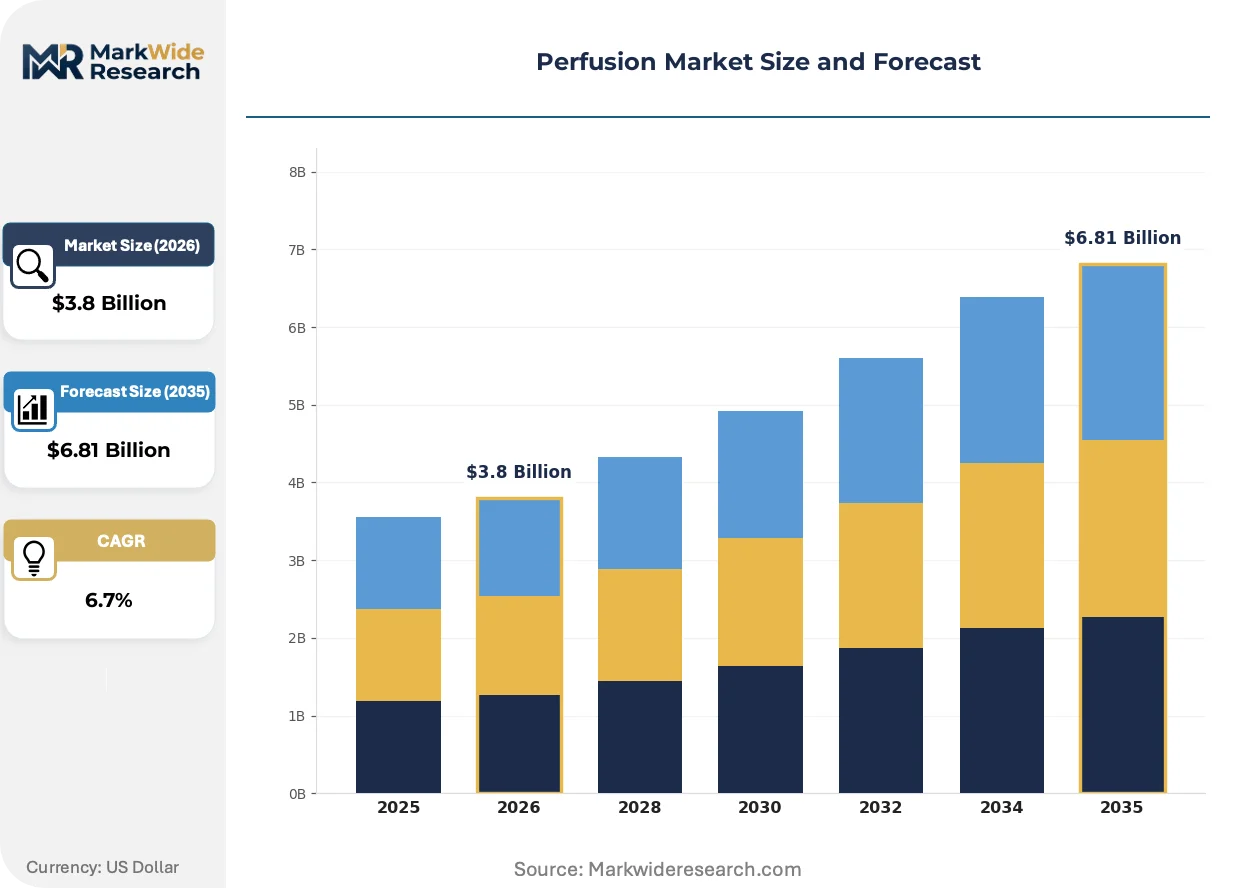
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracorporeal Membrane Oxygenation, Heart-Lung Machine, Perfusion Pumps, Blood Reservoirs Application: Cardiac Surgery, Organ Transplant, Trauma, Respiratory Disorders End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Technology: Mechanical Circulatory Support, Blood Oxygenation Systems, Vascular Perfusion Devices, Automation Systems |
| Companies Covered | Getinge, Medtronic, LivaNova PLC, Terumo Corporation, XVIVO Perfusion AB, TransMedics, Merck KGaA, Repligen Corporation, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perfusion Market Strategic Shifts
Perfusion technology is pivoting from passive blood handling toward active physiologic modulation, with sensor integration and automated feedback loops replacing manual flow management.
Hollow-fiber oxygenation membranes with integrated pressure sensors and real-time clot detection algorithms are rendering obsolete conventional membrane oxygenators that require continuous manual surveillance. Tertiary cardiac centers in Germany and the United States are prioritizing these platforms for high-complexity procedures. The shift is compressing training requirements while elevating capital equipment specifications.
The FDA's breakthrough device designation pathway is compressing review timelines for perfusion innovations that demonstrate substantial advantage over approved alternatives. Manufacturers with established quality management systems capture priority review slots, while smaller entrants face resource constraints in assembling predicate-equivalent clinical packages. Cardiac surgery applications see the highest concentration of designations.
Hospital procurement committees are unbundling service contracts from initial capital purchases, forcing equipment vendors to compete on standalone maintenance pricing. European hospital systems pioneered this separation, with German and Dutch purchasing cooperatives now mandating competitive rebidding for multi-year perfusion platform upkeep. The practice is spreading to US integrated delivery networks seeking to reduce total cost of ownership metrics.
Perfusion Market Segmentation
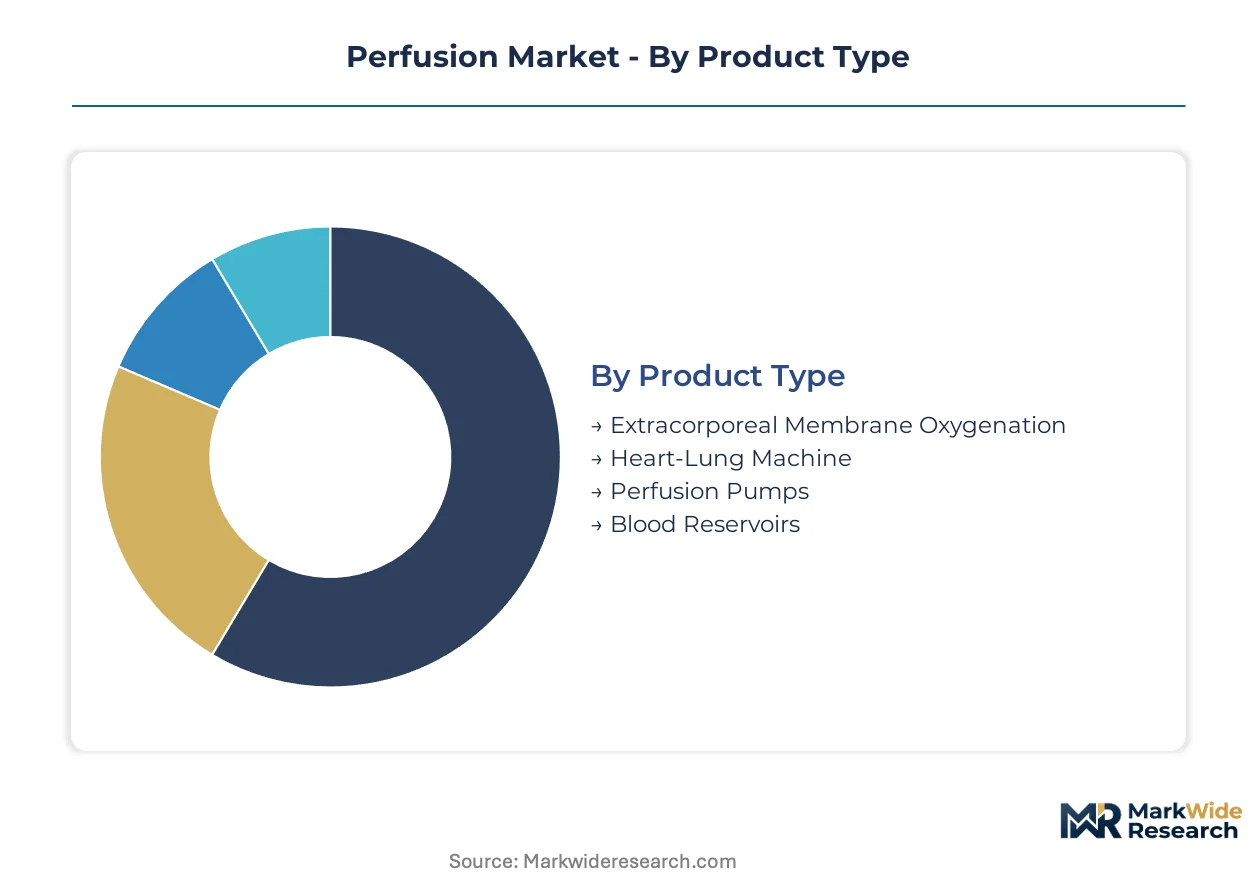
Perfusion equipment purchasing follows distinct technical and clinical workflows that reshape vendor engagement models. Segmentation reveals where capital intensity concentrates versus where consumable attach rates and service contracts generate recurring revenue.
Product Type:
After-sales-service intensity varies dramatically across product categories, with capital platforms demanding multi-year maintenance contracts while consumables drive repeat purchase velocity.
- Extracorporeal Membrane Oxygenation:Integrated membrane-lung circuits operate at blood flow rates of 2-6 liters per minute with integrated heat exchangers. Tertiary cardiac centers in the United States and Germany are prioritizing next-generation ECMO platforms for acute respiratory distress syndrome bridges, though silicone membrane supply bottlenecks constrain fleet expansion.
- Heart-Lung Machine:Central console systems with roller or centrifugal pumps maintain cardiopulmonary bypass during open-heart procedures. Japanese hospital systems are consolidating procurement around integrated platforms that bundle oxygenators, pumps, and monitoring modules under single-vendor service agreements.
- Perfusion Pumps:Roller and centrifugal designs deliver precise flow control with integrated bubble detection and pressure monitoring.
- Blood Reservoirs:Hard-shell and soft-shell configurations manage venous return and cardiotomy suction during bypass procedures.
ECMO holds the largest share; momentum sits with heart-lung machines as cardiac surgery volumes climb in super-aging populations.
Application:
Clinical urgency and reimbursement pathways segment perfusion demand into scheduled procedures versus emergent interventions with diverging equipment specifications.
- Cardiac Surgery:Coronary artery bypass grafting and valve replacement procedures constitute the procedural backbone, requiring sustained cardiopulmonary bypass support. United States tertiary hospitals are expanding hybrid operating suites that combine surgical perfusion with interventional catheterization capabilities.
- Organ Transplant:Normothermic machine perfusion for lung and heart preservation extends viable ischemic windows from hours to days. Major US transplant centers are converting from static cold storage to active perfusion preservation, driving capital allocation toward portable organ care systems.
- Trauma:Emergency thoracotomy and damage-control resuscitation require rapid deployment perfusion support.
- Respiratory Disorders:Acute respiratory failure management deploys veno-venous ECMO as lung-protective ventilation adjunct.
Cardiac surgery dominates absolute procedure volume; organ transplant is climbing the fastest as preservation technology extends donor organ utilization.
End User:
Procurement authority and total cost of ownership calculations diverge sharply between integrated health systems and standalone surgical facilities.
- Hospitals:Tertiary medical centers with dedicated cardiac surgery suites command capital budgets for integrated perfusion platforms. German and Dutch purchasing cooperatives are unbundling service contracts from initial equipment purchases, forcing competitive rebidding on multi-year maintenance agreements.
- Ambulatory Surgical Centers:Limited-service facilities concentrate on diagnostic catheterization and minor interventional procedures with minimal perfusion support requirements.
- Specialty Clinics:Cardiovascular-focused outpatient settings deploy portable ECMO for inter-hospital transport stabilization.
- Research Institutions:Academic medical centers pilot normothermic perfusion protocols for expanded criteria donor organs.
Hospitals capture the dominant installed base; specialty clinics are gaining share fastest as ambulatory ECMO miniaturization enables field deployment.
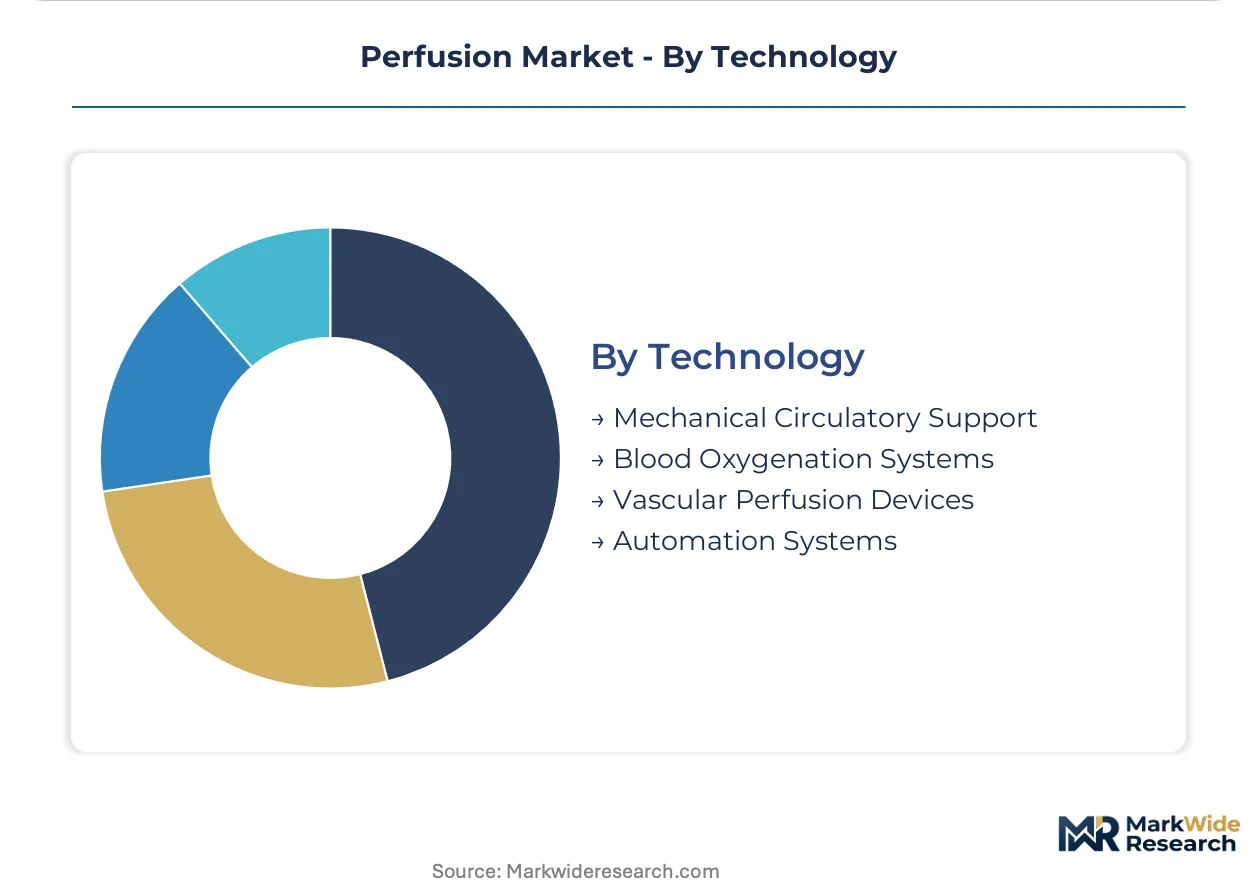
Technology:
Automation maturity and regulatory qualification burden segment technologies into established mechanical platforms versus sensor-integrated smart systems.
- Mechanical Circulatory Support:Centrifugal and roller pump mechanisms provide foundational blood propulsion with established biocompatibility profiles. FDA PMA pathways for breakthrough device designation are compressing review timelines for next-generation pump designs that demonstrate substantial advantage over predicate devices.
- Blood Oxygenation Systems:Hollow-fiber membrane oxygenators with integrated pressure sensors and real-time clot detection algorithms are displacing conventional designs. These platforms reduce perfusionist training requirements while elevating capital specifications at high-complexity centers.
- Vascular Perfusion Devices:Regional perfusion catheters deliver chemotherapeutic agents or organ preservation solutions to isolated vascular beds.
- Automation Systems:Cloud-connected platforms with predictive maintenance capabilities enable subscription revenue models decoupled from hardware replacement cycles.
Blood oxygenation systems command the steepest expansion trajectory as sensor integration replaces manual surveillance; mechanical circulatory support retains the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cardiac surgery volumes and regulatory pathways diverge sharply across major markets, with the United States prioritizing breakthrough device acceleration while Germany and Japan emphasize integrated service networks and super-aging procedural demand respectively.
United States
Tertiary hospitals in Cleveland, Houston, and New York Metro are expanding hybrid cardiac suites that combine surgical perfusion with interventional catheterization capabilities. The FDA's breakthrough device designation pathway compresses review timelines for novel oxygenation membranes and automated pump controls. Major transplant centers in Pittsburgh and San Francisco are converting from static cold storage to normothermic machine perfusion for extended donor organ utilization.
Germany
German hospital systems in Bavaria and North Rhine-Westphalia are consolidating procurement around integrated perfusion platforms with unbundled multi-year service contracts. The EU MDR accelerated conformity assessment pathway enables faster market entry for next-generation ECMO circuits. Medical technology clusters in Tübingen and Aachen host specialized polymer suppliers controlling medical-grade silicone sheet production for oxygenator fabrication.
Japan
Patients over 75 now comprise the majority of complex cardiac procedures at Tokyo and Osaka medical centers, expanding addressable surgical volumes for heart-lung machines. Japan's PMDA maintains stringent clinical evidence requirements that favor established manufacturers with robust quality management systems. The Kansai region anchors domestic production of centrifugal pump mechanisms with established biocompatibility profiles.
India
Greenfield cardiac institutes in Delhi, Mumbai, and Bangalore are specifying perfusion equipment for first-time open-heart surgery programs as tertiary hospital expansion accelerates. The country's national medical device regulator enforces quality standards that elevate barriers for new entrants while consolidating compliance spending among established manufacturers. Medical device manufacturing clusters in Gujarat and Karnataka are developing component supply capabilities for regional equipment assembly.
United Kingdom
London and Southeast England transplant centers are piloting portable organ care systems for extended criteria donor lungs and hearts. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for post-market surveillance and design controls. Academic medical centers in Cambridge and Oxford are advancing automated feedback loop technologies that replace manual perfusion flow management.
Perfusion Market Competitive Environment
Capability concentration sits with integrated platform specialists; scale advantage sits with diversified medical technology conglomerates. The vendor base organizes into three tiers: full-suite perfusion platform providers, consumables-focused specialists, and emerging normothermic organ preservation innovators. Consolidation pressure favors firms with captive silicone membrane supply relationships and established field engineering networks. Dominant competitive moves include strategic partnerships for biocompatibility validation and geographic expansion into India's tertiary hospital greenfield projects.
Among diversified medical technology conglomerates, Getinge and Medtronic exemplify scale-driven platform integration, while LivaNova PLC occupies a position within the consumables-specialist archetype. Getinge leverages integrated service networks across European hospital systems. Medtronic anchors market presence through deep field engineering presence. LivaNova PLC differentiates through repeat purchase velocity from hardware-installed bases. These three represent distinct strategic postures without implying specific market share positions or financial performance.
| Leading Market Players |
|---|
| Getinge |
| Medtronic |
| LivaNova PLC |
| Terumo Corporation |
| XVIVO Perfusion AB |
| TransMedics |
| Merck KGaA |
| Repligen Corporation |
| Nipro Corporation |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in medical-grade silicone sheet fabrication across German and Japanese polymer plants is elevating supplier pricing power while compressing oxygenator manufacturer margins. This utilization squeeze propagates through contract negotiations, forcing equipment vendors to absorb input cost volatility or renegotiate multi-year hospital service agreements.
Pricing Analysis
Long-term service contracts with embedded consumable minimums dominate hospital procurement, though spot purchases for emergency ECMO circuit replacements command premium pricing. Price differentiation rests on FDA breakthrough device designation tier and field engineering density, with US tertiary hospitals least sensitive due to bundled reimbursement, while Indian greenfield cardiac institutes negotiate aggressively on capital equipment.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts centrifugal pump motor and sensor component flows. Supply concentrates in Germany for silicone membranes, Japan for precision pump mechanisms, and the United States for integrated console assembly. Single-source vulnerability in hollow-fiber membrane spinning equipment amplifies lead time risk. Distribution runs through GPO contracts at integrated US health systems and direct hospital relationships in European purchasing cooperatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preventive maintenance subscriptions and remote monitoring software are expanding faster than hardware replacement cycles, converting capital sales into recurring revenue streams that improve customer lifetime value metrics.
For Market Incumbents: Insulate installed base revenue by captive supply agreements with German silicone membrane producers and predictive maintenance platform deployment. Consolidate field engineering presence in Japanese super-aging markets where perfusionist scarcity elevates automation premium. Defend against normothermic organ preservation entrants by extending service contracts into transplant center workflows. For New Entrants and Emerging Players: Portable ECMO miniaturization for inter-hospital transport in India's expanding tertiary cardiac institutes represents the most penetrable entry point. Target research institution partnerships for normothermic perfusion protocol validation as a regulatory credibility bridge. Pursue white-label manufacturing for established vendors' consumable lines to secure initial revenue and quality management system certification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform vendors with integrated service networks and consumable attach rates. Long-term viability favors acquisition targets with FDA breakthrough device designations in progress and established European MDR quality certifications. Monitor EU MDR notified body capacity constraints as an inflection signal for accelerated market entry opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year service contracts with Cleveland Clinic and Houston Methodist secure installed base loyalty and consumable lock-in. |
| CE Marking Pathway | EU MDR accelerated conformity assessment enables faster German and French market entry for next-generation oxygenation membranes. |
| Software Companion Development | Cloud-connected ECMO platforms with predictive maintenance algorithms convert hardware sales into subscription revenue streams. |
| FDA Submission | Breakthrough device designation compresses review timelines for automated perfusion control systems in cardiac surgery applications. |
| Reimbursement Strategy | CMS coverage determinations for normothermic machine perfusion in lung transplantation expand addressable procedure volumes. |
Study Parameters
Operator-level perspectives from perfusionists, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers anchored the qualitative base. These primary insights combined with FDA PMA and 510(k) filings, EU MDR notified body databases, hospital procurement contract registries, and CMS reimbursement determinations. Bottom-up equipment shipment analysis and top-down cardiac surgery volume estimates provided triangulation discipline.
Scenario-bracketing around silicone membrane supply constraints and perfusionist workforce expansion produced bounded projections across the modeling period. Segmentation dimensions included product type, application workflow, end-user procurement authority, and technology automation maturity. CAGRs derived from installed base replacement cycles and procedure volume elasticity to demographic aging. Forecast inputs incorporated EU MDR transition timelines and FDA breakthrough device review velocity.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure cycles or medical device reimbursement rates would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway stability and supply chain normalization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Vascular Injury Treatment Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Non-Invasive Blood Pressure Monitors Market
Cardiovascular Devices
Surgical and Interventional Cardiology Devices Market
Cardiovascular Devices
Intravenous Catheters Market
Cardiovascular Devices
Cardiovascular Devices Market
Cardiovascular Devices
Vital Sign Simulators Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
MRI-Guided Cardiac Ablation Market
Cardiovascular Devices
Global Critical Limb Ischemia Treatment Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
Vena Cava Clips and Filters Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Iliac Artery Stents Market