
 United States Cardiovascular Devices Market | 2026-2036
United States Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United States Cardiovascular Devices Market Analytics
Interventional cardiologist supply is bifurcating between academic medical centers and community hospital systems, creating uneven access to complex transcatheter procedures. Medtronic leverages its structural heart training infrastructure to sustain physician certification pipelines across the Southeast. Abbott Laboratories anchors catheter-based coronary interventions through integrated imaging and device platforms.
Cardiovascular devices encompass implantable and interventional instruments—stents, pacemakers, catheters, and valves—typically fabricated from nitinol, cobalt-chromium alloys, or biocompatible polymers and designed to restore hemodynamic function or electrical conduction. These devices serve hospitals, cardiology clinics, ambulatory surgical centers, and home care settings where precision and biocompatibility determine clinical outcomes. Transcatheter valve platforms command premium positioning as minimally invasive alternatives to open-heart surgery, while robotic-assisted surgical systems represent the fastest-growing technology segment driven by reimbursement alignment and outcomes data. Pacemaker systems remain a mature margin pool with replacement cycles and leadless innovations sustaining manufacturer economics.
FDA premarket notification and breakthrough device designation pathways shape product development timelines and market access for novel cardiovascular technologies in the United States. CMS national coverage determinations and hospital outpatient prospective payment system updates directly influence site-of-service economics and device adoption curves. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled diagnostic adjuncts and CMS technology add-on payment decisions for robotic platforms.
Market Dynamics
Transcatheter structural heart procedures are compressing open surgical volumes and redistributing procedure economics toward catheter-based platforms. This shift concentrates capital deployment in hybrid operating suites and physician training infrastructure.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated premarket review timelines compress commercialization cycles for transcatheter mitral valve repair systems. Ambulatory surgical centers in Texas and Florida expand procedure capacity under this pathway.
- Leadless Pacemaker Technology:Elimination of transvenous leads reduces long-term complication burden and replacement cycle risks. Cardiac electrophysiology labs in academic medical centers drive adoption curves.
- Aging Demographics in Sun Belt States:Concentrated Medicare-eligible populations in Florida and Texas generate procedure volume density that supports dedicated structural heart programs and device inventory commitments.
Market Restraints
- Nitinol and Cobalt-Chromium Alloy Supply Concentration:Specialty metal sourcing depends on limited domestic and European foundry capacity. Input cost volatility constrains margin stability for stent and valve frame manufacturers.
- Physician Certification Bottlenecks:Proctoring requirements and case volume thresholds for transcatheter valve privileges limit addressable operator pool. Academic medical centers control training pipeline access.
- Reimbursement Compression Under Hospital Outpatient Prospective Payment System:CMS rate updates lag device cost inflation for complex catheter-based procedures. Site-of-service economics favor inpatient admission for marginal cases.
Strategic Opportunities
- Home-Based Cardiac Monitoring:Wearable arrhythmia detection and remote patient monitoring platforms extend care continuum beyond clinic walls. Reimbursement codes under Medicare remote physiologic monitoring create revenue streams.
- Artificial Intelligence-Enabled Diagnostic Adjuncts:FDA guidance on machine learning-based coronary CT angiography analysis opens software-as-device pathways. Integrated imaging platforms capture workflow efficiency premiums.
- Ambulatory Surgical Center Expansion:Lower-acuity pacemaker implants and diagnostic catheterizations migrate to freestanding facilities. Certificate-of-need liberalization in select states enables greenfield development.
Industry Challenges
- Interventional Cardiologist Workforce Bifurcation:Complex transcatheter procedures concentrate in academic centers while community hospitals face recruitment gaps. Training program expansion requires protracted fellowship capacity investment.
- Robotic Platform Integration Complexity:CorPath and Magellan systems demand specialized technician staffing and maintenance protocols. Capital intensity and learning curves delay utilization optimization.
- Post-Market Surveillance Data Requirements:FDA mandated real-world evidence collection for transcatheter valves imposes registry participation costs. Long-term durability endpoints extend study timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Cardiovascular Devices Market |
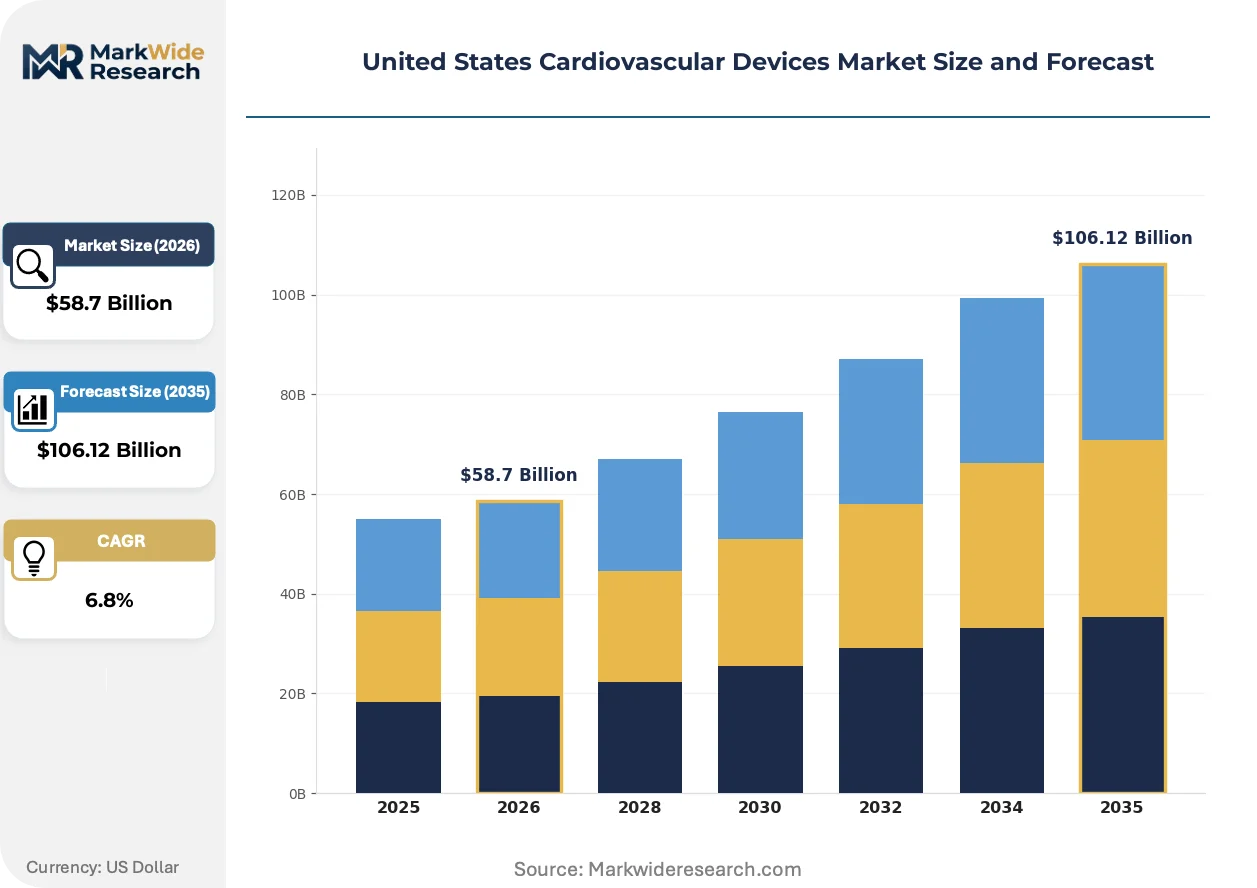
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Catheters, Valves End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Home Care Technology: Minimally Invasive, Implantable, Robotic-Assisted, Transcatheter Application: Coronary Artery Disease, Arrhythmia, Heart Valve Disorders, Peripheral Vascular Disease |
| Companies Covered | Edwards Lifesciences, Cardinal Health, Medtronic, Fresenius Medical Care, Koninklijke Philips, Boston Scientific, Johnson & Johnson, Stryker, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Cardiovascular Devices Market Evolving Landscape
Digital integration and minimally invasive platform advancement are restructuring cardiovascular device value chains. Technology convergence, regulatory pathway evolution, and care site migration define competitive positioning.
Leadless pacemaker systems are displacing traditional transvenous devices in bradyarrhythmia management. Electrophysiology departments at academic medical centers prioritize catheter-based implantation to eliminate lead extraction risks. This transition compresses replacement procedure volumes and shifts inventory requirements toward retrieval-compatible systems.
FDA breakthrough device designation pathways compress premarket approval timelines for transcatheter mitral and tricuspid valve platforms. Structural heart manufacturers align clinical trial endpoints with surrogate measures accepted under this framework. Transcatheter aortic valve replacement programs in high-volume centers expand case selection criteria in response.
Remote cardiac monitoring procurement now favors integrated platform subscriptions over discrete device transactions. Cardiology group practices and integrated delivery networks consolidate vendor relationships around cloud-connected implantable loop recorders and wearable patch systems. This concentration is most visible in Medicare Advantage–dominated markets where capitated contracts incentivize preventive arrhythmia detection.
United States Cardiovascular Devices Market Segmentation
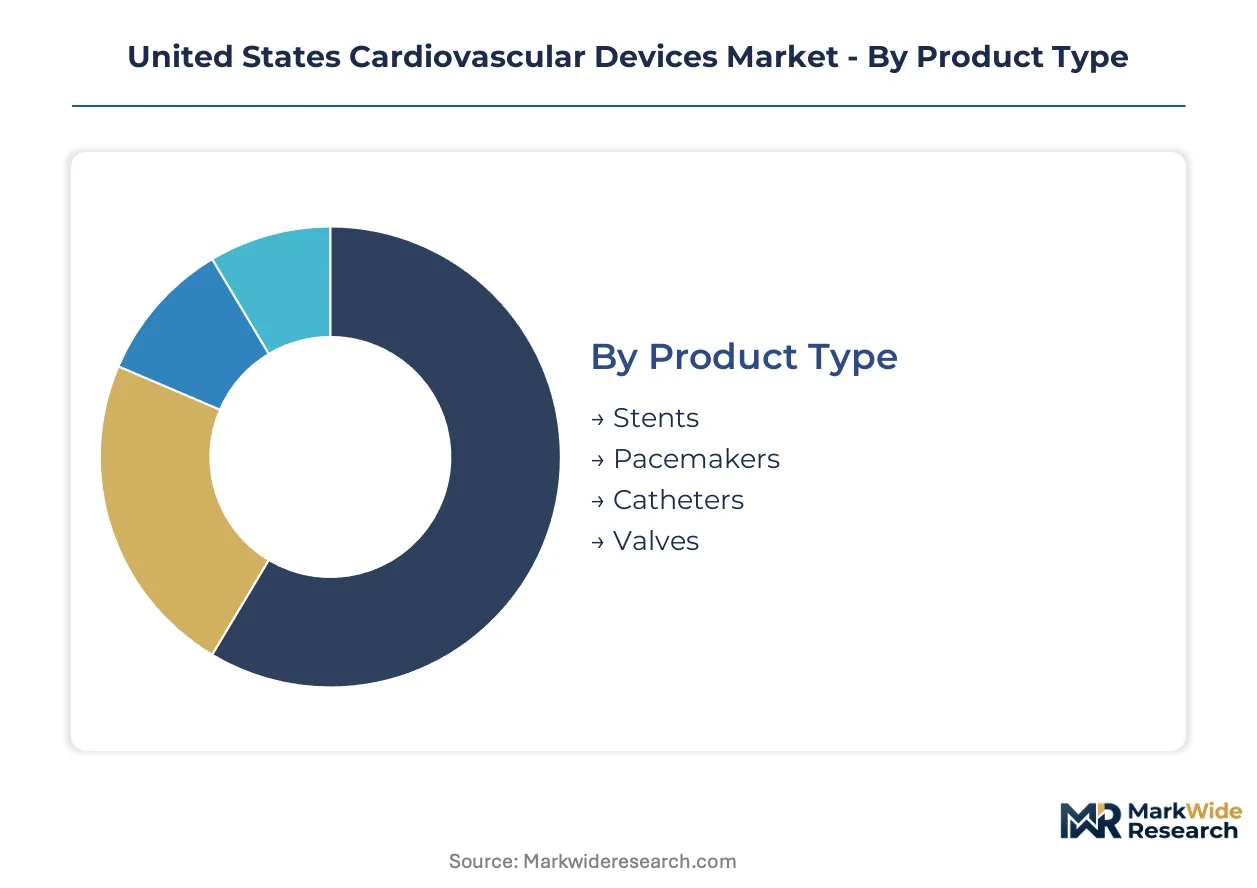
Segmentation reveals how substitution pressures and site-of-service economics redistribute volume across cardiovascular device categories. Structural shifts toward catheter-based platforms and ambulatory settings fragment traditional revenue pools.
Product Type:
Transcatheter platforms exert the strongest substitution pressure on conventional surgical implants, compressing legacy segment economics while elevating premium positioning for minimally invasive alternatives.
- Stents:Drug-eluting and bare-metal coronary stents fabricated from cobalt-chromium alloys or platinum-iridium deliver mechanical revascularization. Demand concentrates in high-volume cardiac catheterization labs across Texas and Florida where procedure density supports inventory depth.
- Valves:Transcatheter aortic and mitral valve replacement systems fabricated from bovine or porcine pericardial tissue mounted on nitinol frames enable minimally invasive structural heart repair. Academic medical centers in the Southeast drive adoption through proctored training pipelines and hybrid operating suite investments.
- Pacemakers:Traditional transvenous and leadless cardiac rhythm management devices restore electrical conduction.
- Catheters:Diagnostic and interventional catheters enable coronary and peripheral vascular access.
Stents retain volume leadership; valves hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive inpatient settings from lean ambulatory facilities, with reimbursement differentials determining site migration velocity.
- Hospitals:Academic medical centers and community hospital systems anchor complex structural heart programs requiring hybrid operating suites and 24-hour surgical backup. Medicare reimbursement under the hospital outpatient prospective payment system shapes device selection for marginal cases.
- Ambulatory Surgical Centers:Freestanding facilities in certificate-of-need liberalized states capture lower-acuity pacemaker implants and diagnostic catheterizations. Texas and Florida certificate-of-need reforms enable greenfield ASC development concentrated in Medicare Advantage–dominated markets.
- Cardiology Clinics:Office-based labs and physician-owned facilities perform diagnostic procedures and device surveillance.
- Home Care:Remote patient monitoring and wearable arrhythmia detection extend post-implant surveillance beyond clinical settings.
Hospitals retain volume leadership; ambulatory surgical centers hold the steepest expansion curve.
Technology:
Application maturity separates established implantable platforms from emerging robotic and transcatheter modalities competing for capital allocation.
- Transcatheter:Catheter-delivered valve repair and replacement systems eliminate sternotomy requirements. Structural heart programs at Cleveland Clinic, Mayo Clinic, and Texas Heart Institute drive case volume concentration through proctoring networks and FDA breakthrough device trial participation.
- Robotic-Assisted:CorPath and Magellan platforms enable precision coronary and peripheral interventions with reduced radiation exposure. Reimbursement alignment under CMS technology add-on payment decisions accelerates capital deployment in high-volume centers.
- Minimally Invasive:Thoracoscopic and percutaneous approaches reduce tissue trauma versus open surgery.
- Implantable:Conventional pacemakers, defibrillators, and loop recorders provide long-term rhythm management.
Implantable technology retains volume leadership; robotic-assisted platforms hold the steepest expansion curve.
Application:
Geographic demand concentration aligns with aging Medicare-eligible populations and cardiac center density, privileging Sun Belt states with procedure volume.
- Coronary Artery Disease:Percutaneous coronary intervention with stent deployment addresses atherosclerotic obstruction. Florida and Texas generate concentrated revascularization volume through Medicare Advantage penetration and cardiology group practice consolidation.
- Heart Valve Disorders:Transcatheter and surgical valve replacement treats degenerative and congenital valvular disease. Structural heart program density in the Southeast creates referral pattern concentration from rural catchment areas.
- Arrhythmia:Catheter ablation and cardiac rhythm management devices manage atrial fibrillation and bradyarrhythmias.
- Peripheral Vascular Disease:Endovascular and surgical interventions address lower-extremity arterial disease.
Coronary artery disease applications retain volume leadership; heart valve disorder treatments hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
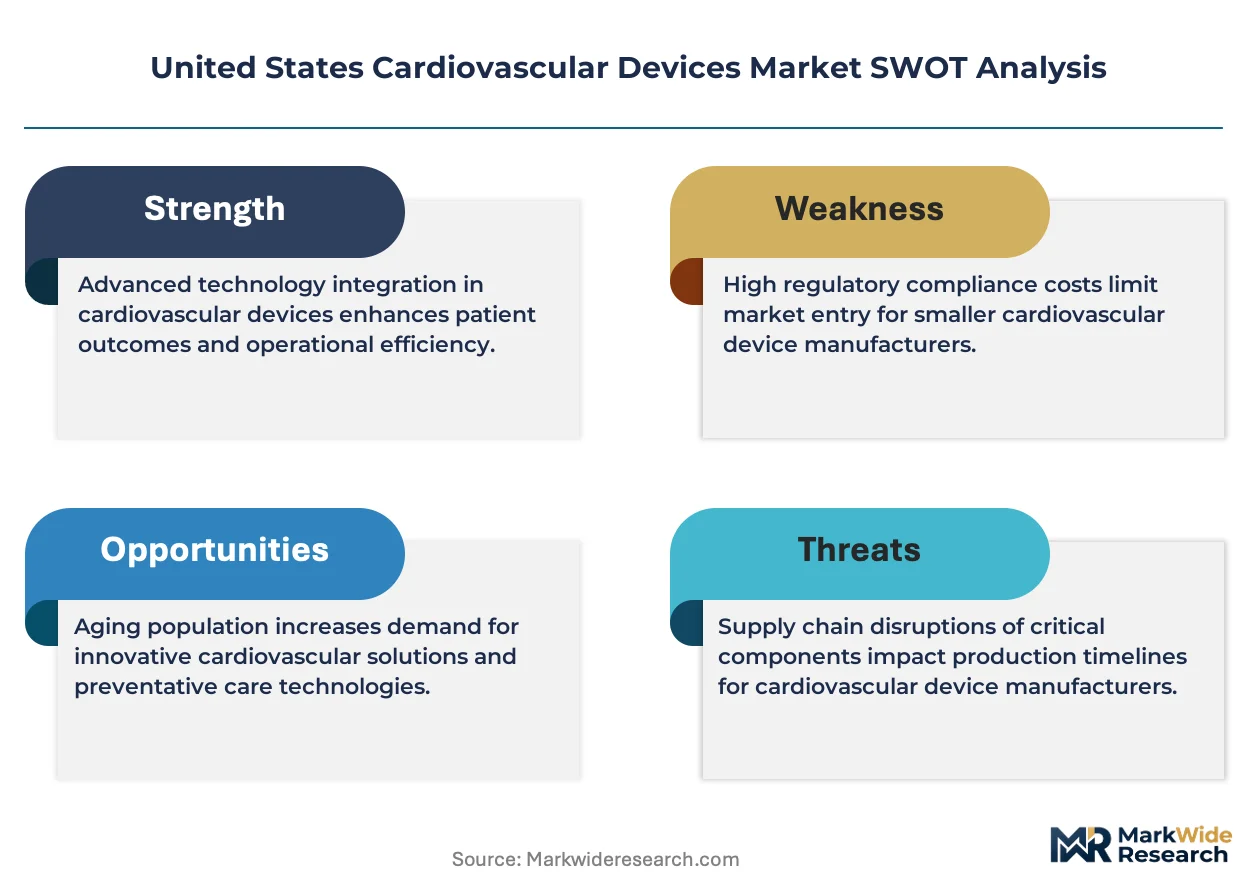
FDA regulatory frameworks anchor device commercialization across the United States, with Medicare reimbursement policies and state-level certificate-of-need regulations shaping regional deployment patterns for cardiovascular technologies.
Southeast
Florida and Georgia concentrate Medicare-eligible populations and cardiac center density that drives structural heart procedure volume. CMS hospital outpatient prospective payment system updates influence site-of-service economics for transcatheter valve programs. The Texas Medical Center in Houston and Tampa General Hospital anchor hybrid operating suite investments and physician training pipelines.
Southwest
Texas generates concentrated demand through aging demographics and cardiology group practice consolidation in Medicare Advantage markets. FDA breakthrough device designation pathways accelerate commercialization timelines for regional academic medical centers. Dallas-Fort Worth and San Antonio metropolitan areas support dedicated structural heart programs with inventory commitments for transcatheter platforms.
Northeast
Massachusetts and New York maintain dense concentrations of academic medical centers with proctored training infrastructure for complex catheter-based procedures. CMS technology add-on payment decisions shape capital deployment for robotic-assisted platforms. The Cleveland Clinic and Mayo Clinic referral networks extend into Boston and New York City catchment areas.
West Coast
California's integrated delivery networks consolidate vendor relationships around remote patient monitoring platforms in capitated Medicare Advantage contracts. FDA guidance on artificial intelligence-enabled diagnostic adjuncts influences software-as-device development in Silicon Valley cardiology technology clusters. Stanford and Cedars-Sinai anchor electrophysiology lab expansion for leadless pacemaker adoption.
Midwest
Illinois and Ohio retain volume leadership in conventional coronary interventions through established cardiac catheterization lab networks. Hospital outpatient prospective payment system rate compression delays site migration for marginal cases. The Cleveland Clinic main campus and Chicago-area health systems maintain hybrid operating suite investments for transcatheter valve programs.
United States Cardiovascular Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning in transcatheter platforms coexists with scale-driven supply chain efficiency. The market consolidates around diversified medical technology conglomerates with integrated imaging and device portfolios, while specialized structural heart players occupy premium niches. Two strategic archetypes dominate: diversified conglomerates with full cardiovascular portfolios, and focused structural heart specialists with breakthrough device pipelines. Competitive moves concentrate on strategic partnerships for training infrastructure and portfolio diversification into remote monitoring platforms.
Among diversified medical technology conglomerates, Edwards Lifesciences, Medtronic, and Abbott Laboratories exemplify the integrated platform archetype. Edwards Lifesciences occupies a position representing transcatheter valve specialization, Medtronic anchors the diversified cardiovascular portfolio with structural heart training infrastructure, and Abbott Laboratories sits within the catheter-based coronary intervention tier with integrated imaging alignment.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| Cardinal Health |
| Medtronic |
| Fresenius Medical Care |
| Koninklijke Philips |
| Boston Scientific |
| Johnson & Johnson |
| Stryker |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
FDA breakthrough device designation pathways gate both supply qualification and price differentiation for cardiovascular device manufacturers seeking premium positioning. CMS reimbursement tiers separate transcatheter valve platforms from conventional surgical implants, creating parallel qualification requirements that manufacturers must satisfy simultaneously.
Pricing Analysis
Price spreads between academic medical centers in Texas and community hospitals in the Midwest exceed 15% for identical transcatheter valve systems. Three-tier pricing structure across premium, standard, and economy levels tracks FDA approval pathway complexity and training infrastructure investment. Pricing pressure stems from CMS hospital outpatient prospective payment system rate compression that lags device cost inflation. Community hospital systems exhibit highest price sensitivity due to thinner procedure margins, while academic medical centers prioritize clinical outcomes over unit cost.
Supply Chain Analysis
Strategic stockpiling of nitinol and cobalt-chromium alloys dominates inventory strategy as foundry capacity constraints extend lead times for stent and valve frame manufacturers. Supply concentrates in domestic specialty metal foundries and German precision alloy producers, with limited alternative sourcing for medical-grade nitinol. Raw material dependencies include bovine pericardial tissue for bioprosthetic valves, platinum-iridium for electrode components, and biocompatible polymers for catheter sheaths. Single-source vulnerability in nitinol supply creates exposure to foundry disruption or export restriction. Distribution runs through GPO contracts with integrated delivery networks and direct hospital procurement for high-value structural heart platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cardiovascular device manufacturers face sustained substitution pressure from catheter-based platforms compressing open surgical volumes. Transcatheter valve systems threaten legacy surgical implant economics while creating premium capture opportunities for trained operators.
For Market Incumbents: Fortify structural heart training infrastructure to sustain physician certification pipelines against emerging competitors. Expand proctored program capacity at Texas Heart Institute and Cleveland Clinic referral networks. Deepen backward integration into nitinol foundry relationships to secure alloy supply against single-source vulnerability. Prioritize FDA breakthrough device designation pursuit for next-generation transcatheter mitral platforms. For New Entrants and Emerging Players: Anchor in ambulatory surgical center expansion corridors in certificate-of-need liberalized states, particularly Florida and Texas Medicare Advantage markets. Target leadless pacemaker retrieval-compatible systems where inventory requirements shift and established players lack entrenched positions. Pursue cloud-connected remote monitoring platforms under Medicare remote physiologic monitoring reimbursement codes. Leverage integrated platform subscription models over discrete device transactions to displace incumbent vendor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across robotic-assisted surgical platforms as CMS technology add-on payment decisions accelerate capital deployment requirements. Long-term viability favors manufacturers with FDA breakthrough device pipelines and established proctoring networks over pure-play stent commoditizers. Target acquisition archetypes include structural heart specialists with transcatheter tricuspid repair programs and AI-enabled diagnostic adjunct developers with FDA software-as-device pathways. Watch for inflection when ambulatory surgical center certificate-of-need liberalization spreads beyond current state boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated premarket review compresses commercialization timelines for transcatheter mitral platforms. |
| Hospital System Partnership | Integrated delivery network contracts secure volume commitments and displace competing vendor relationships. |
| Software Companion Development | AI-enabled coronary CT angiography analysis captures workflow efficiency premiums under FDA guidance. |
| Reimbursement Strategy | Medicare remote physiologic monitoring codes create recurring revenue streams for wearable arrhythmia detection. |
| CE Marking Pathway | European regulatory alignment enables dual-market manufacturing scale and supply chain flexibility. |
Research Methodology
Initial hypotheses were tested against primary input from interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers and refined through secondary validation. Primary research encompassed structured interviews with structural heart program directors at academic medical centers and community hospital systems across Texas, Florida, and the Midwest. Secondary sources included FDA premarket approval filings, CMS national coverage determinations, hospital procurement databases, and GPO contract disclosures. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects and segment-migration impacts. The analytical framework models product type, end user site-of-service, technology modality, and application disease state as core segmentation dimensions. CAGRs derive from procedure volume elasticity to aging demographics, reimbursement rate trajectories, and technology substitution curves. Industry-specific forecast inputs incorporate FDA breakthrough device approval timelines and CMS hospital outpatient prospective payment system update schedules.
Material uncertainties — regulatory pathway delays, alloy supply disruption, and physician certification bottlenecks — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement stability and training pipeline expansion that may require reassessment. Revision becomes warranted when transcatheter procedure volume growth decelerates below structural heart program capacity addition rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Cardiovascular Disease Monitoring and Diagnostic Devices Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Global Cardiac Arrest Treatment Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
UAE Cardiovascular Devices Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Epinephrine Auto-Injectors Market
Cardiovascular Devices
Surgical Heart Valves Market
Cardiovascular Devices
Cardiac Ablation Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Chile Cardiovascular Devices Market
Cardiovascular Devices
Congestive Heart Failure Treatment Devices Market
Cardiovascular Devices
Global Nitinol-Based Medical Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Bioresorbable Coronary Stents Market