
 Global Atrial Fibrillation Surgery Market | 2026-2036
Global Atrial Fibrillation Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Atrial Fibrillation Surgery Market Foresight
Biocompatible polymer composites are hardening catheter construction economics as manufacturers reduce dependence on legacy metal electrode assemblies. Medtronic plc leverages integrated manufacturing across its electrophysiology portfolio to sustain cost advantages in radiofrequency systems. Abbott Laboratories anchors its position through cryoablation platform specialization, while Boston Scientific Corporation competes on balloon-based thermal technology leadership.
Atrial fibrillation surgery encompasses minimally invasive and open-chest procedures designed to disrupt aberrant electrical pathways within cardiac tissue, typically employing thermal or cryogenic energy delivery at temperatures ranging from minus eighty degrees Celsius to sixty degrees Celsius to achieve transmural lesion formation. These interventions restore sinus rhythm and reduce stroke risk in patients refractory to pharmacological management. Catheter ablation dominates procedure volume due to shorter recovery profiles, though hybrid ablation captures premium margins by combining surgical and percutaneous approaches in complex persistent cases. Radiofrequency technology leads installed base metrics, while cryoablation segments expand fastest among electrophysiology labs seeking simplified single-shot pulmonary vein isolation workflows.
FDA premarket notification pathways and EU MDR conformity requirements shape device commercialization timelines and clinical evidence standards for ablation catheter manufacturers. Japan's PMDA and China's NMPA impose additional localization testing that filters market access for non-dominant entrants. Stakeholders must monitor reimbursement parity between catheter-based and surgical maze procedures across Medicare, NHS England, and German statutory health insurance frameworks.
Market Dynamics
Catheter ablation is compressing open surgical volumes as electrophysiology labs in Germany, Japan, and the United States standardize minimally invasive workflows for pulmonary vein isolation.
Growth Catalysts
- Cryoablation Platform Simplification:Single-shot balloon designs reduce procedure time and operator learning curves in busy cardiac centers across the United States.
- FDA Premarket Pathway Acceleration:Streamlined 510(k) clearances for next-generation mapping catheters compress commercialization timelines for novel electrode geometries.
- Hybrid Operating Suite Investment:Integrated surgical-EP environments in German university hospitals enable same-day combined thoracoscopic and percutaneous ablation.
Market Restraints
- Platinum-Iridium Electrode Cost Volatility:Precious metal price swings squeeze gross margins on radiofrequency catheter assemblies sourced through concentrated South African refiners.
- PMDA Localization Testing Burden:Japan's mandatory domestic clinical trials extend time-to-market by eighteen to twenty-four months for non-dominant device entrants.
- Pharmacological Rhythm Control:Direct oral anticoagulants and antiarrhythmic drugs retain first-line status in elderly comorbid populations, capping procedural referral pools.
Strategic Opportunities
- Robotic Navigation Integration:Magnetic and impedance-guided catheter steering systems converge with AI-powered mapping to enable remote EP procedure execution.
- NMPA Green Channel Designation:China's priority review pathway for innovative cardiovascular devices offers accelerated market access for cryoablation platforms with domestic trial data.
- Outpatient Ambulatory Surgery Centers:Same-day discharge protocols in United States freestanding cardiac facilities capture Medicare reimbursement advantages over hospital-based EP labs.
Industry Challenges
- Electrophysiologist Training Pipeline:Fellowship slot constraints in North American academic medical centers create twelve-to-eighteen-month hiring delays for expanding EP service lines.
- EU MDR Technical Documentation:Expanded clinical evidence requirements for legacy ablation catheters force retrospective data collection and notified body recertification sprints.
- Hospital Capital Budget Cycles:Three-dimensional mapping system procurement freezes during fiscal consolidation periods stall installed base expansion in mid-tier cardiac centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Atrial Fibrillation Surgery Market |
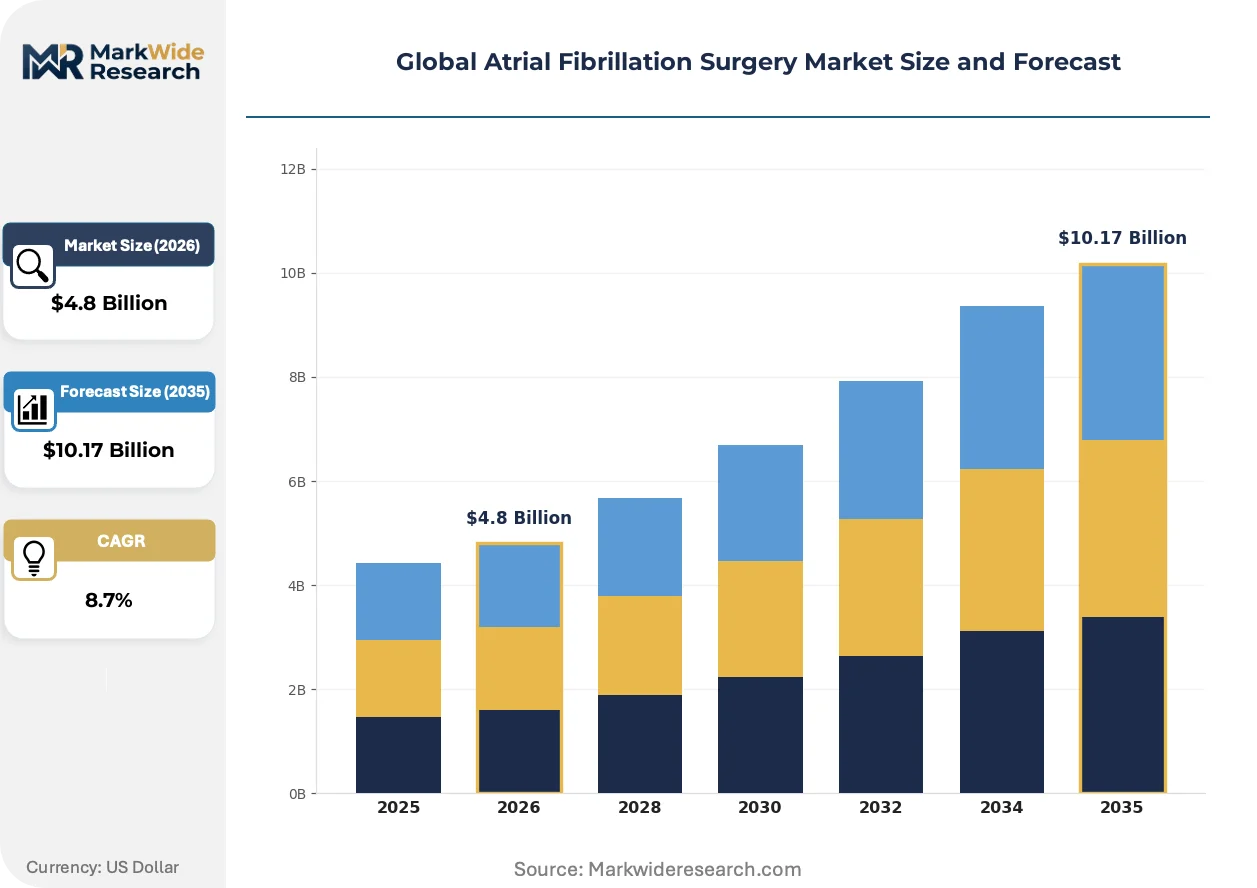
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Cox Maze, Catheter Ablation, Pulmonary Vein Isolation, Hybrid Ablation Technology: Radiofrequency, Cryoablation, Laser Ablation, Ultrasound Ablation Application: Paroxysmal Arrhythmia, Persistent Arrhythmia, Long-standing Persistent Arrhythmia, Postoperative Arrhythmia End User: Cardiac Surgery Centers, Electrophysiology Labs, Specialty Clinics, Ambulatory Surgical Centers |
| Companies Covered | Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, Johnson & Johnson, AtriCure, Inc., Biosense Webster, Inc., Biotronik SE & Co. KG, CardioFocus, Inc., Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Atrial Fibrillation Surgery Market Shifts & Advancements
Pulsed field ablation and contact-force sensing technologies are restructuring competitive positioning in cardiac electrophysiology, while reimbursement parity debates between catheter and surgical approaches intensify across national health systems.
Contact-force sensing radiofrequency catheters is overtaking conventional non-sensed designs in high-volume United States electrophysiology labs. Academic medical centers in Boston and Cleveland now mandate force-feedback integration for complex atrial flutter cases. This capability compression is eliminating price-competitive undifferentiated catheter suppliers from tier-one hospital tenders.
EU MDR clinical evidence requirements are extending post-market surveillance obligations for cryoablation balloon systems marketed in Germany, France, and the Netherlands. Manufacturers must now submit annual safety updates and real-world performance data to maintain CE marking. German statutory health insurers are conditioning DRG reimbursement uplifts on documented MDR compliance certificates.
Site-of-service migration toward ambulatory surgical centers is disrupting traditional hospital-based EP lab economics in the United States. Medicare's HOPPS rate cuts for hospital outpatient departments are redirecting catheter ablation volume to freestanding facilities in Florida, Texas, and Arizona. Cardiovascular service line directors now prioritize capital-light lease arrangements over seven-figure mapping system purchases.
Global Atrial Fibrillation Surgery Market Segmentation
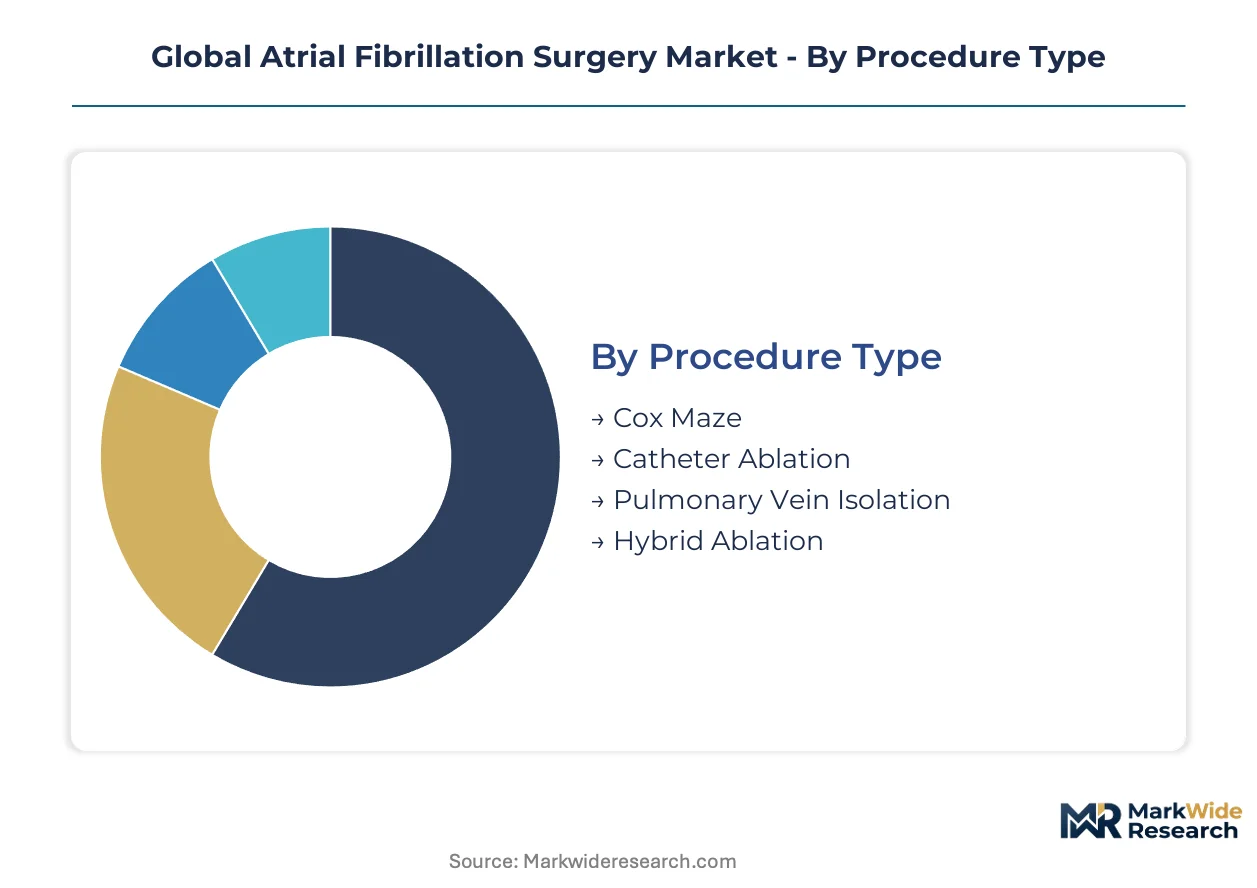
Segmentation in atrial fibrillation surgery reveals how procedure economics, technology platforms, and care delivery settings stratify patient access and manufacturer positioning. Understanding these divides clarifies where capital deployment, regulatory investment, and clinical training resources generate differentiated returns.
Procedure Type:
Standalone open-chest procedures occupy a shrinking installed base while catheter-based and hybrid workflows embed into integrated electrophysiology service lines.
- Catheter Ablation:Percutaneous energy delivery through femoral venous access creates transmural lesions without thoracotomy. Demand clusters in United States electrophysiology labs where same-day discharge protocols maximize Medicare reimbursement efficiency.
- Hybrid Ablation:Combined thoracoscopic surgical and catheter-based ablation targets complex persistent atrial fibrillation through convergent lesion sets. German university hospitals pioneered integrated operating suite investments that enable single-anesthesia combined procedures.
- Cox Maze:The cut-and-sew biatrial lesion pattern remains the gold standard for lesion durability in concomitant cardiac surgery. Standalone volumes have compressed as minimally invasive alternatives capture symptomatic patients without structural heart disease.
- Pulmonary Vein Isolation:Anatomically focused lesion sets encircling pulmonary vein ostia form the foundational strategy for paroxysmal atrial fibrillation. This procedure anchors training curricula and technology development across catheter platforms.
Volume placements concentrate in Catheter Ablation; the faster expansion belongs to Hybrid Ablation.
Technology:
Cost tiers separate capital-intensive platform technologies from disposable catheter systems with lower upfront infrastructure requirements.
- Radiofrequency:Resistive heating through platinum-iridium electrodes achieves transmural temperatures of 50-60°C with precise lesion depth control. Contact-force sensing variants now dominate tenders at Cleveland Clinic, Mayo Clinic, and Massachusetts General Hospital.
- Cryoablation:Nitrous oxide or argon-based balloon systems deliver minus 80°C thermal injury through compliant single-shot designs. Simplified pulmonary vein isolation workflows accelerate adoption in high-volume United States community hospital labs.
- Laser Ablation:Photocoagulation through fiberoptic delivery enables direct visualized lesion creation during thoracoscopic surgery. Surgical volumes remain constrained by capital equipment costs and specialized training requirements.
- Ultrasound Ablation:High-intensity focused acoustic energy generates thermal lesions without direct tissue contact. Limited commercial penetration reflects technical complexity and competition from established thermal modalities.
Radiofrequency maintains the broadest installed base; Cryoablation is climbing the fastest as single-shot designs reduce procedure variability.
Application:
Clinical presentation severity drives technology selection and reimbursement intensity across arrhythmia phenotypes.
- Paroxysmal Arrhythmia:Self-terminating episodes within seven days respond favorably to isolated pulmonary vein isolation. Catheter ablation in ambulatory settings captures this population before progression to persistent forms.
- Persistent Arrhythmia:Sustained episodes requiring electrical or pharmacological cardioversion demand extended lesion sets beyond pulmonary vein isolation. Hybrid approaches gain traction as first-line catheter failure rates rise with arrhythmia duration.
- Long-standing Persistent Arrhythmia:Continuous atrial fibrillation exceeding twelve months exhibits structural remodeling that compromises simple isolation strategies. Surgical maze or hybrid procedures dominate this refractory segment.
- Postoperative Arrhythmia:De novo atrial fibrillation following cardiac surgery presents distinct pathophysiology amenable to prophylactic ablation protocols. Cleveland Clinic and German centers have standardized intraoperative prophylactic approaches.
Paroxysmal Arrhythmia generates the highest procedure counts; Long-standing Persistent Arrhythmia shows the steepest expansion trajectory as hybrid platforms mature.
End User:
Customer type stratification reflects capital intensity, reimbursement model, and procedural volume thresholds.
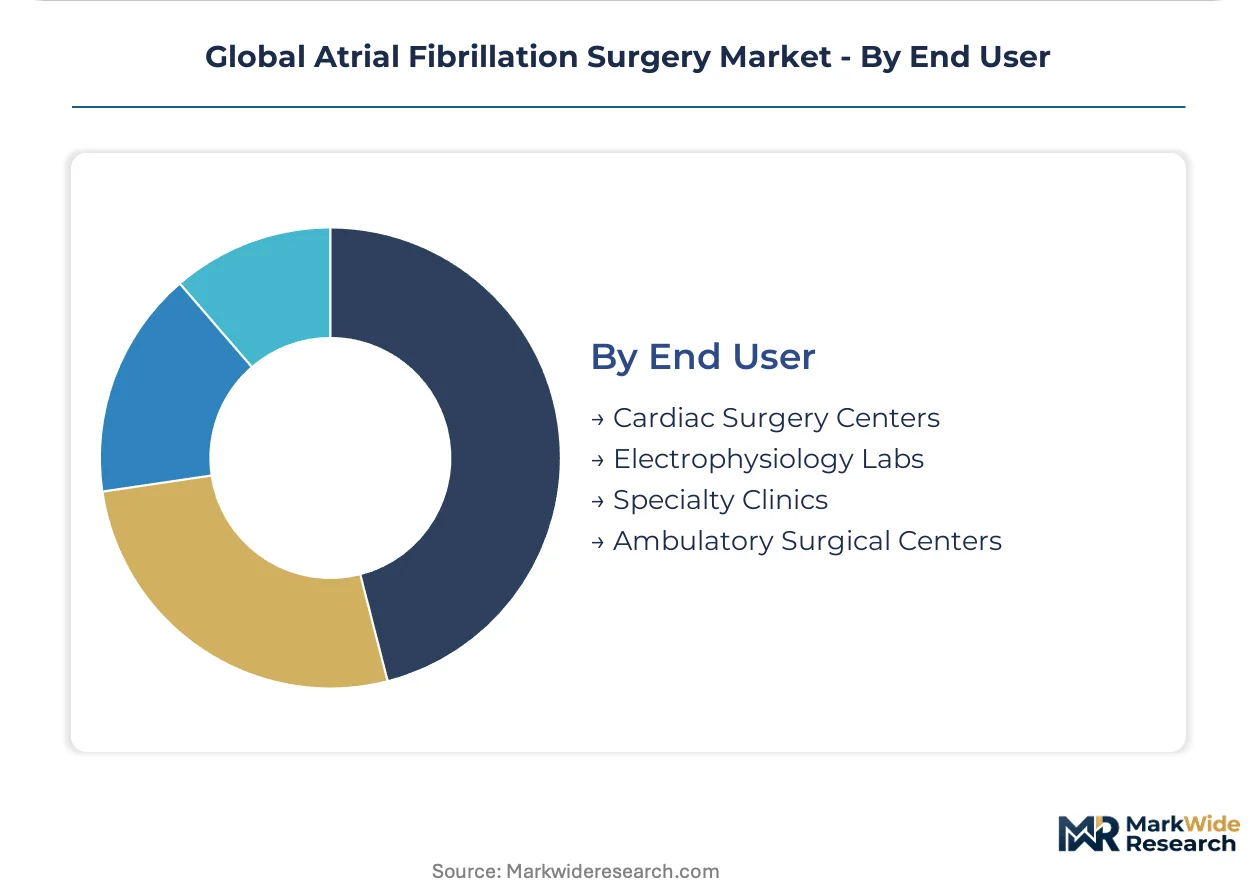
- Electrophysiology Labs:Hospital-based catheterization suites equipped with three-dimensional mapping systems and multiple energy platforms. United States academic medical centers anchor this segment with fellowship-trained operator density.
- Cardiac Surgery Centers:Institutions maintaining cardiothoracic surgery programs capable of open-chest maze and thoracoscopic hybrid procedures. German statutory health insurance frameworks reward these centers with procedure-specific DRG uplifts.
- Ambulatory Surgical Centers:Freestanding facilities exploiting Medicare site-of-service differentials for same-day catheter ablation. Florida, Texas, and Arizona have seen rapid facility proliferation.
- Specialty Clinics:Office-based practices focused on diagnostic electrophysiology and device management with limited ablation capabilities. These settings refer complex cases to hospital-based labs.
Volume concentrates in Electrophysiology Labs; Ambulatory Surgical Centers are gaining share fastest as Medicare payment differentials redirect site-of-service economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophysiology lab density concentrates procedure volume in the United States, Germany, and Japan, where reimbursement frameworks and specialist training pipelines sustain minimally invasive adoption. Regulatory divergence across FDA, EU MDR, and PMDA pathways fragments commercialization timelines for catheter platform manufacturers.
United States
Medicare site-of-service payment differentials redirect catheter ablation volume toward freestanding ambulatory surgical centers in Florida, Texas, and Arizona. FDA 510(k) clearance pathways for next-generation mapping catheters compress time-to-market for novel electrode geometries. Cleveland Clinic and Mayo Clinic anchor high-volume electrophysiology networks where contact-force sensing mandates now dominate equipment tenders.
Germany
Statutory health insurance DRG frameworks reward cardiac surgery centers with procedure-specific uplifts for hybrid ablation workflows. EU MDR conformity requirements extend post-market surveillance obligations for cryoablation balloon systems marketed across German university hospitals. The Rhine-Ruhr and Bavarian medical clusters concentrate integrated operating suite investments enabling same-day thoracoscopic-percutaneous combined procedures.
Japan
PMDA-mandated domestic clinical trials extend regulatory timelines by eighteen to twenty-four months for non-dominant catheter entrants seeking market access. Aging demographics and atrial fibrillation prevalence sustain electrophysiology lab expansion in Tokyo and Osaka academic medical centers. METI industrial policy supports localization partnerships that filter foreign device manufacturer penetration.
China
NMPA green channel designation for innovative cardiovascular devices offers accelerated review for cryoablation platforms submitting domestic trial data. Provincial hospital procurement reforms in Jiangsu and Guangdong prioritize cost-competitive radiofrequency catheter tenders over premium imported systems. The Yangtze River Delta concentrates catheter manufacturing joint ventures serving both domestic demand and export markets.
United Kingdom
NHS England reimbursement parity debates between catheter-based and surgical maze procedures condition capital investment decisions across cardiac centers. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements extends recertification burdens for legacy ablation catheter suppliers. The Greater London and Manchester health clusters drive ambulatory service line reconfigurations toward same-day discharge protocols.
Global Atrial Fibrillation Surgery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated electrophysiology platform vendors commanding premium positions in high-volume academic medical centers while regional catheter suppliers compete on price in mid-tier community hospitals. Market structure tilts toward consolidated leadership among diversified cardiovascular device conglomerates with mapping system-catheter bundled offerings. Three archetypes dominate: full-platform integrators with proprietary navigation ecosystems, cryoablation specialists with single-shot balloon specialization, and radiofrequency catheter manufacturers with contact-force sensing differentiation. Competitive moves center on hybrid operating suite partnerships with German university hospitals and outpatient ambulatory surgery center lease arrangements capturing Medicare site-of-service economics.
Among diversified cardiovascular conglomerates, Medtronic plc, Abbott Laboratories, and Boston Scientific Corporation anchor the premium-tier vendor landscape. Medtronic represents the integrated manufacturing archetype with electrophysiology portfolio breadth spanning mapping systems through energy delivery. Abbott exemplifies cryoablation platform specialization that has simplified pulmonary vein isolation workflows for high-volume United States community labs. Boston Scientific occupies a position defined by balloon-based thermal technology leadership competing for catheter ablation market expansion. These three entities collectively shape procurement standards and clinical training curricula across major electrophysiology service lines.
| Leading Market Players |
|---|
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| Johnson & Johnson |
| AtriCure, Inc. |
| Biosense Webster, Inc. |
| Biotronik SE & Co. KG |
| CardioFocus, Inc. |
| Acutus Medical |
| Others |
Supply & Pricing Matrix
EU MDR clinical evidence requirements for legacy catheter recertification gate qualified supply access and anchor premium-tier pricing for compliant manufacturers serving German and French electrophysiology networks.
Pricing Analysis
Volume concentrates in standard radiofrequency catheter tenders while margins concentrate in contact-force sensing and cryoablation balloon platforms. Three-tier pricing structure across premium, standard, and economy levels separates force-sensed navigation systems from conventional electrode designs from commodity unipolar catheters. Pricing pressure stems from platinum-iridium electrode cost volatility and concentrated South African refiner dependence. Community hospital labs in the United States exhibit highest price sensitivity; academic medical centers in Boston and Cleveland demonstrate lowest sensitivity due to outcome-based procurement mandates.
Supply Chain Analysis
Japan's METI localization partnerships and China's NMPA domestic trial requirements are reshaping sourcing strategies for catheter manufacturers seeking Asia-Pacific market access. Manufacturing concentrates in Costa Rica, Ireland, and Malaysia for sterilized disposable assemblies. Platinum-iridium electrode supply draws from South African refiners; nitrous oxide cryogen supply hinges on industrial gas specialists in Germany and the United States. Single-source vulnerability in precious metal electrode supply creates margin compression risk. Distribution runs through GPO contracts at integrated delivery networks and direct tenders at independent cardiac surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR technical documentation burdens create a barrier-to-entry moat for catheter manufacturers with established notified body relationships and retrospective clinical data libraries.
For Market Incumbents: Deploy backward integration into platinum-iridium electrode supply to buffer South African refiner concentration risk and stabilize gross margins on radiofrequency catheter assemblies. Consolidate hybrid operating suite partnerships with German university hospitals before competitors capture integrated surgical-EP workflow standards. Pulsed field ablation entrants threaten radiofrequency installed base erosion in high-volume United States labs.
For New Entrants and Emerging Players: Ambulatory surgical centers in Florida, Texas, and Arizona represent the most penetrable buyer archetype for capital-light cryoablation platform lease arrangements exploiting Medicare site-of-service differentials. Same-day discharge protocols in freestanding cardiac facilities lack incumbent mapping system lock-in. Target GPO contract participation with regional cardiovascular service line consolidators rather than academic medical center direct tenders.
For Investors and Strategic Acquirers: FDA 510(k) clearance acceleration for next-generation mapping catheters is the leading indicator that robotic navigation integration and AI-powered lesion mapping are approaching commercial inflection. Five-to-ten year viability favors diversified cardiovascular conglomerates with bundled mapping system-catheter offerings over standalone disposable suppliers. Watch for PMDA approval timelines shortening as METI industrial policy shifts toward import facilitation.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity accelerates German statutory health insurance reimbursement uplifts for cryoablation platforms. |
| Hospital System Partnership | Integrated delivery network GPO contracts lock in multi-year catheter supply commitments across electrophysiology service lines. |
| Software Companion Development | AI-powered mapping algorithms differentiate next-generation catheter tenders at Cleveland Clinic and Mayo Clinic networks. |
| Reimbursement Strategy | Medicare site-of-service parity advocacy redirects catheter ablation volume toward ambulatory surgical center economics. |
| FDA Submission | Premarket notification clearances compress commercialization timelines for novel contact-force sensing electrode geometries. |
Research Methodology
FDA 510(k) filings, EU MDR notified body certificates, and CMS Medicare reimbursement databases formed the secondary backbone for market sizing validation. Primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers triangulated against catheter manufacturer SEC disclosures and hospital procurement records. Bottom-up procedure volume estimates across United States, German, Japanese, and Chinese electrophysiology labs converged with top-down market value assessments.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic cross-checks for plausibility. Segmentation dimensions spanned procedure type, energy delivery technology, arrhythmia phenotype severity, and end-user facility category across the analysis window. CAGRs derived from weighted average procedure growth rates and price trajectory assumptions. Forecast inputs incorporated PMDA regulatory timeline lag effects and Medicare site-of-service payment differential persistence.
Revisions become necessary when platinum-iridium commodity price shocks, EU MDR notified body capacity constraints, or electrophysiologist fellowship pipeline disruptions materialize beyond modeled assumptions. Forecasts reflect documented assumptions about reimbursement parity maintenance and cryoablation platform adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Remote Endarterectomy Devices Market
Cardiovascular Devices
Global Nitinol Medical Devices Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Iliac Artery Stents Market
Cardiovascular Devices
Cardiac Medical Device Market
Cardiovascular Devices
Hemodynamic Monitoring Devices Market
Cardiovascular Devices
India Cardiovascular Devices Market
Cardiovascular Devices
Cardiac Implantable Electronic Device Market
Cardiovascular Devices
Integrated Cardiology Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Acute Surgical Mechanical Circulatory Support System Market
Cardiovascular Devices
Wearable Artificial Organs Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market